
 PVC Films Market | 2026-2036
PVC Films Market Size, Share, and Industry Trends Forecast 2026-2036
PVC Films Market Analytics
Modular roll-to-sheet configurations are restructuring buyer procurement patterns across the PVC films value chain. Klockner Pentaplast Group leverages in-house calendering and extrusion assets to sustain supply continuity for medical and food-grade film orders. BASF SE anchors its position through specialized stabilizer and additive portfolios that support high-clarity formulations for pharmaceutical blister packs. Westlake Chemical competes on integrated chlor-alkali and vinyl resin economics across North American and European distribution networks.
PVC films are thermoplastic polymer sheets or rolls manufactured from polyvinyl chloride resin compounded with plasticizers, stabilizers, and processing aids, typically calendered or extruded to thicknesses ranging from ultra-thin gauges below 50 microns to heavy-duty sheets exceeding 500 microns. These films provide barrier protection, printability, and thermoformability for packaging, construction membranes, automotive interior skins, and sterile medical wraps. Flexible PVC commands the largest volume share due to its dominance in stretch-wrap and blood-bag applications where pliability and seal strength prove critical. Transparent PVC films are expanding fastest in pharmaceutical blister packaging as traceability and visual inspection requirements intensify across regulated supply chains. Rigid PVC films occupy a mature but stable position in construction laminates and credit card substrates where dimensional stability and flame resistance justify premium positioning.
The EPA regulates vinyl chloride monomer emissions under the Clean Air Act, while REACH and RoHS in Europe restrict heavy-metal stabilizers and certain phthalate plasticizers in consumer-contact applications. FDA compliance for indirect food additives and USP Class VI testing for medical films create dual certification burdens that filter out smaller compounders lacking analytical infrastructure. Stakeholders must monitor evolving state-level extended producer responsibility laws in California and New York that could impose end-of-life recovery obligations on film converters.
Market Dynamics
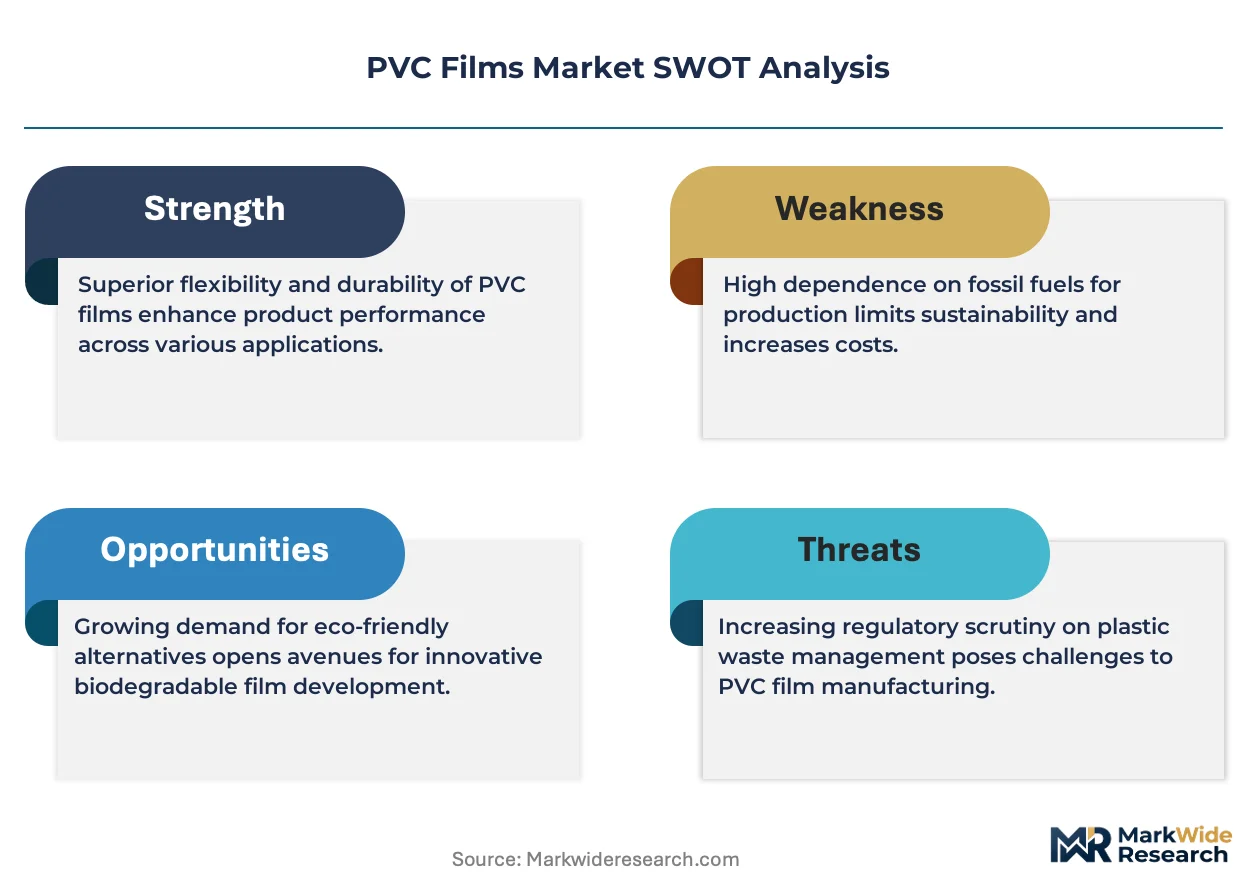
REACH restrictions on phthalate plasticizers are redirecting European formulation investments toward non-orthophthalate alternatives, while packaging converters in food and pharmaceutical sectors simultaneously expand purchase volumes for flexible and transparent grades. This dual pressure is compressing legacy compounder margins and rewarding early movers in bio-based plasticizer development.
Growth Catalysts
- Pharmaceutical blister packaging expansion:Visual inspection requirements and traceability mandates across regulated supply chains are accelerating demand for high-clarity transparent PVC films in sterile medical wraps.
- REACH-driven formulation shift:European restrictions on heavy-metal stabilizers and orthophthalate plasticizers are creating first-mover advantages for compounders with certified non-toxic additive portfolios.
- Extrusion capacity buildout:Domestic converting infrastructure expansion in China, India, and Germany is shortening lead times and reducing import dependency for regional packaging converters.
Market Restraints
- Vinyl chloride monomer supply concentration:Integrated chlor-alkali economics favor producers with captive VCM production, squeezing standalone film extruders in North American and European markets.
- Substitution threat from PET-G and PP films:Non-chlorinated alternatives are capturing share in food-contact applications where brand owners face retailer pressure to eliminate halogenated polymers.
- Extended producer responsibility laws:California and New York state-level recovery obligations are imposing end-of-life compliance costs that filter out smaller converters lacking reverse logistics infrastructure.
Strategic Opportunities
- Bio-based plasticizer penetration:Epoxidized soybean oil and citrate ester formulations are opening premium positioning in medical device packaging where USP Class VI certification commands price premiums.
- Modular roll-to-sheet service models:Slitting and sheeting capabilities integrated at converter level are capturing value previously retained by distributors in just-in-time pharmaceutical supply chains.
- Construction membrane recovery:Post-consumer rigid PVC film collection networks in Germany are creating closed-loop feedstock streams for credit card substrate and laminate manufacturers.
Industry Challenges
- Dual certification burden:Simultaneous FDA indirect food additive compliance and USP Class VI testing for medical films requires analytical infrastructure investments that strain mid-tier compounder balance sheets.
- Plasticizer migration testing complexity:Accelerated aging protocols for non-orthophthalate alternatives lack standardized methods, extending qualification timelines for pharmaceutical blister pack approvals.
- Calendering asset utilization:Thin-gauge flexible film production requires dedicated roll maintenance schedules that conflict with rigid sheet campaigns, complicating capacity planning for multi-product extrusion lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PVC Films Market |
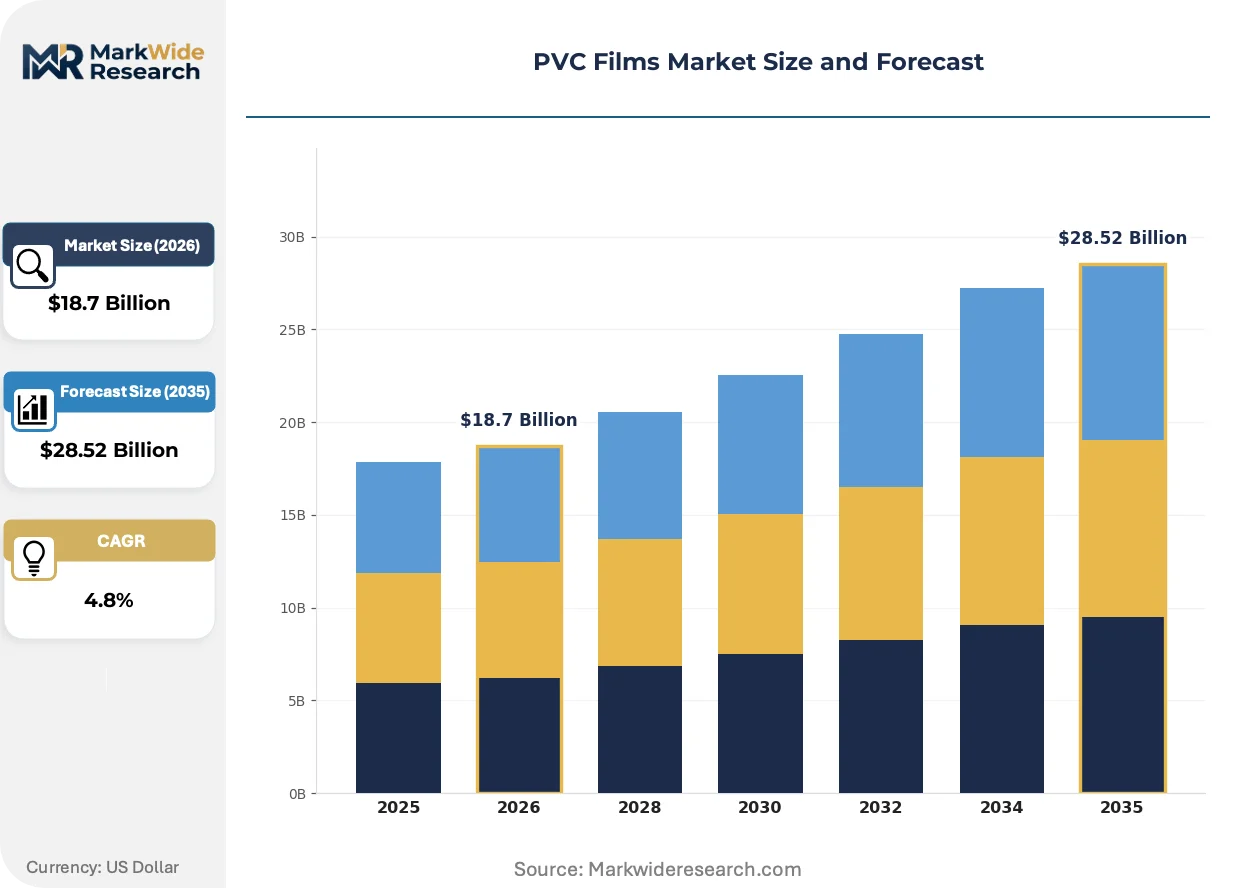
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible PVC, Rigid PVC, Transparent PVC, Foam PVC End Use Industry: Packaging, Automotive Components, Construction Materials, Medical Supplies Form: Sheet, Rolls, Bags, Containers Thickness: Thin, Medium, Thick, Ultra-Thin |
| Companies Covered | 3M Company, SABIC, BASF SE, Kuraray Co., Ltd., Klockner Pentaplast Group, DuPont de Nemours Inc, Kraton Corporation, Westlake Chemical, Saint-Gobain S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PVC Films Market Evolving Landscape
Equipment architecture and regulatory chemistry are converging to compress production batch sizes and accelerate formulation turnover across the PVC films value chain. Three developments are restructuring competitive positioning.
Digital print-receptive surface treatment technology is modularizing converter operations by enabling inline corona and flame treatment systems that switch between packaging grades without line changeover downtime. Pharmaceutical and food-grade film buyers are adopting these configurations to reduce minimum order quantities and support SKU proliferation. This modularizing capability is compressing the economic viability of centralized toll-coating operations that previously captured surface treatment value.
REACH Annex XVII restrictions on cadmium and lead stabilizers are forcing reformulation of construction-grade rigid films toward calcium-zinc and organotin alternatives. The industrial consequence is elevated raw material cost structures for credit card substrate and laminate producers serving European markets. German and French converters are responding by qualifying Asian stabilizer suppliers with ECHA-registered additive portfolios, diversifying sourcing away from legacy Western chemical majors.
Consolidated buying by multinational pharmaceutical packaging groups is compressing supplier bases and unbundling technical service from base film supply contracts. Regional converters in India and China are displacing traditional distributors by offering direct mill relationships with integrated slitting and quality documentation. This concentration is most visible in sterile medical wrap supply chains where traceability requirements favor single-source accountability over fragmented multi-tier distribution.
PVC Films Market Segmentation
PVC film specifications diverge sharply across certification regimes. FDA indirect food additive status, USP Class VI medical clearance, and REACH SVHC compliance each gate access to distinct buyer pools and price tiers.
Product Type:
Certification burden stratifies sharply across these four product categories, with medical and food-contact grades demanding dual FDA and USP documentation that rigid construction films bypass entirely.
- Flexible PVC:Polymer matrices incorporate 30-50% phthalate or bio-based plasticizers to achieve elongation properties exceeding 200%. Blood-bag manufacturers in Germany and stretch-wrap converters in India concentrate purchase volumes here, though REACH Annex XVII restrictions on orthophthalates are compressing legacy supplier margins.
- Transparent PVC:High-clarity formulations rely on organotin or calcium-zinc stabilizer packages with haze values below 2%. Pharmaceutical blister pack demand in regulated supply chains is accelerating qualification timelines for these grades, particularly where traceability mandates require lot-level documentation.
- Rigid PVC:Unplasticized homopolymer sheets with Shore D hardness above 80 serve construction laminates and credit card substrates. Flame-retardant additives meet UL 94 V-0 specifications without the migration testing burden of flexible grades.
- Foam PVC:Cellular structures with densities ranging 0.4-0.7 g/cm³ provide lightweight rigidity for display graphics and interior cladding. Extrusion foaming technology limits viable supplier pools compared to solid film processes.
Flexible PVC sits at the top of the volume ranking, with Transparent PVC climbing the fastest.
End Use Industry:
Customer procurement scale and technical service intensity define margin architecture across these four verticals, with pharmaceutical buyers unbundling supply contracts from technical support.
- Packaging:Food-contact films require FDA 21 CFR 177.1350 compliance for indirect additives, while sterile medical wraps demand USP Class VI endotoxin and cytotoxicity testing. Converters in China are capturing value through integrated slitting and documentation services previously retained by distributors.
- Medical Supplies:Blood bags, IV tubing, and dialysis membranes specify plasticizer migration limits below 10 µg/cm² under accelerated aging protocols. The analytical infrastructure burden filters out mid-tier compounders lacking GC-MS and HPLC capabilities.
- Automotive Components:Interior skins and instrument panel overlays prioritize fogging resistance and UV stability over biocompatibility certification. OEM specification locks favor incumbent suppliers with IATF 16949 quality system credentials.
- Construction Materials:Membranes and laminates emphasize dimensional stability and flame resistance rather than extractables testing. German post-consumer collection networks are creating closed-loop feedstock streams for these applications.
Packaging commands the largest revenue pool, with Medical Supplies expanding most quickly.
Form:
Processing equipment compatibility and logistics cost structures determine converter preferences across these four configurations, with roll formats dominating high-volume pharmaceutical supply chains.
- Rolls:Master rolls up to 2 meters wide enable continuous thermoforming and printing operations. Just-in-time pharmaceutical supply chains favor slit-to-width roll programs that minimize converter inventory carrying costs.
- Sheet:Cut-to-size panels serve point-of-purchase display and construction lamination applications where flatness tolerances exceed roll memory concerns. Sheeting capabilities integrated at extruder level are displacing toll converters.
- Bags:Pre-formed pouches and liners eliminate secondary converting steps for blood collection and specimen transport. Gamma sterilization compatibility requirements narrow qualified supplier bases.
- Containers:Thermoformed trays and blisters represent downstream converted products rather than primary film sales, though integrated converters capture margin through in-house forming operations.
Rolls dominate shipment volumes, with Sheet formats gaining share in construction applications.
Thickness:
Calendering line configuration and gauge control precision segment manufacturing capability, with ultra-thin production requiring dedicated roll maintenance schedules that conflict with heavy-gauge campaigns.
- Thin:Gauges between 50-150 microns balance barrier performance with thermoformability for pharmaceutical blister packs. Gauge uniformity within ±5% enables reliable seal integrity in high-speed packaging lines.
- Ultra-Thin:Sub-50 micron films demand specialized chill roll polishing and tension control for blood-bag and IV tubing applications. Yield advantages drive pharmaceutical preference despite handling complexity.
- Medium:150-300 micron range serves general-purpose packaging and stationery laminates where cost optimization outweighs premium performance specifications.
- Thick:Exceeding 300 microns, these grades provide structural rigidity for credit card substrates and industrial tags. Calendering asset utilization favors rigid sheet campaigns over thin-gauge flexible production.
Thin gauges lead in unit volume, with Ultra-Thin films showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered industrial-scale PVC calendering during the mid-20th century, establishing technical standards and formulation expertise that continue to shape global supply chains. Today, production clusters in China, India, and Germany concentrate extrusion capacity while adapting to diverging regulatory pressures.
China
Packaging converters in Jiangsu and Zhejiang provinces are scaling domestic extrusion lines to serve pharmaceutical and food-grade demand. MIIT's GB standards for food-contact materials are tightening additive migration limits, forcing reformulation investments. The Yangtze River Delta hosts integrated chlor-alkali complexes that supply captive VCM to film producers in Taizhou and Ningbo.
India
Stretch-wrap and blood-bag manufacturers in Maharashtra and Gujarat are expanding purchase volumes for flexible grades. BIS certification requirements for medical device polymers are extending qualification timelines for imported stabilizer packages. The Vadodara-Ahmedabad corridor is attracting extrusion equipment investments from compounders serving domestic pharmaceutical packaging growth.
Germany
REACH Annex XVII restrictions on cadmium and lead stabilizers are redirecting construction-grade rigid film formulations toward calcium-zinc alternatives. ECHA's SVHC candidate list updates are forcing continuous portfolio reviews among compounders in North Rhine-Westphalia. The Cologne-Leverkusen chemical cluster maintains specialized additive development capabilities for high-clarity pharmaceutical grades.
United States
EPA Clean Air Act enforcement on vinyl chloride monomer emissions is constraining expansion options for standalone extruders without captive chlor-alkali integration. California's extended producer responsibility legislation is imposing end-of-life recovery obligations that filter out smaller converters. The Gulf Coast petrochemical corridor supplies resin to film producers serving medical device clusters in Minnesota and Massachusetts.
Japan
Automotive interior skin specifications from Toyota and Honda are prioritizing fogging-resistant formulations with low-VOC emissions. METI's chemical substance management policies are accelerating substitution away from legacy plasticizer packages. The Nagoya industrial zone maintains precision calendering capabilities for ultra-thin gauge medical films.
PVC Films Market Competitive Landscape
The competitive structure tilts toward integrated chemical conglomerates with captive resin supply and specialized compounders with certification depth. Tier-one positions cluster around producers combining chlor-alkali economics with pharmaceutical-grade extrusion assets. Mid-tier converters compete on modular slitting services and regional logistics rather than formulation differentiation. Dominant competitive moves include backward integration into VCM production and geographic expansion through toll-manufacturing partnerships in high-growth Asian markets.
Among European chemical majors, BASF SE anchors the specialty additive segment through stabilizer portfolios that support REACH-compliant formulations. Klockner Pentaplast Group exemplifies the integrated converter archetype with in-house calendering assets serving medical and food-grade film orders. Westlake Chemical occupies a position defined by North American chlor-alkali integration and vinyl resin economics across distribution networks.
| Leading Market Players |
|---|
| 3M Company |
| SABIC |
| BASF SE |
| Kuraray Co., Ltd. |
| Klockner Pentaplast Group |
| DuPont de Nemours Inc |
| Kraton Corporation |
| Westlake Chemical |
| Saint-Gobain S.A. |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap compounders in Germany and Italy anchor specialty PVC film production, their conservative balance sheets limiting aggressive capacity expansion even as REACH compliance costs mount. This ownership pattern concentrates pricing power among integrated chlor-alkali conglomerates with captive VCM supply, while smaller converters absorb margin compression from plasticizer reformulation mandates.
Pricing Analysis
Three-tier pricing structure across pharmaceutical-grade, food-contact, and industrial-standard levels dominates PVC film transactions, with certification burden and volume scale as the primary differentiation drivers. Pharmaceutical-grade films command substantial premiums due to USP Class VI documentation and lot-level traceability requirements, while industrial construction films face acute price erosion from commodity resin competition. Food-contact tiers exhibit the highest price sensitivity as brand owners balance FDA compliance costs against substitution threats from PET-G alternatives.
Supply Chain Analysis
Freight cost differentials between containerized resin imports and domestic VCM production are restructuring procurement geography across the PVC films value chain. Supply concentrates in China, Germany, and India, with extrusion capacity clustering near chlor-alkali complexes in Taizhou, Leverkusen, and Vadodara. Raw material dependencies span vinyl chloride monomer, calcium-zinc stabilizer packages, and epoxidized soybean oil plasticizers. Single-source vulnerability in medical-grade additive supply creates exposure to ECHA SVHC list updates. Distribution runs through direct mill relationships for pharmaceutical converters and regional distributors for construction applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
PVC Films Market functions as a regulatory compounder where REACH Annex XVII restrictions on orthophthalate plasticizers and heavy-metal stabilizers are accelerating demand for certified non-toxic formulations. This regulatory momentum rewards early movers in bio-based plasticizer development and compresses legacy supplier margins.
For Market Incumbents: Deepen backward integration into VCM production or captive chlor-alkali assets to defend margin position against integrated competitors. Expand extrusion capacity in the Yangtze River Delta and Vadodara-Ahmedabad corridor to capture pharmaceutical packaging growth while qualifying Asian stabilizer suppliers to diversify ECHA-registered additive sourcing away from legacy Western chemical majors.
For New Entrants and Emerging Players: Enter via modular roll-to-sheet service models that integrate slitting and quality documentation capabilities, displacing traditional distributors in just-in-time pharmaceutical supply chains. Target bio-based plasticizer formulation as the most penetrable segment, leveraging epoxidized soybean oil and citrate ester platforms to capture USP Class VI-certified medical device packaging demand.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier compounders lacking analytical infrastructure for dual FDA and USP certification. Long-term viability hinges on regulatory chemistry capabilities and pharmaceutical-grade extrusion assets rather than commodity resin economics. Watch ECHA SVHC candidate list updates as the inflection signal for accelerated portfolio consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into VCM Production | Captive chlor-alkali supply insulates margin from vinyl chloride monomer price volatility. |
| Bio-based Plasticizer Certification | USP Class VI clearance for epoxidized soybean oil opens premium medical device packaging segments. |
| Modular Roll-to-Sheet Service Expansion | Integrated slitting capabilities capture distributor value in pharmaceutical just-in-time supply chains. |
| Asian Stabilizer Supplier Qualification | ECHA-registered calcium-zinc alternatives reduce European construction film raw material cost structures. |
| Post-Consumer Collection Network Development | German closed-loop rigid PVC recovery creates feedstock security for credit card substrate manufacturers. |
Research Methodology
Coverage spans China, India, Germany, and the United States, with primary inputs from each region's extrusion clusters and downstream converting hubs. The analysis combines structured interviews with plant managers at calendering facilities, procurement leads at pharmaceutical packaging converters, distribution channel partners serving construction laminators, and technical R&D directors at stabilizer compounders. Secondary validation draws from customs and trade data, SEC 10-K filings of integrated chemical conglomerates, ECHA substance registration databases, and FDA indirect food additive compliance listings. Bottom-up capacity assessments and top-down demand modeling were triangulated to cross-verify volume estimates.
Rate-of-change decomposition across the analysis window separates volume growth from price/mix effects and segment shifts. The forecasting framework models demand by product type, end-use industry, certification tier, and regional production hub. CAGRs were derived from fitted growth curves calibrated against historical chlor-alkali capacity expansion patterns and pharmaceutical packaging investment cycles. Industry-specific inputs include REACH Annex XVII enforcement timelines, MIIT GB standard migration limit tightening, and BIS medical device polymer certification queue lengths.
Inputs from ECHA substance registration databases and FDA compliance listings were available through the study window; gaps in real-time pharmaceutical converter inventory data introduce uncertainty bands around near-term demand inflection points. Forecasts reflect assumptions about regulatory enforcement continuity and plasticizer substitution elasticities. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Spain Plastic Packaging Films Market
Poly film
Surface Printed Film Market
Poly film
PP Laminating Films Market
Poly film
Co Extruded Films Market
Poly film
Colombia Plastic Packaging Films Market
Poly film
Cleanroom Film and Bags Market
Poly film
Synthetic and Bio Thermoplastic Polyurethane (TPU) Films Market
Poly film
Light Reflective Film Market
Poly film
LDPE Films Market
Poly film
Biaxially Oriented Polyethylene Terephthalate (BOPET) Films Market
Poly film
EVOH Encapsulation Film Market
Poly film
Hexacomb Packaging Market
Poly film
Bio-PET Film Market
Poly film
Poly Coated Kraft Paper Market
Poly film
Timber Wrap Films Market
Poly film
Global Biaxially Oriented Polypropylene (BOPP) in Films and Sheets Market