
 Japan Plastic Packaging Film Market | 2026-2036
Japan Plastic Packaging Film Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Plastic Packaging Film Market Insights
Japanese food service chains are unwinding legacy multi-material packaging contracts in favor of mono-polyethylene structures that simplify post-consumer sorting. Futamura Chemical leverages its cellulose-derived barrier coatings to compete in compostable film niches, while Toray Advanced Film anchors the premium oxygen-barrier segment through biaxially oriented nylon lines. Toppan Packaging Products differentiates via gravure-printed decorative films for high-end confectionery, a channel where brand owners control shelf impact.
Plastic packaging film denotes flexible polymer substrates engineered to thicknesses between twelve and two hundred microns, manufactured through cast extrusion, blown extrusion, or biaxial orientation processes to deliver moisture barriers, gas barriers, or mechanical protection. Polyethylene formulations lead volume in Japan due to cost scalability and compatibility with existing recycling infrastructure, though polypropylene films capture margin pools in retort pouch applications where thermal stability commands price premiums. Pharmaceutical packaging represents the fastest-growing application dimension as serialization requirements and biologic drug sensitivity expand demand for high-barrier laminates.
METI's Resource Circulation Strategy for Plastics and the Japan Containers and Packaging Recycling Association's fee structures shape converter material choices, while PMDA stability testing protocols govern film qualification for pharmaceutical contact. JIS standards for food-contact plastics further constrain additive migration limits, forcing reformulation of legacy PVC and polyvinylidene chloride constructions. Stakeholders must monitor whether METI extends mandatory recycled content thresholds beyond current voluntary benchmarks, as this would restructure resin sourcing economics for domestic blown film extruders.
Market Dynamics
METI's Resource Circulation Strategy for Plastics is forcing converters to unwind legacy multi-layer structures and retool for mono-material recyclability, compressing margins while redirecting capital toward polyethylene streamlining.
Growth Catalysts
- Food service automation:Japanese ready-meal chains are scaling high-barrier film purchases for chilled distribution networks, creating pull-through demand for oxygen-scavenging laminates.
- Pharmaceutical serialization:PMDA stability testing protocols for biologic drugs are expanding qualification requirements for high-barrier primary packaging in temperature-sensitive therapies.
- Kanto corridor concentration:Blown film extruders cluster within 100 kilometers of Tokyo-Yokohama logistics hubs, capturing just-in-time supply contracts from beverage and confectionery packagers.
Market Restraints
- Ethylene feedstock volatility:Naphtha-linked polyethylene resin costs swing with regional refinery output, squeezing converter margins on fixed-price annual contracts.
- Barrier coating substitution:Thin aluminum oxide vapor-deposited films face displacement from cellulose-derived alternatives in compostable packaging niches.
- JIS migration limits:Tightening additive thresholds for food-contact plastics are forcing reformulation of legacy PVC constructions, extending qualification timelines.
Strategic Opportunities
- Kansai underpenetration:Osaka-Kobe industrial zones maintain lower film consumption per capita than Kanto, offering whitespace for regional distribution investments.
- Mono-material incentives:Japan Containers and Packaging Recycling Association fee differentials reward simplified polymer streams, subsidizing retooling for pure polyethylene structures.
- Retort pouch thermal stability:Polypropylene films command price premiums in sterilizable applications where polyethylene fails, opening margin pools in prepared curry and rice segments.
Industry Challenges
- Gravure cylinder scarcity:Skilled engravers for high-definition decorative printing retire faster than apprentices enter the trade, constraining Toppan-style premium confectionery output.
- Biaxial orientation capex:Nylon film lines require nine-figure yen commitments with six-year payback horizons, deterring mid-cap entrants from challenging Toray's oxygen-barrier dominance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Plastic Packaging Film Market |
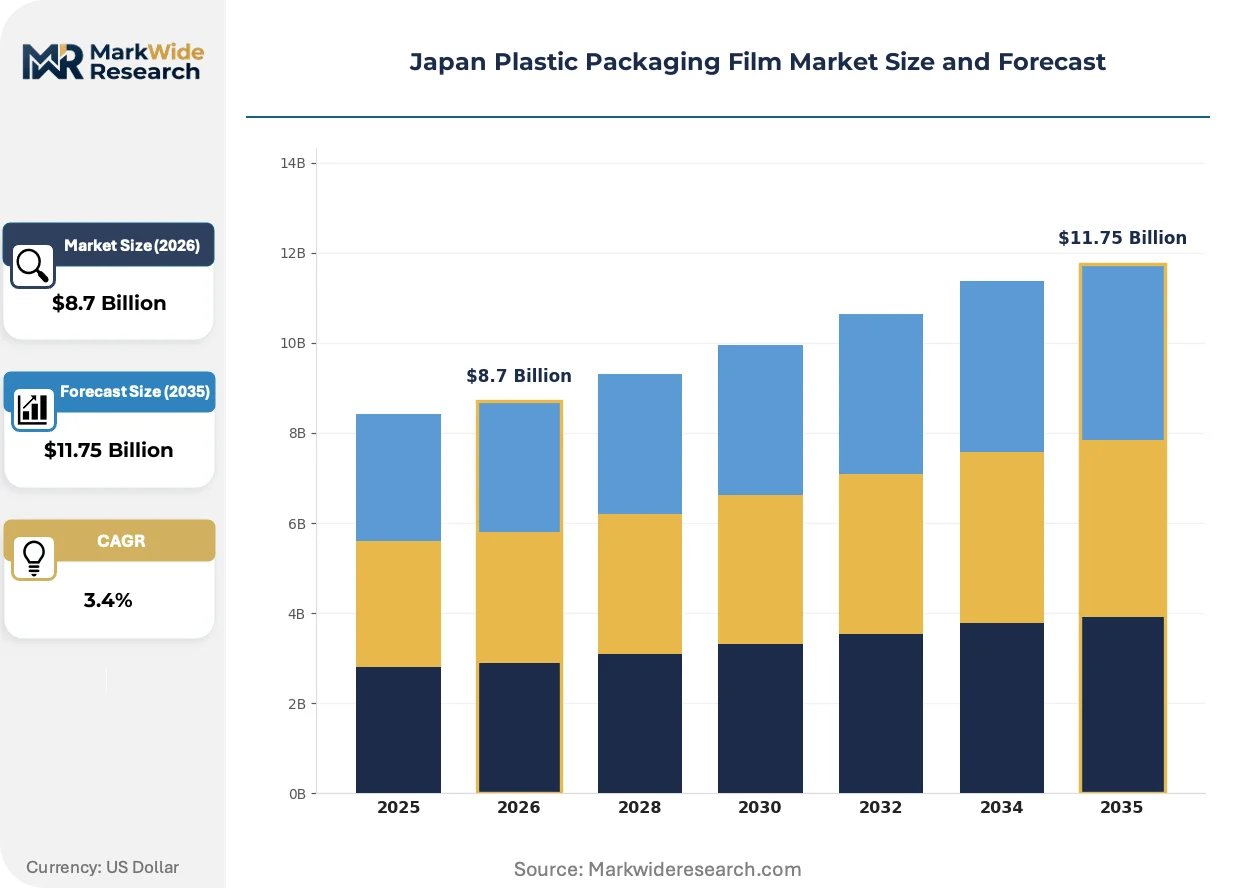
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $11.75 Billion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, Polyvinyl Chloride, Others Application: Food Packaging, Pharmaceutical Packaging, Industrial Packaging, Personal Care Packaging Thickness: Thin Film, Medium Film, Thick Film, Ultra-Thin Film End User: Food Service, Healthcare, Consumer Goods, Electronics |
| Companies Covered | Toray Advanced Film, Futamura Chemical, Toppan Packaging Products, Toyobo, Rengo, Cosmo Films Limited, Unitika, Sekisui Chemical, Dai Nippon Printing, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Plastic Packaging Film Market Trends and Innovations
Japanese converters are racing to collapse multi-material complexity into recyclable mono-polyethylene streams while pharmaceutical and food service buyers demand ever-higher functional performance from thinner substrates.
Cellulose-derived barrier coatings are decomposing the technical advantage of aluminum oxide vapor-deposited films in compostable packaging segments. Futamura Chemical and niche competitors deploy these bio-based layers for fresh produce and premium snack applications where industrial composting infrastructure exists. The shift is compressing addressable volume for conventional metallized films in environmentally positioned product lines.
METI's mandatory recycled content benchmarks are restructuring resin sourcing economics for domestic blown film extruders. The policy creates tiered compliance obligations based on packaging format and volume thresholds, with larger converters facing earlier deadlines. Pharmaceutical contact films remain exempt, preserving virgin polymer requirements for PMDA-qualified barrier laminates in biologic drug packaging.
Centralized procurement through beverage and confectionery headquarters is displacing regional distributor relationships in the Kanto corridor. Brand owners now mandate direct mill relationships with volume commitments and audit rights, compressing intermediary margins. The pattern concentrates most visibly among ready-meal chains seeking traceability for ESG disclosure requirements.
Japan Plastic Packaging Film Market Segmentation
Film specifications diverge sharply across Japanese end-use requirements, with regulatory pressure from METI and PMDA forcing material choices that complicate converter portfolio strategies. Understanding where substitution threats concentrate helps stakeholders allocate retooling capital toward defensible polymer streams.
Product Type:
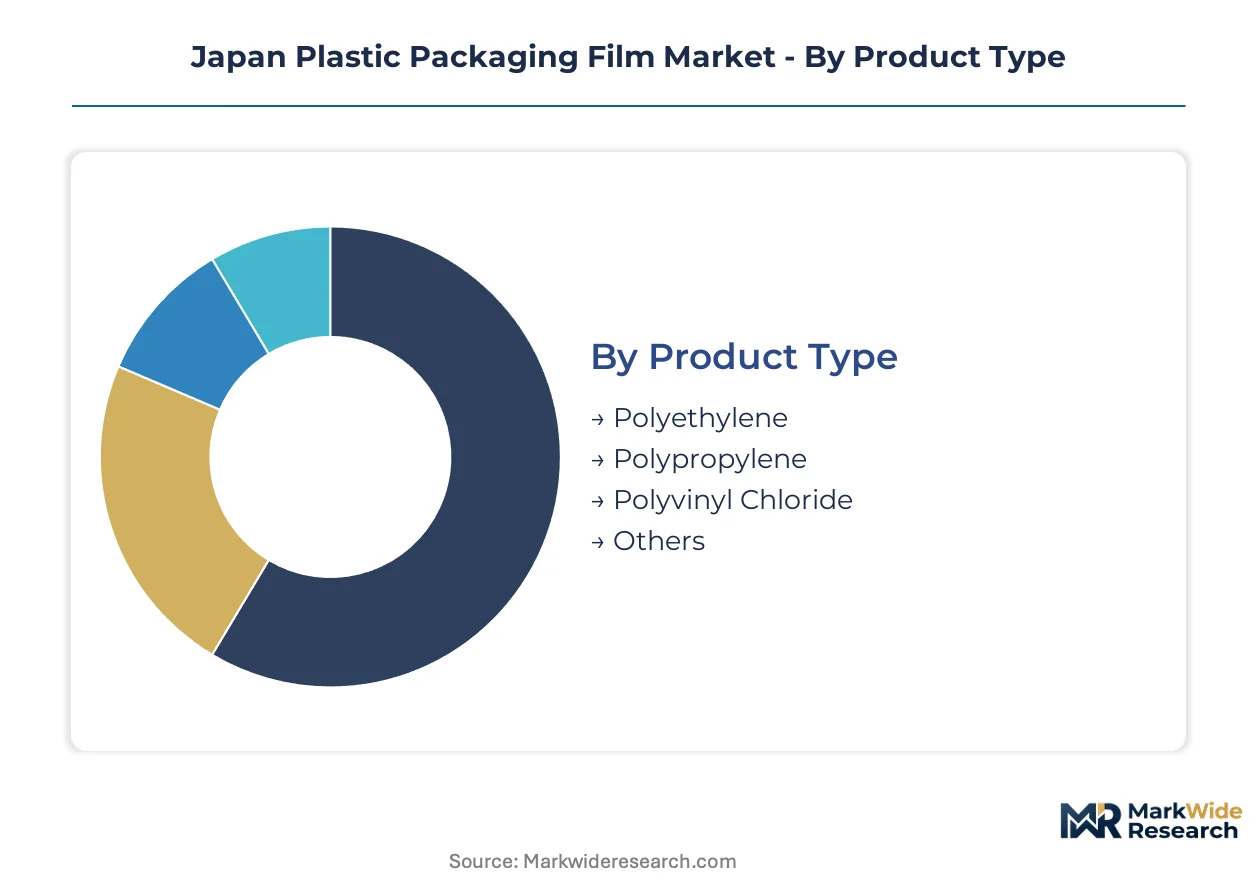
Polyethylene faces the most acute substitution pressure as cellulose-derived barrier coatings and compostable alternatives erode its environmental positioning, while polypropylene's thermal stability shields it from near-term displacement.
- Polyethylene:Linear low-density and metallocene grades dominate blown film extrusion for food-contact applications. Kanto corridor beverage packagers anchor demand despite METI's recyclability mandates forcing mono-material streamlining that favors pure polyethylene structures over legacy laminates.
- Polypropylene:Biaxially oriented films deliver the thermal stability required for retort pouch sterilization at 121°C. Prepared curry and rice manufacturers in the Osaka-Kobe industrial zone pay price premiums for cast polypropylene when polyethylene barrier performance fails under thermal stress.
- Polyvinyl Chloride:Legacy cling film and blister pack constructions face JIS migration limit tightening that extends reformulation timelines.
- Others:Polyamide and ethylene vinyl alcohol copolymers serve niche oxygen-barrier laminates for pharmaceutical serialization requirements.
Polyethylene retains volume leadership; polypropylene holds the steepest expansion curve.
Application:
Cost tier stratification separates commodity food wraps from qualification-intensive pharmaceutical laminates, with the latter commanding five-fold material premiums per square meter.
- Food Packaging:Ready-meal chains and chilled distribution networks pull high-barrier oxygen-scavenging films. Centralized procurement through Tokyo headquarters now mandates direct mill relationships with ESG audit rights, displacing regional distributors.
- Pharmaceutical Packaging:PMDA stability testing protocols for biologic drugs expand qualification requirements for temperature-sensitive therapies. Serialization mandates and cold-chain sensitivity drive specification tightening that preserves virgin polymer requirements despite METI recycled content benchmarks.
- Industrial Packaging:Stretch wrap and pallet unitization films compete on resin cost and gauge efficiency for automotive component logistics.
- Personal Care Packaging:Decorative gravure-printed films for premium cosmetics face cylinder engraver scarcity constraints.
Food packaging commands absolute volume; pharmaceutical packaging is expanding most quickly.
Thickness:
Downgauging pressure from brand owners concentrates demand migration toward thinner specifications that maintain barrier performance with reduced polymer mass per package.
- Thin Film:Twelve to fifty micron specifications serve primary food wraps and overwrap applications. Tokyo-Yokohama logistics hubs favor these gauges for just-in-time delivery efficiency in high-velocity confectionery channels.
- Medium Film:Fifty to one hundred twenty microns balance puncture resistance with material economy for industrial bundling.
- Thick Film:One hundred twenty to two hundred microns provide structural rigidity for heavy-duty shipping sacks in chemical and agricultural sectors.
- Ultra-Thin Film:Sub-twelve micron experimental gauges face commercialization barriers from JIS mechanical property minimums.
Thin film specifications dominate current procurement; ultra-thin film holds the most distant commercialization horizon.
End User:
Customer type segmentation reveals diverging procurement sophistication, with healthcare and food service buyers imposing qualification regimes that commodity consumer goods channels rarely match.
- Food Service:Ready-meal automation and chilled distribution networks scale high-barrier purchases. Brand owners unwind legacy multi-material contracts in favor of mono-polyethylene structures that simplify post-consumer sorting for ESG disclosure.
- Healthcare:Pharmaceutical manufacturers face PMDA serialization requirements and biologic drug sensitivity that expand demand for high-barrier laminates. Virgin polymer exemptions from METI recycled content mandates preserve specification integrity.
- Consumer Goods:Mass-market personal care and household product packagers prioritize unit cost over technical differentiation.
- Electronics:Anti-static and moisture-barrier films for semiconductor component shipping face cyclical demand tied to regional manufacturing output.
Food service anchors procurement volume; healthcare maintains the most demanding specification trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Yokohama and Tokyo Bay container terminals anchor Japan's plastic packaging film distribution, with Kanto corridor extruders positioning within 100 kilometers of these maritime gateways to serve just-in-time procurement from beverage and confectionery headquarters.
Kanto/Tokyo
Ready-meal automation and chilled distribution networks concentrate demand for high-barrier oxygen-scavenging films in the Tokyo-Yokohama industrial zone. METI's Resource Circulation Strategy for Plastics mandates mono-material streamlining that favors pure polyethylene structures over legacy laminates. Blown film extruders cluster around Kawasaki and Chiba to capture direct mill relationships with brand owners imposing ESG audit rights.
Kansai/Osaka
Prepared curry and rice manufacturers in the Osaka-Kobe industrial zone pay price premiums for cast polypropylene thermal stability where polyethylene fails under retort sterilization at 121°C. The Japan Containers and Packaging Recycling Association fee differentials reward simplified polymer streams, subsidizing regional converters retooling for recyclable structures. Kansai maintains lower film consumption per capita than Kanto, offering whitespace for distribution investments.
Chubu/Nagoya
Automotive component logistics drive stretch wrap and pallet unitization film demand tied to Toyota Motor Corporation supply chain density. Industrial packaging specifications prioritize resin cost and gauge efficiency over barrier performance. Nagoya Port serves as the secondary maritime gateway for Central Japan chemical feedstock imports.
Kyushu
Semiconductor component shipping from Fukuoka and Kumamoto fabrication facilities generates cyclical demand for anti-static and moisture-barrier films. Electronics end-users impose strict contamination controls that favor qualified supplier relationships over spot procurement. Kyushu converters compete primarily on logistics proximity rather than technical differentiation.
Tohoku
Agricultural chemical and fertilizer packaging sustains thick-film demand for heavy-duty shipping sacks in Sendai-corridor distribution centers. JIS mechanical property minimums constrain ultra-thin film commercialization attempts in this secondary market. Tohoku extruders operate at lower capacity utilization than Kanto counterparts due to reduced food service and pharmaceutical concentration.
Japan Plastic Packaging Film Market Competitive Landscape
Listed leaders compete with private specialists across barrier technology tiers, with the market consolidating around integrated resin-to-film manufacturers and diversified chemical conglomerates. Toray Advanced Film anchors premium oxygen-barrier positioning through biaxially oriented nylon lines, while mid-cap converters face nine-figure yen capital commitments that deter entry. Three archetypes dominate: integrated chemical conglomerates controlling resin supply, specialized barrier film engineers, and gravure-printed decorative specialists. Competitive moves concentrate on backward integration into resin compounding and technology licensing for mono-material recyclability.
Among Japan-based diversified manufacturers, Toray Advanced Film, Futamura Chemical, and Toppan Packaging Products occupy distinct positioning archetypes. Toray exemplifies the integrated chemical conglomerate model with captive polymer supply and biaxial orientation expertise. Futamura represents the bio-based barrier specialist segment competing in compostable film niches through cellulose-derived coating technology. Toppan sits within the premium decorative tier where gravure-printed confectionery films command sustained margin pools despite cylinder engraver scarcity constraints.
| Leading Market Players |
|---|
| Toray Advanced Film |
| Futamura Chemical |
| Toppan Packaging Products |
| Toyobo |
| Rengo |
| Cosmo Films Limited |
| Unitika |
| Sekisui Chemical |
| Dai Nippon Printing |
| Others |
Pricing and Supply Chain Analysis
METI's Resource Circulation Strategy for Plastics gates both supplier qualification and price differentiation simultaneously, as converters must invest in mono-material retooling to access Japan Containers and Packaging Recycling Association fee subsidies while pharmaceutical buyers pay virgin polymer premiums exempt from recycled content mandates.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates PMDA-qualified pharmaceutical laminates from food-contact mono-polyethylene and industrial stretch wrap grades. Price differentiation rests on certification tier and volume scale, with biologic drug packaging commanding material premiums five-fold above commodity tiers. Cost compression in standard-grade food packaging intensifies as Kanto corridor brand owners consolidate procurement through direct mill relationships. Industrial packaging buyers exhibit highest price sensitivity, while pharmaceutical manufacturers prioritize barrier performance over unit cost.
Supply Chain Analysis
Inbound logistics costs from naphtha feedstock deliveries through Yokohama and Chiba port terminals fluctuate with regional refinery output schedules, compressing converter margins on fixed-price annual contracts. Geographic supply concentrates in Japan, South Korea, and Singapore for polyethylene resin compounding. Raw material dependencies center on ethylene monomer, metallocene catalysts, and barrier coating chemistries. Single-source vulnerability from skilled gravure cylinder engraver scarcity constrains premium decorative film output. Distribution runs through just-in-time direct mill relationships with Tokyo-headquartered brand owners, displacing regional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents an early-cycle expansion story as METI's mandatory recycled content benchmarks accelerate converter retooling and create first-mover advantages in mono-material qualification. Pharmaceutical serialization requirements and biologic drug cold-chain expansion provide sustained tailwinds for high-barrier laminate penetration.
For Market Incumbents: Fortify barrier technology moats through captive biaxial orientation capacity and cellulose-derived coating R&D to defend against aluminum oxide vapor-deposition substitution. Accelerate backward integration into metallocene polyethylene resin compounding to secure feedstock cost control against naphtha-linked volatility. Prioritize PMDA qualification maintenance for pharmaceutical laminates where virgin polymer exemptions preserve margin pools. For New Entrants and Emerging Players: Regional distribution service gaps in Kansai's Osaka-Kobe industrial zone offer whitespace for prepared curry and rice retort pouch specialists. Target cast polypropylene thermal stability applications where polyethylene fails under sterilization stress. Pursue Japan Containers and Packaging Recycling Association certification as a go-to-market credential for fee-subsidized mono-material structures. For Investors and Strategic Acquirers: METI's 2030 recycled content threshold reshapes the acquisition landscape toward converters with proven mono-material streamlining capabilities and pharmaceutical qualification track records. Long-term viability favors integrated resin-to-film manufacturers with captive polymer supply and biaxial orientation assets. Watch for PMDA serialization mandate expansion into generic drug categories as an inflection signal for high-barrier laminate demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Retooling Investment | Japan Containers and Packaging Recycling Association fee subsidies improve converter competitiveness against legacy laminate producers. |
| Cellulose-Derived Coating Development | Futamura Chemical's barrier technology decomposes aluminum oxide film advantages in compostable packaging segments. |
| Biaxial Orientation Capacity Expansion | Nine-figure yen commitments with six-year payback horizons deter mid-cap entrants from challenging Toray's oxygen-barrier dominance. |
| Direct Mill Relationship Consolidation | Centralized procurement through Tokyo headquarters displaces regional distributors and compresses intermediary margins. |
| PMDA Pharmaceutical Qualification | Serialization requirements and biologic drug sensitivity preserve virgin polymer specifications exempt from METI recycled content mandates. |
Research Methodology
Initial hypotheses were tested against primary input from blown film extrusion plant managers, beverage packager procurement leads, pharmaceutical regulatory affairs directors, and gravure printing technical specialists and refined through secondary validation against METI policy circulars, PMDA stability testing protocols, Japan Containers and Packaging Recycling Association fee schedules, and JIS food-contact migration limit standards. Bottom-up demand modeling from end-use procurement patterns triangulated with top-down resin consumption estimates.
Variance decomposition across product type, application, thickness tier, and end-user sophistication dimensions structured the analytical framework over the projection horizon. CAGRs were derived from segment-level volume trajectories weighted by price realization trends. Forecast inputs incorporated ethylene feedstock cost sensitivity, retort pouch thermal stability substitution elasticities, and pharmaceutical serialization mandate expansion scenarios.
Underlying assumptions cover sustained METI enforcement of mono-material recyclability timelines, stable PMDA pharmaceutical packaging exemptions, and continued Kanto corridor procurement consolidation, with deviation risk concentrated in ethylene feedstock volatility and gravure cylinder engraver labor supply constraints. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Global Polycarbonate Sheets and Films Market
Poly film
Thermoplastic Polyurethane (TPU) Films Market
Poly film
Polycoated Packaging Market
Poly film
Isotropic Film Market
Poly film
India Plastic Packaging Film Market
Poly film
Global BOPET Packaging Films Market
Poly film
Poly Coated Kraft Paper Market
Poly film
APET Film Market
Poly film
Polypropylene Packaging Films Market
Poly film
Global Cast Polypropylene Packaging Films Market
Poly film
Global BOPP Films Market
Poly film
Chocolate Wrapping Films Market
Poly film
Latin America Polypropylene (PP) Packaging Film Market
Poly film
Morocco Plastic Packaging Films Market
Poly film
Polyimide Films and Tapes Market
Poly film
Peelable and Resealable Films Market