
 Global Beverage Carton Packaging Machinery Market | 2026-2036
Global Beverage Carton Packaging Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
Global Beverage Carton Packaging Machinery Market Foresight
Buyer concentration across beverage producers is broadening as regional dairy cooperatives and private-label juice brands invest in captive carton filling capacity alongside multinational bottlers. Tetra Pak leverages its integrated aseptic systems portfolio to sustain technology leadership in extended-shelf-life dairy. Krones AG anchors European supply through its specialized wet-end and dry-end carton handling lines. SIG Combibloc differentiates via its focus on tethered-cap compatible machinery ahead of EU single-use plastics rules.
Beverage carton packaging machinery comprises integrated equipment systems that form, fill, and seal liquid-tight containers from laminated paperboard substrates, typically operating at speeds exceeding 24,000 units per hour with hydrogen peroxide or electron-beam sterilization. These systems serve the commercial purpose of preserving flavor integrity and microbiological stability in non-refrigerated distribution chains. Aseptic filling technology leads capital deployment due to its premium positioning in dairy and juice applications, while plunger filling systems occupy the fastest-growing tier as functional beverage startups demand flexible low-volume production. Sealing machinery concentrates margin pools where hermetic integrity requirements for probiotic and plant-based drinks have tightened.
The EU F-Gas Regulation and REACH compliance frameworks compel machinery OEMs to eliminate hydrofluorocarbon-based sterilization cooling and validate paperboard adhesive chemistries for recyclability. FDA pasteurized milk ordinance standards in the United States shape equipment validation protocols for interstate dairy distribution. China's SAMR enforces GB standards for food-contact materials that dictate laminate barrier specifications in carton structures. Stakeholders must monitor diverging national packaging waste collection targets to align machinery design with emerging extended producer responsibility obligations.
Market Dynamics
EU F-Gas Regulation compliance deadlines are compressing replacement cycles for sterilization cooling systems across European dairy and juice operations, forcing capital redeployment toward electron-beam and hydrogen peroxide alternatives.
Growth Catalysts
- ASEPTECH Expansion:Southeast Asian dairy cooperatives are installing extended-shelf-life carton lines to bypass cold-chain infrastructure gaps in Indonesia, Vietnam, and the Philippines.
- EU Green Deal Packaging Mandates:The bloc's recyclability targets for fiber-based containers are accelerating machinery retrofits that handle tethered-cap and mono-material carton structures.
- Functional Beverage Startups:Plunger filling systems are capturing demand from oat milk and probiotic drink producers needing flexible low-volume production runs.
Market Restraints
- Laminate Raw Material Concentration:Barrier film and aluminum foil supply for carton substrates concentrates among a narrow base of European and East Asian chemical suppliers.
- Electron-Beam Validation Costs:FDA and EMA sterilization protocol approvals for beam-based aseptic systems impose multi-year capital lockup before commercial deployment.
- Reusable Bottle Substitution:Deposit-return schemes for glass and PET in Germany, Sweden, and Switzerland are capturing share from single-use carton formats in certain beverage categories.
Strategic Opportunities
- Brazilian Juice Retrofit Wave:Domestic bottlers are converting PET lines to fiber-based carton systems ahead of extended producer responsibility obligations taking effect in 2025-2027.
- China SAMR Barrier Standards:GB food-contact material rules are creating demand for upgraded laminate validation equipment that OEMs can bundle with filling machinery sales.
- Digital Twin Integration:Convergence of IoT sensors and predictive maintenance software is opening service-revenue streams for machinery vendors managing distributed dairy cooperative fleets.
Industry Challenges
- Electron-Beam Technician Scarcity:Specialized skills for high-voltage sterilization system maintenance remain concentrated among a limited pool of trained engineers in Western Europe and Japan.
- Legacy Wet-End Integration:Retrofitting aseptic carton modules into existing dry-end handling lines without halting production requires complex phasing that stretches project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Beverage Carton Packaging Machinery Market |
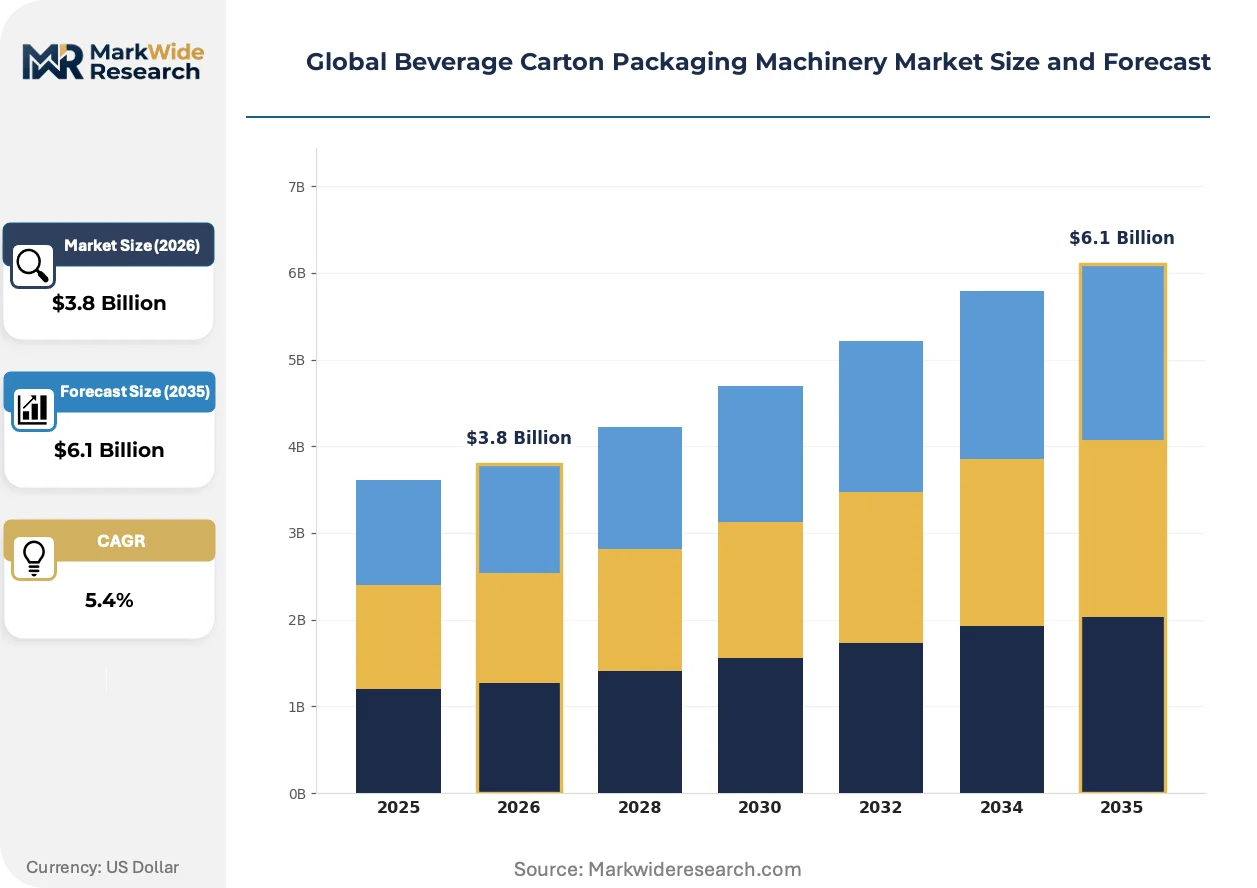
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.1 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Machine Type: Filling Machines, Sealing Machines, Capping Machines, Labeling Machines, Coding Machines Technology: Plunger Filling, Piston Filling, Rotary Filling, Vacuum Filling, Gravity Filling, Aseptic Filling Application: Juice Packaging, Dairy Packaging, Water Packaging, Alcoholic Beverage Packaging, Tea & Coffee Packaging End User: Beverage Producers, Contract Packagers, Bottling Companies, Private Labelers, Food Service Providers |
| Companies Covered | Tetra Pak, SIG Combibloc, Elopak, Krones AG, KHS GmbH, Syntegon Technology GmbH, Robert Bosch Packaging Technology GmbH, Sidel, RA Jones, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Beverage Carton Packaging Machinery Market Shifts & Advancements
Equipment intelligence and sterilization chemistry are converging to redefine how carton packaging machinery preserves product integrity while meeting tightening emissions and material rules.
Electron-beam sterilization is rewriting the capital deployment calculus for extended-shelf-life dairy producers. The technology eliminates hydrogen peroxide residues and reduces water consumption in aseptic filling environments. Major dairy cooperatives in the Netherlands and New Zealand are piloting beam-based lines for premium organic milk segments. This shift is compressing the installed base of legacy chemical sterilization systems and redistributing maintenance revenue toward high-voltage engineering specialists.
REACH adhesive validation requirements are forcing machinery OEMs to requalify paperboard lamination chemistries for recyclability. The regulation mandates disclosure of substances of very high concern in food-contact materials. Equipment suppliers must now certify that heating and sealing modules do not degrade approved adhesive structures during production. German and French packaging machinery builders are responding by embedding real-time temperature monitoring to demonstrate compliance during audits.
After-sales service unbundling is fragmenting how Brazilian and Mexican juice bottlers contract for line maintenance. Buyers are separating spare parts procurement from technical support, sourcing components through third-party channels while retaining OEMs only for critical sterilization module servicing. This pattern is most visible among mid-size private-label producers in São Paulo and Guadalajara seeking to reduce total cost of ownership on retrofit carton lines.
Global Beverage Carton Packaging Machinery Market Segmentation
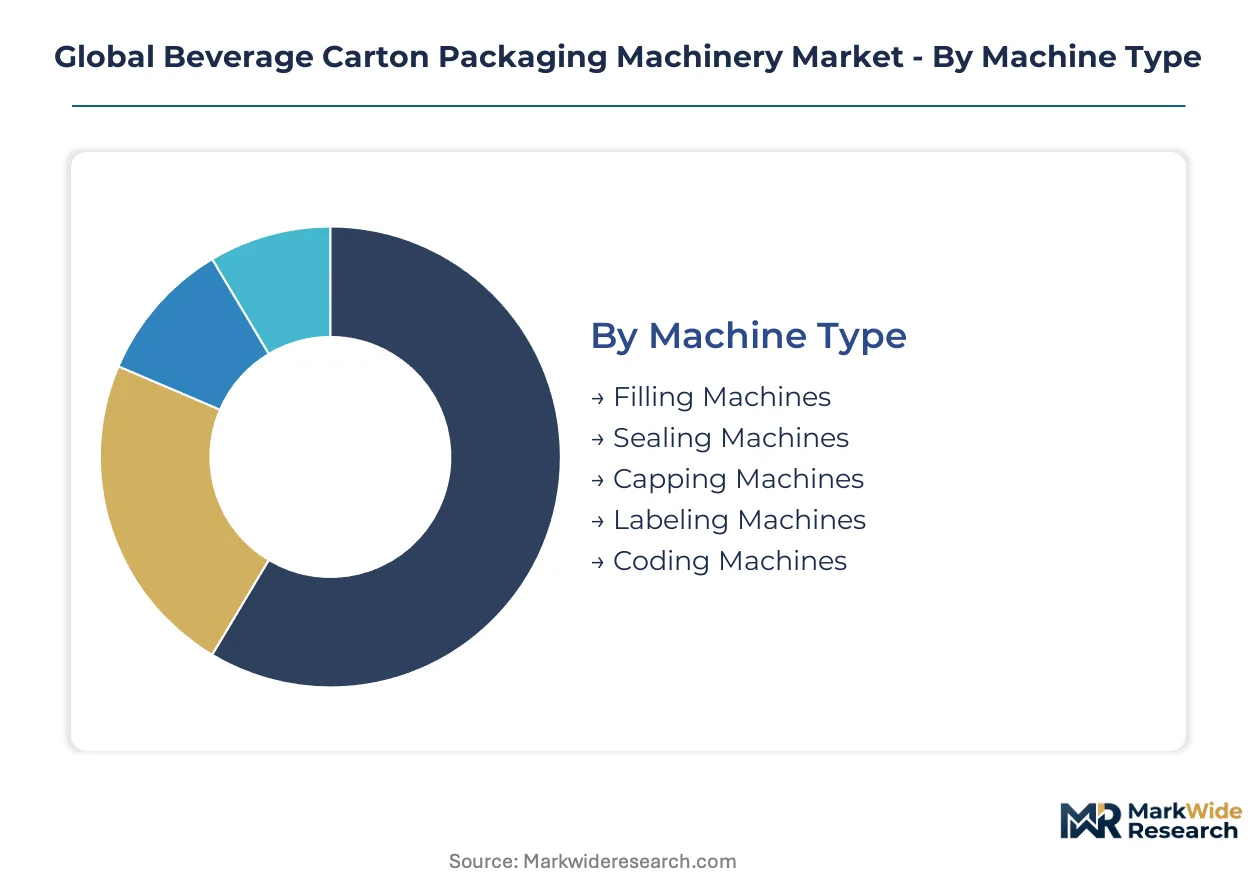
Carton packaging machinery segments diverge sharply between high-speed aseptic systems for shelf-stable dairy and flexible equipment serving functional beverage startups. Technology choices determine capital intensity, regulatory compliance pathways, and aftermarket service revenue potential across each tier.
Machine Type:
Volume concentration sits with filling and sealing modules where line speed and sterility validation drive procurement decisions. Premium margin pools concentrate in coding and labeling systems serving traceability mandates.
- Filling Machines:Core line equipment meters liquid into formed cartons at speeds exceeding 24,000 units per hour. Dairy cooperatives across the Netherlands and New Zealand prioritize aseptic filling modules for extended-shelf-life organic milk segments. Today's leader: Filling Machines. Tomorrow's challenger: Sealing Machines.
- Sealing Machines:Hermetic integrity modules apply heat and pressure to laminate structures, with real-time temperature monitoring now mandatory under REACH adhesive validation rules. Juice bottlers in Brazil retrofitting PET lines demand sealing systems compatible with tethered-cap mono-material cartons ahead of extended producer responsibility deadlines.
- Capping Machines:Equipment securing tethered closures to meet EU single-use plastics directives, with SIG Combibloc advancing integrated cap-application systems.
- Labeling Machines:High-speed applicators handling fiber-based substrate adhesion, critical for private-label juice brands in São Paulo and Guadalajara.
- Coding Machines:Traceability systems embedding lot and expiration data, increasingly bundled with predictive maintenance software for distributed dairy cooperative fleets.
Equipment buyers weight total cost of ownership differently across tiers: filling and sealing dominate upfront capital, while coding and labeling determine compliance audit outcomes.
Technology:
Application requirements split technologies between sterile shelf-stable dairy and ambient-sensitive functional beverages. Sterilization chemistry—hydrogen peroxide, electron-beam, or plunger-based—shapes both regulatory approval timelines and water consumption profiles.
- Aseptic Filling:Hydrogen peroxide or electron-beam sterilization systems preserving microbiological stability in non-refrigerated distribution. Southeast Asian dairy cooperatives in Indonesia, Vietnam, and the Philippines install these lines to bypass cold-chain infrastructure gaps. Leading capital deployment reflects premium positioning in extended-shelf-life segments.
- Plunger Filling:Flexible low-volume systems capturing demand from oat milk and probiotic drink producers needing short production runs. Functional beverage startups favor this technology for its rapid changeover capabilities and reduced minimum order quantities.
- Piston Filling:Viscous liquid handling for plant-based drinks with particulate suspension, common in European organic beverage operations.
- Rotary Filling:Continuous-motion high-throughput systems standard in multinational bottler facilities.
- Vacuum Filling:Oxygen-sensitive product preservation, applied in premium juice and tea segments.
- Gravity Filling:Economical still-water and bulk juice applications where sterility requirements permit simpler mechanics.
Electron-beam validation costs compress near-term adoption despite operational advantages; hydrogen peroxide retains installed base dominance while beam-based pilots expand in premium organic segments.
Application:
End-use concentration varies by geography and regulatory pressure. Dairy and juice command technology investment, while water and alcoholic beverages follow packaging format shifts.
- Juice Packaging:Fiber-based carton conversion wave driving retrofit demand, particularly among Brazilian bottlers ahead of 2025-2027 extended producer responsibility obligations. Tethered-cap compatibility and mono-material structures dominate procurement specifications.
- Dairy Packaging:Extended-shelf-life aseptic systems anchor capital deployment, with EU F-Gas Regulation compliance forcing sterilization cooling upgrades toward electron-beam alternatives. Dutch and New Zealand cooperatives pilot beam-based lines for premium organic segments.
- Water Packaging:Still and sparkling applications, with deposit-return schemes in Germany, Sweden, and Switzerland capturing share from carton formats in certain categories.
- Alcoholic Beverage Packaging:Wine and ready-to-drink cocktails, limited by glass bottle tradition in European markets.
- Tea & Coffee Packaging:Ambient liquid concentrates and ready-to-drink formats, growing in Asian markets with convenience consumption patterns.
Dairy and juice applications concentrate machinery OEM R&D spending; water and alcoholic segments follow rather than drive technology roadmaps.
End User:
Customer structure fragments between captive producers investing in integrated lines and outsourced packagers seeking equipment flexibility. Contract relationships reshape service revenue models.
- Beverage Producers:Multinational dairy and juice companies operating dedicated aseptic carton lines, with Tetra Pak and Krones AG anchoring long-term supply relationships. These buyers prioritize throughput reliability and regulatory validation support.
- Contract Packagers:Third-party operators serving multiple brands, demanding rapid changeover capabilities and modular equipment configurations. After-sales service unbundling is most visible here, with São Paulo and Guadalajara mid-size producers separating spare parts procurement from technical support.
- Bottling Companies:Converted PET line operators, particularly in Brazil, retrofitting for fiber-based carton systems.
- Private Labelers:Retail-owned brands driving tethered-cap and recyclability specifications ahead of EU mandates.
- Food Service Providers:Institutional and out-of-home consumption packaging, smaller scale with emphasis on portion control formats.
Captive beverage producers concentrate premium technology adoption; contract packagers and private labelers amplify volume scaling for validated equipment platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Swedish engineering talent and Swiss precision manufacturing anchor European machinery development, while Brazilian equipment retrofit specialists and Indonesian dairy technicians concentrate operational expertise in emerging production zones.
United States
FDA pasteurized milk ordinance standards shape equipment validation protocols for interstate dairy distribution chains. The agency mandates specific sterilization documentation for aseptic carton lines crossing state borders. Midwest dairy cooperatives in Wisconsin and Minnesota retrofit aging filling systems to comply with evolving pasteurization equipment standards.
Germany
EU F-Gas Regulation deadlines compress replacement cycles for sterilization cooling systems across Bavarian and North Rhine-Westphalian dairy operations. REACH adhesive validation requirements force machinery OEMs to requalify paperboard lamination chemistries for recyclability. Engineering clusters around Stuttgart and Düsseldorf embed real-time temperature monitoring to demonstrate compliance during regulatory audits.
Brazil
Domestic juice bottlers convert PET lines to fiber-based carton systems ahead of extended producer responsibility obligations taking effect between 2025 and 2027. ANVISA enforces food-contact material standards that dictate laminate barrier specifications in converted equipment. São Paulo industrial districts concentrate aftermarket service unbundling patterns, with mid-size producers separating spare parts procurement from technical support contracts.
China
SAMR GB standards for food-contact materials create demand for upgraded laminate validation equipment that OEMs bundle with filling machinery sales. Yangtze River Delta dairy processors install extended-shelf-life lines to reduce cold-chain dependency in inland distribution. Shanghai and Suzhou manufacturing zones concentrate domestic machinery assembly capacity serving regional juice and plant-based drink producers.
Netherlands
Dutch dairy cooperatives pilot electron-beam sterilization lines for premium organic milk segments, eliminating hydrogen peroxide residues and reducing water consumption. EU Green Deal packaging mandates accelerate machinery retrofits handling tethered-cap and mono-material carton structures. Wageningen food technology clusters anchor pilot programs validating beam-based aseptic systems before broader European deployment.
Global Beverage Carton Packaging Machinery Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across equipment tiers, creating a bifurcated structure where scale-driven full-line providers anchor multinational supply relationships while modular specialists capture flexible production demand. Market concentration sits at the high end, where integrated aseptic system portfolios sustain technology leadership positions. Three archetypes dominate: diversified packaging conglomerates with beverage machinery divisions, pure-play carton filling specialists, and regional retrofit system integrators. Competitive moves concentrate on strategic partnerships for electron-beam validation and geographic expansion into Southeast Asian dairy markets.
Among diversified European packaging conglomerates, Krones AG and KHS GmbH occupy positions anchoring continental supply through specialized wet-end and dry-end carton handling lines. Tetra Pak exemplifies the integrated aseptic systems specialist, sustaining technology leadership in extended-shelf-life dairy through captive sterilization chemistry expertise. SIG Combibloc sits within the tethered-cap machinery tier, differentiating via focus on EU single-use plastics compliance ahead of regulatory deadlines.
| Leading Market Players |
|---|
| Tetra Pak |
| SIG Combibloc |
| Elopak |
| Krones AG |
| KHS GmbH |
| Syntegon Technology GmbH |
| Robert Bosch Packaging Technology GmbH |
| Sidel |
| RA Jones |
| Others |
Supply & Pricing Matrix
Electron-beam technician scarcity in Western Europe and Japan widens labor-cost differentials between premium aseptic lines and economy-tier chemical sterilization systems, compressing margin spreads for mid-tier OEMs serving Brazilian retrofitters and Southeast Asian dairy cooperatives.
Pricing Analysis
Service bundling fractures across Brazilian and Mexican juice bottling corridors, with mid-size producers unbundling spare parts procurement from technical support contracts to reduce total cost of ownership. Price differentiation hinges on sterilization chemistry validation tier and after-sales service integration depth. Pricing pressure intensifies in legacy hydrogen peroxide segments as EU F-Gas Regulation deadlines accelerate electron-beam upgrade demand. Contract packagers in São Paulo and Guadalajara exhibit highest price sensitivity, while Dutch dairy cooperatives piloting beam-based organic milk lines show lowest.
Supply Chain Analysis
Ocean freight volatility from German and Swiss precision manufacturing hubs to Southeast Asian dairy installation sites elevates landed cost uncertainty for high-voltage sterilization modules. Barrier film and aluminum foil supply concentrates among narrow European and East Asian chemical suppliers, with laminate substrate production anchored in Germany, Sweden, and China. Single-source vulnerability pervades electron-beam emitter sourcing, where Japanese and Dutch engineering houses control critical high-voltage component fabrication. Distribution runs through OEM-direct channels for multinational beverage producers and third-party system integrators for regional retrofit projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Beverage Carton Packaging Machinery Market represents a late-cycle quality story where electron-beam sterilization validation and tethered-cap compatibility command pricing power as EU Green Deal mandates and F-Gas Regulation deadlines reshape procurement specifications toward premium-tier equipment.
For Market Incumbents: Anticipate accelerated replacement cycles for hydrogen peroxide sterilization cooling systems across European dairy operations by embedding real-time temperature monitoring modules that demonstrate REACH adhesive validation compliance during regulatory audits. Deepen backward integration into high-voltage emitter engineering to offset electron-beam technician scarcity constraining aftermarket service revenue capture in premium organic milk segments.
For New Entrants and Emerging Players: The price-point gap between premium electron-beam aseptic lines and economy-tier plunger filling systems offers white-space entry for modular sterilization retrofit kits targeting Brazilian juice bottlers converting PET infrastructure ahead of extended producer responsibility obligations. Southeast Asian dairy cooperatives in Indonesia and Vietnam present the most penetrable geography given cold-chain infrastructure gaps driving extended-shelf-line investment. Pursue OEM partnership routes that bundle laminate validation equipment with filling machinery sales to accelerate SAMR GB standards compliance.
For Investors and Strategic Acquirers: Diversified packaging conglomerates with beverage machinery divisions are the most active acquirer in this space, seeking electron-beam validation capabilities and Southeast Asian service footprints to complete integrated aseptic system portfolios. Over the medium-term horizon, target acquisition profiles center on regional retrofit system integrators with captive Brazilian or Indonesian customer relationships and proven EU regulatory compliance tooling. The signal to watch is electron-beam pilot program conversion rates among Dutch and New Zealand dairy cooperatives, which indicate premium-tier demand elasticity and validation timeline compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Electron-Beam Sterilization Validation Partnership | EMA and FDA protocol approvals compress multi-year capital lockup timelines for beam-based aseptic deployment. |
| Tethered-Cap Machinery Retrofit Program | EU single-use plastics directives ahead of regulatory deadlines anchor SIG Combibloc's differentiated positioning. |
| Southeast Asian Dairy Cooperative Fleet Service | IoT sensor convergence with predictive maintenance software opens recurring revenue streams for distributed installations. |
| Backward Integration into High-Voltage Emitter Engineering | Japanese and Dutch engineering house concentration creates captive supply vulnerability for sterilization module OEMs. |
| Digital Twin Integration for Line Optimization | Real-time temperature monitoring demonstrates REACH adhesive validation compliance during regulatory audits. |
Research Methodology
Multiple input streams — machinery OEM technical documentation, regulatory filing analysis, and aftermarket service contract review — were reconciled against primary interviews with plant engineers, procurement leads at beverage producers, aftermarket service heads, and dairy cooperative operations managers. Secondary validation drew from EU F-Gas Regulation implementation timelines, SAMR GB standards documentation, ANVISA food-contact material filings, and customs records for barrier film and aluminum foil trade flows. Bottom-up equipment installation tracking and top-down beverage packaging capacity modeling were triangulated to ensure segment-level consistency.
Data-stream reconciliation across machine type, technology, application, and end-user dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from installed base turnover rates, replacement cycle compression effects from regulatory deadlines, and penetration assumptions for electron-beam sterilization in premium organic segments. Forecast inputs incorporated EU Green Deal packaging mandate implementation schedules, Southeast Asian cold-chain infrastructure investment gaps, and Brazilian extended producer responsibility obligation phase-in patterns.
Caveats apply where electron-beam validation timeline extensions, laminate raw material supply disruptions, or reusable bottle deposit-return scheme acceleration could materially shift the outlook. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cartons
North America Corrugated Boxes Market
Cartons
Tuck Top Box Market
Cartons
Folding Cartons Market
Cartons
Global Printed Cartons Market
Cartons
Pick and Place Carton Packers Market
Cartons
Asia Pacific Folding Carton Market
Cartons
Carton Sealer Machine Market
Cartons
Thailand Folding Carton Packaging Market
Cartons
Tablet Cartons Market
Cartons
Fluted Carton Trays Market
Cartons
Horizontal Cartoning Machines Market
Cartons
Carton Bottle Market
Cartons
Carton Display Market
Cartons
Africa Folding Carton Market
Cartons
Japan Corrugated Boxes Market
Cartons
Self - Adhesive Carton Window Patch Machine Market