
 PET Lidding Films Market | 2026-2036
PET Lidding Films Market Size, Share, and Industry Trends Forecast 2026-2036
PET Lidding Films Market Outlook
Peelable-grade specifications is bifurcating the competitive landscape into high-barrier specialists and commodity converters. Amcor plc leverages its global tray-sealing film footprint to sustain volume leadership across chilled dairy and prepared protein segments. Berry Global Inc. differentiates through in-house resin compounding and multi-layer coextrusion capabilities that anchor its position in modified-atmosphere applications. Sealed Air Corporation specializes in resealable lidding systems for retail-ready formats, competing on seal integrity and line-speed compatibility.
PET lidding films are biaxially oriented or cast polyethylene terephthalate sheets, typically 25–50 microns thick, engineered with heat-seal or cold-seal coatings to hermetically close rigid or semi-rigid trays. Their primary purpose is to preserve shelf life, enable tamper evidence, and support consumer convenience features such as peelability and resealability. Heat-seal formulations dominate current volume owing to their compatibility with CPET and APET tray substrates across high-speed form-fill-seal lines. Resealable constructions represent the fastest-expanding segment as retailers demand extended home-use functionality and reduced food waste. Cold-seal variants occupy a narrower but higher-margin niche in temperature-sensitive pharmaceutical blister and chocolate confectionery applications.
EMA food-contact regulations, EU REACH substance restrictions, and F-Gas Regulation phase-down mandates collectively tighten material compliance burdens for European converters while accelerating substitution toward mono-material recyclable constructions. FDA food-contact notification requirements and state-level extended producer responsibility laws in California and New York impose parallel compliance costs on North American suppliers. Stakeholders must monitor evolving mono-material recyclability certifications and deposit-return scheme expansions to anticipate which seal-layer chemistries will retain market access.
Market Dynamics
Tray-sealing automation in European protein processing is compressing order cycles and forcing converters toward just-in-time film supply contracts with penalty clauses for line stoppages.
Growth Catalysts
- EU F-Gas Regulation phase-down:Refrigerant restrictions accelerate demand for high-barrier lidding that extends shelf life without controlled-atmosphere cooling, favoring advanced PET constructions.
- Modified-atmosphere packaging:Retailers in Germany and France mandate extended-case-life specifications for fresh poultry and red meat, pulling film specifications toward oxygen-scavenging seal layers.
- Tray-sealing line speeds:Form-fill-seal equipment operating above 120 cycles per minute requires cold-seal compatible films that reduce thermal stress on heat-sensitive contents.
Market Restraints
- Ethylene glycol feedstock volatility:Crude-linked purified terephthalic acid pricing swings compress converter margins and deter long-term contract commitments.
- Specialty adhesive concentration:Heat-seal coating chemistry relies on a narrow supplier base concentrated in southern Germany and northern Italy, creating single-source vulnerability.
- Multi-layer incompatibility with mechanical recycling:EVOH and PA barrier layers complicate mono-material sorting streams, exposing converters to EU Extended Producer Responsibility penalties.
Strategic Opportunities
- Pharmaceutical cold-seal adoption:Temperature-sensitive blister packs for biologics represent an underpenetrated niche where PET lidding displaces PVC and aluminum laminates.
- Digital printing integration:Inline variable-data decoration enables short-run SKU proliferation for regional dairy brands without plate changeover costs.
- Deposit-return scheme alignment:Germany's DRS expansion to food-contact packaging creates preferential market access for films certified through Interseroh and Der Grüne Punkt streams.
Industry Challenges
- Multi-layer coextrusion technician scarcity:Operating seven-layer blown film lines requires specialized training that regional vocational programs have not scaled to match equipment installation rates.
- Migration testing timelines:EU 10/2011 compliance for novel seal-layer additives extends certification cycles to 18-24 months, delaying product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PET Lidding Films Market |
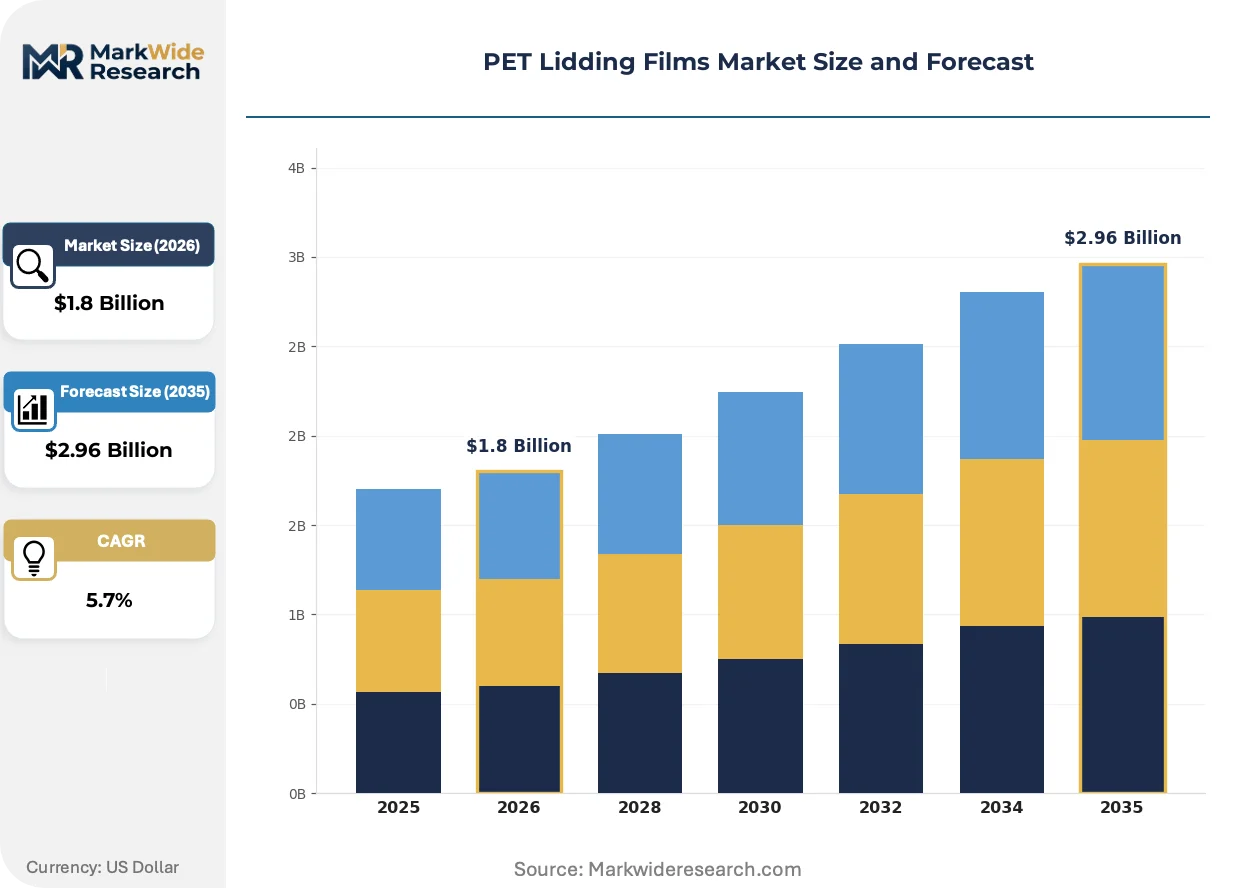
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heat Seal, Cold Seal, Pealable, Resealable Material: Polyethylene, Polypropylene, PET, Aluminium Application: Food Packaging, Pharmaceutical, Consumer Goods, Electronics End User: Manufacturers, Retailers, Distributors, Food Service |
| Companies Covered | Amcor plc, Sealed Air Corporation, Berry Global Inc., Klöckner Pentaplast, Constantia Flexibles, Cosmo Films Ltd, WINPAK Ltd., PLASTOPIL, Parkside Flexibles, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PET Lidding Films Market Strategic Shifts
Digitalization of packaging workflows and regulatory pressure on material circularity are converging to reshape converter R&D priorities and capital allocation across the value chain.
Mono-material recyclable constructions are bifurcating the technical landscape between commodity converters and barrier specialists. Retailers in France and the Netherlands now specify Interseroh-certified mono-PET lidding for private-label ready meals. This specification shift is compressing demand for traditional multi-layer laminates while creating margin pools for converters with in-house resin alloying capabilities.
REACH substance restrictions on per- and polyfluoroalkyl substances are eliminating conventional grease-resistant coatings from food-contact applications. ECHA's 2023 PFAS restriction proposal forces converters to validate silicone-based and bio-based alternatives through migration testing protocols. Chilled dairy applications in Scandinavia are most exposed, with several processors accelerating qualification timelines to secure supply continuity.
Resealable lidding systems are displacing single-use peelable formats in premium protein and cheese segments. Retailers in Germany and Austria now specify home-use functionality as a listing condition for extended-case-life products. This preference shift concentrates volume with converters possessing laser-scoring and micro-perforation capabilities integrated into slitting operations.
PET Lidding Films Market Segmentation
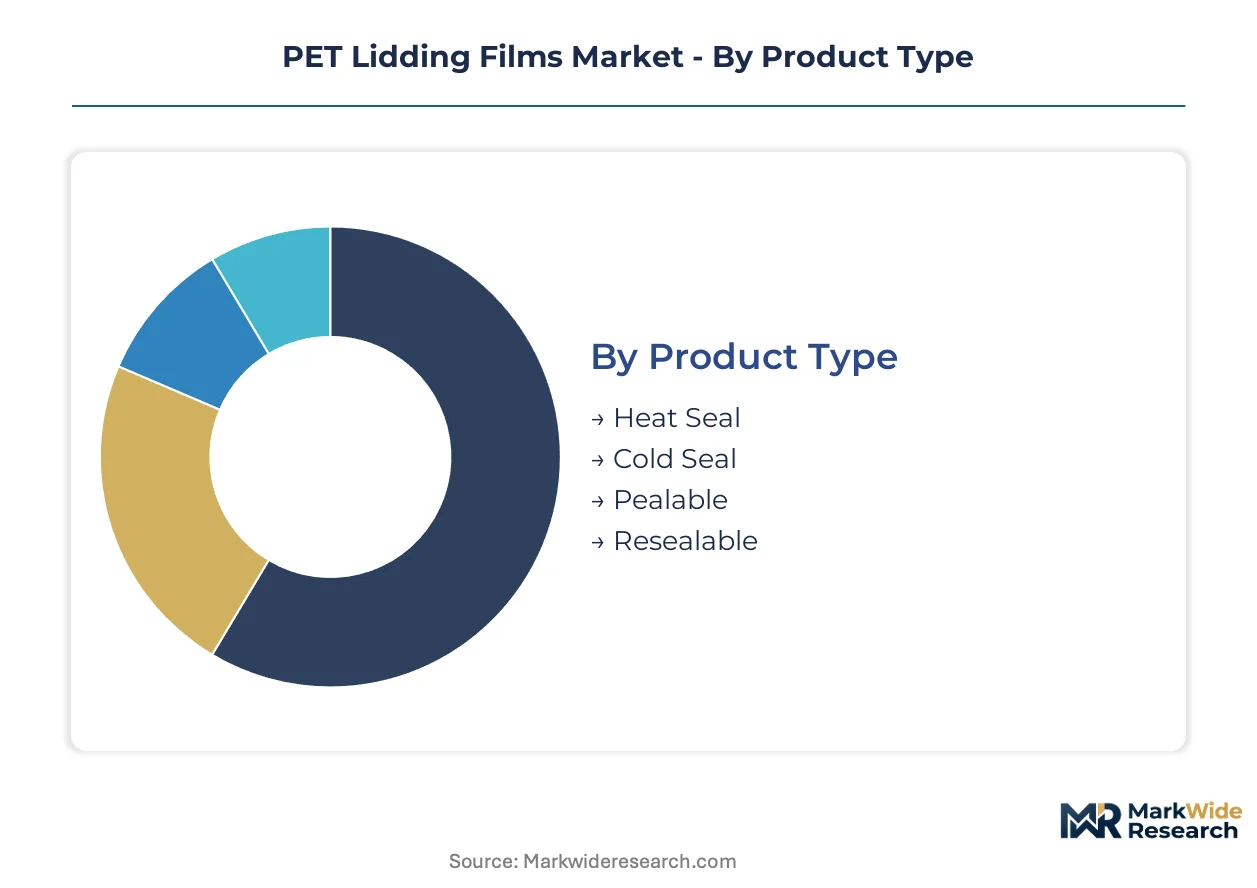
PET lidding films serve divergent performance requirements across seal technologies, substrate compatibilities, and end-use specifications. Segmentation reveals where converters capture premium pricing versus commodity volume, and which material constructions face regulatory displacement.
Product Type:
Margin pools concentrate in functional seal layers that enable line-speed gains or extended shelf-life claims.
- Heat Seal:Biaxially oriented PET sheets with thermal-activated adhesive layers bond to CPET and APET trays at temperatures above 120°C. German poultry processors and French dairy cooperatives specify heat-seal lidding for form-fill-seal lines operating above 100 cycles per minute, where seal integrity failures trigger automatic rejection and line stoppage penalties.
- Resealable:Laser-scored films with pressure-sensitive adhesive strips enable multiple open-close cycles for retail-ready protein and cheese formats. Austrian retailers now mandate home-use functionality as a listing condition for premium private-label SKUs, concentrating demand with converters possessing integrated micro-perforation and slitting capabilities.
- Cold Seal:Pressure-sensitive coatings activate without heat, serving temperature-sensitive pharmaceutical blisters and chocolate confectionery where thermal stress degrades product integrity.
- Peelable:Controlled-adhesion formulations enable clean separation from tray flanges without residue, standard for ready-to-eat meals and single-serve dairy portions where consumer convenience drives repeat purchase.
The dominant share belongs to Heat Seal, while Resealable is closing the gap fastest.
Material:
Substrate selection tracks regulatory pressure on recyclability and feedstock cost exposure.
- PET:Biaxially oriented or cast polyethylene terephthalate dominates volume through compatibility with existing tray-sealing infrastructure and emerging mono-material recycling streams certified through Interseroh and Der Grüne Punkt.
- Polyethylene:Lower-cost sealant layers in multi-laminate constructions face mounting pressure from EU Extended Producer Responsibility schemes that penalize non-recyclable multi-material combinations.
- Polypropylene:Enhanced thermal resistance suits retort applications and high-temperature fill operations where PET deformation risks compromise seal geometry.
- Aluminium:Foil laminates deliver absolute barrier performance for oxygen-sensitive pharmaceuticals and extended-shelf-life military rations, though mechanical recycling incompatibility narrows addressable market access.
PET commands the installed base, while Polypropylene is expanding most quickly in retort-ready segments.
Application:
End-use concentration determines barrier specification intensity and certification burden.
- Food Packaging:Modified-atmosphere specifications for fresh meat and chilled dairy pull film constructions toward oxygen-scavenging seal layers and EVOH barrier coatings, with German retailers mandating extended case life as a procurement condition.
- Pharmaceutical:Cold-seal PET lidding displaces PVC and aluminium laminates in temperature-sensitive biologic blister packs, where EU REACH substance restrictions on halogenated materials accelerate substrate substitution timelines.
- Consumer Goods:Cosmetic and personal care applications prioritize clarity and printability over barrier performance, with shorter qualification cycles and lower migration testing burdens than food-contact or pharmaceutical grades.
- Electronics:Anti-static and moisture-barrier specifications for semiconductor and component packaging represent a specialty niche with concentrated demand from German automotive electronics clusters.
Food Packaging holds the volume concentration, though Pharmaceutical is gaining share fastest on regulatory-driven material substitution.
End User:
Procurement authority shapes contract structure and technical service intensity.
- Manufacturers:Protein processors and dairy cooperatives in Germany and France specify film performance through direct converter relationships with penalty clauses for supply interruption, compressing order cycles toward just-in-time delivery.
- Retailers:Private-label ready-to-eal meal programs in the Netherlands and Scandinavia now mandate Interseroh-certified mono-PET constructions, shifting specification authority from processors to retail technical teams.
- Distributors:Regional packaging wholesalers aggregate fragmented food-service demand with limited technical specification influence, capturing margin through logistics rather than formulation expertise.
- Food Service:Central kitchen and contract catering operations prioritize cost minimization over extended shelf-life functionality, with lower barrier requirements and higher price elasticity than retail-facing segments.
Manufacturers retain the dominant procurement volume, while Retailers are consolidating specification authority most aggressively.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Food service buyers in Southern Europe exhibit acute price sensitivity, while German retailers absorb premium pricing for certified mono-material constructions. This elasticity divergence shapes converter investment allocation across the continent.
Germany
Tray-sealing automation in poultry and red meat processing drives specification intensity for oxygen-scavenging seal layers. The F-Gas Regulation phase-down accelerates demand for high-barrier films that extend shelf life without controlled-atmosphere cooling. The Rhine-Main packaging cluster around Frankfurt anchors converter R&D for mono-PET recyclable constructions.
France
Private-label ready-to-eal meal programs mandate Interseroh-certified mono-PET lidding, shifting specification authority from processors to retail technical teams. REACH substance restrictions on PFAS grease-resistant coatings force accelerated validation of silicone-based alternatives. The Lyon-Auvergne dairy corridor concentrates cold-seal qualification activity for chilled applications.
Netherlands
Deposit-return scheme expansion to food-contact packaging creates preferential market access for Der Grüne Punkt-certified films. Retailer procurement consolidation compresses order cycles toward just-in-time supply contracts with line-stoppage penalties. The Rotterdam port logistics hub facilitates resin import flows for regional converter operations.
Italy
Specialty adhesive supply concentration in northern Italy creates single-source vulnerability for heat-seal coating chemistry. Modified-atmosphere specifications for fresh pasta and prepared sauces pull film constructions toward EVOH barrier layers. The Bologna-Modena packaging machinery corridor integrates film supply with form-fill-seal equipment OEMs.
United Kingdom
Post-Brexit divergence from EU 10/2011 migration testing timelines extends certification cycles for novel seal-layer additives. Retailer sustainability mandates drive substitution toward mechanically recyclable mono-material constructions. The Midlands food manufacturing belt concentrates tray-sealing automation investment for chilled ready meals.
PET Lidding Films Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the value chain. The market structure consolidates around integrated resin compounders with captive seal-layer formulation capabilities, while regional converters compete on logistics proximity and short-run flexibility. Three archetypes dominate: global film specialists with multi-layer coextrusion scale, mid-tier European converters with retailer certification relationships, and Asia-Pacific volume producers serving commodity segments. Competitive moves concentrate on backward integration into resin alloying and strategic partnerships with tray-sealing equipment OEMs.
Within the global specialist tier, Amcor plc and Sealed Air Corporation occupy positions defined by tray-sealing film scale and resealable system integration respectively. Berry Global Inc. exemplifies the integrated compounder archetype through in-house resin capabilities. These three entities anchor the premium specification segment where retailer certification requirements create defensive moats against commodity competition.
| Leading Market Players |
|---|
| Amcor plc |
| Sealed Air Corporation |
| Berry Global Inc. |
| Klöckner Pentaplast |
| Constantia Flexibles |
| Cosmo Films Ltd |
| WINPAK Ltd. |
| PLASTOPIL |
| Parkside Flexibles |
| Others |
Value Chain & Pricing Dynamics
Interseroh and Der Grüne Punkt certifications gate supply qualification for German retailers while simultaneously enabling 15-25% price premiums over uncertified mono-PET alternatives. This dual function compresses margin pools for commodity converters unable to fund certification timelines while concentrating pricing power with integrated compounders possessing in-house resin alloying capabilities.
Pricing Analysis
After-sales technical service contracts and line-integration support drive lifetime value beyond base film supply. Pricing stratifies across premium, standard, and economy tiers based on certification grade and seal-layer complexity. Cost compression in standard-grade heat-seal constructions intensifies as Asian volume producers expand European distribution. Food-service buyers in Southern Europe exhibit acute price sensitivity, while German retailers absorb premiums for certified mono-material supply.
Supply Chain Analysis
Inventory cycles have compressed to 7-10 days for just-in-time tray-sealing operations, with line-stoppage penalties forcing converters toward regional warehousing. Feedstock supply concentrates in Germany, Belgium, and the Netherlands through integrated PTA-PET operations. Specialty adhesive chemistry draws from a narrow supplier base concentrated in southern Germany and northern Italy. Single-source vulnerability in heat-seal coating inputs exposes converters to supply interruption risk. Distribution runs through converter-direct relationships with protein processors and dairy cooperatives, bypassing traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Retailer procurement consolidation across Germany, France, and the Netherlands has shifted specification authority from processors to retail technical teams, compressing converter margins while elevating certification requirements as competitive barriers.
For Market Incumbents: Secure backward integration into resin alloying to defend margin position against commodity Asian imports. Lock in multi-year just-in-time supply contracts with penalty structures that deter customer switching. Invest in laser-scoring and micro-perforation capabilities to capture resealable specification premiums as Austrian and German retailers mandate home-use functionality.
For New Entrants and Emerging Players: Anchor in pharmaceutical cold-seal applications where REACH-driven PVC displacement creates white-space opportunity with lower incumbent concentration. Target Scandinavian chilled dairy processors accelerating PFAS-free coating qualification timelines. Lead with digital printing integration for short-run SKU proliferation serving regional dairy brands.
For Investors and Strategic Acquirers: EU F-Gas Regulation phase-down reshapes the acquisition landscape by elevating high-barrier film specialists over commodity converters dependent on controlled-atmosphere cooling infrastructure. Target mid-tier European converters with established retailer certification relationships and captive seal-layer formulation capabilities. Watch migration testing timeline extensions under EU 10/2011 as a signal for product launch delays that could strain working capital.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Alloying | Captures margin pools in mono-PET recyclable constructions certified through Interseroh streams. |
| Digital Printing Capability Addition | Enables short-run SKU proliferation for regional dairy brands without plate changeover costs. |
| Laser-Scoring and Micro-Perforation Investment | Secures resealable specification premiums as German retailers mandate home-use functionality. |
| Pharmaceutical Cold-Seal Qualification | Displaces PVC and aluminum laminates in temperature-sensitive biologic blister packs under REACH pressure. |
| Deposit-Return Scheme Alignment | Creates preferential market access for Der Grüne Punkt-certified films as Germany expands DRS coverage. |
Study Parameters
Initial hypotheses were tested against primary input from tray-sealing equipment OEMs, converter plant managers, retail packaging specification leads, and protein processor procurement directors, and refined through secondary validation against customs trade data, EU F-Gas Regulation implementation reports, SEC filings from listed packaging groups, and Interseroh certification databases. Bottom-up volume estimates from film gauge and line-speed assumptions were triangulated against top-down addressable market calculations.
Variance decomposition across seal technology, substrate compatibility, and end-use specification dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level volume trajectories weighted by pricing tier concentration. Forecast inputs incorporated tray-sealing automation rates, EU Extended Producer Responsibility penalty schedules, and REACH substance restriction timelines.
Decision-makers should treat outputs as directional under assumptions of sustained EU regulatory enforcement and stable ethylene glycol feedstock availability; material deviation would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Asia-Pacific Ethylene-Vinyl Alcohol Copolymer (EVOH) Packaging Films Market
Poly film
EVOH Encapsulation Film Market
Poly film
Thermoforming Films Market
Poly film
High Density Polyethylene Film Market
Poly film
Global BOPP Films Market
Poly film
Laminating Film Market
Poly film
Synthetic and Bio Thermoplastic Polyurethane (TPU) Films Market
Poly film
Timber Wrap Films Market
Poly film
India BOPP Films Market
Poly film
Polystyrene Films Market
Poly film
Surface Printed Film Market
Poly film
Soft Touch Lamination Film Market
Poly film
Global Biaxially Oriented Polypropylene (BOPP) in Films and Sheets Market
Poly film
Blown Film Extruder Market
Poly film
PCR Bubble Films Market
Poly film
Global Polyethylene Packaging Market