
 Polyethylene Film Market | 2026-2036
Polyethylene Film Market Size, Share, and Industry Trends Forecast 2026-2036
Polyethylene Film Market Analysis
Market Dynamics
Subscription-based film supply contracts with embedded recycling take-back clauses is rebalancing how resin converters monetize customer relationships. Berry Global Inc. leverages its North American blown film capacity to anchor long-term supply agreements with private-label food brands. Amcor plc sustains margin through specialized healthcare film certifications that command premium pricing. Mondi plc competes via integrated kraft paper-polyethylene hybrid solutions that reduce overall packaging weight.
Product Landscape
Polyethylene film comprises extruded thermoplastic sheets ranging from 0.5 mil to 10 mil thickness, manufactured through blown or cast processes using ethylene polymers with densities from 0.910 to 0.965 g/cm³, serving primarily as moisture barriers, protective layers, and flexible containment systems across industrial and consumer applications. LLDPE films dominate flexible food packaging due to superior puncture resistance and downgauging potential that reduces material intensity per package. Agricultural mulch films represent a maturing HDPE segment where price competition has compressed margins and shifted volume toward Asian converters.
Regulatory Environment
Europe's REACH regulation and the EU Packaging and Packaging Waste Directive constrain virgin resin ratios in consumer-facing applications, while the FDA governs food-contact compliance in the United States through 21 CFR 177.1520. China's GB standards and India's BIS certification requirements create divergent testing protocols that fragment cross-border product qualification. Stakeholders must monitor evolving extended producer responsibility frameworks and recyclability labeling mandates that will determine which film constructions retain market access.
Market Dynamics
Quick-service restaurant chains are consolidating polyethylene film demand through centralized procurement hubs, compressing supplier margins while favoring converters with multi-site distribution networks and certified recyclate capabilities.
Growth Catalysts
- Food packaging automation:Quick-service restaurant chains are deploying high-speed form-fill-seal lines that favor LLDPE films with consistent gauge tolerances and seal integrity under accelerated cycle times.
- REACH compliance premiums:Europe's ECHA enforcement of certified recyclate streams is creating price premiums for converters with verified post-consumer content documentation and mass-balance accounting.
- India's western corridor concentration:Stretching from Mumbai to Ahmedabad, this industrial belt is attracting blown film capacity to serve domestic food processors and export-oriented pharmaceutical packaging.
Market Restraints
- Ethylene feedstock volatility:Naphtha-cracker margins in Northeast Asia swing with crude oil benchmarks, destabilizing resin contract pricing for film converters locked into annual supply agreements.
- HDPE agricultural commoditization:Asian converters have captured mulch film volume through price competition, eroding margin structures for established suppliers in mature markets.
- Mechanical recycling contamination limits:Multi-layer barrier constructions with EVOH or PA interlayers cannot enter standard mechanical recycling streams, constraining circular economy participation.
Strategic Opportunities
- Pharmaceutical serialization compliance:EU MDR and FDA track-and-trace mandates are expanding demand for high-clarity PE films with embedded authentication layers and tamper-evident features.
- Paper-plastic hybrid formats:Mondi's integrated kraft paper-PE solutions demonstrate weight reduction pathways that meet Amazon's Frustration-Free Packaging certification thresholds.
- Subscription contract structures:Embedded take-back clauses in multi-year supply agreements are converting resin converters into circular service providers with recurring revenue streams.
Industry Challenges
- Multi-jurisdiction certification timelines:Cross-border film qualification requires sequential testing against FDA 21 CFR 177.1520, EU 10/2011, and China's GB standards, extending product launch cycles by 8-14 months.
- Blow molding-to-film talent migration:Experienced extrusion technicians are exiting flexible packaging for rigid container operations with cleaner plant environments and more predictable shift schedules.
- Legacy extruder retrofit costs:Converting cast film lines to handle post-consumer recyclate requires screw and die modifications that strain mid-cap converter balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyethylene Film Market |
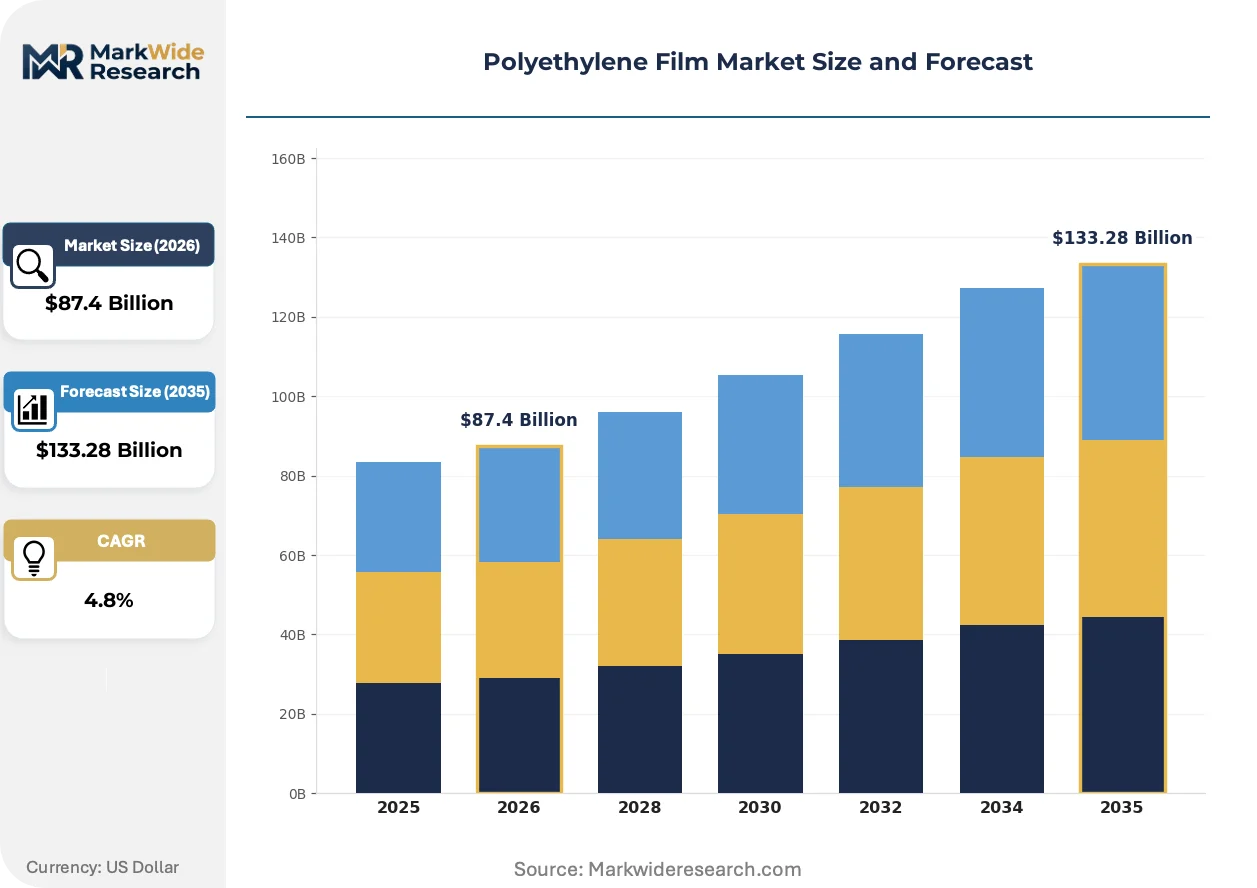
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $133.28 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LDPE, LLDPE, HDPE, mLLDPE Application: Packaging, Agriculture, Construction, Electronics Thickness: Thin, Medium, Thick, Ultra-Thin End User: Food & Beverage, Healthcare, Automotive, Consumer Goods |
| Companies Covered | RKW Group, Sigma Plastics Group, Berry Global Inc., Coveris Holdings S.A., Mondi plc, Amcor plc, Mitsubishi Chemical Group, Intertape Polymer Group Inc., Sealed Air Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyethylene Film Market Emerging Trajectories
Digital watermarking and blockchain traceability are converging with mechanical recycling advances to restructure how polyethylene film value chains authenticate circular claims and access premium price tiers.
Mono-material barrier films with plasma-enhanced surface treatments are unifying oxygen and moisture protection within single-polymer constructions. Food brands in Germany and the Netherlands are specifying these formats to satisfy ECHA recyclability assessments. This unification is compressing demand for conventional multi-layer coextrusions with incompatible polymer combinations.
Europe's Packaging and Packaging Waste Directive is mandating minimum recycled content thresholds for consumer-facing applications. Converters are restructuring supply chains to secure mass-balance-certified resins through chemical recycling partnerships. Flexible food packaging in France and Italy faces the steepest compliance curves as national implementation deadlines precede EU-wide harmonization.
Centralized procurement hubs operated by quick-service restaurant chains are compressing supplier rosters and extending payment terms. Regional distributors with inventory-positioning capabilities are displacing direct mill relationships in the US Southeast and UK Midlands. This concentration is most visible in poultry and produce packaging, where buyers prioritize supply security over resin brand specification.
Polyethylene Film Market Segmentation
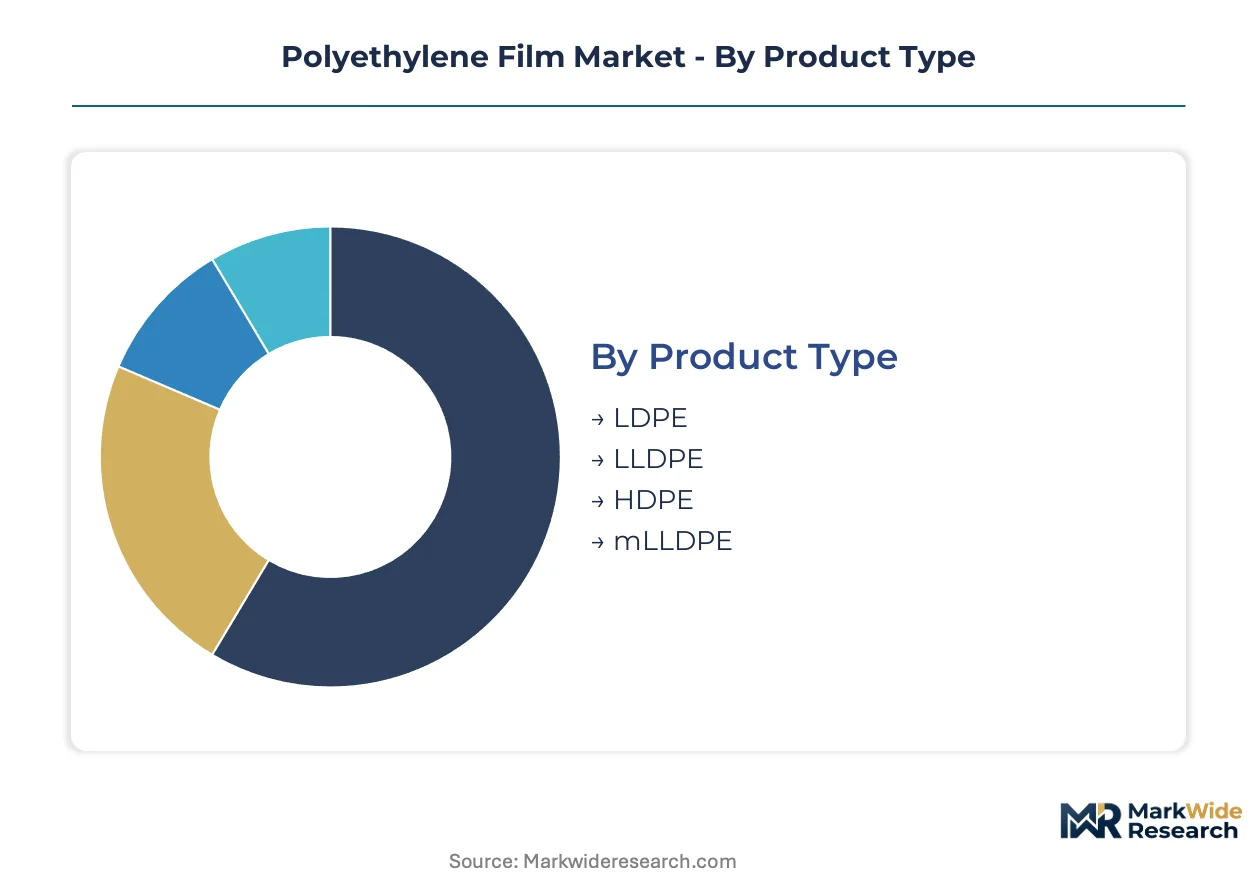
Segmentation in polyethylene film markets reveals how resin density, gauge tolerance, and end-use certification requirements fragment converter capabilities and customer procurement strategies across incompatible specification tiers.
Product Type:
Resin density differentiations concentrate blown film capacity among converters with cracker-adjacent feedstock positions and specialized metallocene catalyst licensing.
- LLDPE:Linear low-density formulations with 0.915-0.925 g/cm³ density and superior puncture resistance dominate quick-service restaurant packaging specifications. Demand concentrates in North American poultry and produce applications where downgauging to 0.8-1.2 mil reduces material intensity per package while maintaining seal integrity under high-speed form-fill-seal automation.
- LDPE:Branched-chain low-density polyethylene manufactured via high-pressure tubular reactors yields films with exceptional clarity and processability. European healthcare packaging specifications favor LDPE for medical device pouches requiring gamma sterilization compatibility, though REACH-compliant recyclate sourcing constrains virgin resin ratios in consumer-facing applications.
- HDPE:High-density grades with 0.941-0.965 g/cm³ density serve agricultural mulch and construction vapor barrier segments where stiffness and moisture resistance outweigh flexibility requirements.
- mLLDPE:Metallocene-catalyzed linear low-density resins enable ultra-thin gauge production with enhanced optical properties for premium food display packaging.
Today's leader: LLDPE. Tomorrow's challenger: mLLDPE.
Application:
End-use diversification separates converters by capital intensity — packaging lines demand multi-layer coextrusion investments while agricultural film runs on simpler monolayer equipment.
- Packaging:Flexible food containment systems ranging from 0.5 mil shrink wrap to 4 mil heavy-duty shipping sacks. Quick-service restaurant chains in the US Southeast and UK Midlands consolidate procurement through centralized hubs that specify certified recyclate content and mass-balance documentation.
- Agriculture:Mulch films, greenhouse sheeting, and silage wrap constitute a volume-driven segment where Asian converters have captured market share through price-competitive HDPE supply.
- Construction:Vapor barriers, concrete curing blankets, and temporary enclosure films require UV stabilization and puncture resistance for jobsite durability.
- Electronics:Anti-static and cleanroom-grade films protect semiconductor components and display panels during assembly and transport.
Packaging commands margin premiums. Agriculture faces steepest price compression.
Thickness:
Gauge stratification aligns with equipment capabilities — thin films demand precision die gap control while thick constructions stress cooling and haul-off systems.
- Thin (below 1 mil):Downgauged LLDPE formulations for lightweight food wraps and overwrap applications. German and Dutch food brands specify these formats to satisfy ECHA recyclability assessments under the EU Packaging and Packaging Waste Directive.
- Medium (1-3 mil):Standard industrial and consumer packaging gauges balancing cost and performance across the broadest converter base.
- Thick (3-6 mil):Heavy-duty shipping sacks, drum liners, and protective sheeting for construction and industrial markets.
- Ultra-Thin (below 0.5 mil):Emerging stretch and cling wrap segments enabled by mLLDPE and advanced process control.
Medium gauge retains volume dominance. Ultra-thin formats are climbing the fastest as downgauging accelerates.
End User:
Customer certification requirements fragment the supply base — FDA 21 CFR 177.1520 compliance for food contact, EU MDR serialization for healthcare, and automotive IATF quality systems create non-overlapping converter qualifications.
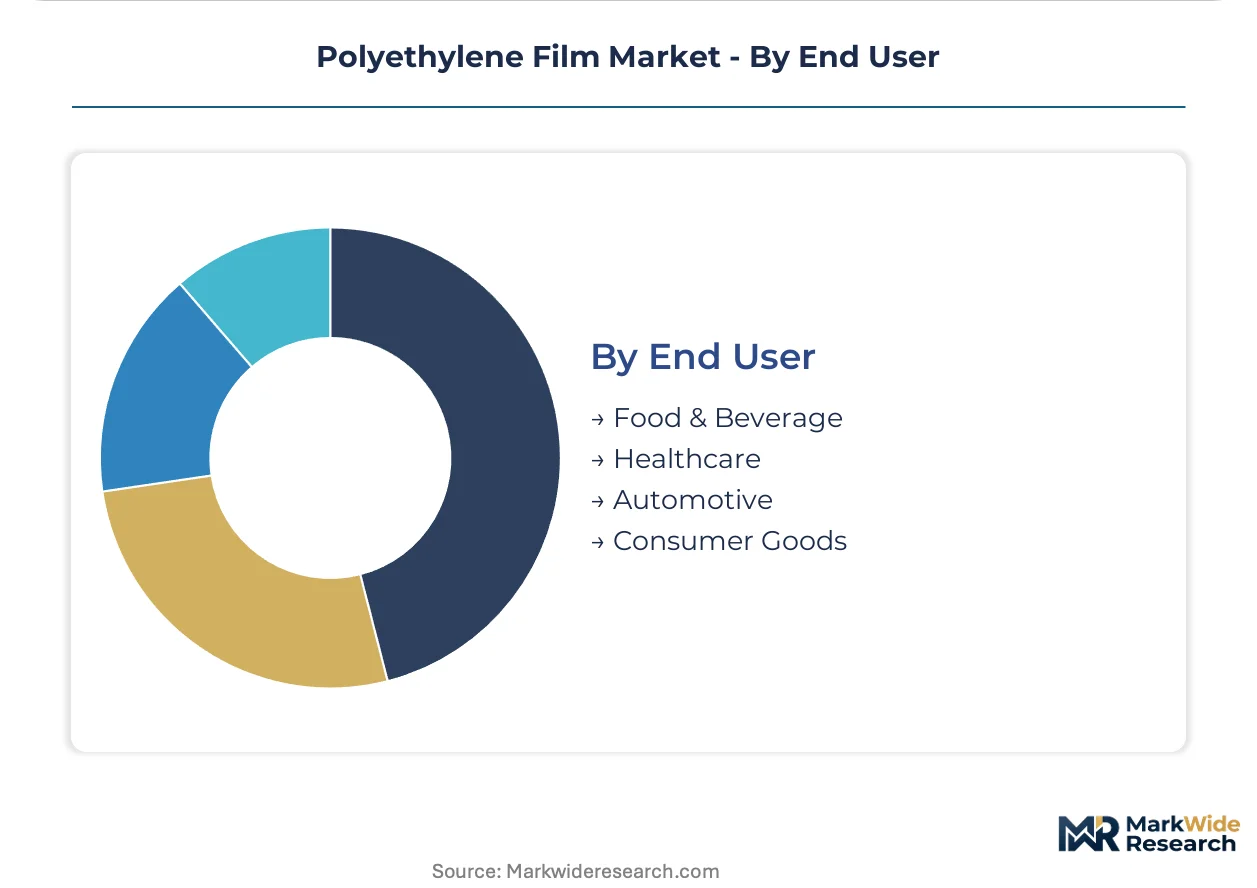
- Food & Beverage:The largest demand concentration spanning fresh produce, processed proteins, and dairy applications. India's western industrial corridor from Mumbai to Ahmedabad attracts blown film capacity to serve domestic food processors and export-oriented pharmaceutical packaging with integrated food-grade and healthcare certifications.
- Healthcare:Sterilizable films with embedded authentication layers and tamper-evident features for EU MDR and FDA track-and-trace mandates. Amcor plc sustains margin through specialized healthcare film certifications that command premium pricing.
- Automotive:Protective films for interior components and exterior paint protection during assembly and transit.
- Consumer Goods:Retail display packaging, e-commerce protective wrap, and household product containment.
Food & Beverage anchors volume. Healthcare delivers margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Converters are relocating blown film capacity toward jurisdictions with lower compliance costs for virgin resin documentation, creating supply-chain arbitrage between REACH-regulated Europe and markets with emerging extended producer responsibility frameworks.
Germany
Food brands in Bavaria and Baden-Württemberg specify mono-material barrier films to satisfy ECHA recyclability assessments under the EU Packaging and Packaging Waste Directive. The country's national chemical regulator enforces mass-balance accounting for post-consumer content claims. The Rhine-Ruhr industrial corridor hosts converters restructuring supply chains to secure certified recyclate streams ahead of national implementation deadlines.
United States
Quick-service restaurant chains in the Southeast consolidate procurement through centralized hubs demanding certified recyclate capabilities and multi-site distribution networks. FDA governs food-contact compliance through 21 CFR 177.1520. The US Gulf Coast petrochemical corridor anchors resin supply for flexible packaging converters serving poultry and produce applications.
China
Domestic food processors and export-oriented pharmaceutical packaging operations drive demand for blown film with integrated certifications. GB standards and SAMR oversight create testing protocols that fragment cross-border product qualification. The Yangtze River Delta concentration attracts capacity serving both local consumption and re-export markets.
India
Domestic food processors and pharmaceutical packaging exporters concentrate demand in the western industrial corridor stretching from Mumbai to Ahmedabad. BIS certification requirements and FSSAI oversight govern film qualifications for food-contact applications. Gujarat's petrochemical infrastructure supports backward-integrated converters with captive resin supply.
Netherlands
German and Dutch food brands specify downgauged LLDPE formats to meet ECHA recyclability thresholds. The country's national chemical regulator enforces REACH documentation for converters accessing premium price tiers. The Rotterdam-Antwerp petrochemical hub supplies resin to flexible packaging operations serving pan-European distribution.
Polyethylene Film Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with food packaging favoring integrated converters and agricultural films tilting toward price-competitive Asian suppliers. The market exhibits tiered concentration: global resin-integrated majors, regional multi-site distributors, and single-plant specialists. Two archetypes dominate—cracker-adjacent converters with feedstock cost advantages, and certification-heavy healthcare specialists commanding premium pricing. Capacity expansion and strategic partnerships represent the dominant competitive moves as firms secure mass-balance resin allocations.
Among diversified packaging conglomerates, Berry Global Inc., Amcor plc, and Mondi plc occupy positions reflecting distinct strategic postures. Berry Global Inc. exemplifies the North American blown film capacity anchor securing long-term supply agreements. Amcor plc represents the healthcare certification specialist sustaining margin through specialized film qualifications. Mondi plc sits within the integrated hybrid-solutions tier demonstrating paper-plastic weight reduction pathways.
| Leading Market Players |
|---|
| RKW Group |
| Sigma Plastics Group |
| Berry Global Inc. |
| Coveris Holdings S.A. |
| Mondi plc |
| Amcor plc |
| Mitsubishi Chemical Group |
| Intertape Polymer Group Inc. |
| Sealed Air Corporation |
| Others |
Supply Flow & Price Mechanics
Centralized procurement hubs operated by quick-service restaurant chains are squeezing supplier margins and extending payment terms, forcing converters to consolidate distribution networks and absorb freight costs to retain volume commitments.
Pricing Analysis
Distributor margins in the US Southeast and UK Midlands compress as regional inventory-positioning capabilities displace direct mill relationships. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale, with REACH-compliant recyclate streams commanding premiums over virgin resin alternatives. Price erosion runs through agricultural mulch films as Asian converters capture share via cost-competitive HDPE supply. Quick-service restaurant chains exhibit highest price sensitivity, while pharmaceutical packaging buyers prioritize compliance documentation over unit economics.
Supply Chain Analysis
Freight cost volatility from Middle East naphtha crackers to European and Indian converters destabilizes landed resin pricing. Supply concentrates in Saudi Arabia, South Korea, and the US Gulf Coast for ethylene feedstock, with blown film extrusion clustering in India's western corridor and Germany's Rhine-Ruhr belt. Raw material dependencies rest on naphtha cracker margins, metallocene catalyst licensing, and mass-balance-certified recyclate allocations. Single-source vulnerability in specialized healthcare film certifications creates supply chain risk. Distribution runs through regional multi-site distributors with certified recyclate capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The polyethylene film market functions as a stable compounder anchored by perpetual food packaging demand from quick-service restaurant chains with recurring replenishment cycles.
For Market Incumbents: Anchor long-term supply agreements through embedded recycling take-back clauses that convert transactional resin sales into recurring service revenue. Defend margin position by securing mass-balance-certified recyclate allocations ahead of EU Packaging and Packaging Waste Directive implementation deadlines. Counter Asian price competition in agricultural films with specialized healthcare certifications that command premium pricing and create switching costs. For New Entrants and Emerging Players: The gap between premium healthcare-certified films and economy-grade agricultural mulch creates white-space opportunity in mid-tier food packaging with verified post-consumer content. Target India's western industrial corridor from Mumbai to Ahmedabad, where domestic food processors and pharmaceutical exporters concentrate demand and BIS certification barriers remain surmountable. Enter through toll-manufacturing partnerships with cracker-adjacent converters to bypass captive resin cost disadvantages. For Investors and Strategic Acquirers: Asymmetric upside sits with certification-heavy healthcare specialists possessing EU MDR and FDA track-and-trace film capabilities. The five-to-ten year viability window favors converters with integrated kraft paper-PE hybrid solutions that reduce packaging weight and meet Amazon Frustration-Free Packaging thresholds. Monitor ECHA enforcement actions on mass-balance accounting as an inflection indicator for which recyclate documentation standards will determine premium market access.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recyclate Sourcing | Secures mass-balance-certified resin allocations ahead of EU directive implementation deadlines. |
| Healthcare Certification Investment | EU MDR and FDA track-and-trace mandates expand addressable market for high-clarity PE films. |
| Capacity Expansion in India | Gujarat's petrochemical infrastructure supports captive resin supply for western corridor food processors. |
| Long-term Supply Agreement Restructuring | Embedded take-back clauses convert resin converters into circular service providers with recurring revenue. |
| Joint Venture for Mono-Material Barrier Films | Plasma-enhanced surface treatments unify oxygen protection within single-polymer recyclable constructions. |
Methodological Framework
Bottom-up food packaging demand modeling reconciled against top-down ethylene cracker capacity tracking forms the analytical core of this study. Primary interviews with blown film plant managers, quick-service restaurant procurement directors, pharmaceutical packaging quality leads, and resin distribution channel partners combine with secondary validation from customs trade data, SEC 10-K filings of listed packaging conglomerates, and ECHA substance registration databases. Triangulation across these sources ensures demand estimates align with observable supply-side investments.
Historical trendline analysis of LLDPE film gauge downgauging and recyclate content specifications establishes baseline growth patterns across the projection horizon. Segmentation modeling incorporates resin density tier, end-use certification requirements, thickness gauge stratification, and regional regulatory cluster dimensions. CAGRs derive from fitted growth curves adjusted for feedstock cost volatility and extended producer responsibility framework implementation schedules. Forecast inputs include quick-service restaurant chain expansion pipelines and pharmaceutical serialization mandate compliance deadlines.
The model assumes a particular technology adoption path for mono-material barrier films with plasma-enhanced surface treatments; alternative pathways for conventional multi-layer coextrusions with EVOH interlayers would alter the outlook. Forecasts reflect assumptions about REACH enforcement intensity and mechanical recycling contamination limits. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Cast Stretch Packaging Films Market
Poly film
Thermoforming Films Market
Poly film
Italy Plastic Packaging Films Market
Poly film
PVC Film for Medical Market
Poly film
Stretch Films Packs Market
Poly film
Polyethylene Furanoate Films Market
Poly film
Polyolefin Films Market
Poly film
PCR Lidding Films Market
Poly film
Chocolate Wrapping Films Market
Poly film
Global Thermoplastic Films Market
Poly film
Asia-Pacific Ethylene-Vinyl Alcohol Copolymer (EVOH) Packaging Films Market
Poly film
Global Blown Stretch Packaging Films Market
Poly film
Morocco Plastic Packaging Films Market
Poly film
MDO-PE Films Market
Poly film
Brazil Plastic Packaging Films Market
Poly film
Poly Coated Kraft Paper Market