
 Child Resistant Pipette Closures Market | 2026-2036
Child Resistant Pipette Closures Market Size, Share, and Industry Trends Forecast 2026-2036
Child Resistant Pipette Closures Market Outlook
Buyer concentration among pharmaceutical contract packagers is shifting toward integrated suppliers capable of dual-source validation. AptarGroup leverages its push-and-twist technology platform to anchor relationships with multinational drug manufacturers. Berry Global sustains manufacturing scale across North American and European molding facilities. Silgan Holdings competes through backward integration into resin compounding and precision mold fabrication.
Child resistant pipette closures are mechanical dispensing devices engineered with torque-limited engagement mechanisms, typically molded from polypropylene or HDPE with integrated elastomeric seals, designed to prevent access by children under fifty-two months while permitting adult operation. Their primary commercial purpose is to satisfy poison prevention mandates for liquid pharmaceutical, chemical, and cannabis product packaging. Push-and-twist configurations dominate unit volumes due to regulatory familiarity and adult ergonomics, while squeeze-actuated variants capture premium positioning in pediatric and geriatric dosage formats. Plastic resins anchor material demand through cost efficiency and sterilization compatibility, though rubber gasket integration represents a concentrated margin pool for specialized compounders serving laboratory and hospital end users.
The FDA enforces Poison Prevention Packaging Act compliance through standardized child-test protocols that directly determine product certification timelines and market access eligibility. The European Medicines Agency references EN ISO 8317 child-resistant packaging standards within centralized marketing authorization procedures, while REACH chemical restrictions constrain elastomer formulation choices for export-bound closures. Stakeholders must monitor evolving state-level cannabis packaging regulations in the United States and emerging biologic drug delivery formats that demand modified closure geometries.
Market Dynamics
Pharmaceutical contract packagers are consolidating supplier relationships around dual-source validated partners capable of ISO 8317 certification and REACH-compliant elastomer integration, compressing vendor pools while elevating technical qualification thresholds.
Growth Catalysts
- FDA Poison Prevention Packaging Act enforcement:Mandatory child-test protocols for liquid pharmaceuticals are expanding addressable demand for certified push-and-twist closures across over-the-counter and prescription segments.
- German contract manufacturing clusters:Specialized molding facilities in Bavaria and Baden-Württemberg are anchoring European pharmaceutical packaging networks with integrated quality validation.
- HDPE resin sterilization compatibility:Steam and gamma-radiation stable polymers are enabling single-use pipette closure adoption in biologic drug filling lines.
Market Restraints
- Polypropylene feedstock volatility:Propylene monomer price swings from naphtha cracking margins are compressing molding economics for high-volume closure producers.
- Specialized elastomer supply concentration:Medical-grade EPDM and silicone gasket compounders in Germany and Switzerland represent a concentrated margin chokepoint for export-bound manufacturers.
- REACH chemical restriction scope expansion:ECHA candidate list updates for phthalate alternatives are forcing reformulation cycles that extend certification timelines.
Strategic Opportunities
- Cannabis packaging regulation fragmentation:State-level mandates in California, Colorado, and Illinois are creating demand for customizable torque-limited geometries outside traditional pharmaceutical channels.
- Pediatric dosage format premiumization:Squeeze-actuated variants with integrated dose counting are capturing positioning in allergy and cough-cold liquid portfolios.
- ISO 15378 GMP convergence:Pharmaceutical primary packaging material standards are creating certification arbitrage for suppliers with pre-validated quality systems.
Industry Challenges
- Precision mold fabrication skill scarcity:Multi-cavity hot-runner tool design expertise is concentrating among aging German and Austrian toolmaking workforces.
- Dual-source validation timeline compression:Pharmaceutical packagers are demanding parallel qualification of alternate suppliers within 18-month procurement windows.
- Legacy filling line integration friction:Modified closure geometries for biologic formats require capper head retrofits that disrupt validated production schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Child Resistant Pipette Closures Market |
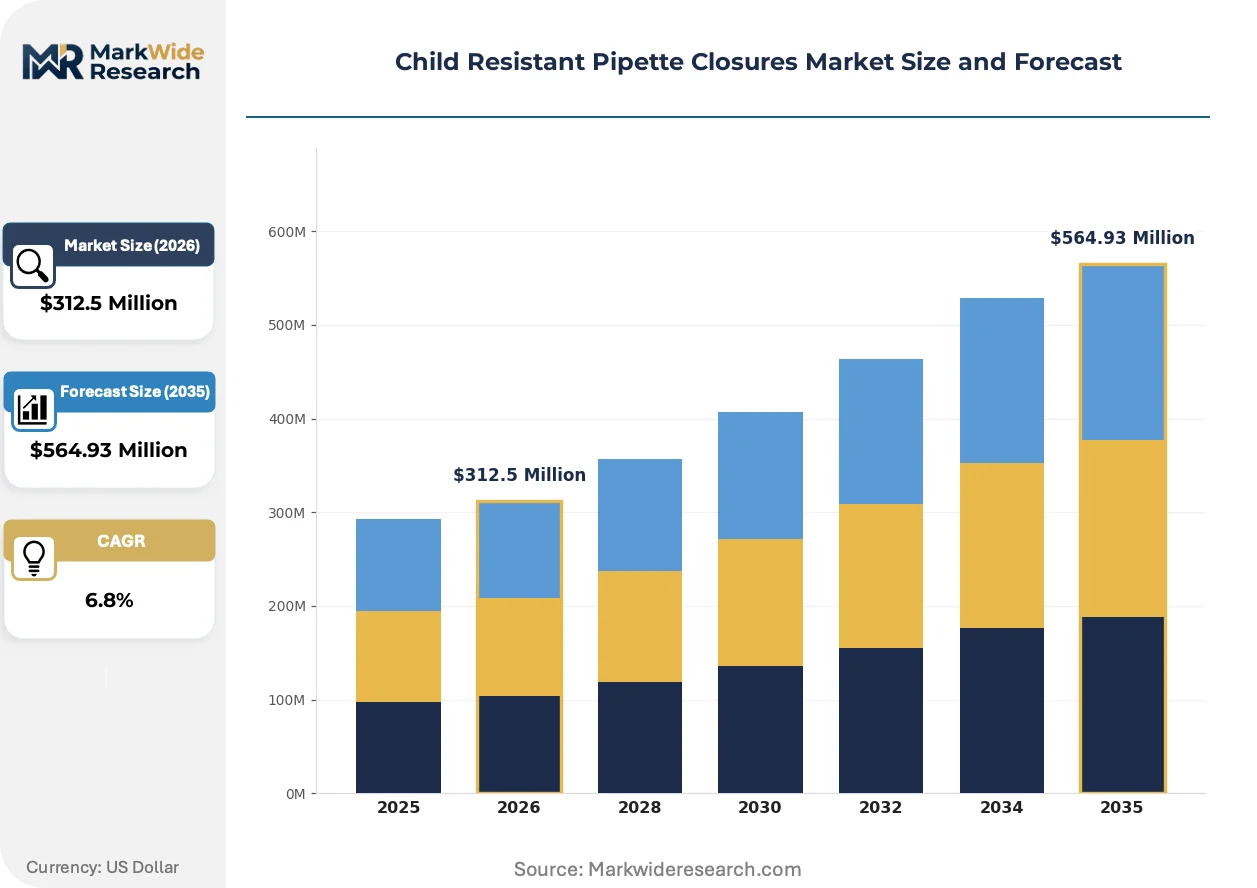
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $564.93 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Push-and-Twist, Squeeze, Snap-on, Screw Cap Material: Plastic, Rubber, Glass, Metal End User: Hospitals, Laboratories, Pharmacies, Research Facilities Application: Pharmaceuticals, Chemicals, Food & Beverages, Cosmetics |
| Companies Covered | AptarGroup, Berry Global, Silgan Holdings, Mold-Rite Plastics, Unilife Corporation, Comar, Global Closure Systems, Amcor, Cospak, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Child Resistant Pipette Closures Market Strategic Shifts
Automation of quality assurance and torque verification is displacing manual testing protocols, while regulatory scope expansion and buyer consolidation are reconfiguring supplier qualification criteria.
Vision-guided robotic inspection systems are automating dimensional and torque-limit verification at line speeds exceeding 400 units per minute. Pharmaceutical packagers in Germany and Switzerland are deploying these systems to satisfy batch record requirements for FDA and EMA submissions. This automation is compressing defect escape rates and reducing manual inspection headcount in high-volume filling operations.
REACH Annex XVII restrictions on microplastics and chemical migration are compelling reformulation of elastomeric seal compounds for European export-bound closures. ECHA guidance on phthalate alternatives is forcing compounders to validate new curative systems without sacrificing compression set performance. Laboratory and hospital end-use segments in France and the Netherlands are experiencing the longest qualification delays due to biocompatibility retesting requirements.
Dual-source validation mandates from multinational drug manufacturers are consolidating procurement around integrated suppliers with captive resin compounding and in-house mold fabrication. Contract packagers are displacing single-source relationships with parallel supplier development programs spanning 12-to-24 month timelines. This pattern is most visible in Germany, where Bayer and Boehringer Ingelheim packaging networks are driving supplier consolidation.
Child Resistant Pipette Closures Market Segmentation
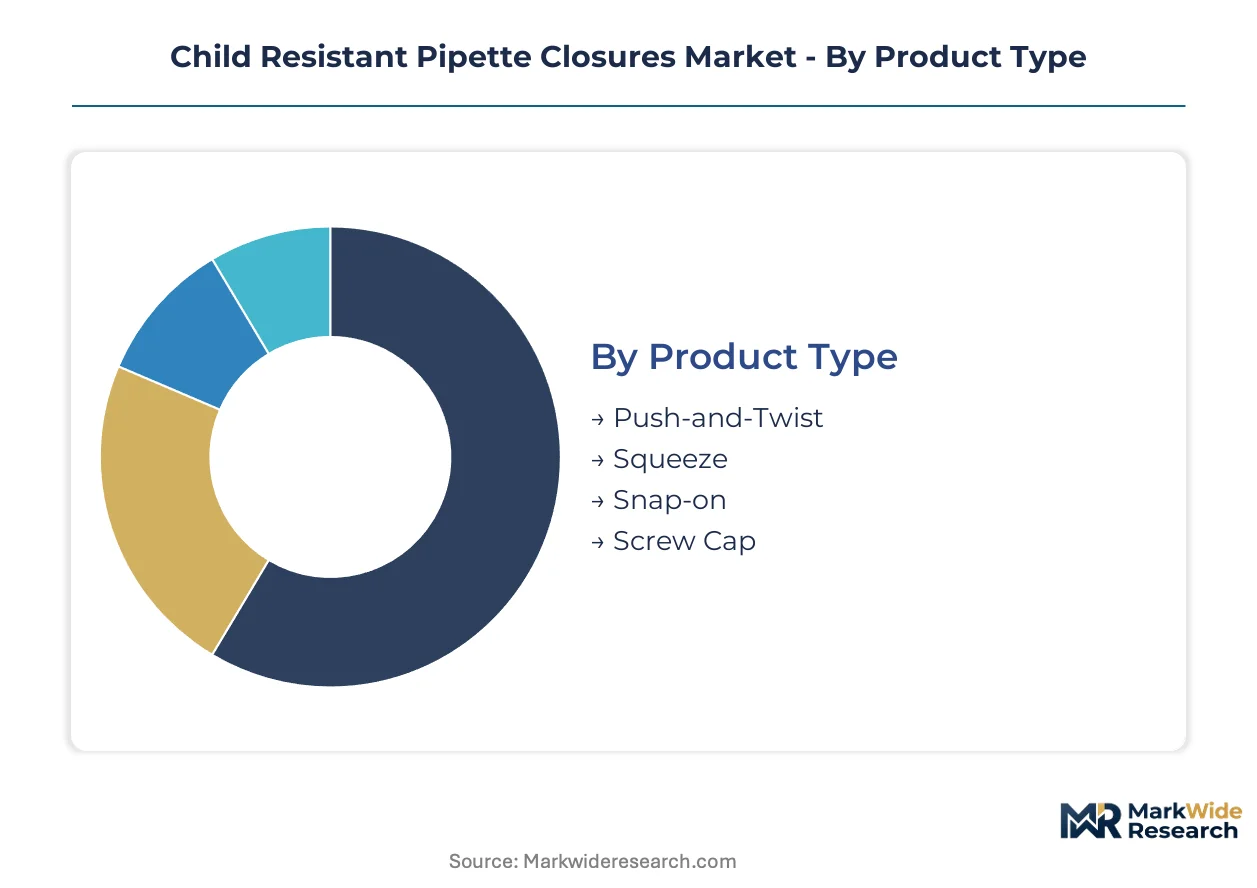
Segmentation in child resistant pipette closures determines certification pathways, tooling investments, and margin structures. Product geometry and material composition directly govern compliance eligibility across FDA, EMA, and ISO 8317 frameworks.
Product Type:
Capital intensity concentrates in multi-cavity hot-runner molds for torque-limited mechanisms, where precision tolerances demand specialized German and Austrian toolmaking expertise.
- Push-and-Twist:Torque-limited engagement with polypropylene or HDPE bodies and integrated elastomeric seals. Pharmaceutical contract packagers in Germany and Switzerland specify this configuration for FDA Poison Prevention Packaging Act compliance, driving the largest procurement volumes.
- Squeeze:Dual-action compression and rotation release requiring complex internal rib geometries and calibrated flex zones. Demand concentrates in pediatric allergy and cough-cold liquid portfolios where adult ergonomics must accommodate reduced grip strength.
- Snap-on:Single-motion engagement with audible confirmation, suited for single-use biologic filling lines where capper head speeds exceed 400 units per minute.
- Screw Cap:Traditional helical thread engagement with child-resistant liners, deployed in legacy chemical and industrial applications where regulatory novelty is absent.
Most installed capacity flows through Push-and-Twist configurations. Expansion is steepest in Squeeze variants.
Material:
Feedstock selection governs sterilization compatibility, REACH compliance scope, and resin compounding backward integration economics.
- Plastic:Polypropylene and HDPE dominate through steam and gamma-radiation stability, with Bavarian and Baden-Württemberg molding facilities anchoring European supply. ECHA microplastic restrictions are forcing reformulation cycles for export-bound closures.
- Rubber:Medical-grade EPDM and silicone gaskets represent a concentrated margin pool, with German and Swiss compounders controlling qualification timelines for compression set performance.
- Glass:Borosilicate dropper assemblies for high-value biologic and essential oil applications, constrained by fragility in automated filling environments.
- Metal:Aluminum overcaps and threaded collars in premium cosmetic and cannabis packaging, where torque-limited aluminum shells satisfy state-level mandates in California and Colorado.
Plastic resins carry the heaviest capital deployment in injection molding infrastructure. Rubber compounds command the steepest qualification barriers.
End User:
Buyer technical specifications diverge sharply between regulated pharmaceutical channels and institutional laboratory procurement.
- Hospitals:Single-use sterile pipette closures with lot-level traceability and gamma-irradiation validation, procured through GPO contracts with ISO 15378 quality system requirements.
- Laboratories:Research-grade dispensing systems with chemical resistance specifications, where REACH-compliant elastomer selection extends procurement cycles in France and the Netherlands.
- Pharmacies:OTC and prescription liquid packaging with child-test certification, governed by FDA enforcement of standardized protocols.
- Research Facilities:Custom torque geometries for novel biologic formats, requiring capper head retrofits that disrupt validated production schedules.
Hospital procurement concentrates the highest certification burden. Research facilities are gaining share fastest in modified closure development.
Application:
Regulatory jurisdiction and hazard classification determine closure performance standards and testing protocol selection.
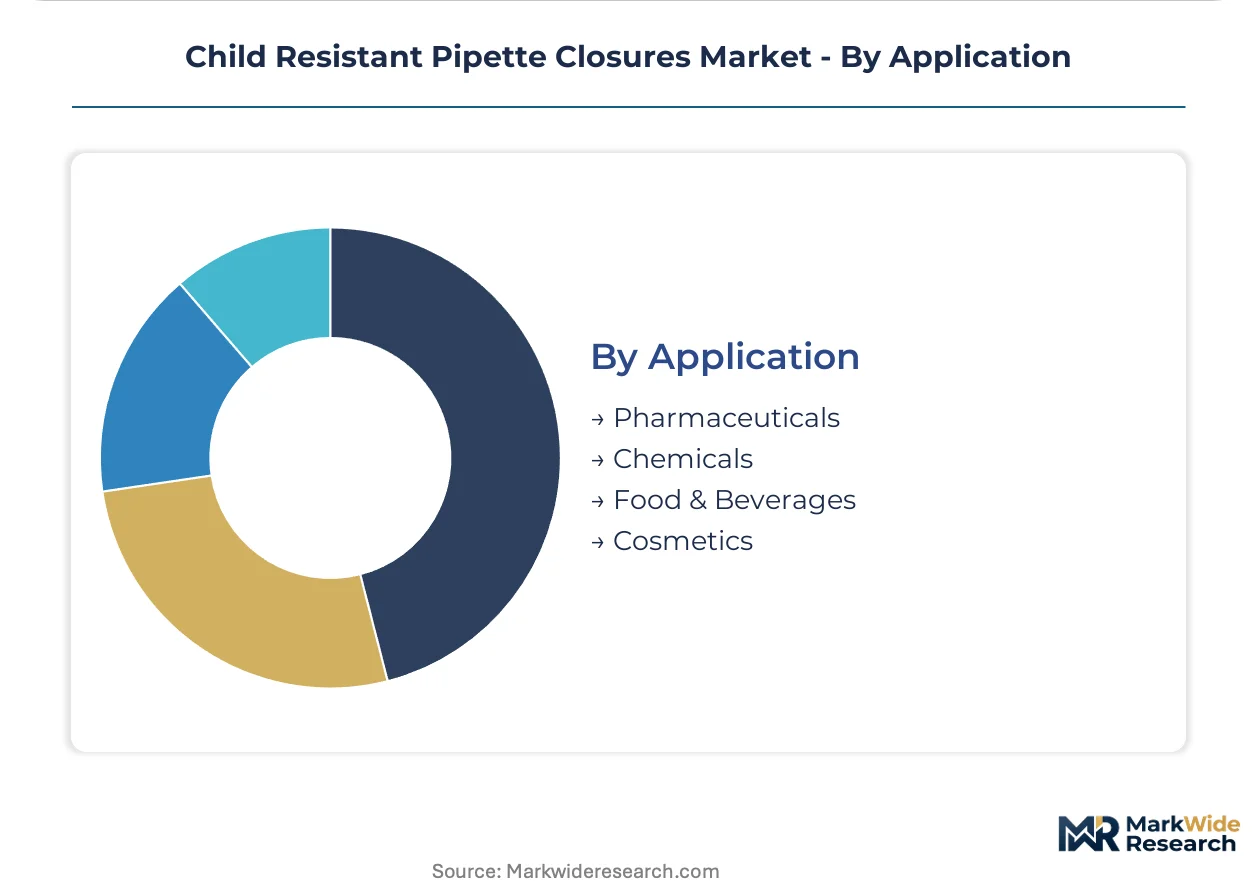
- Pharmaceuticals:Liquid prescription and OTC drugs under FDA Poison Prevention Packaging Act and EMA centralized marketing authorization, where EN ISO 8317 certification is mandatory for European access.
- Chemicals:Industrial solvents and cleaning agents with CPSC child-resistant packaging requirements, often satisfied by lower-cost screw cap configurations.
- Food & Beverages:Essential oils and concentrated flavorings with emerging state-level cannabis packaging regulation overlap in California and Illinois.
- Cosmetics:Premium serums and active ingredient formulations where adult ergonomics and brand aesthetics override regulatory complexity.
Pharmaceutical applications absorb the majority of validated production capacity. Cannabis-adjacent food and beverage segments are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands specialized molding infrastructure for pharmaceutical-grade closures, while the United States drives regulatory enforcement through FDA child-test protocols. Switzerland and France concentrate elastomer compounding expertise. China and India are expanding domestic certification capacity for export-bound supply.
United States
California and Colorado state-level cannabis packaging mandates are generating demand for customizable torque-limited geometries outside traditional pharmaceutical channels. The FDA enforces Poison Prevention Packaging Act compliance through standardized child-test protocols that determine market access eligibility. Contract packagers in the Northeast and Midwest are consolidating supplier relationships around dual-source validated partners.
Germany
Bavarian and Baden-Württemberg molding facilities anchor European pharmaceutical packaging networks with integrated quality validation and ISO 8317 certification. The country's national pharmaceutical regulator references EN ISO 8317 standards within centralized marketing authorization procedures. Precision mold fabrication expertise concentrates among specialized toolmaking workforces in Stuttgart and Munich industrial clusters.
Switzerland
Swissmedic oversight and REACH-compliant elastomer integration requirements position the country as a concentrated margin chokepoint for medical-grade EPDM and silicone gasket compounders. ECHA guidance on phthalate alternatives forces compounders to validate new curative systems. Basel and Zurich house specialized facilities serving laboratory and hospital procurement networks.
France
Laboratory and hospital end-use segments in Île-de-France and the Netherlands-bordering regions experience extended qualification delays due to biocompatibility retesting requirements under expanding REACH chemical restrictions. ANSM enforces medical device safety standards that constrain elastomer formulation choices. Lyon and Paris pharmaceutical corridors are deploying vision-guided robotic inspection systems for batch record compliance.
China
Yangtze River Delta and Pearl River Delta manufacturing zones are scaling injection molding infrastructure for export-bound plastic resin closures. The national medical products administration is strengthening alignment with ISO standards for medical device safety. Shanghai and Suzhou industrial parks are attracting pharmaceutical packaging foreign direct investment for regional supply chain integration.
Child Resistant Pipette Closures Market Competitive Environment
German and Swiss producers anchor the premium-tier certification segment; North American specialists hold scale-driven positions in high-volume molding. The vendor base separates into three tiers: integrated multinationals with captive resin compounding, mid-cap regional molders with ISO 15378 pre-validation, and specialized elastomer compounders serving laboratory niches. Competitive moves concentrate on dual-source validation partnerships and backward integration into precision mold fabrication.
Among integrated packaging multinationals, AptarGroup, Berry Global, and Silgan Holdings exemplify archetype differentiation across the supplier spectrum. AptarGroup occupies a position representing push-and-twist technology platform specialists. Berry Global exemplifies manufacturing scale deployment across continental molding networks. Silgan Holdings anchors backward integration models spanning resin compounding and toolmaking capabilities.
| Leading Market Players |
|---|
| AptarGroup |
| Berry Global |
| Silgan Holdings |
| Mold-Rite Plastics |
| Unilife Corporation |
| Comar |
| Global Closure Systems |
| Amcor |
| Cospak |
| Others |
Value Chain & Pricing Dynamics
Propylene monomer costs from naphtha cracking margins cascade through three pricing tiers: German precision molders capture premium positioning through ISO 8317 pre-certification, mid-cap regional suppliers compete on REACH-compliant elastomer integration, and Asian export molders absorb feedstock volatility to defend volume slots.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for standard-grade polypropylene closures. Three-tier pricing structure across premium, standard, and economy levels separates Swiss-certified elastomer-integrated units from German mid-tier molders and Chinese export-base supply. Cost compression in the economy tier is intensifying because propylene feedstock volatility compresses molding margins. Hospital GPO contracts show least price sensitivity due to ISO 15378 quality mandates, while cannabis packaging distributors in California and Colorado exhibit highest sensitivity to unit cost.
Supply Chain Analysis
Domestic-content mandates in European pharmaceutical procurement are reshaping sourcing patterns for export-bound manufacturers. Supply concentrates in Germany, Switzerland, and China, with Bavarian toolmaking clusters anchoring precision mold fabrication. The chain draws from propylene monomer feedstocks, medical-grade EPDM compounders, and multi-cavity hot-runner tooling. Single-source vulnerability concentrates in German and Austrian precision mold design expertise. Distribution runs through pharmaceutical contract packagers with dual-source validation requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play: REACH compliance costs in Switzerland and Germany create cost-advantaged entry points for pre-certified Asian suppliers serving European pharmaceutical networks.
For Market Incumbents: Lock in dual-source validation partnerships with Bayer and Boehringer Ingelheim packaging networks before 18-month procurement windows compress further. Defend margin position through backward integration into resin compounding and captive mold fabrication capabilities. Priority lever: precision mold tooling expertise scarcity in aging German and Austrian workforces. For New Entrants and Emerging Players: FDA Poison Prevention Packaging Act enforcement in the United States opens a window for certified push-and-twist closure supply to Northeast and Midwest contract packagers. Target cannabis packaging distributors in California, Colorado, and Illinois where state-level mandates outrun incumbent certification capacity. Go-to-market angle: customizable torque-limited geometries with rapid mold modification turnaround. For Investors and Strategic Acquirers: Consolidation pressure builds where dual-source validation mandates from multinational drug manufacturers eliminate single-source suppliers. Long-term viability favors integrated players with captive elastomer compounding and in-house ISO 8317 certification. Acquisition target archetype: mid-cap German molders with pre-validated quality systems and aging ownership. Signal to watch: pharmaceutical packager procurement team expansion in Shanghai and Suzhou industrial parks.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive polypropylene supply insulates AptarGroup and Silgan Holdings from propylene monomer volatility. |
| ISO 8317 Pre-Certification Investment | Pre-validated quality systems accelerate Bayer and Boehringer Ingelheim dual-source validation timelines. |
| Precision Mold Fabrication Capability Buildout | Multi-cavity hot-runner expertise concentrates in Stuttgart and Munich industrial clusters. |
| REACH-Compliant Elastomer Reformulation | Medical-grade EPDM compounders in Basel and Zurich control compression set performance qualification. |
| Cannabis Packaging Regulatory Arbitrage | State-level mandates in California and Colorado create demand outside traditional pharmaceutical channels. |
Study Parameters
Bottom-up pharmaceutical contract packager modeling reconciled against top-down resin compounding and molding capacity tracking forms the analytical core. Primary interviews with pharmaceutical packaging procurement managers, regulatory affairs leads at multinational drug manufacturers, precision mold toolmakers in Stuttgart and Munich, and medical-grade elastomer compounders in Basel and Zurich combined with secondary validation from FDA 510(k) filings, EMA centralized marketing authorization procedures, EN ISO 8317 certification registries, and REACH Annex XVII restriction updates.
Input-output matrices mapped polypropylene and HDPE resin flows through injection molding infrastructure to end-use segments across the analysis window. Segmentation dimensions modeled include product geometry, material composition, end-user procurement channel, and application regulatory jurisdiction. CAGRs were derived from installed capacity utilization rates and certification timeline compression patterns. Forecast inputs incorporated propylene monomer price elasticity and dual-source validation mandate adoption curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under ECHA candidate list expansion for phthalate alternatives and state-level cannabis packaging regulatory fragmentation. Forecasts reflect documented assumptions about certification timeline stability and mold fabrication skill availability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Cork Stoppers Market
Caps and Closures
Bar Top Corks Market
Caps and Closures
South Africa Plastic Caps and Closures Market
Caps and Closures
Push Pull Closure Market
Caps and Closures
Dual Flap Dispensing Closure Market
Caps and Closures
Caps and Closures Market
Caps and Closures
Overcaps Market
Caps and Closures
Spray Caps Market
Caps and Closures
India Plastic Caps and Closures Market
Caps and Closures
Latin America Plastic Caps and Closure Market
Caps and Closures
Bag Closure Clips Market
Caps and Closures
Flapper Caps Market
Caps and Closures
Sport Caps and Closures Market
Caps and Closures
Indonesia Plastic Caps and Closures Market
Caps and Closures
Flat Valve Caps and Closures Market
Caps and Closures
Sleeve Rubber Stoppers Market