
 Lid Laminates Market | 2026-2036
Lid Laminates Market Size, Share, and Industry Trends Forecast 2026-2036
Lid Laminates Market Foresight
Asset-light leasing arrangements for coextrusion equipment is narrowing the capital barrier for mid-tier converters seeking foil laminate capacity. Amcor Limited leverages its vertical integration into aluminum sourcing to sustain margin control across European dairy accounts. Berry Global Inc. anchors its position through high-speed thermoforming partnerships with North American food manufacturers. Constantia Flexibles Group GmbH differentiates via pharmaceutical-grade cleanroom certification for blister lid supply.
Lid laminates are multilayer barrier structures, typically combining aluminum foil, polypropylene, polyethylene, or paper substrates through adhesive lamination or extrusion coating, engineered to provide hermetic sealing, oxygen exclusion, and peelable or weld-seal functionality for container closure systems. Plastic laminates dominate unit volume in beverage packaging where cost sensitivity and line speed requirements prioritize polyolefin structures, while foil laminates command premium positioning in pharmaceutical applications demanding moisture and light barrier integrity. Composite laminates represent the fastest-growing product category as brand owners reformulate around EU Green Deal recyclability mandates and mono-material compatibility targets.
The EU Green Deal and REACH frameworks in Europe, alongside FDA compliance requirements for pharmaceutical packaging in the United States, are elevating migration testing protocols and substance restriction lists that directly shape laminate adhesive selection and layer composition. EFSA evaluations of recycled content authorization are creating regulatory lead times that favor converters with pre-validated material libraries and established notifier relationships. Stakeholders must monitor evolving extended producer responsibility schemes and deposit-return system expansions to anticipate which laminate structures will retain market access across priority jurisdictions.
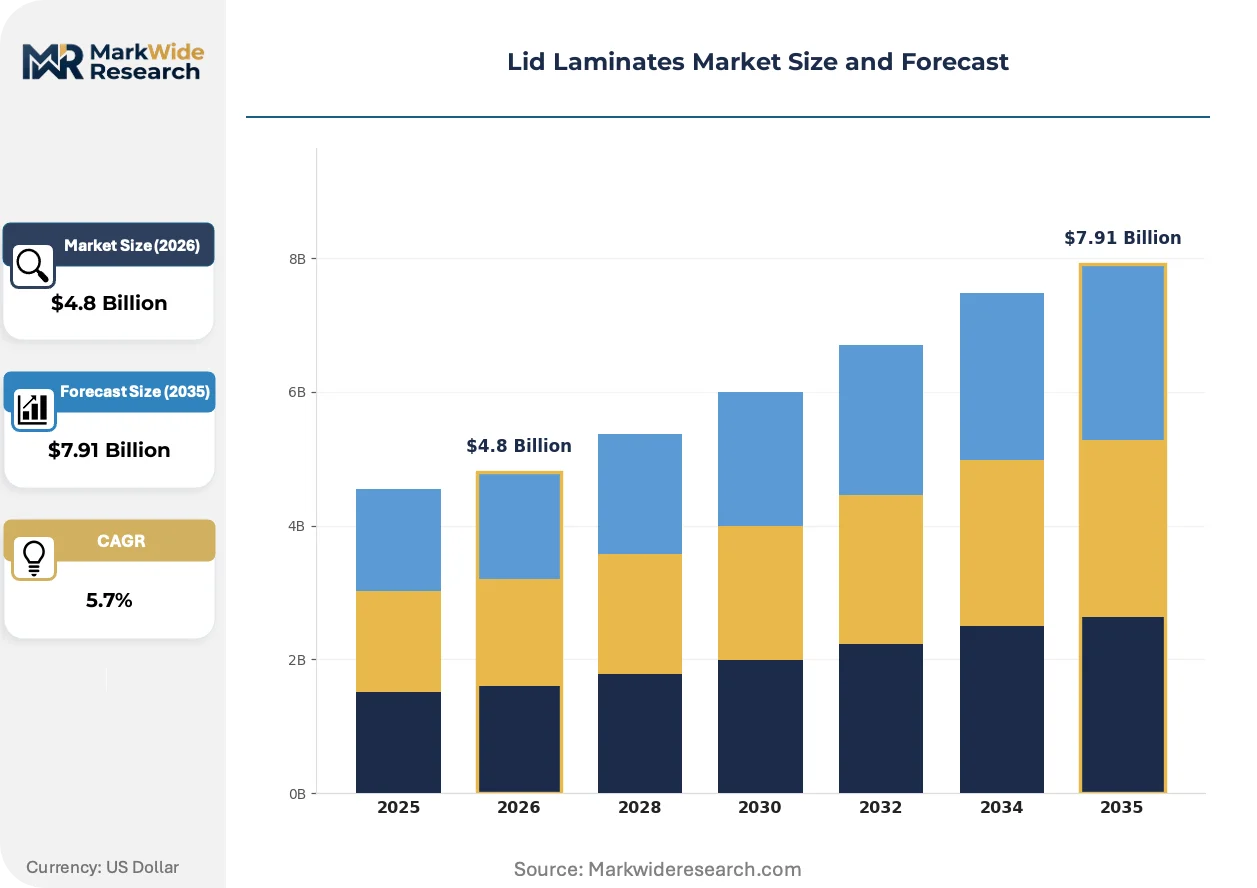
Market Dynamics
The EU Green Deal's packaging waste directives are compressing demand toward recyclable mono-material and composite laminate structures, forcing converters to revalidate adhesive chemistries and layer configurations ahead of regulatory deadlines.
Growth Catalysts
- EFSA Recycled Content Pathways:Pre-authorization frameworks for post-consumer polypropylene in food-contact laminates are accelerating material substitution timelines for dairy processors in Germany and France.
- Pharmaceutical Blister Expansion:Moisture-sensitive biologic formulations are pulling foil laminate demand from sterile injectables into oral solid dose packaging across European manufacturing corridors.
- Aluminum Sourcing Integration:Captive supply of rolled foil is insulating margin structures for converters serving extended shelf-life yogurt and cream segments.
Market Restraints
- Adhesive Migration Testing Costs:EFSA and FDA dual compliance requirements for laminate adhesives are extending qualification timelines and elevating R&D overhead for mid-tier converters.
- Olefin Price Volatility:Polypropylene and polyethylene feedstock swings are compressing margin predictability for beverage-focused plastic laminate producers.
- Equipment Capex Concentration:Coextrusion and high-speed thermoforming lines require capital commitments that favor scale players, narrowing entry paths for regional converters.
Strategic Opportunities
- Deposit-Return System Alignment:EU member state expansions of DRS coverage for dairy and ready-meal containers are creating first-mover advantage for PET-compatible laminate structures.
- Cleanroom Certification Arbitrage:Pharmaceutical-grade blister lid supply remains underserved in Eastern European manufacturing zones, rewarding converters with ISO 14644-1 validated facilities.
- Paper-Foil Hybrid Convergence:Fiber-based barrier substrates combined with ultrathin aluminum layers are opening premium positioning in organic and natural food segments.
Industry Challenges
- Adhesive Chemist Talent Scarcity:Formulation expertise for low-migration, high-bond laminating adhesives is concentrating at legacy European suppliers, constraining new entrant R&D velocity.
- Legacy Thermoforming Retrofit Complexity:Converters face integration friction upgrading sealing station tooling for peelable weld-seal functionality demanded by portion-control dairy formats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lid Laminates Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foil Laminates, Paper Laminates, Plastic Laminates, Composite Laminates Application: Food Packaging, Pharmaceutical Packaging, Cosmetic Packaging, Beverage Packaging End User: Food Manufacturers, Pharmaceutical Companies, Cosmetic Brands, Beverage Companies Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Amcor Limited, Berry Global Inc., Constantia Flexibles Group GmbH, Coveris Holdings S.A., Mondi Group, Sealed Air Corporation, Sonoco Products Company, Huhtamaki Oyj, Winpak Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lid Laminates Market Shifts & Advancements
Material science convergence and regulatory chemistry restrictions are actively reconfiguring how laminate structures are engineered, tested, and qualified for market access across food and pharmaceutical end-uses.
Barrier coating technology is hybridizing. Solvent-free adhesive lamination systems are replacing conventional polyurethane chemistries in high-volume dairy applications. German and French converters are adopting electron-beam cured adhesives at accelerated qualification paces. This hybridization is compressing the viable supply base to players with in-house polymerization capabilities.
REACH substance restriction expansions are reshaping laminate formulation. ECHA candidate list additions for bisphenol derivatives and certain phthalate plasticizers are forcing adhesive requalification cycles. Pharmaceutical blister lid suppliers face the tightest substitution timelines. Foil-dominant structures are gaining preference where polymer modification risks barrier integrity.
Brand owner specification consolidation is concentrating procurement leverage. Pan-European dairy groups are reducing approved laminate supplier lists from regional fragmentation toward single-source national contracts. Direct converter relationships are displacing distributor intermediaries in Germany's food processing corridor. This concentration is most visible in extended shelf-life cream and yogurt segments where line speed and seal reliability failures carry high downtime costs.
Lid Laminates Market Segmentation
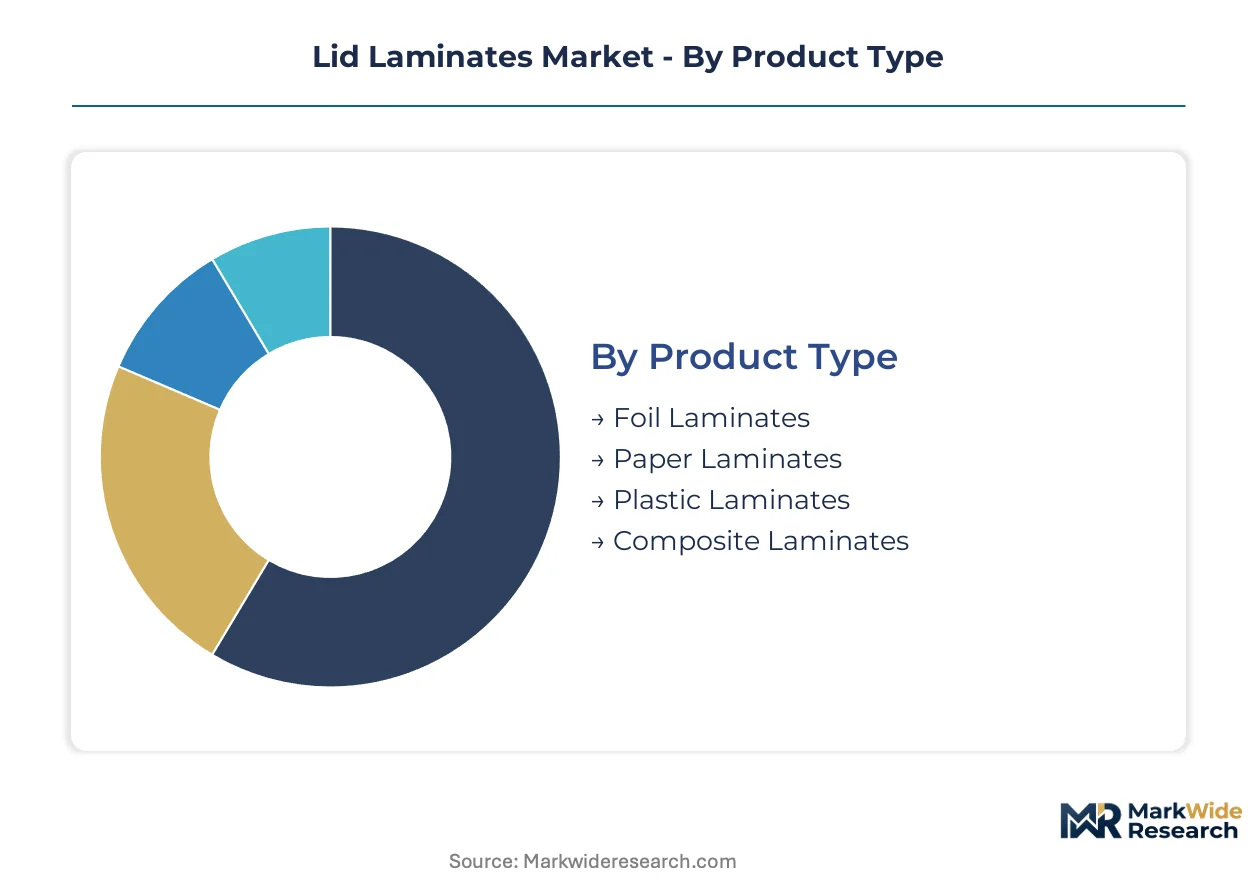
Lid laminate specifications diverge sharply across end-use requirements, with pharmaceutical barrier demands commanding fundamentally different material stacks than beverage cost-optimized structures. Segmentation discipline separates converters by validated capability tier rather than commodity positioning.
Product Type:
Cycle times vary dramatically: foil laminates turn on quarterly pharmaceutical procurement cycles, while plastic laminates rotate on monthly beverage line reviews. Composite laminates sit between, reformulating on 18-month regulatory windows.
- Foil Laminates:Aluminum-polypropylene or aluminum-polyethylene multilayer structures providing absolute moisture and light barrier integrity. Demand concentrates in German and French pharmaceutical manufacturing corridors where EMA stability requirements mandate foil-dominant blister lids for moisture-sensitive biologics.
- Composite Laminates:Engineered combinations of fiber substrates, ultrathin metallic layers, and sealant films designed for mono-material recyclability. German dairy processors are accelerating adoption ahead of EU Green Deal deadlines, with EFSA pre-authorization frameworks compressing substitution timelines.
- Plastic Laminates:Polyolefin-dominant structures optimized for high-speed thermoforming and cost-sensitive beverage applications.
- Paper Laminates:Fiber-based barrier substrates with polymer or wax coatings for dry food and organic positioning.
Foil laminates dominate installed base in pharmaceutical corridors. Composite laminates are where expansion concentrates as brand owners reformulate around EU Green Deal recyclability mandates.
Application:
Margin structures stratify by validation burden: pharmaceutical applications carry 3-5x the qualification overhead of beverage packaging, concentrating supply among certified converters.
- Food Packaging:Peelable and weld-seal lid structures for extended shelf-life dairy, ready meals, and portion-control formats. German yogurt and cream segments are consolidating supplier lists from regional fragmentation toward single-source national contracts where line speed reliability failures carry high downtime costs.
- Pharmaceutical Packaging:Hermetic blister lids and lidding foils for oral solid dose and sterile injectable applications. Moisture-sensitive biologic formulations are pulling foil laminate demand from sterile injectables into oral solid dose packaging across European manufacturing corridors.
- Beverage Packaging:Polyolefin-optimized structures for cup and bottle sealing where cost sensitivity and line speed requirements prioritize high-throughput plastic laminates.
- Cosmetic Packaging:Decorative and functional lids for cream, serum, and personal care containers with premium aesthetic requirements.
Food packaging commands unit volume leadership. Pharmaceutical packaging is climbing the fastest on biologic formulation expansion and barrier integrity mandates.
End User:
Procurement leverage separates by scale: multinational food manufacturers negotiate direct converter relationships, while mid-tier cosmetic brands route through distributor intermediaries.
- Food Manufacturers:Pan-European dairy groups and ready-meal processors specifying laminate structures for extended shelf-life and portion-control formats. Direct converter relationships are displacing distributor intermediaries in Germany's food processing corridor.
- Pharmaceutical Companies:Oral solid dose and sterile injectable manufacturers with EMA and FDA dual compliance requirements. REACH substance restriction expansions are forcing adhesive requalification cycles with the tightest substitution timelines.
- Cosmetic Brands:Premium and mass-market personal care companies with decorative and functional lid requirements.
- Beverage Companies:Bottled and cupped beverage producers prioritizing polyolefin structures for cost and speed.
Food manufacturers anchor procurement volume. Pharmaceutical companies are driving specification complexity and margin expansion.
Distribution Channel:
Channel selection tracks customer scale and technical service intensity, with direct sales capturing complex pharmaceutical qualifications and distributors serving fragmented cosmetic accounts.
- Direct Sales:Converter-customer relationships for pharmaceutical and large food accounts requiring technical service, formulation co-development, and regulatory documentation. Brand owner specification consolidation is concentrating procurement leverage through direct relationships.
- Distributors:Intermediary networks serving mid-tier converters and regional accounts with standardized product lines. Distributor intermediaries are losing share in Germany's food processing corridor as direct relationships consolidate.
- Online Retail:Digital procurement platforms for standardized laminate specifications and small-volume orders.
- Wholesalers:Bulk inventory positions for commodity-grade plastic laminates in beverage applications.
Direct sales capture the highest-value pharmaceutical and dairy accounts. Distributors retain position in fragmented cosmetic and small-converter segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in lid laminates tilt toward net-import positions in pharmaceutical-intensive economies while packaging converters in Germany and France sustain export surplus in dairy-grade foil structures. The EU Green Deal's packaging waste directives are compressing regional demand toward recyclable composite laminates, forcing cross-border revalidation of adhesive chemistries ahead of regulatory deadlines.
Germany
Extended shelf-life yogurt and cream segments are consolidating supplier lists toward single-source national contracts where line speed reliability failures carry high downtime costs. EFSA pre-authorization frameworks for post-consumer polypropylene are accelerating material substitution timelines ahead of EU Green Deal deadlines. Bavaria's food processing corridor anchors foil laminate demand from dairy processors reformulating around recyclability mandates.
France
Pharmaceutical blister lid supply is expanding as moisture-sensitive biologic formulations pull foil laminate demand from sterile injectables into oral solid dose packaging. ANSM stability requirements for EMA compliance mandate foil-dominant structures in Paris-region manufacturing zones. The Île-de-France pharmaceutical cluster is driving specification complexity and margin expansion for certified converters.
United States
FDA dual compliance requirements for pharmaceutical packaging are elevating migration testing protocols that shape laminate adhesive selection and layer composition. Berry Global Inc. anchors high-speed thermoforming partnerships with food manufacturers prioritizing polyolefin structures for cost and line speed. The Midwest dairy belt is adopting peelable weld-seal functionality for portion-control formats.
China
SAMR packaging standards and dual carbon goals are accelerating domestic converter investment in solvent-free adhesive lamination systems. Yangtze River Delta manufacturing zones are absorbing technology transfer for electron-beam cured adhesive platforms. Local dairy processors are testing paper-foil hybrid substrates for organic positioning in premium segments.
India
FSSAI food-contact regulations and PLI scheme incentives for packaging materials are drawing investment in coextrusion capacity for beverage-focused plastic laminates. Maharashtra and Gujarat industrial corridors are hosting mid-tier converters seeking asset-light leasing arrangements for foil laminate capacity expansion. Migration testing infrastructure remains concentrated at legacy European suppliers, constraining new entrant R&D velocity.
Lid Laminates Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in adhesive chemistry and substrate supply. The vendor base organizes around three tiers: multinational converters with captive aluminum sourcing, mid-scale specialists with pharmaceutical cleanroom certification, and regional players competing on beverage-grade plastic laminate volume. Strategic moves concentrate on backward integration into rolled foil production and high-speed thermoforming line partnerships with food manufacturers.
Within the multinational converter tier, Amcor Limited, Berry Global Inc., and Constantia Flexibles Group GmbH exemplify divergent positioning archetypes. Amcor represents the backward-integrated model with upstream control over aluminum sourcing. Berry Global occupies the high-speed thermoforming partnership vector with North American food manufacturers. Constantia Flexibles sits within the pharmaceutical-grade certification tier, anchoring blister lid supply through ISO 14644-1 validated facilities. These three structures illustrate how margin control, line speed reliability, and regulatory qualification separate competitive positions in an increasingly consolidated procurement environment.
| Leading Market Players |
|---|
| Amcor Limited |
| Berry Global Inc. |
| Constantia Flexibles Group GmbH |
| Coveris Holdings S.A. |
| Mondi Group |
| Sealed Air Corporation |
| Sonoco Products Company |
| Huhtamaki Oyj |
| Winpak Ltd. |
| Others |
Supply & Pricing Matrix
Overcapacity in China's Yangtze River Delta coextrusion corridor is compressing margin structures for plastic laminate exporters while simultaneously hardening pricing power for European foil laminate specialists with captive aluminum supply. This utilization divergence is forcing mid-tier converters to choose between volume-driven commodity positioning and defensible premium tiers anchored in regulatory qualification.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in the lid laminates market. Pharmaceutical-grade foil laminates with EMA/FDA dual certification command substantial premiums over beverage-focused plastic structures, while composite laminates with EFSA pre-authorization occupy a widening mid-tier. Pricing pressure stems from polypropylene feedstock volatility and adhesive requalification costs, with beverage manufacturers exhibiting highest price sensitivity and pharmaceutical companies least willing to trade barrier integrity for cost reduction.
Supply Chain Analysis
Export-control restrictions on electron-beam curing technology are limiting technology transfer to emerging converter markets and concentrating advanced adhesive lamination capacity in Germany, France, and select North American corridors. Raw material flows draw from rolled aluminum suppliers in Germany, polypropylene resin producers in the Middle East, and specialty adhesive formulators concentrated in Western Europe. Single-source vulnerability around pharmaceutical-grade cleanroom-certified facilities represents the dominant supply chain risk. Distribution runs through direct converter relationships for large food and pharmaceutical accounts, with distributor networks retaining position in fragmented cosmetic segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The lid laminates market functions as a service-attach opportunity where formulation co-development and regulatory documentation subscriptions expand faster than commodity substrate supply. Technical service contracts for adhesive requalification and migration testing represent the fastest-growing recurring-revenue layer.
For Market Incumbents: Pre-empt adhesive chemist talent scarcity by acquiring specialized formulation houses with established EFSA notifier relationships before qualification timelines extend further. Consolidate supplier lists in Germany's dairy processing corridor through exclusive line-speed reliability guarantees that raise switching costs. Backward integration into rolled foil production insulates margin structures from aluminum price volatility. For New Entrants and Emerging Players: Pursue cleanroom certification arbitrage in Eastern European pharmaceutical manufacturing zones where ISO 14644-1 validated blister lid supply remains underserved. Target India's Maharashtra and Gujarat industrial corridors through asset-light leasing arrangements for coextrusion equipment that narrow capital barriers. Lead with solvent-free adhesive lamination platforms that accelerate ahead of REACH substance restriction expansions. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among converters with pharmaceutical-grade certification and established direct relationships with pan-European dairy groups. Long-term viability over the coming decade favors specialists with pre-validated material libraries and regulatory documentation capabilities. Watch EFSA recycled content authorization timelines as the critical inflection signal for composite laminate substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rolled Foil | Captive aluminum sourcing insulates Amcor's margin control across European dairy accounts. |
| High-Speed Thermoforming Partnership | Berry Global's line-speed reliability commitments anchor North American food manufacturer loyalty. |
| Cleanroom Certification Investment | ISO 14644-1 validation opens underserved Eastern European pharmaceutical blister lid supply. |
| Solvent-Free Adhesive Platform Launch | German and French converters adopting electron-beam cured systems compress viable supply base. |
| Deposit-Return System Alignment | PET-compatible laminate structures capture first-mover advantage in EU member state expansions. |
Research Methodology
Initial hypotheses were tested against primary input from adhesive formulation chemists, food packaging procurement directors, pharmaceutical regulatory affairs leads, and coextrusion equipment operators and refined through secondary validation against EFSA pre-authorization frameworks, FDA migration testing protocols, EU Green Deal packaging waste directives, and SEC filings from listed converters. Bottom-up volume estimates from individual facility capacities and top-down demand segmentation from end-use consumption patterns were triangulated to cross-check outputs.
Demand-supply balance modeling across the projection horizon incorporated product type segmentation by barrier performance tier, application segmentation by validation burden, end-user segmentation by procurement leverage, and geographic segmentation by regulatory cluster. CAGRs were derived from fitted growth curves calibrated to historical substitution patterns and forward-looking material authorization timelines. Key inputs included EFSA recycled content approval schedules and pharmaceutical biologic formulation expansion trajectories.
Sensitivities concentrate around ECHA candidate list expansions for adhesive substances and olefin feedstock price volatility. Forecasts reflect assumptions regarding regulatory deadline adherence and converter qualification velocity. Material shifts in EU Green Deal implementation timelines or EFSA authorization pathways would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Cold Chain Packaging Materials Market
Packaging Materials
Direct Thermal Printing Films Market
Packaging Materials
MDO Films Market
Packaging Materials
Packaging Inserts Market
Packaging Materials
Card Films Market
Packaging Materials
Cushion Case Liner Market
Packaging Materials
Bottle Sealing Wax Market
Packaging Materials
Child Resistant Re-Closable Edible Bags Market
Packaging Materials
Global Hot Stamping Foils Market
Packaging Materials
Myanmar Packaging Market
Packaging Materials
Urn Liners Market
Packaging Materials
China Packaging Market
Packaging Materials
Sanitizer Packaging Market
Packaging Materials
Global Adherence Packaging Market
Packaging Materials
Africa Packaging Market
Packaging Materials
Strapping Materials Market