
 Sun Control Films Market | 2026-2036
Sun Control Films Market Size, Share, and Industry Trends Forecast 2026-2036
Sun Control Films Market Outlook
Modular film kits that bundle ceramic tint with edge-sealing accessories is shifting procurement patterns for automotive aftermarket buyers. 3M leverages its multi-layer sputtering expertise to sustain premium positioning in reflective and ceramic grades. Eastman Chemical Company anchors North American supply through captive polyester production and chemical intermediates. Garware Hi-Tech Films competes on cost-engineered tinted films for price-sensitive commercial installations across South Asia.
Sun control films are thin, optically engineered polymer laminates, typically 1.5–2 mil thick, composed of dyed, metallized, or nano-ceramic layers bonded to polyethylene terephthalate substrates that selectively transmit visible light while rejecting infrared and ultraviolet radiation. Their primary commercial purpose is to reduce solar heat gain through glazed surfaces, lowering HVAC loads and extending interior material lifespans. Ceramic films now lead product type margins due to signal-transparency advantages in connected vehicles and smart buildings, while reflective films dominate volume in Middle Eastern architectural specifications where extreme solar irradiance demands maximum rejection. The transportation end user segment shows the fastest trajectory as electric vehicle manufacturers specify lightweight film solutions to reduce air-conditioning drain on battery range.
The US Environmental Protection Agency and Department of Energy shape demand through ENERGY STAR glazing performance benchmarks and tax incentive eligibility for building retrofits. India's Bureau of Energy Efficiency and Bureau of Indian Standards enforce mandatory cool-roof and fenestration codes that directly specify solar heat gain coefficients. China's Ministry of Ecology and Environment advances dual carbon goals that pressure commercial developers toward high-performance envelope materials. Stakeholders must monitor evolving national energy codes and automotive OEM specification shifts to anticipate which film technologies will secure preferential placement in procurement frameworks.
Market Dynamics
Building energy codes across Asia-Pacific are mandating solar heat gain coefficient thresholds that force specification of ceramic and nano-metallized films over conventional dyed alternatives, compressing legacy product margins while elevating performance-grade procurement.
Growth Catalysts
- China's dual carbon goals:The Ministry of Ecology and Environment pressures commercial developers to retrofit envelopes with high-rejection glazing, accelerating specification of sputtered ceramic films in tier-one cities.
- Automotive electrification:Electric vehicle manufacturers prioritize lightweight film solutions to reduce HVAC drain on battery range, creating pull for ultra-thin nano-ceramic laminates in assembly plant contracts.
- India's Bureau of Energy Efficiency mandates:Mandatory cool-roof and fenestration codes in the western corridor from Mumbai to Gujarat drive volume procurement for cost-engineered reflective films in new commercial construction.
Market Restraints
- Polyester resin cost volatility:Crude-linked feedstock fluctuations squeeze margins for film laminators dependent on spot-market polyethylene terephthalate resin.
- Concentrated sputtering equipment supply:German and Japanese vacuum coating system manufacturers create 18-24 month lead times for capacity expansion.
- Signal-interference limitations:Metallized films face specification bans in connected vehicle and smart building applications where 5G and V2X transparency is mandatory.
Strategic Opportunities
- Modular automotive aftermarket kits:Bundle ceramic tint with edge-sealing accessories to capture DIY installers shifting from professional application services.
- India's western corridor expansion:New automotive assembly plants in Gujarat create concentrated demand for OEM-specified solar control glazing in manufacturing facilities.
- US ENERGY STAR retrofit incentives:Tax credit eligibility for building envelope improvements drives replacement cycles in aging commercial stock across sun-belt states.
Industry Challenges
- Multi-layer sputtering technician scarcity:Vacuum coating expertise concentrates among aging workforces in Japan and Germany, constraining quality-controlled capacity scaling.
- Automotive OEM certification timelines:Windscreen film approval processes from NHTSA and equivalent bodies extend 24-36 months, freezing formulation changes mid-cycle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sun Control Films Market |
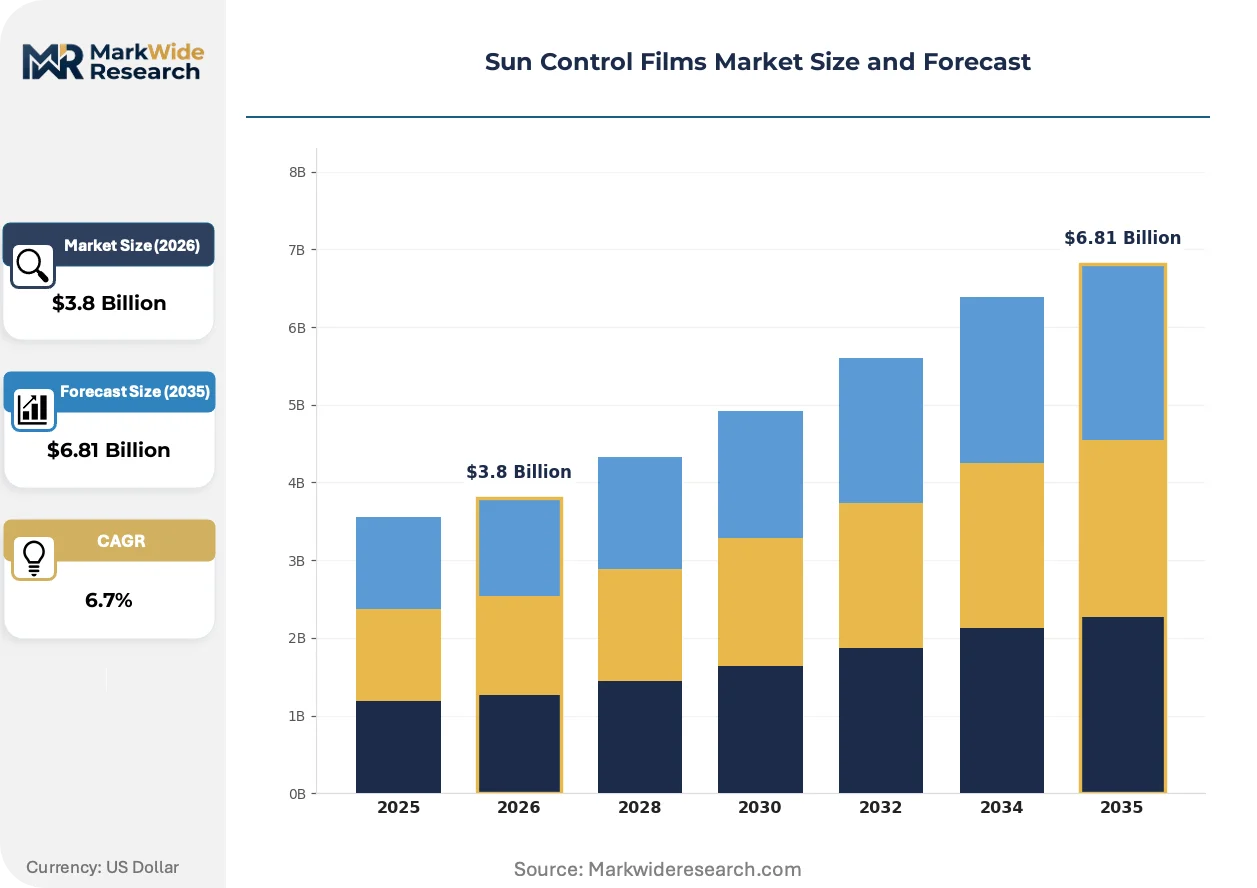
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clear Films, Tinted Films, Reflective Films, Ceramic Films Application: Automotive, Architectural, Decorative, Safety End User: Residential, Commercial, Industrial, Transportation Installation Type: DIY, Professional, Automotive Shops, Commercial Services |
| Companies Covered | Avery Dennison Corporation, Madico, 3M, LINTEC Corporation, Johnson Window Films, Eastman Chemical Company, Garware Hi-Tech Films, Toray Industries, Saint-Gobain, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sun Control Films Market Strategic Shifts
Automated deposition systems and AI-driven optical modeling are compressing product development cycles while regulatory benchmarking forces performance transparency across building and transportation applications.
Nano-ceramic multi-layer sputtering is automating precision control over infrared rejection spectra. Tier-one automotive glazing suppliers are adopting these systems at scale to meet OEM specifications for 5G-transparent solar control. The technology is automating quality consistency that previously required manual calibration, reducing batch-to-batch variance below 2%.
India's Bureau of Indian Standards and Bureau of Energy Efficiency have harmonized cool-roof and fenestration performance thresholds under mandatory labeling schemes. Commercial developers now face audit-linked penalties for non-compliance, forcing substitution of dyed films with metallized or ceramic grades. Western corridor construction from Mumbai to Gujarat shows the steepest specification upgrades as code enforcement tightens.
Fleet managers and commercial property owners are consolidating film procurement under performance-guaranteed service contracts rather than material-only transactions. Professional installation networks in the US sun-belt are unbundling after-sales warranty administration from product supply, capturing recurring revenue streams. This restructuring is most visible in California and Texas commercial retrofit markets where energy benchmarking disclosure laws create ongoing compliance obligations.
Sun Control Films Market Segmentation
Film specification in sun control markets hinges on thermal rejection targets, signal transparency requirements, and installation labor availability. Buyers navigate trade-offs between ceramic performance premiums and reflective film economics across automotive and building envelope applications.
Product Type:
Buyers select film chemistry based on solar heat gain coefficient mandates and electromagnetic transparency needs in connected environments.
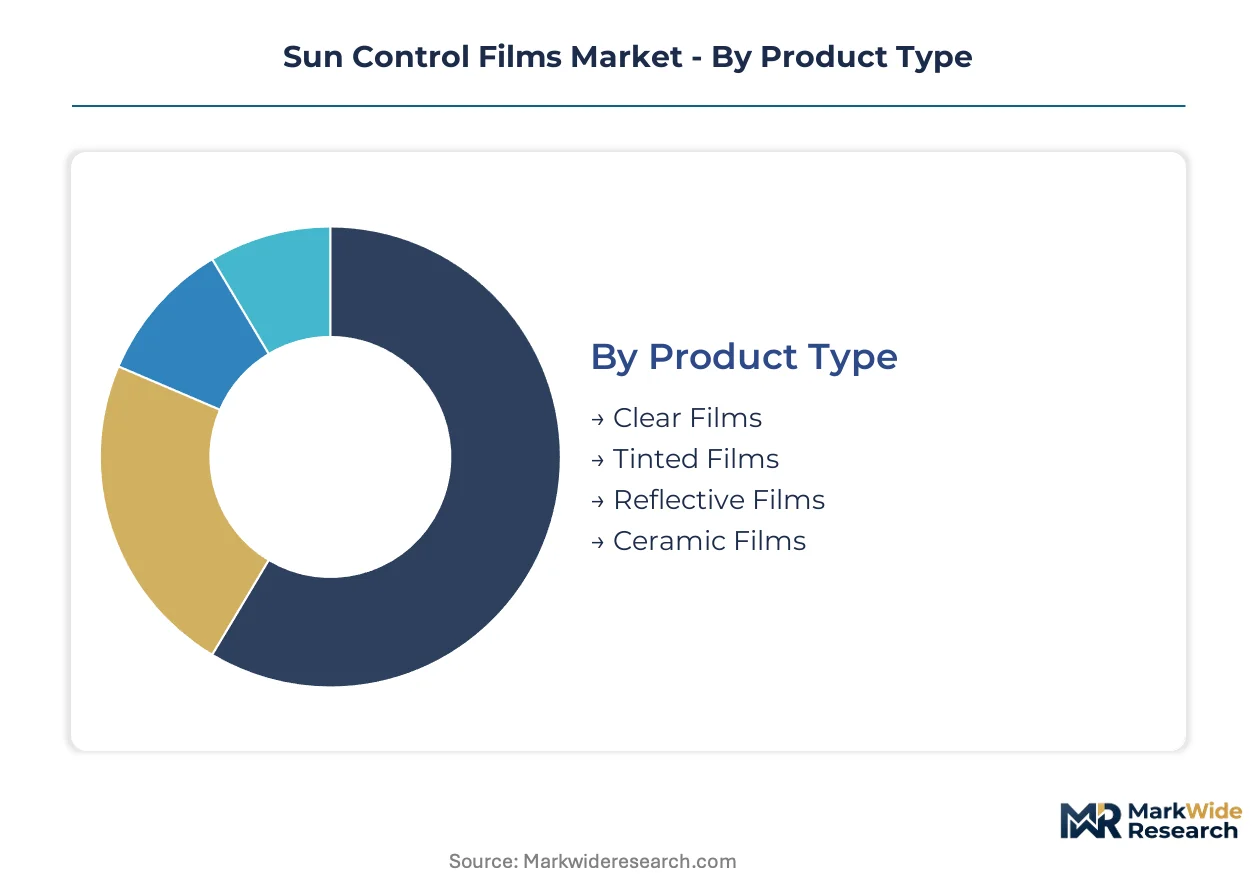
- Ceramic Films:Nano-ceramic multi-layer sputtering deposits metal oxides onto PET substrates, delivering infrared rejection without metallized signal interference. Electric vehicle manufacturers in China specify these for 5G-transparent windscreen integration, paying premium positioning to avoid V2X communication degradation.
- Reflective Films:Metallized aluminum or silver layers bonded to polyester achieve maximum solar reflectance through mirror-like surfaces. Middle Eastern commercial developers in Dubai and Riyadh specify these for facade retrofits under extreme irradiance conditions, accepting visible glare trade-offs for HVAC load reduction.
- Tinted Films:Dyed PET laminates absorb solar energy rather than reflecting it, suited for cost-constrained residential retrofits.
- Clear Films:Spectrally selective coatings reject ultraviolet and near-infrared while preserving visible light transmission for heritage building applications.
Reflective films lead on scale in Middle Eastern architectural specifications; ceramic films lead on momentum through automotive electrification and smart building connectivity mandates.
Application:
End-use concentration varies by regulatory pressure intensity and construction cycle timing across building and transportation sectors.
- Automotive:OEM assembly plants and aftermarket channels demand lightweight, optically precise laminates for side and rear glazing. India's western corridor from Mumbai to Gujarat shows concentrated procurement as new electric vehicle manufacturing facilities specify factory-applied solar control to minimize battery air-conditioning drain.
- Architectural:Commercial building retrofits and new construction specify films for envelope compliance with energy codes. US sun-belt property owners leverage ENERGY STAR tax incentives to fund reflective and ceramic installations in aging office stock.
- Decorative:Frosted, patterned, and colored films serve privacy and branding functions in retail and hospitality interiors.
- Safety:Shatter-resistant laminates combine solar control with glass retention for hurricane zones and security applications.
Architectural applications anchor volume through building code enforcement; automotive applications climb fastest as electrification reshapes thermal management priorities.
End User:
Procurement sophistication divides between compliance-driven commercial entities and price-sensitive residential buyers.
- Commercial:Property owners and facility managers negotiate performance-guaranteed service contracts bundling material, installation, and warranty administration. California and Texas commercial retrofits show unbundled procurement restructuring as energy benchmarking disclosure laws create ongoing compliance obligations.
- Transportation:Fleet operators and automotive OEMs specify films for fuel efficiency and battery range preservation. Electric vehicle manufacturers prioritize ultra-thin nano-ceramic grades to reduce HVAC electrical load.
- Residential:Homeowners select DIY or professional installation based on warranty requirements and technical confidence.
- Industrial:Manufacturing facilities with extensive glazing specify high-rejection films for worker comfort and process temperature stability.
Commercial end users dominate value capture through consolidated procurement; transportation end users gain share fastest via automotive electrification specifications.
Installation Type:
Labor availability and warranty terms shape channel selection between self-application and certified professional networks.
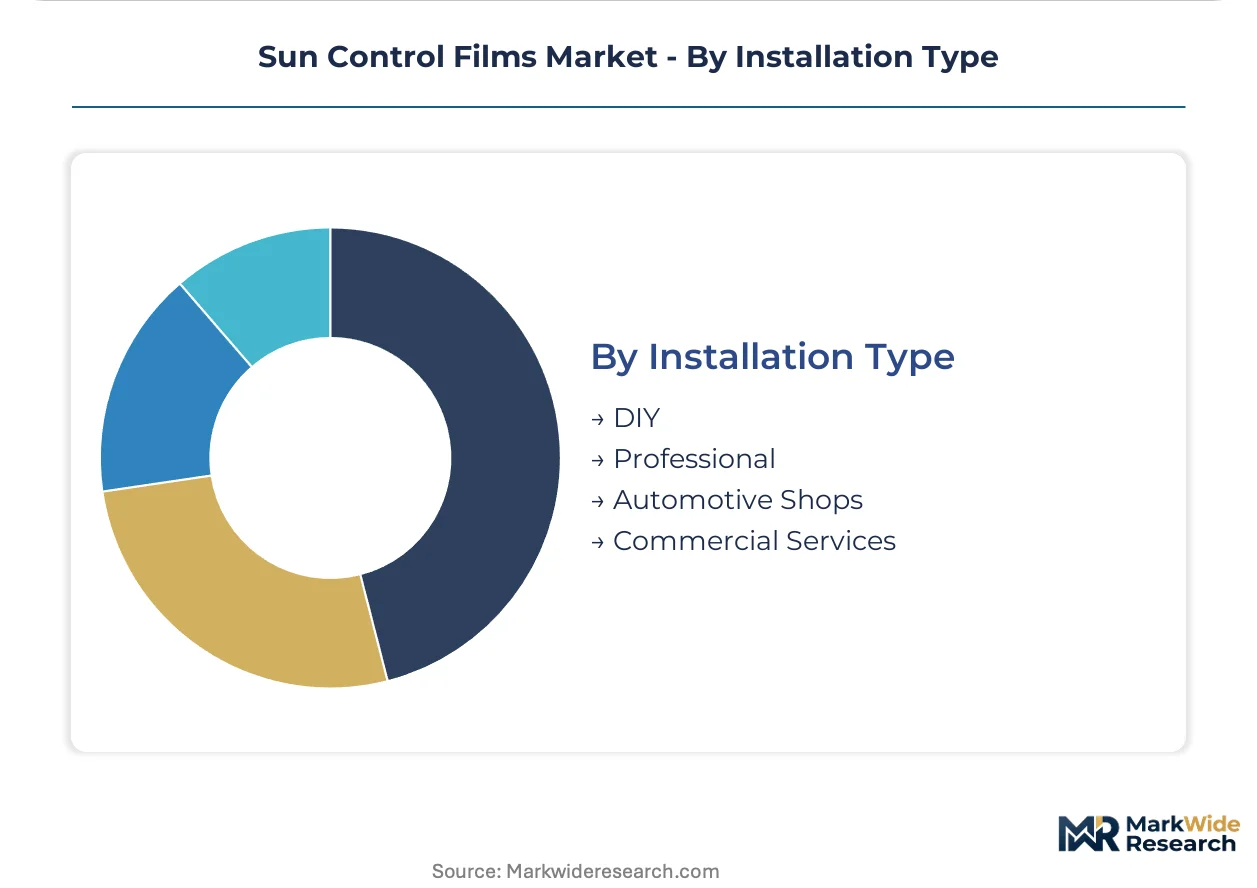
- Professional:Certified installers deliver manufacturer-backed warranties through controlled application environments. US sun-belt commercial retrofit markets show professional networks unbundling after-sales warranty administration from product supply to capture recurring revenue.
- Automotive Shops:Dealership and independent detailers bundle film application with vehicle purchase or service visits.
- DIY:Modular ceramic tint kits with edge-sealing accessories capture automotive aftermarket buyers shifting from professional services.
- Commercial Services:Large-scale property maintenance contractors execute multi-building retrofit programs for institutional owners.
Professional installation leads on scale through warranty requirements; DIY kits gain momentum fastest via modular product innovation and labor cost avoidance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The sun control films industry traces its commercial scale to the United States, where 3M pioneered multi-layer sputtering in the 1960s and established the technical foundation for metallized and ceramic grades now specified worldwide.
United States
Commercial building retrofits across California and Texas drive specification of reflective and ceramic films as property owners leverage ENERGY STAR tax incentives. The EPA and Department of Energy enforce glazing performance benchmarks that disqualify conventional dyed alternatives from incentive eligibility. Sun-belt cities from Phoenix to Miami show concentrated professional installation networks unbundling warranty administration from product supply.
China
Tier-one cities including Beijing and Shanghai are retrofitting commercial envelopes with sputtered ceramic films to meet dual carbon goals under Ministry of Ecology and Environment pressure. Updated green building standards mandate solar heat gain coefficient thresholds that compress margins for legacy dyed products. The Yangtze River Delta manufacturing corridor supplies nano-ceramic laminates to domestic electric vehicle assembly plants prioritizing 5G-transparent windscreen integration.
India
The western corridor from Mumbai to Gujarat concentrates demand for cost-engineered reflective films as new commercial construction and automotive assembly plants require extensive glazing treatment. The Bureau of Energy Efficiency and Bureau of Indian Standards enforce mandatory cool-roof and fenestration codes with audit-linked penalties for non-compliance. Gujarat's emerging electric vehicle manufacturing facilities specify factory-applied solar control to minimize battery air-conditioning drain.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg specify ultra-thin nano-ceramic grades for electric vehicle thermal management, creating pull for precision-coated laminates. REACH compliance and EU Green Deal carbon accounting pressure envelope material selection in commercial retrofits. Stuttgart and Munich engineering clusters concentrate vacuum coating equipment expertise that constrains quality-controlled capacity scaling across Europe.
United Arab Emirates
Dubai and Riyadh developers specify maximum-rejection reflective films for facade retrofits under extreme solar irradiance conditions. The Ministry of Energy and Infrastructure advances building efficiency codes that mandate high-performance envelope materials in new commercial stock. Jebel Ali industrial zone hosts film laminators serving Gulf Cooperation Council markets where visible glare trade-offs are accepted for HVAC load reduction.
Sun Control Films Market Competitive Environment
The competitive structure tilts toward diversified materials conglomerates with captive polyester supply and precision coating capabilities. Three to five multinational chemical and film specialists command premium positioning through multi-layer sputtering expertise, while regional laminators compete on cost-engineered formulations for price-sensitive specifications. Strategic moves concentrate on backward integration into resin production and geographic expansion through distribution partnerships in high-growth corridors.
Among diversified materials conglomerates, 3M and Eastman Chemical Company exemplify archetypes with upstream control over chemical intermediates and optical coating technologies. Garware Hi-Tech Films occupies a position within the Asia-Pacific cost-engineering tier, competing on volume supply for commercial installations across South Asia. Saint-Gobain represents the building materials integration archetype, leveraging envelope systems expertise to bundle film specification with structural glazing contracts.
| Leading Market Players |
|---|
| Avery Dennison Corporation |
| Madico |
| 3M |
| LINTEC Corporation |
| Johnson Window Films |
| Eastman Chemical Company |
| Garware Hi-Tech Films |
| Toray Industries |
| Saint-Gobain |
| Others |
Value Chain & Pricing Dynamics
Performance-grade certification divergence between sputtered ceramic and conventional dyed films manifests in both pricing premiums and supply chain configurations, with multi-layer deposition expertise concentrating in Japan and Germany while cost-engineered alternatives source from South Asian resin hubs.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates sputtered ceramic grades from metallized mid-tiers and dyed commodity films. Price differentiation rests on ENERGY STAR certification eligibility and automotive OEM approval status, with premium tiers commanding positioning for 5G-transparent specifications. Cost compression in economy-tier dyed laminates is intensifying because of polyester resin spot-market volatility. Residential DIY buyers exhibit highest price sensitivity, while electric vehicle manufacturers show lowest sensitivity due to battery range preservation priorities.
Supply Chain Analysis
Multi-layer sputtering technician scarcity in Stuttgart and Nagoya constrains quality-controlled capacity scaling for precision-coated laminates. Supply concentrates in China for nano-ceramic substrate production, the United States for captive polyester resin, and Germany for vacuum coating equipment. Raw material dependencies draw from crude-linked polyethylene terephthalate resin, metal oxide sputtering targets, and edge-sealing adhesive systems. Single-source vulnerability runs through German and Japanese vacuum coating equipment manufacturers. Distribution runs through professional installation networks in US sun-belt states and automotive OEM assembly plant contracts in India's western corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in sun control films hinges on ceramic grade substitution displacing legacy dyed volumes, with nano-ceramic sputtering yields improving as automated deposition systems compress batch variance.
For Market Incumbents: Deepen backward integration into polyester resin production to offset crude-linked feedstock volatility squeezing laminator margins. Anchor capacity expansion in India's western corridor to capture Bureau of Energy Efficiency mandate-driven procurement from Mumbai to Gujarat. Defend against emerging Asian cost-engineered entrants by securing automotive OEM certification timelines that freeze formulation changes. For New Entrants and Emerging Players: India's Bureau of Energy Efficiency mandates in the western corridor open a window for cost-engineered reflective film supply to new commercial construction and automotive assembly plants. Target modular automotive aftermarket kits bundling ceramic tint with edge-sealing accessories to capture DIY installers shifting from professional services. Pursue unbundled warranty administration contracts in California and Texas commercial retrofit markets. For Investors and Strategic Acquirers: Consolidation pressure builds where vacuum coating expertise concentrates among aging workforces in Japan and Germany, constraining quality-controlled capacity scaling. Long-term viability favors targets with captive resin supply and multi-layer sputtering technician pipelines. Watch NHTSA and equivalent automotive regulator specification shifts as inflection indicators for ceramic grade demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Production | Captive polyester supply insulates margins from crude-linked feedstock volatility. |
| Automated Deposition System Deployment | AI-driven optical modeling compresses ceramic film development cycles below manual calibration thresholds. |
| Geographic Expansion in India's Western Corridor | Bureau of Energy Efficiency mandates concentrate procurement from Mumbai to Gujarat. |
| Modular Aftermarket Kit Development | DIY ceramic tint bundles capture automotive buyers shifting from professional installation services. |
| Performance-Guaranteed Service Contract Unbundling | California and Texas commercial retrofits separate warranty administration from product supply. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with film laminator plant managers, automotive OEM procurement leads, commercial property facility managers, and professional installation network operators with secondary validation. Secondary sources drew from Bureau of Energy Efficiency compliance filings, ENERGY STAR glazing performance databases, customs trade data on polyethylene terephthalate resin, and automotive production registration records. Bottom-up segment sizing and top-down market triangulation cross-validated volume estimates.
Segment-weighting across product type, application, end user, and installation type dimensions drove analytical framework construction across the analysis window. Ceramic, reflective, tinted, and clear film chemistries were modeled against architectural, automotive, decorative, and safety applications. CAGRs derived from regression analysis of historical specification shifts and regulatory mandate enforcement timelines. Electric vehicle content-per-vehicle assumptions and building code solar heat gain coefficient thresholds served as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under polyester resin price volatility and sputtering equipment delivery delays. Projections reflect assumptions on regulatory enforcement intensity and automotive OEM specification adoption rates. Material deviation in Ministry of Ecology and Environment dual carbon goal acceleration or NHTSA windscreen film approval timeline compression warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Punnet Packaging Market
Packaging Materials
Thailand Packaging Market
Packaging Materials
Packaging Suction Cups Market
Packaging Materials
Expendable Packaging Market
Packaging Materials
Thermal Insulation Packaging Market
Packaging Materials
Cold Chain Packaging Materials Market
Packaging Materials
Global Adherence Packaging Market
Packaging Materials
France Packaging Market
Packaging Materials
Packaging Straps and Buckles Market
Packaging Materials
Production Page Volume Market
Packaging Materials
Single-Use Packaging Market
Packaging Materials
Asia-Pacific Airless Packaging Market
Packaging Materials
United Arab Emirates (UAE) Disposables (Single-Use) Packaging Market
Packaging Materials
Thermal Lamination Films Market
Packaging Materials
Hot-Melt Based Packaging Market
Packaging Materials
Reel in Box Market