
 Smart Surfaces Market | 2026-2036
Smart Surfaces Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Surfaces Market Intelligence
The shift from passive coatings to embedded sensor-actuator systems is fragmenting the traditional materials supply chain. This change creates openings for specialized material science firms. Corning Incorporated leverages its expertise in specialty glass to develop interactive panels for automotive cockpits and architectural facades. Separately, BASF SE competes with a broad portfolio of conductive and light-responsive chemical formulations, targeting large-scale industrial clients across multiple end-uses.
Smart surfaces are engineered materials with embedded functionalities that allow them to sense and react to environmental stimuli like light, temperature, or touch. Their responsiveness is typically achieved through the integration of piezoelectric sensors or electrochromic layers. Self-cleaning films and conductive coatings represent high-volume product categories. Demand from architectural enhancement applications for dynamic facades and smart windows is a primary growth engine, surpassing traditional consumer electronics use cases.
Regulatory frameworks increasingly influence material composition and performance claims. The EU’s RoHS directive restricts hazardous substances in electronic components, while the US EPA sets standards for chemical coatings. These rules compel manufacturers to invest in compliant, sustainable material innovations. Navigating the convergence of material science and digital technology will be critical for suppliers to secure long-term contracts with automotive and construction OEMs.
Market Dynamics
The convergence of material science with embedded electronics is the central force shaping the market. This integration transforms passive materials into active systems, fragmenting traditional supply chains and creating new value streams for firms specializing in sensor-actuator technologies.
Growth Catalysts
- Advanced Piezoelectric Materials:Innovations in piezoelectric films and sensors are enabling new human-machine interfaces. These materials are critical for developing touch-responsive controls in automotive cockpits and interactive architectural elements.
- Energy Efficiency Mandates:Regulations like the EU Green Deal are compelling the construction industry to adopt energy-saving technologies. This drives demand for smart windows and dynamic facades that optimize natural light and reduce HVAC loads.
- Automotive Sector Demand:The automotive industry's push for enhanced user experience and vehicle differentiation is a significant catalyst. Carmakers are integrating smart surfaces for dynamic ambient lighting, self-cleaning glass, and interactive dashboards.
Market Restraints
- High Material and Integration Costs:The initial investment for smart surface materials like electrochromic glass and conductive polymers remains substantially higher than for conventional alternatives, limiting adoption in cost-sensitive projects.
- Technical Integration Complexity:Embedding and wiring sensors, actuators, and control electronics into materials without compromising durability or aesthetics presents a significant manufacturing hurdle for both construction and automotive OEMs.
- Regulatory Compliance Overhead:Materials must comply with multiple frameworks, such as the EU's RoHS for electronics and REACH for chemical safety, which increases development costs and lengthens time-to-market.
Strategic Opportunities
- Healthcare and Sanitation Applications:The development of self-cleaning and antimicrobial surfaces presents a major opportunity. These materials can be deployed in hospitals and public transit to reduce surface contamination and improve hygiene.
- Expansion in Aerospace:The aerospace industry offers a niche for lightweight, multifunctional surfaces. Applications include dimmable cabin windows, ice-phobic wing coatings, and integrated structural health monitoring sensors.
- Data Monetization from IoT Integration:Connecting smart surfaces to IoT platforms allows for the collection of environmental and usage data. This opens avenues for offering data-as-a-service for predictive maintenance and space utilization analytics.
Industry Challenges
- Lack of Standardization:The absence of universal communication protocols and interoperability standards between different smart surface systems and building or vehicle control networks complicates system integration for end-users.
- Durability and Lifecycle Reliability:Ensuring the long-term performance and reliability of embedded electronic components when exposed to environmental stressors like UV radiation, moisture, and physical impact is a primary technical challenge.
- Specialized Workforce Scarcity:A talent gap exists for professionals who possess combined expertise in material science, electronics, and software engineering, which is necessary for developing next-generation smart surface products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Surfaces Market |
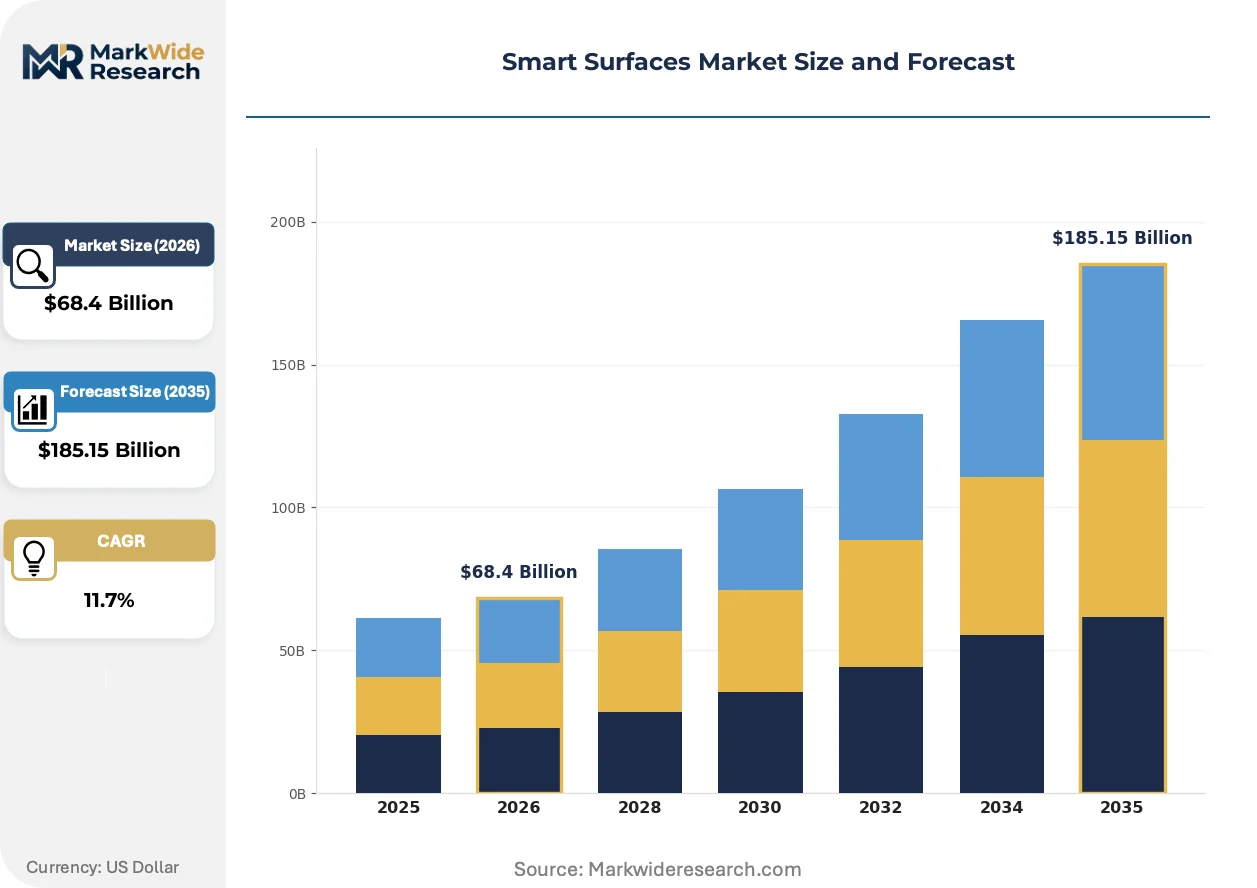
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $185.15 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Interactive Panels, Self-Cleaning Films, Conductive Coatings, Light-Responsive Films, Temperature-Sensitive Surfaces Technology: Capacitive Touch, Electrochromic, Piezoelectric, Thermochromic, Photovoltaic Application: Consumer Electronics, Smart Packaging, Architectural Enhancement, Transportation Interiors, Security Systems End User: Technology Developers, Packaging Manufacturers, Building Contractors, Automotive Suppliers, Security Providers |
| Companies Covered | Clariant AG, Evonik Industries AG, 3M Company, Corning Incorporated, AkzoNobel N.V., BASF SE, P2i Limited, Marelli Holdings Co., Ltd., DuPont de Nemours, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Surfaces Market Strategic Shifts & Innovations
The evolution of functional materials into intelligent, responsive systems is the dominant theme. This shift moves surfaces from being passive structural elements to active participants in an environment, capable of sensing, reacting, and communicating with other digital systems.
Self-Healing Polymers Self-healing polymers, which can autonomously repair minor scratches and abrasions through intrinsic chemical reactions, are a key material innovation. The automotive and consumer electronics sectors are adopting these for high-touch interior components and exterior coatings to enhance durability. This technology is hybridizing the function of a protective coating with active maintenance, reducing long-term ownership costs.
Building Performance Standards Energy performance standards for buildings, such as the mandates within the EU's Energy Performance of Buildings Directive (EPBD), are becoming more stringent. The directive compels property developers and owners to invest in technologies that reduce energy consumption. The architectural glass and facade segment is most affected, accelerating its shift toward dynamic glazing and insulated smart materials to meet these regulatory targets.
System-Level Procurement A notable shift is occurring where OEMs in automotive and construction are sourcing integrated smart surface systems rather than individual components. This change favors Tier 1 suppliers who can deliver pre-validated, assembled modules, displacing traditional distributors of films or coatings. This pattern is highly visible in Germany's advanced manufacturing sector, where efficiency and supply chain simplification are paramount.
Smart Surfaces Market Segmentation
Smart surfaces integrate advanced materials with embedded functionalities, creating responsive systems. Understanding the market segmentation reveals distinct value propositions and varying adoption rates across industries. This analysis dissects the market into key product types, underlying technologies, diverse applications, and primary end-users.
Product Type:
The turnover rates for smart surface product types vary significantly, with some components requiring frequent updates while others offer long-term durability in fixed installations.
- Interactive Panels:These advanced displays integrate touch, haptic feedback, and visual elements, often utilizing multi-layer glass or polymer substrates. Demand concentrates in automotive cockpits and high-end architectural facades, driven by user experience enhancements and aesthetic integration.
- Self-Cleaning Films:Self-cleaning films employ photocatalytic or superhydrophobic properties, actively repelling dirt, water, and contaminants from surfaces. The construction sector and automotive industry show strong demand, particularly for windows and mirrors, to reduce maintenance costs.
- Conductive Coatings:Conductive coatings provide electrical pathways on non-conductive substrates, crucial for touchscreens and electromagnetic shielding.
- Light-Responsive Films:These films dynamically adjust light transmission or reflection based on external stimuli, optimizing energy use in buildings and vehicles.
- Temperature-Sensitive Surfaces:Temperature-sensitive surfaces change properties in response to thermal variations, used for smart packaging indicators and thermal management.
Conductive Coatings dominates the installed base due to widespread use in consumer electronics. Interactive Panels is where expansion concentrates, especially within automotive applications.
Technology:
The underlying technologies exhibit a range of cost structures, influencing their viability for mass-market adoption versus specialized high-value applications.
- Piezoelectric:Piezoelectric technology converts mechanical stress into electrical energy and vice versa, enabling sensors, actuators, and energy harvesting. Its application in human-machine interfaces for automotive cockpits and structural health monitoring in aerospace drives significant investment.
- Electrochromic:Electrochromic materials reversibly change their optical properties, such as transparency or color, when an electrical voltage is applied. This technology sees substantial demand in smart windows for buildings and dimmable mirrors in vehicles, supporting energy efficiency mandates.
- Capacitive Touch:Capacitive touch technology detects human touch through changes in electrical fields, forming the basis for most modern touchscreens.
- Thermochromic:Thermochromic materials change color in response to temperature variations, often used for visual indicators and aesthetic effects.
- Photovoltaic:Photovoltaic technologies convert light energy directly into electricity, integrating power generation into surfaces like building facades.
Capacitive Touch technology currently holds the largest market share due to its ubiquity in consumer devices. Piezoelectric technology is gaining significant traction for its versatile sensing and actuation capabilities.
Application:
Applications for smart surfaces span diverse sectors, with some demanding high-volume, standardized solutions while others require highly customized, low-volume integrations.
- Architectural Enhancement:This application involves integrating smart surfaces into building envelopes, including dynamic facades, smart windows, and interactive interior elements. Demand is concentrating in Germany and other European markets, driven by energy efficiency mandates and aesthetic innovation in urban development.
- Transportation Interiors:Smart surfaces in transportation interiors include interactive dashboards, ambient lighting, and self-cleaning cabin surfaces. The automotive sector is a primary driver, focusing on enhanced user experience and vehicle differentiation through advanced human-machine interfaces.
- Consumer Electronics:Consumer electronics utilize smart surfaces for touchscreens, haptic feedback, and protective coatings in devices like smartphones and wearables.
- Smart Packaging:Smart packaging incorporates sensors or indicators into packaging materials for freshness monitoring, anti-counterfeiting, and user interaction.
- Security Systems:Security systems leverage smart surfaces for biometric authentication, integrated access controls, and tamper-evident features on sensitive assets.
Architectural Enhancement represents the fastest-growing trajectory for smart surface integration. Consumer Electronics continues to drive substantial foundational demand for established smart surface technologies.
End User:
The end-user landscape for smart surfaces is characterized by varying degrees of supply chain integration and direct procurement strategies.
- Automotive Suppliers:These entities integrate smart surface components into vehicle sub-assemblies and systems, supplying directly to original equipment manufacturers. Their procurement patterns favor system-level solutions and pre-validated modules to streamline manufacturing and ensure regulatory compliance.
- Building Contractors:Building contractors incorporate smart windows, dynamic facades, and interactive interior surfaces into commercial and residential projects. Demand for energy-efficient and aesthetically pleasing solutions drives their material choices, often influenced by local building codes.
- Technology Developers:Technology developers focus on research and innovation, creating new smart surface materials and integrating them into novel product concepts.
- Packaging Manufacturers:Packaging manufacturers adopt smart surfaces for functional packaging, including sensors for product freshness and interactive branding elements.
- Security Providers:Security providers implement smart surfaces in access control systems, surveillance equipment, and secure identification solutions.
Automotive Suppliers account for a significant portion of the total market spend on advanced smart surface integrations. Building Contractors are increasingly adopting these technologies to meet evolving sustainability standards.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export advanced smart surface components to automotive and construction OEMs across Europe and North America. This trade corridor highlights the market's reliance on specialized material science and precision engineering. Demand for energy-efficient and interactive solutions drives this cross-border supply, influencing global product development.
Germany
Demand for smart surfaces in Germany is propelled by its advanced automotive manufacturing and green building initiatives. The EU Green Deal mandates stringent energy efficiency standards, accelerating adoption of dynamic facades. Automotive clusters in Bavaria and Baden-Württemberg integrate interactive panels and self-cleaning films into next-generation vehicles.
United States
The United States market sees significant demand for smart surfaces in commercial construction and consumer electronics. The US EPA regulations for chemical coatings influence material innovation, favoring sustainable formulations. Technology hubs in California and the Pacific Northwest drive the integration of capacitive touch and light-responsive films.
Japan
Japan's smart surfaces market is characterized by strong demand from its automotive and electronics industries, focusing on advanced human-machine interfaces. METI initiatives support R&D in functional materials, promoting innovation in piezoelectric sensors. Major industrial centers like the Kanto region lead in developing self-healing polymers for durable consumer devices.
China
China experiences robust demand for smart surfaces, particularly in large-scale infrastructure projects and electric vehicle production. GB standards for product safety and environmental protection shape material development. Manufacturing zones in the Yangtze River Delta integrate smart glass and interactive displays into urban developments and automotive interiors.
South Korea
South Korea's smart surfaces market is driven by its leading position in consumer electronics and a rapidly expanding automotive sector. The country's national regulators emphasize product quality and technological advancement. Seoul Capital Area companies are at the forefront of developing advanced interactive panels and conductive coatings for next-generation devices.
Smart Surfaces Market Key Industry Players
Channel-controlling players compete with product-specialist players across a tiered market structure. The landscape exhibits fragmentation among material science firms, while system integrators consolidate offerings. Strategic archetypes include specialized material formulators, integrated component manufacturers, and application-specific solution providers. Dominant competitive moves involve strategic partnerships to co-develop integrated systems and portfolio diversification into high-growth application areas.
Specialists in advanced material formulations, such as BASF SE and Clariant AG, exemplify the chemical industry's pivot towards functional surfaces. These European-based entities occupy a position focused on developing broad portfolios of conductive and light-responsive chemical formulations. Their offerings target large-scale industrial clients across diverse end-uses, from architectural coatings to automotive interiors, emphasizing performance and sustainability. DuPont de Nemours, Inc. also sits within this archetype, providing specialized polymers and films that enable new smart surface functionalities for various industrial applications.
| Leading Market Players |
|---|
| Clariant AG |
| Evonik Industries AG |
| 3M Company |
| Corning Incorporated |
| AkzoNobel N.V. |
| BASF SE |
| P2i Limited |
| Marelli Holdings Co., Ltd. |
| DuPont de Nemours, Inc. |
Cost & Logistics Intelligence
Germany's advanced manufacturing clusters, particularly in automotive and construction, significantly influence downstream pricing power by consolidating demand for integrated smart surface systems. This concentration of procurement in key industrial hubs enables OEMs to dictate terms for pre-validated modules, impacting supplier margins across the value chain.
Pricing Analysis
Cost-plus contract patterns, often indexed to raw material inputs like specialty glass or conductive polymers, characterize the pricing for advanced smart surfaces. Price differentiation stems from the customization level required for architectural integration and the performance quality grade for automotive applications. Pricing pressure arises from the high initial investment costs for materials, which limits broader adoption in cost-sensitive projects. Building contractors and smaller consumer electronics manufacturers often exhibit the highest price sensitivity.
Supply Chain Analysis
Export-control regimes for advanced functional materials, especially those with dual-use potential, restrict technology flows and shape the smart surface supply chain. Supply concentrations in Germany, Japan, and South Korea provide core components like piezoelectric sensors and electrochromic layers. This market relies on specialized chemical formulations and embedded electronics. Regulatory restrictions, such as the EU's RoHS directive, pose a structural risk, increasing development costs. Distribution runs through Tier 1 suppliers who deliver pre-validated, assembled modules directly to automotive and construction OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a defensive moat story, primarily justified by the regulatory entrenchment created by stringent energy efficiency mandates and hazardous substance restrictions.
For Market Incumbents:
Build regulatory compliance moats by investing heavily in sustainable material innovations that meet or exceed frameworks like the EU Green Deal. Forge strategic partnerships with automotive and construction OEMs to co-develop integrated systems, mitigating the threat from specialized material science firms. Leverage certification investment in areas like REACH compliance to differentiate offerings and ensure long-term contracts.
For New Entrants and Emerging Players:
Healthcare and sanitation applications, particularly for self-cleaning and antimicrobial surfaces, represent the most penetrable entry point. The aerospace sector also offers niche opportunities for lightweight, multifunctional surfaces. A go-to-market angle focusing on application-specific solutions for high-value hygiene or weight-reduction problems can bypass established competition in broader segments.
For Investors and Strategic Acquirers:
Mid-cycle technology positioning favors integrated component manufacturers and specialized material science firms capable of delivering system-level solutions. The long-term viability of smart surfaces is strong, driven by the shift from passive materials to active, intelligent systems over the next 5-10 years. Monitor the adoption rate of standardization protocols as a key inflection indicator for broader market scalability.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Advanced Materials | Increases production of critical inputs like piezoelectric films, reducing single-source dependency for automotive OEMs. |
| Strategic Partnership with Automotive OEMs | Secures long-term contracts for interactive panels and self-cleaning films, driving product integration into next-generation vehicles. |
| Product Launch of Self-Healing Polymers | Enhances durability for high-touch interior components and exterior coatings, reducing maintenance costs for end-users. |
| Green Manufacturing Transition for Formulations | Ensures compliance with environmental regulations like US EPA standards, appealing to sustainability-focused building contractors. |
| Platform Integration for IoT Data | Enables data-as-a-service offerings for predictive maintenance and space utilization analytics in smart buildings. |
Research Approach
The analysis maps smart surface sub-sectors including Architectural Enhancement, Transportation Interiors, and Consumer Electronics, each validated through extensive primary interviews. Stakeholders included material science executives, automotive procurement leads, and construction project managers. Secondary research triangulated findings with regulatory filings from the EU RoHS and US EPA, industry association reports, and company financial disclosures, ensuring a robust bottom-up and top-down approach.
The forecast framework held macroeconomic conditions fixed, while varying technological adoption rates and regulatory impacts across the analysis window. Segmentation dimensions modeled included product type, underlying technology, diverse applications, end-user categories, and regional adoption patterns. Compound annual growth rates were derived from historical trends and projected market penetration rates, with energy efficiency mandates and automotive production volumes serving as key industry-specific forecast inputs.
Practitioners should monitor policy shifts in green building standards, advancements in material science, or supply chain disruptions for early signals of market redirection. Forecasts reflect assumptions regarding regulatory stability and technological progression. Material shifts in regulatory compliance frameworks or core material costs would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Next Generation Technologies
Hyperloop Technology Market
Next Generation Technologies
Enterprise Quantum Computing Market
Next Generation Technologies
5G New Radio Market
Next Generation Technologies
Next Generation Network (NGN) Equipment Market
Next Generation Technologies
Nearfield Communication (NFC) Market
Next Generation Technologies
Japan ICT Market
Next Generation Technologies
Next-Generation Communication Devices Market
Next Generation Technologies
Global Next Generation Wireless Communication Market
Next Generation Technologies
Next Generation Wireless Network Market
Next Generation Technologies
Ireland ICT Market
Next Generation Technologies
Poc Platform and Technology Market
Next Generation Technologies
Quantum Computing Market
Next Generation Technologies
Fog Computing Market
Next Generation Technologies
Europe Quantum Computing Market
Next Generation Technologies
Oman ICT Market
Next Generation Technologies
Malaysia ICT Market