
 Next-Generation Communication Devices Market | 2026-2036
Next-Generation Communication Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Next-Generation Communication Devices Market Foresight
Enterprise distribution channels for 5G infrastructure are reshaping how vendors reach industrial buyers. Huawei Technologies Co. Ltd. controls captive manufacturing of baseband processors and radio units, sustaining cost advantages across emerging markets. Cisco Systems Inc. competes through software-defined networking stacks that anchor its enterprise switching and routing portfolios. Nokia Corporation specializes in Open RAN architectures, positioning its portfolio for operators pursuing vendor diversification.
Next-generation communication devices integrate advanced radio frequency front-ends, beamforming antenna arrays, and low-latency protocol stacks to enable high-throughput data exchange across cellular and local-area networks. These systems typically operate in sub-6 GHz and millimeter-wave spectrum bands, with power amplifiers fabricated on gallium nitride substrates to achieve thermal efficiency at elevated frequencies. Smartphones and wearables dominate consumer-facing revenue pools, though enterprise-grade 5G routers and ruggedized tablets capture wider margins due to customization requirements and extended service contracts. Wi-Fi 6 and Bluetooth modules are embedding into laptops and tablets at accelerating rates, displacing legacy 802.11ac chipsets in refresh cycles.
The FCC governs spectrum auctions and device certification timelines in the United States, while ETSI coordinates harmonized standards across European member states and the EU AI Act imposes transparency obligations on connected devices with embedded intelligence. China's MIIT enforces domestic 5G base station deployment quotas and GB standards for electromagnetic compatibility, constraining market access for non-compliant imports. Stakeholders must monitor spectrum allocation decisions, semiconductor export controls, and evolving cybersecurity mandates to calibrate regional investment priorities.
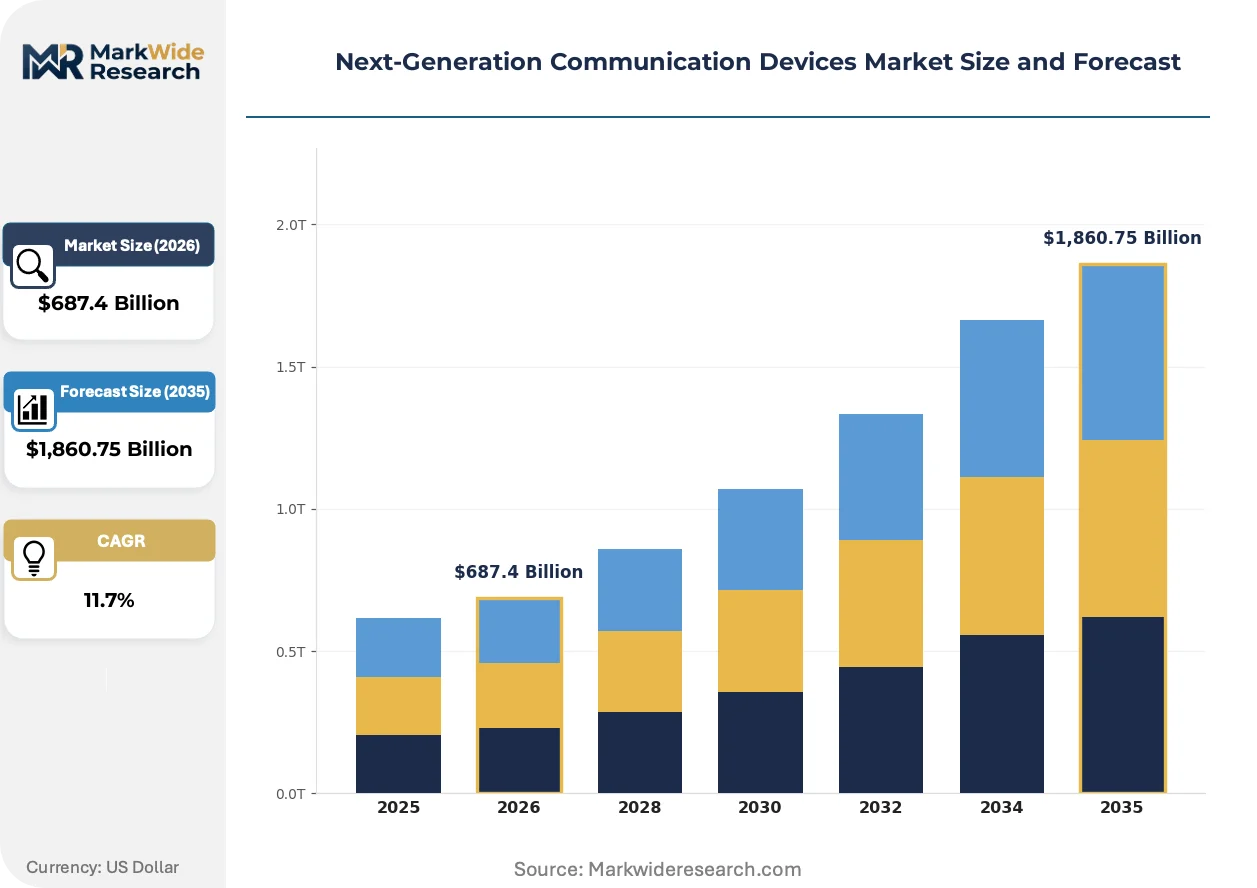
Market Dynamics
Spectrum reallocation mandates in the United States, Germany, and South Korea are compressing millimeter-wave infrastructure deployment timelines, forcing equipment vendors to accelerate radio frequency front-end development cycles while enterprise buyers consolidate procurement around 5G-enabled endpoints.
Growth Catalysts
- Enterprise 5G Adoption:Manufacturing floors and logistics hubs are deploying private 5G networks to replace Wi-Fi 4 and Wi-Fi 5 infrastructure, driving demand for ruggedized tablets and industrial routers with sub-6 GHz compatibility.
- China's MIIT Deployment Quotas:State-mandated 5G base station installation targets are sustaining procurement volumes for domestic equipment vendors and compatible terminal manufacturers across tier-one and tier-two cities.
- Gallium Nitride Substrate Maturation:Power amplifier fabrication on GaN substrates is achieving thermal efficiency at elevated frequencies, enabling beamforming antenna arrays in millimeter-wave spectrum bands.
Market Restraints
- Semiconductor Export Controls:Trade restrictions on advanced chip fabrication equipment are constraining baseband processor supply chains for non-domestic vendors in key manufacturing geographies.
- Millimeter-Wave Propagation Limitations:Signal attenuation through physical obstacles requires dense small-cell deployment, elevating total cost of ownership for outdoor coverage in urban canyons.
- ETSI Harmonization Friction:Divergent national implementations of Open RAN interface standards are fragmenting equipment interoperability across European member states.
Strategic Opportunities
- India's PLI Scheme for Telecom:Production-linked incentives for domestic 5G equipment manufacturing are attracting component assembly investments from multinational radio unit suppliers.
- Wi-Fi 6 and Bluetooth Convergence:Coexistence protocols enabling simultaneous operation in unlicensed spectrum are creating unified connectivity modules for laptop and tablet refresh cycles.
- EU AI Act Transparency Mandates:Compliance requirements for connected devices with embedded intelligence are opening certification service revenue streams for testing laboratories.
Industry Challenges
- Radio Frequency Engineering Talent Scarcity:Specialized expertise in beamforming algorithm development and antenna design is concentrated among a limited pool of experienced practitioners.
- Legacy 802.11ac Integration Complexity:Enterprise IT departments face protocol stack conflicts when bridging existing wireless infrastructure with 5G private network deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Next-Generation Communication Devices Market |
| Market Size in 2026 | $687.4 Billion |
| Market Size in 2035 | $1,860.75 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smartphones, Tablets, Wearables, Laptops Technology: 5G, Wi-Fi 6, Bluetooth, NFC End User: Enterprises, Consumers, Educational Institutions, Government Service Type: Cloud Services, Maintenance, Software Updates, Consultation |
| Companies Covered | Huawei Technologies Co. Ltd., Cisco Systems Inc., Netgear Inc., Telefonaktiebolaget LM Ericsson, Koninklijke Philips NV, Qualcomm Technologies Inc., Nokia Corporation, Samsung Electronics Co. Ltd., Analog Devices Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Next-Generation Communication Devices Market Shifts & Advancements
Open RAN disaggregation is dismantling vertically integrated supplier relationships, creating entry points for specialized radio unit vendors and software-defined networking stack providers.
Beamforming antenna arrays with active electronically scanned elements are digitizing signal processing at the edge of cellular networks. Industrial automation buyers in automotive assembly plants are deploying these systems to replace wired Ethernet for mobile robot coordination. This architecture is digitizing latency-sensitive control loops that previously required physical cable infrastructure.
The EU AI Act imposes transparency obligations on connected devices with embedded intelligence, requiring algorithmic decision documentation and human oversight interfaces. Equipment manufacturers serving European markets must redesign firmware architectures to support audit trails and explainability features. Smartphone and wearable producers face the steepest compliance burdens due to the volume of AI-enabled features in consumer-facing products.
Enterprise buyers are consolidating 5G infrastructure procurement through systems integrators rather than direct equipment vendor relationships. Manufacturing and logistics sectors are displacing traditional telecom reseller channels with specialized industrial connectivity consultants. This pattern is most pronounced in Germany, where Mittelstand firms rely on regional system houses for private network design and regulatory navigation.
Next-Generation Communication Devices Market Segmentation
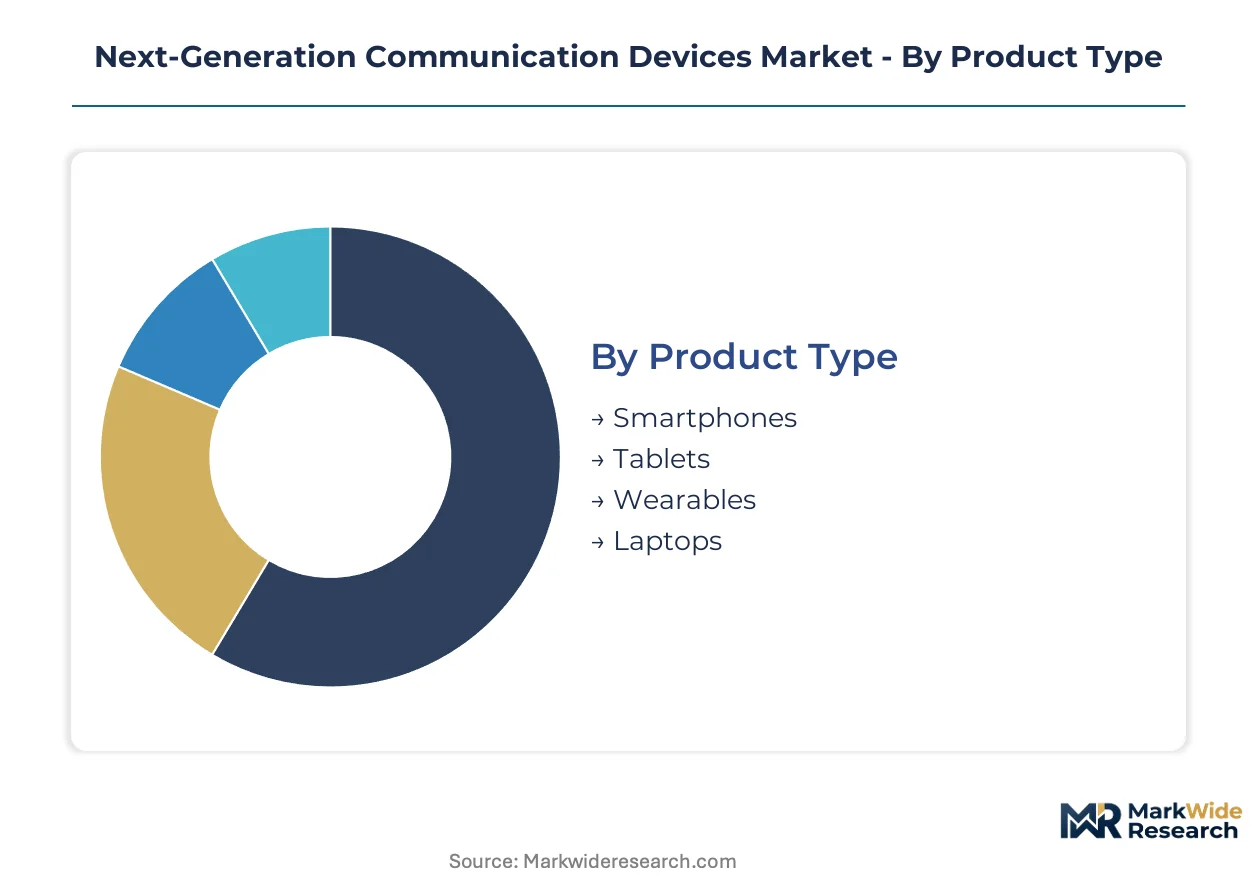
Next-generation communication devices require differentiated service architectures across hardware tiers. High-refresh-rate smartphones demand continuous firmware optimization cycles. Enterprise-grade tablets necessitate multi-year maintenance contracts with guaranteed uptime SLAs.
Product Type:
After-sales-service intensity varies dramatically across form factors, with ruggedized industrial tablets requiring field technician dispatch networks while consumer wearables rely on mail-in replacement programs.
- Smartphones:These devices integrate sub-6 GHz and millimeter-wave modems with gallium nitride power amplifiers for thermal efficiency. Procurement concentrates in China, where MIIT-mandated 5G rollout programs drive domestic vendor volumes for baseband-compatible terminals.
- Tablets:Enterprise and consumer variants split sharply on service requirements. Manufacturing floors in Germany source ruggedized units through regional system houses for private 5G network integration, with FCC certification timelines governing US import eligibility.
- Wearables:Bluetooth Low Energy and NFC modules enable health-monitoring ecosystems with minimal service touchpoints.
- Laptops:Wi-Fi 6 and 5G modem convergence in premium business segments displaces legacy 802.11ac infrastructure during corporate refresh cycles.
By volume, Smartphones leads. By growth pace, Tablets is ahead.
Technology:
Cost tier stratification separates premium radio frequency front-ends from commoditized short-range protocols, with beamforming arrays commanding tenfold pricing premiums over basic Bluetooth modules.
- 5G:Sub-6 GHz and millimeter-wave implementations require gallium nitride substrate fabrication for power amplifier thermal management. China's state-backed base station deployment quotas sustain procurement volumes for compatible terminals across tier-one and tier-two cities.
- Wi-Fi 6:OFDMA and MU-MIMO capabilities enable dense device concentration in enterprise environments. Logistics hubs in South Korea replace Wi-Fi 4 infrastructure with private 5G-Wi-Fi 6 hybrid networks to support automated guided vehicle coordination.
- Bluetooth:Low-energy protocols dominate wearable and peripheral connectivity with minimal certification overhead.
- NFC:Contactless payment and access control modules embed across smartphone and wearable form factors with standardized antenna specifications.
By installed base, Bluetooth dominates. By expansion trajectory, 5G is climbing the fastest.
End User:
Customer type determines procurement channel structure, with enterprise buyers consolidating through systems integrators while consumer segments flow through retail and carrier distribution.
- Enterprises:Manufacturing floors and logistics hubs deploy private 5G networks with ruggedized tablets and industrial routers. Germany's Mittelstand firms rely on regional system houses for network design and ETSI harmonization navigation.
- Consumers:Smartphone and wearable procurement concentrates through carrier subsidy programs and direct-to-retail channels with minimal post-sale service engagement.
- Educational Institutions:Bulk tablet and laptop procurement for one-to-one device programs emphasizes durability warranties and centralized fleet management tools.
- Government:Secure communications mandates drive specialized procurement for encrypted endpoints with domestic supply chain requirements.
By unit volume, Consumers leads. By margin expansion, Enterprises is gaining share fastest.
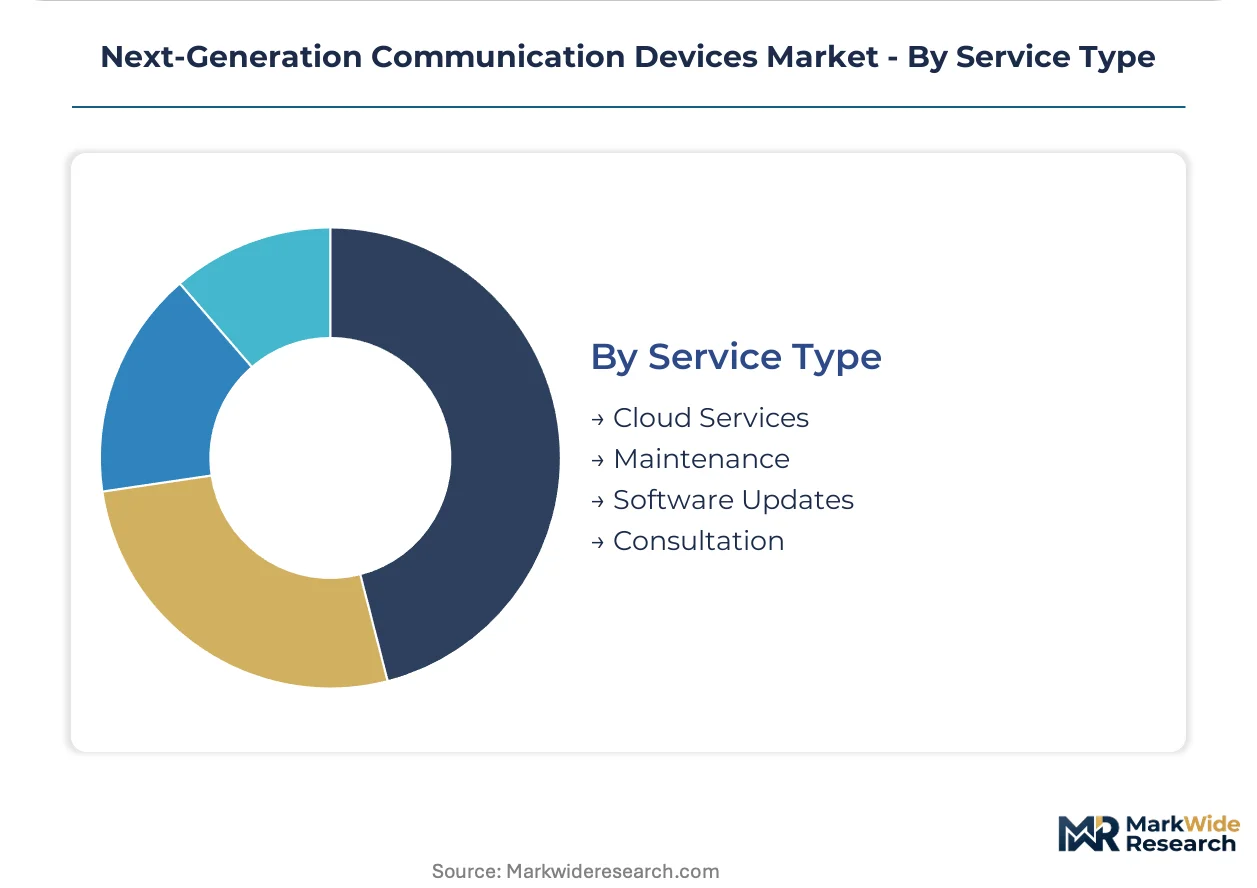
Service Type:
Margin structure inverts between hardware and recurring revenue streams, with cloud services and maintenance contracts capturing lifetime value multiples exceeding initial equipment sales.
- Cloud Services:Edge computing and device management platforms enable over-the-air configuration updates. Enterprise buyers in automotive assembly plants subscribe to mobile robot coordination services that replace wired Ethernet infrastructure.
- Maintenance:Field service networks for industrial tablets and routers command premium pricing due to radio frequency engineering talent scarcity and guaranteed uptime requirements.
- Software Updates:Firmware architectures must support EU AI Act audit trails and explainability features for connected devices with embedded intelligence.
- Consultation:Private 5G network design services fragment across regional system houses in Germany and specialized industrial connectivity consultants in the United States.
By revenue concentration, Maintenance leads. By growth pace, Cloud Services is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Submarine cable landing stations in Singapore anchor Southeast Asia's data traffic exchange, underwriting the city-state's role as a regional interconnection hub. Dense fiber backbones in Frankfurt and Amsterdam sustain Europe's cross-border bandwidth distribution. China's terrestrial trunk lines connecting coastal manufacturing zones to inland data centers compress latency for industrial automation networks.
United States
Private 5G network deployments in automotive assembly plants across Michigan and South Carolina drive demand for millimeter-wave radio units. FCC spectrum auctions in the 3.7-3.98 GHz C-band and 24 GHz millimeter-wave bands have accelerated infrastructure buildout timelines. Seattle's cloud computing corridor hosts edge data centers processing low-latency workloads for Pacific Northwest manufacturing clients.
Germany
Mittelstand manufacturers in Baden-Württemberg and Bavaria procure ruggedized industrial tablets through regional system houses for factory floor connectivity. ETSI Open RAN interface standards face divergent national implementations, fragmenting equipment interoperability across federal states. Munich's industrial automation cluster integrates beamforming antenna arrays into mobile robot coordination systems.
China
MIIT-mandated 5G base station installation targets sustain procurement volumes for domestic equipment vendors across tier-one and tier-two cities. GB standards for electromagnetic compatibility constrain market access for non-compliant imports. Shenzhen's electronics manufacturing ecosystem produces gallium nitride power amplifiers for thermal-efficient millimeter-wave infrastructure.
South Korea
Logistics hubs in Incheon and Busan deploy private 5G-Wi-Fi 6 hybrid networks to coordinate automated guided vehicle fleets. Spectrum reallocation mandates in the 28 GHz band compress millimeter-wave infrastructure deployment timelines. Seoul's digital media city cluster consumes high-throughput endpoints for content production and real-time broadcasting.
India
TRAI's production-linked incentive scheme for telecom equipment manufacturing attracts component assembly investments from multinational radio unit suppliers. Domestic 5G base station deployment accelerates in Maharashtra and Karnataka following spectrum auctions. Bangalore's technology corridor hosts firmware development centers for embedded intelligence compliance.
Next-Generation Communication Devices Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in radio frequency and baseband silicon. The vendor base stratifies across three tiers: vertically integrated infrastructure providers, software-defined networking stack vendors, and specialized radio unit fabricators. Two strategic archetypes dominate: captive semiconductor manufacturers sustaining cost advantages through in-house fabrication, and open architecture advocates positioning for operator diversification mandates. Competitive moves concentrate on strategic partnerships for spectrum access and portfolio diversification into edge computing services.
Among Asia-Pacific-based infrastructure providers, Huawei Technologies Co. Ltd. and Samsung Electronics Co. Ltd. occupy positions reflecting integrated manufacturing depth. European specialists Telefonaktiebolaget LM Ericsson and Nokia Corporation exemplify the open architecture vector. United States-based Cisco Systems Inc. and Qualcomm Technologies Inc. sit within the software-defined and silicon component tiers respectively. These six entities represent the competitive core, with component specialists Analog Devices Inc. and network equipment vendor Netgear Inc. anchoring upstream and downstream niches. Koninklijke Philips NV rounds out the landscape through connected health and consumer electronics positioning.
| Leading Market Players |
|---|
| Huawei Technologies Co. Ltd. |
| Cisco Systems Inc. |
| Netgear Inc. |
| Telefonaktiebolaget LM Ericsson |
| Koninklijke Philips NV |
| Qualcomm Technologies Inc. |
| Nokia Corporation |
| Samsung Electronics Co. Ltd. |
| Analog Devices Inc. |
| Others |
Supply & Pricing Matrix
Gallium nitride substrate fabrication in China and South Korea concentrates upstream thermal efficiency advantages, anchoring margin pools in millimeter-wave radio unit assembly rather than commoditized Bluetooth module production. Equipment vendors with captive GaN supply chains capture pricing power in beamforming antenna arrays while facing cost compression in legacy Wi-Fi 6 chipsets.
Pricing Analysis
Volume-discount tiering structures separate enterprise-grade 5G routers with multi-year service contracts from consumer smartphone spot purchases. Three-tier pricing structure across premium beamforming arrays, standard sub-6 GHz modems, and economy Bluetooth modules reflects certification grade and after-sales bundling intensity. Cost compression in economy tiers is intensifying because of gallium nitride substrate commoditization in Shenzhen manufacturing clusters. Enterprise buyers in German automotive assembly plants exhibit lowest price sensitivity due to uptime SLA requirements, while educational tablet procurement shows highest sensitivity to per-unit hardware costs.
Supply Chain Analysis
Export-control restrictions on advanced lithography equipment limit baseband processor flows from Netherlands and United States fabrication facilities to Chinese assembly plants. Supply chain concentration rests on Taiwan for RF front-end silicon, China for gallium nitride power amplifiers, and South Korea for millimeter-wave antenna substrates. Single-source vulnerability in beamforming algorithm IP creates chokepoints for specialized radio unit vendors. Distribution runs through systems integrators in Germany and carrier-locked channels in South Korea rather than direct equipment vendor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Next-generation communication devices represent a high-growth disruption as FCC spectrum reallocation and analogous mandates in Germany and South Korea compress millimeter-wave infrastructure deployment timelines, forcing procurement consolidation around 5G-enabled endpoints.
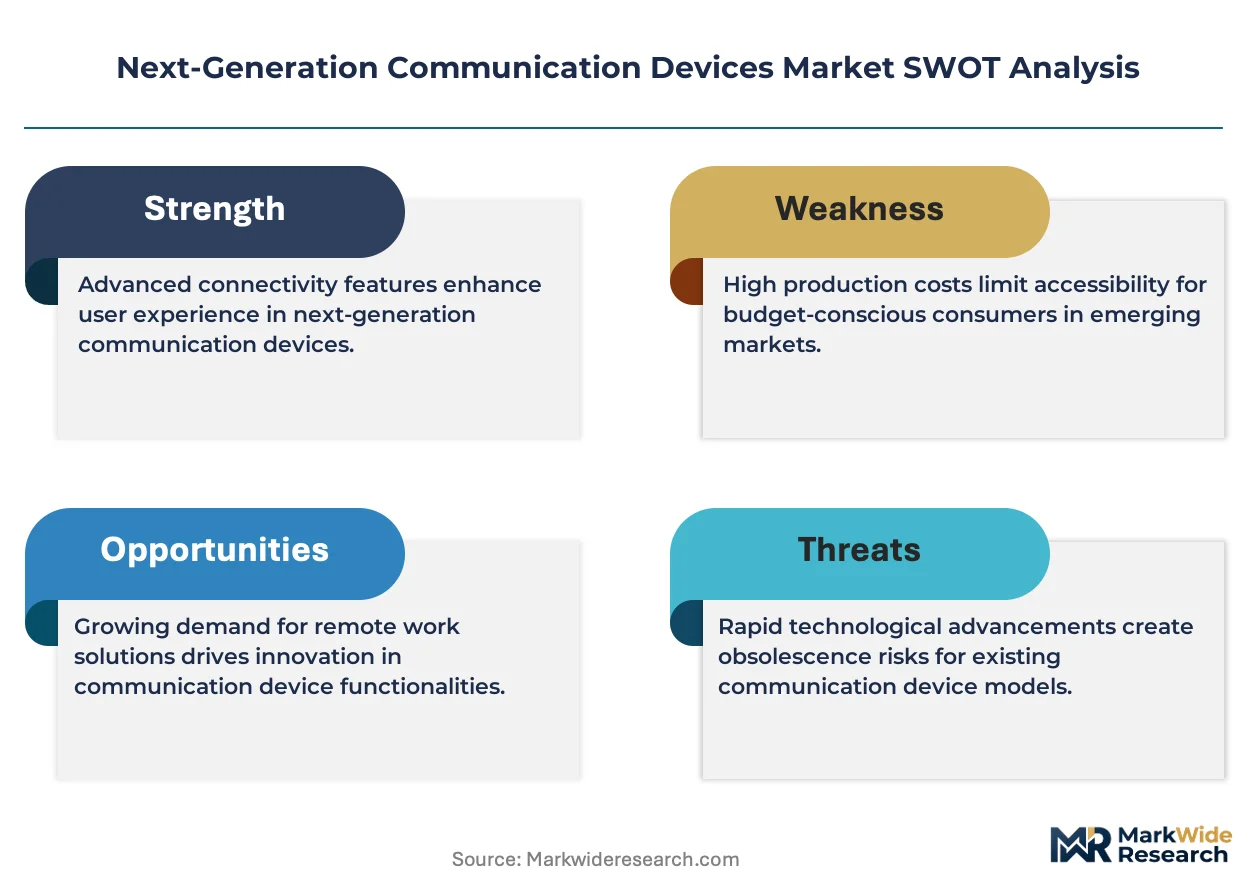
For Market Incumbents: Harden software-defined networking stack differentiation against Open RAN disaggregation threats by deepening in-house beamforming algorithm development. Secure captive gallium nitride substrate supply through backward integration into Chinese or South Korean wafer fabrication partnerships. Certification investment in EU AI Act transparency architectures protects European market access against compliance-driven procurement shifts. For New Entrants and Emerging Players: Build out specialized radio unit fabrication capabilities targeting India's PLI scheme for telecom equipment manufacturing, where component assembly incentives attract multinational supplier investments. Private 5G network design services for Mittelstand manufacturers in Germany present the most penetrable white-space, with regional system house partnerships as the essential go-to-market angle. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed industrial connectivity consultants consolidating procurement influence in manufacturing and logistics sectors. Long-term viability across the five-to-ten year window hinges on spectrum access portfolios and edge computing service attach rates. The signal to watch is Open RAN interface standard harmonization progress across ETSI member states, which would unlock vendor diversification procurement waves.| Strategic Initiative | Industry Significance |
|---|---|
| Gallium Nitride Substrate Backward Integration | Captive GaN supply from Chinese wafer fabs secures thermal efficiency advantages in millimeter-wave power amplifiers. |
| EU AI Act Compliance Certification | Algorithmic audit trail architectures from testing laboratories unlock procurement eligibility for European enterprise buyers. |
| Private 5G Network Design Services | Regional system house partnerships in Germany displace traditional telecom reseller channels for Mittelstand manufacturers. |
| Open RAN Software Stack Development | Disaggregated radio unit interfaces from Nokia and Ericsson architectures capture operator diversification mandates. |
| India PLI Scheme Manufacturing Footprint | Component assembly investments in Maharashtra and Karnataka attract production-linked incentive benefits for radio unit suppliers. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with RF engineering directors at base station vendors, procurement leads at German automotive OEMs, private network designers at regional German system houses, and firmware architects at smartphone manufacturers. Secondary validation drew from FCC spectrum auction records, ETSI Open RAN interface specifications, MIIT deployment quota announcements, and customs data on gallium nitride substrate trade flows. Bottom-up equipment shipment modeling and top-down service revenue aggregation were triangulated across the analysis window.
Calibration against historical base station installation trajectories in China and private 5G network adoption curves in Germany anchored the analytical framework. Segmentation dimensions modeled include product type, technology protocol, end-user archetype, and service intensity tier across the projection horizon. CAGRs were derived from installed base growth rates and average revenue per unit expansion in enterprise versus consumer segments. Forecast inputs incorporated spectrum reallocation timeline assumptions and semiconductor export control stringency indices.
Stress conditions across FCC certification delays, ETSI harmonization friction, and gallium nitride supply concentration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding MIIT quota enforcement and Open RAN adoption velocity. Material shifts in C-band spectrum auction participation or EU AI Act implementation timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Next Generation Technologies
Ireland ICT Market
Next Generation Technologies
Fog Computing Market
Next Generation Technologies
Jordan ICT Market
Next Generation Technologies
Bulgaria ICT Market
Next Generation Technologies
Information and Communications Technology (ICT) Market
Next Generation Technologies
Poc Platform and Technology Market
Next Generation Technologies
5G New Radio Market
Next Generation Technologies
Next Generation Network (NGN) Equipment Market
Next Generation Technologies
Nearfield Communication (NFC) Market
Next Generation Technologies
Enterprise Quantum Computing Market
Next Generation Technologies
Malaysia ICT Market
Next Generation Technologies
Hyperloop Technology Market
Next Generation Technologies
Quantum Information Processing Market
Next Generation Technologies
Japan ICT Market
Next Generation Technologies
Global Next Generation Wireless Communication Market
Next Generation Technologies
Oman ICT Market