
 South Africa Data Center Construction Market | 2026-2036
South Africa Data Center Construction Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Data Center Construction Market Insights
Project finance through sale-and-leaseback arrangements is tilting competitive dynamics toward operators with balance-sheet capacity to own land and utility interconnects. Equinix leverages its global credit rating to secure long-term power purchase agreements that anchor multi-phase campus developments. Teraco Data Environments sustains its position through deep vertical integration into fiber and substation infrastructure. Open Access Data Centres competes by specializing in modular build-to-suit delivery that compresses commissioning timelines for enterprise tenants.
South Africa data center construction encompasses the engineering, procurement, and physical assembly of mission-critical facilities housing servers, storage, and network equipment, typically requiring power densities exceeding 15 kW per rack and redundant cooling architectures. These structures serve as the physical backbone for cloud computing, financial transaction processing, and sovereign data residency compliance. Hyperscale deployments command the largest capital allocation pools, while edge nodes represent the fastest-growing footprint as latency-sensitive applications proliferate. Colocation remains the most mature revenue stream, though margin compression in standardized rack space is pushing operators toward managed services and interconnection layering.
The National Energy Regulator of South Africa governs grid connection timelines and tariff structures that directly determine project feasibility, while municipal bylaws in Johannesburg, Cape Town, and Durban impose varying zoning and environmental clearance requirements that extend permitting cycles. ISO 27001 and the country's POPIA data protection framework shape facility design standards around physical access controls and audit documentation. Stakeholders must weigh the trade-off between greenfield campus scale in underdeveloped corridors against brownfield retrofit speed in established fiber nodes.
Market Dynamics
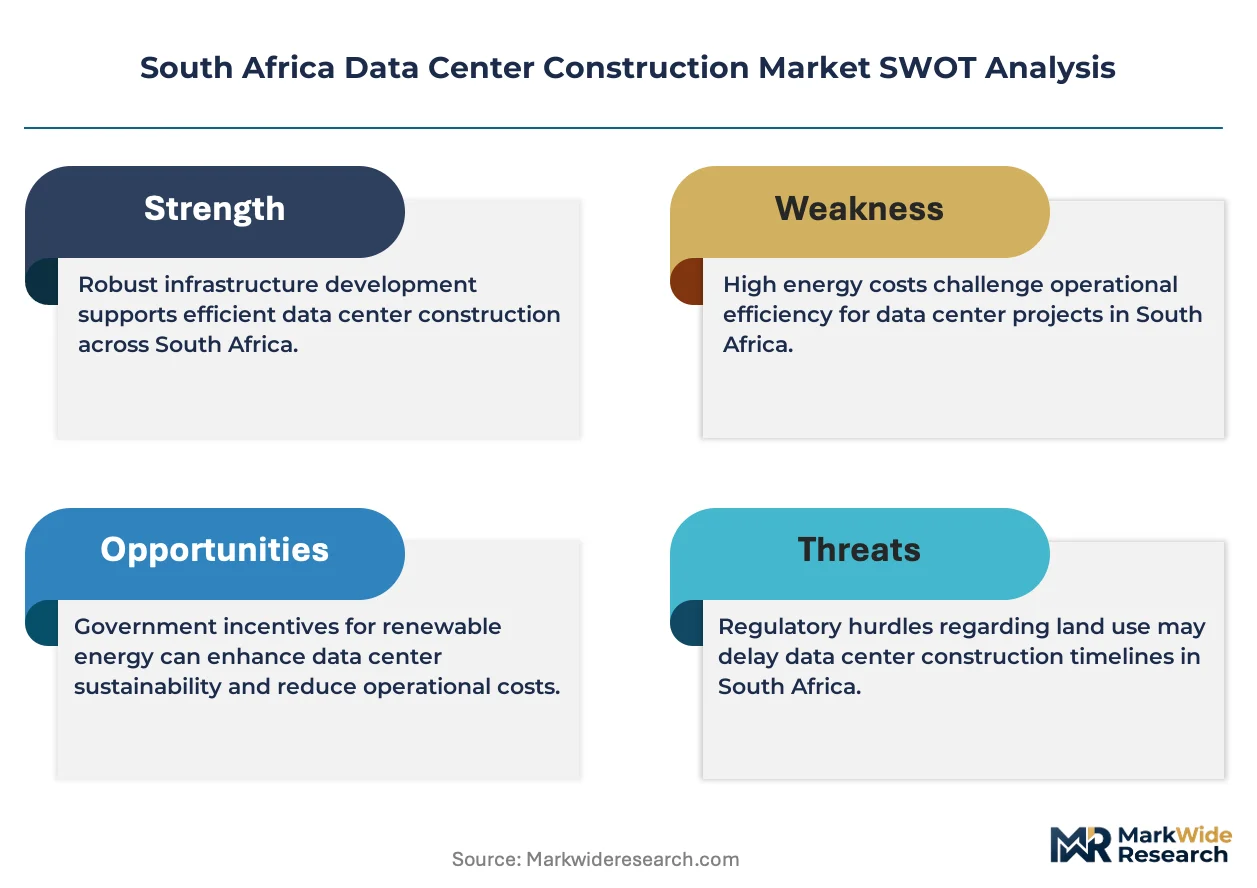
Grid interconnection timelines from the National Energy Regulator of South Africa now constitute the single largest determinant of project viability, compressing development cycles for operators unable to secure early substation allocation in Gauteng's northern corridor.
Growth Catalysts
- POPIA Compliance Mandates:Data localization requirements under South Africa's data protection framework compel financial institutions and healthcare providers to expand sovereign hosting capacity.
- Liquid Cooling Deployment:Power densities exceeding 15 kW per rack in hyperscale facilities drive adoption of immersion and direct-to-chip thermal management architectures.
- Cloud Service Provider Expansion:International hyperscalers anchor multi-phase campus developments through long-term power purchase agreements secured against utility interconnection reform.
Market Restraints
- Grid Connection Queuing:Municipal substation capacity constraints in Johannesburg extend commissioning timelines by 18-24 months for projects lacking pre-allocated transformer capacity.
- Land Scarcity Premium:Northern corridor site availability has compressed to under 50 hectares of developable land with fiber and power co-location.
- Construction Input Volatility:Steel reinforcement bar and copper busbar pricing fluctuations compress margin predictability for fixed-price EPC contracts.
Strategic Opportunities
- Western Cape Secondary Cluster:Cape Town's Atlantic Seaboard corridor offers lower land costs and submarine cable landing proximity for latency-sensitive workloads.
- Edge Node Distributed Architecture:5G network densification creates demand for sub-1 MW facilities in Durban, Port Elizabeth, and Bloemfontein.
- Renewable Energy Wheeling:Draft regulations enabling private power purchase agreement wheeling across municipal boundaries reduce grid dependency for off-grid campus designs.
Industry Challenges
- Mission-Critical Construction Labor Pool:Qualified MEP contractors with data center commissioning experience concentrate among three Johannesburg-based firms, creating bidding bottlenecks.
- ISO 27001 Certification Timeline:Physical access control documentation and audit trail system implementation extends operational readiness by 4-6 months post-construction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Data Center Construction Market |
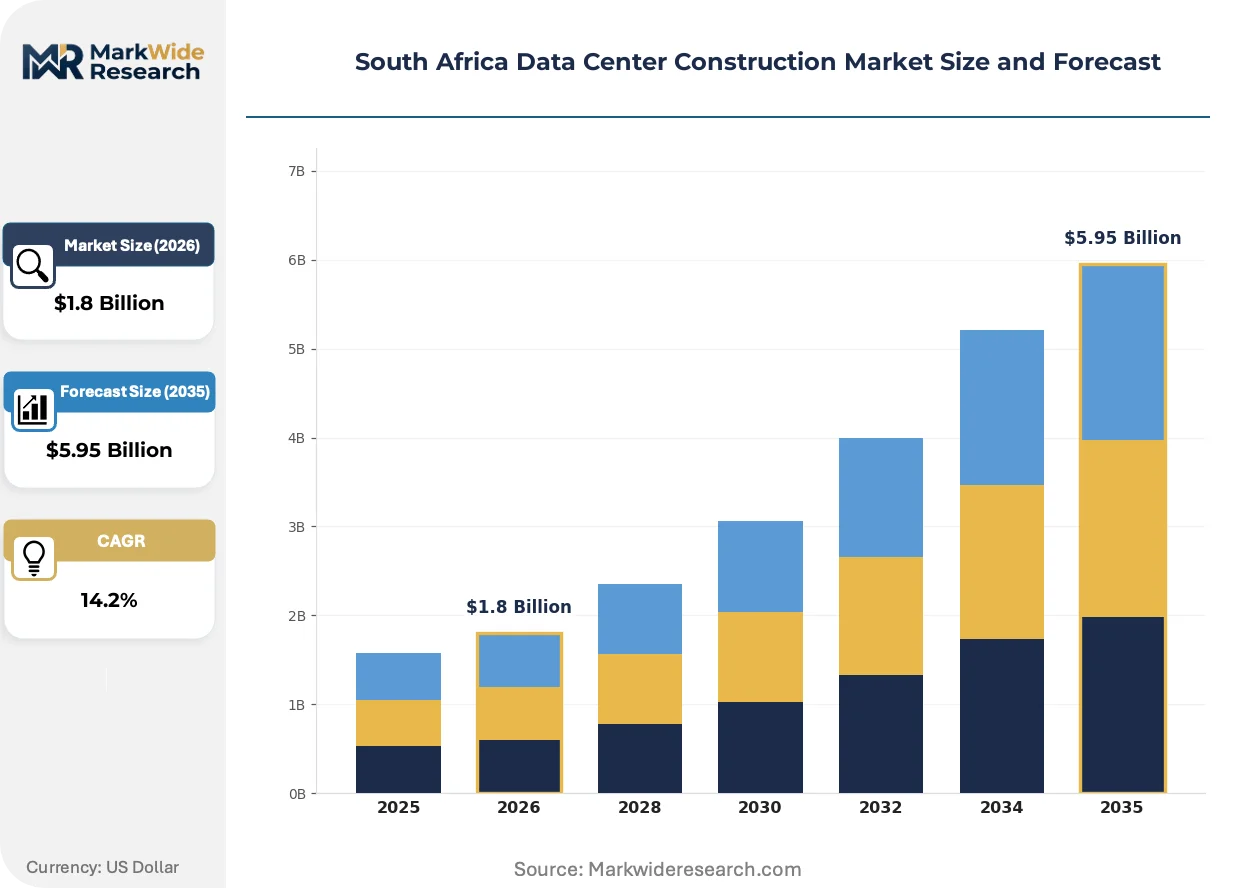
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Colocation, Hyperscale, Edge, Managed Services Power Source: Renewable, Grid, Diesel, Hybrid Construction Material: Steel, Concrete, Glass, Prefabricated End User: Telecom, IT Service Providers, Enterprises, Government |
| Companies Covered | Equinix, Open Access Data Centres, Teraco Data Environments, Digital Realty, IXAfrica Data Centres, Vantage Data Centers, NTT Global Data Centers, Google Cloud, Africa Data Centres, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Data Center Construction Market Trends and Innovations
Modular prefabrication and software-defined infrastructure are compressing traditional build schedules while thermal design shifts accommodate rack densities that exceed legacy cooling capacity.
Direct liquid cooling systems utilizing dielectric fluids and cold plate architectures are rendering obsolete air-cooled designs for racks above 20 kW density. Hyperscale operators in Johannesburg's northern corridor have standardized on immersion cooling for AI training clusters. This shift is rendering obsolete traditional CRAH unit specifications in new construction tenders.
The National Energy Regulator of South Africa's grid interconnection reform prioritizes data center loads in municipal planning frameworks. Developers must now secure substation allocation letters before zoning approval, reversing the traditional sequence. Western Cape municipalities have adopted accelerated permitting for facilities committing to 100% renewable energy sourcing.
Enterprise tenants now specify modular build-to-suit delivery with phased commissioning clauses rather than speculative shell construction. Colocation providers in Gauteng compete on compression of "power-on" milestones from 18 months to 9 months. Financial services firms drive this preference shift through penalty clauses tied to revenue-critical system migration deadlines.
South Africa Data Center Construction Market Segmentation
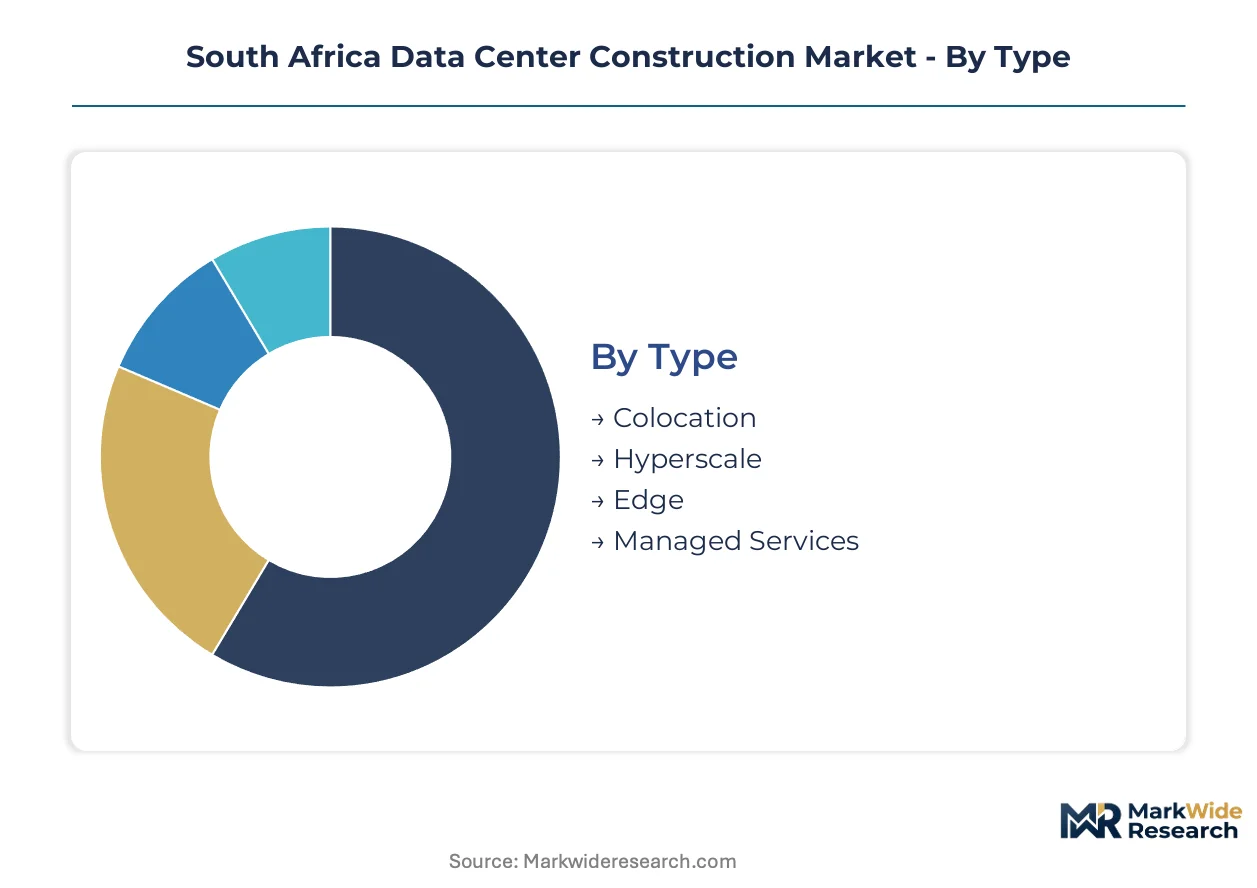
Construction specifications diverge sharply across deployment archetypes in South Africa's data center market. Power density requirements, cooling architectures, and commissioning timelines vary by an order of magnitude between hyperscale campuses and edge nodes, fragmenting contractor specialization and procurement patterns.
Type:
Mature colocation formats coexist with emerging edge architectures, creating a bifurcated contractor landscape where legacy skills and modular fabrication capabilities rarely overlap.
- Colocation:Multi-tenant facilities with standardized 4-8 kW rack densities dominate Johannesburg's northern corridor. Financial services firms and cloud resellers anchor lease commitments, though margin compression in commoditized rack space is pushing operators toward interconnection layering and managed services.
- Hyperscale:Single-tenant campuses exceeding 20 MW aggregate capacity command the largest capital allocation pools. International cloud service providers anchor these developments through long-term power purchase agreements secured against National Energy Regulator of South Africa grid interconnection reform.
- Edge:Sub-1 MW facilities address 5G network densification and latency-sensitive workloads. Cape Town's Atlantic Seaboard corridor and Durban are seeing concentrated demand for distributed nodes.
- Managed Services:Facilities combining physical infrastructure with operational outsourcing for enterprise tenants requiring sovereign data residency compliance under POPIA mandates.
Colocation handles the majority of throughput; edge is the fastest mover on share.
Power Source:
Cost tiers separate renewable-backed developments from diesel-dependent legacy sites, with hybrid configurations commanding premium valuations in land-constrained corridors.
- Renewable:Solar and wind power purchase agreements with private wheeling across municipal boundaries. Western Cape municipalities have adopted accelerated permitting for facilities committing to 100% renewable sourcing.
- Grid:Municipal substation interconnects from Eskom distribution networks remain the baseline, though queuing timelines now constitute the single largest determinant of project viability.
- Diesel:Backup generation sets for Tier III and Tier IV uptime compliance. Fuel storage regulations and emissions bylaws in Johannesburg and Cape Town impose additional civil works costs.
- Hybrid:Grid-primary with renewable offset and diesel reserve. This configuration dominates new hyperscale tenders seeking to reduce exposure to National Energy Regulator of South Africa interconnection delays.
Grid-connected sites retain the largest installed base; hybrid configurations are expanding most quickly as developers seek to de-risk commissioning timelines.
Construction Material:
Volume concentration in steel and concrete reflects established contractor capabilities, while prefabricated modules are displacing traditional build methods for speed-sensitive deployments.
- Steel:Structural frames and cladding for rapid envelope closure. Reinforcement bar pricing volatility compresses margin predictability for fixed-price EPC contracts.
- Concrete:Blast-resistant walls and thermal mass for passive cooling in Cape Town's temperate climate. Extended curing timelines conflict with enterprise tenant migration deadlines.
- Glass:Facade systems for aesthetic compliance in Cape Town's Atlantic Seaboard zoning districts. Limited structural role beyond architectural specification.
- Prefabricated:Modular data hall units factory-assembled with integrated MEP. Open Access Data Centres and similar specialists compress commissioning timelines through this approach.
Steel and concrete handle the majority of square meterage; prefabricated is gaining share fastest among hyperscale and edge deployments.
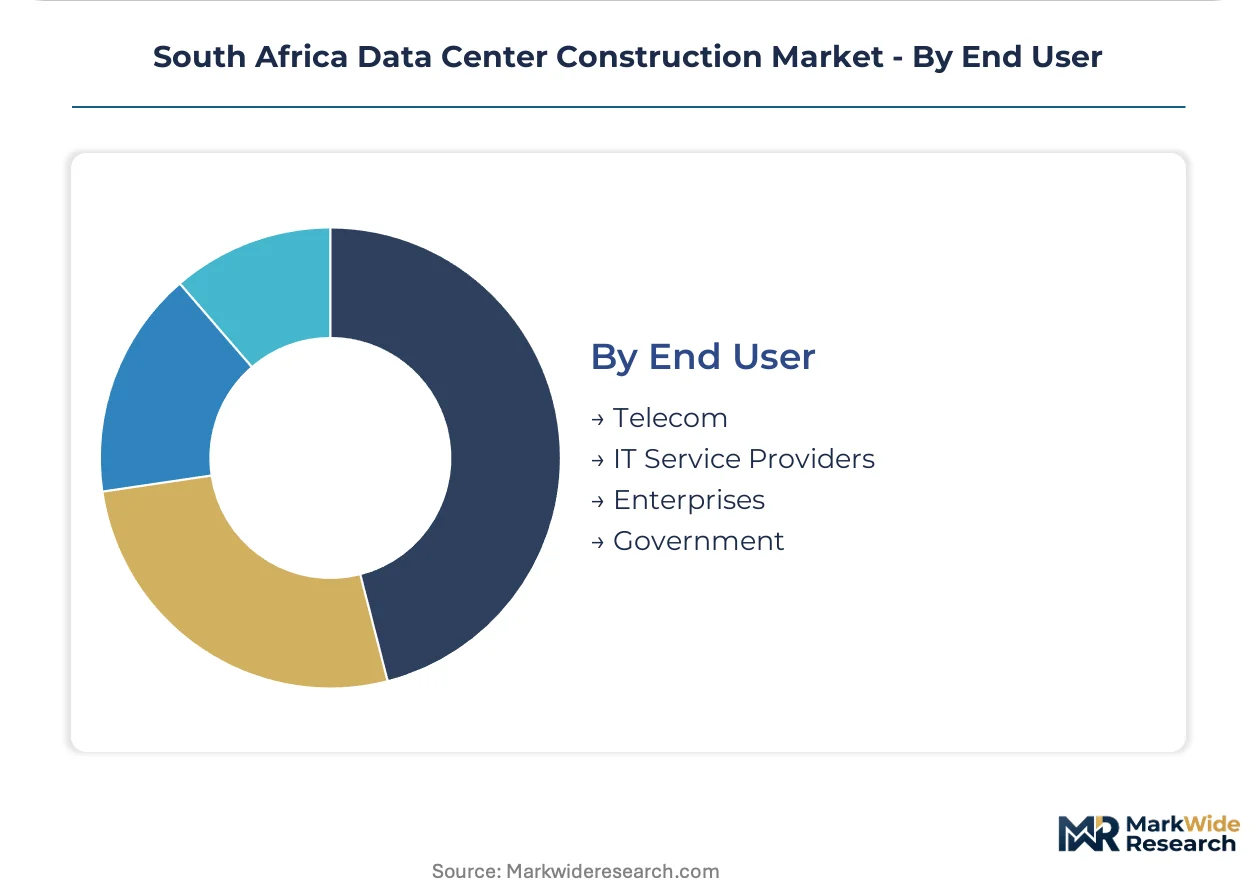
End User:
Customer type dictates redundancy tiers, compliance documentation, and geographic clustering, with financial services and sovereign entities driving the most stringent specifications.
- Telecom:Facilities supporting mobile network operator core infrastructure and 5G edge aggregation. Telkom, MTN, and Vodacom anchor demand in Gauteng and Western Cape.
- IT Service Providers:Multi-tenant environments serving mid-market enterprises through managed hosting and cloud brokerage. These operators compete on compression of power-on milestones.
- Enterprises:Single-tenant build-to-suit for financial institutions, healthcare providers, and mining houses. POPIA compliance mandates and latency requirements dictate site selection.
- Government:Sovereign cloud and critical infrastructure facilities subject to additional security clearance and domestic content requirements.
Enterprises and IT service providers handle the majority of capacity absorption; government is climbing the fastest as sovereign cloud initiatives accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Africa's data center construction market exhibits pronounced internal trade flow imbalances, with Gauteng and Western Cape importing specialized MEP engineering talent and prefabricated module assemblies from coastal manufacturing zones while exporting colocation services to neighboring SADC markets.
Gauteng
Johannesburg's northern corridor concentrates hyperscale demand from financial institutions and cloud service providers requiring sub-10ms latency to Sandton banking nodes. The National Energy Regulator of South Africa's grid interconnection reforms prioritize data center loads in municipal planning frameworks, reversing traditional permitting sequences. Midrand and Waterfall City anchor the densest cluster, where land scarcity has compressed developable parcels to under 50 hectares with co-located fiber and substation infrastructure.
Western Cape
Cape Town's Atlantic Seaboard corridor attracts latency-sensitive workloads requiring submarine cable landing proximity to Europe and Asia. Municipal bylaws in the City of Cape Town impose accelerated permitting timelines for facilities committing to 100% renewable energy sourcing. Stellenbosch and Paarl secondary nodes are emerging as lower-cost alternatives to northern corridor land premiums, though fiber backhaul capacity remains constrained.
KwaZulu-Natal
Durban anchors 5G edge aggregation demand from mobile network operators densifying coverage along the N3 logistics corridor. The eThekwini Municipality's zoning amendments for telecommunications infrastructure have streamlined environmental clearance requirements for sub-1 MW facilities. Umhlanga Ridge and Ballito sub-markets are seeing concentrated speculative development targeting enterprise disaster recovery deployments.
Eastern Cape
Port Elizabeth's Coega Industrial Development Zone offers purpose-built data center zoning with embedded renewable energy wheeling infrastructure. The Eastern Cape Development Corporation's investment incentives target facilities serving the automotive sector's industrial IoT requirements. Gqeberha's limited fiber diversity and distance from major internet exchange points constrain hyperscale attractiveness relative to primary corridors.
South Africa Data Center Construction Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream. The South Africa market structures around three distinct capability layers: global hyperscale operators with balance-sheet capacity for multi-phase campus ownership, regional specialists with deep vertical integration into fiber and substation infrastructure, and modular fabricators compressing commissioning timelines through prefabricated delivery. Competitive dynamics center on land and utility interconnect pre-positioning rather than price-based rivalry. Consolidation pressure operates through sale-and-leaseback arrangements that favor operators with investment-grade credit ratings.
Within the global operator tier, Equinix and Digital Realty exemplify balance-sheet-driven campus strategies anchored by long-term power purchase agreements. Regional specialists Teraco Data Environments and Open Access Data Centres occupy positions defined by infrastructure control depth rather than geographic scope alone. These five named entities collectively represent the competitive archetype spectrum: credit-rated platform ownership, vertical infrastructure integration, and modular build-to-suit velocity.
| Leading Market Players |
|---|
| Equinix |
| Open Access Data Centres |
| Teraco Data Environments |
| Digital Realty |
| IXAfrica Data Centres |
| Vantage Data Centers |
| NTT Global Data Centers |
| Google Cloud |
| Africa Data Centres |
| Others |
Pricing and Supply Chain Analysis
Steel reinforcement bar and copper busbar sourcing from Chinese and Turkish mills concentrates cost volatility in the hands of Johannesburg-based EPC contractors, pushing margin pools toward operators with captive procurement desks and long-dated fixed-price agreements.
Pricing Analysis
Cloud service providers and financial institutions anchor a project-based pricing structure where hyperscale campuses command fixed-price EPC contracts with penalty clauses tied to power-on milestones. Price differentiation separates Tier III certified facilities with redundant substations from Tier II builds with single-source grid dependency. Cost compression in standardized colocation rack space is intensifying because Open Access Data Centres and modular specialists compress commissioning timelines below 12 months. Mid-market enterprises exhibit highest price sensitivity, while sovereign entities and hyperscalers prioritize uptime guarantees over capital expenditure minimization.
Supply Chain Analysis
Prefabricated modular units and precision cooling equipment feed from manufacturing clusters in Germany, China, and the United States, with dielectric fluids and cold plate assemblies drawing from specialty chemical producers in South Korea and Japan. Steel structural frames, copper busbars, and diesel generator sets constitute the heaviest raw material dependencies. Single-source vulnerability concentrates in qualified MEP contractors with data center commissioning experience, where three Johannesburg-based firms control mission-critical labor pools. Distribution runs through direct EPC contracting for hyperscale developments and modular fabricator partnerships for edge deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must navigate substitution pressure from modular build-to-suit specialists that compress commissioning timelines and erode traditional EPC margins in standardized deployments.
For Market Incumbents: Insulate core hyperscale relationships through backward integration into substation infrastructure and fiber backhaul in Gauteng's northern corridor. Secure early allocation letters from the National Energy Regulator of South Africa before zoning approval to defend against Teraco Data Environments' vertical infrastructure control. Anchor multi-phase campus developments with long-term power purchase agreements that lock in tenant commitments across renewable energy wheeling configurations. For New Entrants and Emerging Players: Establish a beachhead in Western Cape secondary clusters where Cape Town's accelerated permitting for 100% renewable facilities creates lower land-cost entry points than Johannesburg's northern corridor. Target sub-1 MW edge nodes in Durban and Port Elizabeth where 5G densification demand outpaces incumbent capacity deployment. Differentiate through ISO 27001 certification pre-completion to capture financial services tenants with POPIA compliance mandates. For Investors and Strategic Acquirers: Capital is best deployed toward regional specialists with embedded utility interconnects and fiber control rather than speculative greenfield developers lacking substation allocation. Long-term viability rests on land and power pre-positioning in corridors where developable parcels with co-located infrastructure have compressed below 50 hectares. Monitor the National Energy Regulator of South Africa's grid interconnection reform implementation as the primary inflection signal for project pipeline acceleration or constraint.| Strategic Initiative | Industry Significance |
|---|---|
| Substation Infrastructure Pre-Positioning | Secures early transformer allocation from the National Energy Regulator of South Africa before competitors queue. |
| Liquid Cooling System Deployment | Enables hyperscale AI training clusters exceeding 20 kW per rack density in Johannesburg's northern corridor. |
| Renewable Energy Wheeling Agreements | Reduces grid dependency through private power purchase agreement structures across municipal boundaries. |
| Modular Prefabricated Delivery | Compresses commissioning timelines from 18 months to 9 months for enterprise tenant migration deadlines. |
| ISO 27001 Certification Investment | Captures financial services and healthcare POPIA compliance mandates with documented physical access controls. |
Research Methodology
The analysis maps colocation, hyperscale, edge, and managed services deployment archetypes, each validated through EPC contractors, data center operators, municipal planning officers, and enterprise IT procurement leads. Primary interviews with substation engineers and fiber network planners combined with secondary validation against Eskom distribution planning documents, National Energy Regulator of South Africa interconnection filings, and municipal zoning records. Bottom-up project pipeline tracking and top-down capex allocation analysis triangulate market sizing across construction material, power source, and end user segments.
Assumptions held fixed include the National Energy Regulator of South Africa's grid interconnection reform prioritization of data center loads, while renewable energy wheeling regulation timelines and steel input pricing were varied across sensitivity scenarios. Segmentation modeling spans facility type, power source configuration, construction material, and end user vertical throughout the forecast period. CAGRs derive from project-level commissioning schedules and tenant absorption rates, with hyperscale power density requirements and liquid cooling adoption curves as key demand-side inputs.
Sensitivities concentrate around municipal substation capacity constraints in Johannesburg extending timelines and construction input volatility compressing EPC margins. Cross-checking against hyperscaler public capex disclosures and municipal planning pipeline databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Poland Data Center Rack Market
Data Center Infrastructure
Singapore Data Center Server Market
Data Center Infrastructure
United States (US) Data Center Construction Market
Data Center Infrastructure
Norway Data Center Market
Data Center Infrastructure
Saudi Arabia Data Center Rack Market
Data Center Infrastructure
Sweden Data Center Rack Market
Data Center Infrastructure
New Zealand Data Center Power Market
Data Center Infrastructure
Europe Data Center Colocation Market
Data Center Infrastructure
Taiwan Data Center Market
Data Center Infrastructure
Italy Data Center Physical Security Market
Data Center Infrastructure
China Data Center Construction Market
Data Center Infrastructure
Brazil Data Center Rack Market
Data Center Infrastructure
Middle East and Africa Data Center Infrastructure Management Market
Data Center Infrastructure
Server Station Market
Data Center Infrastructure
Singapore Data Center Market
Data Center Infrastructure
Switzerland Data Center Construction Market