
 Hyperloop Technology Market | 2026-2036
Hyperloop Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Hyperloop Technology Market Analysis
Buyer concentration is recalibrating as transportation authorities and sovereign infrastructure funds consolidate procurement authority while private investors fragment across regional consortia. The Boring Company leverages its tunneling heritage to compete for underground vacuum-tube rights-of-way. TransPod Inc. anchors Canadian-European development corridors with proprietary propulsion designs. Hardt Global Mobility specializes in low-speed magnetic levitation interfaces that bridge conventional rail to hyperloop networks.
Hyperloop technology comprises sealed vacuum-tube transit systems that eliminate aerodynamic drag through partial or near-complete air evacuation, enabling passenger or freight pods to travel at speeds exceeding 700 mph using magnetic levitation and linear induction propulsion. The primary industrial purpose centers on displacing short-haul aviation and congested intercity highway corridors with zero-direct-emission ground transport. Vacuum tube infrastructure commands the deepest capital commitment and longest deployment timelines among technology segments, while propulsion systems concentrate the highest intellectual property density and supplier margin pools. Freight-oriented system types are gaining structural traction as port-to-inland logistics operators evaluate captive tube networks against diesel trucking cost volatility.
The US Department of Transportation and the Federal Railroad Administration are developing safety certification frameworks that will gate market access for commercial hyperloop corridors, while the European Union's TEN-T infrastructure funding criteria increasingly prioritize cross-border high-capacity transit links. Saudi Arabia's national transport regulator and the UAE's road and transport authority are advancing permitting sandboxes that attract developer capital ahead of codified standards. Stakeholders must monitor which regulatory jurisdiction first achieves enforceable certification protocols, as that geography will likely capture the initial wave of institutional infrastructure investment.
Market Dynamics
Sovereign infrastructure funds are consolidating procurement authority over vacuum-tube corridor development, pressuring developers to front-load safety certification costs before revenue streams materialize. This capital concentration is redrawing competitive entry barriers across the Middle East and North American pilot zones.
Growth Catalysts
- Saudi NEOM Corridor Commitments:Sovereign capital allocation to the Qiddiya-Red Sea route is validating commercial feasibility studies and attracting European engineering consortium participation.
- USDOT Emerging Guidance Framework:The Federal Railroad Administration's safety protocol development is creating certification clarity that unlocks institutional investor due diligence.
- Linear Induction Propulsion Maturation:Magnetic levitation interface standardization is reducing pod-to-tube integration risk and compressing supplier qualification timelines.
Market Restraints
- Steel and Composite Tube Input Volatility:Vacuum vessel fabrication depends on specialized alloy supply chains concentrated in East Asian foundries, exposing project budgets to commodity price swings.
- Permitting Timeline Uncertainty:The absence of codified hyperloop standards in US federal rail law forces developers to pursue case-by-case waivers, extending pre-construction phases.
- Short-Haul Aviation Substitution Economics:Regional jet operators in the Emirates and Texas corridor are pricing aggressively to retain premium passengers during pilot phase delays.
Strategic Opportunities
- UAE Logistics Corridor Sandboxing:Dubai's road and transport authority is permitting captive freight tube networks between Jebel Ali port and inland distribution centers ahead of passenger certification.
- EU TEN-T Cross-Border Funding Criteria:The European Union's infrastructure prioritization framework is channeling development capital toward Netherlands-Germany corridor feasibility studies.
- Maglev-Hyperloop Hybrid Interfaces:Conventional high-speed rail termini in Spain and Italy present pod-handoff integration points that extend network reach without full tube construction.
Industry Challenges
- Vacuum Engineering Talent Scarcity:The specialized skill set for large-scale pressure vessel maintenance and leak-rate certification is concentrated among aerospace contractors, creating recruitment bottlenecks.
- Pod-to-Tube Certification Sequencing:Safety validation requires simultaneous subsystem approval that compresses development schedules and strains testing facility capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hyperloop Technology Market |
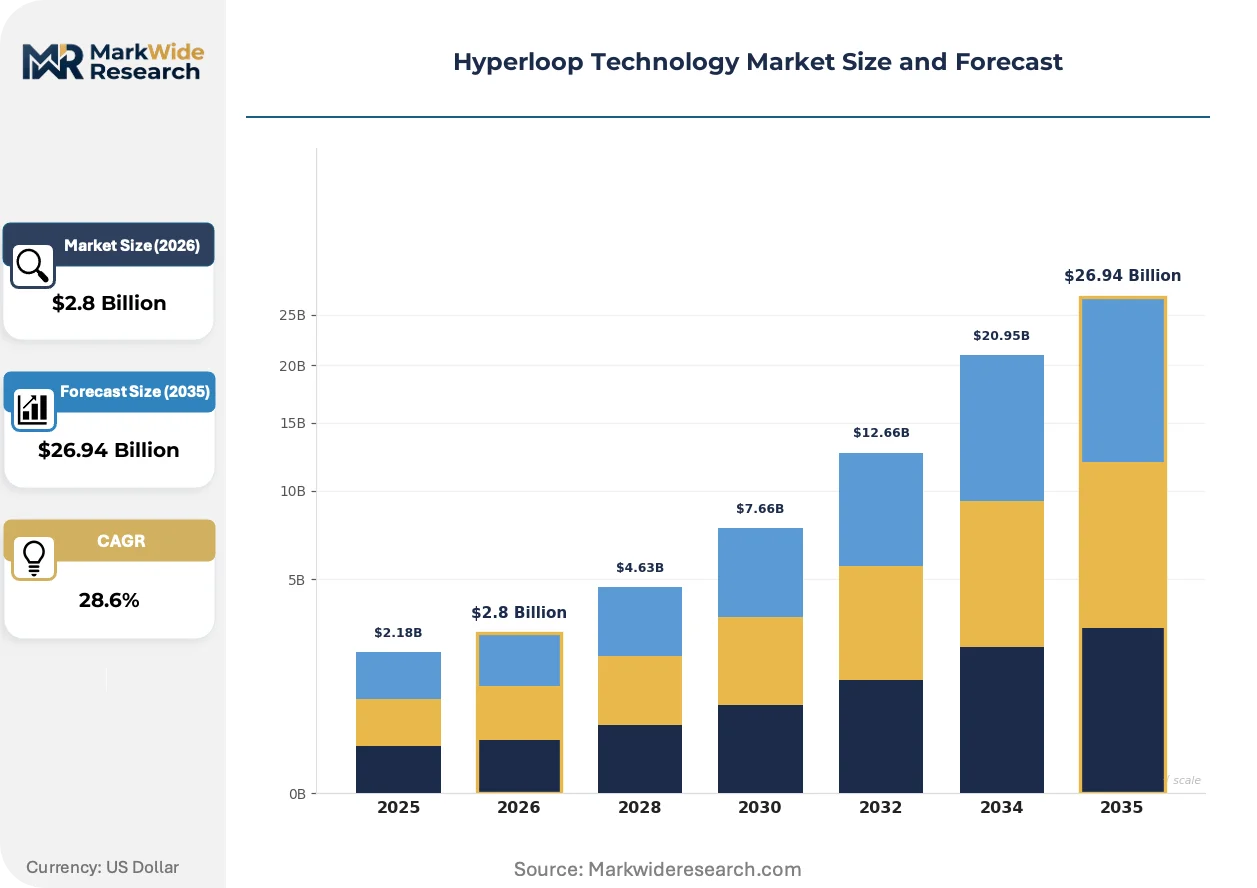
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $26.94 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Maglev, Vacuum Tubes, Propulsion Systems, Guidance Systems End User: Transportation Authorities, Governments, Private Investors, Infrastructure Developers Deployment: Urban, Intercity, Regional, International System Type: Passenger, Freight, Hybrid, Test Systems |
| Companies Covered | The Boring Company (SpaceX), TransPod Inc., Hyperloop Transportation Technologies, Nevomo, Zeleros Hyperloop, Virgin Hyperloop, Hardt Global Mobility, AECOM, Dinclix GroundWorks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hyperloop Technology Market Emerging Trajectories
Magnetic levitation and autonomous pod control systems are merging with civil tunneling advances, compressing the timeline between pilot demonstration and commercial corridor operation. Developers are racing to lock in proprietary interface standards before regulatory bodies mandate interoperability protocols.
Passive magnetic levitation using permanent magnet arrays is converging with active linear motor propulsion to eliminate onboard power systems and reduce pod weight. Freight operators in the Emirates are piloting this configuration for 300-mile port-inland routes. The convergence is collapsing the capital cost gap between hyperloop and conventional electrified rail.
The US Department of Transportation's emerging high-speed ground transit guidance is forcing developers to align pod safety systems with Federal Railroad Administration crashworthiness standards. This regulatory convergence is redirecting engineering resources toward redundant braking and emergency egress systems. Passenger corridor projects in Texas and the Midwest are absorbing the compliance cost burden most heavily.
Logistics buyers are consolidating procurement authority through sovereign infrastructure funds rather than fragmented private operators. This concentration is displacing venture capital from early-stage tube developers toward late-stage certification specialists. The shift is most visible in Saudi Arabia and the UAE, where transport authorities now dictate technical specifications in pre-development agreements.
Hyperloop Technology Market Segmentation
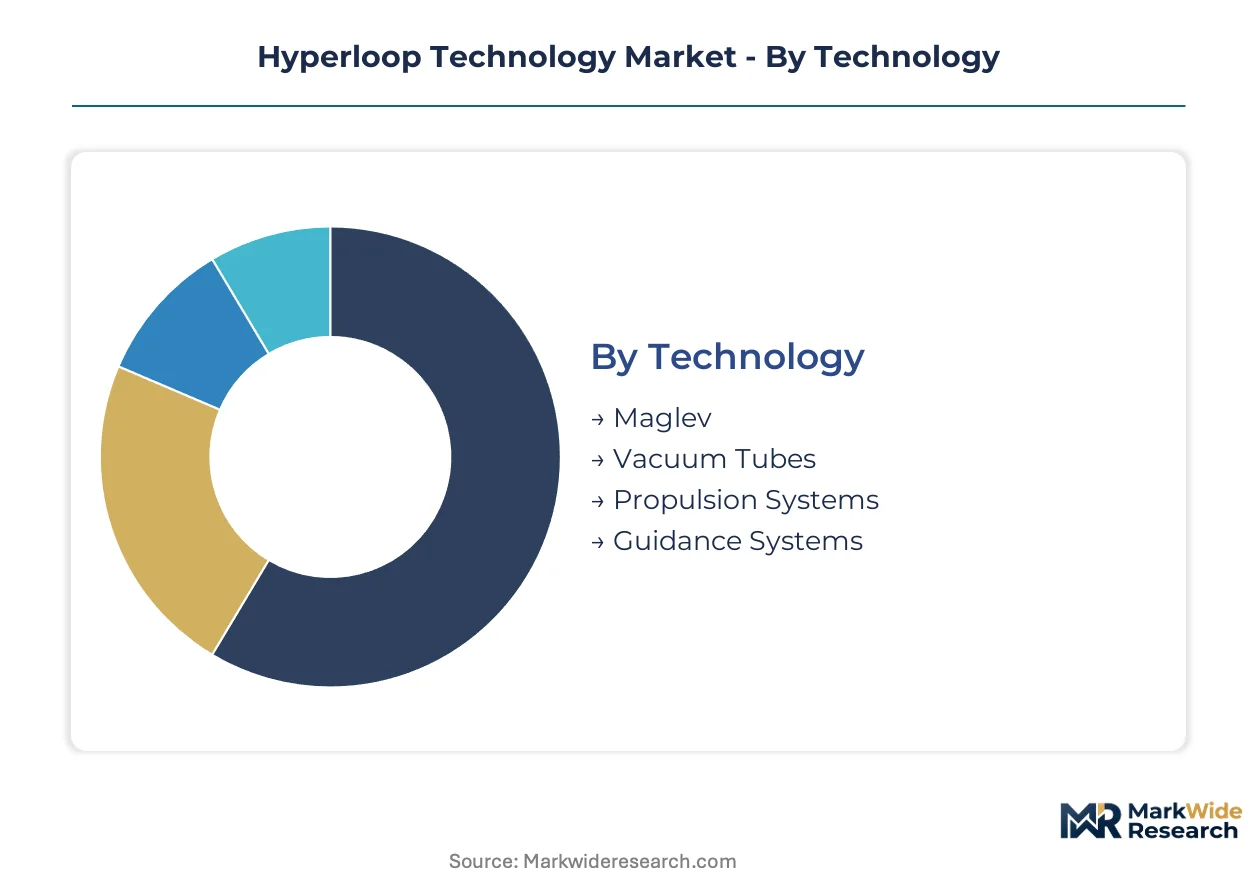
Segmentation in the Hyperloop Technology Market reveals how capital allocation and regulatory pressure concentrate across distinct technology layers and deployment scales. Understanding these divisions exposes where procurement authority consolidates and where supplier margins pool.
Technology:
Supply concentration in vacuum vessel fabrication and propulsion engineering creates divergent margin structures across technology tiers.
- Vacuum Tubes:Sealed pressure vessels require specialized alloy steel and composite fabrication from East Asian foundries. Saudi Arabia's NEOM corridor and UAE logistics pilots are absorbing the bulk of current tube procurement spend, though commodity price volatility strains project budgets.
- Propulsion Systems:Linear induction motors and magnetic levitation arrays concentrate the highest intellectual property density in the market. European engineering consortiums are locking in proprietary interface standards ahead of interoperability mandates from the US Federal Railroad Administration.
- Maglev:Passive permanent magnet arrays are converging with active motor systems to eliminate onboard power. Freight operators in Dubai are piloting this configuration for port-inland routes.
- Guidance Systems:Autonomous pod control and collision avoidance algorithms draw talent from aerospace contractors, creating recruitment bottlenecks.
Today's leader: Vacuum Tubes. Tomorrow's challenger: Propulsion Systems.
End User:
Customer type determines contract structure, with sovereign funds demanding front-loaded certification and private investors seeking revenue-sharing mechanisms.
- Transportation Authorities:Dubai's Road and Transport Authority and Saudi Arabia's national transport regulator now dictate technical specifications in pre-development agreements, consolidating procurement authority over corridor rights-of-way.
- Governments:The US Department of Transportation's emerging guidance framework is gating market access through Federal Railroad Administration safety protocols, forcing developers to absorb compliance costs before commercial deployment.
- Private Investors:Venture capital is fragmenting across regional consortia as late-stage certification specialists displace early-stage tube developers.
- Infrastructure Developers:The Boring Company leverages tunneling heritage to compete for underground vacuum-tube rights-of-way in North American pilot zones.
Transportation Authorities capture current procurement volume. Infrastructure Developers are climbing fastest as sovereign capital seeks turnkey delivery partners.
Deployment:
Geographic span of corridors dictates regulatory complexity and capital intensity, with longer routes facing multiplied permitting jurisdictions.
- Intercity:Routes between major population centers like the Texas corridor and Netherlands-Germany links attract EU TEN-T funding and USDOT certification focus, compressing timelines between pilot and commercial operation.
- Regional:Cross-border corridors face the steepest regulatory burden, requiring simultaneous subsystem approval that strains testing facility capacity.
- Urban:Short-distance networks within metropolitan areas encounter localized land acquisition challenges and municipal permitting layers.
- International:Transcontinental routes remain conceptual due to unresolved standard harmonization between national rail regulators.
Intercity dominates committed capital. Regional corridors hold steepest expansion trajectory once certification protocols converge.
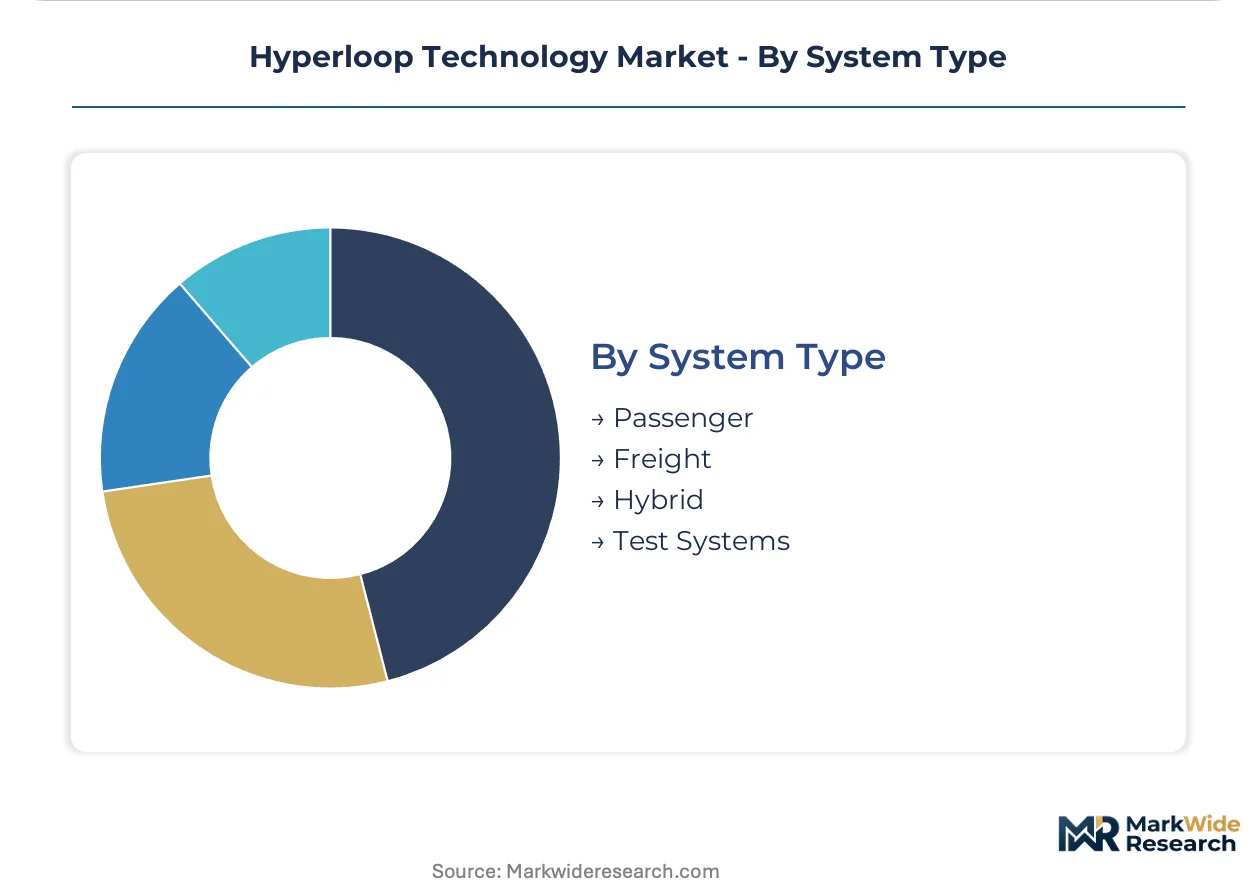
System Type:
Application purpose shapes pod design, with freight configurations gaining traction as logistics operators evaluate captive tube networks against diesel trucking volatility.
- Freight:Port-to-inland cargo networks between Jebel Ali and UAE distribution centers are advancing through sandbox permitting ahead of passenger certification, collapsing the capital cost gap with conventional electrified rail.
- Passenger:Texas and Midwest corridors absorb the heaviest compliance cost burden as developers align pod safety systems with Federal Railroad Administration crashworthiness standards.
- Hybrid:Dual-use systems capable of passenger and freight conversion present certification sequencing challenges but extend network utilization rates.
- Test Systems:Demonstration tracks in Spain and Italy serve as pod-handoff integration points between conventional high-speed rail and full tube networks.
Freight leads near-term deployment. Hybrid systems are gaining share fastest as operators seek utilization flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized vacuum engineering talent concentrates in aerospace clusters across Saudi Arabia, the United Arab Emirates, the United States, the Netherlands, and Spain, anchoring corridor development in these geographies.
Saudi Arabia
NEOM's Qiddiya-Red Sea route absorbs sovereign capital allocation, validating commercial feasibility studies. The national transport regulator advances permitting sandboxes ahead of codified standards. The northwestern corridor cluster attracts European engineering consortium participation for vacuum vessel fabrication.
United Arab Emirates
Dubai's logistics corridor studies concentrate infrastructure developer capital around Jebel Ali port-to-inland networks. The Road and Transport Authority dictates technical specifications in pre-development agreements, consolidating procurement authority over freight tube pilots.
United States
Texas and Midwest passenger corridors absorb Federal Railroad Administration compliance cost burdens. The US Department of Transportation's emerging guidance framework gates market access through safety protocol development, unlocking institutional investor due diligence.
Netherlands
EU TEN-T cross-border funding criteria channel development capital toward Netherlands-Germany corridor feasibility studies. The Dutch-German border region serves as a testbed for maglev-hyperloop hybrid interfaces at conventional high-speed rail termini.
Spain
Demonstration tracks in Spanish industrial clusters function as pod-handoff integration points between conventional rail and full tube networks. The country's national transport infrastructure program evaluates passive magnetic levitation configurations for 300-mile freight routes.
Hyperloop Technology Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across the vacuum-tube transit value chain. Market structure tilts toward consolidation as sovereign infrastructure funds concentrate procurement authority over corridor rights-of-way. Three archetypes dominate: tunneling heritage contractors, proprietary propulsion designers, and maglev interface specialists. Competitive moves center on strategic partnerships for certification sequencing and geographic expansion into sandbox-permitting jurisdictions.
Among tunneling-focused contractors, The Boring Company anchors the underground rights-of-way segment. TransPod Inc. and Hardt Global Mobility occupy positions within the propulsion and magnetic levitation specialist tier, representing Canadian-European and low-speed interface archetypes respectively. Virgin Hyperloop exemplifies the integrated system developer model. These companies sit within a competitive map where late-stage certification capabilities displace early-stage tube development in capital allocation priority.
| Leading Market Players |
|---|
| The Boring Company (SpaceX) |
| TransPod Inc. |
| Hyperloop Transportation Technologies |
| Nevomo |
| Zeleros Hyperloop |
| Virgin Hyperloop |
| Hardt Global Mobility |
| AECOM |
| Dinclix GroundWorks |
| Others |
Supply Flow & Price Mechanics
Certification-grade bifurcation between Federal Railroad Administration-aligned safety systems and sandbox-permitted freight pilots manifests in divergent pricing structures and supplier qualification timelines. Premium passenger corridor developers absorb front-loaded compliance costs while UAE logistics operators exploit regulatory flexibility to compress capital deployment schedules.
Pricing Analysis
Capacity additions in Saudi Arabia are reshaping price floors for vacuum vessel fabrication as NEOM corridor commitments absorb foundry output from East Asian suppliers. Project-based contract structures dominate, with price differentiation resting on ISO 45001 safety certification tier and sovereign fund backing scale. Cost compression in passenger-grade tube segments is intensifying because Federal Railroad Administration crashworthiness mandates redirect engineering resources toward redundant braking systems. Transportation authorities with pre-development specification authority exhibit lowest price sensitivity, while fragmented venture capital investors face the steepest margin pressure.
Supply Chain Analysis
Dual-sourcing requirements from sovereign infrastructure funds mandate multi-supplier qualification for specialized alloy steel and composite pressure vessel fabrication. Geographic supply concentration centers on China, Japan, and South Korea for high-grade steel inputs, with European engineering consortiums anchoring propulsion system intellectual property development. Raw material dependencies include nickel-based superalloys, carbon fiber composites, and rare-earth permanent magnets. Single-source vulnerability persists in linear induction motor winding fabrication, where aerospace contractor talent pools create recruitment bottlenecks. Distribution runs through sovereign fund-led procurement consortia that consolidate corridor rights-of-way authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Hyperloop Technology Market functions as a stable compounder anchored by sovereign infrastructure fund commitments that front-load capital across multi-decade deployment horizons.
For Market Incumbents: Hedge certification sequencing risk by diversifying across sandbox-permitting jurisdictions like the UAE and Saudi Arabia while maintaining Federal Railroad Administration engagement for long-term US corridor access. Prioritize backward integration into vacuum engineering talent pools through aerospace contractor recruitment partnerships. Defensive positioning requires locking proprietary interface standards before interoperability mandates crystallize. For New Entrants and Emerging Players: Passive magnetic levitation convergence with active linear motor systems offers a technology-first wedge into freight-oriented deployments where certification timelines compress relative to passenger corridors. White-space targets concentrate on UAE port-to-inland logistics networks and Netherlands-Germany cross-border feasibility studies. A certification-specialist go-to-market angle bypasses early-stage tube development capital intensity. For Investors and Strategic Acquirers: Consolidation pressure builds where late-stage safety validation capabilities displace venture-backed early-stage developers in capital allocation priority. Long-term viability favors integrated system developers with tunneling heritage or proprietary propulsion portfolios over pure-play component suppliers. The signal to watch is which regulatory jurisdiction first achieves enforceable certification protocols, as that geography captures initial institutional infrastructure investment waves.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Sequencing Partnership | Aligns pod-to-tube safety validation with Federal Railroad Administration timelines. |
| Sovereign Fund Pre-Development Agreement | Locks technical specification authority with Saudi or UAE transport regulators. |
| Maglev-Hyperloop Interface Development | Extends network reach through conventional high-speed rail termini integration. |
| Freight Corridor Sandboxing | Exploits Dubai Road and Transport Authority permitting ahead of passenger rules. |
| Aerospace Talent Acquisition | Addresses vacuum engineering scarcity through contractor recruitment pipelines. |
Methodological Framework
Bottom-up corridor deployment modeling reconciled against top-down sovereign fund capital flow tracking forms the analytical core of this study. Primary interviews with transportation authority procurement directors, vacuum vessel fabrication plant managers, Federal Railroad Administration certification specialists, and sovereign infrastructure fund investment officers combined with secondary validation from US Department of Transportation guidance filings, EU TEN-T infrastructure prioritization documents, Saudi national transport regulator permitting records, and customs data on specialized alloy steel trade flows. Triangulation across these sources ensures supply-side and demand-side estimates converge.
Input-output matrices map vacuum tube capital intensity, propulsion system intellectual property licensing values, and maglev interface deployment scales across technology, end user, deployment span, and system type dimensions. CAGRs derive from regression analysis of historical infrastructure project timelines and regulatory approval velocity patterns. Industry-specific forecast inputs include Federal Railroad Administration safety protocol development pace and EU TEN-T cross-border funding allocation cycles.
The model holds under stable sovereign capital commitment conditions; deviation in US federal rail law codification timelines or East Asian foundry supply disruptions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Next Generation Technologies
M2M Connections Market
Next Generation Technologies
Europe Quantum Computing Market
Next Generation Technologies
Fog Computing Market
Next Generation Technologies
Nigeria ICT Market
Next Generation Technologies
Next-Generation Communication Devices Market
Next Generation Technologies
Jordan ICT Market
Next Generation Technologies
Next Generation Network (NGN) Equipment Market
Next Generation Technologies
Information and Communications Technology (ICT) Market
Next Generation Technologies
Japan ICT Market
Next Generation Technologies
Enterprise Quantum Computing Market
Next Generation Technologies
Bulgaria ICT Market
Next Generation Technologies
Oman ICT Market
Next Generation Technologies
Global Next Generation Wireless Communication Market
Next Generation Technologies
Quantum Information Processing Market
Next Generation Technologies
Next Generation Wireless Network Market
Next Generation Technologies
5G New Radio Market