
 Malaysia ICT Market | 2026-2036
Malaysia ICT Market Size, Share, and Industry Trends Forecast 2026-2036
Malaysia ICT Market Foresight
Enterprise software licensing is fragmenting across subscription, usage-based, and perpetual models as Malaysian buyers demand pricing flexibility. Telekom Malaysia Berhad anchors the infrastructure layer through its fiber and data center assets. CelcomDigi Berhad competes aggressively in mobile enterprise solutions. Maxis Berhad specializes in managed services for financial institutions.
Information and communications technology in Malaysia encompasses computing hardware, software applications, telecommunications infrastructure, and digital services delivered through fiber-optic backbones, 5G radio access networks, and cloud-native architectures operating at sub-20ms latency for enterprise workloads. The primary purpose spans automating business processes, enabling real-time data exchange, and supporting national digital transformation objectives. Hardware and network segments retain dominant revenue share due to ongoing 5G rollout obligations under the government's JENDELA plan, while cloud deployment models capture accelerating enterprise migration from legacy on-premises systems. Services revenue pools deepen around cybersecurity and data analytics as Malaysian enterprises face escalating threat environments.
Malaysia's Communications and Multimedia Commission (MCMC) enforces licensing frameworks that shape market entry for telecommunications providers and cloud operators. The country's Personal Data Protection Act (PDPA) and BIS-equivalent cybersecurity certifications constrain how vendors architect data residency and cross-border transfer protocols. The Securities Commission Malaysia and Bank Negara Malaysia impose technology risk management guidelines that dictate ICT procurement standards for financial services buyers. Stakeholders must monitor how impending amendments to the PDPA and emerging AI governance frameworks from the Ministry of Science, Technology and Innovation reshape compliance costs and competitive positioning.
Market Dynamics
Malaysia's ICT sector is undergoing structural compression as the MyDIGITAL framework mandates cloud-first procurement across federal agencies, forcing legacy infrastructure vendors to re-architect delivery models around data sovereignty requirements.
Growth Catalysts
- JENDELA infrastructure obligations:Government-mandated 5G spectrum allocation and fiber densification targets are pulling capital into radio access network equipment and edge data center buildouts across Peninsular Malaysia.
- SME cloud migration:Malaysia Digital Economy Corporation incentives are accelerating small and medium enterprise adoption of software-as-a-service financial and inventory management platforms.
- Iskandar Puteri cluster:Johor's special economic zone is concentrating data center investments from hyperscale operators seeking Singapore spillover capacity with lower land and power costs.
Market Restraints
- Semiconductor input volatility:Server and networking hardware manufacturers face margin pressure from memory chip and GPU supply fluctuations originating from Taiwan and South Korea fabrication facilities.
- Single wholesale network dependency:DNB's monopoly over 5G infrastructure creates concentration risk for mobile network operators negotiating access terms and coverage timelines.
- Cross-border data friction:PDPA restrictions on personal data transfer outside Malaysia complicate multi-region cloud architectures for multinational enterprise clients.
Strategic Opportunities
- East Malaysia penetration gap:Sarawak and Sabah present underdeveloped fixed broadband and enterprise software markets relative to Peninsular infrastructure density.
- AI governance preparation:Anticipated Ministry of Science, Technology and Innovation frameworks will create compliance service demand for algorithmic auditing and bias testing tools.
- Cybersecurity managed services:Bank Negara Malaysia technology risk management guidelines are pushing financial institutions toward outsourced security operations centers rather than in-house builds.
Industry Challenges
- Cloud architecture talent scarcity:Kubernetes and multi-cloud orchestration skills command premium wages as local universities lag curriculum updates behind hyperscale certification requirements.
- Legacy system integration complexity:Government agencies and banks maintain decades-old mainframe dependencies that conflict with API-first modernization timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Malaysia ICT Market |
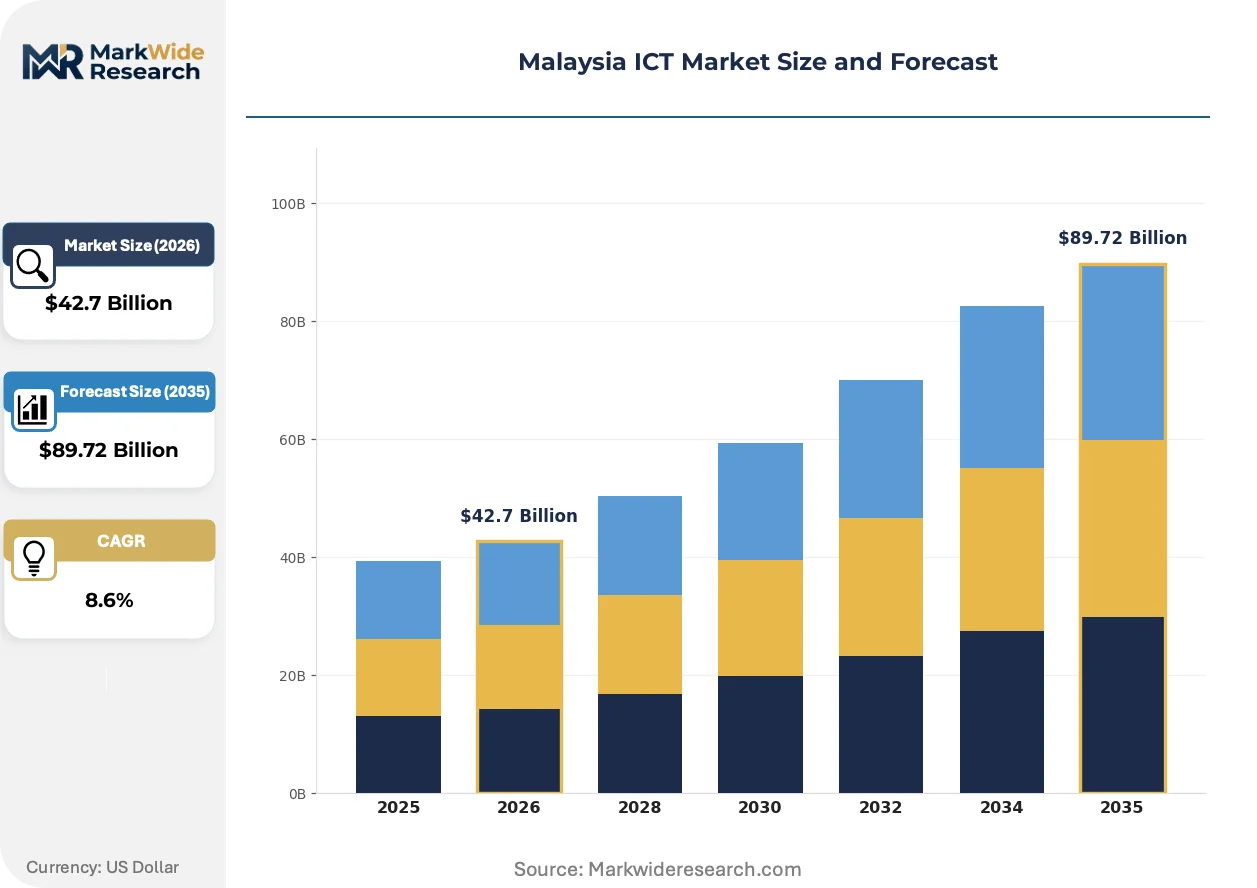
| Market Size in 2026 | $42.7 Billion |
| Market Size in 2035 | $89.72 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Hardware, Services, Network Deployment Model: On-Premises, Cloud, Hybrid, Edge End User: Government, Enterprises, SMEs, Education Technology: AI, IoT, Big Data, Blockchain |
| Companies Covered | Telekom Malaysia Berhad, CelcomDigi Berhad, Maxis Berhad, Tata Consultancy Services, IBM Corporation, Wipro Technologies, Cisco Systems (Malaysia) Sdn Bhd, Dell Technologies Inc., Accenture plc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Malaysia ICT Market Shifts & Advancements
Software-defined infrastructure and sovereign cloud architectures are redrawing competitive boundaries in Malaysian enterprise technology procurement, compressing traditional hardware resale margins while elevating compliance-centric service contracts.
Hyperscale edge computing nodes are collapsing the distinction between centralized cloud and on-premises infrastructure for latency-sensitive manufacturing and financial trading workloads. Malaysian automotive and electronics manufacturers in the Klang Valley are deploying these nodes at sub-10 millisecond proximity to factory floors. This topology is collapsing traditional managed service provider revenue pools as vendors must now engineer distributed Kubernetes environments rather than monolithic data center contracts.
Amendments to Malaysia's Personal Data Protection Act are tightening consent management and breach notification requirements for data processors handling consumer financial and health records. The MCMC is aligning enforcement protocols with ASEAN cross-border data flow frameworks. Financial services and healthcare providers are responding by localizing primary data storage and engaging third-party auditors for PDPA compliance certification.
Enterprise buyers are unbundling hardware procurement from implementation services, demanding separate pricing for equipment, integration, and ongoing support. Systems integrators accustomed to bundled margin structures are seeing pressure from direct vendor sales teams and independent implementation specialists. This pattern is most pronounced among Petronas-linked energy sector buyers and government-linked investment corporations in Kuala Lumpur.
Malaysia ICT Market Segmentation
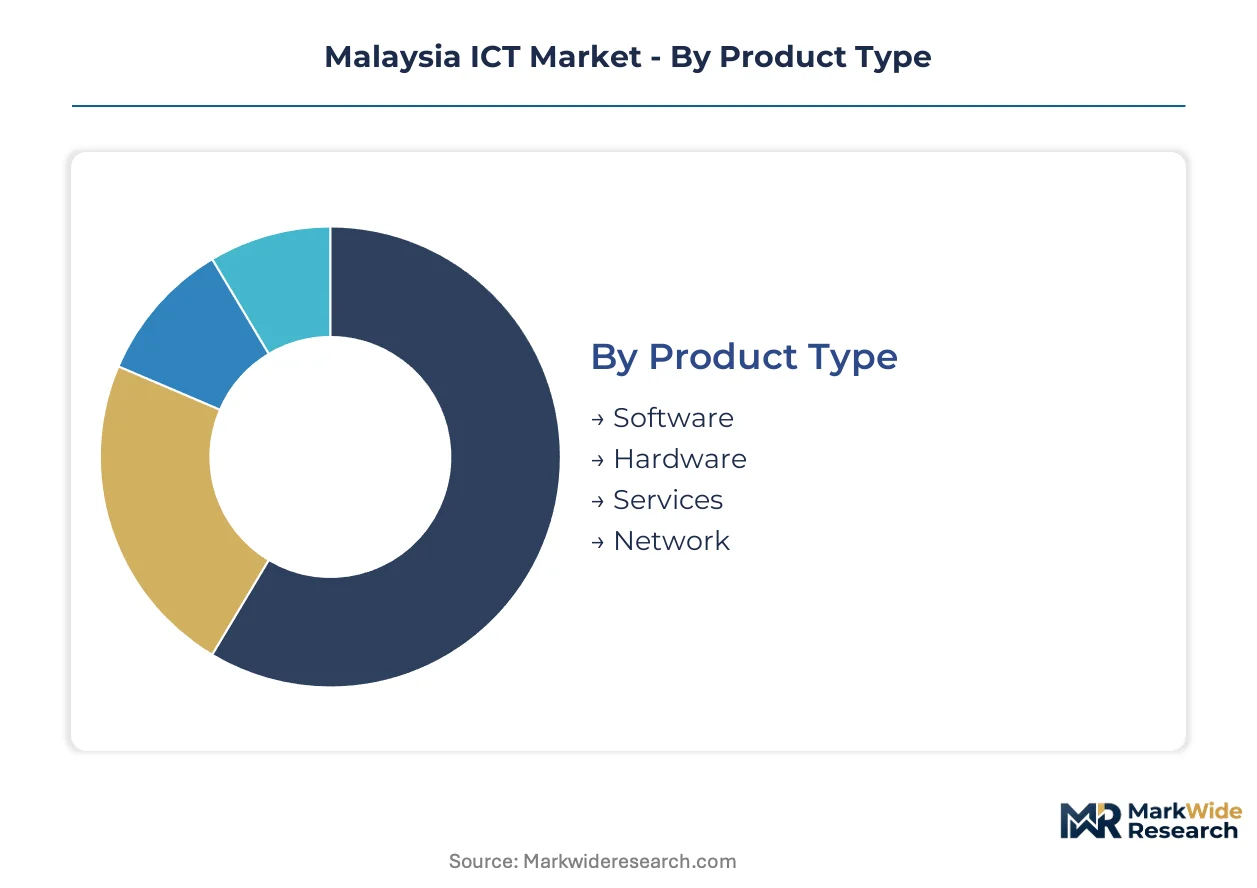
Malaysia's ICT market segments along four critical dimensions that determine procurement patterns, margin structures, and vendor positioning. Each axis reflects distinct buyer priorities shaped by MyDIGITAL mandates, JENDERA infrastructure timelines, and sector-specific compliance regimes.
Product Type:
Use-case spectrum spans legacy infrastructure replacement to cloud-native application deployment across federal agencies and private enterprises.
- Software:Enterprise resource planning and customer relationship management platforms dominate procurement volumes. Banking and Petronas-linked energy buyers in Kuala Lumpur drive demand for subscription-based licensing with embedded PDPA compliance modules.
- Hardware:Servers, storage arrays, and networking equipment constitute the foundational layer. 5G radio access network buildouts under JENDELA obligations concentrate demand for baseband units and massive MIMO antennas across Peninsular Malaysia.
- Services:Systems integration and managed security operations support digital transformation initiatives. Financial institutions outsource cybersecurity operations to comply with Bank Negara Malaysia technology risk management guidelines.
- Network:Fiber-optic backhaul and fixed wireless access infrastructure expand connectivity reach. Telekom Malaysia Berhad's fiber densification targets in Selangor and Johor anchor capital deployment schedules.
Established volume favors Hardware; emerging adoption favors Software.
Deployment Model:
Cost tier differentiation separates capital-intensive legacy estates from operational-expenditure cloud migrations favored by budget-constrained agencies.
- On-Premises:Legacy mainframe and private data center installations persist in Bank Negara Malaysia-regulated financial institutions. Regulatory data residency requirements sustain demand despite higher total cost of ownership.
- Cloud:Software-as-a-service and infrastructure-as-a-service models accelerate under MyDIGITAL cloud-first procurement mandates. Malaysia Digital Economy Corporation incentives pull SMEs toward financial and inventory management platforms.
- Hybrid:Workload-specific architectures split sensitive data processing on-premises from scalable compute in sovereign cloud facilities. Government agencies adopt this model to balance JENDELA connectivity targets with PDPA compliance.
- Edge:Distributed computing nodes deploy at sub-10 millisecond proximity to factory floors. Klang Valley automotive and electronics manufacturers utilize these for real-time quality control and predictive maintenance.
Hybrid architectures gain share fastest among enterprise buyers; Edge deployment climbs the fastest in manufacturing verticals.
End User:
Customer type determines contract scale, sales cycle length, and compliance complexity across the Malaysian ICT procurement landscape.
- Government:Federal and state agencies operate under mandatory cloud-first policies with sovereign data requirements. MCMC licensing frameworks shape vendor eligibility for telecommunications and cloud service contracts.
- Enterprises:Large corporations in banking, energy, and telecommunications drive premium service demand. Technology risk management guidelines from Bank Negara Malaysia and Securities Commission Malaysia dictate procurement standards.
- SMEs:Small and medium enterprises adopt standardized SaaS platforms through Malaysia Digital Economy Corporation incentive programs. Cloud migration accelerates as legacy on-premises maintenance costs escalate.
- Education:Universities and vocational institutes require scalable learning management systems and research computing infrastructure. Connectivity gaps in East Malaysia institutions limit platform deployment reach.
Enterprise contracts deliver highest absolute value; SME segment expands most quickly on volume basis.
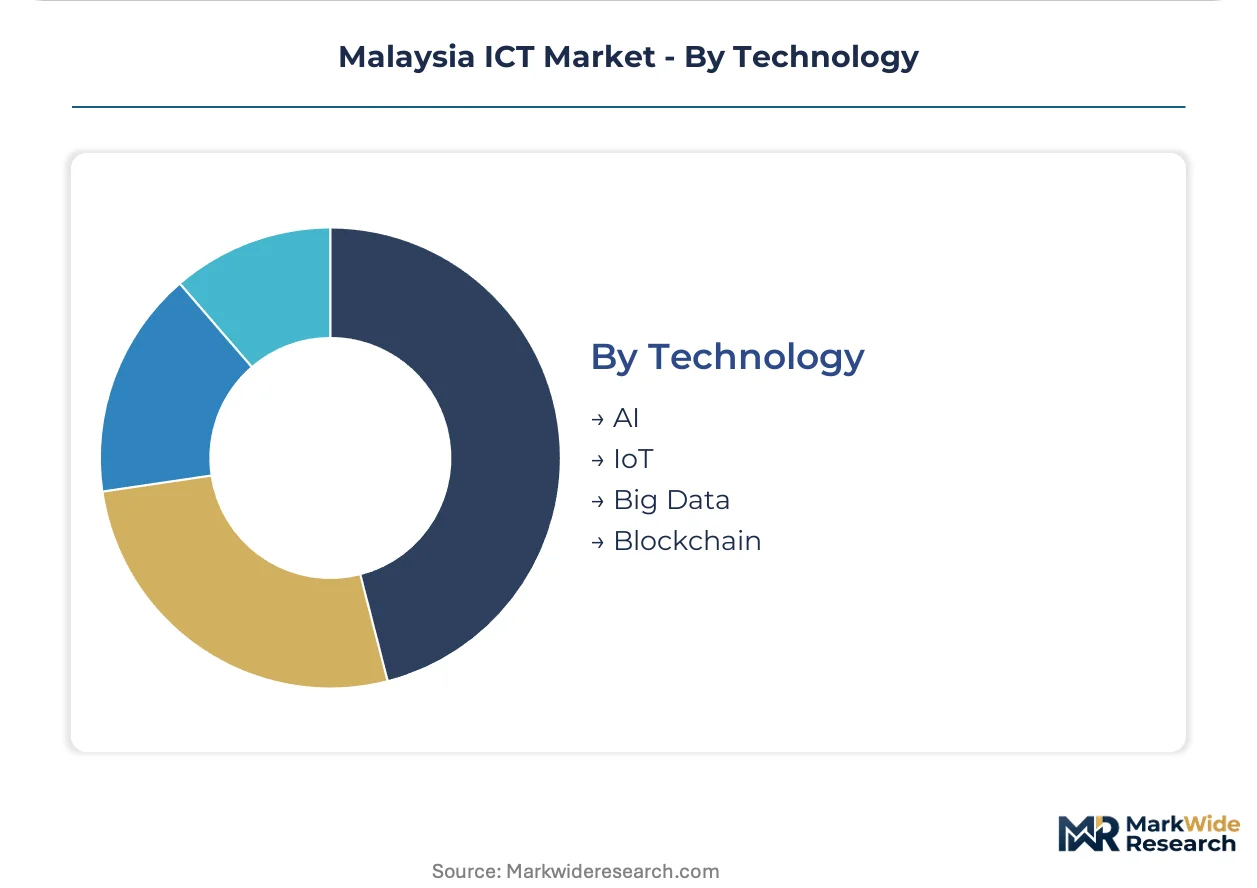
Technology:
Maturity gradient separates production-ready implementations from pilot-phase innovations awaiting regulatory clarity.
- AI:Machine learning platforms and generative AI tools enter enterprise workflows. Anticipated Ministry of Science, Technology and Innovation governance frameworks create demand for algorithmic auditing services.
- IoT:Sensor networks and industrial automation systems deploy across manufacturing and logistics operations. Palm oil plantations and smart city initiatives in Iskandar Puteri anchor adoption clusters.
- Big Data:Analytics platforms process operational and customer data for predictive insights. Financial institutions leverage these for fraud detection and credit risk modeling under regulatory scrutiny.
- Blockchain:Distributed ledger applications remain concentrated in trade finance and supply chain traceability pilots. Regulatory uncertainty from Securities Commission Malaysia limits mainstream deployment.
Big Data commands established enterprise budgets; AI investment shows steepest expansion trajectory pending governance finalization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Malaysian ICT buyers in East Malaysia exhibit the highest price elasticity, while Klang Valley enterprises absorb premium pricing for compliance-grade solutions. Federal procurement mandates compress margins for infrastructure vendors serving government agencies. SME segments in secondary cities drive volume growth through standardized SaaS adoption.
Selangor
Enterprise data center demand concentrates in Cyberjaya and Petaling Jaya, where hyperscale operators seek sovereign cloud capacity. The Malaysia Digital Economy Corporation channels incentives toward cloud-first SMEs in Shah Alam industrial zones. Telekom Malaysia Berhad's fiber densification targets anchor capital deployment across the Greater Klang Valley corridor.
Kuala Lumpur
Financial institutions headquartered in the city center drive managed security services procurement under Bank Negara Malaysia technology risk guidelines. The Securities Commission Malaysia imposes technology risk management standards on capital markets participants. Petronas-linked energy buyers in the KLCC district unbundle hardware from implementation services, pressuring systems integrator margins.
Johor
Iskandar Puteri's special economic zone concentrates data center investments from operators seeking Singapore spillover capacity with lower land and power costs. The Johor state government aligns zoning permits with federal JENDELA connectivity targets. Pasir Gudang industrial estates host edge computing nodes serving automotive and electronics manufacturers.
Sarawak
Underdeveloped fixed broadband infrastructure limits enterprise software deployment reach beyond Kuching and Miri urban centers. The Sarawak state government pursues digital economy initiatives through the Sarawak Multimedia Authority. Rural connectivity gaps sustain demand for satellite and fixed wireless access solutions in interior divisions.
Penang
Electronics manufacturing clusters in Bayan Lepas and Batu Kawan drive industrial IoT and predictive maintenance platform adoption. The Penang state government coordinates with federal MyDIGITAL frameworks for SME digitization grants. Georgetown's services sector generates demand for cybersecurity and data analytics outsourcing.
Malaysia ICT Market Competitive Landscape
Integrated telecommunications providers and global technology consultancies split the Malaysian ICT market along infrastructure-versus-services lines. Market concentration is moderate, with three domestic operators controlling network-layer revenue while international vendors capture enterprise software and services pools. Two strategic archetypes dominate: asset-heavy infrastructure incumbents with fiber and data center holdings, and capability-dense global integrators delivering cloud migration and cybersecurity. Competitive moves center on sovereign cloud partnerships and managed security service buildouts.
Within the infrastructure-incumbent tier, Telekom Malaysia Berhad and CelcomDigi Berhad exemplify contrasting strategic positions—one anchored in fixed-line fiber dominance, the other in mobile enterprise solutions. Maxis Berhad occupies a position specializing in financial services managed services. Among global integrators, Tata Consultancy Services and Accenture plc represent the scale-driven archetype, while Cisco Systems (Malaysia) Sdn Bhd and Dell Technologies Inc. anchor hardware-centric delivery models. IBM Corporation and Wipro Technologies sit within the hybrid services-hardware positioning, reflecting broader industry patterns of portfolio convergence around cloud-native architectures.
| Leading Market Players |
|---|
| Telekom Malaysia Berhad |
| CelcomDigi Berhad |
| Maxis Berhad |
| Tata Consultancy Services |
| IBM Corporation |
| Wipro Technologies |
| Cisco Systems (Malaysia) Sdn Bhd |
| Dell Technologies Inc. |
| Accenture plc |
| Others |
Supply & Pricing Matrix
Iskandar Puteri's data center cluster capacity expansion directly compresses cloud infrastructure pricing power across Peninsular Malaysia as hyperscale operators exploit Johor's land and power cost arbitrage against Singapore. This geographic supply shift forces legacy hardware vendors to unbundle service contracts from equipment sales or cede share to sovereign cloud alternatives.
Pricing Analysis
Managed security operations and multi-year support contracts drive lifetime value for systems integrators serving Bank Negara Malaysia-regulated financial institutions. Three-tier pricing structure across premium compliance-grade, standard enterprise, and economy SME levels stratifies the market, with certification against PDPA and BIS-equivalent cybersecurity standards commanding substantial premiums. Cost compression in hardware resale is intensifying because enterprise buyers increasingly source servers and networking equipment directly from manufacturers, bypassing traditional distributor markups. Government agencies exhibit lowest price sensitivity due to sovereign data requirements, while East Malaysia SMEs absorb highest elasticity as Malaysia Digital Economy Corporation incentives narrow their viable procurement window.
Supply Chain Analysis
Extended payment terms from 60 to 90 days now characterize supplier financing arrangements for telecommunications infrastructure vendors serving DNB's 5G single wholesale network. Taiwan and South Korea fabrication facilities anchor semiconductor supply for server and networking hardware, with memory chip and GPU inputs drawing from concentrated East Asian production nodes. Supply chain risk centers on single-source vulnerability for advanced networking silicon, where geopolitical friction could disrupt JENDELA rollout timelines. Distribution runs through Telekom Malaysia Berhad's fiber assets and authorized systems integrator networks, with direct vendor sales teams increasingly penetrating Petronas-linked energy and Kuala Lumpur financial institution accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Malaysia's ICT sector tracks a cyclical recovery pattern tied to JENDELA infrastructure obligation completion schedules, with capital deployment waves peaking as 5G coverage targets approach fulfillment.
For Market Incumbents: Harden sovereign cloud positioning through data center capacity additions in Cyberjaya and Iskandar Puteri before hyperscale operators consolidate edge node deployments. Deepen vertical integration into fiber backhaul assets to defend against DNB access term renegotiations that threaten mobile network operator margins. Prioritize PDPA compliance certification investments as amendments tighten consent management requirements. For New Entrants and Emerging Players: East Malaysia's underdeveloped fixed broadband infrastructure in Sarawak interior divisions represents the most penetrable entry point for satellite and fixed wireless access specialists. AI governance preparation services for algorithmic auditing and bias testing tools offer second white-space target as Ministry of Science, Technology and Innovation frameworks finalize. Go-to-market through Malaysia Digital Economy Corporation SME incentive channels accelerates customer acquisition without direct incumbent confrontation. For Investors and Strategic Acquirers: Carve-out targets emerge from global technology consultancies seeking to divest non-core Southeast Asian implementation practices. Long-term viability over a multi-year horizon favors vendors with sovereign cloud certifications and Bank Negara Malaysia technology risk management guideline compliance. Watch for DNB monopoly restructuring signals as the critical inflection indicator for mobile network operator valuation recovery.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Partnership | Aligns vendor eligibility with MCMC licensing frameworks for federal agency procurement. |
| Managed Security Service Buildout | Addresses Bank Negara Malaysia outsourcing mandates for financial institution cybersecurity operations. |
| Edge Computing Node Deployment | Captures sub-10 millisecond latency demand from Klang Valley automotive manufacturers. |
| PDPA Compliance Certification Investment | Positions data processors for tightened consent management and breach notification requirements. |
| East Malaysia Connectivity Expansion | Exploits Sarawak and Sabah infrastructure gaps through satellite and fixed wireless access. |
Research Methodology
Cross-validation between primary interviews with telecommunications infrastructure planners and secondary analysis of MCMC regulatory filings anchors the qualitative findings in this study. Chief technology officers at financial institutions, DNB network engineers, Malaysia Digital Economy Corporation program directors, and systems integrator delivery heads contributed primary perspectives. SEC filings from listed technology vendors, JENDELA progress reports, hyperscaler capex disclosures, and sovereign cloud certification databases supplied secondary validation. Bottom-up demand modeling from SME adoption rates and top-down supply assessment from data center pipeline capacity triangulate market sizing.
Calibration against historical cloud migration velocity and 5G infrastructure deployment cadence shapes the projection framework across the analysis window. Segmentation dimensions include deployment model, organization size tier, vertical industry, compliance complexity level, and regional infrastructure maturity. CAGRs derive from compounding annual adoption rate assumptions adjusted for regulatory milestone impacts. Forecast inputs incorporate MyDIGITAL procurement mandate enforcement intensity and PDPA amendment implementation timelines.
Macroeconomic conditions sit as an overlay; deviation in ringgit exchange rates, semiconductor input costs, or federal infrastructure budget allocations would shift the trajectory. Forecasts reflect documented assumptions about JENDELA obligation adherence and sovereign cloud demand elasticity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Next Generation Technologies
Japan ICT Market
Next Generation Technologies
Poc Platform and Technology Market
Next Generation Technologies
GCC ICT Market
Next Generation Technologies
Nearfield Communication (NFC) Market
Next Generation Technologies
Smart Surfaces Market
Next Generation Technologies
Information and Communications Technology (ICT) Market
Next Generation Technologies
M2M Connections Market
Next Generation Technologies
5G New Radio Market
Next Generation Technologies
Europe Quantum Computing Market
Next Generation Technologies
Next Generation Wireless Network Market
Next Generation Technologies
Oman ICT Market
Next Generation Technologies
Global Next Generation Wireless Communication Market
Next Generation Technologies
Ireland ICT Market
Next Generation Technologies
Next Generation Network (NGN) Equipment Market
Next Generation Technologies
Enterprise Quantum Computing Market
Next Generation Technologies
Hyperloop Technology Market