
 Nearfield Communication (NFC) Market | 2026-2036
Nearfield Communication (NFC) Market Size, Share, and Industry Trends Forecast 2026-2036
Nearfield Communication (NFC) Market Intelligence
Silicon-on-insulator substrates are broadening cost-performance tradeoffs for NFC controller chips. NXP Semiconductors leverages its foundry partnerships to sustain die-shrink advantages across payment and identity segments. STMicroelectronics anchors European automotive and industrial NFC supply through certified secure-element production. Qualcomm Technologies competes by integrating NFC controllers directly into Snapdragon mobile platforms, reducing bill-of-materials overhead for handset OEMs.
Nearfield Communication denotes short-range wireless technology operating at 13.56 MHz with typical coupling distances under 10 centimeters, enabling encrypted data exchange between proximate devices through inductive coupling. The technology serves primarily as an interface for secure transactions, device pairing, and credential verification in consumer and enterprise environments. Mobile Devices dominates unit volume as smartphone OEMs embed NFC as a standard feature across price tiers, while Contactless Payments captures the largest value pool due to interchange-fee economics and terminal refresh cycles. Wearables represents the fastest-growing product type as smartwatches and fitness bands add transit and payment credentials, though Point of Sale Terminals retains higher per-unit margins.
The EU Radio Equipment Directive and ETSI EN 300 330 standards govern electromagnetic compatibility and spectrum use for NFC devices sold in Europe, while the PCI Security Standards Council mandates contactless payment terminal certification worldwide. India's BIS and CDSCO impose additional testing for NFC-enabled medical devices and payment hardware entering that market. Stakeholders must monitor evolving interoperability requirements between proprietary wallet ecosystems and open-loop transit standards to preserve addressable market breadth.
Market Dynamics
Contactless payment mandates from transit authorities and retail consortiums are compressing terminal refresh cycles and forcing secure-element foundries to expand die capacity ahead of demand curves.
Growth Catalysts
- EU Radio Equipment Directive:Harmonized electromagnetic compatibility standards reduce country-by-country certification costs for NFC hardware manufacturers targeting European retail and automotive channels.
- Transit system digitization:Urban mobility authorities in China, Japan, and Brazil are replacing proprietary closed-loop cards with open-loop NFC credentialing that interoperates with mobile wallets.
- Silicon-on-insulator substrates:Advanced wafer materials enable smaller die footprints and lower power consumption for wearable NFC controllers, expanding addressable device categories.
Market Restraints
- Secure-element foundry concentration:Taiwan and South Korea dominate specialty semiconductor fabrication for payment-grade NFC chips, creating single-source vulnerability for module assemblers.
- Inductive coupling distance limitation:The physics of 13.56 MHz near-field interaction caps reliable read range below 10 centimeters, constraining use cases requiring longer-range credential exchange.
- PCI Security Standards Council certification:Contactless payment terminal approval cycles extend 12-18 months, delaying product launches and freezing engineering resources across compliance phases.
Strategic Opportunities
- India BIS and RBI payment hardware mandates:Domestic manufacturing incentives and data-localization requirements create protected demand pools for certified NFC terminal producers establishing local assembly.
- Automotive digital key convergence:Integration of NFC with Bluetooth Low Energy and ultra-wideband is electrifying vehicle access control architectures, opening high-margin supply contracts with tier-1 module suppliers.
- Healthcare credentialing expansion:NFC-enabled patient identification and medication authentication systems are penetrating hospital networks in Germany, the United Kingdom, and Australia.
Industry Challenges
- Secure-element firmware talent scarcity:Specialized embedded security engineering expertise concentrates at a handful of semiconductor design houses, inflating compensation and extending hiring timelines.
- Legacy POS terminal replacement inertia:Small-format retailers in Southern Europe and Southeast Asia defer hardware upgrades despite end-of-support deadlines, fragmenting addressable terminal volumes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nearfield Communication (NFC) Market |
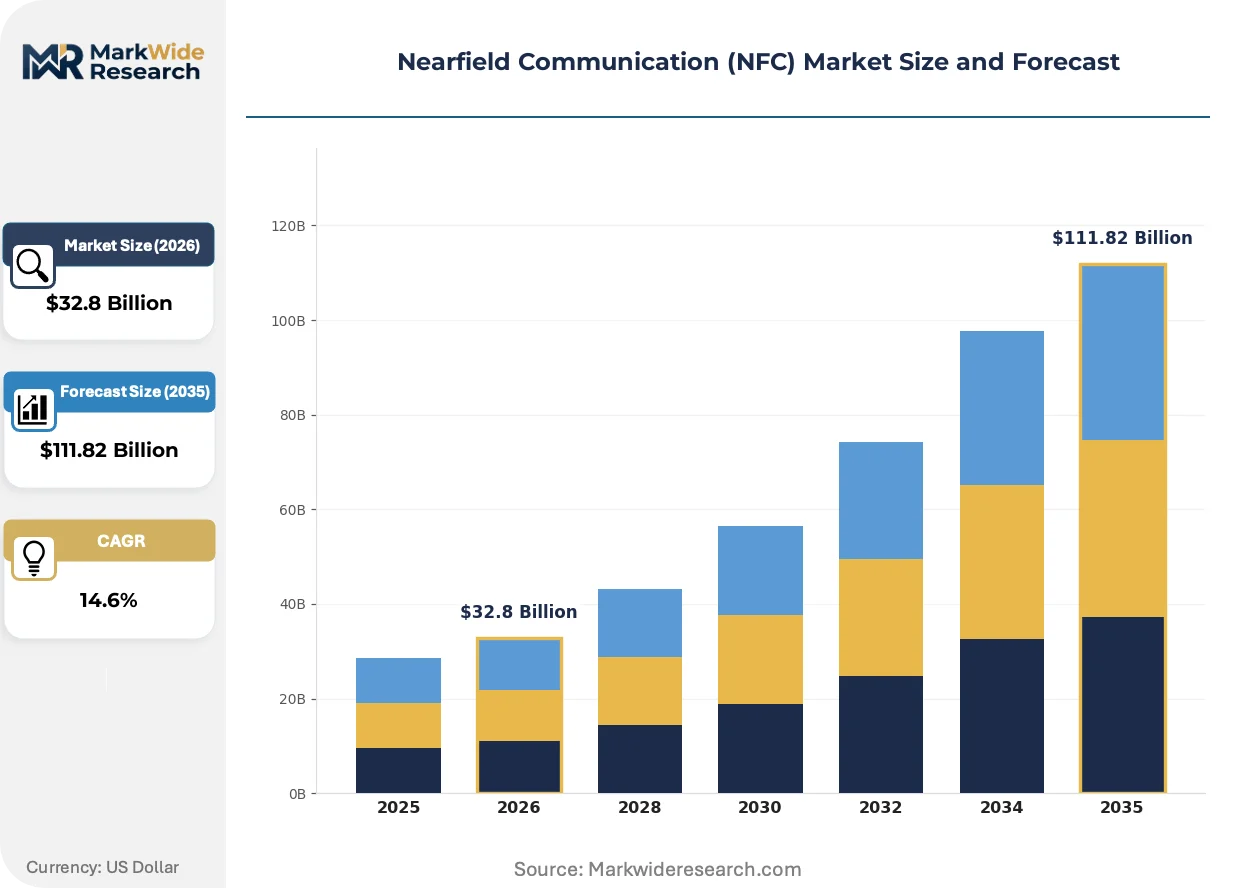
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $111.82 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Cards, Mobile Devices, Wearables, Point of Sale Terminals Technology: Peer-to-Peer, Card Emulation, Reader/Writer, NFC Forum Application: Contactless Payments, Access Control, Data Transfer, Ticketing End User: Retail, Transportation, Healthcare, Logistics |
| Companies Covered | NXP Semiconductors, Broadcom, Qualcomm Technologies, STMicroelectronics, Infineon Technologies, Texas Instruments, Renesas Electronics Corporation, ams-OSRAM, Thales, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nearfield Communication (NFC) Market Strategic Shifts & Innovations
Hardware-software convergence in secure transaction architectures is compressing time-to-market for credential-issuing platforms while fragmenting competitive moats across the value chain.
Passive NFC sensing tags with integrated environmental monitors are electrifying cold-chain logistics and pharmaceutical authenticity verification. Pharmaceutical distributors in North America and Western Europe are piloting temperature-logging NFC labels at pallet and unit levels. This capability is compressing insurance premiums and liability exposure for high-value biologics shippers.
China's MIIT GB standards for NFC-enabled IoT devices are mandating domestic cryptographic algorithms for products sold into government and financial services procurement channels. Module vendors must maintain parallel firmware streams to serve Chinese and non-Chinese markets from shared hardware platforms. Industrial automation and access control OEMs with China exposure are absorbing the largest compliance engineering burden.
Enterprise buyers are unbundling terminal hardware from payment processing contracts, forcing OEMs to compete on device specifications and service terms rather than bundled acquiring relationships. Large retail chains in France, Italy, and Spain are running parallel procurement processes for hardware and merchant services. This pattern is most pronounced among grocery and convenience store operators with multi-thousand-unit estate refresh requirements.
Nearfield Communication (NFC) Market Segmentation
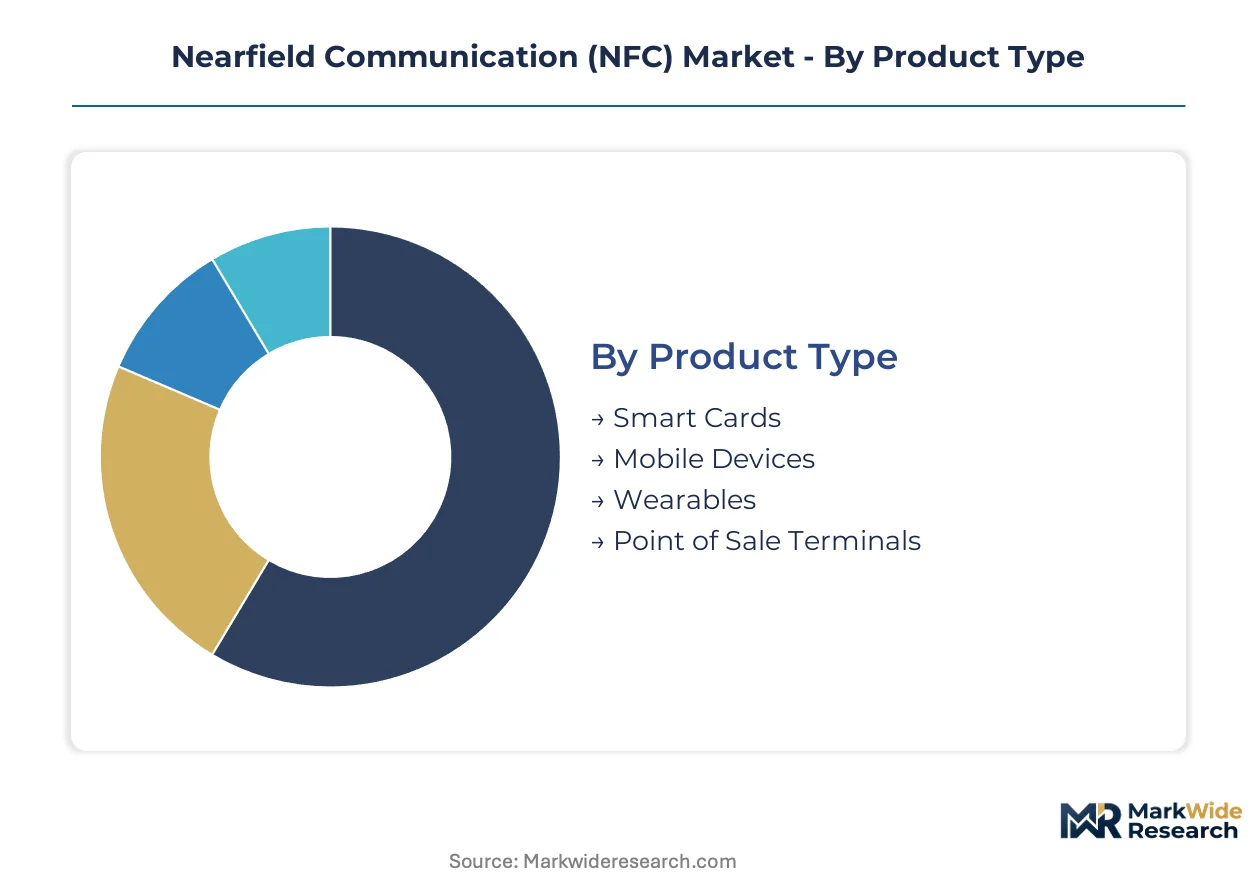
NFC market segmentation reveals divergent certification burdens across product categories. Payment-grade hardware demands PCI Security Standards Council approval cycles extending 12-18 months, while transit and access credentials operate under lighter interoperability testing regimes.
Product Type:
Payment-grade segments face the heaviest regulatory burden through PCI Security Standards Council terminal certification and EU Radio Equipment Directive electromagnetic compliance, while consumer electronics navigate lighter CE marking and FCC equipment authorization pathways.
- Smart Cards:Polyvinyl chloride and polycarbonate substrates embed copper coil antennas and secure-element microcontrollers for credential storage. Banking consortiums in France and Japan are accelerating contactless card issuance to displace magnetic-stripe infrastructure. PCI Security Standards Council mandates govern physical and logical security testing for payment credentials.
- Mobile Devices:Handset OEMs integrate NFC controllers into baseband processor modules or discrete secure elements alongside Bluetooth and Wi-Fi radios. China MIIT GB standards require domestic cryptographic algorithms for devices sold into government procurement channels, forcing parallel firmware streams.
- Wearables:Smartwatch and fitness band manufacturers embed reduced-size NFC antennas within compact form factors. Expanding most quickly as transit authorities in Brazil and Japan credential wrist-worn devices for open-loop fare collection.
- Point of Sale Terminals:Retail countertop and mobile readers combine NFC controllers with EMV chip acceptance and PIN entry security. Terminal OEMs serving India must navigate BIS certification and RBI payment hardware localization mandates.
Leading the category by volume: Mobile Devices. Growing fastest: Wearables.
Technology:
Operating-mode segmentation determines interoperability testing scope and ecosystem lock-in risk for module vendors.
- Peer-to-Peer:Device-to-device pairing protocols enable contactless business card exchange and file transfer between proximate handsets. Android Beam and similar implementations concentrate demand in enterprise collaboration tools.
- Card Emulation:Host-card emulation and secure-element-based credential presentation power mobile wallet transactions. Transit digitization in China and open-loop fare system adoption in São Paulo and Tokyo are accelerating deployment.
- Reader/Writer:Active NFC polling enables tag reading for asset tracking and smart poster interaction. Industrial automation OEMs in Germany integrate reader modules into manufacturing execution systems.
- NFC Forum:Standardized tag type specifications ensure cross-manufacturer interoperability for NDEF message exchange. Device certification through NFC Forum compliance programs reduces integration friction for accessory makers.
Highest certification overhead: Card Emulation. Steepest expansion trajectory: Reader/Writer in industrial applications.
Application:
Use-case segmentation maps directly to payment network economics and fare collection authority procurement cycles.
- Contactless Payments:EMV contactless and mobile wallet transactions generate interchange-fee revenue pools that fund terminal refresh subsidies. Retail consortiums in Italy and Spain are unbundling hardware procurement from merchant acquiring contracts.
- Access Control:Corporate campus and residential building credentialing replaces proximity card infrastructure with NFC-compatible mobile credentials. Commercial real estate operators in the United Kingdom are piloting smartphone-based entry systems.
- Data Transfer:Low-bandwidth device pairing and configuration exchange serves industrial field service and consumer electronics setup workflows.
- Ticketing:Event venue and public transit fare media digitization concentrates demand in urban mobility authorities replacing closed-loop card systems. São Paulo's Metrô and Tokyo Metro are expanding open-loop acceptance.
Largest value capture: Contactless Payments. Gaining share fastest: Ticketing through transit authority digitization mandates.
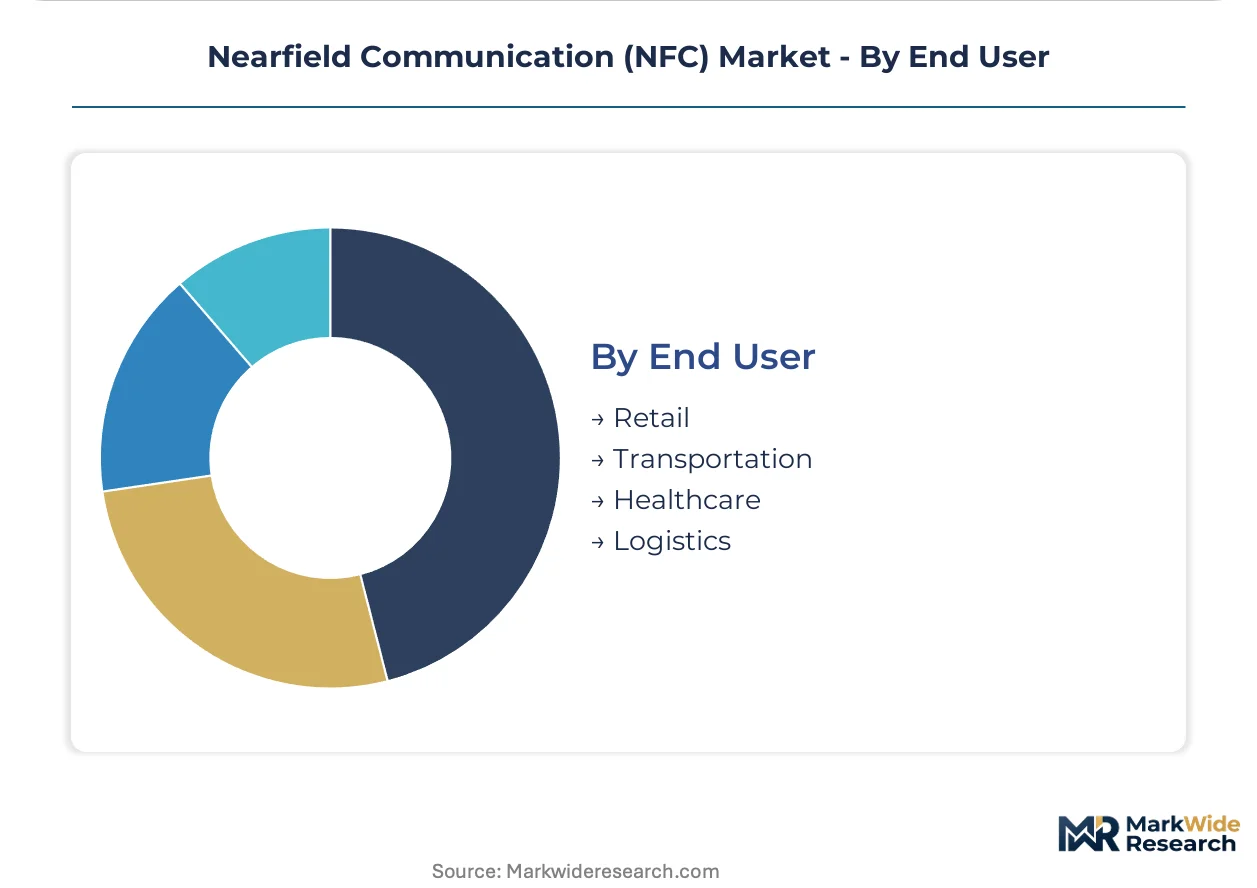
End User:
Vertical segmentation determines security tier requirements and procurement decision-maker profiles.
- Retail:Grocery and convenience store chains with multi-thousand-unit estates drive terminal volume through coordinated refresh programs. French supermarket operators are running parallel hardware and merchant services procurement processes.
- Transportation:Urban mobility authorities and event venues manage credential issuance and fare collection infrastructure. China's metro systems lead mobile wallet penetration and transit digitization velocity.
- Healthcare:Hospital networks in Germany and Australia deploy NFC-enabled patient identification and medication authentication to reduce administration errors.
- Logistics:Cold-chain pharmaceutical distributors in North America pilot temperature-logging NFC labels for biologics shipment monitoring.
Dominant procurement volume: Retail. Climbing the fastest: Healthcare credentialing expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates mobile wallet penetration and transit system digitization, while regulatory divergence across major economies fragments certification pathways for NFC hardware vendors.
China
Urban mobility authorities in Beijing, Shanghai, and Shenzhen drive open-loop transit credentialing at scale. MIIT GB standards mandate domestic cryptographic algorithms for government and financial procurement channels. The Yangtze River Delta hosts module vendors maintaining parallel firmware streams to serve domestic and export markets from shared hardware platforms.
United States
Retail consortiums accelerate terminal refresh cycles through unbundled hardware procurement from merchant acquiring contracts. FCC equipment authorization governs electromagnetic compliance for consumer electronics and payment terminals. Cold-chain pharmaceutical distributors in the Northeast and California pilot temperature-logging NFC labels for biologics shipment monitoring.
Germany
Industrial automation OEMs integrate NFC reader modules into manufacturing execution systems for asset tracking. CE marking and ETSI EN 300 330 standards govern electromagnetic compatibility for devices sold across the European Union. Hospital networks in Bavaria and North Rhine-Westphalia deploy patient identification and medication authentication systems.
India
Domestic manufacturing incentives and data-localization requirements create protected demand pools for certified terminal producers. BIS certification and RBI payment hardware mandates govern NFC-enabled devices entering the market. Terminal assemblers in Maharashtra and Karnataka establish local production to satisfy public sector procurement preferences.
Japan
Transit digitization velocity exceeds most markets as Tokyo Metro and regional operators expand open-loop acceptance. METI oversees industrial standards coordination for IoT device interoperability. Osaka and Nagoya clusters concentrate wearable OEMs credentialing wrist-worn devices for fare collection systems.
Nearfield Communication (NFC) Market Key Industry Players
Capacity expansion dominates the current landscape as secure-element foundries in Taiwan and South Korea add die capacity ahead of demand curves. The vendor base concentrates around semiconductor design houses with embedded security expertise and integrated platform providers serving handset OEMs. Three archetypes anchor competitive positioning: specialty secure-element fabricators, diversified analog-mixed signal suppliers, and mobile platform integrators. Strategic partnerships between foundries and fabless designers, plus geographic expansion into protected procurement markets, represent the dominant competitive vectors.
Among European diversified suppliers, NXP Semiconductors and STMicroelectronics occupy positions spanning payment, identity, and automotive segments. Qualcomm Technologies exemplifies the platform-integration archetype through Snapdragon mobile platforms. These three anchors represent divergent approaches to controller architecture — discrete secure elements versus baseband-integrated solutions versus certified automotive-grade production.
| Leading Market Players |
|---|
| NXP Semiconductors |
| Broadcom |
| Qualcomm Technologies |
| STMicroelectronics |
| Infineon Technologies |
| Texas Instruments |
| Renesas Electronics Corporation |
| ams-OSRAM |
| Thales |
| Others |
Cost & Logistics Intelligence
Secure-element firmware engineering talent scarcity in Taiwan and South Korea widens labor-cost differentials between premium certified modules and economy-tier reader components, compressing mid-market pricing spreads as foundries compete for specialized embedded security expertise.
Pricing Analysis
Volume concentrates in mobile device NFC controllers with thin margins, while payment-grade secure elements and automotive digital key modules capture premium pricing. Three-tier pricing structure across PCI-certified terminals, CE-marked industrial readers, and unlicensed consumer accessories reflects certification-grade differentiation. Pricing pressure stems from unbundled hardware procurement in European retail, forcing terminal OEMs to compete on device specifications alone. Grocery and convenience chains exhibit highest price sensitivity, while automotive tier-1 suppliers prioritize security certification over unit cost.
Supply Chain Analysis
Reverse-logistics flows for payment terminal refurbishment and secure-element module returns concentrate in Taiwan and South Korea, where foundries reclaim die capacity from end-of-life devices. Specialty semiconductor fabrication draws from silicon-on-insulator wafer supplies, copper coil antenna substrates, and cryptographic IP cores. Single-source vulnerability pervades payment-grade secure-element production, with Taiwan Semiconductor and Samsung Foundry anchoring global capacity. Distribution runs through module assemblers in China's Yangtze River Delta, European automotive tier-1 suppliers, and Indian BIS-certified terminal producers serving domestic procurement mandates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where PCI Security Standards Council certification cycles extending 12-18 months erect barrier-to-entry moats protecting incumbent secure-element fabricators from commoditization.
For Market Incumbents: Cement die-shrink advantages through foundry partnership exclusivity in Taiwan and South Korea to outpace fabless competitors on power consumption metrics. Expand certified production capacity ahead of India's BIS localization mandates and Brazil's transit digitization curves. Defend against host-card emulation commoditization by deepening automotive digital key integration with Bluetooth Low Energy and ultra-wideband convergence.
For New Entrants and Emerging Players: Begin with healthcare credentialing expansion in Germany and Australia, where hospital network procurement lacks incumbent payment-terminal concentration. Target patient identification and medication authentication systems as the most penetrable vertical, leveraging lighter interoperability testing regimes compared to PCI-mandated hardware. Pursue direct partnerships with hospital IT integrators rather than competing through distribution channels dominated by established secure-element vendors.
For Investors and Strategic Acquirers: Re-rating potential sits with diversified analog-mixed signal suppliers possessing automotive-grade certified production given electrification of vehicle access control architectures. Long-term viability favors players spanning payment, identity, and industrial segments with resilient revenue mix across terminal refresh cycles. Monitor transit authority open-loop credentialing mandates in São Paulo, Tokyo, and Chinese metro systems as volume inflection indicators for wearable NFC controller demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Secure-Element Foundry Partnership | Exclusivity agreements with Taiwan and South Korean fabricators lock in die-shrink roadmaps for payment-grade controllers. |
| Automotive Digital Key Integration | Multi-protocol convergence with ultra-wideband and Bluetooth Low Energy electrifies tier-1 module supplier contracts. |
| India BIS Localization Compliance | Domestic assembly certification satisfies RBI payment hardware mandates and public sector procurement preferences. |
| Healthcare Credentialing Platform Launch | Hospital network partnerships in Germany and Australia bypass PCI-mandated terminal certification barriers. |
| Parallel Firmware Stream Maintenance | Dual cryptographic algorithm support for China MIIT GB standards preserves access to government procurement channels. |
Research Approach
Multi-period observation of secure-element foundry capacity announcements, transit authority procurement timelines, and payment terminal certification cycles anchored the trend analysis, supplemented by interviews with semiconductor design executives, terminal OEM procurement directors, and hospital IT integration specialists. Secondary validation drew from MIIT GB standard filings, PCI Security Standards Council certification databases, ETSI EN 300 330 electromagnetic compliance records, and BIS registration data. Bottom-up modeling of unit volumes across mobile devices, wearables, and point-of-sale terminals triangulated against top-down value estimates from interchange-fee economics and terminal refresh subsidies.
Segment-weighting approaches distributed value across product type, operating mode, application, and end-user verticals, with additional modeling of certification-tier differentiation between PCI-mandated payment hardware and lighter-regime transit credentials. CAGRs were derived from demand-curve projections for wearable NFC controllers and open-loop transit digitization velocity across the analysis window. Forecast inputs incorporated foundry die capacity expansion schedules, EU Radio Equipment Directive harmonization timelines, and India's PLI scheme incentive structures for domestic terminal assembly.
Underlying measurement precision varies by segment; mobile device and contactless payment volumes carry tighter precision due to established OEM reporting, while healthcare credentialing and cold-chain logistics applications reflect emerging adoption curves with wider confidence intervals. Forecasts assume sustained transit authority digitization mandates and continued secure-element foundry concentration, with revision triggers including tariff disruption on Taiwan-sourced wafers or accelerated host-card emulation displacement. Practitioners should monitor BIS certification queue lengths and São Paulo Metro open-loop expansion timelines for early signals of supply-demand imbalance.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Next Generation Technologies
5G New Radio Market
Next Generation Technologies
Nigeria ICT Market
Next Generation Technologies
Jordan ICT Market
Next Generation Technologies
Quantum Computing Market
Next Generation Technologies
Smart Surfaces Market
Next Generation Technologies
Poc Platform and Technology Market
Next Generation Technologies
Next Generation Network (NGN) Equipment Market
Next Generation Technologies
Fog Computing Market
Next Generation Technologies
Bulgaria ICT Market
Next Generation Technologies
Quantum Information Processing Market
Next Generation Technologies
Malaysia ICT Market
Next Generation Technologies
Hyperloop Technology Market
Next Generation Technologies
Europe Quantum Computing Market
Next Generation Technologies
Information and Communications Technology (ICT) Market
Next Generation Technologies
Next-Generation Communication Devices Market
Next Generation Technologies
Hyperscale Edge Computing Market