
 Quantum Computing Market | 2026-2036
Quantum Computing Market Size, Share, and Industry Trends Forecast 2026-2036
Quantum Computing Market Analysis
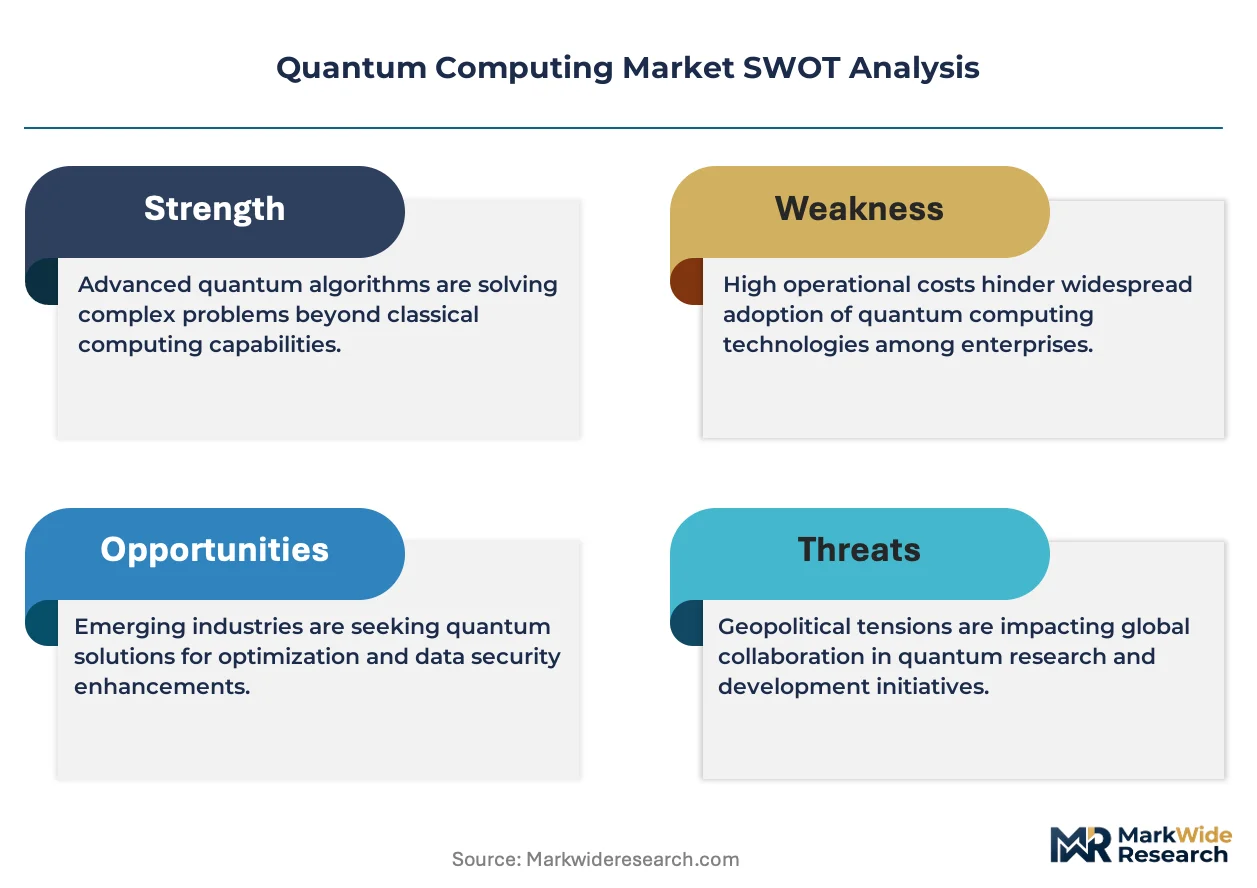
ISO/IEC 23837 quantum key distribution security evaluation is collapsing the qualification cycle for commercial system deployment. IBM leverages its superconducting qubit fabrication network to sustain foundry-scale production in New York State. Google anchors its competitive position through Sycamore processor roadmap execution and cryogenic control electronics specialization.
Quantum computing harnesses superposition and entanglement phenomena to process information using qubits operating at millikelvin temperatures, enabling exponential speedup for specific combinatorial problems in cryptography and materials science. Superconducting qubits currently dominate hardware revenue due to mature fabrication protocols borrowed from semiconductor lithography. Trapped ion systems differentiate through superior coherence times and lower error rates, attracting pharmaceutical end users running variational quantum eigensolver algorithms for drug discovery. Quantum software occupies the fastest-expanding margin pool as middleware layers abstract hardware heterogeneity for enterprise developers.
NIST post-quantum cryptography standardization is forcing federal contractors and BFSI institutions to audit encryption infrastructure ahead of cryptanalytically relevant quantum computer arrival. The US CHIPS and Science Act and EU Quantum Flagship program collectively shape demand by conditioning grant funding on domestic supply chain participation and workforce development benchmarks. Stakeholders must monitor NIST algorithm finalization timelines and national export control harmonization to calibrate R&D allocation across hardware modalities.
Market Dynamics
Superconducting qubit fabrication networks are consolidating around cryogenic control electronics specialization, compressing the hardware qualification cycle while ISO/IEC 23837 security evaluation protocols accelerate commercial system deployment timelines.
Growth Catalysts
- US CHIPS and Science Act:Federal investment mandates domestic quantum infrastructure buildout, conditioning grant funding on workforce development benchmarks and supply chain localization.
- Pharmaceutical molecular simulation:Drug discovery workloads are pulling variational quantum eigensolver adoption, with Munich Quantum Valley anchoring hardware-software venture clustering.
- NIST post-quantum cryptography:Federal contractors and BFSI institutions face mandatory encryption infrastructure audits ahead of cryptanalytically relevant quantum computer arrival.
Market Restraints
- Dilution refrigerator supply concentration:Cryogenic infrastructure fabrication concentrates among specialized industrial gas equipment suppliers, creating single-source vulnerability for millikelvin system deployment.
- Error correction overhead:Logical qubit requirements demand physical qubit counts exceeding current fabrication yields, extending commercial utility timelines.
- Helium-3 isotope scarcity:Nuclear non-proliferation protocols restrict quantum-grade cryogen feedstock availability, compressing dilution unit production capacity.
Strategic Opportunities
- Germany hardware clustering:Munich Quantum Valley infrastructure is attracting trapped ion ventures seeking proximity to Fraunhofer fabrication partnerships and EU Quantum Flagship funding access.
- Middleware abstraction layers:Quantum software stacks are opening enterprise developer access across superconducting and trapped ion hardware heterogeneity.
- EU Quantum Flagship workforce mandates:Grant conditions require domestic PhD pipeline development, creating captive talent pools for regional venture formation.
Industry Challenges
- Cryogenic control electronics engineering:Millikelvin signal routing and FPGA-based pulse generation require physics-electrical engineering cross-training unavailable in standard semiconductor curricula.
- Qubit calibration cycle compression:Drift compensation demands continuous automated tuning, stretching operational expenditure models beyond initial capex projections.
- Export control harmonization friction:Dual-use technology classifications vary across US, EU, and Japanese regulatory frameworks, complicating multinational deployment architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Quantum Computing Market |
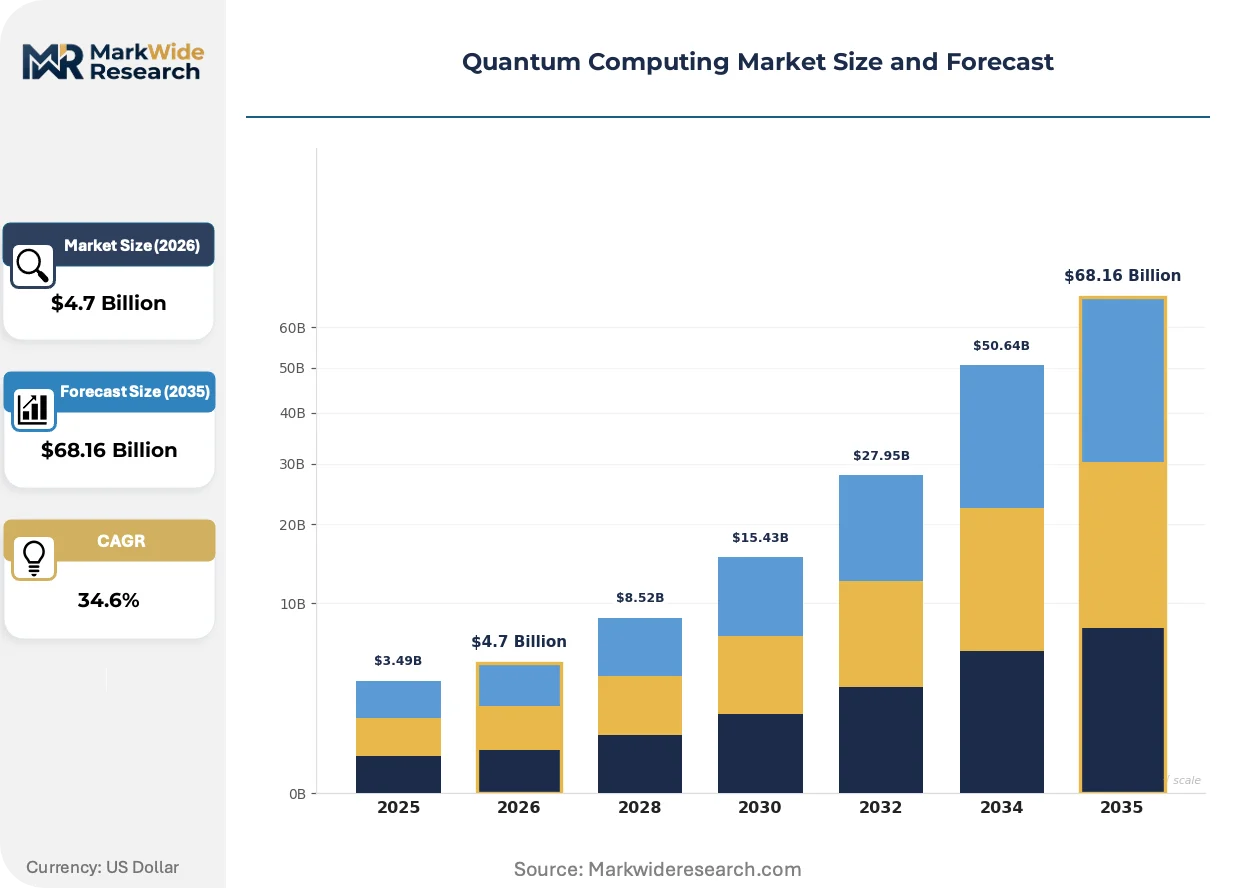
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $68.16 Billion |
| CAGR (2026 – 2036) | 34.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Quantum Processors, Quantum Sensors, Quantum Software, Quantum Communication End User: Academia, Government, BFSI, Pharmaceuticals Technology: Superconducting Qubits, Trapped Ions, Topological Qubits, Photonic Systems Application: Cryptography, Drug Discovery, Financial Modeling, Optimization |
| Companies Covered | IBM, Google, Microsoft, Amazon Web Services, D-Wave Quantum Inc., Rigetti Computing, IonQ, Quantinuum, Intel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Quantum Computing Market Emerging Trajectories
Trapped ion coherence time advantages are pulling pharmaceutical end users away from superconducting platforms, while middleware abstraction layers compress hardware switching costs for enterprise developers.
Photonic interconnect architectures are displacing coaxial cabling in modular quantum processor designs. Pharmaceutical firms running variational quantum eigensolver workloads favor trapped ion systems for superior gate fidelity. The shift is compressing superconducting qubit foundry dominance in molecular simulation segments.
ISO/IEC 23837 security evaluation frameworks are collapsing commercial quantum key distribution deployment timelines. Federal contractors must demonstrate compliance ahead of NIST post-quantum cryptography finalization. BFSI institutions in Germany and the US are prioritizing certified systems for encryption infrastructure audits.
Enterprise procurement patterns are consolidating around hardware-agnostic software contracts. Buyers demand portability across superconducting, trapped ion, and photonic backends, displacing vendor-specific stack commitments. This specification shift concentrates contract value in middleware and algorithm optimization layers rather than bare-metal qubit access.
Quantum Computing Market Segmentation
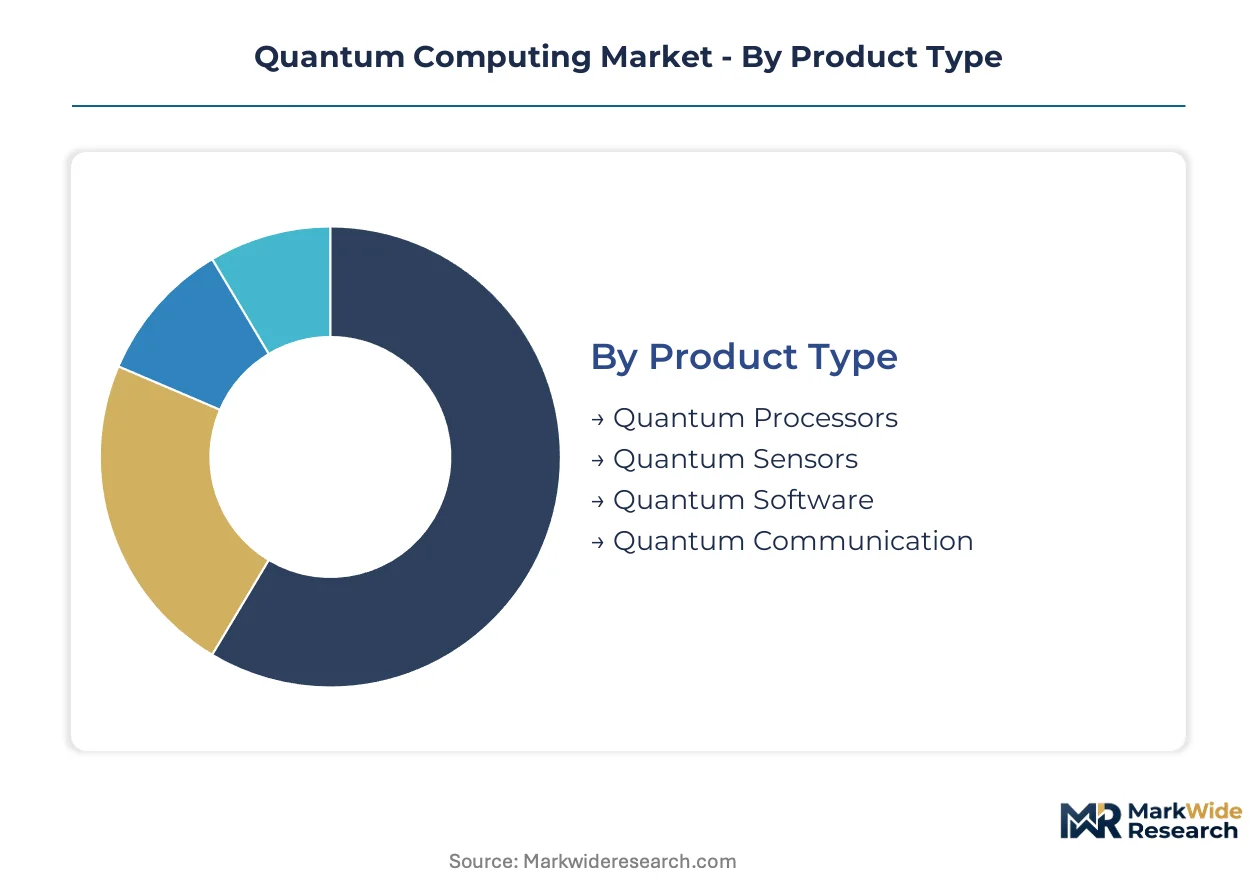
Quantum computing segmentation reveals divergent maturity curves across hardware modalities and software layers. Procurement patterns fragment between federal R&D contracts and enterprise pilot programs with distinct technical specifications.
Product Type:
Domestic production concentrates quantum processors and sensors in US and German fabrication networks, while quantum software development spreads across distributed engineering teams in India and Eastern Europe.
- Quantum Processors:Superconducting and trapped ion architectures fabricated at millikelvin specifications. US CHIPS Act funding anchors domestic foundry expansion in New York State and Colorado, though dilution refrigerator supply constraints compress deployment timelines.
- Quantum Software:Middleware abstraction layers and algorithm optimization stacks enabling hardware-agnostic enterprise deployment. Demand concentrates among pharmaceutical firms seeking variational quantum eigensolver integration without vendor lock-in.
- Quantum Sensors:Atomic interferometry and nitrogen-vacancy center devices for precision navigation and magnetic field mapping. Defense procurement drives domestic sourcing requirements.
- Quantum Communication:Quantum key distribution hardware and entanglement-based networking infrastructure. ISO/IEC 23837 certification mandates accelerate commercial qualification cycles.
Quantum processors hold the largest share; momentum sits with quantum software.
End User:
Cost tier stratification separates capital-intensive government programs from subscription-based enterprise access models.
- Government:National laboratory procurement and defense agency programs spanning cryptanalysis and secure communications. NIST post-quantum cryptography mandates drive encryption infrastructure audit spending.
- Pharmaceuticals:Molecular simulation workloads leveraging variational quantum eigensolvers for drug discovery. Munich Quantum Valley clustering attracts hardware-software venture partnerships seeking Fraunfer fabrication access.
- BFSI:Risk modeling and portfolio optimization pilots, with EU institutions prioritizing GDPR-compliant quantum key distribution for transaction security.
- Academia:Foundational research access through cloud-based quantum computing platforms and national supercomputing center partnerships.
Government holds the largest share; momentum sits with pharmaceuticals.
Technology:
Application requirements dictate hardware selection, with coherence time specifications and gate fidelity thresholds driving procurement decisions.
- Superconducting Qubits:Josephson junction arrays fabricated through adapted semiconductor lithography. Mature foundry protocols sustain foundry-scale production, though error correction overhead demands physical qubit counts beyond current yields.
- Trapped Ions:Laser-manipulated atomic qubits in electromagnetic traps offering superior coherence times. Pharmaceutical end users favor this modality for drug discovery workloads requiring sustained quantum states.
- Photonic Systems:Linear optical quantum computing and continuous-variable approaches. Modular interconnect architectures displace coaxial cabling in distributed processor designs.
- Topological Qubits:Majorana zero-mode devices pursued for intrinsic error protection. Microsoft and academic consortia anchor development, with longer commercialization horizons.
Superconducting qubits hold the largest share; trapped ions are climbing the fastest.
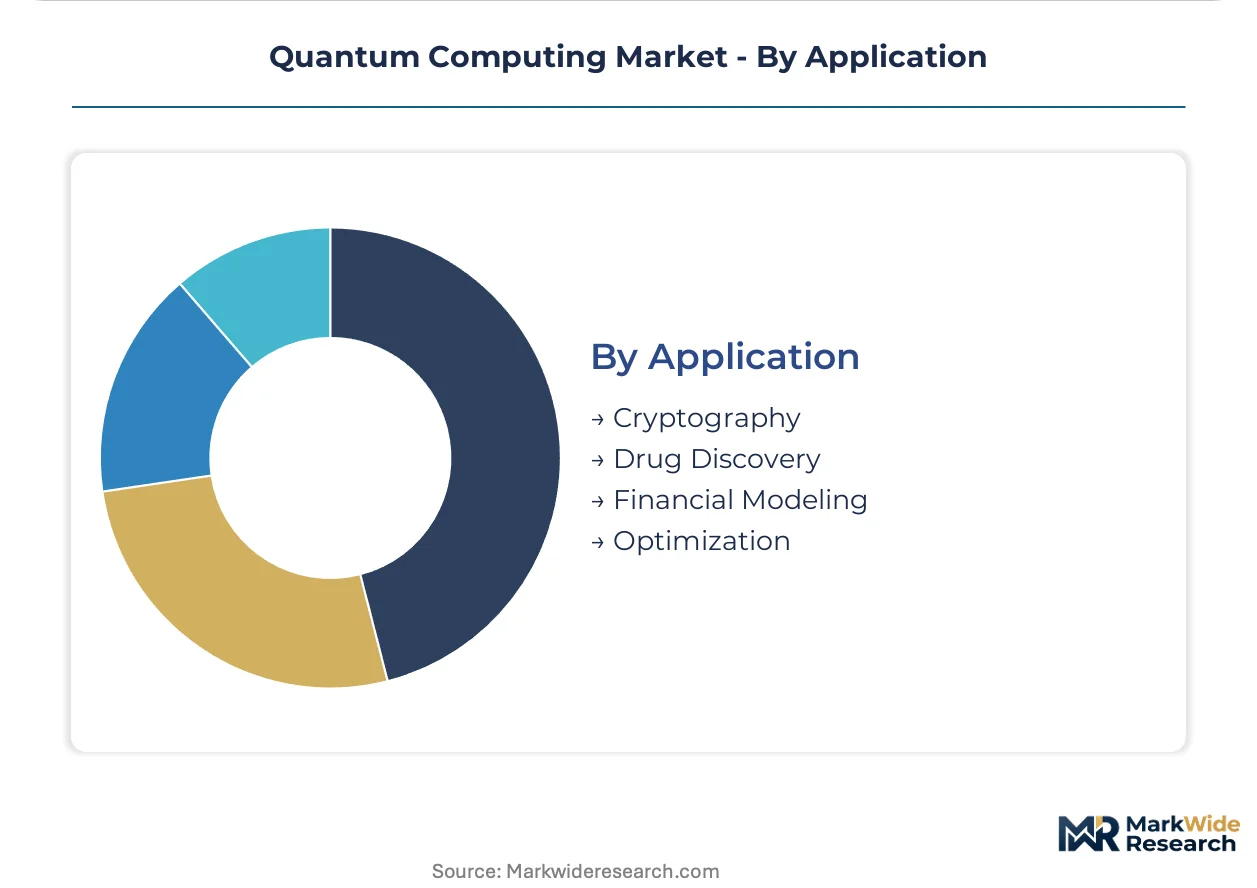
Application:
Customer type segmentation separates defense-classified workloads from commercial optimization problems with divergent security and latency requirements.
- Drug Discovery:Variational quantum eigensolver algorithms for molecular ground-state energy calculation. Munich Quantum Valley hardware clustering accelerates pharmaceutical pilot programs.
- Cryptography:Quantum key distribution deployment and post-quantum algorithm migration. Federal contractors face mandatory NIST compliance timelines.
- Financial Modeling:Monte Carlo acceleration and portfolio risk optimization. BFSI institutions pilot cloud-based access before bare-metal procurement.
- Optimization:Combinatorial logistics and supply chain problems across manufacturing and transportation verticals. Middleware abstraction enables hardware-agnostic algorithm portability.
Drug discovery holds the largest share; cryptography is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US CHIPS and Science Act channels federal investment toward domestic quantum infrastructure buildout, conditioning grant funding on workforce development benchmarks and supply chain localization. Germany anchors European momentum through the Munich Quantum Valley cluster, while China accelerates state-backed superconducting qubit fabrication at scale.
United States
National laboratory procurement and defense agency programs drive demand for cryptanalysis and secure communications applications. NIST post-quantum cryptography mandates force federal contractors to audit encryption infrastructure ahead of quantum computer arrival. New York State hosts IBM's superconducting qubit foundry network, sustaining foundry-scale production through adapted semiconductor lithography.
Germany
Pharmaceutical molecular simulation workloads pull variational quantum eigensolver adoption from drug discovery end users. EU Quantum Flagship program conditions grant funding on domestic PhD pipeline development and captive talent pool formation. Munich Quantum Valley anchors hardware-software venture clustering, attracting trapped ion specialists seeking Fraunhofer fabrication partnerships.
China
State-backed research institutes pursue superconducting and photonic quantum processor development for strategic technology autonomy. National standards bodies accelerate domestic quantum key distribution certification protocols parallel to ISO/IEC frameworks. Beijing and Hefei host concentrated academic-industry consortia advancing cryogenic control electronics engineering.
United Kingdom
BFSI institutions pilot quantum-enabled portfolio risk optimization and Monte Carlo acceleration through cloud-based access models. National quantum computing center procurement mandates domestic supply chain participation for hardware-software integration contracts. Cambridge and Oxford anchor university spinout formation, concentrating trapped ion and photonics ventures near fabrication partnerships.
Japan
Corporate research divisions advance superconducting qubit coherence time extension for materials science applications. METI funding programs target cryogenic infrastructure localization to reduce dilution refrigerator import dependence. Tokyo and Osaka metropolitan areas concentrate quantum software engineering talent for middleware abstraction layer development.
Quantum Computing Market Vendor Landscape
Listed leaders compete with private specialists across hardware modality specialization, creating a tiered structure where scale-driven incumbents anchor superconducting foundry production while venture-backed entrants pursue trapped ion differentiation. Strategic archetypes separate into integrated cloud platform operators, pure-play hardware fabricators, and algorithm optimization software vendors. Competitive moves concentrate on cryogenic control electronics vertical integration and strategic partnerships with national laboratory procurement programs.
Among US-based technology conglomerates, IBM and Google exemplify integrated platform archetypes spanning superconducting processor fabrication through cloud access provisioning, while IonQ represents the venture-scaled trapped ion specialist tier competing on coherence time specifications for pharmaceutical end users.
| Leading Market Players |
|---|
| IBM |
| Microsoft |
| Amazon Web Services |
| D-Wave Quantum Inc. |
| Rigetti Computing |
| IonQ |
| Quantinuum |
| Intel |
| Others |
Supply Flow & Price Mechanics
ISO/IEC 23837 certification requirements gate both supplier qualification and price differentiation in quantum computing procurement, compressing deployment timelines for certified systems while widening spreads between compliant and non-compliant hardware tiers. Federal contractors and BFSI institutions face mandatory compliance timelines that reshape procurement budgets and supplier selection criteria simultaneously.
Pricing Analysis
Certification level creates the primary spread between quantum system tiers, with ISO/IEC 23837-compliant quantum key distribution hardware commanding substantial premiums over uncertified alternatives. Three-tier pricing structure across enterprise-grade certified systems, pilot-program qualified hardware, and research-access bare-metal configurations reflects this segmentation. Cost compression in research-access tiers is intensifying because cloud-based abstraction layers commoditize qubit-hour consumption. Government procurement programs demonstrate the lowest price sensitivity, while academic institutions and early-stage pharmaceutical pilots exhibit the highest.
Supply Chain Analysis
The United States and Germany anchor superconducting qubit fabrication and cryogenic control electronics production, while Finland and Japan concentrate dilution refrigerator manufacturing. Quantum-grade helium-3 isotope feedstock draws from nuclear non-proliferation treaty-limited stockpiles, and specialized FPGA-based pulse generation hardware rests on semiconductor foundry partnerships. Single-source vulnerability in millikelvin cryogenic infrastructure creates systemic deployment risk. Distribution runs through national laboratory procurement channels and direct enterprise sales teams with extended qualification cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hardware modality fragmentation and middleware abstraction are splintering procurement patterns, creating specialized niches for trapped ion coherence-time specialists and cryogenic electronics engineers.
For Market Incumbents: Consolidate cryogenic control electronics capabilities through backward integration into FPGA-based pulse generation and millikelvin signal routing engineering. Lock in Fraunhofer fabrication partnerships in Germany to defend against trapped ion venture clustering. Prioritize ISO/IEC 23837 pre-certification investment to capture federal contractor procurement windows ahead of NIST post-quantum cryptography finalization.
For New Entrants and Emerging Players: Anchor in Munich Quantum Valley infrastructure to access EU Quantum Flagship funding and captive PhD talent pools. Target pharmaceutical molecular simulation segments where variational quantum eigensolver workloads favor coherence-time specifications over superconducting gate speeds. Pursue middleware abstraction layer development to enable hardware-agnostic enterprise contracts.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across dilution refrigerator manufacturing and cryogenic control electronics verticals. Five-to-ten-year viability hinges on national laboratory procurement relationship depth and export control license holdings. Target acquisition archetypes: trapped ion ventures with Fraunhofer partnerships or superconducting foundries with CHIPS Act qualification. Monitor helium-3 isotope supply allocation decisions as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Cryogenic Control Electronics Integration | Captures margin pool from millikelvin signal routing specialization demanded by IBM and Google roadmaps. |
| ISO/IEC 23837 Pre-Certification Investment | Accelerates federal contractor qualification timelines ahead of NIST post-quantum cryptography mandates. |
| Munich Quantum Valley Partnership Formation | Unlocks EU Quantum Flagship funding access and Fraunhofer fabrication proximity for trapped ion ventures. |
| Middleware Abstraction Layer Development | Enables hardware-agnostic enterprise procurement contracts displacing vendor-specific stack commitments. |
| Helium-3 Supply Agreement Structuring | Secures dilution refrigerator production capacity against nuclear non-proliferation protocol constraints. |
Methodological Framework
A spread of perspectives from quantum hardware engineers, pharmaceutical R&D directors, federal procurement officers, and cryogenic systems specialists converged on the working assumptions shaping this analysis. Primary interviews with trapped ion fabrication leads and superconducting foundry operations managers combined with secondary validation against NIST post-quantum cryptography documentation, EU Quantum Flagship grant disclosures, and SEC filings from listed quantum computing ventures. Bottom-up triangulation across hardware modality production volumes and top-down reconciliation against national laboratory budget appropriations anchored the quantitative framework.
Segmentation dimensions modeled span hardware modality, software layer abstraction, end-user vertical, and regional regulatory cluster across the projection horizon. CAGRs derived from fitted growth curves incorporate pharmaceutical molecular simulation adoption rates, federal encryption infrastructure audit spending patterns, and cloud-based quantum access subscription trajectories. Cryogenic infrastructure deployment constraints and workforce development benchmark compliance feed into capacity-limited supply-side assumptions.
Material uncertainties — helium-3 isotope supply disruption, export control harmonization friction, and error correction overhead timeline slippage — sit outside the modeled envelope. Forecasts reflect documented assumptions about NIST algorithm finalization schedules and CHIPS Act funding disbursement continuity. Recalibration cycles align with material shifts in national laboratory procurement award announcements and ISO/IEC certification protocol updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Next Generation Technologies
Nigeria ICT Market
Next Generation Technologies
Next-Generation Communication Devices Market
Next Generation Technologies
Nearfield Communication (NFC) Market
Next Generation Technologies
Next Generation Wireless Network Market
Next Generation Technologies
Hyperloop Technology Market
Next Generation Technologies
Quantum Information Processing Market
Next Generation Technologies
Ireland ICT Market
Next Generation Technologies
Bulgaria ICT Market
Next Generation Technologies
Information and Communications Technology (ICT) Market
Next Generation Technologies
Smart Surfaces Market
Next Generation Technologies
5G New Radio Market
Next Generation Technologies
Jordan ICT Market
Next Generation Technologies
Europe Quantum Computing Market
Next Generation Technologies
Poc Platform and Technology Market
Next Generation Technologies
Enterprise Quantum Computing Market
Next Generation Technologies
M2M Connections Market