
 North America Energy Management Systems Market | 2026-2036
North America Energy Management Systems Market Size, Share, and Industry Trends Forecast 2026-2036
North America Energy Management Systems Market Analytics
Market Context
Data center power density requirements are rebalancing the commercial-industrial user mix across North America. Johnson Controls International leverages its building automation heritage to anchor large-scale campus deployments. Honeywell International competes through integrated controls that span HVAC, lighting, and power distribution. Schneider Electric SE differentiates via microgrid-ready architectures that sustain margin in high-complexity installations.
Technical Definition and Segments
Energy management systems encompass software platforms, sensor networks, control hardware, and analytics services that monitor, control, and optimize energy consumption across facilities and grids, typically integrating real-time metering with automated load scheduling to reduce kilowatt-hour intensity and demand charges. Software and cloud solutions command expanding share as subscription models displace perpetual licenses, while demand response applications attract utility co-investment that hardware-centric deployments rarely capture. On-premises systems retain footholds in critical infrastructure where cybersecurity protocols restrict external connectivity, though hybrid deployment architectures are gaining traction among industrial end users seeking staged cloud migration paths.
Regulatory Environment
The US EPA and Department of Energy efficiency mandates, alongside state-level building performance standards in California and New York, are tightening baseline requirements for commercial energy intensity and disclosure. FERC Order 2222 enables distributed energy resource aggregation that expands addressable demand for utility-facing load management platforms. Stakeholders must monitor how state utility commission rulings on grid modernization cost recovery reshape the business case for behind-the-meter EMS investments.
Market Dynamics
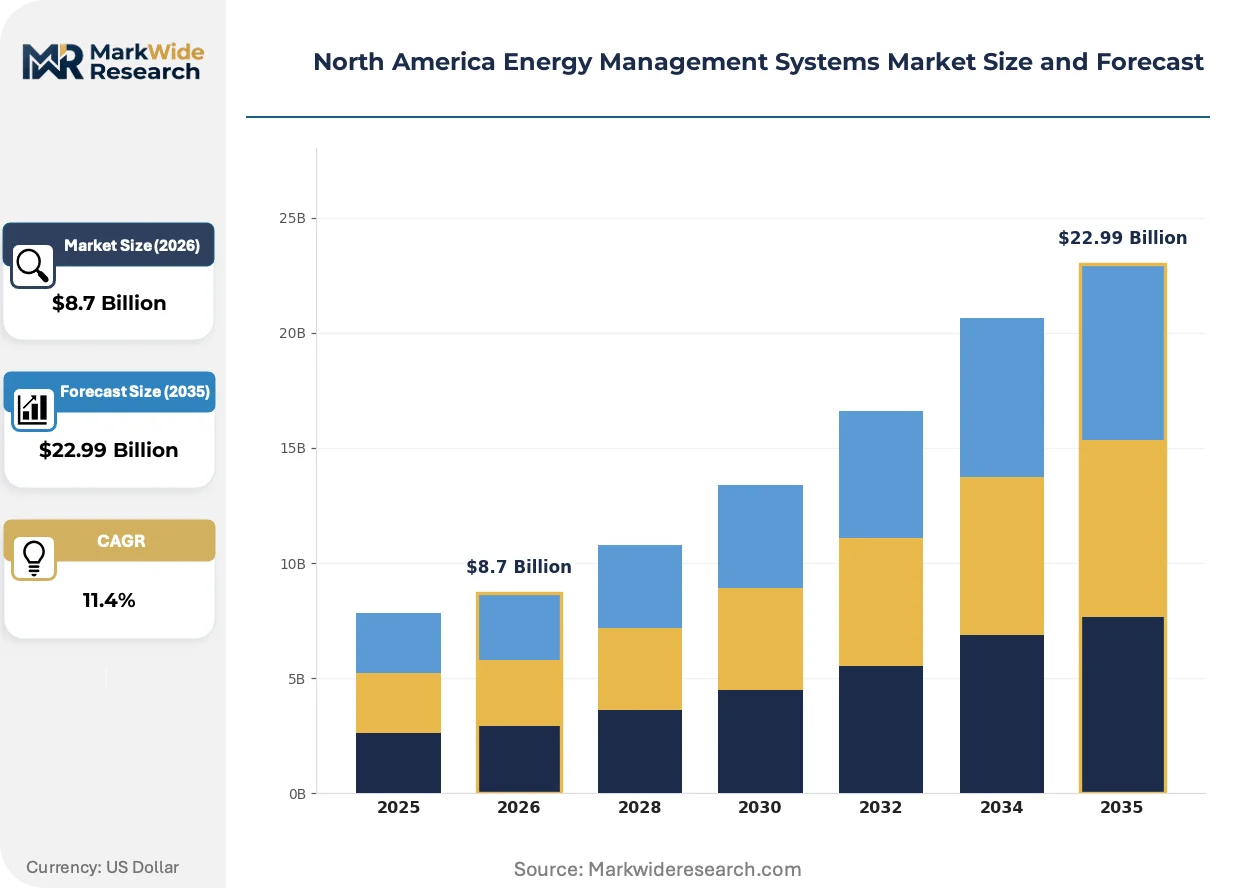
The US Inflation Reduction Act's efficiency incentives are compressing procurement cycles as facility operators race to capture tax credits before qualification windows narrow. This regulatory pressure is reshaping how commercial building portfolios evaluate platform investments.
Growth Catalysts
- California's Title 24 building standards:Mandatory energy benchmarking and disclosure requirements are forcing commercial property managers to deploy automated metering infrastructure. The state's decarbonization mandates accelerate retrofit timelines.
- Data center power density escalation:Hyperscale facilities in Texas and Virginia are driving demand for real-time load scheduling platforms. These operators prioritize kilowatt-hour intensity reduction to manage utility demand charges.
- FERC Order 2222 aggregation frameworks:Distributed energy resource participation rules enable behind-the-meter assets to bid into wholesale markets. This creates new revenue streams for commercial EMS deployments.
Market Restraints
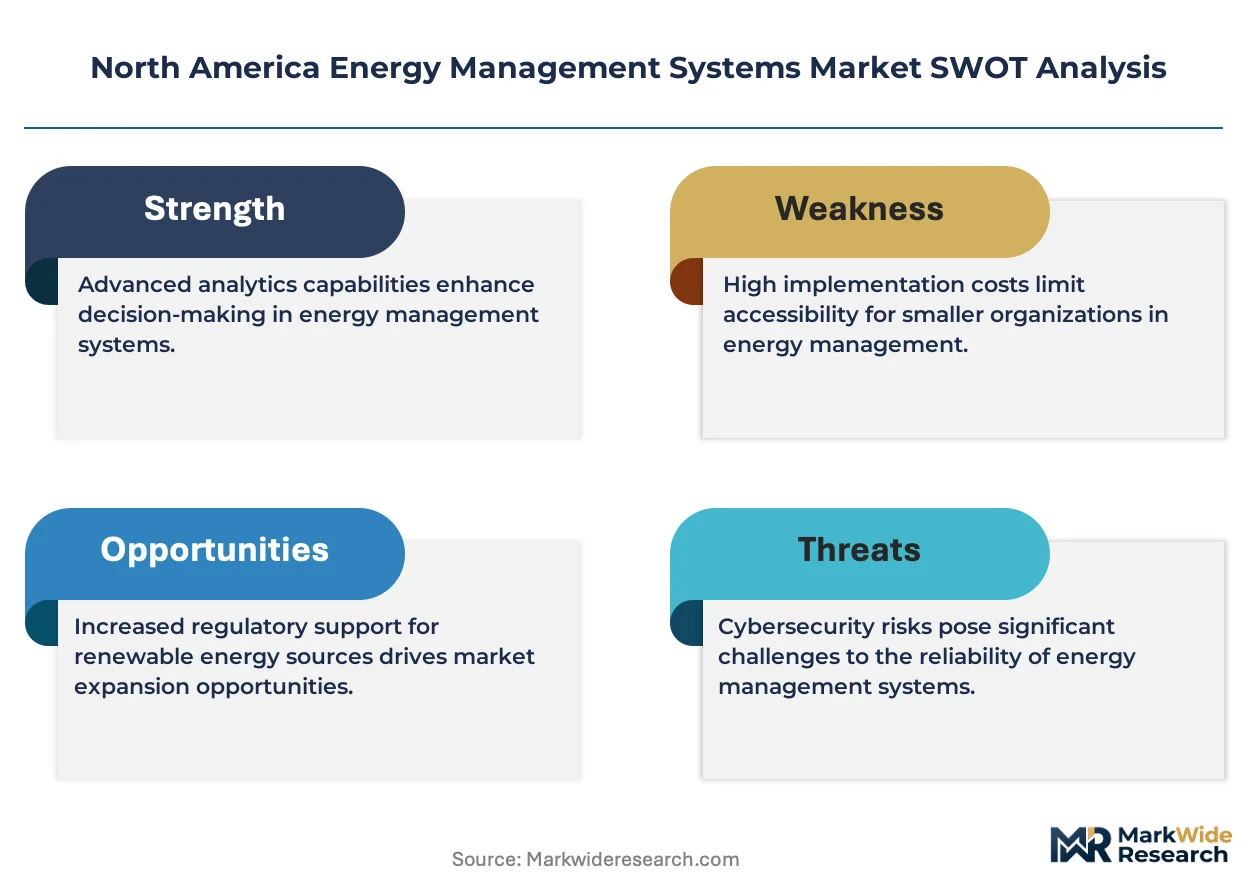
- Semiconductor supply concentration:Control hardware manufacturing depends on concentrated Asian foundry capacity. Lead times for programmable logic controllers and power meters extend deployment schedules.
- Cybersecurity compliance friction:Critical infrastructure operators face NERC CIP and state-level requirements that restrict external cloud connectivity. On-premises architectures carry higher total cost of ownership.
- Skilled technician scarcity:Commissioning complex building automation networks requires certified controls specialists. Labor shortages in electrical trades delay project handoffs.
Strategic Opportunities
- New York Local Law 97 carbon caps:Building performance standards create compliance-driven demand for predictive analytics. Penalty structures strengthen the business case for comprehensive monitoring platforms.
- Microgrid-ready architecture convergence:Integration of solar inverters, battery storage controls, and grid-interactive water heaters opens campus-scale projects. Industrial end users seek unified orchestration layers.
- Texas ERCOT price volatility exposure:Real-time wholesale rate spikes are forcing commercial load centers toward automated demand response. Subscription-based flexibility services attract new buyer segments.
Industry Challenges
- Legacy BAS protocol fragmentation:Proprietary communication standards from incumbent building automation vendors complicate multi-site integration. Open-source middleware adoption remains uneven.
- Utility interconnection queue delays:Behind-the-meter generation assets face months-long approval timelines. Project developers absorb carrying costs that erode EMS project returns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Energy Management Systems Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Software, Hardware, Services, Cloud Solutions End User: Commercial, Industrial, Residential, Utilities Application: Energy Monitoring, Demand Response, Renewable Integration, Load Management Deployment: On-Premises, Cloud-Based, Hybrid, Others |
| Companies Covered | Johnson Controls International, Honeywell International, Siemens AG, Schneider Electric SE, General Electric, ABB Limited, IBM Corporation, Eaton Corporation, C3.ai, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Energy Management Systems Market Evolving Landscape
Artificial intelligence inference at the edge is compressing response latencies for load prediction algorithms. Platform vendors are racing to embed machine learning models directly into gateway hardware.
Digital twin modeling is integrating physics-based building simulation with live sensor streams. University campuses and healthcare complexes in California are piloting these platforms to optimize HVAC staging. The technology is integrating thermal mass dynamics with occupancy forecasting to preemptively adjust setpoints.
The US Department of Energy's Better Buildings Challenge is tightening disclosure requirements for commercial energy intensity. Participants must now report whole-building performance metrics annually. Large office portfolios in New York and Chicago are responding by consolidating fragmented metering systems into unified data lakes.
Subscription pricing for software layers is displacing perpetual license models in mid-market commercial deployments. Facility management firms in Texas and Florida are bundling analytics services with hardware leases. Property owners with limited capital budgets prefer operational expenditure treatment for efficiency investments.
North America Energy Management Systems Market Segmentation
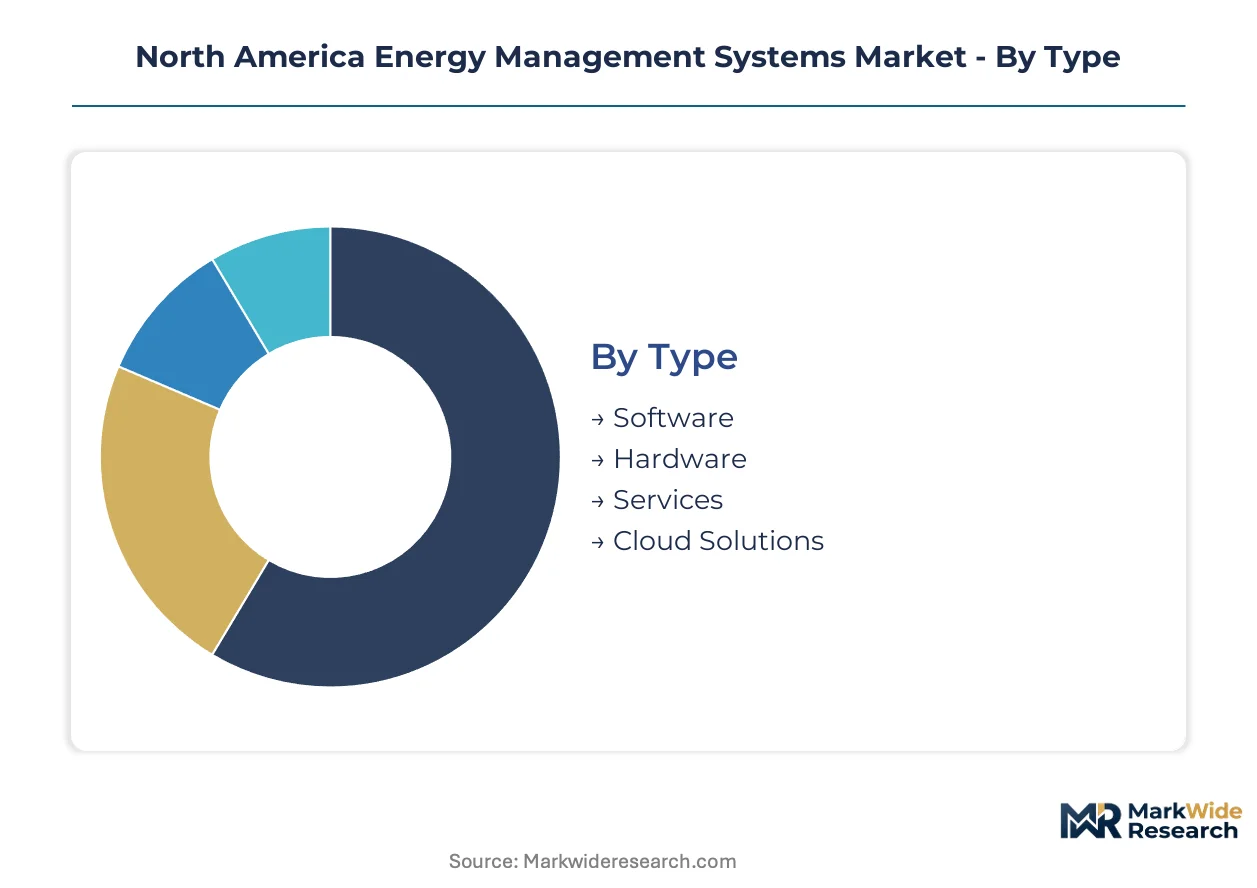
EMS procurement patterns diverge sharply across deployment scales and regulatory exposure. Facility operators select platform architectures based on cybersecurity mandates, capital availability, and utility rate structure complexity.
Type:
Certification requirements vary by segment: hardware components face UL and FCC emissions testing, while cloud solutions navigate SOC 2 and state-level data privacy frameworks.
- Software:Analytics platforms process real-time metering data through machine learning inference engines. Demand concentrates in California and New York commercial portfolios where Local Law 97 and Title 24 mandate automated benchmarking. The segment attracts utility co-investment for demand response orchestration.
- Hardware:Sensor networks, programmable logic controllers, and power meters form the physical measurement layer. Texas data center operators drive procurement of high-density metering infrastructure to manage ERCOT demand charge exposure. Lead times extend due to Asian foundry concentration.
- Services:Commissioning, system integration, and ongoing optimization support. Skilled technician scarcity in electrical trades constrains deployment velocity across mid-market commercial buildings.
- Cloud Solutions:Subscription-based platforms with remote monitoring capabilities. Florida and Texas facility management firms favor operational expenditure treatment for efficiency investments.
Leading the category by volume: Hardware. Growing fastest: Cloud Solutions.
End User:
Cost tier differentiation separates enterprise-grade deployments from scaled-down implementations.
- Commercial:Office portfolios, retail chains, and hospitality properties deploy unified metering across multi-site footprints. New York Local Law 97 carbon caps accelerate predictive analytics adoption among large office landlords.
- Industrial:Manufacturing campuses and process facilities prioritize load scheduling to manage utility demand charges. Microgrid-ready architectures gain traction for behind-the-meter solar and storage integration.
- Residential:Single-family and multi-family building automation with utility-facing demand response enrollment. California and Texas utility programs subsidize smart thermostat and water heater controls.
- Utilities:Grid operators and load-serving entities procure aggregation platforms for FERC Order 2222 compliance. Wholesale market participation rules expand addressable demand for distributed energy resource orchestration.
Commercial deployments dominate absolute spending. Industrial applications climb fastest as power density requirements escalate.
Application:
Functional maturity separates established monitoring from emerging grid-interactive capabilities.
- Energy Monitoring:Real-time consumption tracking and benchmarking against baseline performance. California Title 24 mandates drive automated metering infrastructure deployment across commercial property portfolios.
- Demand Response:Automated load curtailment in response to utility signals or wholesale price spikes. Texas ERCOT volatility exposure forces commercial load centers toward subscription-based flexibility services.
- Renewable Integration:Solar inverter and battery storage control for behind-the-meter generation. Utility interconnection queue delays erode project returns in high-growth markets.
- Load Management:Predictive scheduling of HVAC, lighting, and process loads. University campuses in California pilot digital twin modeling for thermal mass optimization.
Energy Monitoring holds the largest installed base. Demand Response expands most quickly under FERC aggregation frameworks.
Deployment:
Customer risk tolerance and cybersecurity posture determine architecture selection.
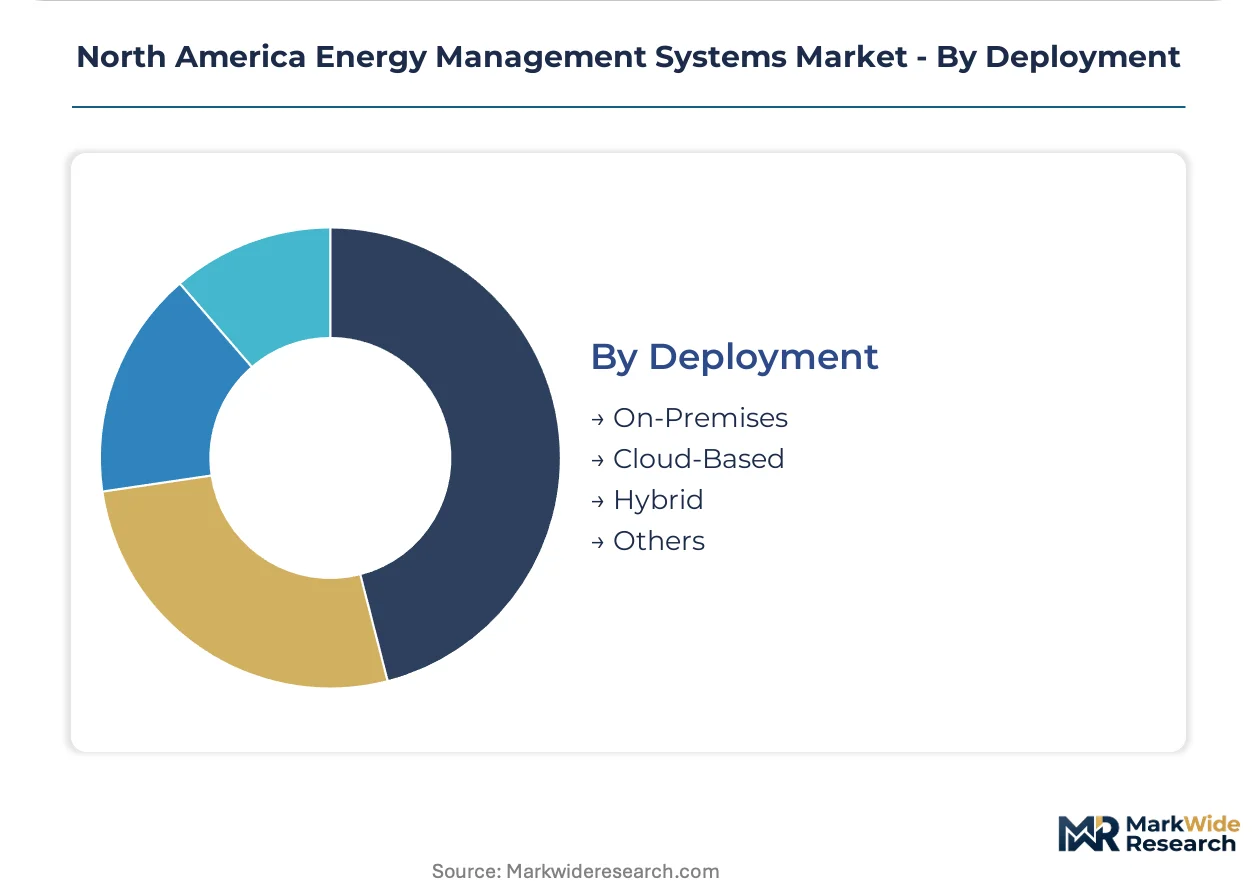
- On-Premises:Local server infrastructure with restricted external connectivity. Critical infrastructure operators accept higher total cost of ownership to satisfy NERC CIP requirements.
- Cloud-Based:Fully managed SaaS platforms with remote accessibility. Mid-market commercial adopters in Florida and Texas prefer subscription pricing and reduced IT burden.
- Hybrid:Edge processing with cloud analytics synchronization. Industrial end users pursue staged migration paths that preserve operational continuity.
- Others:Managed service and colocation arrangements for specialized compliance environments.
Cloud-Based deployments lead new bookings. Hybrid architectures gain share fastest among industrial facilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Inflation Reduction Act's tax credit zones concentrate EMS deployment in states with overlapping utility rate volatility and building performance mandates.
United States
Data center power density requirements in Texas and Virginia drive real-time load scheduling platform procurement. FERC Order 2222 aggregation frameworks enable behind-the-meter assets to bid into wholesale markets, expanding addressable demand for commercial deployments. California's Title 24 building standards and New York Local Law 97 carbon caps accelerate automated metering infrastructure across commercial portfolios in Los Angeles, San Francisco, and New York City.
Canada
Provincial carbon pricing mechanisms in Ontario and British Columbia strengthen the business case for campus-scale energy optimization. Natural Resources Canada's Green Buildings Strategy mandates energy benchmarking for federal facilities. Toronto and Vancouver commercial landlords consolidate fragmented metering systems to satisfy disclosure requirements and utility incentive programs.
Mexico
Industrial manufacturing clusters in Nuevo León and Baja California deploy load management platforms to manage CFE demand charges. The country's national energy regulator advances grid modernization rules that expand behind-the-meter solar integration opportunities. Monterrey automotive suppliers pilot microgrid-ready architectures to sustain operations during grid instability events.
North America Energy Management Systems Market Competitive Landscape
Top-tier vendors anchor the premium integration tier, while mid-market specialists compete on deployment velocity and subscription pricing. The vendor base organizes around three strategic archetypes: building automation heritage players, industrial controls conglomerates, and cloud-native analytics platforms. Consolidation pressure favors vendors with captive distribution networks and multi-protocol integration capabilities. Dominant competitive moves include strategic partnerships with utility demand response programs and portfolio diversification into microgrid orchestration software.
Within the building automation heritage tier, Johnson Controls International and Honeywell International occupy positions defined by large-scale campus deployment experience. Schneider Electric SE exemplifies the microgrid-ready architecture specialization that sustains margin in high-complexity installations. These three entities represent distinct competitive vectors—legacy controls integration, unified multi-system platforms, and distributed energy resource orchestration—that structure rivalry across commercial and industrial end-use segments.
| Leading Market Players |
|---|
| Johnson Controls International |
| Honeywell International |
| Siemens AG |
| Schneider Electric SE |
| General Electric |
| ABB Limited |
| IBM Corporation |
| Eaton Corporation |
| C3.ai |
| Others |
Value Network & Pricing Analysis
Certified controls specialists concentrated in Texas and California electrical trades command wage premiums that compress margins on economy-tier deployments while sustaining pricing power for enterprise-grade integration contracts. Labor-cost differentials between unionized metropolitan markets and right-to-work states drive three-tier pricing spreads that separate premium commissioning services from standardized hardware packages.
Pricing Analysis
Premium pricing attaches to short lead-time delivery of programmable logic controllers and power meters, while spot inventory of prior-generation sensors trades at discounted rates. The dominant structure stratifies across subscription-based SaaS analytics, project-based hardware integration, and managed services retainers. Price differentiation rests on UL certification tier and geographic delivery cost, with cybersecurity-hardened on-premises architectures carrying sustained premiums. Cost compression in mid-market cloud subscriptions is intensifying because utility co-investment programs cap recoverable software fees. Data center operators in ERCOT markets show least price sensitivity due to demand charge exposure, while small commercial portfolios in Florida exhibit highest sensitivity to upfront capital outlays.
Supply Chain Analysis
Freight cost volatility from Asian manufacturing hubs to North American distribution centers amplifies landed cost uncertainty for sensor networks and control hardware. Supply concentrates in Taiwan for semiconductor components, China for power meter assembly, and Mexico for enclosure fabrication. Raw material dependencies span rare earth magnets for motor controls, copper for power distribution components, and lithium for battery-backed gateway units. Single-source vulnerability in programmable logic controller chipsets exposes deployment timelines to foundry allocation decisions. Distribution runs through authorized systems integrators who bundle commissioning labor with hardware procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance arena where New York Local Law 97's escalating carbon penalties erect barrier-to-entry moats for vendors with certified benchmarking platforms and established utility incentive program relationships.
For Market Incumbents: Anticipate margin compression from cloud-native analytics platforms by deepening backward integration into edge gateway manufacturing and securing exclusive distribution agreements with California Title 24 compliance consultants. Threat substitution from AI-native building automation entrants demands accelerated R&D investment in digital twin orchestration layers. Channel control through captive systems integrator networks remains the priority defensive lever. For New Entrants and Emerging Players: Begin with Texas ERCOT-linked demand response subscriptions where automated load curtailment services face limited incumbent saturation and price volatility creates urgent buyer need. The most penetrable white space sits in mid-market commercial portfolios between 50,000 and 200,000 square feet lacking dedicated energy management staff. A utility partnership go-to-market angle unlocks co-investment capital and accelerates customer acquisition velocity. For Investors and Strategic Acquirers: Re-rating potential sits with microgrid-ready platform specialists given FERC Order 2222 aggregation frameworks expanding addressable revenue pools. Long-term viability across the analysis window favors vendors with multi-protocol integration capabilities and captive distribution through building automation heritage channels. The signal to watch is state utility commission rulings on grid modernization cost recovery that reshape behind-the-meter investment returns.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifying HVAC, lighting, and power distribution controls strengthens campus-scale competitive positioning against fragmented point solutions. |
| Strategic Partnership | Utility demand response program alliances unlock co-investment capital and accelerate mid-market commercial customer acquisition. |
| Acquisition of Specialist Firm | Digital twin modeling capabilities address California university and healthcare complex pilot requirements for thermal mass optimization. |
| Geographic Expansion | Texas and Virginia data center clusters offer concentrated hyperscale procurement opportunities for real-time load scheduling platforms. |
| Product Launch | Edge AI gateway hardware with embedded machine learning inference compresses response latencies for ERCOT price volatility exposure. |
Research Methodology
EPA enforcement databases, FERC Order 2222 implementation filings, and EIA commercial building energy consumption surveys formed the secondary backbone. Primary interviews with utility demand response program managers, building automation systems integrators, and commercial real estate sustainability directors combined with this secondary validation. Bottom-up and top-down triangulation cross-checked facility-level deployment estimates against state-level incentive program disbursement records.
Bottom-up modeling aggregated individual project economics across deployment scale tiers, while top-down analysis tracked regulatory mandate adoption curves. Segmentation dimensions included software versus hardware versus services revenue mix, on-premises versus cloud versus hybrid architecture, and commercial versus industrial versus utility end-user categories. CAGRs derived from fitted adoption curves incorporating IRA tax credit phase-out schedules and state building performance standard enforcement timelines. Forecast inputs included ERCOT wholesale price volatility indices and California Title 24 compliance deadline clustering.
Underlying measurement precision varies by segment; utility-facing aggregation platforms carry tighter precision than fragmented mid-market commercial deployments. Forecasts reflect assumptions regarding semiconductor supply normalization and skilled technician pipeline expansion that industry stakeholders should weight against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Management Systems
Smart Cooling Systems Market
Energy Management Systems
GCC Desert Air Coolers Market
Energy Management Systems
Smart Thermostat Market
Energy Management Systems
Europe Home Energy Management System Market
Energy Management Systems
India Home Ventilation System Market
Energy Management Systems
Noise Mitigation System Market
Energy Management Systems
Smart Utilities Management Market
Energy Management Systems
District Cooling Market
Energy Management Systems
Global Digital Utility Market
Energy Management Systems
Global Thermal Management Technologies Market
Energy Management Systems
Africa Digital Showers Market
Energy Management Systems
Global Next-Generation Building Energy Management Systems Market
Energy Management Systems
United Arab Emirates Portable Air Conditioning Market
Energy Management Systems
EV Smart HVAC System Market
Energy Management Systems
Bed Cooling System Market
Energy Management Systems
Smart Climate Control Market