
 Ireland ICT Market | 2026-2036
Ireland ICT Market Size, Share, and Industry Trends Forecast 2026-2036
Ireland ICT Market Insights
Enterprise software licensing channels are rewriting how technology reaches Irish buyers. Microsoft Corporation leverages its entrenched productivity stack to sustain renewal rates across public sector accounts. Amazon Web Services Inc. anchors hyperscale cloud capacity from its Dublin Region data centers. Intel Corporation competes through semiconductor design operations that extend its influence over hardware procurement patterns in Irish enterprise.
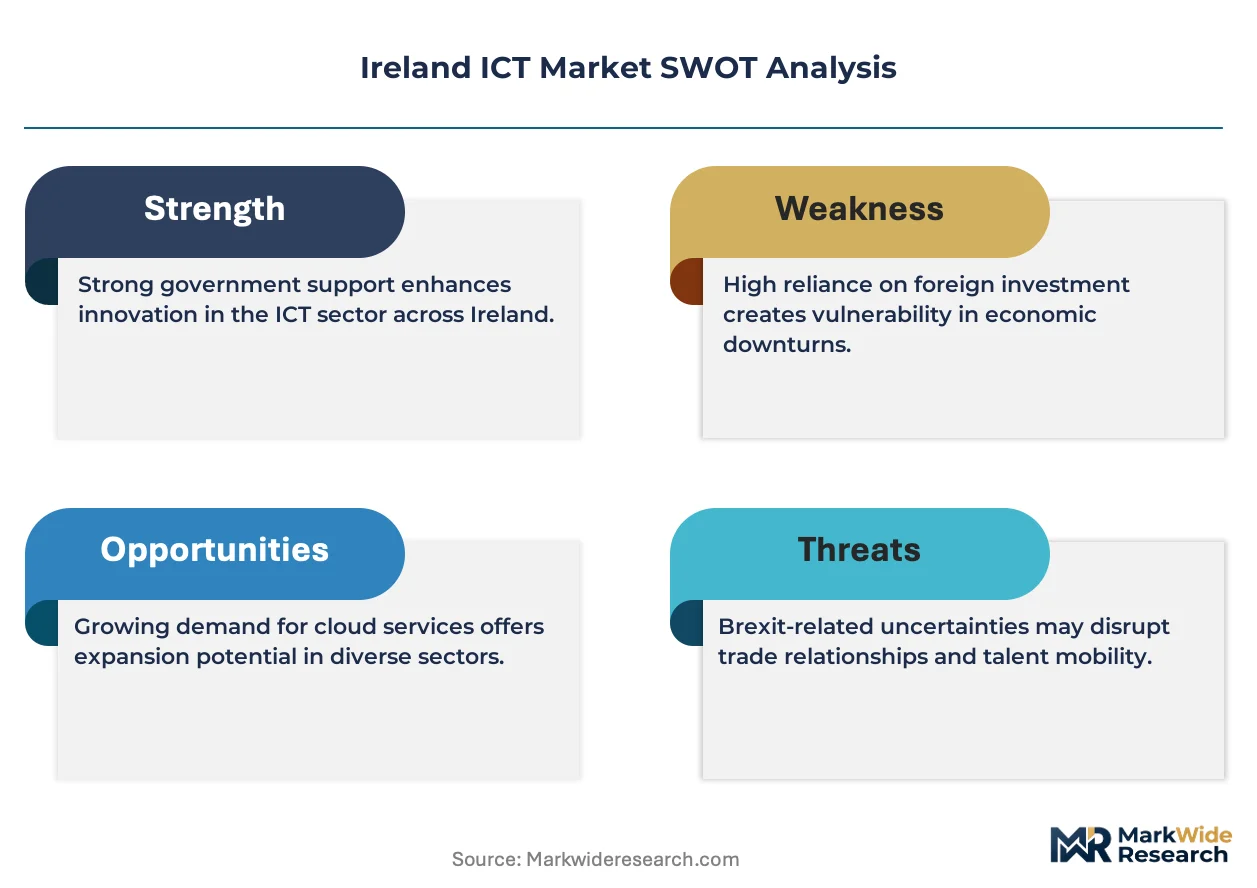
Information and communications technology encompasses electronic systems, software architectures, and network infrastructure that process, store, and transmit data across organizational boundaries. The field operates through layered technology stacks where semiconductor performance, protocol interoperability, and encryption standards determine functional capability. Cloud Solutions within the Solution Type dimension commands the dominant margin pool as Irish enterprises shift capital expenditure to operational models. Cybersecurity within the Technology dimension is expanding fastest as financial services and pharmaceutical multinationals harden digital perimeters against regulatory scrutiny. Software as a Service within the Service Model dimension has matured into the default delivery mechanism for enterprise applications.
Ireland's Data Protection Commission enforces GDPR obligations that shape how cloud providers architect data residency and cross-border transfer mechanisms. The Central Bank of Ireland's operational resilience requirements for financial services direct cybersecurity procurement toward certified vendors. The EU AI Act, transposed through Irish implementing legislation, will force algorithmic system audits across automated decision-making deployments. Stakeholders must monitor how rapidly the national regulatory framework tightens around frontier technologies without fragmenting from EU harmonization.
Market Dynamics
Enterprise cloud migration across Ireland's financial services corridor is compressing procurement cycles and forcing incumbent vendors to restructure licensing models around operational expenditure frameworks.
Growth Catalysts
- GDPR enforcement:The Data Protection Commission's stringent cross-border data transfer rulings are compelling enterprises to adopt sovereign cloud architectures with Irish data residency guarantees.
- Financial services operational resilience:The Central Bank of Ireland's mandatory cybersecurity certification requirements are accelerating procurement of managed security services among Dublin-headquartered banks and insurers.
- Edge computing deployment:Pharmaceutical manufacturing clusters in Cork and Galway are driving demand for low-latency processing infrastructure to support real-time quality control systems.
Market Restraints
- Hyperscale supply concentration:Dublin Region data center capacity is dominated by three global cloud operators, creating single-point-of-failure risk for enterprise workload continuity.
- Semiconductor input volatility:Enterprise hardware refresh cycles face disruption from concentrated advanced chip fabrication in East Asian foundries.
- EU AI Act compliance friction:Algorithmic audit requirements for automated decision-making systems are extending procurement timelines for AI-enabled enterprise software.
Strategic Opportunities
- Regional edge expansion:Secondary cities including Limerick and Waterford present underpenetrated demand for distributed cloud infrastructure serving indigenous software firms.
- Quantum-safe cryptography:Convergence of post-quantum encryption standards with financial sector procurement mandates creates white space for security technology vendors.
- Green data center incentives:Ireland's renewable energy grid integration policies offer regulatory tailwinds for carbon-neutral colocation services targeting ESG-mandated multinationals.
Industry Challenges
- Specialized cloud architecture skills:Enterprise migration projects face execution bottlenecks due to scarcity of certified Kubernetes and multi-cloud orchestration engineers.
- Legacy system integration complexity:Mainframe-dependent financial institutions encounter friction unbundling core banking platforms into API-native cloud architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ireland ICT Market |
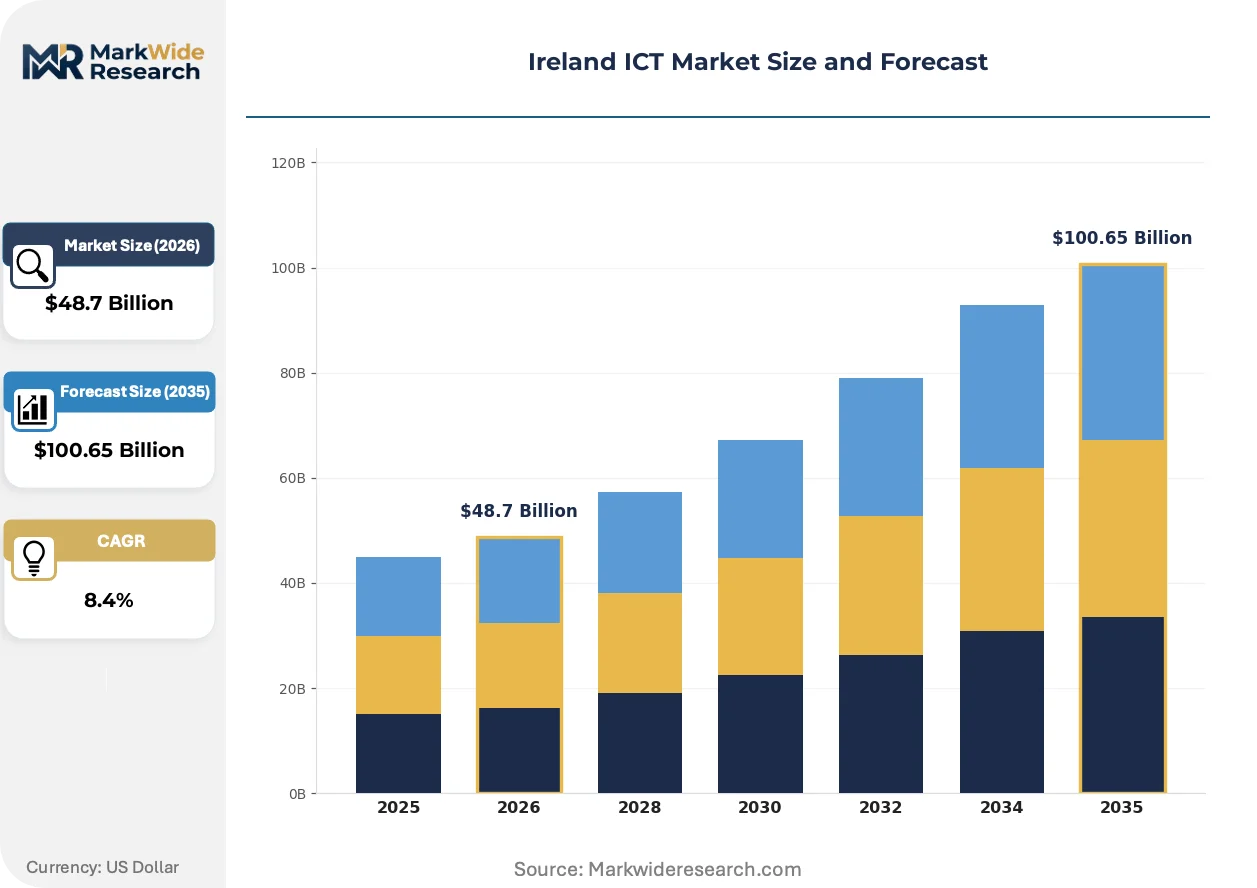
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $100.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Hardware, Software, Network Services, Cloud Solutions End User: Enterprises, SMEs, Government, Educational Institutions Service Model: Infrastructure as a Service, Platform as a Service, Software as a Service, Managed Services Technology: AI, IoT, Cybersecurity, Blockchain |
| Companies Covered | Microsoft Corporation, Alphabet Inc., Amazon Web Services Inc., Intel Corporation, Apple, IBM, Cisco Systems, Oracle Corporation, Hewlett Packard Enterprise, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ireland ICT Market Trends and Innovations
Technology deployment patterns across Irish enterprises are converging around sovereignty requirements, automated compliance tooling, and consumption-based commercial structures that displace perpetual licensing.
Confidential computing is hybridizing secure enclave architectures with public cloud infrastructure to enable sensitive data processing without vendor visibility. Pharmaceutical quality assurance teams at Cork manufacturing sites are piloting these capabilities for batch record analysis. The technology is hybridizing procurement criteria by forcing security evaluations to prioritize cryptographic attestation over network perimeter controls.
The EU AI Act's risk-classification framework is mandating conformity assessments for high-risk algorithmic systems before deployment. Irish medical device software vendors must now document training data provenance and bias mitigation protocols. Financial services automated underwriting platforms face the tightest compliance timelines, with implementation roadmaps accelerating through 2025.
Enterprise buyers are consolidating vendor relationships around integrated platform stacks rather than best-of-breed point solutions. Indigenous Irish software firms report lengthening sales cycles as procurement teams prioritize incumbent ecosystem extensions. This concentration is most visible among Dublin-based professional services firms standardizing on single-vendor productivity and infrastructure clouds.
Ireland ICT Market Segmentation
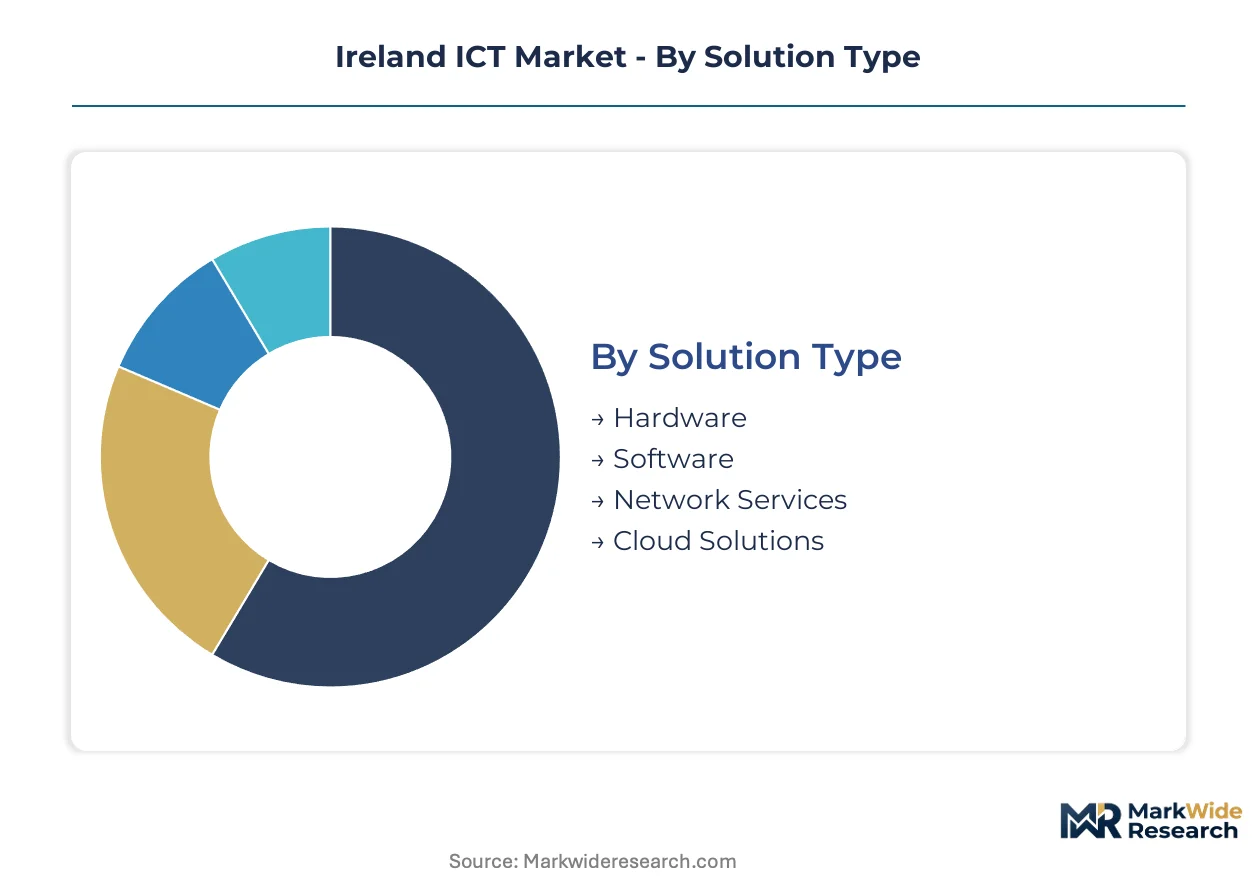
ICT procurement patterns across Ireland diverge sharply by organizational scale, regulatory exposure, and cloud maturity. Segmentation reveals how sovereign data requirements and operational resilience mandates reshape vendor selection criteria across Dublin's financial corridor and indigenous technology clusters.
Solution Type:
Cost tier differentiation separates capital-intensive infrastructure from operational expenditure models across Irish enterprise accounts.
- Cloud Solutions:Public and private cloud deployments enable workload portability with Irish data residency guarantees. Financial services firms in Dublin's IFSC are migrating core banking platforms to sovereign cloud architectures under Central Bank operational resilience directives.
- Software:Enterprise application licensing spans perpetual, subscription, and consumption-based commercial structures. Indigenous Irish SaaS vendors serving pharmaceutical supply chains in Cork report procurement teams prioritizing integrated platform stacks over point solutions.
- Hardware:Server, storage, and endpoint equipment procurement cycles face semiconductor supply volatility from concentrated East Asian fabrication.
- Network Services:Connectivity infrastructure including SD-WAN and 5G private networks supports edge computing deployments in Galway manufacturing zones.
Cloud Solutions holds installed capacity. Software is rotating up the share rankings.
End User:
Customer type determines compliance burden and procurement sophistication across Irish ICT demand pools.
- Enterprises:Multinational corporations and large domestic firms command dedicated procurement functions with certified vendor programs. Pharmaceutical headquarters in Dublin and Cork are driving quantum-safe cryptography pilots under EU cybersecurity certification frameworks.
- Government:Central and local government bodies operate under strict public spending codes and GDPR accountability requirements. The Office of the Government Chief Information Officer is consolidating cloud procurement frameworks around standardized security classifications.
- SMEs:Small and medium enterprises access ICT through managed service providers and bundled productivity subscriptions. Indigenous software clusters in Limerick and Waterford present underpenetrated demand for distributed infrastructure.
- Educational Institutions:Universities and technical colleges balance research computing needs against student-facing service delivery. Trinity College Dublin and University College Cork are expanding high-performance computing partnerships with regional data center operators.
Enterprises dominate current spend. Government is climbing the fastest as digital transformation accelerates across public services.
Service Model:
Delivery maturity stratifies across infrastructure abstraction layers from raw compute to fully managed applications.
- Software as a Service:Cloud-native application delivery has displaced on-premise deployment as the default enterprise mechanism. Dublin-based professional services firms are standardizing on single-vendor productivity clouds with embedded compliance tooling.
- Managed Services:Outsourced IT operations including security operations centers and infrastructure monitoring address skills scarcity. The Central Bank of Ireland's mandatory cybersecurity certification is accelerating procurement among insurers and asset managers.
- Infrastructure as a Service:Raw compute, storage, and networking resources provisioned on demand support variable workload patterns. Dublin Region hyperscale capacity concentration creates continuity planning challenges for enterprise architects.
- Platform as a Service:Developer-centric environments with pre-integrated middleware accelerate application lifecycle velocity. Indigenous Irish software firms report Kubernetes orchestration expertise gaps constraining platform adoption timelines.
Software as a Service commands current deployment preference. Managed Services is gaining share fastest under regulatory compliance pressure.
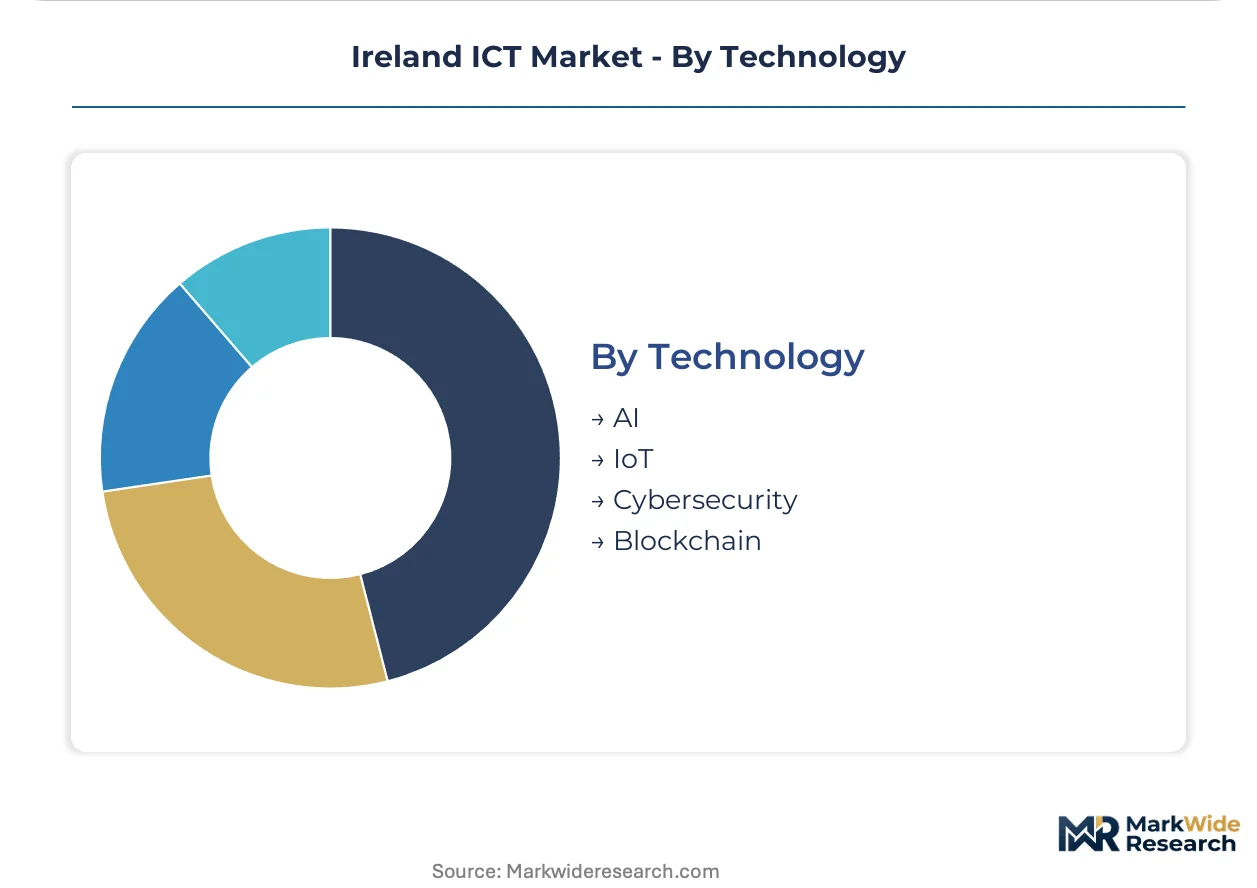
Technology:
Functional capability layers determine security posture and processing architecture across Irish ICT stacks.
- Cybersecurity:Threat detection, identity management, and encryption technologies harden digital perimeters against regulatory scrutiny. Financial services automated underwriting platforms face compressed implementation timelines under EU AI Act risk classification.
- AI:Machine learning and generative systems automate decision-making across customer service and risk assessment. Irish medical device software vendors must document training data provenance and bias mitigation protocols.
- IoT:Connected sensor networks enable real-time monitoring across pharmaceutical manufacturing and agricultural operations. Cork and Galway production facilities are piloting confidential computing for batch record analysis at the edge.
- Blockchain:Distributed ledger technologies support supply chain traceability and digital identity verification. Adoption remains concentrated in pilot programs within financial services consortiums.
Cybersecurity holds defensive spend priority. AI is expanding most quickly as algorithmic audit requirements reshape procurement specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Celtic Interconnector submarine cable linking Ireland to France anchors the island's digital infrastructure position, enabling low-latency connectivity to continental European markets while supporting Dublin's emergence as a hyperscale data center hub.
United States
Enterprise software procurement from US-headquartered vendors dominates Irish public sector frameworks. The SEC's cybersecurity disclosure rules for listed entities indirectly shape Irish subsidiary compliance obligations. Dublin-based financial services firms align operational resilience reporting with US regulatory expectations.
Germany
Industrial automation demand from German manufacturing multinationals drives IoT deployment across Irish operations. The KBA's automotive cybersecurity standards influence procurement specifications for connected vehicle platforms. Cork pharmaceutical facilities implement German-origin quality management systems for batch traceability.
United Kingdom
Post-Brexit data transfer arrangements position Ireland as a GDPR-equivalent jurisdiction for UK enterprise workload placement. The UK Information Commissioner's adequacy determinations shape cross-border cloud architecture decisions. Belfast-Dublin fiber corridors support financial services continuity planning.
France
ANSM medical device software requirements align with Irish regulatory convergence under EU MDR implementation. The CNIL's enforcement precedents on automated decision-making inform Irish Data Protection Commission guidance. Paris-Dublin research computing partnerships expand under European High-Performance Computing Joint Undertaking frameworks.
Netherlands
Amsterdam Internet Exchange peering relationships underpin Irish content delivery network performance. The Dutch Authority for Digital Infrastructure's cloud security certification frameworks influence Irish government procurement criteria. Rotterdam-Dublin maritime logistics digitalization drives supply chain software demand.
Ireland ICT Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream. The Ireland ICT market concentrates around hyperscale cloud operators with Dublin Region data center presence, while indigenous software vendors occupy niche vertical applications. Three archetypes dominate: productivity suite incumbents leveraging entrenched enterprise relationships, infrastructure-as-a-service providers anchoring sovereign cloud capacity, and cybersecurity specialists addressing financial sector compliance mandates. Competitive dynamics revolve around ecosystem lock-in through integrated platform stacks and strategic partnerships with indigenous system integrators.
Among US-headquartered technology conglomerates, Microsoft Corporation exemplifies the productivity platform archetype through its entrenched public sector presence. Amazon Web Services Inc. occupies the hyperscale infrastructure position with Dublin Region capacity concentration. Intel Corporation represents the semiconductor design specialist model extending hardware procurement influence. These entities anchor competitive positioning without exhausting the vendor landscape, as indigenous Irish firms and European specialists occupy adjacent service tiers.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Alphabet Inc. |
| Amazon Web Services Inc. |
| Intel Corporation |
| Apple |
| IBM |
| Cisco Systems |
| Oracle Corporation |
| Hewlett Packard Enterprise |
| Others |
Pricing and Supply Chain Analysis
Hyperscale data center concentration in Dublin Region creates single-source dependency that compresses pricing spreads between sovereign cloud tiers and standard infrastructure while forcing enterprise buyers toward multi-vendor distribution strategies. This supply chokepoint simultaneously elevates premium-tier pricing for guaranteed Irish data residency and erodes mid-market margins through capacity-constrained spot procurement.
Pricing Analysis
Volume-discount tiering structures dominate enterprise SaaS and infrastructure-as-a-service contracts, with hyperscalers offering committed-use discounts that separate multinational anchor tenants from indigenous software firms purchasing on-demand capacity. Price differentiation hinges on data residency certification level and cross-border transfer guarantee scope, with Central Bank operational resilience mandates driving premium tier absorption among Dublin financial services firms. Cost compression in mid-market cloud subscriptions intensifies as AWS, Microsoft, and Google compete for indigenous technology company workloads. SMEs exhibit highest price sensitivity, while pharmaceutical multinationals prioritize compliance-grade sovereign capacity over unit economics.
Supply Chain Analysis
Upstream semiconductor feedstock flows from Taiwan, South Korea, and the United States anchor enterprise hardware refresh cycles for Irish data center operators and financial services infrastructure teams. Advanced logic chips, high-bandwidth memory modules, and specialized networking silicon constitute critical input dependencies. Single-source vulnerability concentrates in East Asian foundry capacity, with geopolitical friction threatening server and storage equipment lead times. Distribution runs through Dublin-based systems integrators and direct hyperscale procurement channels serving enterprise accounts, with secondary city demand in Cork and Galway accessing infrastructure through managed service provider intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion characterizes Ireland's ICT market as EU AI Act compliance deadlines and sovereign cloud mandates accelerate procurement velocity across financial services and pharmaceutical verticals.
For Market Incumbents: Build switching-cost moats through deep integration of compliance tooling into productivity platform stacks, embedding GDPR audit automation and AI Act conformity assessment workflows that raise replacement costs for Dublin-headquartered banks. Anchor defensive positioning with exclusive data center partnerships in secondary cities, preempting challenger access to Limerick and Waterford edge computing demand. Threat from indigenous SaaS vendors with vertical-specific AI compliance modules demands preemptive certification investment in EU cybersecurity frameworks. For New Entrants and Emerging Players: Build out quantum-safe cryptography capabilities targeting financial services procurement timelines compressed by post-quantum encryption mandates from the Central Bank of Ireland. White space concentrates in managed security services for mid-market pharmaceutical firms lacking in-house algorithmic audit expertise. Go-to-market traction requires channel partnerships with indigenous system integrators holding existing Central Bank certification relationships. For Investors and Strategic Acquirers: The market sits at a regulatory-driven upgrade phase that favors compliance-embedded infrastructure specialists over generic cloud resellers. Long-term viability across the next decade hinges on sustained enforcement of EU AI Act risk classifications and GDPR cross-border transfer restrictions. Acquisition target archetypes include indigenous cybersecurity firms with Central Bank certification and edge computing operators with renewable energy grid integration. Signal to watch is Data Protection Commission enforcement velocity on automated decision-making systems.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Certification | Central Bank operational resilience mandates require Irish data residency guarantees for core banking platforms. |
| AI Act Compliance Integration | Medical device software vendors must embed training data provenance documentation into development pipelines. |
| Edge Infrastructure Expansion | Pharmaceutical manufacturing clusters in Cork and Galway drive low-latency quality control system demand. |
| Quantum-Safe Cryptography Deployment | Post-quantum encryption standards converge with financial sector procurement mandates for automated underwriting platforms. |
| Green Data Center Positioning | Ireland's renewable energy grid integration policies create regulatory tailwinds for carbon-neutral colocation services. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC hyperscaler filings, Central Bank of Ireland operational resilience guidance, and EU AI Act implementing legislation. Interviews with chief technology officers, IT procurement officers at Dublin financial services firms, platform engineers at indigenous software vendors, and channel partners supplying government frameworks informed demand-side validation. Secondary sources include Data Protection Commission enforcement decisions, hyperscaler capex disclosures, and pharmaceutical manufacturing facility announcements. Bottom-up segment sizing triangulates against top-down macroeconomic anchors for the Irish technology sector.
Forecast inputs incorporate deployment model transitions, organization size-based procurement sophistication, vertical regulatory exposure, integration complexity tiers, and regional adoption patterns across Dublin, Cork, Galway, and secondary cities. Segmentation dimensions span solution type, end user category, service model maturity, and technology functional layer. CAGRs derive from elasticity modeling against enterprise cloud migration velocity and compliance-driven replacement cycles. Industry-specific inputs include Central Bank certification timelines and EU AI Act risk-classification implementation roadmaps.
Stress conditions across semiconductor supply volatility, Data Protection Commission enforcement intensity, and hyperscale capacity concentration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory harmonization and enterprise cloud migration continuity. Cross-checking against Central Bank operational resilience audit frequency and EU AI Act delegated act publication schedules is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Next Generation Technologies
Next Generation Wireless Network Market
Next Generation Technologies
Bulgaria ICT Market
Next Generation Technologies
Poc Platform and Technology Market
Next Generation Technologies
Next Generation Network (NGN) Equipment Market
Next Generation Technologies
Information and Communications Technology (ICT) Market
Next Generation Technologies
Smart Surfaces Market
Next Generation Technologies
Quantum Information Processing Market
Next Generation Technologies
Global Next Generation Wireless Communication Market
Next Generation Technologies
Nearfield Communication (NFC) Market
Next Generation Technologies
Jordan ICT Market
Next Generation Technologies
Next-Generation Communication Devices Market
Next Generation Technologies
Oman ICT Market
Next Generation Technologies
Japan ICT Market
Next Generation Technologies
Fog Computing Market
Next Generation Technologies
Enterprise Quantum Computing Market
Next Generation Technologies
Quantum Computing Market