
 Optical Coatings Design Software Market | 2026-2036
Optical Coatings Design Software Market Size, Share, and Industry Trends Forecast 2026-2036
Optical Coatings Design Software Market Analysis
Cloud-native thin-film simulation architectures is rewriting how optical engineers iterate coating stacks across distributed teams. Ansys leverages its multiphysics platform to anchor high-end aerospace and defense accounts. RP Photonics specializes in fiber laser and nonlinear optics extensions that differentiate its solver modules. Thin Film Center sustains its educational and consultancy channel dominance through embedded software licensing.
Optical coatings design software comprises computational platforms that model electromagnetic wave propagation through layered dielectric and metallic thin films, typically resolving layer thicknesses to sub-nanometer precision while optimizing for target spectral transmittance or reflectance curves. These tools serve the industrial purpose of eliminating costly physical prototyping iterations in precision optics manufacturing. Anti-reflective coatings and filter coatings command the deepest margin pools due to their complexity and sensitivity in military and medical imaging applications. Mirror coatings for high-power laser systems represent the fastest-growing application segment as ultrafast laser deployment expands.
ISO 10110 surface specification standards and the EU F-Gas Regulation shape product roadmaps by mandating low-environmental-impact deposition process modeling. The US FDA and EMA both influence medical imaging lens qualification protocols that ripple backward into design software validation requirements. Stakeholders must monitor how REACH chemical restrictions and emerging dual-use export controls reshape permissible material libraries in coating databases.
Market Dynamics
Cloud-native thin-film simulation architectures are compressing iteration cycles across distributed engineering teams, forcing incumbent vendors to rearchitect legacy desktop applications or cede aerospace and defense accounts to multiphysics platforms.
Growth Catalysts
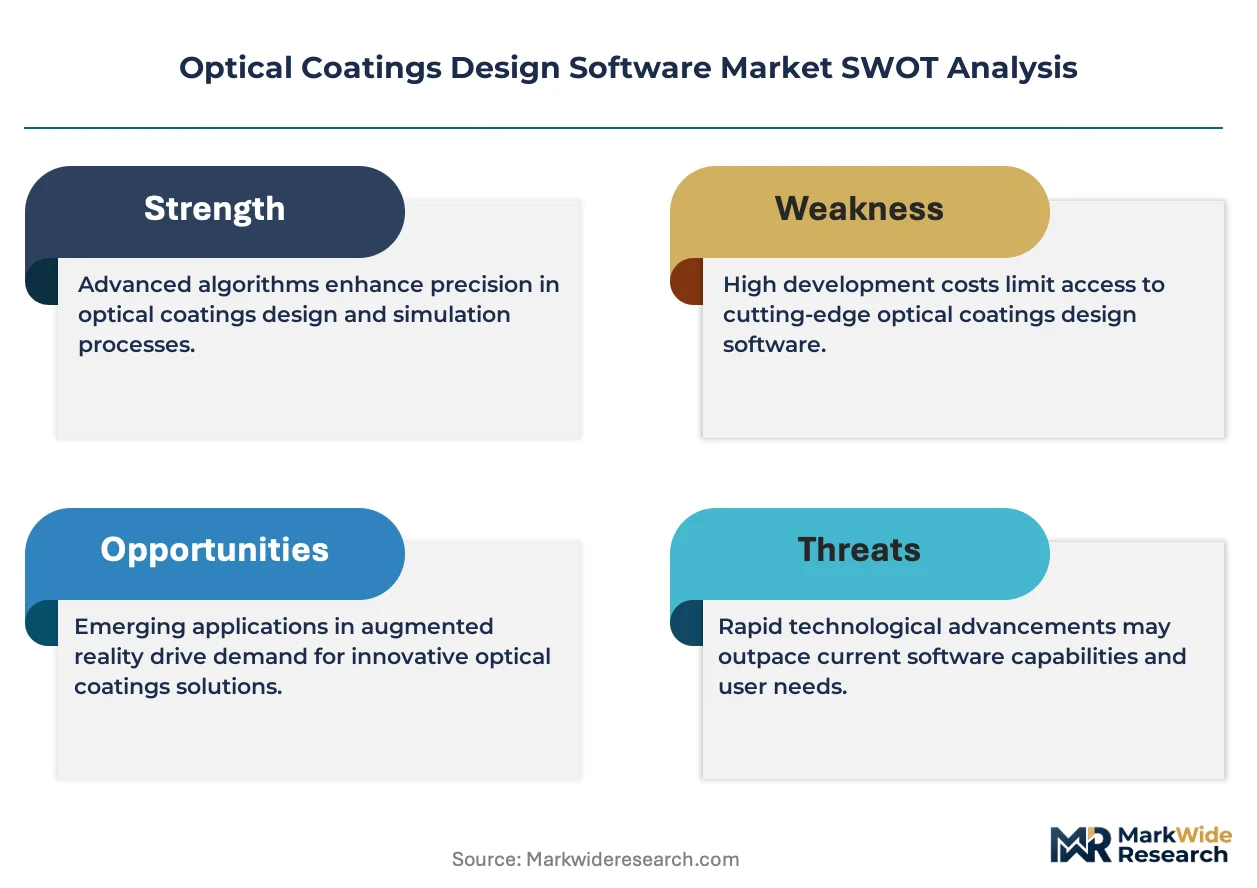
- EU F-Gas Regulation:REACH compliance mandates for low-global-warming-potential deposition processes are accelerating demand for environmentally optimized coating stack designs in precision optics manufacturing.
- Ultrafast laser deployment:Medical device and semiconductor equipment manufacturers are expanding mirror coating specifications for high-power laser systems, pulling advanced electromagnetic solver adoption.
- Germany's precision optics cluster:Concentrated R&D activity around Jena and Munich is generating sustained software licensing demand from Zeiss, Leica, and their supply chain partners.
Market Restraints
- Specialized talent scarcity:Electromagnetic wave propagation modeling expertise concentrates within a narrow pool of physicists and optical engineers, constraining vendor scaling.
- High-fidelity compute costs:Sub-nanometer precision simulations require GPU-intensive infrastructure that mid-tier manufacturers struggle to provision internally.
- Legacy system entrenchment:Proprietary thin-film databases built over decades in major aerospace primes create switching friction against modern cloud-native platforms.
Strategic Opportunities
- India's PLI scheme:Production-linked incentives for semiconductor and solar manufacturing are creating first-mover advantage for coating design software vendors establishing local training partnerships.
- AR/VR waveguide coatings:Emerging demand for diffractive optical element stacks in consumer electronics represents unpenetrated application white space.
- ISO 10110-7 revision:Updated surface imperfection tolerances are forcing metrology-software integration that opens embedded licensing channels.
Industry Challenges
- Multiphysics integration complexity:Thermal-mechanical-optical coupling requirements in high-power laser systems strain solver convergence stability.
- Dual-use export control navigation:Coating databases containing military-applicable refractive index data face licensing restrictions under evolving US and EU trade regulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Optical Coatings Design Software Market |
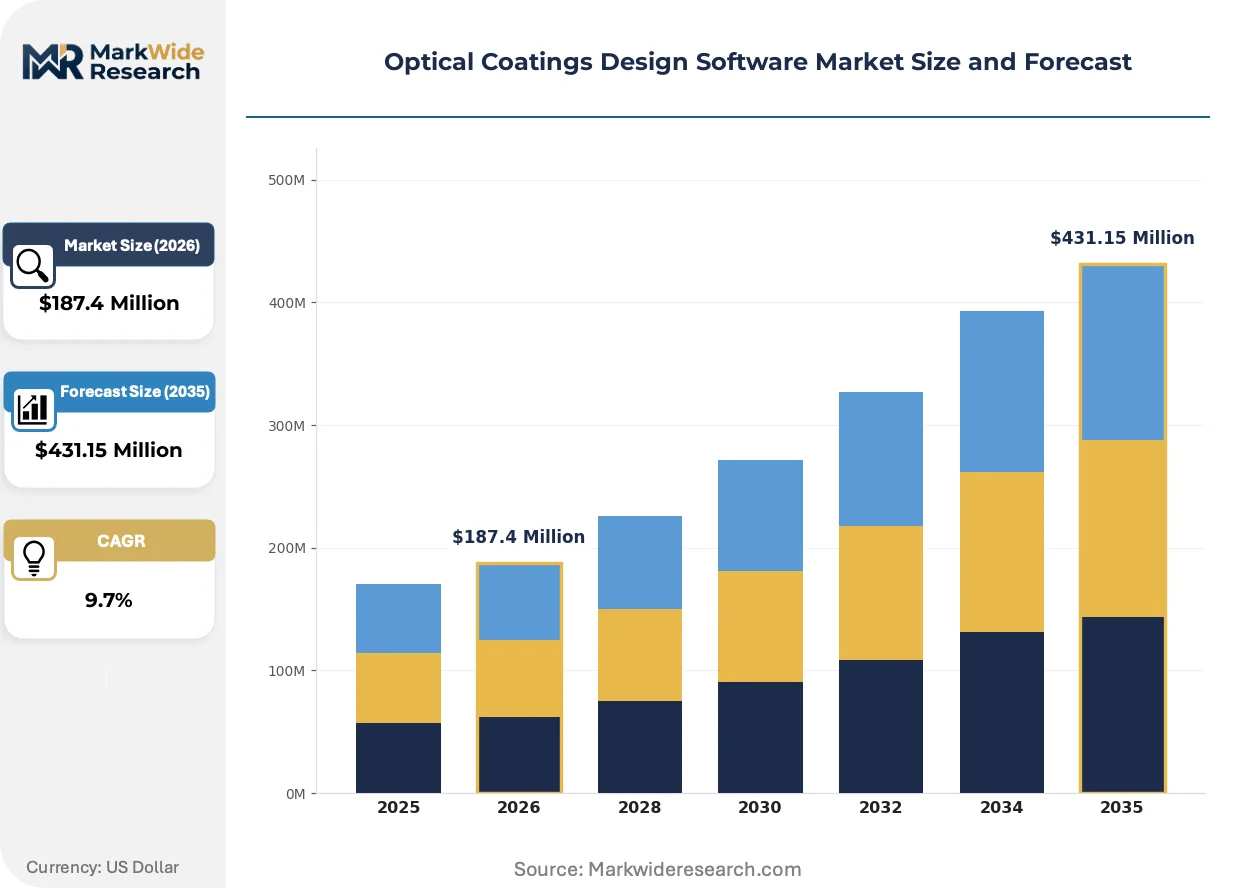
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $431.15 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thin Film, Anti-Reflective Coatings, Mirror Coatings, Filter Coatings End User: Optical Manufacturers, Research Institutions, Aerospace, Consumer Electronics Technology: Physical Vapor Deposition, Chemical Vapor Deposition, Sputtering, Reactive Sputtering Application: Lens Manufacturing, Display Technology, Solar Cells, Medical Imaging |
| Companies Covered | Ansys, FTG Software, Scientific Computing International, LightMachinery, RP Photonics, Thin Film Center, OptiLayer, Optenso, Synopsys, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Optical Coatings Design Software Market Emerging Trajectories
Computational methods are migrating from standalone thin-film optimizers toward integrated multiphysics environments, compressing the boundary between optical design and manufacturing process simulation.
GPU-accelerated rigorous coupled-wave analysis is virtualizing how photonics engineers model subwavelength grating structures and metamaterial coatings. Aerospace primes in Germany and the US are deploying these solvers for freeform mirror segments requiring polarization-sensitive performance across extreme temperature ranges. The technology is virtualizing physical prototyping budgets that previously consumed 40-60% of coating development cycles.
REACH chemical restrictions and the EU F-Gas Regulation are forcing deposition process modeling into design software roadmaps. Vendors must now integrate sputtering rate predictions and environmental impact scoring alongside traditional spectral optimization. Medical imaging lens manufacturers face the tightest compliance timelines as EMA qualification protocols ripple backward into software validation requirements.
Subscription pricing for cloud-native simulation seats is displacing perpetual licenses among mid-tier precision optics houses. German SMEs around Munich are consolidating vendor relationships toward platforms offering collaborative stack versioning and automated tolerance analysis. This procurement consolidation concentrates purchasing power with integrators capable of bundling design, deposition monitoring, and metrology workflows.
Optical Coatings Design Software Market Segmentation
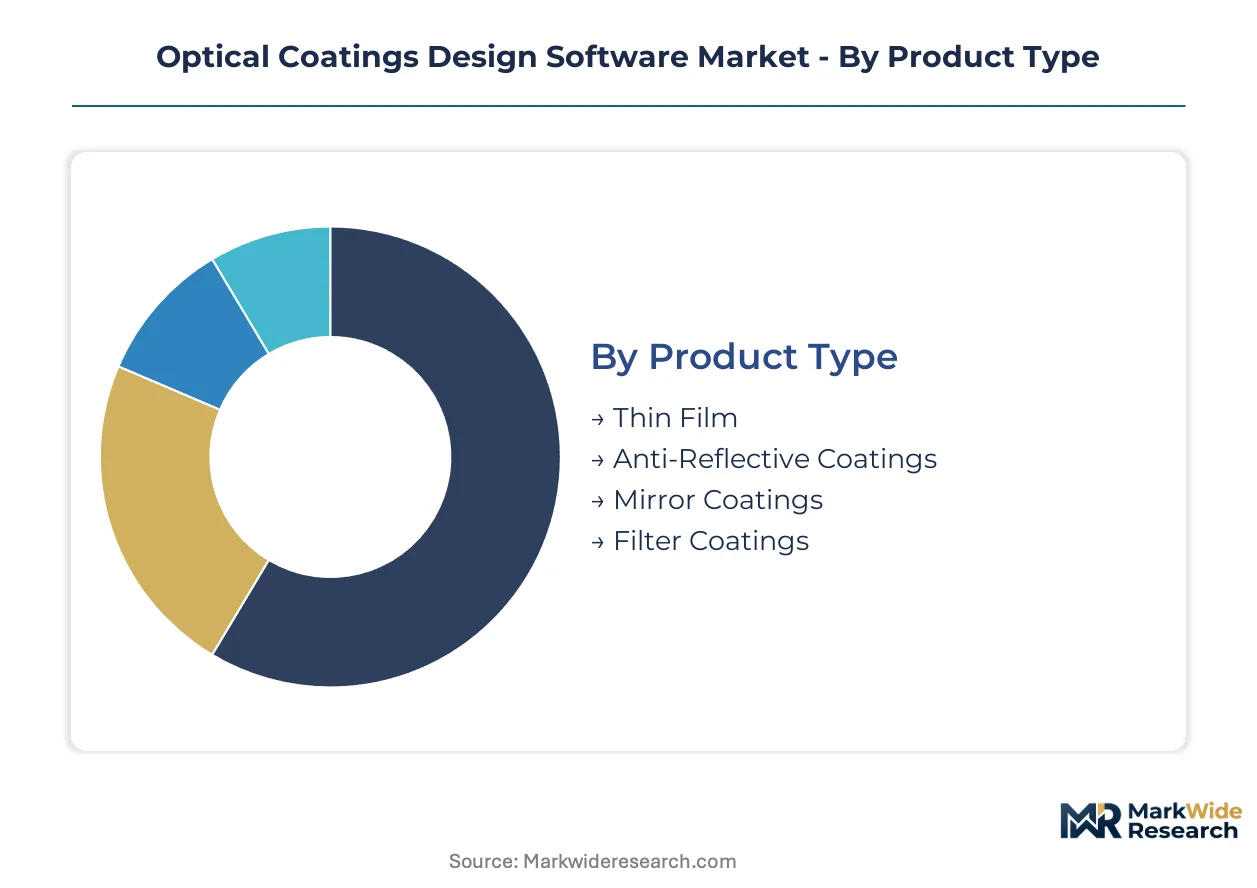
Segmentation in optical coatings design software reveals how solver capabilities align with deposition physics and end-use validation requirements. Each dimension exposes distinct procurement patterns and integration complexity that vendors must address through specialized module architectures.
Product Type:
After-sales service intensity varies sharply across coating categories, with high-power mirror systems demanding continuous solver calibration support while standardized anti-reflective stacks require minimal vendor intervention.
- Mirror Coatings:Thermal-mechanical-optical coupling solvers dominate this category for high-power laser systems. Aerospace primes in Germany deploy these tools for freeform mirror segments requiring polarization stability across temperature extremes. Ultrafast laser manufacturers pull advanced electromagnetic solver adoption fastest here.
- Anti-Reflective Coatings:These stacks optimize spectral transmittance through sub-nanometer layer precision. Medical imaging lens manufacturers in Jena concentrate procurement for FDA and EMA qualification protocols. REACH chemical restrictions force deposition process modeling integration.
- Thin Film:Foundational electromagnetic wave propagation modeling serves prototyping elimination across precision optics.
- Filter Coatings:Narrowband and edge filter designs support military and medical imaging with stringent spectral discrimination requirements.
Anti-reflective coatings hold the largest share; momentum sits with mirror coatings.
End User:
Cost tier stratification separates enterprise multiphysics platform subscriptions from mid-tier perpetual licenses, with research institutions occupying a distinct procurement bracket between commercial and academic pricing.
- Aerospace:Defense primes require GPU-intensive rigorous coupled-wave analysis for polarization-sensitive performance validation. The US and Germany dominate licensing volume through sustained R&D budgets. Dual-use export controls constrain refractive index database distribution.
- Optical Manufacturers:German SMEs around Munich consolidate toward cloud-native platforms with collaborative stack versioning. Subscription pricing displaces perpetual licenses fastest in this tier. Automated tolerance analysis drives vendor selection.
- Research Institutions:Academic licensing sustains educational channel dominance through embedded software partnerships.
- Consumer Electronics:AR/VR waveguide coating demand for diffractive optical elements represents unpenetrated application white space.
Optical manufacturers command current volume; aerospace shows the steepest expansion trajectory.
Technology:
Application concentration determines solver specialization, with physical vapor deposition commanding the deepest physics integration while reactive variants demand kinetic modeling extensions.
- Physical Vapor Deposition:Evaporation and ion-assisted deposition simulation anchors legacy aerospace prime workflows. Proprietary thin-film databases built over decades create switching friction against modern platforms. Germany's precision optics cluster sustains dominant licensing demand.
- Sputtering:Rate prediction algorithms integrate with environmental impact scoring under EU F-Gas Regulation compliance. Mid-tier manufacturers struggle with GPU-intensive infrastructure provisioning for high-fidelity simulations.
- Chemical Vapor Deposition:Gas-phase reaction kinetics modeling supports semiconductor equipment coating specifications.
- Reactive Sputtering:Plasma chemistry coupling extends solver modules for compound thin-film stoichiometry control.
Physical vapor deposition retains the largest installed base; sputtering gains share fastest.
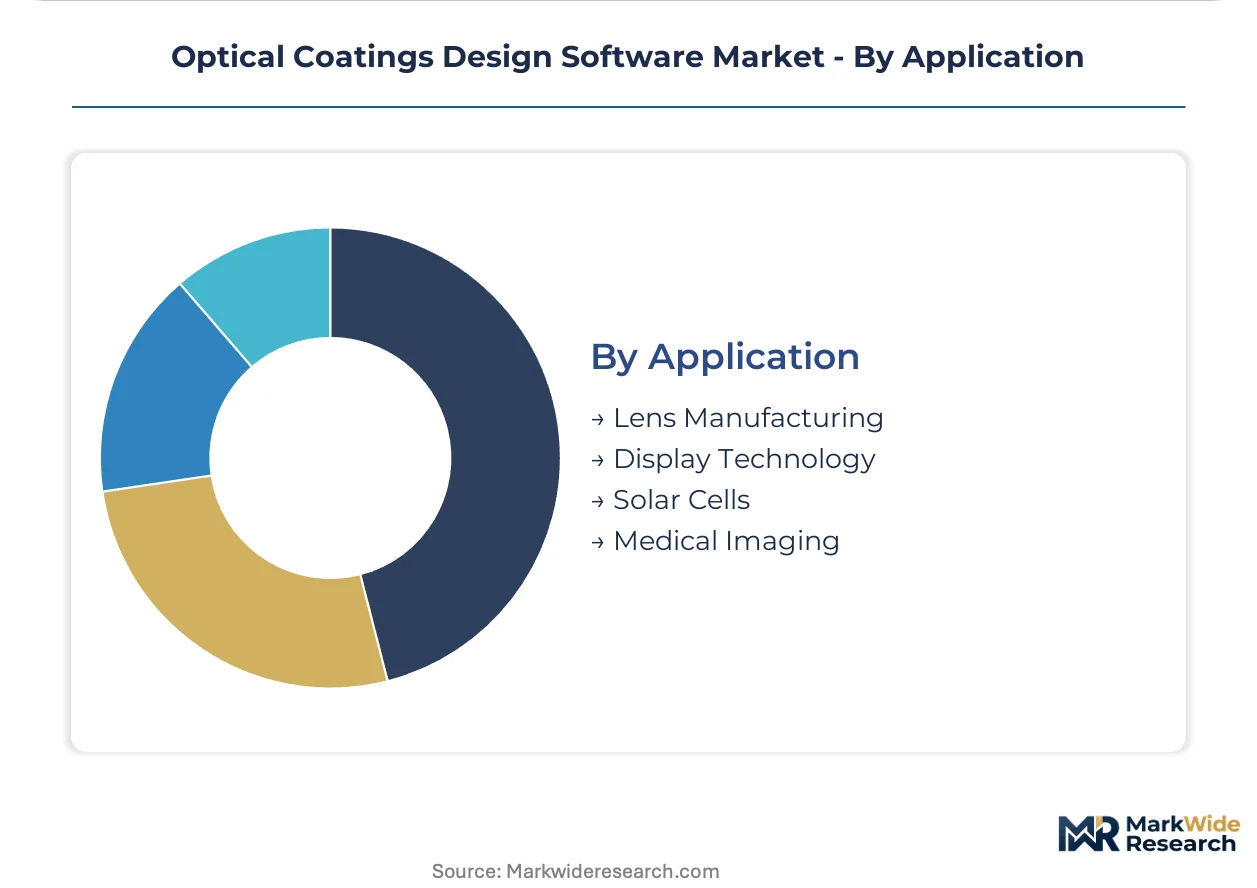
Application:
Customer type segmentation separates qualification-intensive medical imaging from volume-driven display technology, with solar cells occupying an emerging procurement tier shaped by India's PLI scheme incentives.
- Medical Imaging:ISO 10110-7 surface imperfection tolerances force metrology-software integration. EMA qualification protocols ripple backward into design software validation requirements. Tightest REACH compliance timelines concentrate here.
- Solar Cells:India's production-linked incentives for semiconductor and solar manufacturing create first-mover advantage for vendors establishing local training partnerships. Anti-reflective coating optimization drives solver adoption.
- Lens Manufacturing:Sub-nanometer precision requirements span consumer through military-grade specifications.
- Display Technology:Large-area coating uniformity modeling supports OLED and quantum dot manufacturing scale-up.
Medical imaging holds the largest share; solar cells climb the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Net software licensing flows concentrate in precision optics manufacturing clusters where aerospace primes and medical device exporters anchor demand. Germany and the United States generate sustained outbound technology transfer through embedded design software bundled with coating equipment. India's emerging solar and semiconductor fabrication base is shifting toward import substitution for simulation tools.
Germany
Jena and Munich host Europe's densest precision optics ecosystem, with Zeiss and Leica supply chains driving perpetual license renewals. The EU F-Gas Regulation and REACH compliance mandates accelerate environmentally optimized coating stack procurement. Bavaria's SME fabricators consolidate vendor relationships toward cloud-native platforms with collaborative versioning.
United States
Aerospace and defense primes in California and Massachusetts deploy GPU-intensive rigorous coupled-wave analysis for polarization-sensitive mirror validation. FDA qualification protocols for medical imaging lenses ripple backward into design software validation requirements. Dual-use export controls constrain refractive index database distribution to allied defense programs.
Japan
Osaka and Nagoya manufacturing corridors sustain demand for ion-assisted deposition simulation tied to semiconductor equipment exports. METI industrial standards shape solver calibration requirements for high-power laser coating specifications. Domestic vendors face pricing pressure from German and US multiphysics platform entrants.
India
Telangana and Karnataka semiconductor fabrication zones leverage PLI scheme incentives to attract coating design software training partnerships. Solar cell anti-reflective optimization drives first-mover solver adoption among domestic PV manufacturers. CDSCO medical device regulations are beginning to influence lens qualification protocol imports.
China
Yangtze River Delta optoelectronics clusters consume sputtering rate prediction algorithms under MIIT industrial upgrading directives. Domestic software alternatives gain share in military-applicable coating segments restricted by US export controls. NMPA medical imaging standards create compliance translation challenges for Western validation frameworks.
Optical Coatings Design Software Market Vendor Landscape
On the supply side, the industry is bifurcated between multiphysics platform incumbents and specialized thin-film solver boutiques. Tiered procurement patterns separate enterprise aerospace accounts from mid-tier optical manufacturer subscriptions. Two strategic archetypes dominate: physics-engineering hybrids bundling deposition monitoring integration, and educational-channel specialists monetizing embedded academic licensing. Competitive moves concentrate on cloud-native rearchitecture and automated tolerance analysis module deployment.
Among multiphysics platform providers, Ansys anchors the high-end aerospace and defense segment through its integrated electromagnetic-thermal-mechanical solver environment. RP Photonics exemplifies the specialized boutique archetype, occupying a position within fiber laser and nonlinear optics extension modules that differentiate its electromagnetic solver offerings. Thin Film Center represents the educational-channel specialist model, sustaining market presence through consultancy-embedded software licensing rather than direct enterprise sales.
| Leading Market Players |
|---|
| Ansys |
| FTG Software |
| Scientific Computing International |
| LightMachinery |
| RP Photonics |
| Thin Film Center |
| OptiLayer |
| Optenso |
| Synopsys |
| Others |
Supply Flow & Price Mechanics
Jena and Munich anchor Europe's precision optics software supply, with Bavarian SME fabricators consolidating procurement toward integrated platforms that bundle electromagnetic solvers with deposition monitoring. This geographic concentration grants incumbent vendors pricing leverage over mid-tier optical manufacturers seeking collaborative stack versioning and automated tolerance analysis modules.
Pricing Analysis
Legacy desktop perpetual licenses command premium positioning against cloud-native subscription tiers, with GPU-accelerated rigorous coupled-wave analysis modules carrying the steepest price premiums. Three-tier pricing structure across premium, standard, and economy levels separates aerospace defense primes from mid-tier optical manufacturers and academic research institutions. Cost compression in the standard tier is intensifying because German SMEs are consolidating vendor relationships and demanding bundled metrology integration. Academic licensing through embedded consultancy partnerships shows the highest price sensitivity, while aerospace primes exhibit inelastic demand for polarization-sensitive solver validation.
Supply Chain Analysis
Contract manufacturing concentration for deposition equipment simulation modules rests with specialized electromagnetic solver boutiques in Germany, the United States, and Japan. Raw material dependencies include GPU compute infrastructure from NVIDIA and AMD, refractive index database subscriptions, and sputtering rate prediction algorithm licenses. Single-source vulnerability concentrates in proprietary thin-film databases built over decades in aerospace primes, creating switching friction against modern platforms. Distribution runs through direct enterprise sales for defense accounts and educational-channel partnerships for academic licensing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Optical coatings design software functions as a service-attach business where continuous solver calibration support and automated tolerance analysis modules expand recurring revenue faster than perpetual license hardware sales.
For Market Incumbents: Build switching-cost moats through proprietary thin-film database lock-in and deposition monitoring integration that raises replacement costs for aerospace primes. Deepen backward integration into sputtering rate prediction algorithms to capture EU F-Gas Regulation compliance budgets. Counter cloud-native multiphysics platforms by embedding collaborative stack versioning into legacy workflows. For New Entrants and Emerging Players: Build out AR/VR waveguide coating simulation for diffractive optical element stacks in consumer electronics, the most penetrable white space with unmet demand. Target India's PLI scheme semiconductor fabrication zones through local training partnerships that establish first-mover solver adoption. Pursue academic licensing channels through embedded consultancy relationships rather than direct enterprise competition. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among specialized boutiques with fiber laser and nonlinear optics extension modules that differentiate electromagnetic solver offerings. Five-to-ten year viability favors vendors integrating REACH compliance scoring and environmental impact modeling alongside spectral optimization. Watch for inflection in GPU-accelerated rigorous coupled-wave analysis adoption among ultrafast laser manufacturers as the signal for solver specialization premium expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Migration | Compresses iteration cycles for distributed engineering teams across German precision optics clusters. |
| Deposition Process Modeling Integration | Captures EU F-Gas Regulation compliance budgets with sputtering rate prediction algorithms. |
| Academic Licensing Channel Expansion | Sustains embedded software presence through consultancy partnerships with Jena and Munich research institutions. |
| GPU-Accelerated Solver Development | Virtualizes physical prototyping budgets that previously consumed coating development cycles. |
| Metrology-Software Integration | Opens embedded licensing channels under ISO 10110-7 revised surface imperfection tolerances. |
Methodological Framework
Initial hypotheses were tested against primary input from optical design engineers, deposition equipment procurement managers, aerospace prime R&D directors, and academic research institution licensing officers, then refined through secondary validation. Primary fieldwork combined structured interviews with CTOs at precision optics manufacturers and regulatory affairs leads at medical imaging lens producers. Secondary sources included SEC filings from multiphysics platform providers, EMA qualification protocol documentation, EU F-Gas Regulation compliance databases, and ISO 10110 standard revision records. Bottom-up segment sizing triangulated against top-down aerospace and defense R&D expenditure estimates.
Demand-supply-balance framing anchored the analytical framework across the analysis window, modeling solver adoption by coating type, deposition technology, end-use vertical, and geographic precision optics cluster. Segmentation dimensions included mirror versus anti-reflective versus filter coating applications, physical vapor deposition versus sputtering versus chemical vapor deposition technologies, and aerospace versus optical manufacturer versus research institution end users. CAGRs derived from installed base renewal rates and new seat expansion trajectories. Industry-specific inputs incorporated ultrafast laser deployment pipelines and India's PLI scheme incentive disbursement schedules.
The forecast holds incumbent behavior within observed patterns; aggressive moves by cloud-native multiphysics platform entrants or domestic Chinese software alternatives would shift outcomes. Specific risk factors include REACH chemical restriction expansions narrowing permissible material libraries and dual-use export control tightening constraining refractive index database distribution. Quarterly review of GPU-accelerated solver adoption rates and PLI scheme training partnership announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Sweepstakes Software Market
Software & Services
G Suite Technology Services Market
Software & Services
Global Time Series Analysis Software Market
Software & Services
Discount Management Software Market
Software & Services
Staffing Agency Software Market
Software & Services
Emotion Recognition and Sentiment Analysis Software Market
Software & Services
Ground Handling Software Market
Software & Services
Global Pre-Employment Testing Software Market
Software & Services
Global Recreation Management Software Market
Software & Services
Global Online Proofing Software Market
Software & Services
Resonator Design Software Market
Software & Services
Global Decision Making Software Market
Software & Services
Global Managed Application Services Market
Software & Services
Freight Management Software Market
Software & Services
Data Compression Software Market
Software & Services
Global Self-Service BI Market