
 Japan ICT Market | 2026-2036
Japan ICT Market Size, Share, and Industry Trends Forecast 2026-2036
Japan ICT Market Intelligence
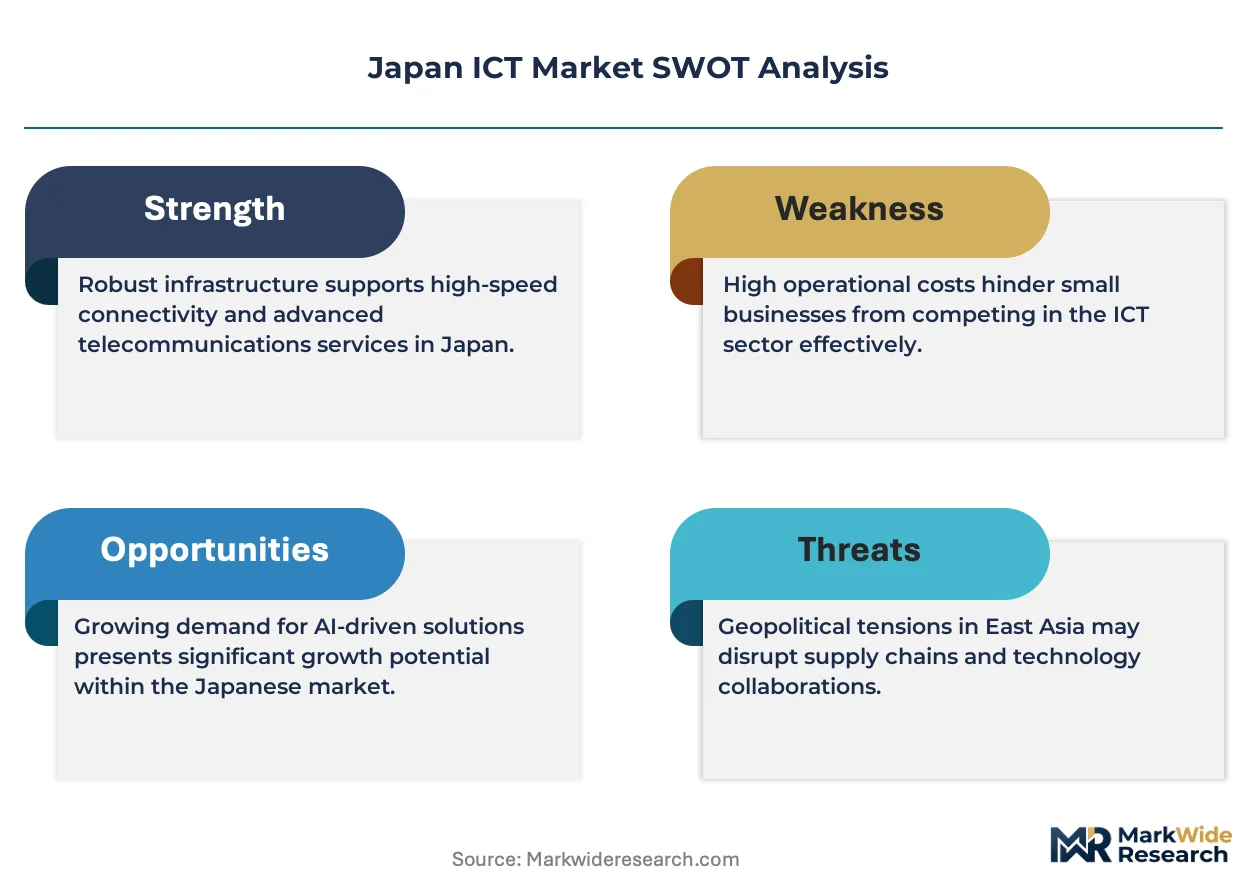
Modular service bundling is decoupling legacy system overhauls from full-stack vendor lock-in across Japanese enterprises. Fujitsu Limited leverages its mainframe heritage to anchor hybrid cloud transitions for conservative financial institutions. NEC Corporation competes through deep integration of AI and biometric authentication in government digital identity programs. SoftBank extends capital-scale investment into domestic data center expansion and 5G standalone infrastructure.
Japan ICT encompasses information and communication technology infrastructure, software systems, and digital services operating across computing, networking, and data management layers, typically governed by latency thresholds below 10 milliseconds for real-time industrial control and encryption protocols meeting FISC standards. Its primary purpose is enabling enterprise digitization, consumer connectivity, and public service delivery through interoperable platforms. Services and cloud solutions command the dominant margin pool as enterprises shift from capital-intensive hardware refresh cycles to operational expenditure models. AI and IoT within the technology dimension represent the fastest-expanding demand vector, driven by predictive maintenance in automotive and precision electronics manufacturing. Hardware retains structural importance in semiconductor fabrication equipment and specialized edge computing nodes supporting factory-floor deployments.
METI's data governance frameworks and the PMDA's digital health validation pathways shape product standards for cross-border data handling and healthcare AI market access. JIS standards and the country's national cybersecurity regulator enforce baseline encryption and supply chain integrity requirements for critical infrastructure procurement. Stakeholders must weigh domestic content thresholds against the cost advantages of offshore cloud regions when architecting multi-year platform commitments.
Market Dynamics
Japanese enterprises face mounting pressure from METI's Society 5.0 mandates to replace legacy mainframe architectures with hybrid cloud infrastructure while maintaining sub-10 millisecond latency for factory-floor control systems. This structural force is compressing procurement cycles and forcing vendor consolidation across financial services and precision manufacturing.
Growth Catalysts
- Society 5.0 Framework:METI's policy roadmap mandates AI-driven automation across healthcare, mobility, and fintech, creating procurement pull for IoT-enabled industrial platforms and predictive maintenance systems in automotive supply chains.
- Financial Services:Conservative banking institutions are accelerating hybrid cloud transitions to meet FISC encryption standards while reducing mainframe operational expenditure through modular service bundling.
- Edge Computing:Factory-floor deployments of specialized computing nodes supporting real-time quality control in precision electronics manufacturing are expanding demand for low-latency infrastructure.
Market Restraints
- Domestic Semiconductor Equipment:Concentration of lithography and etching tool supply from Tokyo Electron and limited alternative vendors creates procurement vulnerability for foundry expansion timelines.
- Labor Cost Escalation:Shrinking domestic IT workforce and immigration restrictions inflate implementation costs for multilingual system integration projects.
- Cross-Border Data Friction:METI's data-free flow with trust principles imposes compliance overhead on multinational enterprises seeking unified cloud architectures across Japan and offshore regions.
Strategic Opportunities
- Hokkaido Data Center Expansion:Cooler climates and renewable energy access position northern Japan for hyperscale facility development serving Tokyo-Osaka corridor latency requirements.
- Digital Health Validation:PMDA's streamlined pathways for AI diagnostic software create first-mover advantage for imaging analytics vendors targeting hospital procurement.
- 5G Standalone Infrastructure:SoftBank's capital deployment into network slicing enables private cellular networks for autonomous logistics in Kansai manufacturing zones.
Industry Challenges
- Mainframe Integration Complexity:COBOL-dependent core banking systems resist API-layer abstraction, forcing costly parallel-run validation periods during cloud migration.
- Cybersecurity Certification Bottlenecks:JIS standards and national cybersecurity regulator audits create 12-18 month approval timelines for critical infrastructure software vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan ICT Market |
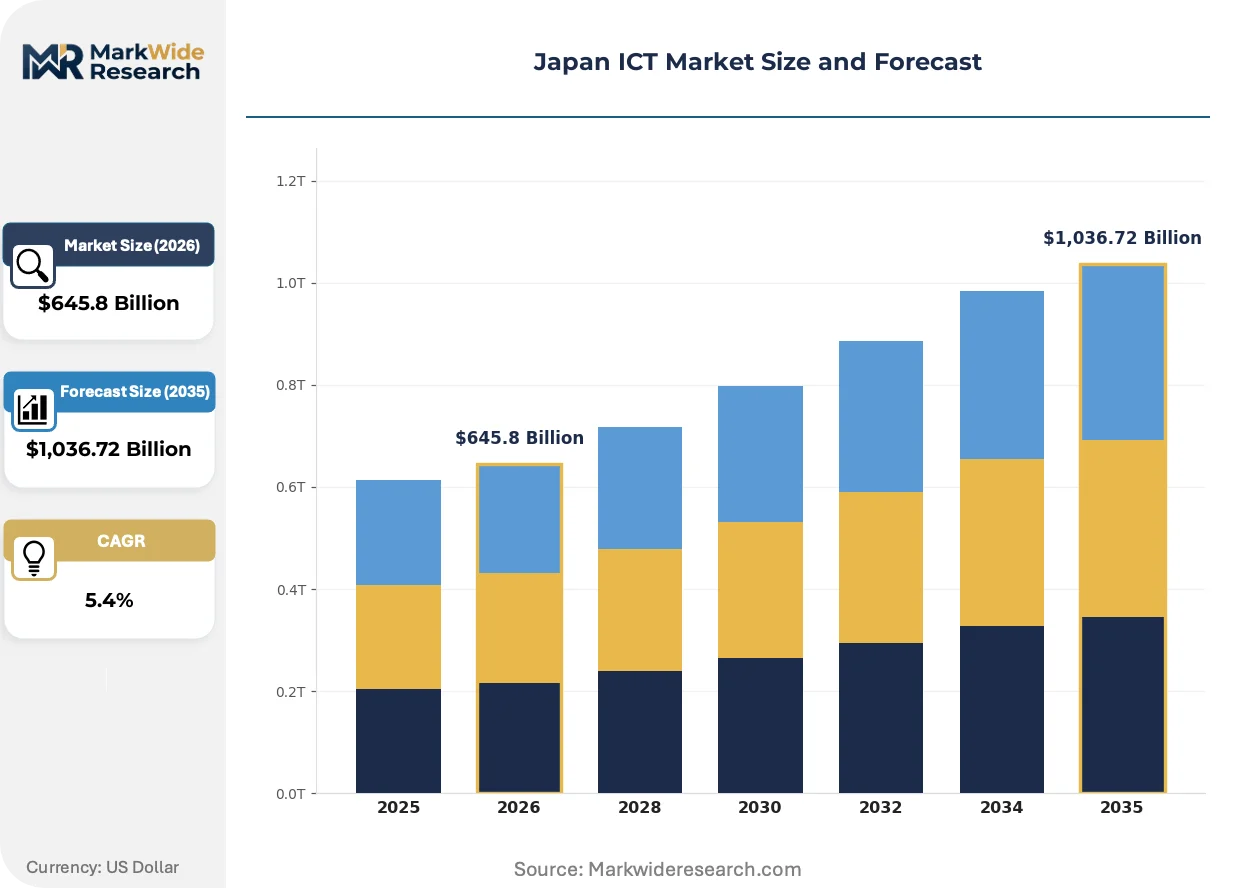
| Market Size in 2026 | $645.8 Billion |
| Market Size in 2035 | $1,036.72 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Hardware, Services, Cloud Solutions End User: Government, Education, Healthcare, Enterprises Technology: AI, IoT, Big Data, Blockchain Deployment: On-Premises, Cloud-Based, Hybrid, Managed |
| Companies Covered | NTT DATA, KDDI, Fujitsu Limited, TIS Inc., IBM Japan Ltd, NEC Corporation, SoftBank, Ericsson Japan, Hitachi Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan ICT Market Strategic Shifts & Innovations
Generative AI is absorbing software development workflows across Japanese enterprises, compressing traditional system integration timelines while demanding new GPU infrastructure procurement patterns. Three convergent forces are restructuring competitive positioning.
Containerized microservices architectures are absorbing monolithic enterprise resource planning deployments in manufacturing and retail sectors. Mid-cap automotive suppliers are adopting Kubernetes-orchestrated workloads to decouple inventory management from legacy SAP instances. This absorption is compressing vendor lock-in duration and enabling multi-cloud failover strategies for supply chain continuity.
METI's data governance frameworks are mandating explainable AI documentation for financial lending algorithms and insurance underwriting models. Domestic banks must deploy interpretable machine learning pipelines to satisfy audit requirements. The regulation is forcing vendors to abandon black-box neural networks in favor of decision-tree ensembles for credit risk scoring.
Consumption-based licensing is displacing perpetual software ownership in enterprise procurement. Tokyo-based financial institutions now negotiate three-year operational expenditure contracts for core banking platforms. This shift is visible most acutely in securities trading infrastructure, where volume-linked pricing aligns vendor revenue with transaction throughput.
Japan ICT Market Segmentation
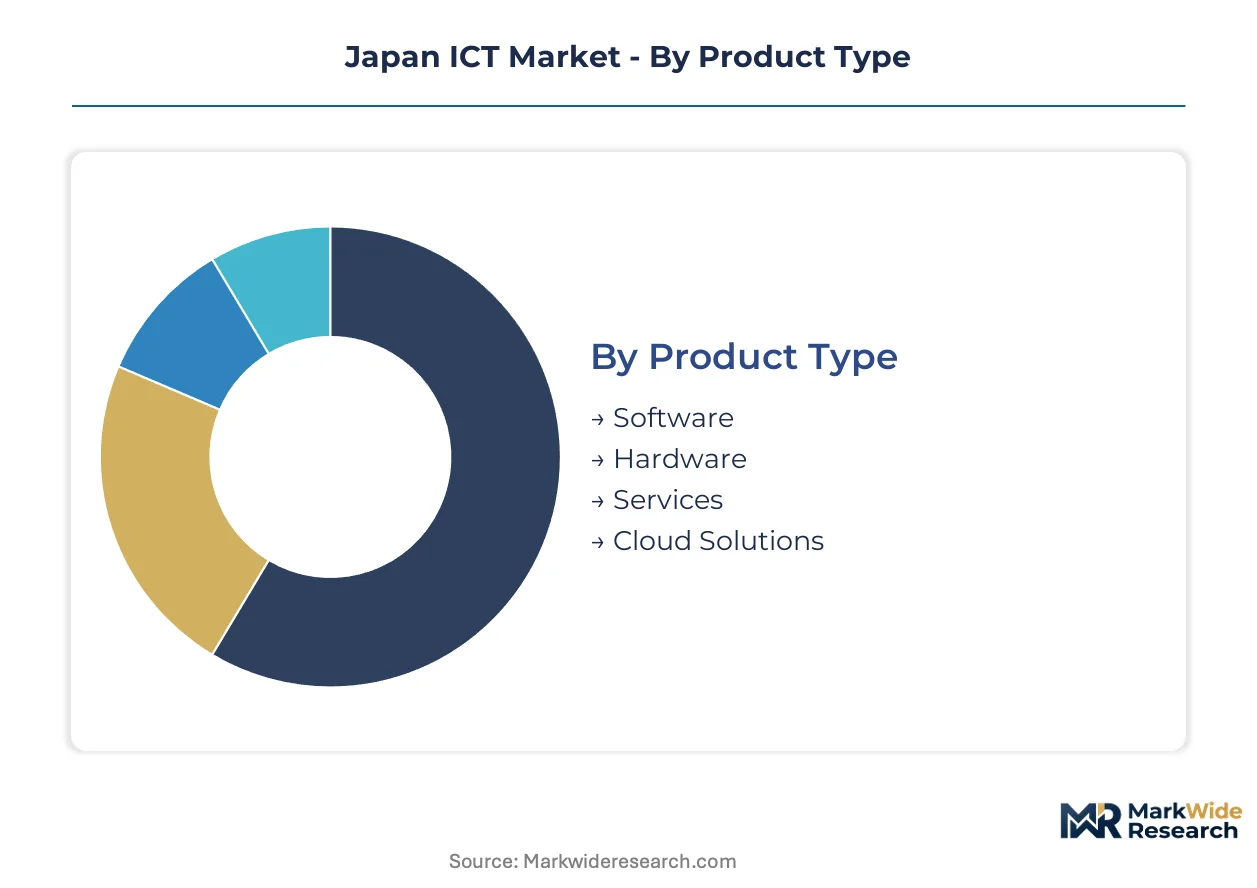
Segmentation in Japan ICT reveals how procurement priorities diverge between conservative financial institutions demanding mainframe-compatible solutions and precision manufacturers requiring sub-10 millisecond edge infrastructure. Understanding these fault lines enables vendors to align product roadmaps with METI's Society 5.0 compliance mandates.
Product Type:
Standardization dominates hardware procurement under JIS certification requirements, while software and services exhibit extensive customization for legacy system integration.
- Software:Enterprise applications and system integration platforms absorb the largest procurement budgets as financial institutions replace COBOL-dependent core banking systems with API-layer abstraction. Tokyo-based banks negotiate three-year operational expenditure contracts for modular service bundling that reduces mainframe operational expenditure.
- Services:System integration and managed services command premium pricing where multilingual implementation teams address labor cost escalation from shrinking domestic IT workforce. Implementation timelines stretch 12-18 months for critical infrastructure software requiring national cybersecurity regulator audits.
- Hardware:Semiconductor fabrication equipment and specialized edge computing nodes retain structural importance for factory-floor deployments in precision electronics manufacturing.
- Cloud Solutions:Hybrid infrastructure dominates procurement as enterprises balance METI's data-free flow with trust principles against offshore cloud cost advantages.
Most installed capacity flows through Services. Expansion is steepest in Cloud Solutions.
End User:
Cost tiers separate government digital identity programs with biometric authentication requirements from education sector budget-constrained refresh cycles.
- Enterprises:Manufacturing and financial services drive hybrid cloud transitions with Society 5.0 mandates compressing procurement cycles. Automotive supply chains deploy IoT-enabled industrial platforms for predictive maintenance while banks pursue FISC-compliant encryption standards.
- Government:Digital identity programs and critical infrastructure procurement enforce domestic content thresholds and JIS baseline encryption requirements. Biometric authentication integration creates multi-year platform commitments with deep vendor relationships.
- Healthcare:PMDA's streamlined pathways for AI diagnostic software accelerate imaging analytics procurement for hospital networks.
- Education:Budget constraints favor volume-linked pricing and consumption-based licensing over perpetual software ownership.
Enterprise procurement absorbs the dominant share of vendor revenue. Healthcare demonstrates the steepest expansion trajectory as PMDA validation pathways mature.
Technology:
Application maturity separates production-ready IoT deployments from experimental blockchain pilots in supply chain traceability.
- AI:Generative AI absorbs software development workflows while METI mandates explainable AI documentation for financial lending algorithms. Interpretable machine learning pipelines displace black-box neural networks for credit risk scoring.
- IoT:Factory-floor sensor networks and predictive maintenance systems concentrate demand in automotive and precision electronics manufacturing. Real-time quality control requires specialized edge computing nodes with sub-10 millisecond latency.
- Big Data:Analytics platforms support cross-border data handling compliance under METI governance frameworks.
- Blockchain:Supply chain traceability pilots remain limited by interoperability standards and validation overhead.
IoT carries the largest installed base. AI is climbing the fastest as GPU infrastructure procurement patterns reshape vendor relationships.
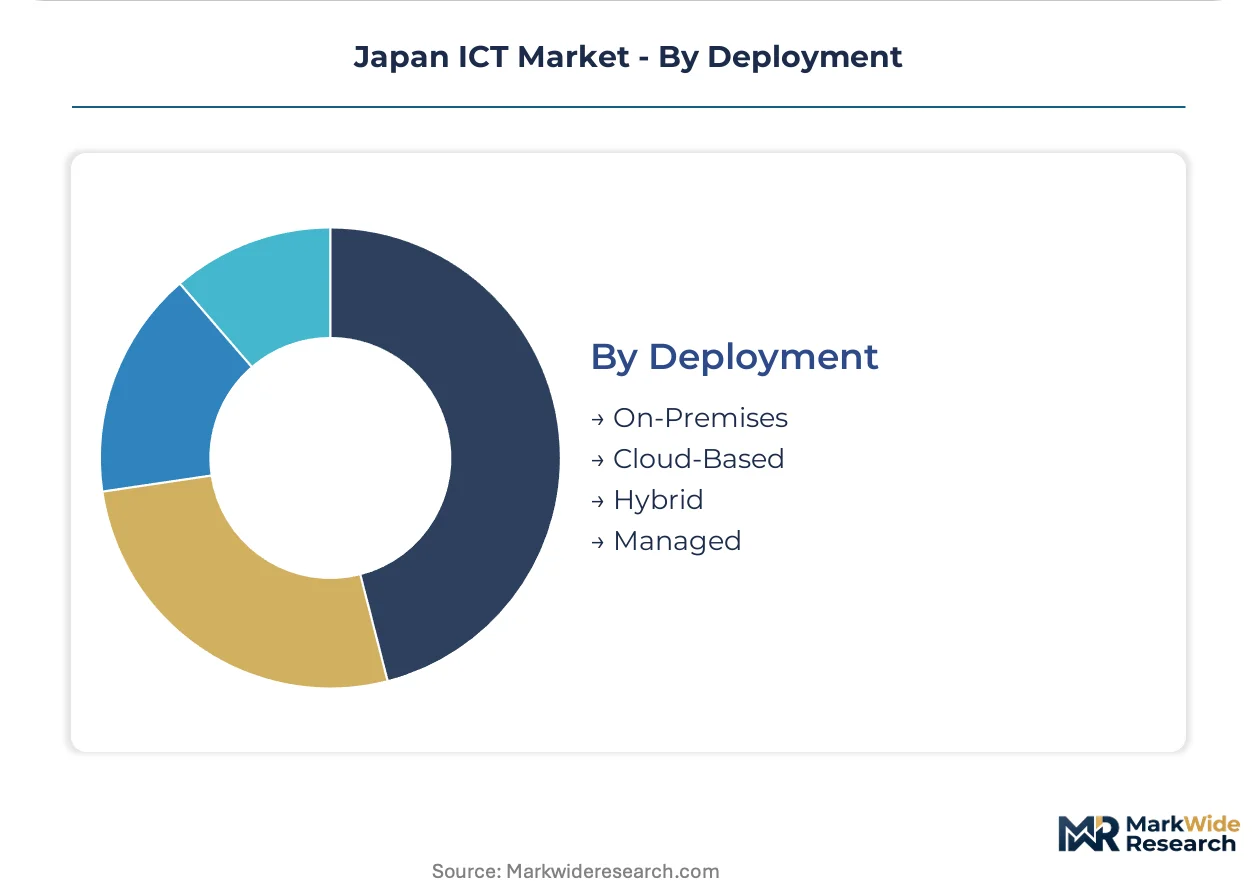
Deployment:
Customer type separates conservative financial institutions requiring managed services from mid-cap manufacturers adopting cloud-native architectures.
- Hybrid:Dominant architecture combining on-premises legacy mainframe heritage with cloud burst capacity for transaction processing. Fujitsu leverages mainframe relationships to anchor transitions for conservative banking institutions.
- Cloud-Based:Kubernetes-orchestrated workloads enable multi-cloud failover strategies for supply chain continuity in mid-cap automotive suppliers. Containerized microservices absorb monolithic enterprise resource planning deployments.
- On-Premises:Persists in critical infrastructure requiring air-gapped security and JIS certification maintenance.
- Managed:Outsourced operations reduce internal IT headcount pressure where immigration restrictions constrain workforce expansion.
Hybrid deployments hold the majority of committed capacity. Cloud-Based configurations are gaining share fastest among manufacturing sector entrants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's ICT industry traces its modern lineage to the 1960s mainframe era, when Tokyo-based conglomerates built computing infrastructure for keiretsu manufacturing networks. This heritage shapes today's hybrid cloud transitions and Society 5.0 policy mandates.
Kanto/Tokyo
Financial services and hyperscale data center demand concentrate here, with Tokyo-based banks negotiating three-year operational expenditure contracts for core banking platforms. METI's data-free flow with trust principles imposes compliance overhead on multinational enterprises seeking unified cloud architectures. The Tokyo-Osaka corridor anchors hybrid infrastructure deployments for latency-sensitive transaction processing.
Kansai/Osaka
Precision electronics manufacturing drives IoT-enabled industrial platform procurement, with automotive supply chains deploying predictive maintenance systems. JIS standards enforce baseline encryption requirements for factory-floor edge computing nodes. Osaka's industrial zones specialize in sub-10 millisecond latency infrastructure for real-time quality control.
Chubu/Nagoya
Automotive OEM headquarters and tier-one suppliers cluster here, absorbing GPU infrastructure for generative AI software development workflows. PMDA's digital health validation pathways create secondary demand for imaging analytics in medical device manufacturing. Nagoya's manufacturing belt integrates containerized microservices into legacy enterprise resource planning systems.
Hokkaido
Cooler climates and renewable energy access position this northern region for hyperscale facility development serving Tokyo-Osaka corridor latency requirements. SoftBank's capital deployment into domestic data center expansion targets Hokkaido's power cost advantages. Sapporo's emerging tech corridor attracts cloud burst capacity for financial services disaster recovery.
Kyushu
Semiconductor fabrication equipment demand concentrates in Fukuoka's industrial zones, with Tokyo Electron's lithography tools supporting foundry expansion timelines. Domestic content thresholds in critical infrastructure procurement favor local system integrators. Kyushu's manufacturing base adopts Kubernetes-orchestrated workloads for supply chain continuity.
Japan ICT Market Key Industry Players
Premium-margin players sit above commodity-margin players across encryption certification tiers and mainframe integration complexity. The vendor base organizes around three strategic archetypes: heritage mainframe operators leveraging COBOL-era relationships, AI-biometric specialists capturing government digital identity programs, and capital-scale infrastructure deployers building 5G standalone networks. Competitive moves concentrate on modular service bundling to decouple legacy overhauls from full-stack lock-in, plus Hokkaido data center expansion to capture renewable energy arbitrage.
Within the heritage systems tier, Fujitsu Limited and Hitachi Ltd occupy positions anchored by decades-long financial institution relationships. NEC Corporation exemplifies the AI-biometric specialist archetype through its integration in government digital identity frameworks. SoftBank represents the capital-scale infrastructure deployer, with its domestic data center and 5G standalone investments shaping private cellular network availability for Kansai manufacturing zones.
| Leading Market Players |
|---|
| NTT DATA |
| KDDI |
| Fujitsu Limited |
| TIS Inc. |
| IBM Japan Ltd |
| NEC Corporation |
| SoftBank |
| Ericsson Japan |
| Hitachi Ltd |
| Others |
Cost & Logistics Intelligence
Tokyo-Osaka corridor financial institutions anchor demand for three-year operational expenditure contracts, compressing vendor margins through volume-linked pricing and modular service bundling. This buyer concentration forces suppliers to absorb certification costs upfront while competing on latency guarantees and FISC encryption compliance.
Pricing Analysis
Consumption-based licensing structures separate premium managed services from standard cloud subscriptions and economy-tier self-service portals. Price differentiation hinges on JIS certification grade and after-sales service bundling, with cybersecurity audit support commanding substantial premiums. Cost compression in economy tiers intensifies as offshore cloud regions compete on raw compute pricing. Conservative banking institutions demonstrate lowest price sensitivity, prioritizing mainframe-compatible transitions over unit cost.
Supply Chain Analysis
Domestic content thresholds in METI procurement mandates are reshaping sourcing patterns for critical infrastructure software and semiconductor fabrication equipment. Supply concentrates in Japan, Taiwan, and South Korea for lithography tools, specialized edge computing nodes, and GPU infrastructure. Component dependencies include advanced packaging substrates, high-bandwidth memory modules, and precision sensor arrays. Single-source vulnerability from Tokyo Electron's etching tool dominance creates procurement bottlenecks. Distribution runs through keiretsu-affiliated system integrators with deep financial institution relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan ICT functions as a late-cycle quality market where procurement cycles compress toward premium-tier vendors capable of sub-10 millisecond latency and FISC-compliant encryption. Demand is shifting toward explainable AI documentation and hybrid cloud architectures that satisfy METI's data-free flow with trust principles.
For Market Incumbents: Hedge against margin erosion from offshore cloud competition by deepening mainframe integration expertise and accelerating Hokkaido data center capacity. Secure multi-year platform commitments through biometric authentication bundling in government digital identity programs. Invest in interpretable machine learning pipelines ahead of METI audit requirement expansion.
For New Entrants and Emerging Players: Begin with PMDA validation pathway specialization for AI diagnostic imaging, where streamlined approval creates first-mover advantage. Target mid-cap automotive suppliers adopting Kubernetes-orchestrated workloads for supply chain continuity. Lead with consumption-based licensing and multilingual implementation teams to address labor cost escalation.
For Investors and Strategic Acquirers: Heritage technology conglomerates with mainframe relationships and government security clearances are the most active acquirer in this space, consolidating modular service capabilities. Five-to-ten year viability favors vendors with captive domestic data center assets and renewable energy positioning. Monitor SoftBank's capital deployment pace into 5G standalone infrastructure as inflection signal for private cellular network availability.
| Strategic Initiative | Industry Significance |
|---|---|
| Hokkaido Hyperscale Facility Development | Captures renewable energy arbitrage for Tokyo-Osaka corridor latency requirements. |
| Biometric Authentication Platform Integration | Secures multi-year government digital identity commitments with NEC and Fujitsu. |
| Explainable AI Pipeline Deployment | Satisfies METI audit mandates for financial lending algorithm documentation. |
| 5G Standalone Network Slicing | Enables private cellular networks for autonomous logistics in Kansai manufacturing zones. |
| Containerized Microservices Architecture | Decouples monolithic SAP instances for mid-cap automotive supplier adoption. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with CTOs, IT procurement officers, platform engineers, and integration specialists with secondary validation. Data sources included METI policy filings, PMDA approval databases, hyperscaler capex disclosures, JIS certification registries, and keiretsu procurement records. Bottom-up vendor revenue triangulation against top-down enterprise IT spending estimates anchored market sizing.
Segment-weighting approaches distributed value across deployment models, organization size, vertical industry, integration complexity, and regional adoption patterns. CAGRs derived from trend extrapolation and driver elasticity modeling across the analysis window. Forecast inputs incorporated Society 5.0 policy implementation timelines and semiconductor equipment delivery schedules.
Caveats apply where METI data governance revisions, PMDA validation pathway changes, or Tokyo Electron supply disruptions could materially shift the outlook. Forecasts reflect documented assumptions about immigration policy relaxation and domestic workforce expansion. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Next Generation Technologies
Enterprise Quantum Computing Market
Next Generation Technologies
Next Generation Network (NGN) Equipment Market
Next Generation Technologies
Jordan ICT Market
Next Generation Technologies
Smart Surfaces Market
Next Generation Technologies
Ireland ICT Market
Next Generation Technologies
Quantum Computing Market
Next Generation Technologies
Hyperscale Edge Computing Market
Next Generation Technologies
Information and Communications Technology (ICT) Market
Next Generation Technologies
Fog Computing Market
Next Generation Technologies
Oman ICT Market
Next Generation Technologies
Bulgaria ICT Market
Next Generation Technologies
Quantum Information Processing Market
Next Generation Technologies
Europe Quantum Computing Market
Next Generation Technologies
Global Next Generation Wireless Communication Market
Next Generation Technologies
Poc Platform and Technology Market
Next Generation Technologies
M2M Connections Market