
 Europe Quantum Computing Market | 2026-2036
Europe Quantum Computing Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Quantum Computing Market Insights
Superconducting qubit coherence time extension is rewriting the engineering economics of fault-tolerant quantum processors. IQM Quantum Computers anchors its competitive position through in-house cryogenic control electronics fabrication in Espoo and Munich. Pasqal SAS differentiates via neutral-atom architectures that sidestep the dilution refrigerator bottleneck plaguing superconducting rivals. Quantinuum Ltd. leverages its trapped-ion heritage from Honeywell and Cambridge Quantum to sustain premium pricing in enterprise software subscriptions.
Quantum computing deploys systems that manipulate quantum bits through superposition and entanglement, typically requiring operation at millikelvin temperatures near absolute zero with coherence times measured in microseconds to milliseconds; its primary commercial purpose is solving combinatorial optimization, quantum simulation, and cryptographic problems intractable to classical supercomputers. Hardware currently occupies the dominant revenue share given the capital intensity of dilution refrigerators and custom cryogenic cabling, though cloud-based services represent the fastest-expanding margin pool as hyperscale providers abstract physical infrastructure complexity from end users. Superconducting qubits lead European installed base counts due to IBM Corporation's Zurich heritage and IQM's regional foundry investments, while photonic quantum computing gains research traction for room-temperature operation potential in telecommunications applications.
The EU Chips Act and European Quantum Flagship shape capital allocation toward sovereign supply chains, while ETSI quantum-safe cryptography standards and national regulators in Germany's BSI and France's ANSSI mandate migration timelines for critical infrastructure. REACH compliance constrains cryogenic coolant chemistry selection, particularly for helium-3 recycling protocols. Stakeholders must monitor whether trapped-ion or photonic platforms achieve sufficient logical qubit counts to displace superconducting dominance before European hardware investments crystallize around irreversible fabrication commitments.
Market Dynamics
Superconducting qubit coherence time extension is compressing the engineering economics of fault-tolerant quantum processors, forcing capital allocation toward cryogenic control electronics fabrication and dilution refrigerator capacity expansion across European quantum clusters.
Growth Catalysts
- EU Chips Act capital injection:Sovereign supply chain mandates are channeling public investment into regional foundry capacity for quantum processor fabrication, reducing dependency on non-European semiconductor tooling.
- Financial services pilot scaling:Portfolio optimization and risk modeling applications in German and French banking are generating recurring cloud-access revenue that subsidizes hardware development costs.
- Neutral-atom architectural maturation:Trapped-ion and photonic alternatives are achieving logical qubit densities that challenge superconducting dominance, diversifying hardware procurement options for enterprise buyers.
Market Restraints
- Helium-3 supply concentration:Cryogenic coolant sourcing depends on limited Russian and US stockpiles, with REACH compliance constraining recycling protocol chemistry and driving input cost volatility.
- Dilution refrigerator fabrication bottleneck:European capacity for millikelvin-temperature systems concentrates in a handful of specialized vendors, creating supply concentration risk for hardware deployment timelines.
- ETSI quantum-safe migration friction:Cryptographic standard transition timelines mandated by Germany's BSI and France's ANSSI impose compliance overhead that delays enterprise procurement decisions.
Strategic Opportunities
- Netherlands quantum ecosystem expansion:Delft's concentration of academic and spin-out activity positions the region for underpenetrated industrial chemistry and materials science simulation demand.
- Room-temperature photonic computing convergence:Integration of telecom-grade photonics with quantum processors eliminates dilution refrigerator capex, opening mid-market enterprise segments previously priced out of superconducting access.
- European Quantum Flagship Phase 2:Continued public co-investment in application-specific quantum computing reduces customer acquisition costs for algorithm developers targeting sovereign infrastructure mandates.
Industry Challenges
- Cryogenic engineering talent scarcity:Millikelvin system design and fault-tolerant control electronics fabrication require specialized skill sets concentrated in a small pool of academic and national laboratory alumni.
- Cloud-to-hardware integration complexity:Enterprise buyers demand seamless abstraction layers that mask qubit-level variability, forcing vendors to absorb software engineering costs that compress service margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Quantum Computing Market |
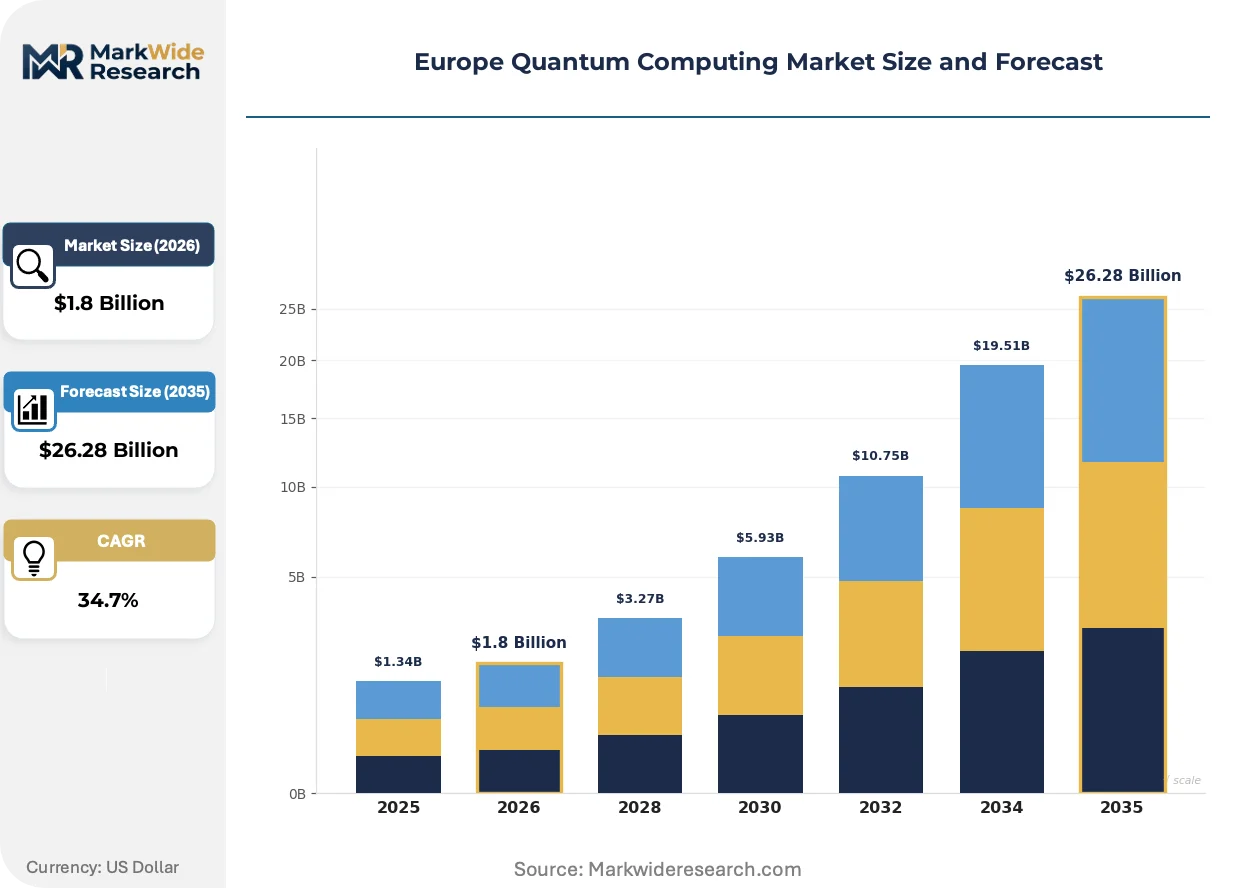
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $26.28 Billion |
| CAGR (2026 – 2036) | 34.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hardware, Software, Services, Integrated Solutions End User: Telecommunications, BFSI, Defense, Academia Deployment: On-Premises, Cloud-Based, Hybrid, Edge Computing Technology: Superconducting Qubits, Trapped Ions, Photonic Quantum Computing, Quantum Annealers |
| Companies Covered | IBM Corporation, IQM Quantum Computers, Quantinuum Ltd., Pasqal SAS, Alice & Bob, Alpine Quantum Technologies, IonQ Inc., D-Wave Quantum Inc., Atom Computing, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Quantum Computing Market Trends and Innovations
European quantum computing is undergoing a platform diversification phase where architectural bets are crystallizing around distinct temperature regimes and error-correction strategies, reshaping competitive positioning before market share stabilizes.
Superconducting transmon qubits with extended coherence times are digitizing the fault-tolerance threshold for quantum error correction, enabling more compact physical-to-logical qubit ratios. German automotive and pharmaceutical enterprises are piloting these systems for molecular simulation workloads. This compression of hardware overhead is digitizing the path to commercially viable quantum advantage in optimization problems.
REACH and F-Gas Regulation amendments are tightening constraints on cryogenic coolant chemistry and helium recycling protocols, elevating compliance costs for superconducting platform operators. The regulatory pressure is accelerating investment in closed-cycle dilution refrigerator designs and alternative cooling architectures. French and German national regulators are enforcing these mandates most strictly, pushing hardware developers toward neutral-atom and photonic alternatives that operate at higher temperatures.
Enterprise procurement patterns are gravitating toward subscription-based cloud access models that bundle algorithm development support with compute credits, displacing capital-intensive on-premise system purchases. Financial services and pharmaceutical verticals in Munich and Paris-Saclay are driving this shift, preferring operational expenditure structures that align quantum spending with demonstrable workflow integration milestones. This behavioral pivot is most visible in Germany, where BSI cybersecurity certification requirements add friction to direct hardware ownership.
Europe Quantum Computing Market Segmentation
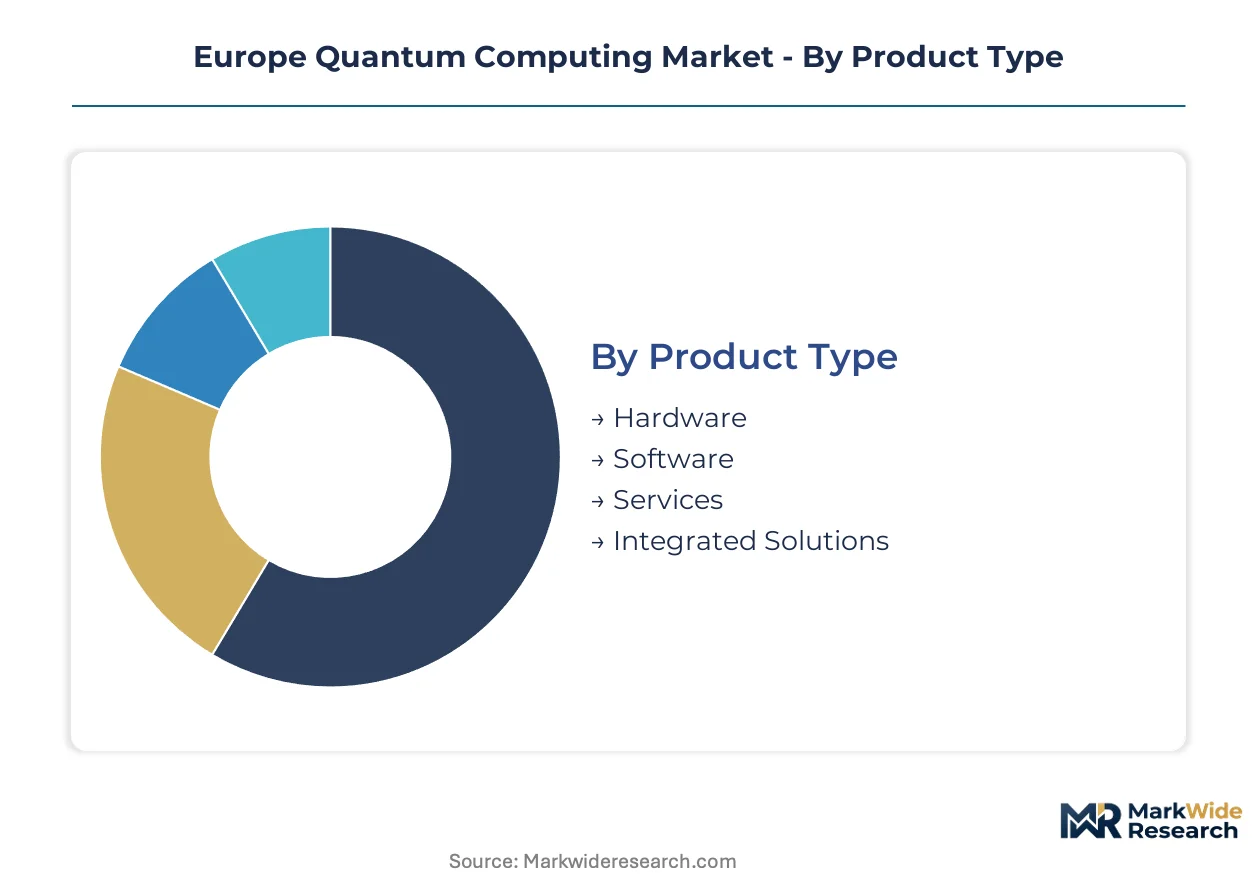
Segmentation in quantum computing reveals how capital intensity, temperature regimes, and regulatory compliance reshape procurement patterns across European enterprise buyers. Hardware and cloud deployment models command divergent margin structures, while technology choices lock customers into irreversible architectural commitments.
Product Type:
After-sales-service intensity varies dramatically across product categories, with cryogenic hardware demanding continuous field engineering support while software subscriptions rely on remote update cycles.
- Hardware:Dilution refrigerators, cryogenic cabling, and quantum processor chips require millikelvin operation and specialized maintenance contracts. German automotive and pharmaceutical enterprises in Munich cluster procurement around superconducting systems with multi-year service agreements.
- Services:Cloud access credits bundled with algorithm development support represent the fastest-expanding margin pool as financial services firms in Paris-Saclay prefer operational expenditure alignment with workflow milestones.
- Software:Quantum development kits and error-correction middleware abstract physical qubit variability for enterprise developers.
- Integrated Solutions:Turnkey systems combining hardware, software, and professional services target sovereign infrastructure mandates under the European Quantum Flagship.
By volume, Hardware leads. By growth pace, Services is expanding most quickly.
End User:
Customer sophistication tiers separate institutional buyers with captive quantum expertise from enterprises outsourcing algorithm development entirely.
- BFSI:Portfolio optimization and risk modeling pilots in Frankfurt and Paris generate recurring cloud revenue that subsidizes hardware development. Regulatory pressure from BSI and ANSSI accelerates procurement timelines for quantum-safe cryptography preparation.
- Academia:National laboratory and university consortia in Delft, Munich, and Grenoble anchor early-stage hardware validation and talent pipeline development.
- Telecommunications:Room-temperature photonic quantum computing attracts interest for quantum key distribution integration with existing fiber infrastructure.
- Defense:Sovereign capability mandates under EU Chips Act channel classified procurement toward domestic superconducting and trapped-ion platforms.
By installed base, Academia dominates. By commercial revenue conversion, BFSI is gaining share fastest.
Deployment:
Capital expenditure thresholds and data sovereignty requirements partition buyers across infrastructure ownership models.
- Cloud-Based:Hyperscale abstraction layers mask qubit-level complexity, enabling pharmaceutical and financial services verticals to trial quantum advantage without dilution refrigerator capital commitment.
- On-Premises:Direct hardware ownership satisfies BSI cybersecurity certification requirements for German critical infrastructure operators despite higher total cost of ownership.
- Hybrid:Workload-specific routing between classical high-performance computing and quantum processors optimizes cost per algorithmic step.
- Edge Computing:Distributed quantum sensing applications in industrial chemistry monitoring drive specialized deployment configurations.
By customer count, Cloud-Based leads. By contract value concentration, On-Premises shows the steepest expansion trajectory.
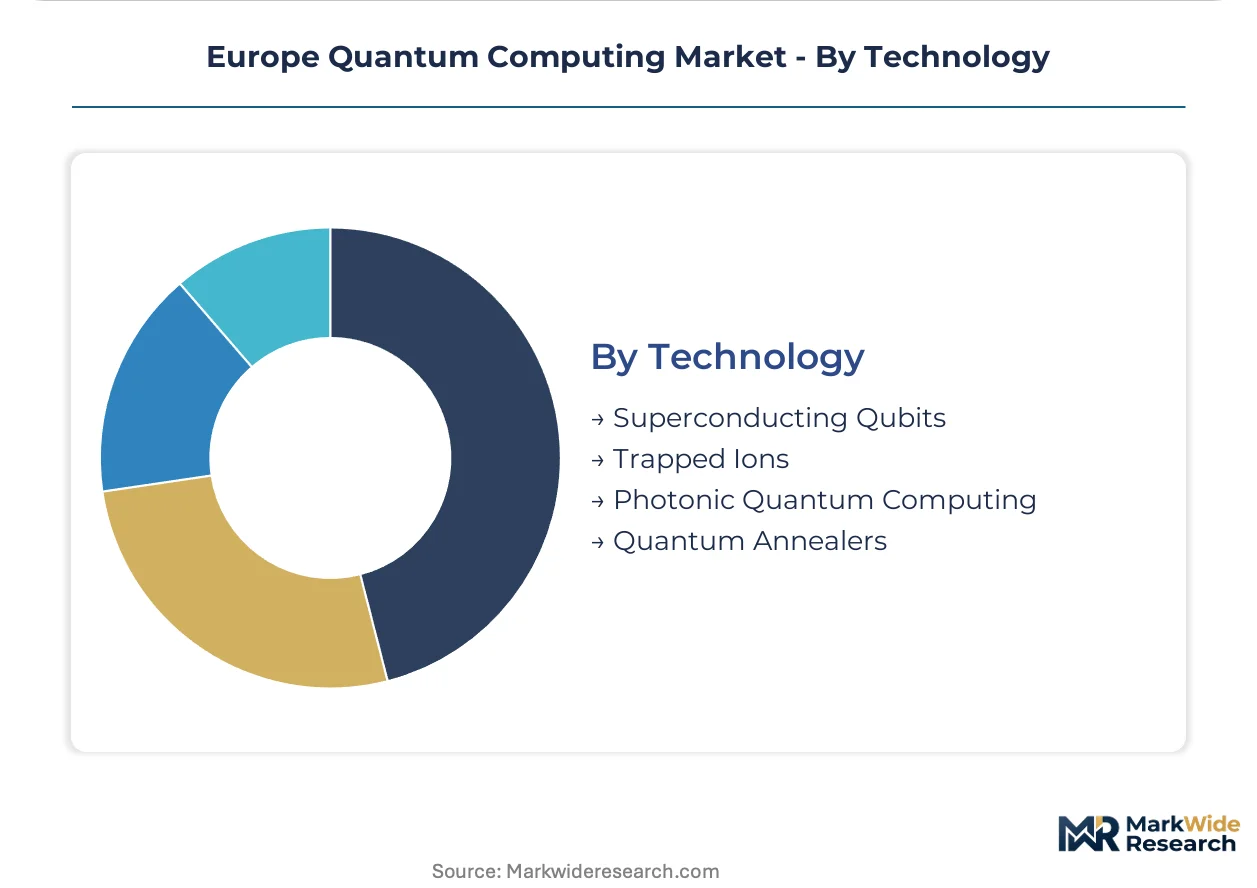
Technology:
Platform selection crystallizes around temperature regimes, with millikelvin superconducting systems competing against room-temperature photonic alternatives for different workload classes.
- Superconducting Qubits:Transmon architectures with extended coherence times digitize fault-tolerance thresholds for quantum error correction. IBM's Zurich heritage and IQM's Espoo-Munich foundry investments anchor European installed base leadership.
- Trapped Ions:Quantinuum leverages Honeywell-Cambridge Quantum heritage to sustain premium pricing through high-fidelity gate operations and all-to-all connectivity advantages in molecular simulation.
- Photonic Quantum Computing:Telecom-grade component integration eliminates cryogenic capex, opening mid-market segments previously priced out of superconducting access.
- Quantum Annealers:Specialized optimization hardware targets discrete combinatorial problems in logistics and financial portfolio construction with shallower quantum circuit requirements.
By deployment count, Superconducting Qubits leads. By investment flow diversification, Photonic Quantum Computing is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Europe's quantum computing trade flows reveal a net importer position in cryogenic hardware balanced by emerging processor fabrication exports from Nordic and German foundries. Capital formation concentrates in sovereign capability mandates rather than pure commercial demand, reshaping regional investment patterns.
Germany
Automotive and pharmaceutical enterprises in Munich and Stuttgart drive superconducting system procurement for molecular simulation workloads. BSI cybersecurity certification requirements under national critical infrastructure protection laws accelerate procurement timelines for quantum-safe cryptography preparation. The Munich quantum cluster anchors hardware validation partnerships between industrial end-users and cryogenic engineering specialists.
France
Financial services institutions in Paris-Saclay scale cloud-access pilots for portfolio optimization, generating recurring operational expenditure commitments. ANSSI mandates cryptographic migration timelines that compress enterprise decision cycles for quantum-ready security infrastructure. The Paris-Saclay plateau concentrates neutral-atom research spin-outs alongside established aerospace supply chain integration.
Netherlands
Delft's academic-industrial ecosystem generates specialized demand for industrial chemistry and materials science simulation applications. REACH compliance enforcement on helium-3 recycling protocols elevates operational costs for superconducting platform operators. The Randstad corridor houses Europe's densest concentration of quantum sensing and photonics integration facilities.
United Kingdom
Cambridge and Oxford research consortia sustain trapped-ion platform development through national quantum computing program funding. UK Research and Innovation coordinates sovereign capability investments independent of EU funding mechanisms post-Brexit. The Cambridge cluster leverages heritage connections to Honeywell-Quantinuum commercialization pathways.
Finland
Espoo-based cryogenic control electronics fabrication serves as a regional supply anchor for superconducting processor architectures. National innovation agency Business Finland channels public co-investment into application-specific quantum computing development. The Helsinki-Espoo corridor specializes in dilution refrigerator component manufacturing and low-temperature measurement systems.
Europe Quantum Computing Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic archetypes: cryogenic hardware fabricators with captive foundry investments, cloud-access platform operators bundling algorithm support with compute credits, and neutral-atom specialists sidestepping refrigeration infrastructure requirements. Competitive maneuvering centers on strategic partnerships with national quantum flagship programs and in-house fabrication commitments that lock in irreversible capital allocations.
Among hardware-centric fabricators, IQM Quantum Computers and Pasqal SAS exemplify divergent architectural bets on superconducting versus neutral-atom platforms. Quantinuum Ltd. occupies a distinctive position bridging trapped-ion heritage with enterprise software subscription models. These three anchors represent the spectrum of European competitive positioning before market share stabilizes around proven fault-tolerance thresholds.
| Leading Market Players |
|---|
| IBM Corporation |
| IQM Quantum Computers |
| Quantinuum Ltd. |
| Pasqal SAS |
| Alice & Bob |
| Alpine Quantum Technologies |
| IonQ Inc. |
| D-Wave Quantum Inc. |
| Atom Computing |
| Others |
Pricing and Supply Chain Analysis
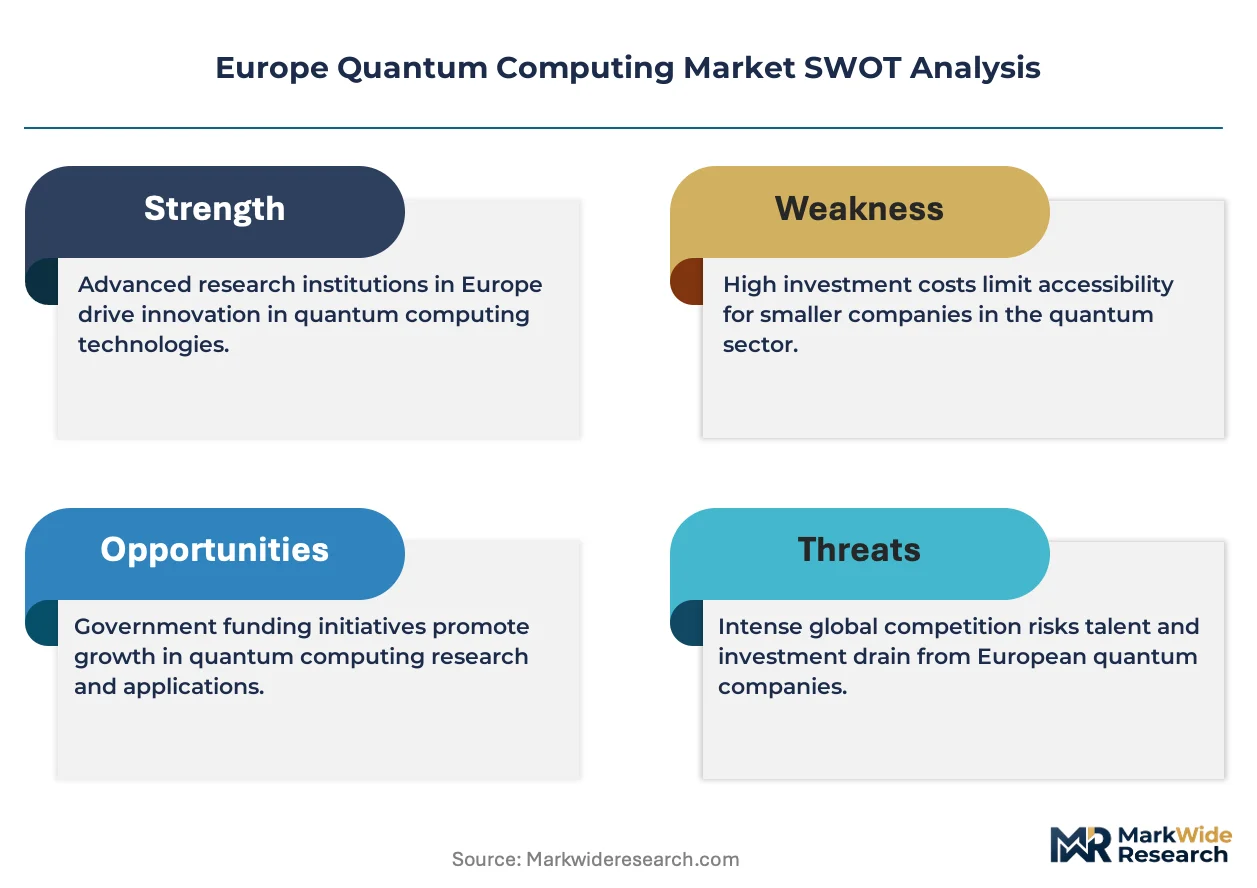
Helium-3 supply concentration in Russian and US stockpiles determines both the tiered pricing spreads across cryogenic hardware categories and the geographic clustering of dilution refrigerator fabrication capacity in Europe's quantum computing market. REACH compliance constraints on recycling protocol chemistry amplify input cost volatility, compressing margins for superconducting platform operators while elevating premium pricing for neutral-atom alternatives that bypass millikelvin infrastructure requirements.
Pricing Analysis
Current-generation superconducting systems command substantial premiums over prior-generation trapped-ion platforms and emerging photonic alternatives, with pricing stratifying across premium, standard, and economy tiers based on logical qubit count and error-correction overhead. Certification level under Germany's BSI and France's ANSSI frameworks drives differentiation, as quantum-safe cryptography readiness commands higher subscription rates in financial services procurement. Cost compression in cloud-access services is intensifying because hyperscale providers abstract physical infrastructure complexity, eroding hardware vendor margins. Academic and national laboratory buyers exhibit highest price sensitivity, while sovereign defense and critical infrastructure operators demonstrate lowest sensitivity due to capability mandates.
Supply Chain Analysis
Contract manufacturing for cryogenic control electronics concentrates in Finland's Espoo corridor and Germany's Munich cluster, with IQM's captive foundry investments anchoring regional processor fabrication capacity. Geographic supply concentration centers on Finland, Germany, and the Netherlands for dilution refrigerator components and superconducting chip production. Raw material dependencies draw from limited helium-3 reserves, niobium for superconducting circuits, and specialized cryogenic cabling alloys. Single-source vulnerability in dilution refrigerator engineering talent creates procurement bottlenecks for hardware deployment timelines. Distribution runs through direct vendor-to-enterprise contracts for on-premises systems, supplemented by hyperscale cloud provider partnerships for subscription-based access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's quantum computing market requires substitution defense against room-temperature photonic platforms that threaten to displace cryogenic hardware investments before fault-tolerance thresholds crystallize. Incumbents must navigate architectural uncertainty while locking in irreversible fabrication commitments.
For Market Incumbents: Build captive cryogenic engineering moats through in-house dilution refrigerator component production and exclusive partnerships with Delft and Munich academic consortia. Secure backward integration into helium-3 recycling infrastructure to mitigate supply concentration risk from Russian and US stockpiles. Prioritize BSI and ANSSI certification pathways that create switching costs for enterprise buyers evaluating photonic alternatives. For New Entrants and Emerging Players: Netherlands industrial chemistry and materials science simulation demand offers underpenetrated entry points for algorithm developers targeting SME segments priced out of superconducting access. Photonic quantum computing integration with existing telecom fiber infrastructure represents the most penetrable deployment vector. Go-to-market execution should leverage European Quantum Flagship Phase 2 co-investment mechanisms to reduce customer acquisition costs. For Investors and Strategic Acquirers: The market sits at a platform-diversification phase that favors trapped-ion specialists with demonstrated molecular simulation traction and neutral-atom players achieving logical qubit density milestones. Long-term viability over the next decade hinges on architectural bets crystallizing before European hardware investments harden around irreversible commitments. Monitor helium-3 supply contract renegotiations and REACH amendment enforcement as inflection indicators for superconducting platform cost structures.| Strategic Initiative | Industry Significance |
|---|---|
| Cryogenic Control Electronics Captive Production | In-house fabrication at Espoo and Munich facilities reduces dependency on non-European semiconductor tooling. |
| Neutral-Atom Platform Scale-Up | Pasqal's Paris-Saclay operations sidestep dilution refrigerator bottlenecks plaguing superconducting rivals. |
| Cloud-Access Subscription Expansion | Hyperscale partnerships with Frankfurt and Paris financial services firms generate recurring operational expenditure commitments. |
| Helium-3 Closed-Cycle Recycling Investment | REACH-compliant protocols address supply concentration risk from limited Russian and US stockpiles. |
| Quantum-Safe Cryptography Certification | BSI and ANSSI compliance creates switching costs for enterprise buyers evaluating platform migrations. |
Research Methodology
Desk research of EU Chips Act implementation documents, European Quantum Flagship program disclosures, and ETSI quantum-safe cryptography standards preceded structured interviews with cryogenic hardware engineering leads, cloud platform product managers, financial services quantum computing procurement officers, and national laboratory research directors. Secondary validation drew from academic publications in quantum error correction, trade customs data for cryogenic component imports, and national regulatory filings with Germany's BSI and France's ANSSI. Bottom-up sizing of hardware unit shipments and cloud-access subscription volumes triangulated against top-down public investment flow analysis.
The forecast framework holds EU Chips Act capital injection schedules and European Quantum Flagship Phase 2 funding commitments as fixed boundary conditions, while varying helium-3 supply scenarios and REACH regulatory enforcement intensity across sensitivity cases. Segmentation modeling incorporated product type, end-user vertical, deployment architecture, and technology platform dimensions. CAGRs were derived from installed base expansion curves and cloud revenue per customer trends. Industry-specific inputs included dilution refrigerator manufacturing capacity constraints and logical qubit roadmap milestones from superconducting and trapped-ion developers.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by photonic quantum computing entrants or abrupt helium-3 export restrictions would shift outcomes substantially. Quarterly review of cryogenic engineering hiring rates, European Quantum Flagship grant award velocities, and BSI/ANSSI certification completion timelines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Next Generation Technologies
Poc Platform and Technology Market
Next Generation Technologies
Japan ICT Market
Next Generation Technologies
Ireland ICT Market
Next Generation Technologies
Next Generation Wireless Network Market
Next Generation Technologies
Nigeria ICT Market
Next Generation Technologies
Quantum Information Processing Market
Next Generation Technologies
Hyperloop Technology Market
Next Generation Technologies
Information and Communications Technology (ICT) Market
Next Generation Technologies
Next-Generation Communication Devices Market
Next Generation Technologies
Fog Computing Market
Next Generation Technologies
5G New Radio Market
Next Generation Technologies
Global Next Generation Wireless Communication Market
Next Generation Technologies
Hyperscale Edge Computing Market
Next Generation Technologies
Malaysia ICT Market
Next Generation Technologies
Nearfield Communication (NFC) Market
Next Generation Technologies
Quantum Computing Market