
 Enterprise Quantum Computing Market | 2026-2036
Enterprise Quantum Computing Market Size, Share, and Industry Trends Forecast 2026-2036
Enterprise Quantum Computing Market Intelligence
The unbundling of quantum hardware from software via Quantum-as-a-Service (QaaS) platforms is repositioning buyer choice away from capital-intensive on-premises systems. This model lowers the barrier to entry for enterprises seeking to explore quantum capabilities. IBM leverages its full-stack development to offer integrated solutions from processor to cloud access. D-Wave Quantum Inc. specializes in annealing-based computers for specific optimization tasks, while Google pioneers advancements in gate-based superconducting qubit systems.
Enterprise quantum computing utilizes principles like superposition and entanglement to process information in qubits, solving problems intractable for classical machines. A key performance metric is quantum volume, which incorporates qubit count, connectivity, and error rates. Cloud-based deployment models provide the primary access route for most enterprises, enabling experimentation without owning hardware. Within applications, financial modeling and drug discovery are seeing significant investment, primarily using technologies like superconducting qubits and trapped ions.
National security export controls in the United States and China restrict the transfer of sensitive quantum technologies and components. The development of post-quantum cryptography standards by the National Institute of Standards and Technology (NIST) is forcing a re-evaluation of digital security infrastructure. In Europe, the EU AI Act may also create future compliance obligations for quantum machine learning applications. Vendor selection will increasingly hinge on the demonstrated performance of quantum hardware on specific, industry-relevant benchmark problems.
Market Dynamics
The enterprise quantum computing market's structure is defined by the strategic unbundling of hardware from software. This shift, enabled by Quantum-as-a-Service platforms, moves enterprise focus from capital acquisition to accessing specific computational capabilities for industry-relevant problems.
Growth Catalysts
- Qubit Stability Advances:The development of superconducting and trapped-ion qubits with longer coherence times and lower error rates is a critical technological enabler, allowing for more complex and meaningful computations before the quantum state decoheres.
- Financial Sector Demand:The financial modeling sector presents strong demand for quantum algorithms to perform complex risk analysis, derivative pricing, and portfolio optimization at speeds and scales intractable for classical high-performance computing.
- Government R&D Investment:Concentrated research and development funding in the United States, particularly through collaborations between national laboratories and universities, accelerates foundational science and builds a necessary pipeline of specialized talent.
Market Restraints
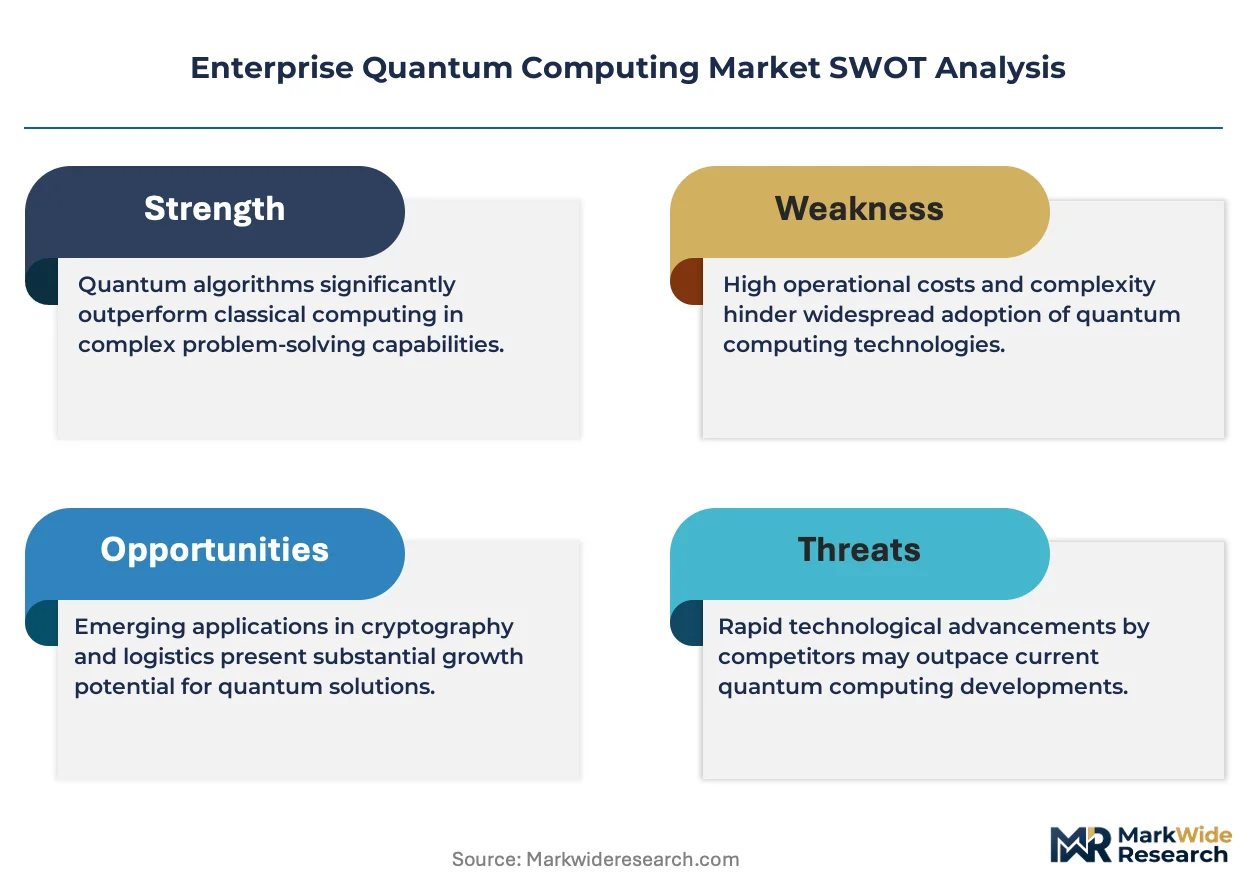
- Quantum Decoherence:The inherent instability of qubits, which lose their quantum state due to environmental interactions, remains the primary technical barrier, severely limiting the scale and duration of computations currently possible.
- Export Controls:National security-driven export controls on dual-use quantum technologies, particularly by the United States and China, create significant friction for international collaboration, talent mobility, and global supply chain integration.
- High Capital Costs:The extreme cost of building and maintaining quantum computers, including specialized cryogenic cooling and electromagnetic shielding infrastructure, presents a formidable barrier to on-premises deployment for most enterprises.
Strategic Opportunities
- Quantum Machine Learning:The application of quantum algorithms to enhance machine learning models represents a significant growth vector, offering potential breakthroughs in areas like pattern recognition and optimization for artificial intelligence systems.
- Hybrid Computing Models:Integrating quantum processing units (QPUs) with classical high-performance computing (HPC) resources creates hybrid systems that can strategically allocate computational tasks, accelerating solutions for complex optimization and simulation problems.
- Materials Science Simulation:There is a substantial opportunity to apply quantum computing to simulate molecular and material interactions at a fundamental level, accelerating the discovery of new catalysts, pharmaceuticals, and battery materials.
Industry Challenges
- Specialized Talent Scarcity:A pronounced shortage of professionals with expertise in quantum physics, hardware engineering, and quantum algorithm development constrains the ability of both vendors and end-users to scale their quantum initiatives.
- Benchmarking Standardization:The absence of universally accepted performance benchmarks makes it difficult for enterprises to conduct like-for-like comparisons of different quantum hardware architectures, such as gate-based versus annealing systems.
- Legacy System Integration:A significant operational hurdle is the complexity of integrating quantum computing workflows with existing enterprise IT infrastructure, classical data pipelines, and established software development practices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Enterprise Quantum Computing Market |
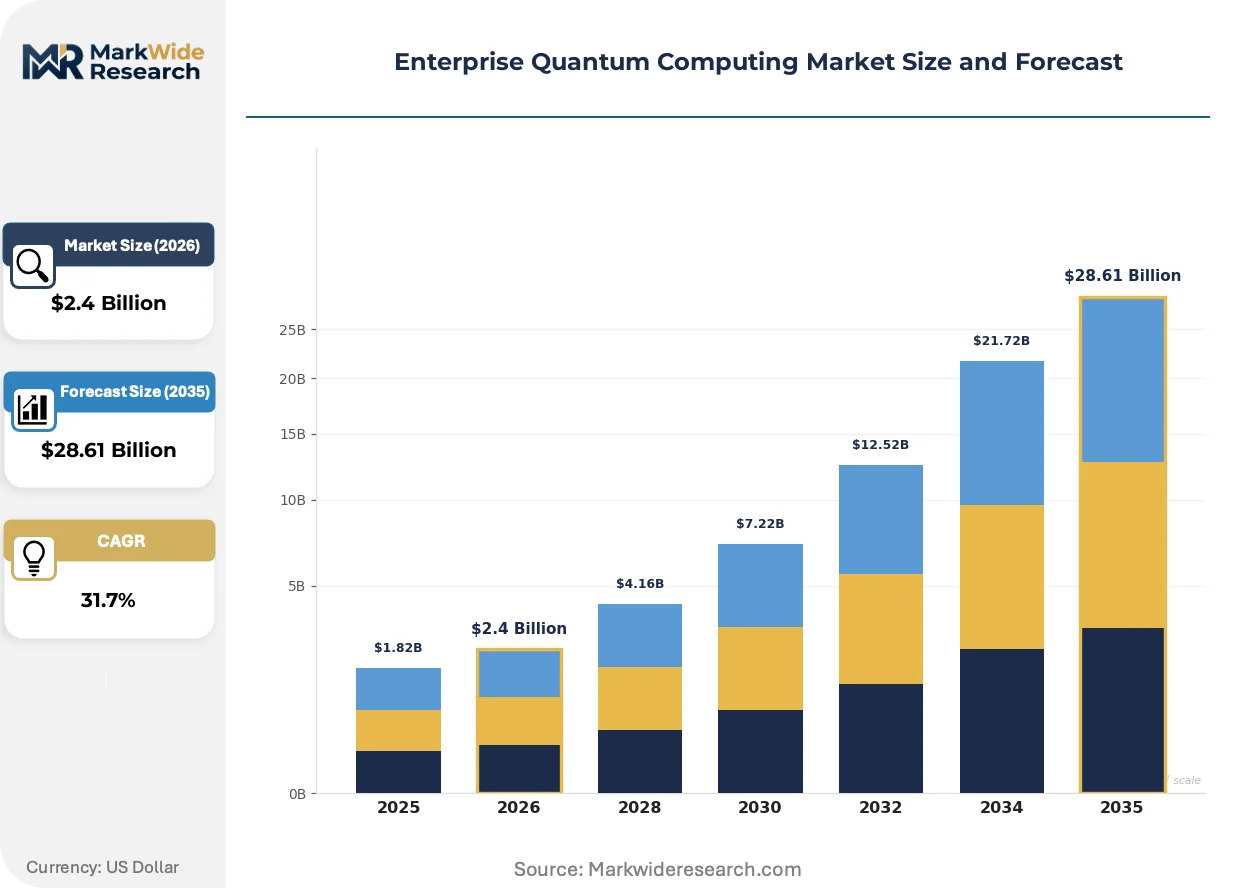
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $28.61 Billion |
| CAGR (2026 – 2036) | 31.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Quantum-as-a-Service Technology: Superconducting Qubits, Trapped Ions, Topological Qubits, Photonic Quantum Computing, Silicon Spin Qubits Application: Cryptography, Drug Discovery, Financial Modeling, Material Simulation, Supply Chain Optimization End User Industry: Banking & Finance, Aerospace & Defense, Telecommunications, Energy & Utilities |
| Companies Covered | IBM, Google, Microsoft, D-Wave Quantum Inc., Rigetti Computing, IonQ, Intel Corporation, Quantinuum, Amazon Web Services, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Enterprise Quantum Computing Market Strategic Shifts & Innovations
A fundamental re-evaluation of value is underway, shifting focus from raw hardware metrics like qubit count toward the demonstrated ability of a quantum system to solve specific, industry-defined benchmark problems. This performance-centric view is maturing the market beyond experimental curiosity.
Quantum error correction (QEC) codes are algorithms designed to protect quantum information from environmental noise and other errors. Hardware developers are now actively implementing rudimentary QEC protocols, moving them from theoretical concepts to physical reality. This evolution in active error management is expanding into the foundational work required for building fault-tolerant quantum computers capable of solving large-scale commercial problems.
The post-quantum cryptography (PQC) standardization process led by the United States National Institute of Standards and Technology (NIST) is creating a global mandate for cryptographic modernization. This initiative compels organizations to inventory all systems using public-key cryptography and prepare for a transition to new, quantum-resistant algorithms. The financial services and government sectors are most affected, accelerating pilot programs to safeguard sensitive data against future quantum threats.
A distinct change in enterprise consumption models favors access over ownership. The Quantum-as-a-Service (QaaS) model, delivered via major cloud providers, is displacing direct hardware acquisition by lowering the barrier to entry and enabling experimentation without massive capital outlay. This trend is most prominent in North America and Europe, where enterprises can access diverse quantum backends from competing hardware vendors through a single cloud interface.
Enterprise Quantum Computing Market Segmentation
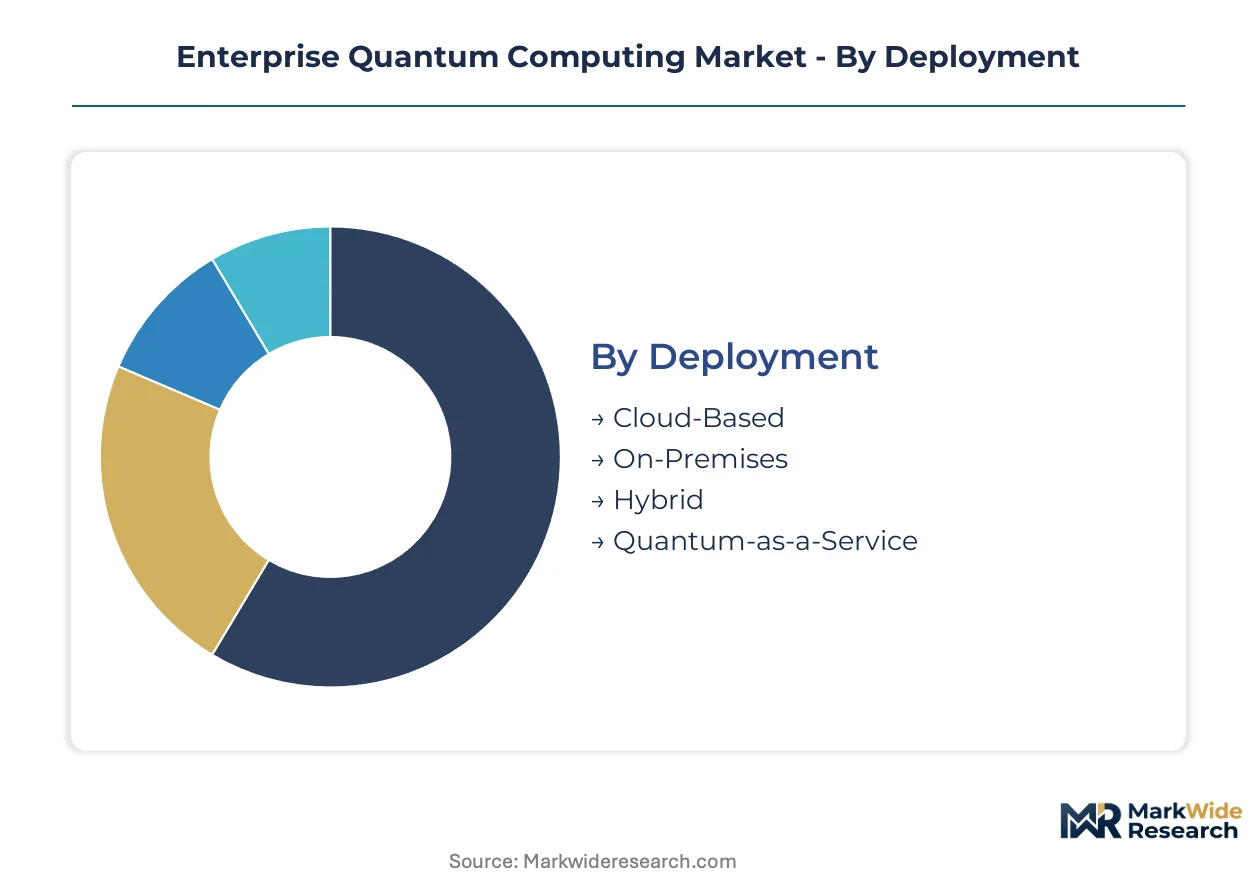
Market segmentation provides a critical framework for understanding the diverse operational models and technological preferences within enterprise quantum computing. Enterprises evaluate quantum solutions based on deployment flexibility, the underlying qubit technology, specific application benefits, and their industry's unique computational demands.
Deployment:
The supply of enterprise quantum computing capabilities increasingly concentrates through cloud-based platforms, offering scalable access without significant upfront capital investment. This model democratizes access to advanced quantum hardware for a broader range of businesses.
- Cloud-Based:This model provides remote access to quantum processors over the internet, enabling enterprises to execute quantum algorithms and experiment with different architectures without owning physical hardware. Demand for cloud access is concentrating across North America and Europe, driven by innovation hubs in the United States and Germany.
- Quantum-as-a-Service:QaaS platforms unbundle hardware from software, delivering integrated quantum computing resources, development tools, and support via a subscription model. This approach significantly lowers the barrier to entry for small and medium-sized enterprises seeking to explore quantum capabilities in countries like the United Kingdom.
- On-Premises:Direct acquisition and installation of quantum computing systems within an organization's own data centers, requiring substantial capital outlay and specialized infrastructure.
- Hybrid:Integration of a quantum processing unit (QPU) with classical high-performance computing (HPC) resources, strategically allocating tasks between quantum and classical systems.
Today's leader: Cloud-Based. Tomorrow's challenger: Quantum-as-a-Service.
Technology:
Enterprises select quantum technology based on its maturity, error rates, and suitability for specific computational challenges, with different qubit types offering distinct performance characteristics for various applications.
- Superconducting Qubits:These qubits operate at ultra-low temperatures, utilizing superconducting circuits for information processing, and are a primary focus for gate-based quantum computers. IBM and Google are major developers, leveraging these for complex simulations and optimization tasks.
- Trapped Ions:Individual ions held by electromagnetic fields serve as qubits, offering long coherence times and high fidelity operations, making them suitable for high-precision quantum computations. Companies like IonQ are advancing this technology for quantum chemistry and secure communication.
- Topological Qubits:These theoretical qubits aim to encode information in non-local properties of matter, offering intrinsic error resistance, a critical advantage for fault-tolerant quantum computing.
- Photonic Quantum Computing:This approach uses photons as qubits, leveraging optical components for computation, offering potential for room-temperature operation and high-speed data transfer.
- Silicon Spin Qubits:Silicon-based qubits leverage the spin of individual electrons, offering compatibility with existing semiconductor manufacturing techniques and potential for high scalability.
Superconducting Qubits represent the fastest-growing trajectory, while Photonic Quantum Computing shows significant potential for future applications.
Application:
The choice of quantum application by end-users depends heavily on the specific business problems that current quantum hardware can address more efficiently than classical methods, focusing on areas with high computational complexity.
- Financial Modeling:Quantum algorithms offer significant advantages for complex risk analysis, derivative pricing, and portfolio optimization, providing faster and more accurate results for financial institutions globally. Demand is particularly strong in major financial centers like New York and London.
- Drug Discovery:Quantum computing can simulate molecular interactions at a fundamental level, accelerating the identification of new drug candidates and optimizing existing compounds. Pharmaceutical companies in the United States and Switzerland are investing heavily in this area.
- Cryptography:Quantum algorithms pose a threat to current public-key encryption standards, driving demand for post-quantum cryptography development and implementation by government agencies and defense contractors.
- Material Simulation:Simulating material properties at the quantum level can lead to the discovery of new materials with enhanced characteristics for industries such as manufacturing and energy.
- Supply Chain Optimization:Quantum annealing and gate-based algorithms can solve complex logistics and scheduling problems, improving efficiency across global supply chains.
Financial Modeling currently drives the largest volume of enterprise engagement, with Drug Discovery showing a rapid increase in computational demand.
End User Industry:
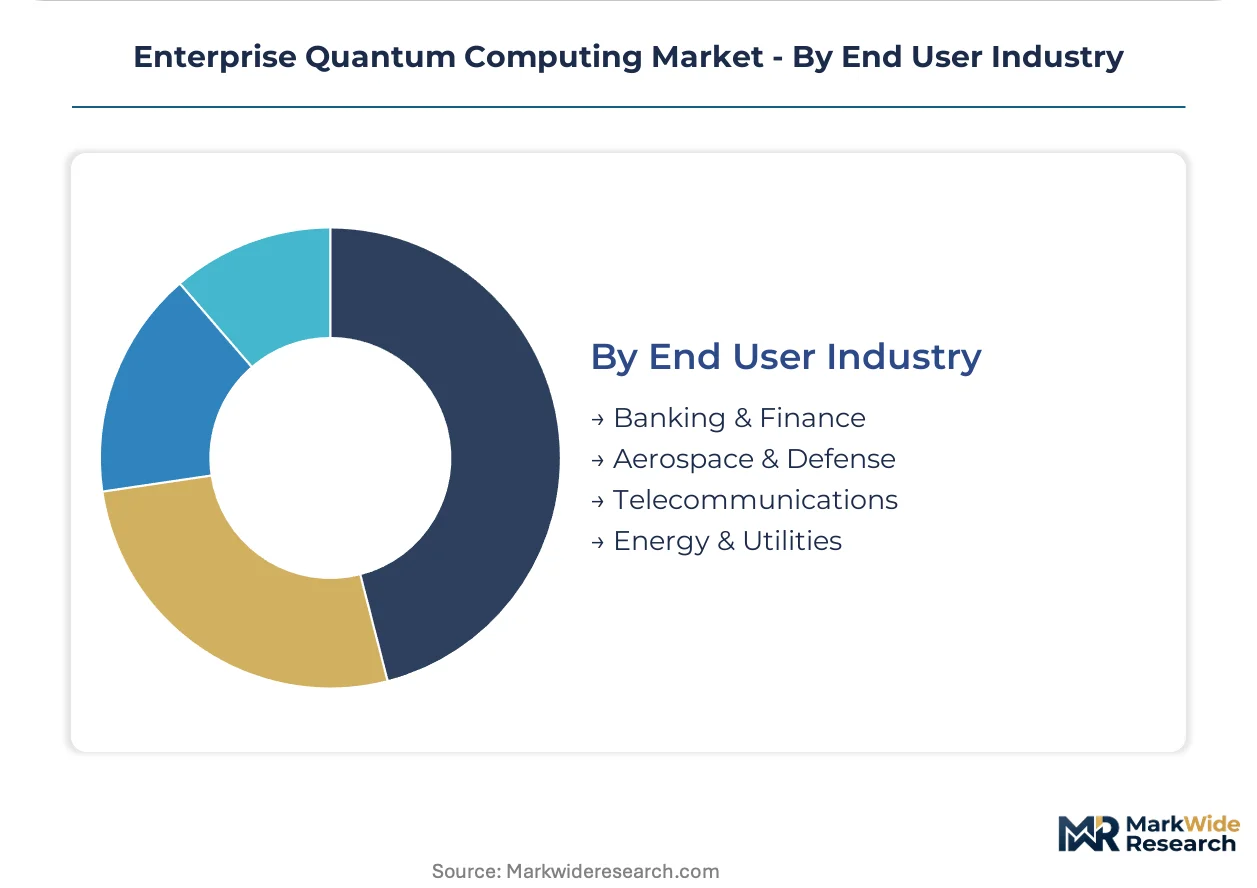
Different industries adopt enterprise quantum computing based on their inherent need for advanced computational power, the criticality of data security, and the potential for transformational impact on their core business processes.
- Banking & Finance:This sector utilizes quantum computing for fraud detection, high-frequency trading optimization, and complex risk management, where computational speed directly impacts market advantage. Financial institutions in Japan and Singapore are exploring these capabilities.
- Aerospace & Defense:Quantum computing applications include secure communications, advanced material design for aircraft, and optimization of complex logistical operations, crucial for national security and technological superiority. Governments in the United States and China prioritize this domain.
- Telecommunications:Quantum solutions enhance network optimization, improve data encryption for secure communication, and accelerate the development of next-generation communication protocols.
- Energy & Utilities:This industry applies quantum computing to optimize smart grids, improve energy storage solutions, and simulate new materials for more efficient energy generation.
Banking & Finance currently demonstrates the highest margin potential for quantum service providers, while Aerospace & Defense commands significant strategic investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Quantum computing's foundational principles emerged from theoretical physics in the mid-20th century, with significant scaling and commercialization efforts accelerating in the 21st. Early breakthroughs in qubit development and algorithm design primarily stemmed from university research and government-funded initiatives. This historical lineage established key regions as epicenters for quantum innovation.
United States
Demand for quantum algorithms in drug discovery and national security applications is substantial. The National Institute of Standards and Technology (NIST) drives post-quantum cryptography standards. Silicon Valley and Boston serve as technology hubs, fostering collaboration between startups and major tech firms.
Germany
Enterprise adoption in the financial sector for risk analysis and optimization tasks is a strong driver. The EU AI Act may introduce compliance obligations for quantum machine learning. Munich and Dresden are emerging centers, attracting investment in quantum hardware development.
Japan
Financial institutions in Japan seek quantum solutions for high-frequency trading and portfolio optimization. The Ministry of Economy, Trade and Industry (METI) supports quantum technology research. Tokyo's financial district and research institutes actively pilot quantum applications.
China
Government-backed initiatives drive demand for quantum computing in aerospace & defense and secure communications. National security export controls restrict sensitive quantum technology transfers. Beijing and Shanghai host significant national laboratories and quantum research facilities.
United Kingdom
Small and medium-sized enterprises (SMEs) access quantum capabilities through Quantum-as-a-Service platforms. The UK government actively funds quantum technology programs. London's financial hub and university spin-outs focus on quantum software development.
Enterprise Quantum Computing Market Key Industry Players
Premium-margin players sit above commodity-margin players across hardware performance and software integration in enterprise quantum computing. The market structure reveals a tiered landscape, with few full-stack providers and numerous specialized hardware or software developers. Three strategic archetypes define the competitive terrain: integrated solution providers offering end-to-end solutions, niche hardware specialists focusing on specific qubit technologies, and cloud-based QaaS platforms democratizing access. Companies pursue strategic partnerships for ecosystem expansion and technology licensing to broaden market reach and accelerate innovation.
Within the full-stack provider archetype, IBM exemplifies integrated solutions, offering everything from processor design to cloud access for diverse enterprise needs. D-Wave Quantum Inc. occupies a specialized position, focusing on annealing-based computers tailored for specific optimization tasks like logistics and financial modeling. Google represents a major player advancing gate-based superconducting qubit systems, often accessible through cloud platforms for advanced research. These entities anchor distinct segments of the market, influencing technology development and service delivery models. Their varied approaches highlight the diverse pathways to quantum capability for enterprises across different computational requirements.
| Leading Market Players |
|---|
| IBM |
| Microsoft |
| D-Wave Quantum Inc. |
| Rigetti Computing |
| IonQ |
| Intel Corporation |
| Quantinuum |
| Amazon Web Services |
| Others |
Cost & Logistics Intelligence
Demand for demonstrated performance on specific industry-relevant benchmark problems forces hardware and software providers to invest heavily in R&D, impacting the cost structure and ultimately the pricing of quantum solutions. This shift elevates the value of proven computational capability over raw hardware metrics.
Pricing Analysis
Subscription-based Quantum-as-a-Service (QaaS) models dominate enterprise quantum computing pricing, offering tiered access to computational resources. Price differentiation stems from the quantum volume of the accessible hardware and the level of integrated software support. Pricing pressure stems from the increasing competition among QaaS providers and the ongoing need for enterprises to justify ROI. Financial institutions, early adopters, show lower price sensitivity for mission-critical applications, while smaller enterprises prioritize cost-effective experimentation.
Supply Chain Analysis
Logistics and freight costs for specialized cryogenic cooling systems and high-precision optical components contribute to the overall cost of quantum hardware deployment. Geographic supply concentration for advanced semiconductor components centers on countries like the United States, Taiwan, and South Korea. Raw material dependencies include specialized rare earth elements for trapped ions and high-purity superconducting materials. A structural risk involves export controls, particularly from the United States and China, which restrict sensitive technology transfers. Distribution runs through cloud providers offering QaaS platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is increasingly a late-cycle quality story, as enterprises shift demand toward quantum systems that demonstrate superior performance on specific, industry-relevant benchmark problems. The focus is now on proven, reliable computational outcomes rather than theoretical potential.
For Market Incumbents: Cement full-stack development capabilities by integrating advanced error correction protocols into existing hardware and software platforms. This counters the threat from specialized niche hardware players and emerging open-source software initiatives. Invest in talent development through university partnerships, leveraging government R&D funding as a key lever to maintain a competitive edge.
For New Entrants and Emerging Players: Capture market share by specializing in high-fidelity qubit technologies like trapped ions for quantum chemistry applications. The drug discovery segment in the United States and Switzerland represents a penetrable market due to high computational demand. A strong go-to-market angle involves offering highly optimized, application-specific quantum algorithms via QaaS platforms.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized software developers and algorithm providers who can abstract hardware complexity for end-users. Long-term viability hinges on companies demonstrating verifiable quantum advantage for specific enterprise problems. The signal to watch is the successful deployment of fault-tolerant quantum error correction in commercial systems.
| Strategic Initiative | Industry Significance |
|---|---|
| Integrate Quantum Error Correction | This enhances qubit stability and extends computation duration for complex enterprise problems. |
| Expand QaaS Platform Offerings | Democratizes access to quantum hardware, lowering entry barriers for diverse enterprise users. |
| Invest in Post-Quantum Cryptography | Safeguards sensitive data against future quantum threats, crucial for financial and government sectors. |
| Form University Research Partnerships | Accelerates foundational science and builds a pipeline of specialized quantum talent. |
| Develop Hybrid Computing Solutions | Optimizes computational efficiency by allocating tasks between quantum and classical systems. |
Research Approach
Bottom-up financial modeling and drug discovery application modeling reconciled against top-down hardware and software supply-side tracking forms the analytical core of this study. Primary research involved in-depth interviews with quantum physicists, algorithm developers, enterprise CTOs, and government research leads. Secondary validation drew from NIST post-quantum cryptography standards, EU AI Act documentation, and corporate financial filings. Triangulation across these sources ensures robust market sizing.
An input-output matrix drives the quantitative analysis, projecting market evolution across the analysis window. Segmentation dimensions modeled include deployment model, qubit technology, application area, and end-user industry, alongside regional adoption patterns. Compound annual growth rates were derived from historical trends, technological advancement trajectories, and projected enterprise investment. Key forecast inputs include estimated quantum volume improvements and enterprise digital transformation budgets.
Underlying measurement precision varies by segment; financial modeling and drug discovery carry tighter precision than others due to established enterprise engagement. Forecasts reflect assumptions regarding technological breakthroughs and regulatory shifts. Export controls and qubit decoherence are specific risk factors that could revise future projections. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Next Generation Technologies
Nigeria ICT Market
Next Generation Technologies
Smart Surfaces Market
Next Generation Technologies
Europe Quantum Computing Market
Next Generation Technologies
Bulgaria ICT Market
Next Generation Technologies
Global Next Generation Wireless Communication Market
Next Generation Technologies
GCC ICT Market
Next Generation Technologies
Nearfield Communication (NFC) Market
Next Generation Technologies
Quantum Computing Market
Next Generation Technologies
Next-Generation Communication Devices Market
Next Generation Technologies
Malaysia ICT Market
Next Generation Technologies
Hyperloop Technology Market
Next Generation Technologies
Information and Communications Technology (ICT) Market
Next Generation Technologies
M2M Connections Market
Next Generation Technologies
Jordan ICT Market
Next Generation Technologies
Next Generation Network (NGN) Equipment Market
Next Generation Technologies
Japan ICT Market