
 Poc Platform and Technology Market | 2026-2036
Poc Platform and Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Poc Platform and Technology Market Outlook
EU MDR and IVDR compliance requirements for decentralized diagnostics is broadening the addressable market for manufacturers willing to certify connected platforms. Abbott Laboratories leverages its vertically integrated manufacturing footprint to sustain cost advantages across instrument and consumable production. Roche anchors its position through deep R&D investment in molecular diagnostics miniaturization. Siemens Healthineers competes on integrated health informatics that bridge acute and ambulatory settings.
Point-of-care platforms and technologies encompass portable diagnostic systems, connected data infrastructure, and cloud-enabled analytics that deliver clinical-grade results outside centralized laboratories, typically operating with sample-to-answer workflows under 30 minutes and bidirectional EHR integration. The primary purpose is to compress diagnostic turnaround time while maintaining analytical performance equivalent to laboratory analyzers. Cloud-based and hybrid technology deployments are capturing disproportionate investment as health systems prioritize interoperability and remote monitoring capabilities. Healthcare institutions represent the dominant end-user segment, though startup-driven innovation in open-source architectures is creating new channel dynamics that challenge incumbent pricing power.
FDA 510(k) and CLIA waiver pathways govern US market entry, while EU MDR and IVDR establish conformity benchmarks across European member states, collectively elevating validation costs but also filtering out lower-reliability entrants. Health Canada and Japan's PMDA maintain similarly stringent premarket review frameworks that shape global product roadmaps. Stakeholders must weigh regulatory capital intensity against the margin compression risk of remaining in legacy laboratory-centric models without platform diversification.
Market Dynamics
CLIA-waived molecular diagnostics are compressing validation timelines and forcing manufacturers to reconfigure R&D pipelines around decentralized regulatory pathways rather than centralized laboratory benchmarks.
Growth Catalysts
- FDA 510(k) Streamlining:Accelerated premarket review for multiplex respiratory panels is pulling assay developers toward infectious disease applications with shorter time-to-revenue cycles.
- Cloud-Enabled Analytics:Bidirectional EHR integration requirements from hospital procurement committees are elevating platform bids that include native interoperability modules.
- Germany:The country's statutory health insurance reimbursement reforms for ambulatory diagnostics are expanding addressable volume for connected care platforms in outpatient networks.
Market Restraints
- Reagent Supply Concentration:Lyophilized enzyme production concentrates among three contract manufacturers in Switzerland and Singapore, creating input vulnerability for mid-scale assay developers.
- EU IVDR Technical Documentation:Expanded clinical evidence requirements for Class C devices are extending conformity assessment timelines and freezing product line extensions.
- Optical Component Substitution:CMOS sensors are displacing traditional photomultiplier tubes in fluorescence detection, forcing instrument architecture redesigns for incumbent platforms.
Strategic Opportunities
- India:CDSCO's phased implementation of medical device rules for in-vitro diagnostics is opening registration pathways for previously unregulated point-of-care categories.
- Microfluidics-AI Convergence:Real-time image analysis at the cartridge level is enabling instrument-free result interpretation for resource-limited settings.
- Direct-to-Employer Contracts:Occupational health screening programs are bypassing traditional distributor networks and contracting directly with platform manufacturers for on-site testing infrastructure.
Industry Challenges
- Multidisciplinary Talent Scarcity:The intersection of assay chemistry, embedded firmware, and clinical regulatory science requires hybrid skill sets that remain scarce in regional hiring markets.
- Legacy LIS Integration:Hospital information systems built on HL7 v2 messaging protocols demand custom middleware development for cloud-native point-of-care platforms.
- Patent Thicket Navigation:CRISPR-based detection methods face overlapping intellectual property claims across university licensing offices and commercial holders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Poc Platform and Technology Market |
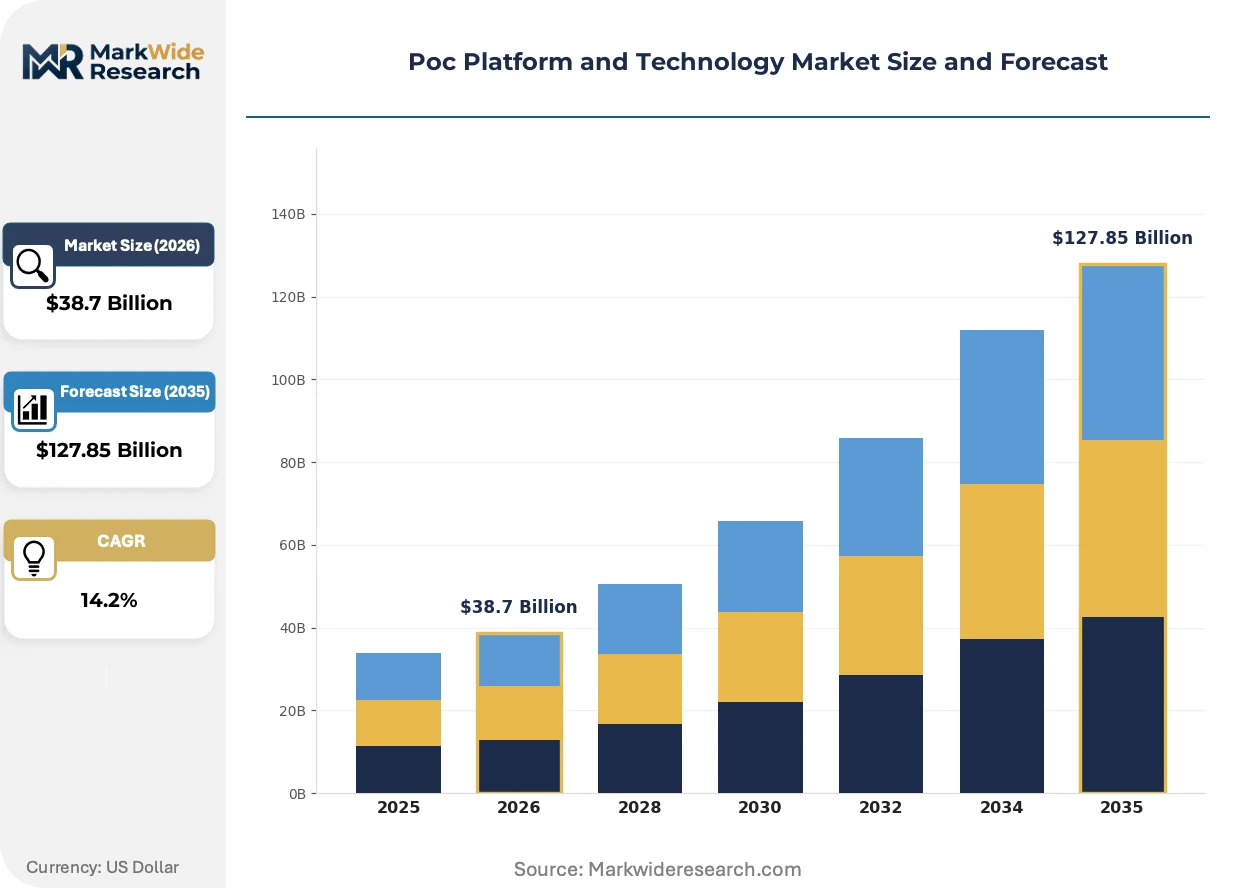
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $127.85 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Cloud-Based, On-Premises, Hybrid, Open Source Deployment Model: Public Cloud, Private Cloud, Multi-Cloud, Community Cloud End User: Healthcare Institutions, Educational Institutions, Corporates, Startups Service Type: Consulting, Support, Integration, Maintenance |
| Companies Covered | Abbott Laboratories, Roche, Siemens Healthineers, Becton, Dickinson and Company, Danaher, bioMérieux, LumiraDx, Co-Diagnostics, Vital Biosciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Poc Platform and Technology Market Strategic Shifts
Sample-to-answer workflow compression is redefining competitive moats around speed-to-result rather than analytical sensitivity alone, with regulatory science now trailing instrument engineering cycles.
Cartridge-based nucleic acid amplification is consolidating previously discrete preparation, amplification, and detection steps into sealed single-use consumables. Emergency departments in tertiary hospitals are adopting these platforms for bloodstream infection identification within 60 minutes of draw. The technology is consolidating vendor relationships around integrated instrument-consumable contracts that lock out modular competitors.
EU MDR Article 10 post-market surveillance requirements are mandating systematic collection of real-world performance data across installed device bases. Manufacturers must now fund prospective registry studies or risk certificate suspension during renewal audits. Class C in-vitro diagnostic device holders with legacy CE-IVDD certifications are most affected, with many accelerating IVDR transition timelines to avoid supply interruption.
Hospital procurement committees are unbundling instrument placement from reagent supply agreements, separating capital acquisition from consumable commitment. Group purchasing organizations are capturing this disintermediation by negotiating multi-hospital platform contracts that override individual site preferences. The United States exhibits this pattern most visibly, where integrated delivery networks now mandate interoperability certification as a gate for vendor qualification.
Poc Platform and Technology Market Segmentation
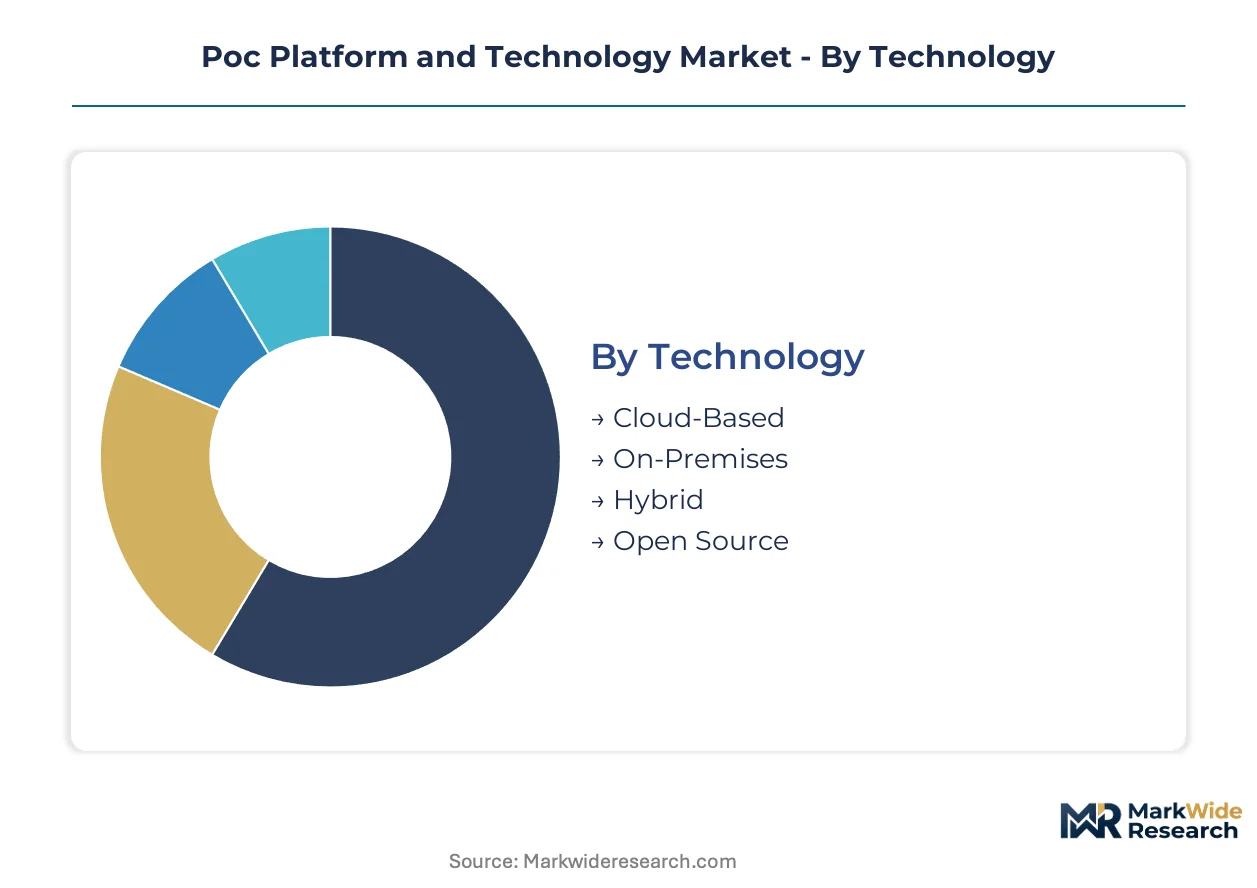
Point-of-care platform segmentation reveals how procurement priorities diverge across buyer sophistication levels and infrastructure maturity. Technology choices determine regulatory pathway complexity, while deployment models reflect institutional risk tolerance toward data sovereignty.
Technology:
Buyers in this category differentiate by interoperability requirements and capital deployment preferences.
- Cloud-Based:Fully managed infrastructure with native HL7 FHIR connectivity and automatic software updates. Demand concentrates in United States integrated delivery networks where CMS interoperability mandates drive procurement specifications. Bidirectional EHR integration has become a non-negotiable requirement for hospital committee approval.
- Hybrid:Split architecture retaining sensitive processing on-premises while leveraging cloud analytics for population health dashboards. Germany's statutory health insurance funds favor this model for ambulatory networks requiring local data residency with centralized reporting.
- On-Premises:Air-gapped systems for high-security environments with complete institutional control over update cycles. Military and correctional health facilities in the United States specify these configurations.
- Open Source:Modular architectures allowing custom assay development without licensing fees. Startup-driven innovation clusters in India leverage CDSCO's new IVD registration pathways to commercialize locally adapted platforms.
Volume sits with Cloud-Based; growth tilts toward Hybrid.
Deployment Model:
Institutional scale and patient volume determine infrastructure architecture choices in this category.
- Private Cloud:Dedicated tenant environments with single-institution data isolation and custom SLA terms. Large tertiary hospitals in China under NMPA cybersecurity guidelines mandate these deployments for molecular diagnostics data.
- Multi-Cloud:Distributed workloads across two or more hyperscaler environments to mitigate vendor lock-in and ensure continuity. Health systems in the United States with multi-state footprints adopt this model to satisfy divergent state privacy regulations.
- Public Cloud:Shared infrastructure with pay-per-test economics and minimal IT overhead. Federally qualified health centers with constrained capital budgets favor this approach for infectious disease screening programs.
- Community Cloud:Collaborative infrastructure serving affiliated provider networks with standardized assay menus. Regional hospital alliances in Germany deploy these for coordinated antibiotic stewardship across member institutions.
Private Cloud captures the largest installed base; Multi-Cloud is climbing the fastest as procurement committees unbundle vendor relationships.
End User:
Budget authority and workflow integration complexity separate buyers across this category.
- Healthcare Institutions:Acute care hospitals, outpatient clinics, and long-term care facilities with established quality management systems. These buyers dominate procurement volume and drive CLIA-waiver pathway demand for decentralized molecular testing.
- Corporates:Occupational health departments and on-site wellness programs seeking direct contracts bypassing traditional distribution. Direct-to-employer agreements are reshaping channel economics for platform manufacturers.
- Educational Institutions:University medical centers and research hospitals with dual clinical-research missions requiring flexible assay development environments.
- Startups:Emerging diagnostic companies leveraging open-source architectures to compress development timelines and avoid incumbent licensing structures.
Healthcare Institutions anchor current revenue; Corporates are gaining share fastest through occupational health bypass of distributor networks.
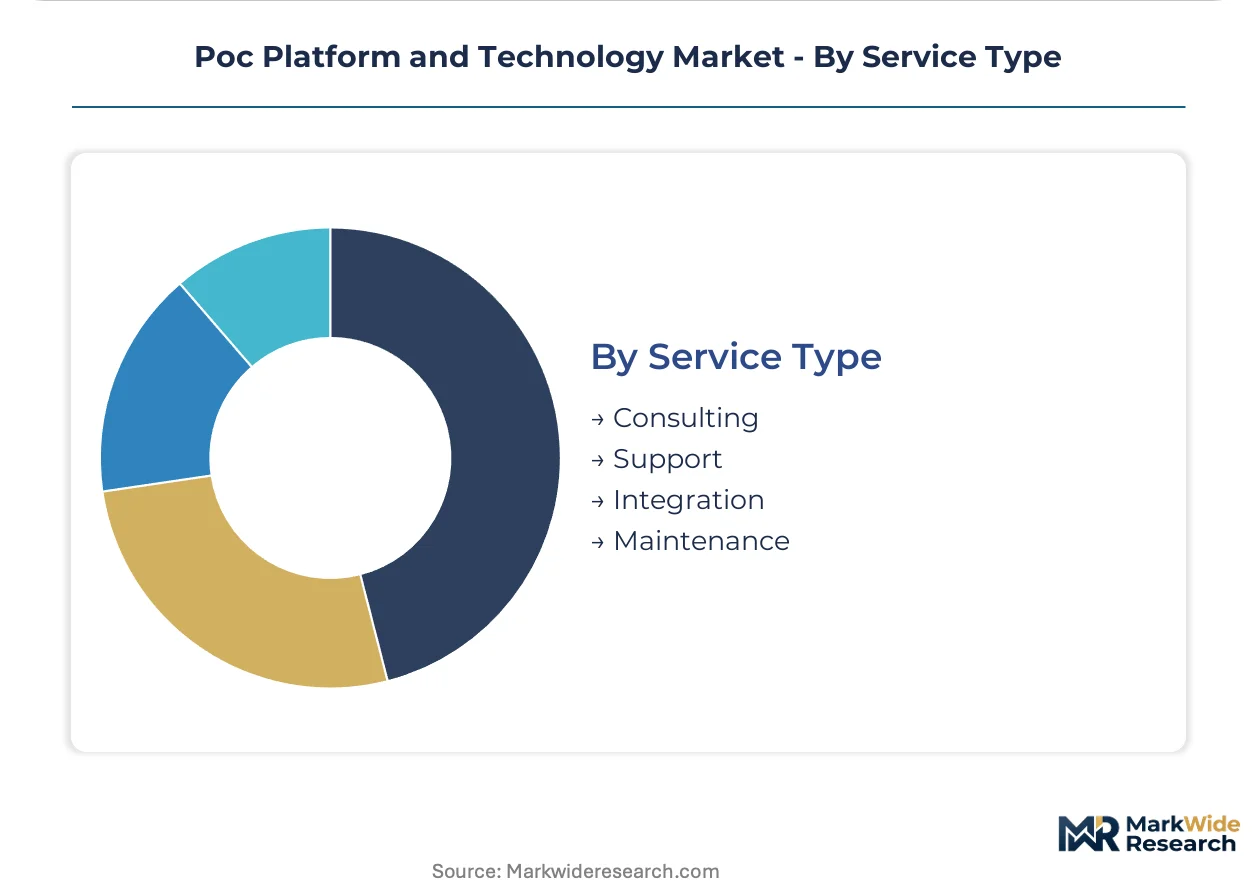
Service Type:
Internal technical capacity gaps determine which service layers buyers externalize versus retain in-house.
- Integration:Middleware development connecting cloud-native platforms to legacy LIS infrastructure built on HL7 v2 protocols. Hospital information system fragmentation creates persistent demand for custom interface engineering.
- Support:Tiered response contracts covering instrument calibration, assay troubleshooting, and regulatory documentation updates. EU IVDR technical documentation requirements are extending support contract durations.
- Consulting:Workflow redesign and staff training for sample-to-answer platform adoption in emergency department settings.
- Maintenance:Preventive service schedules and component replacement programs ensuring CLIA compliance for waived devices.
Integration commands premium pricing; Support exhibits the steepest expansion trajectory as IVDR transition timelines compress.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's biotech corridor anchors North American point-of-care platform development, with venture deployment clustering around Kendall Square and Seaport innovation districts. Germany's Ruhr Valley and China's Yangtze River Delta host comparable manufacturing density for decentralized diagnostic systems.
United States
FDA 510(k) streamlining for multiplex respiratory panels accelerates assay developer migration toward infectious disease applications. CMS interoperability mandates drive integrated delivery network procurement specifications toward bidirectional EHR integration. Greater Boston hosts the densest startup concentration for microfluidics-AI convergence platforms.
Germany
Statutory health insurance reimbursement reforms expand ambulatory diagnostic volumes for connected care platforms across outpatient networks. EU MDR and IVDR compliance requirements elevate validation costs while filtering lower-reliability entrants from the market. The Ruhr Valley maintains concentrated lyophilized enzyme production capacity serving European assay manufacturers.
China
NMPA cybersecurity guidelines mandate private cloud deployments for molecular diagnostics data in large tertiary hospitals. Domestic manufacturers compress cost structures for cartridge-based nucleic acid amplification systems. The Yangtze River Delta hosts the region's deepest precision manufacturing base for optical detection components.
India
CDSCO's phased medical device rules implementation opens registration pathways for previously unregulated point-of-care categories. Startup-driven innovation clusters leverage open-source architectures to commercialize locally adapted platforms. Hyderabad and Bangalore anchor the subcontinent's diagnostic platform engineering talent pools.
Japan
PMDA maintains stringent premarket review frameworks that shape global product roadmaps for platform manufacturers. Miniaturization R&D investment concentrates in Osaka-Kobe manufacturing corridors with deep precision instrumentation heritage. Corporate occupational health programs drive direct-to-employer contracting models bypassing traditional distribution channels.
Poc Platform and Technology Market Competitive Environment
The competitive structure tilts toward vertically integrated conglomerates with captive consumable production and established regulatory submission infrastructure. Three archetypes dominate: diversified life science conglomerates with deep assay chemistry libraries, precision instrumentation specialists with embedded firmware capabilities, and cloud-native platform startups leveraging open-source architectures. Consolidation pressure intensifies around integrated instrument-consumable contracts that lock out modular competitors, while strategic partnerships between microfluidics engineers and AI developers accelerate workflow compression timelines.
Among diversified life science conglomerates, Abbott Laboratories, Roche, and Siemens Healthineers occupy positions defined by manufacturing scale and regulatory capital depth. Abbott's vertically integrated footprint spans instrument and consumable production. Roche anchors molecular diagnostics miniaturization investment. Siemens Healthineers competes through integrated health informatics bridging acute and ambulatory settings.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Roche |
| Siemens Healthineers |
| Becton, Dickinson and Company |
| Danaher |
| bioMérieux |
| LumiraDx |
| Co-Diagnostics |
| Vital Biosciences |
| Others |
Value Chain & Pricing Dynamics
Hospital procurement committee unbundling of instrument placement from reagent supply agreements is forcing manufacturers toward transparent per-test economics and compressing margin structures across cloud-native platform tiers.
Pricing Analysis
Outcome-based pricing anchored to diagnostic throughput and CLIA compliance uptime dominates integrated delivery network contracts in the United States. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared molecular platforms from CE-IVDD legacy systems and open-source alternatives. Cost compression in mid-tier hybrid deployments is intensifying because group purchasing organizations negotiate multi-hospital contracts that override individual site preferences. Federally qualified health centers exhibit the sharpest price sensitivity, while military health facilities accept premium positioning for air-gapped security configurations.
Supply Chain Analysis
Single-source vulnerability sits with Swiss and Singaporean contract manufacturers controlling lyophilized enzyme production for nucleic acid amplification chemistries. Optical detection component manufacturing draws from China's Yangtze River Delta precision base, Germany's Ruhr Valley instrumentation corridor, and Japan's Osaka-Kobe miniaturization clusters. Tariff exposure on CMOS sensor imports from East Asian fabrication facilities threatens fluorescence detection platform cost structures. Distribution runs through integrated instrument-consumable contracts that lock hospital systems into multi-year exclusive supply arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU IVDR technical documentation requirements and extended conformity assessment timelines are accelerating consolidation pressure, forcing mid-scale assay developers toward acquisition or exit.
For Market Incumbents: Deploy captive consumable production capacity to defend margin position against modular competitors. Abbott Laboratories and Roche sustain cost advantages through backward integration into cartridge manufacturing, while Siemens Healthineers leverages health informatics integration to raise switching costs. Incumbents must accelerate IVDR transition timelines to avoid certificate suspension during renewal audits. For New Entrants and Emerging Players: CDSCO's phased medical device rules implementation in India opens a window for open-source platform commercialization in previously unregulated point-of-care categories. Microfluidics-AI convergence for instrument-free result interpretation offers the most penetrable white space in resource-limited settings. Direct-to-employer occupational health contracts bypass distributor margin extraction and accelerate revenue recognition. For Investors and Strategic Acquirers: The window for entry favors vertically integrated platform developers with established regulatory submission infrastructure and CLIA-waiver pathway expertise. Long-term viability hinges on cloud-native interoperability certification and bidirectional EHR integration capabilities. Watch for FDA 510(k) streamlining announcements on multiplex respiratory panels as an inflection signal for infectious disease assay developer valuations.| Strategic Initiative | Industry Significance |
|---|---|
| IVDR Transition Acceleration | Class C device holders avoiding supply interruption during certificate renewal audits gain procurement advantage. |
| Microfluidics-AI Platform Development | Real-time image analysis at cartridge level enables instrument-free deployment in India's emerging diagnostic networks. |
| Direct-to-Employer Contracting | Occupational health bypass of traditional distribution channels reshapes channel economics for platform manufacturers. |
| Hybrid Cloud Architecture Deployment | Germany's statutory health insurance funds favor split infrastructure for ambulatory networks requiring data residency. |
| Lyophilized Enzyme Supply Diversification | Reducing dependence on Swiss and Singaporean contract manufacturers mitigates input vulnerability for assay developers. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, cross-referenced with primary interviews with hospital procurement committee directors, biomedical engineers, GPO contracts managers, and CLIA laboratory directors. FDA 510(k) premarket notification databases, EU MDR and IVDR conformity assessment records, and CMS Medicare reimbursement schedules provided secondary validation. Bottom-up instrument and consumable volume estimates reconciled with top-down healthcare expenditure allocations across the analysis window.
Data-stream reconciliation across technology deployment models, end-user institutional scale, and regional regulatory clusters shaped the analytical framework. Cloud-based, hybrid, on-premises, and open-source architectures were modeled against healthcare institution, corporate occupational health, educational medical center, and startup developer segments. CAGRs derived from fitted growth curves incorporating NMPA cybersecurity guideline implementation timelines and CDSCO registration pathway phase-ins. Microfluidics-AI convergence adoption rates and cartridge-based nucleic acid amplification platform penetration supplied industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for cloud-native platform interoperability would alter the outlook if hospital information system fragmentation persists. Forecasts reflect assumptions around FDA streamlining maintenance and EU IVDR transition pacing. Deviation in lyophilized enzyme supply concentration or CMOS sensor tariff exposure would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Next Generation Technologies
Nearfield Communication (NFC) Market
Next Generation Technologies
Hyperloop Technology Market
Next Generation Technologies
Enterprise Quantum Computing Market
Next Generation Technologies
Global Next Generation Wireless Communication Market
Next Generation Technologies
Next Generation Wireless Network Market
Next Generation Technologies
Bulgaria ICT Market
Next Generation Technologies
Next-Generation Communication Devices Market
Next Generation Technologies
Ireland ICT Market
Next Generation Technologies
Quantum Information Processing Market
Next Generation Technologies
Europe Quantum Computing Market
Next Generation Technologies
Nigeria ICT Market
Next Generation Technologies
Information and Communications Technology (ICT) Market
Next Generation Technologies
5G New Radio Market
Next Generation Technologies
Japan ICT Market
Next Generation Technologies
Next Generation Network (NGN) Equipment Market
Next Generation Technologies
Malaysia ICT Market