
 Fog Computing Market | 2026-2036
Fog Computing Market Size, Share, and Industry Trends Forecast 2026-2036
Fog Computing Market Analysis
GDPR is hardening the cost-of-entry calculus for centralized cloud providers serving European industrial clients. Cisco Systems leverages its networking hardware dominance to anchor edge-node deployments across manufacturing corridors. IBM Corporation sustains competitive differentiation through its hybrid cloud integration layer bridging on-premises fog nodes with enterprise data centers. Dell Technologies specializes in ruggedized edge infrastructure purpose-built for factory-floor conditions.
Fog computing denotes a distributed computing paradigm that extends cloud capabilities to the network edge through localized data processing nodes typically operating within 10-20 milliseconds of endpoint devices. These nodes perform real-time analytics, protocol translation, and storage buffering to reduce bandwidth costs and latency for mission-critical operational technology systems. Industrial Automation and Vehicle Telematics represent the most structurally significant application segments, with the former commanding established margin pools in predictive maintenance and the latter accelerating fastest as autonomous driving validation demands sub-100-millisecond decision loops. Edge Analytics dominates the technology dimension where inference workloads outpace raw data transmission economics.
The EU AI Act, GDPR, and the Cyber Resilience Act collectively reshape product standards by mandating localized data governance and traceability for AI-enabled edge systems. Germany's BSI and France's ANSSI enforce national cybersecurity certification schemes that gate market access for foreign fog infrastructure vendors. Stakeholders must monitor divergence between EU harmonized standards and emerging national implementation acts as compliance fragmentation threatens interoperability across member-state deployments.
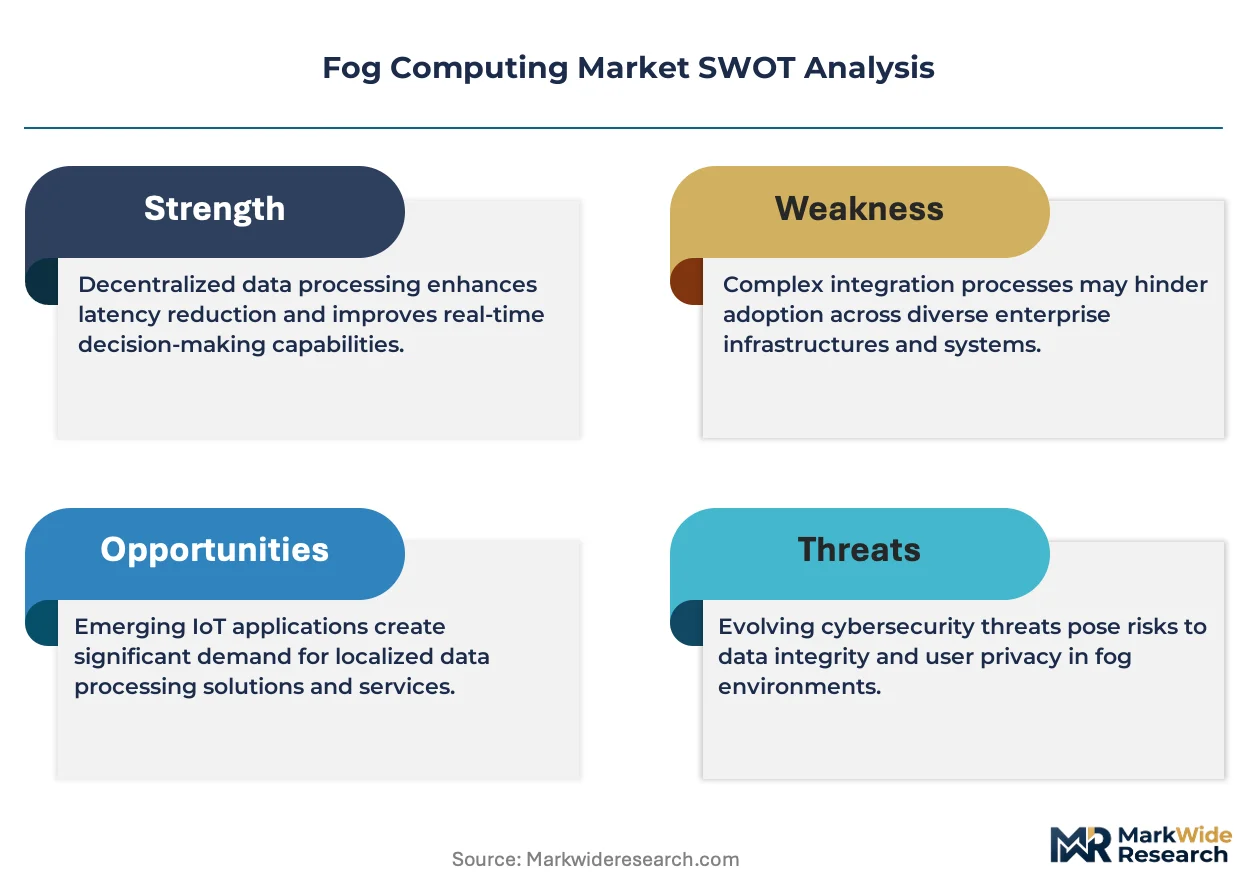
Market Dynamics
Latency requirements from autonomous vehicle validation loops and GDPR-mandated data localization are compressing cloud architectures toward distributed edge nodes. Industrial automation clusters in Germany and smart city deployments across France and Italy accelerate this structural migration.
Growth Catalysts
- EU AI Act compliance mandates:Localized inference and traceability requirements push AI-enabled operational technology systems toward fog architectures. Manufacturing facilities in Bavaria deploy edge nodes to satisfy algorithmic audit trails.
- Vehicle telematics validation:Sub-100-millisecond decision loops for autonomous driving systems demand distributed processing. German automotive testing corridors anchor regional fog infrastructure rollouts.
- Industrial predictive maintenance:Real-time vibration analytics on factory floors reduce unplanned downtime. Baden-Württemberg's automation clusters concentrate edge node deployment.
Market Restraints
- BSI certification timelines:Germany's federal cybersecurity agency enforces prolonged validation cycles for foreign fog hardware vendors. Market entry stretches 18-24 months.
- Edge hardware cost structure:Ruggedized industrial-grade servers command 3-4x premium over standard data center equipment. Factory-floor conditions necessitate specialized thermal and vibration tolerance.
- Interoperability fragmentation:Divergent national implementation acts across EU member states threaten cross-border deployment standardization. France's ANSSI and Italy's ACN maintain distinct certification pathways.
Strategic Opportunities
- France smart city expansion:Municipal governments in Lyon and Marseille deploy latency-sensitive traffic management systems. Public procurement channels open for edge infrastructure vendors.
- 5G-MEC convergence:Multi-access edge computing integration with fog nodes creates unified low-latency platforms. Telecom operators in Germany pilot converged architectures for industrial clients.
- Cyber Resilience Act tailwinds:Mandatory security-by-design requirements for connected devices favor established fog vendors with hardened supply chains. Certification advantages compound for early-compliant hardware.
Industry Challenges
- Edge-AI engineering scarcity:Specialized talent combining embedded systems, machine learning optimization, and OT security commands premium compensation. German technical universities struggle to graduate sufficient practitioners.
- Legacy SCADA integration:Brownfield manufacturing environments operate decades-old control systems with incompatible protocols. Fog node deployment requires costly middleware development.
- Fragmented vendor ecosystems:Proprietary management platforms from networking, server, and software suppliers complicate unified operations. Industrial buyers face integration overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fog Computing Market |
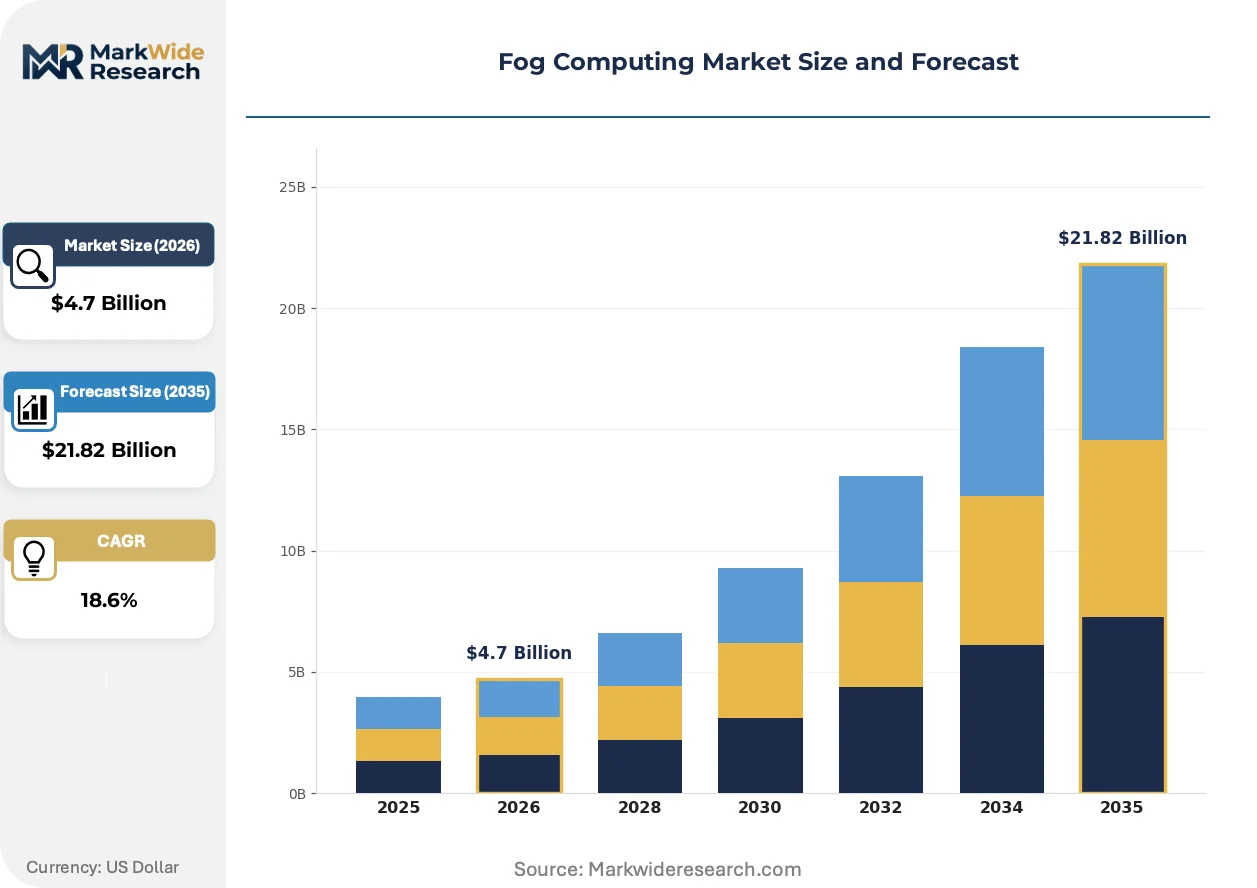
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $21.82 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Smart Cities, Industrial Automation, Vehicle Telematics, Healthcare Monitoring Technology: Edge Analytics, IoT Integration, Distributed Architecture, Security Solutions Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises End User: Telecommunications, Manufacturing, Transportation, Energy |
| Companies Covered | Cisco Systems, IBM Corporation, Dell Technologies, Microsoft Corporation, Intel Corporation, Fujitsu Limited, Huawei Technologies, ARM Holdings, GE Digital, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fog Computing Market Emerging Trajectories
Containerized microservices and Kubernetes-orchestrated edge workloads are displacing monolithic fog software stacks. European industrial buyers prioritize modular architectures that decouple hardware refresh cycles from application updates.
Microservices-based edge platforms is modularizing software deployment across heterogeneous hardware estates. German automotive suppliers adopt containerized analytics to isolate safety-critical from non-critical workloads on shared fog nodes. This architecture compresses certification scope and accelerates update cycles without full system revalidation.
The EU Cyber Resilience Act mandates vulnerability disclosure and automatic update mechanisms for connected edge devices. Hardware vendors must embed over-the-air capabilities and maintain decade-long security support commitments. Industrial automation buyers in France and Italy now require documented update pipelines as procurement gate criteria.
Buyers are unbundling hardware procurement from software licensing and managed services. German manufacturing conglomerates negotiate separate contracts for ruggedized servers, edge orchestration platforms, and predictive analytics subscriptions. This trisected purchasing pattern shifts vendor relationships from capital equipment sales toward recurring service engagements.
Fog Computing Market Segmentation
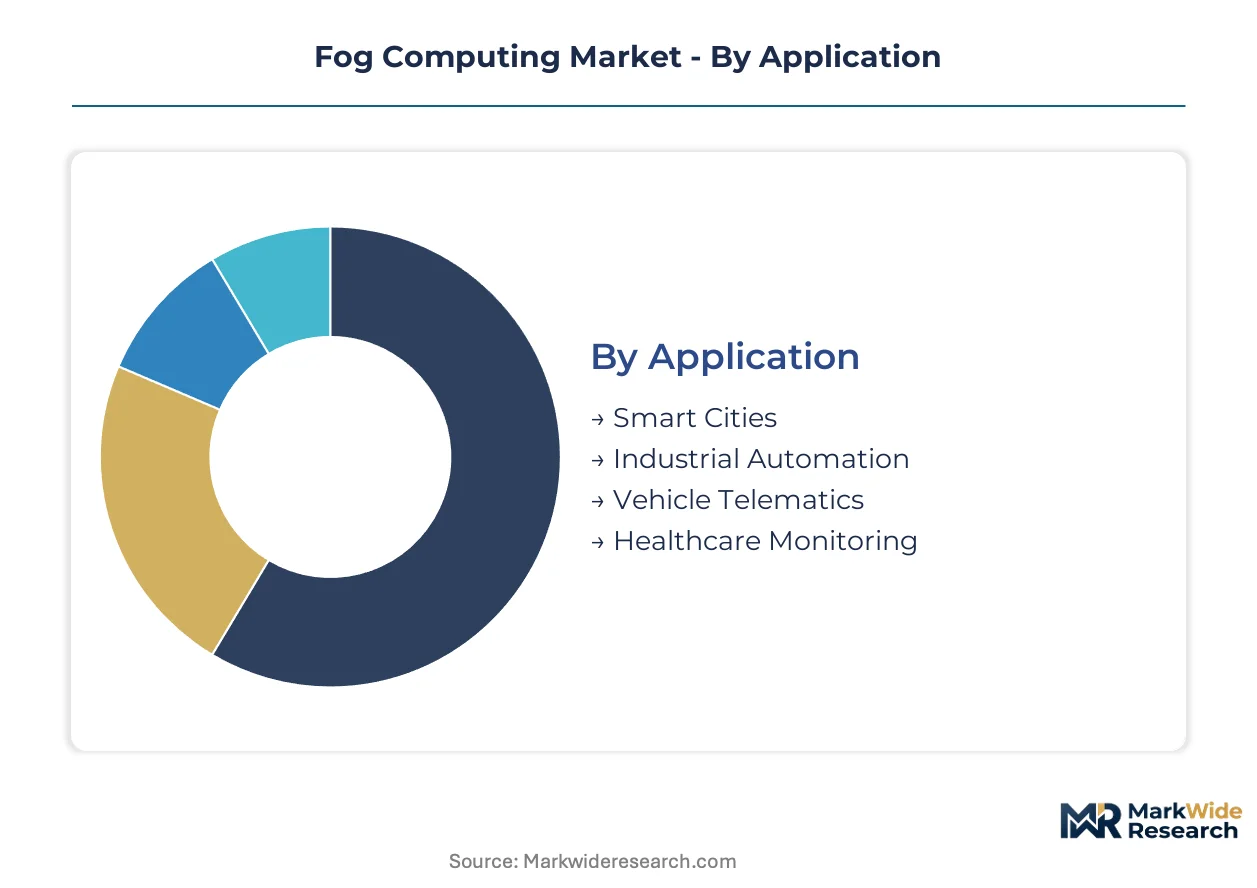
Fog computing architectures fragment across multiple technical and commercial axes, each commanding distinct procurement patterns and margin structures. Buyers prioritize latency specifications, data sovereignty requirements, and legacy integration complexity when selecting segment configurations. The analysis below maps these dimensions to deployment concentration and emerging demand pockets.
Application:
Technical performance thresholds and regulatory exposure determine application-level deployment economics.
- Industrial Automation:Predictive maintenance workloads process vibration and thermal telemetry at 10-20 millisecond latency. Baden-Württemberg manufacturing clusters anchor concentrated demand as GDPR-mandated data localization compels on-premise inference.
- Vehicle Telematics:Autonomous driving validation loops require sub-100-millisecond decision architectures. German automotive testing corridors in Bavaria and Lower Saxony drive specialized fog node deployment for real-time sensor fusion.
- Smart Cities:Municipal traffic management and public safety systems in Lyon and Marseille deploy latency-sensitive edge processing for congestion optimization.
- Healthcare Monitoring:Continuous patient telemetry systems in French university hospitals process biometric streams under CNIL data governance requirements.
Mature deployment sits with Industrial Automation. Newer deployment is concentrated in Vehicle Telematics.
Technology:
Capability scarcity and certification burden concentrate competitive differentiation at the technology layer.
- Edge Analytics:Inference workloads execute locally to minimize bandwidth costs and satisfy GDPR data minimization principles. Manufacturing facilities in Bavaria deploy containerized microservices to isolate safety-critical from operational analytics.
- IoT Integration:Protocol translation gateways bridge heterogeneous sensor networks to enterprise systems. France's smart city rollouts in Marseille standardize on MQTT and OPC-UA convergence layers for vendor interoperability.
- Distributed Architecture:Federated node orchestration enables workload mobility across edge clusters. German telecom operators pilot 5G-MEC convergence for industrial latency guarantees.
- Security Solutions:Hardware root-of-trust and encrypted enclaves address EU Cyber Resilience Act mandates. BSI certification requirements in Germany extend validation timelines for foreign security module vendors.
Edge Analytics commands established margin pools. Security Solutions faces steepest expansion trajectory from regulatory tailwinds.
Deployment Model:
Data sovereignty risk and capital efficiency trade-offs shape deployment model selection across regulated industries.
- Hybrid Cloud:Workload portability between on-premise fog nodes and centralized cloud reserves operational flexibility. IBM's integration layer bridges edge inference with enterprise data lake archival for German automotive suppliers.
- Private Cloud:Dedicated infrastructure satisfies GDPR Article 32 security requirements and algorithmic audit trails under EU AI Act. Baden-Württemberg automation clusters favor capex-heavy private deployments for IP protection.
- On-Premises:Fully localized processing eliminates third-party data exposure for critical infrastructure operators. French energy utilities deploy air-gapped fog nodes for grid control system isolation.
- Public Cloud:Shared edge resources serve latency-tolerant workloads with lower compliance exposure. Italian smart city pilots experiment with public edge zones for non-sensitive traffic analytics.
Hybrid Cloud captures manufacturing procurement preference. On-Premises gains share fastest from critical infrastructure hardening.
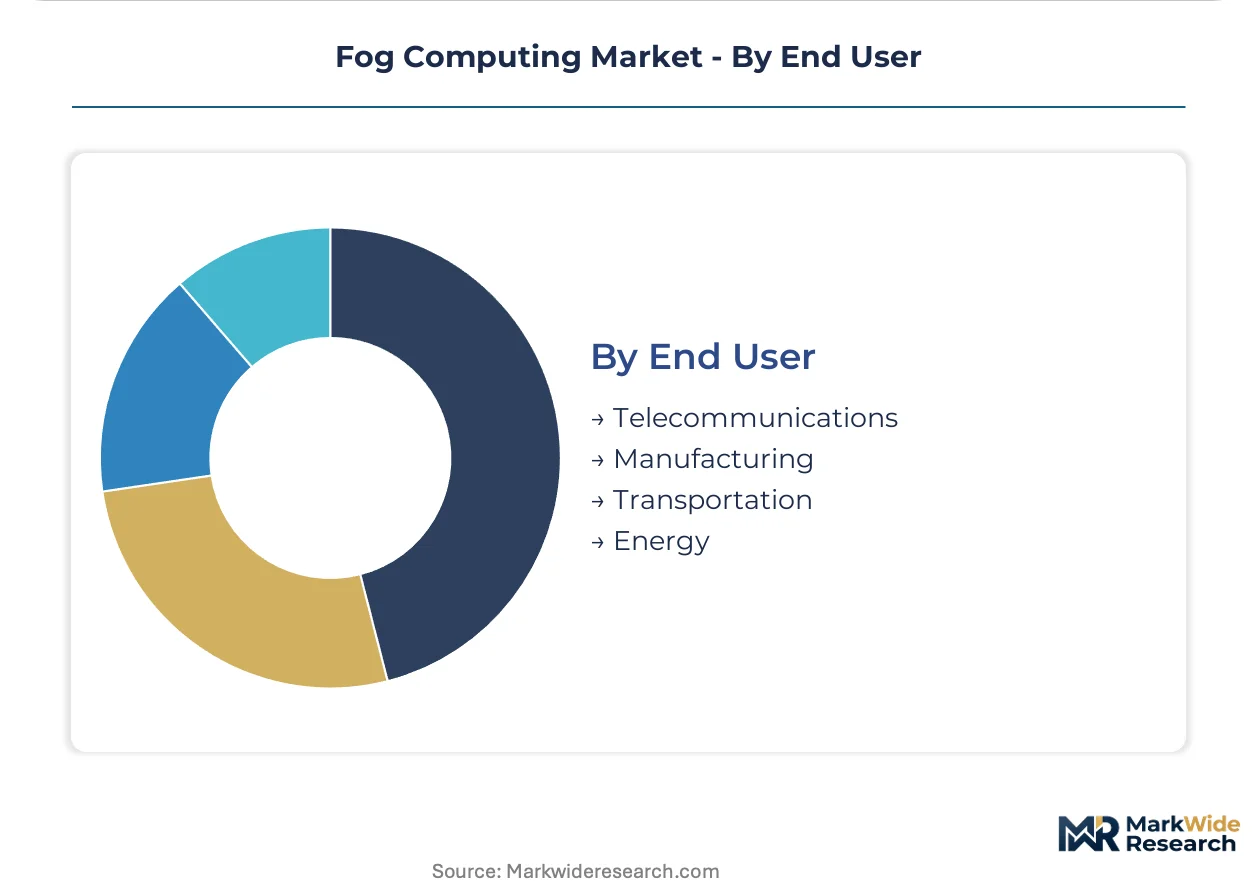
End User:
Operational technology maturity and regulatory scrutiny intensity vary sharply across end-user verticals.
- Manufacturing:Brownfield automation environments demand protocol adaptation for decades-old SCADA systems. Dell's ruggedized servers tolerate thermal and vibration stress on Bavarian factory floors.
- Telecommunications:5G network slicing and multi-access edge computing convergence create unified low-latency platforms. Deutsche Telekom pilots integrated fog-MEC architectures for industrial clients.
- Transportation:Connected vehicle infrastructure and logistics optimization drive distributed processing demand. German autobahn digitization projects deploy roadside fog nodes for cooperative intelligent transport systems.
- Energy:Distributed generation monitoring and grid stability analytics require sub-second response loops. France's RTE and Italy's Terna trial edge nodes for renewable intermittency management.
Manufacturing holds deepest installed base. Telecommunications represents the most technology-forward procurement profile.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Industrie 4.0 tax incentives and France's smart city special economic zones concentrate European fog computing deployment. Municipal procurement programs and industrial automation subsidies accelerate localized edge infrastructure across manufacturing corridors and urban centers.
Germany
Baden-Württemberg's automotive suppliers deploy predictive maintenance nodes for real-time vibration analytics. BSI cybersecurity certification mandates extend hardware validation timelines to 18-24 months for foreign vendors. Bavarian industrial clusters around Munich and Nuremberg anchor concentrated fog node rollouts for factory-floor inference workloads.
France
Lyon and Marseille municipal governments procure latency-sensitive traffic management systems through public tender channels. CNIL data governance requirements under GDPR Article 32 compel localized processing for healthcare telemetry in Paris university hospitals. Auvergne-Rhône-Alpes manufacturing facilities adopt edge nodes to satisfy algorithmic audit trail mandates from the EU AI Act.
United States
Autonomous vehicle testing corridors in California and Arizona demand sub-100-millisecond decision architectures for sensor fusion validation. NHTSA safety regulations and state-level data privacy laws create fragmented compliance landscapes for cross-border deployments. Detroit automotive engineering centers pilot fog-MEC convergence for connected vehicle infrastructure.
China
MIIT industrial internet initiatives subsidize edge node deployment across Yangtze River Delta manufacturing zones. GB standards for connected device security mandate localized data processing for critical infrastructure operators. Shenzhen and Shanghai smart city programs deploy roadside fog nodes for intelligent transport system coordination.
Japan
METI digital transformation grants accelerate fog computing adoption in Nagoya automotive supplier networks. JIS standards for industrial IoT security create certification requirements for foreign hardware vendors. Kanto region electronics manufacturers deploy edge analytics for semiconductor fabrication quality control.
Fog Computing Market Vendor Landscape
German industrial automation specialists anchor one tier; US cloud-native platform providers hold another. The vendor base concentrates around three strategic layers: networking hardware incumbents with edge-node distribution, hybrid cloud integrators bridging on-premises and centralized systems, and ruggedized server fabricators purpose-built for factory-floor conditions. Competitive moves center on 5G-MEC convergence partnerships and modular microservices architectures that decouple hardware refresh from software update cycles.
Within the networking-centric tier, Cisco Systems exemplifies hardware-anchored deployment models across manufacturing corridors. IBM Corporation occupies a position bridging hybrid cloud integration layers for enterprise data center connectivity. Dell Technologies represents ruggedized infrastructure specialization for thermal and vibration-stressed industrial environments.
| Leading Market Players |
|---|
| Cisco Systems |
| IBM Corporation |
| Dell Technologies |
| Microsoft Corporation |
| Intel Corporation |
| Fujitsu Limited |
| Huawei Technologies |
| ARM Holdings |
| GE Digital |
| Others |
Supply Flow & Price Mechanics
GDPR-mandated data localization compels European industrial buyers to procure certified edge hardware with 18-24 month BSI validation timelines, forcing suppliers to pre-position inventory and compressing margins on rushed deployments. This procurement pressure concentrates pricing power with domestic German vendors who maintain shorter certification cycles.
Pricing Analysis
Short lead-time premiums of 15-25% apply to BSI-certified fog nodes delivered within 90 days versus standard 12-month procurement cycles. Three-tier pricing structure across premium-certified, standard-industrial, and economy-grade tiers differentiates by cybersecurity certification level and thermal tolerance specifications. Cost compression in economy tiers intensifies as Chinese networking vendors enter European smart city tenders. Municipal governments in France and Italy exhibit highest price sensitivity due to public procurement budget constraints, while German automotive suppliers prioritize certification reliability over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from Bavarian automotive clusters and Baden-Württemberg automation corridors, bypassing distributor markups. Manufacturing concentrates in Germany, Taiwan, and China, with German facilities producing ruggedized enclosures and Taiwanese foundries fabricating edge AI accelerators. Component sourcing draws from South Korean memory suppliers, Japanese precision thermal management systems, and Chinese power supply manufacturers. Single-source vulnerability in AI chip supply creates exposure to export control restrictions. Distribution runs through systems integrators specializing in OT-IT convergence for brownfield manufacturing environments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a vertical-integration race where control over edge AI chip supply and BSI certification capabilities determines competitive sustainability. Players are pursuing backward integration into semiconductor design to secure inference workload performance.
For Market Incumbents: Anticipate margin compression from Chinese networking vendors by hardening BSI certification advantages and pre-integrating 5G-MEC convergence layers. Defensive consolidation through acquisition of containerized orchestration specialists will isolate safety-critical workloads. Prioritize captive supply of edge AI accelerators to reduce dependency on Taiwanese foundry allocation.
For New Entrants and Emerging Players: Mid-sized French manufacturing conglomerates with legacy SCADA systems represent an underserved buyer archetype requiring protocol translation middleware rather than full-stack replacement. White-space concentration sits in healthcare telemetry edge nodes for CNIL-compliant French university hospitals. Channel partnership with Deutsche Telekom's 5G-MEC pilot programs offers lowest-friction market entry.
For Investors and Strategic Acquirers: The window for entry favors containerized edge orchestration specialists with Kubernetes-native architectures and existing BSI certification relationships. Long-term viability hinges on recurring service revenue attachment rates above hardware depreciation cycles. Monitor divergence between EU harmonized standards and national implementation acts as the inflection signal for interoperability premium capture.
| Strategic Initiative | Industry Significance |
|---|---|
| BSI Certification Pre-Investment | Accelerates German market entry timelines from 24 months to 12 months for foreign hardware vendors. |
| 5G-MEC Convergence Partnership | Deutsche Telekom pilots integrate fog nodes with network slicing for industrial latency guarantees. |
| Containerized Microservices Platform | Bavarian automotive suppliers isolate safety-critical workloads to compress revalidation scope. |
| Edge AI Accelerator Supply Agreement | Taiwanese foundry allocation secures inference performance for predictive maintenance workloads. |
| Healthcare Telemetry Specialization | CNIL-compliant architectures open French hospital procurement channels under GDPR Article 32. |
Methodological Framework
Document review covered EU regulatory filings including AI Act implementation guidance, BSI certification databases, and GDPR Article 32 technical standards, complemented by interviews with plant engineers at Baden-Württemberg manufacturing facilities, procurement leads at German automotive OEMs, edge infrastructure architects at telecom operators, and cybersecurity compliance officers at French energy utilities. Secondary validation drew from SEC 10-K disclosures of networking hardware vendors, EU customs trade data for edge server imports, and ANSSI certification pathway documentation. Bottom-up deployment estimates across industrial clusters were triangulated against top-down market sizing from infrastructure capex disclosures.
Market value and volume trajectories across the projection horizon reflect segment-level modeling of application types, technology layers, and deployment configurations with particular attention to hybrid cloud integration complexity and on-premises air-gapped requirements. CAGRs were derived from regression analysis of historical infrastructure spending correlated with regulatory mandate effective dates and industrial automation investment cycles. Forecast inputs incorporated BSI certification queue lengths, 5G-MEC pilot expansion timelines, and Cyber Resilience Act implementation schedules.
Revisions become necessary when EU member state divergence from harmonized standards accelerates, export controls disrupt AI chip supply, or autonomous vehicle validation timelines compress faster than edge node deployment capacity. Forecasts reflect assumptions about certification timeline stability and foundry allocation continuity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Next Generation Technologies
Quantum Information Processing Market
Next Generation Technologies
Hyperscale Edge Computing Market
Next Generation Technologies
Information and Communications Technology (ICT) Market
Next Generation Technologies
Jordan ICT Market
Next Generation Technologies
Oman ICT Market
Next Generation Technologies
Next Generation Wireless Network Market
Next Generation Technologies
Malaysia ICT Market
Next Generation Technologies
Hyperloop Technology Market
Next Generation Technologies
Smart Surfaces Market
Next Generation Technologies
Nigeria ICT Market
Next Generation Technologies
Europe Quantum Computing Market
Next Generation Technologies
Poc Platform and Technology Market
Next Generation Technologies
GCC ICT Market
Next Generation Technologies
M2M Connections Market
Next Generation Technologies
Japan ICT Market
Next Generation Technologies
Global Next Generation Wireless Communication Market