
 Oman ICT Market | 2026-2036
Oman ICT Market Size, Share, and Industry Trends Forecast 2026-2036
Oman ICT Market Analytics
Project finance for submarine cable landing stations and sovereign cloud nodes is reshaping competitive entry in Oman's ICT sector. Cisco Systems leverages its routing and switching installed base to sustain long-term service contracts with government ministries. Huawei Investment & Holding Co., Ltd. anchors its position through aggressive localization commitments and training academy investments. Microsoft Corporation differentiates via Azure stack deployments that comply with emerging data residency requirements.
Information and communications technology in Oman encompasses software platforms, server and storage hardware, fiber and wireless networking infrastructure, and managed services that enable data processing, transmission, and enterprise automation across commercial and public systems. The technology stack spans cloud computing architectures, artificial intelligence inference engines, Internet of Things sensor networks, and distributed analytics frameworks purpose-built for latency-sensitive workloads in energy and logistics. Services currently capture the deepest margin pools as buyers shift from capital-intensive hardware refresh cycles to outcome-based managed service agreements. Cloud computing leads technology adoption as hyperscaler edge nodes proliferate across Sohar and Salalah free zones.
TRA spectrum allocation frameworks and CITC cybersecurity certification requirements shape vendor qualification pathways and procurement eligibility for foreign suppliers. Oman Computer Services navigates these regulatory layers by maintaining sovereign data center certifications and local staffing quotas that satisfy national content policies. Stakeholders must monitor how evolving data classification rules and critical infrastructure designations redraw competitive boundaries between global platform providers and domestic system integrators.
Market Dynamics
Sovereign cloud mandates and CITC data localization requirements are restructuring vendor qualification pathways, forcing hyperscalers to deploy edge nodes inside Oman and domestic integrators to obtain sovereign certification.
Growth Catalysts
- TRAI-aligned spectrum reforms:New allocation frameworks for 5G and IoT bands enable private network deployments across energy and logistics corridors.
- Critical infrastructure hardening:Government ministries mandate cybersecurity certification for operational technology systems, expanding managed security service contracts.
- Free zone edge proliferation:Hyperscalers anchor compute nodes in Sohar and Salalah, reducing latency for industrial automation workloads.
Market Restraints
- Specialized engineering talent scarcity:Domestic supply of cloud architects and cybersecurity analysts lags deployment timelines, inflating compensation costs.
- Submarine cable concentration risk:Landing station dependence on Fujairah and Salalah corridors creates single-point vulnerability for international bandwidth.
- Legacy system integration friction:Petroleum and utilities sectors operate decades-old SCADA infrastructure resistant to API-based modernization.
Strategic Opportunities
- Dhofar logistics corridor:Port automation and cold-chain IoT sensor networks remain underpenetrated relative to Muscat and Sohar.
- AI inference at the edge:Convergence of computer vision and 5G private networks enables real-time quality control for manufacturing.
- Public-private partnership frameworks:Oman Investment Authority co-financing mechanisms reduce capex burden for sovereign cloud infrastructure.
Industry Challenges
- CITC certification timelines:Multi-stage approval processes for critical infrastructure designation delay revenue recognition by quarters.
- Multi-cloud orchestration complexity:Enterprise buyers demand unified management across Azure, AWS, and domestic sovereign stacks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oman ICT Market |
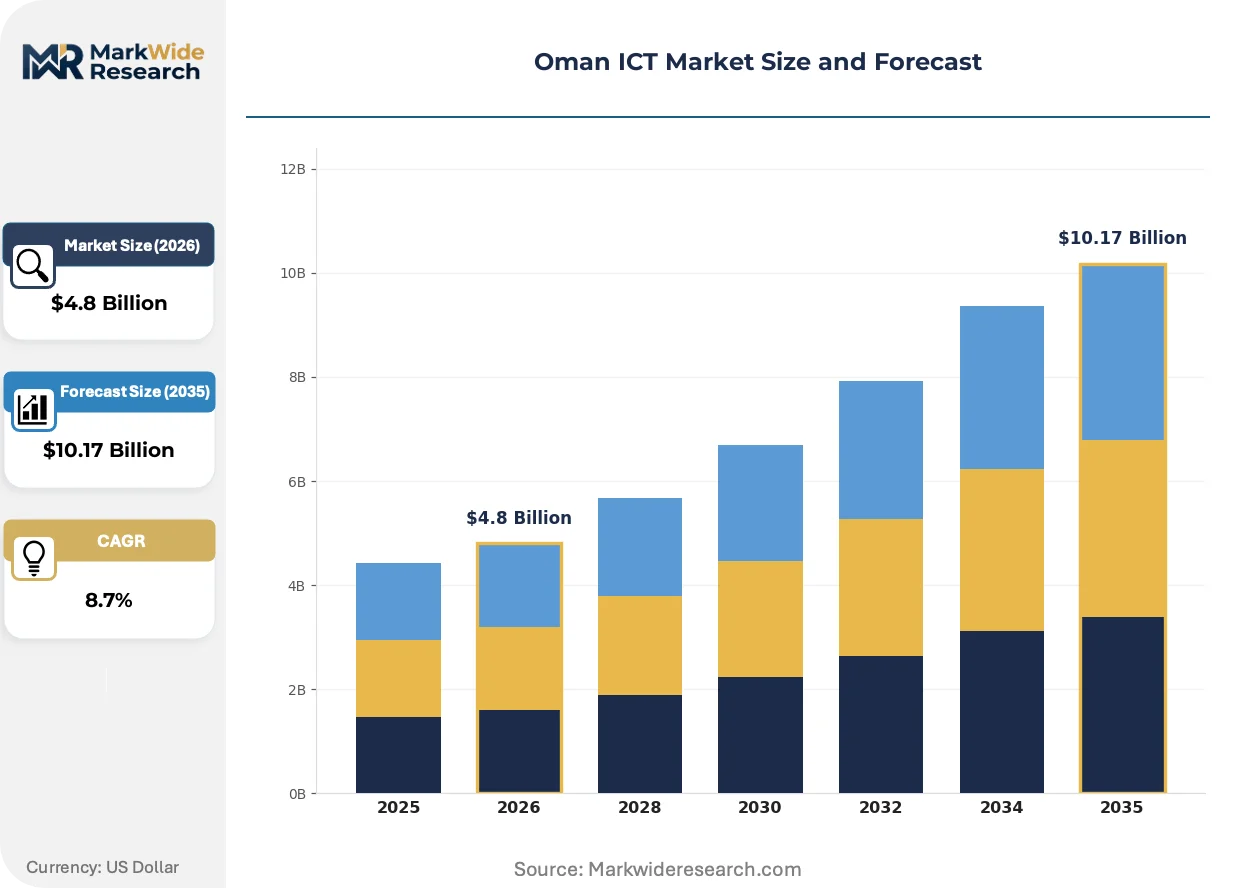
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Hardware, Networking, Services End User: Government, Education, Healthcare, Enterprises Technology: Cloud Computing, AI, IoT, Big Data Application: Telecommunications, Cybersecurity, E-Governance, Data Analytics |
| Companies Covered | Cisco Systems, Hewlett Packard Enterprise, IBM Corporation, Microsoft Corporation, Huawei Investment & Holding Co., Ltd., Oracle Corporation, SAP SE, Oman Computer Services, Cognizant Technology Solutions, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oman ICT Market Evolving Landscape
Network function virtualization and containerized workloads are displacing hardware-centric infrastructure procurement, compressing refresh cycles and expanding software-defined service margins.
Software-defined wide area networking is virtualizing branch connectivity for retail and banking footprints. Mid-market enterprises in Muscat and Nizwa adopt managed SD-WAN services to replace MPLS contracts. This virtualization is compressing router hardware refresh demand while expanding recurring security service attach rates.
CITC cybersecurity certification requirements now mandate sovereign data center audits and local encryption key custody for critical infrastructure operators. Foreign platform providers must establish Omani legal entities and staff local security operations centers. Energy and water utilities face the steepest compliance burden, driving preference toward pre-certified domestic system integrators.
Enterprise buyers unbundle hardware procurement from professional services, awarding separate contracts for infrastructure, implementation, and ongoing managed operations. Systems integrators respond with staff augmentation and outcome-based SLA structures. This pattern concentrates in government and defense verticals where multi-source procurement rules apply.
Oman ICT Market Segmentation
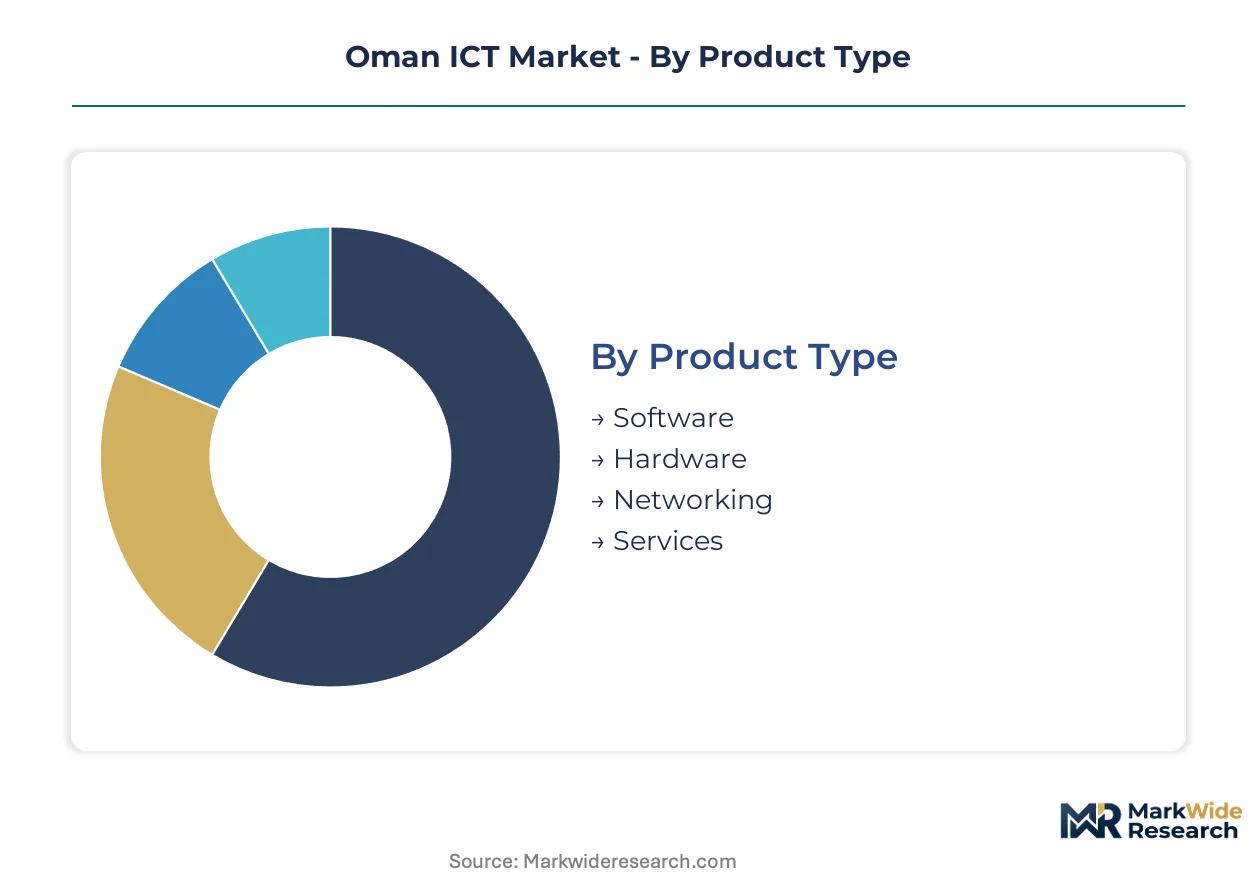
Segmentation in Oman's ICT market exposes how procurement patterns diverge between sovereign infrastructure mandates and commercial digital transformation. Buyers in Muscat and Salalah free zones prioritize different technology stacks than ministries in the interior governorates.
Product Type:
Mature segments dominate current revenue while emerging categories capture strategic investment flows.
- Software:Enterprise resource planning and customer relationship management platforms form the deployment core. Government ministries in Muscat drive demand for sovereign-certified applications that satisfy CITC data residency requirements.
- Hardware:Server and storage infrastructure anchors capital expenditure cycles. Petroleum operators in the interior governorates maintain refresh timelines for SCADA-adjacent compute clusters despite cloud migration pressures.
- Networking:Fiber and wireless infrastructure enable 5G private networks across logistics corridors.
- Services:Managed security and cloud migration consulting expand recurring revenue pools.
Services handles the majority of throughput; software is the fastest mover on share.
End User:
Customer type determines procurement complexity and contract duration more than technology specification.
- Government:Ministries and defense agencies operate under strict CITC certification and local content quotas. Multi-source procurement rules unbundle hardware, implementation, and managed operations into separate award cycles.
- Enterprises:Energy, logistics, and banking verticals drive private cloud and edge computing adoption. Free zone operators in Sohar and Salalah prioritize latency-sensitive workloads over sovereign compliance.
- Healthcare:Hospital networks and diagnostic chains modernize electronic medical record infrastructure.
- Education:Universities and technical institutes expand digital campus platforms and remote learning capabilities.
Government commands the largest contract values; enterprises are expanding most quickly.
Technology:
Deployment maturity separates established infrastructure from experimental pilot programs.
- Cloud Computing:Hyperscaler edge nodes and sovereign cloud stacks constitute the primary investment wave. Azure and domestic certified providers compete for ministry workloads requiring local encryption key custody.
- AI:Computer vision and predictive analytics concentrate in manufacturing quality control and port automation. 5G private networks in Sohar free zone enable real-time inference for logistics optimization.
- IoT:Sensor networks monitor critical infrastructure across energy and water utilities.
- Big Data:Distributed analytics frameworks process seismic and reservoir data for petroleum operators.
Cloud computing absorbs the dominant share of capital; AI is climbing the fastest.
Application:
Use case concentration reflects Oman's economic structure and regulatory priorities.
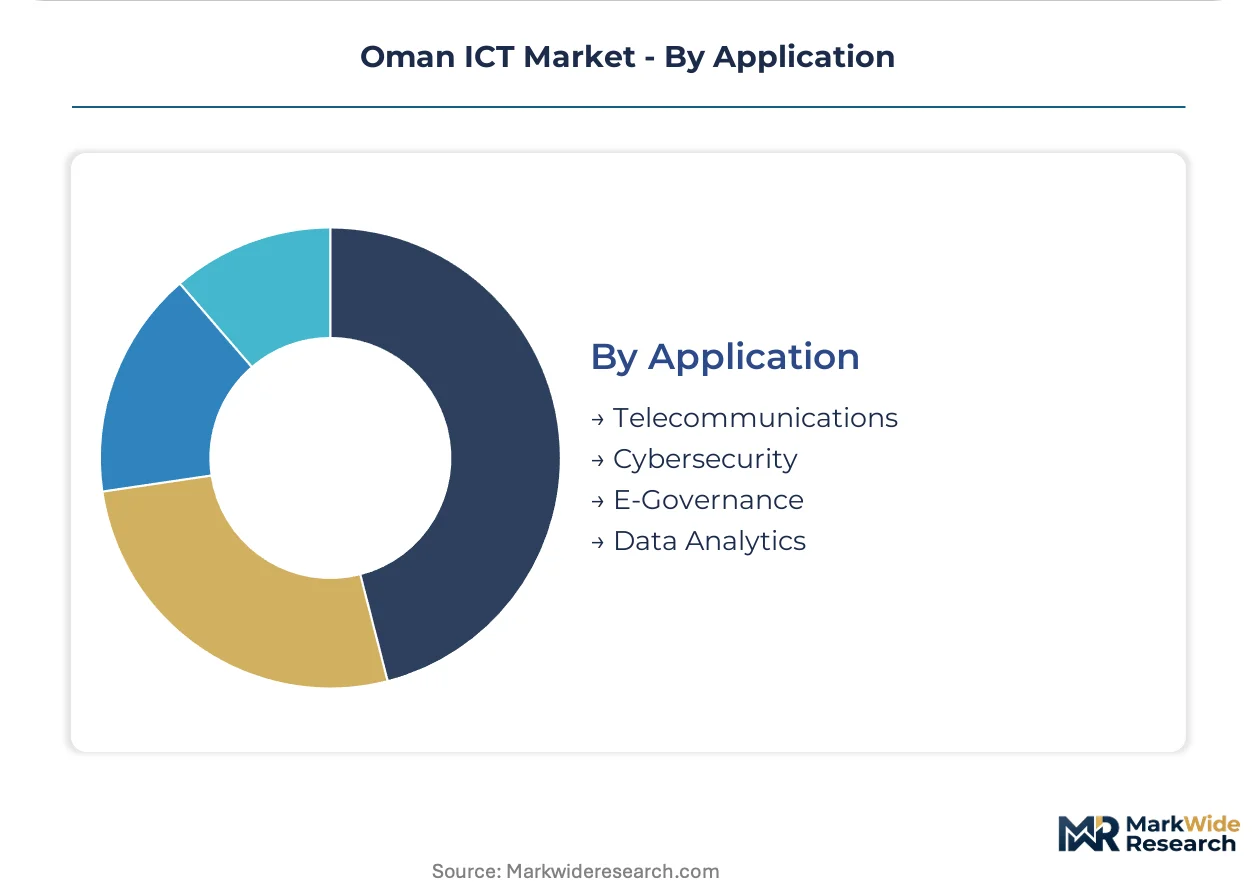
- Cybersecurity:CITC certification mandates for critical infrastructure operators expand managed security service contracts. Energy and water utilities face the steepest compliance burden, favoring pre-certified domestic integrators.
- Telecommunications:TRAI-aligned spectrum reforms enable 5G and IoT private networks across energy and logistics corridors. Submarine cable landing stations at Salalah anchor international bandwidth capacity.
- E-Governance:Digital procurement platforms and citizen service portals modernize public administration.
- Data Analytics:Petroleum reservoir modeling and logistics optimization drive specialized workload demand.
Cybersecurity generates the deepest margin pools; telecommunications shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government ministries in Muscat concentrate procurement authority for sovereign cloud infrastructure, while free zone operators in Sohar and Salalah drive commercial edge computing demand. Energy and logistics enterprises anchor technology adoption across the interior governorates. CITC certification requirements reshape vendor eligibility nationwide.
Muscat Governorate
Ministries and defense agencies dominate demand for CITC-certified cybersecurity services and sovereign cloud platforms. The Information Technology Authority mandates local encryption key custody for critical infrastructure operators. Ruwi and Al Khuwair districts host concentrated data center clusters serving government workloads.
Al Batinah North and South
Petroleum operators in Sohar Free Zone sustain capital expenditure for SCADA-adjacent compute clusters and private 5G networks. Port automation projects at Sohar Port Authority drive IoT sensor network deployments. Industrial zones anchor edge computing nodes for latency-sensitive manufacturing quality control.
Dhofar Governorate
Salalah Free Zone operators prioritize hyperscaler edge nodes for logistics optimization and cold-chain monitoring. The Salalah submarine cable landing station anchors international bandwidth capacity for regional connectivity. Port automation and free zone digital infrastructure remain underpenetrated relative to northern economic corridors.
Ad Dakhiliyah and Ash Sharqiyah
Utility operators across Nizwa and Sur face steep CITC compliance burdens for water and energy infrastructure cybersecurity. Domestic system integrators with pre-certified sovereign data center credentials capture preference. Regional technical institutes expand digital campus platforms and workforce training capacity.
Oman ICT Market Competitive Landscape
Channel-controlling players compete with product-specialist players for procurement contracts across government and enterprise verticals. The vendor base concentrates around three tiers: hyperscaler platform providers with sovereign cloud deployments, domestic system integrators holding CITC certifications, and global hardware manufacturers with established routing and switching installed bases. Strategic differentiation centers on localization commitments, training academy investments, and compliance with data residency mandates. Competitive moves emphasize partnership frameworks with Oman Investment Authority co-financing mechanisms and multi-cloud orchestration capabilities.
Among global platform providers, Microsoft Corporation and Cisco Systems exemplify contrasting archetypes: the former anchors position through Azure stack deployments satisfying emerging data residency requirements, while the latter leverages long-term routing and switching installed bases to sustain service contracts with government ministries. Huawei Investment & Holding Co., Ltd. occupies a distinct position through aggressive localization commitments and training academy investments. Domestic capability concentrates in Oman Computer Services, which navigates regulatory layers by maintaining sovereign data center certifications and local staffing quotas.
| Leading Market Players |
|---|
| Cisco Systems |
| Hewlett Packard Enterprise |
| IBM Corporation |
| Microsoft Corporation |
| Huawei Investment & Holding Co., Ltd. |
| Oracle Corporation |
| SAP SE |
| Oman Computer Services |
| Cognizant Technology Solutions |
| Others |
Value Network & Pricing Analysis
Salalah Free Zone hyperscaler edge capacity anchors downstream pricing power for cloud services across Dhofar Governorate, while Muscat sovereign cloud deployments command premiums tied to CITC certification compliance. Procurement patterns diverge sharply between latency-sensitive commercial workloads and residency-mandated government infrastructure.
Pricing Analysis
CITC certification tier creates the primary spread between sovereign-qualified and standard commercial offerings. Three-tier pricing structure across certified-premium, standard-managed, and economy-self-service levels dominates enterprise software procurement. Cost compression in hardware resale is intensifying because buyers unbundle infrastructure from professional services. Government ministries show least price sensitivity due to compliance mandates, while mid-market retailers in Nizwa demonstrate highest elasticity.
Supply Chain Analysis
Original design manufacturers in Taiwan, Malaysia, and China hold concentrated server and networking equipment capacity serving Omani system integrators. Component sourcing draws from memory fabs in South Korea, optical transceiver specialists in Japan, and power supply vendors in Vietnam. Single-source vulnerability runs through submarine cable landing stations at Fujairah and Salalah corridors. Distribution runs through Dubai-based regional distributors with last-mile integration by CITC-certified domestic partners.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Domestic cloud architect and cybersecurity analyst shortages inflate implementation timelines and compensation costs, compressing margins for time-sensitive deployments. Vendors who solve this talent pipeline constraint capture disproportionate procurement preference.
For Market Incumbents: Insulate recurring revenue streams by embedding outcome-based SLA structures into ministry contracts before procurement unbundling accelerates. Prioritize sovereign data center certification renewals to defend against emerging domestic integrators. Vertical integration into training academy operations reduces talent acquisition friction and locks in long-term service attach rates. For New Entrants and Emerging Players: Dhofar logistics corridor cold-chain IoT and port automation present the most penetrable white-space relative to saturated Muscat and Sohar markets. Target pre-certified partnership routes with Oman Investment Authority co-financing frameworks to bypass capital intensity barriers. Lead with AI inference-at-the-edge pilots demonstrating real-time quality control outcomes to manufacturing buyers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors domestic system integrators with CITC sovereign certifications and established government relationships over pure-play hyperscaler resellers. Long-term viability rests on compliance infrastructure moats rather than transient price advantages. Monitor CITC critical infrastructure designation expansion as the inflection signal for accelerated consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Certification | CITC data residency compliance unlocks ministry procurement eligibility and multi-year managed service contracts. |
| Training Academy Investment | Localized cloud architect pipelines reduce talent scarcity premiums and anchor long-term customer relationships. |
| Edge Node Deployment | Hyperscaler compute presence in Salalah Free Zone captures latency-sensitive logistics and manufacturing workloads. |
| Multi-Cloud Orchestration Platform | Unified Azure-AWS-sovereign stack management addresses enterprise buyer complexity and expands services attach. |
| Public-Private Partnership Framework | Oman Investment Authority co-financing reduces sovereign infrastructure capex burden and accelerates revenue recognition. |
Research Methodology
The analysis maps cloud computing architectures, cybersecurity services, networking infrastructure, and managed services segments, each validated through chief technology officers, IT procurement officers, CITC compliance leads, and systems integration specialists. Primary fieldwork combined structured interviews with secondary validation against SEC filings, hyperscaler capex disclosures, CITC regulatory notices, and Oman Investment Authority project databases. Bottom-up deployment sizing and top-down macroeconomic triangulation anchored value estimates.
Assumptions held TRAI spectrum allocation timelines and CITC certification requirements fixed across the modeling period, while varying energy sector capital expenditure cycles and logistics automation adoption curves. Segmentation modeled deployment model, organization size, vertical industry, integration complexity, and regional adoption pattern dimensions. CAGRs derived from fitted growth curves applied to base-year estimates, with petroleum operator technology refresh cycles and free zone foreign direct investment flows as key forecast inputs.
Practitioners should monitor CITC data classification rule revisions and critical infrastructure designation expansion for early signals of vendor eligibility shifts. Forecasts reflect assumptions about regulatory continuity and submarine cable capacity expansion. Quarterly review of ministry procurement award patterns and hyperscaler edge node commissioning timelines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Next Generation Technologies
Europe Quantum Computing Market
Next Generation Technologies
Nearfield Communication (NFC) Market
Next Generation Technologies
Quantum Computing Market
Next Generation Technologies
Nigeria ICT Market
Next Generation Technologies
Japan ICT Market
Next Generation Technologies
Quantum Information Processing Market
Next Generation Technologies
Next-Generation Communication Devices Market
Next Generation Technologies
Global Next Generation Wireless Communication Market
Next Generation Technologies
Ireland ICT Market
Next Generation Technologies
Enterprise Quantum Computing Market
Next Generation Technologies
Smart Surfaces Market
Next Generation Technologies
Poc Platform and Technology Market
Next Generation Technologies
Information and Communications Technology (ICT) Market
Next Generation Technologies
Malaysia ICT Market
Next Generation Technologies
Fog Computing Market
Next Generation Technologies
Next Generation Wireless Network Market