
 Next Generation Network (NGN) Equipment Market | 2026-2036
Next Generation Network (NGN) Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Next Generation Network (NGN) Equipment Market Foresight
Platform licensing revenue is fragmenting between proprietary hardware stacks and open-source software distributions. Cisco Systems leverages its installed base of enterprise routers to sustain recurring subscription income. Huawei Investments and Holding Co. anchors its position through in-house semiconductor fabrication for baseband units. Nokia Corporation competes aggressively in open RAN partnerships with European telecom providers.
Next Generation Network equipment encompasses packet-switched infrastructure that converges voice, video, and data services over IP-based architectures, typically operating at throughput thresholds exceeding 100 Gbps per node. The primary purpose centers on replacing legacy circuit-switched systems with programmable, software-defined cores that enable dynamic bandwidth allocation. Routers and switches capture the dominant share of hardware expenditure as carriers refresh backbone capacity. SDN and NFV deployments are expanding fastest among enterprises seeking to decouple control planes from proprietary silicon. Cloud-based and virtualized delivery models concentrate margin pools in managed services rather than one-time equipment sales.
The Federal Communications Commission in the United States restricts equipment from designated national security risks, reshaping supplier eligibility for federal broadband subsidies. The European Telecommunications Standards Institute mandates interoperability benchmarks under its NFV specifications, while the International Telecommunication Union coordinates global 5G spectrum harmonization. China's Ministry of Industry and Information Technology enforces domestic encryption standards for core network elements. Stakeholders must monitor divergent national certification regimes when architecting multi-country supply chains.
Market Dynamics
The convergence of cloud-native architectures with hardware disaggregation is compressing traditional equipment refresh cycles and redistributing value from proprietary silicon to software orchestration layers.
Growth Catalysts
- 5G Standalone Core Deployments:South Korean carriers are accelerating packet core virtualization to support network slicing for industrial automation.
- EU Cybersecurity Certification:Mandates under the Cybersecurity Act create compliance-driven replacement demand for critical network infrastructure.
- Open RAN Interoperability:European Telecommunications Standards Institute specifications enable multi-vendor deployments that reduce supplier lock-in.
Market Restraints
- Advanced Node Semiconductor Constraints:Baseband processor fabrication depends on concentrated Taiwan-based foundry capacity.
- FCC Equipment Authorization Restrictions:Designated vendor prohibitions limit supplier pools for US federal broadband subsidy programs.
- Optical Component Cost Volatility:Coherent DSP and laser supply tightness elevates transport layer capital intensity.
Strategic Opportunities
- Edge Computing Convergence:Integration of multi-access edge computing with 5G cores creates distributed compute revenue pools.
- India Digital Infrastructure Expansion:BharatNet rural fiberization and 5G spectrum allocation drive greenfield core investments.
- Green Network Mandates:EU Green Deal energy efficiency standards incentivize thermal-optimized chassis and liquid cooling retrofits.
Industry Challenges
- Cloud-Native Talent Scarcity:Container orchestration and Kubernetes specialization gaps constrain vendor delivery timelines.
- Multi-Vendor Integration Complexity:Disaggregated radio access networks require systems integration capabilities absent from traditional deployment models.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Next Generation Network (NGN) Equipment Market |
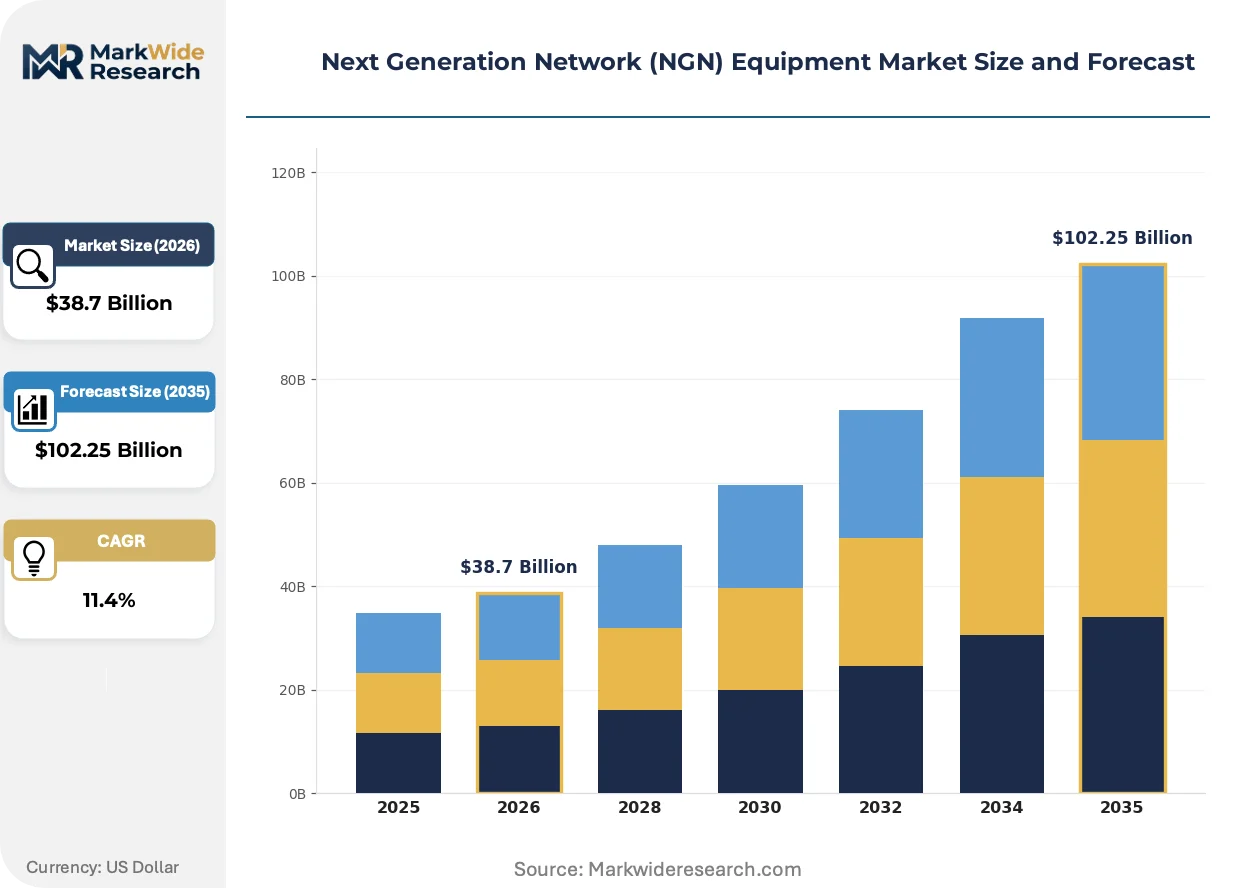
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $102.25 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Routers, Switches, Gateways, Access Points Technology: SDN, NFV, 5G, MPLS End User: Telecom Providers, Enterprises, Government, ISPs Deployment: On-Premises, Cloud-Based, Hybrid, Virtualized |
| Companies Covered | Ericsson, Qualcomm Incorporated, Cisco Systems, ZTE Corporation, Hewlett Packard Enterprise, Huawei Investments and Holding Co., Samsung Electronics, Juniper Networks, Nokia Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Next Generation Network (NGN) Equipment Market Shifts & Advancements
Software-defined disaggregation is fragmenting vertically integrated supply structures and relocating margin capture toward orchestration software and managed services.
Cloud-native network functions running on commodity x86 servers are rendering obsolete purpose-built packet processing appliances in mobile core deployments. Tier-1 carriers in Germany and Japan are migrating subscriber management and session control to containerized microservices. This shift compresses hardware refresh revenue while expanding recurring software license streams.
The EU AI Act imposes risk classification requirements on automated network management systems that influence traffic routing decisions. Equipment vendors must embed explainability and human oversight mechanisms into intent-based networking software. Core network automation platforms face heightened compliance scrutiny relative to transport layer hardware.
Telecom procurement organizations are consolidating vendor panels and demanding outcome-based performance guarantees rather than equipment specifications. German and US carriers now contract for availability and latency thresholds with penalty clauses. This transfers operational risk to suppliers and accelerates managed services penetration over capital sales.
Next Generation Network (NGN) Equipment Market Segmentation
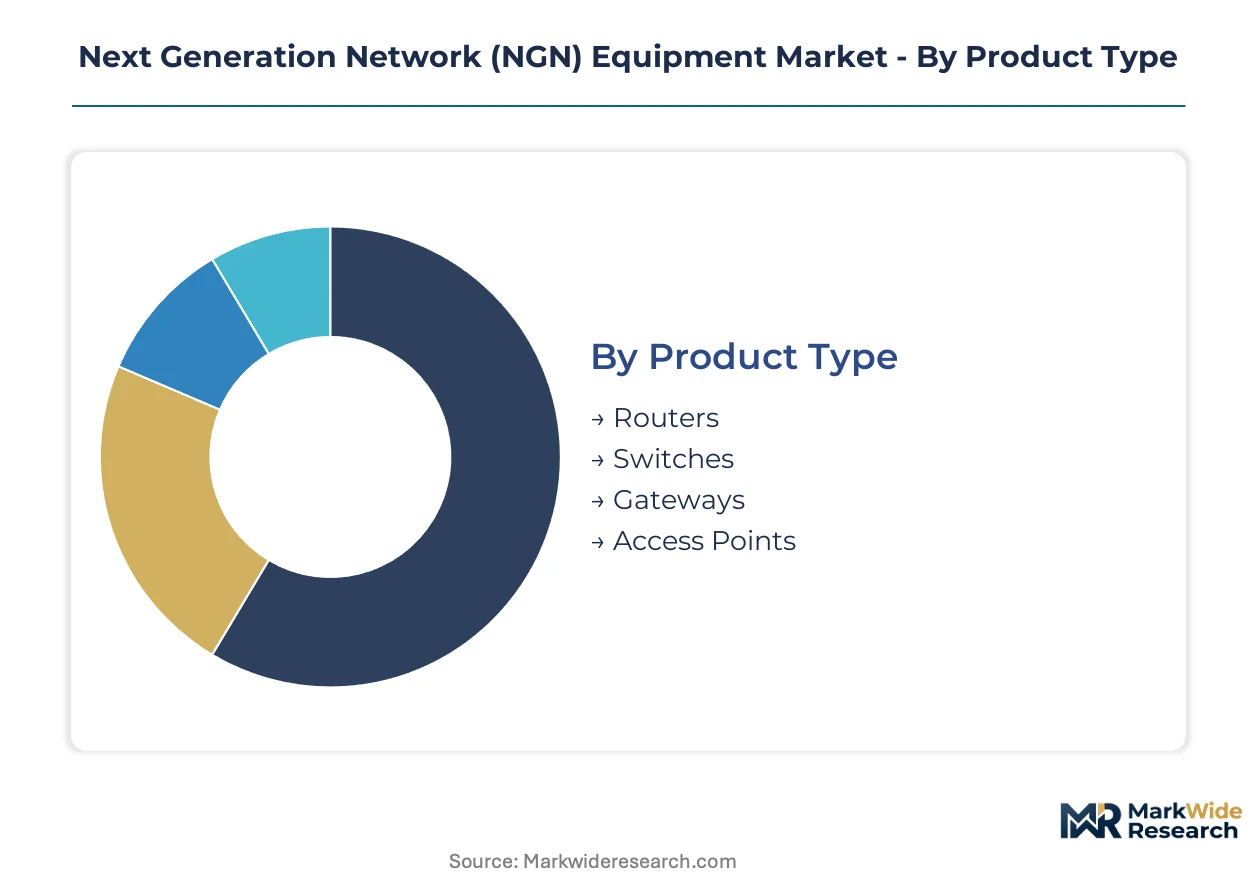
NGN equipment segmentation reveals divergent refresh dynamics across infrastructure layers. Product type determines capital cycle timing, while deployment mode shapes margin capture between hardware and recurring software streams.
Product Type:
Routers and switches turn over every 4-5 years as backbone capacity scales, whereas gateways and access points refresh faster at 2-3 year intervals driven by endpoint density growth.
- Routers:High-throughput packet forwarding engines operating at 100+ Gbps per slot, deployed in carrier core and aggregation tiers. German and US carriers dominate procurement for IP/MPLS backbone refreshes, constrained by FCC equipment authorization restrictions that reshape supplier eligibility.
- Switches:Layer 2/3 fabric devices with programmable data planes enabling SDN controller integration. Enterprise demand concentrates in Japan for campus network modernization, pressured by EU Green Deal thermal efficiency mandates affecting chassis design.
- Gateways:Protocol translation nodes bridging legacy circuit-switched domains to IP cores. Telecom providers in South Korea deploy these for 5G interworking functions.
- Access Points:Radio and wireline termination equipment at network edge. ISPs in India expand these for BharatNet rural fiberization.
Routers dominate installed base value. Access points are where expansion concentrates.
Technology:
Cost tier stratification separates mature MPLS implementations from emerging cloud-native stacks, with SDN and NFV commanding premium orchestration licensing.
- SDN:Control plane decoupling architectures enabling centralized traffic engineering. German carriers lead deployment for industrial automation network slicing, facing EU AI Act compliance requirements for automated management systems.
- NFV:Virtualized network functions on commodity compute replacing purpose-built appliances. Japanese enterprises adopt these fastest for subscriber management containerization.
- 5G:New radio and core specifications with network slicing capabilities. South Korean carriers drive standalone core virtualization.
- MPLS:Label-switched path technology for traffic engineering and VPN services. Legacy installations persist in government networks with slower refresh cycles.
MPLS retains widest installed base footprint. NFV is climbing the fastest as virtualization displaces hardware.
End User:
Volume concentration varies sharply: telecom providers account for backbone expenditure, while enterprises show fastest growth in edge computing integration.
- Telecom Providers:Tier-1 and Tier-2 carriers operating national and regional networks. South Korean and German providers drive 5G core investments, constrained by advanced node semiconductor dependencies for baseband processing.
- Enterprises:Large organizations building private networks and hybrid cloud connectivity. US financial services and healthcare verticals expand SD-WAN deployments under HIPAA security requirements.
- Government:Federal, state, and municipal network operators. US federal programs face FCC designated vendor prohibitions limiting supplier pools.
- ISPs:Internet service providers of varying scale. Indian operators expand for rural digital infrastructure under TRAI spectrum allocation frameworks.
Telecom providers dominate capital deployment. Enterprises are gaining share fastest for edge-integrated deployments.
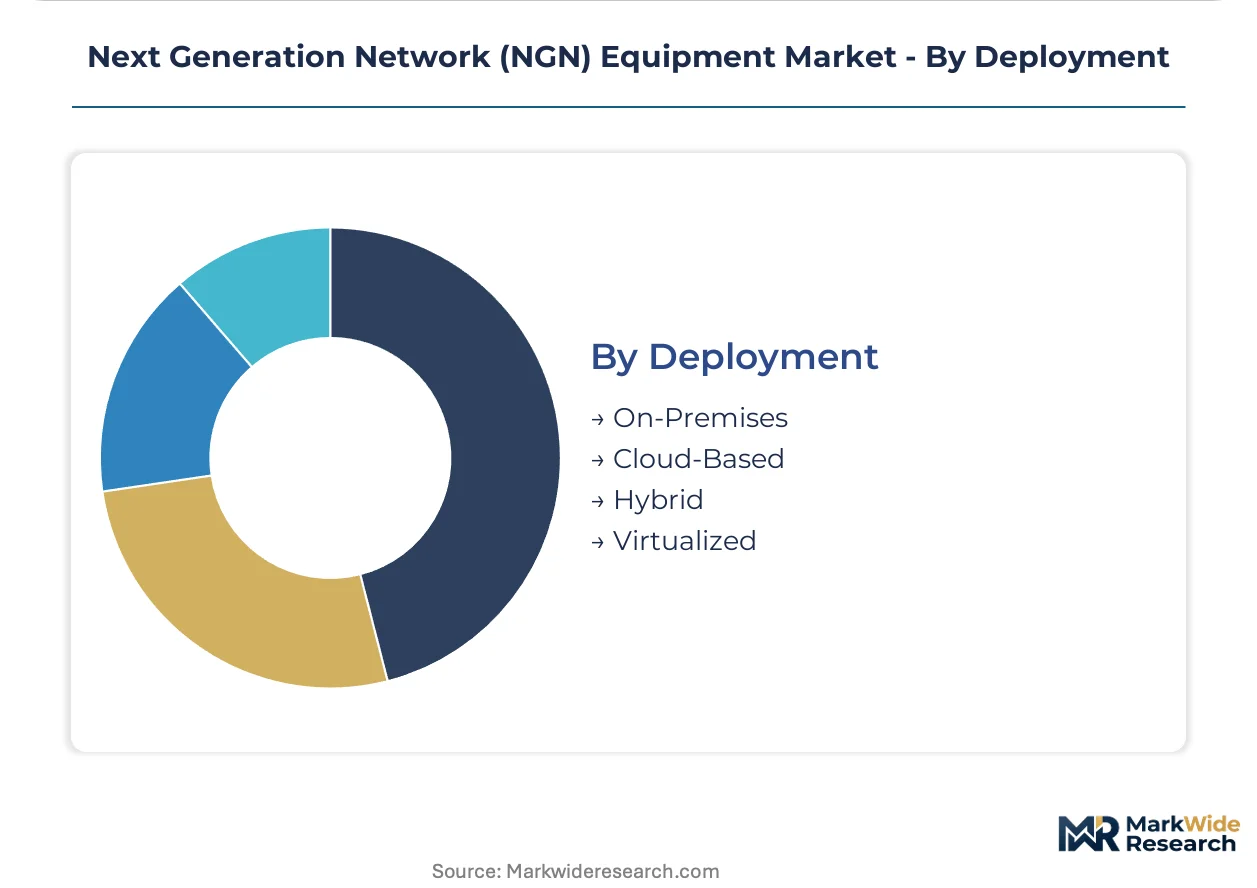
Deployment:
Margin structure inverts across deployment modes: on-premises captures hardware markup, while cloud-based and virtualized shifts value to managed services.
- On-Premises:Physical equipment installed in customer facilities with full operational ownership. Government and regulated industries in Japan prefer this for data sovereignty under METI guidelines.
- Cloud-Based:Network functions delivered as-a-service from hyperscaler or telecom cloud infrastructure. German carriers contract availability-based performance guarantees with penalty clauses.
- Hybrid:Mixed estate combining owned hardware with cloud-orchestrated functions. US enterprises adopt this for phased SDN migration.
- Virtualized:Software-only network functions on customer-managed compute. South Korean carriers deploy these for packet core network slicing.
On-premises retains largest installed base. Cloud-based is expanding most quickly as procurement shifts to outcome-based contracting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea deploys 5G standalone cores for industrial network slicing while Germany prioritizes open RAN interoperability under ETSI mandates. The United States restricts federal procurement through FCC equipment authorization frameworks, diverging from India's greenfield fiberization push.
United States
Telecom providers refresh IP/MPLS backbone capacity for cloud-native traffic engineering. FCC designated vendor prohibitions reshape supplier eligibility for federal broadband subsidy programs. Dallas-Fort Worth anchors hyperscaler edge computing clusters integrating multi-access edge computing with 5G cores.
Germany
Carriers contract availability-based performance guarantees with penalty clauses for industrial automation networks. EU Cybersecurity Act mandates stricter certification for critical network infrastructure components. Munich-Stuttgart corridor hosts ETSI-aligned open RAN interoperability testing for multi-vendor deployments.
South Korea
Carriers accelerate packet core virtualization to support network slicing for manufacturing automation. MFDS cybersecurity frameworks govern automated network management system deployments. Seoul Capital Area concentrates baseband unit demand for advanced node semiconductor-dependent 5G infrastructure.
Japan
Enterprises migrate subscriber management to containerized microservices on commodity x86 servers. METI data sovereignty guidelines shape on-premises deployment preferences for regulated industries. Tokyo-Osaka corridor leads SD-WAN adoption for financial services under HIPAA-aligned security requirements.
India
ISPs expand rural fiberization under BharatNet for greenfield core investments. TRAI spectrum allocation frameworks govern 5G network rollout timelines. Karnataka-Telangana corridor concentrates cloud-based network function deployments for cost-optimized scalability.
Next Generation Network (NGN) Equipment Market Competitive Landscape
Capability concentration sits with semiconductor-integrated vendors; scale advantage sits with installed-base incumbents. The vendor structure stratifies across three tiers: proprietary hardware stack providers, open-source software distributors, and cloud-native orchestration specialists. Strategic differentiation runs through vertical integration depth and managed services penetration. Competitive moves center on open RAN partnership formation and edge computing convergence plays.
Within the integrated semiconductor tier, Huawei Investments and Holding Co. and Qualcomm Incorporated exemplify captive fabrication strategies for baseband processing. Cisco Systems occupies a position among subscription-model incumbents leveraging enterprise router installed bases for recurring revenue. Nokia Corporation and Ericsson sit within the open RAN partnership archetype competing for European telecom provider contracts under interoperability mandates.
| Leading Market Players |
|---|
| Ericsson |
| Qualcomm Incorporated |
| Cisco Systems |
| ZTE Corporation |
| Hewlett Packard Enterprise |
| Huawei Investments and Holding Co. |
| Samsung Electronics |
| Juniper Networks |
| Nokia Corporation |
| Others |
Supply & Pricing Matrix
Taipei-Hsinchu Science Park anchors advanced node foundry capacity for baseband processors, concentrating silicon supply power among a handful of contract manufacturers and compressing margin capture downstream for equipment vendors locked into long-term wafer allocation agreements.
Pricing Analysis
Long-term offtake contracts dominate procurement between tier-1 carriers and semiconductor-integrated vendors, while spot purchasing persists for optical components and commodity compute hardware. Three-tier pricing structure across premium, standard, and economy levels separates ETSI-certified core infrastructure from uncertified edge equipment and refurbished legacy systems. Cost compression in transport layer optics is intensifying because coherent DSP supply tightness elevates capital intensity for backbone refreshes. Government buyers under FCC equipment authorization frameworks show highest price sensitivity due to restricted supplier pools, whereas South Korean carriers demonstrate lowest sensitivity when contracting for 5G standalone core virtualization.
Supply Chain Analysis
TSMC and Samsung Foundry hold captive capacity for 7nm and below baseband processor fabrication, while Foxconn and Jabil concentrate EMS assembly for chassis and thermal management systems. Taiwan, South Korea, and Vietnam anchor component sourcing for advanced semiconductors, precision optics, and mechanical enclosures respectively. Raw material dependencies span silicon wafers, rare earth elements for laser components, and copper alloys for high-speed interconnects. Single-source vulnerability in Taiwan-based foundry capacity poses structural risk given geopolitical exposure. Distribution runs through direct carrier procurement teams for core infrastructure and value-added resellers for enterprise edge deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-native disaggregation fragments vertically integrated supply structures, creating entry niches for orchestration software specialists as telecom procurement shifts toward outcome-based performance contracting.
For Market Incumbents: Harden subscription revenue streams by embedding managed services into router and switch deployments before open RAN interoperability standards commoditize hardware differentiation. Defensive consolidation through backward integration into captive semiconductor fabrication protects against Taiwan foundry concentration risk. Prioritize certification investment under EU Cybersecurity Act mandates to lock out unqualified competitors from European critical infrastructure procurement. For New Entrants and Emerging Players: Establish a beachhead in multi-access edge computing orchestration software where incumbent hardware vendors lack cloud-native deployment expertise. Target Indian ISPs expanding BharatNet rural fiberization for greenfield core investments unencumbered by legacy migration complexity. Deploy consumption-based SaaS pricing to bypass capital-intensive equipment sales cycles and align with carrier outcome-based contracting preferences. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vendors with installed base penetration in enterprise SD-WAN and private 5G networks where subscription attach rates exceed hardware refresh cycles. Long-term viability favors acquisition targets with container orchestration capabilities and Kubernetes specialization addressing cloud-native talent scarcity. Monitor EU AI Act compliance milestones for automated network management systems as inflection indicator for regulatory-driven replacement demand.| Strategic Initiative | Industry Significance |
|---|---|
| Open RAN Partnership Formation | ETSI-aligned interoperability testing in Munich-Stuttgart corridor enables multi-vendor deployments reducing supplier lock-in. |
| Edge Computing Convergence | Dallas-Fort Worth hyperscaler clusters integrate multi-access edge computing with 5G cores creating distributed compute revenue pools. |
| Managed Services Penetration | German carriers now contract availability thresholds with penalty clauses transferring operational risk from buyers to vendors. |
| Semiconductor Backward Integration | Captive fabrication strategies for baseband processing insulate against Taiwan foundry concentration and advanced node constraints. |
| Cloud-Native Certification Investment | EU AI Act risk classification requirements for automated traffic routing systems create compliance-driven competitive moats. |
Research Methodology
Initial hypotheses were tested against primary input from carrier network architects, cloud infrastructure procurement officers, and open RAN integration specialists and refined through secondary validation against hyperscaler capex disclosures, SEC equipment vendor filings, ETSI specification releases, and TRAI spectrum allocation records. Bottom-up triangulation across deployment mode segmentation and top-down reconciliation against aggregate carrier capital expenditure patterns anchored volume estimates.
Demand-supply-balance framing modeled capacity installation rates against semiconductor foundry allocation constraints and optical component lead times across the analysis window. Segmentation dimensions included product type, technology stack, deployment mode, and end-user vertical with regional regulatory cluster overlays. CAGRs derived from logistic diffusion curves fitted to 5G standalone core adoption patterns and cloud-native migration velocity in enterprise segments. Industry-specific forecast inputs incorporated FCC equipment authorization restriction impacts and EU Cybersecurity Act compliance timelines.
Sensitivities concentrate around Taiwan semiconductor supply disruptions, EU AI Act enforcement intensity, and carrier shift velocity from capital sales to managed services contracting. Forecasts reflect documented assumptions on spectrum allocation timelines and foundry capacity expansion plans. Quarterly review of ETSI certification completion rates and hyperscaler edge computing cluster announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Next Generation Technologies
Ireland ICT Market
Next Generation Technologies
Bulgaria ICT Market
Next Generation Technologies
Smart Surfaces Market
Next Generation Technologies
M2M Connections Market
Next Generation Technologies
Poc Platform and Technology Market
Next Generation Technologies
GCC ICT Market
Next Generation Technologies
Oman ICT Market
Next Generation Technologies
Next-Generation Communication Devices Market
Next Generation Technologies
Hyperloop Technology Market
Next Generation Technologies
Fog Computing Market
Next Generation Technologies
Europe Quantum Computing Market
Next Generation Technologies
Quantum Information Processing Market
Next Generation Technologies
Nigeria ICT Market
Next Generation Technologies
Enterprise Quantum Computing Market
Next Generation Technologies
Nearfield Communication (NFC) Market
Next Generation Technologies
Quantum Computing Market