
 Global Energy Harvesting System for Wireless Sensor Network Market | 2026-2036
Global Energy Harvesting System for Wireless Sensor Network Market Size, Share, and Industry Trends Forecast 2026-2036
Global Energy Harvesting System for Wireless Sensor Network Market Foresight
The performance gap between custom-engineered energy harvesting modules and off-the-shelf photovoltaic cells is expanding, with premium tiers integrating multi-source hybrid architectures while commodity offerings rely on single-source silicon designs. EnOcean GmbH leverages proprietary kinetic-to-electrical transducers to dominate building automation channels across European commercial real estate. Texas Instruments sustains R&D intensity in ultra-low-power management ICs that condition intermittent harvester output for reliable sensor operation. STMicroelectronics anchors its position through MEMS fabrication scale, producing piezoelectric resonators with sub-milliwatt threshold sensitivity.
An energy harvesting system for wireless sensor network captures ambient mechanical, thermal, electromagnetic, or radiant energy and converts it into regulated electrical power for distributed sensing nodes, typically operating at input voltages below one volt with power budgets measured in microwatts to milliwatts. These systems eliminate battery replacement cycles in remote or inaccessible installations, enabling perpetual operation for structural integrity monitors on bridges, pipelines, and rotating machinery. Photovoltaic harvesting leads installed base across outdoor agricultural monitoring and smart city deployments where consistent solar irradiance supports predictable output. Vibration energy harvesters represent the fastest-expanding technology type as industrial predictive maintenance programs retrofit existing rotating equipment with wireless temperature and acceleration sensors. Thermoelectric generators command margin concentration in defense and oil & gas applications where extreme temperature differentials justify specialized material costs.
The EU F-Gas Regulation and REACH chemical restrictions shape component material selection, compelling harvester manufacturers to eliminate restricted substances in thermoelectric bismuth telluride formulations and polymer encapsulants. China's MIIT enforces GB standards for electromagnetic compatibility that determine market access for RF energy harvesting modules deployed in telecommunications infrastructure. The US FCC Part 15 rules constrain unintentional radiator emissions from ambient RF harvesters, directly limiting power conversion efficiency in unlicensed spectrum bands. Stakeholders must monitor evolving interoperability standards between energy harvesting power management ICs and emerging low-power wide-area network protocols.
Market Dynamics
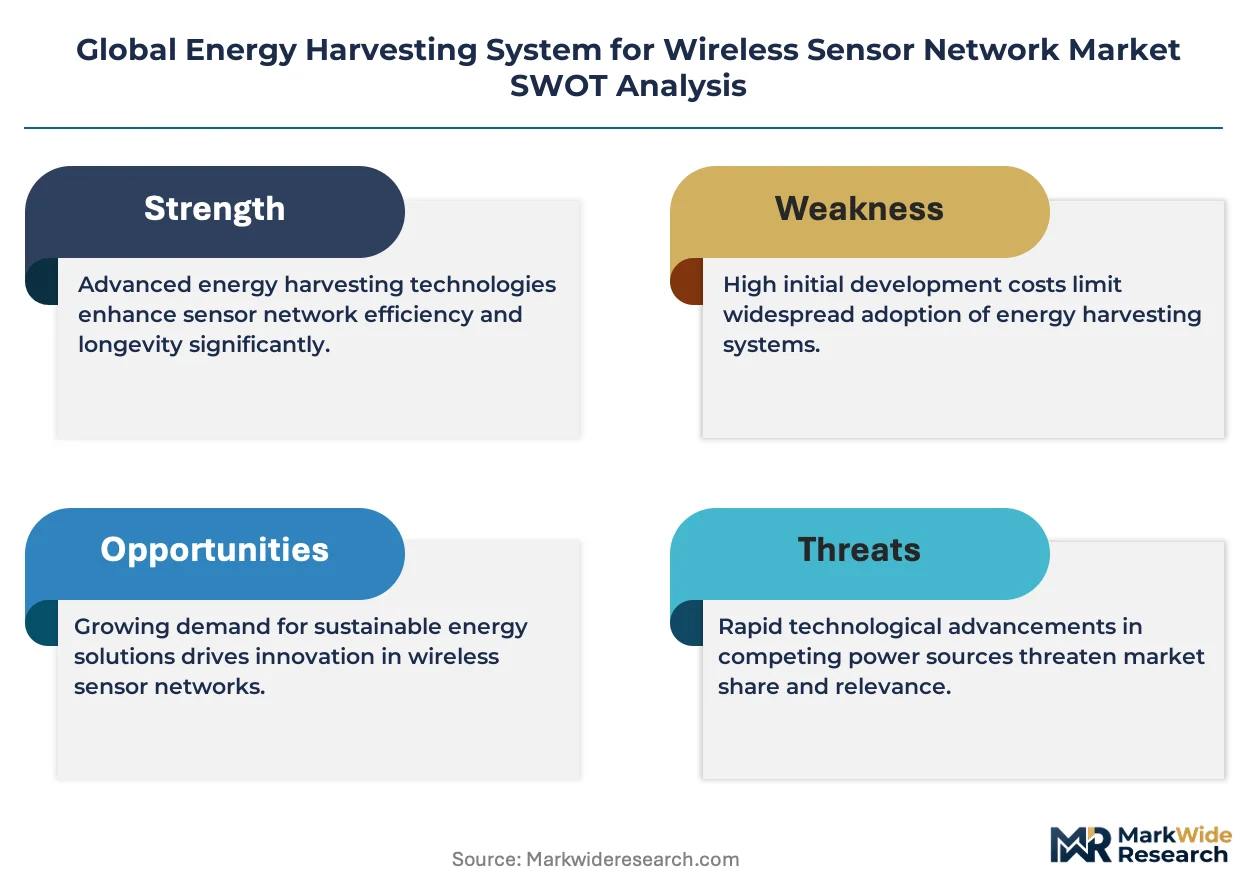
Hybrid multi-source architectures are compressing the addressable market for single-source photovoltaic modules as industrial buyers prioritize reliability over unit cost in predictive maintenance deployments.
Growth Catalysts
- EU Green Deal efficiency mandates:The framework accelerates battery substitution in building automation across German commercial real estate and Dutch logistics facilities.
- Thermoelectric material advances:Bismuth telluride formulations with enhanced figure-of-merit values unlock milliwatt-scale output from modest temperature gradients in automotive exhaust monitoring.
- East Asian manufacturing corridors:Fabs in Taiwan and automotive plants in South Korea drive concentrated demand for continuous environmental monitoring without wired infrastructure.
Market Restraints
- Raw material concentration:Tellurium supply concentrates in Chinese and Russian mining operations, exposing thermoelectric generator costs to geopolitical supply volatility.
- Power conversion physics:RF energy harvesters face hard efficiency ceilings imposed by US FCC Part 15 emission limits in unlicensed spectrum bands.
- Silicon photovoltaic commoditization:Crystalline silicon cells from Southeast Asian contract manufacturers exert price pressure on premium multi-source hybrid designs.
Strategic Opportunities
- India's PLI scheme for electronics:Domestic manufacturing incentives create localized assembly opportunities for vibration harvesters targeting textile and cement plant retrofits.
- MEMS-piezoelectric convergence:Micro-fabricated resonators integrated with conditioning electronics enable sub-milliwatt threshold sensitivity for bridge structural monitors.
- Japan's METI carbon neutrality roadmap:Building energy codes mandate wireless sensor networks in commercial structures, creating regulatory tailwind for kinetic-to-electrical transducers.
Industry Challenges
- Multi-physics simulation expertise:Harvester design requires rare cross-functional capability spanning mechanical vibration analysis, thermal engineering, and ultra-low-power electronics.
- EMC certification timelines:China's GB standards for electromagnetic compatibility impose extended validation cycles for RF energy harvesting modules before telecommunications infrastructure deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Energy Harvesting System for Wireless Sensor Network Market |
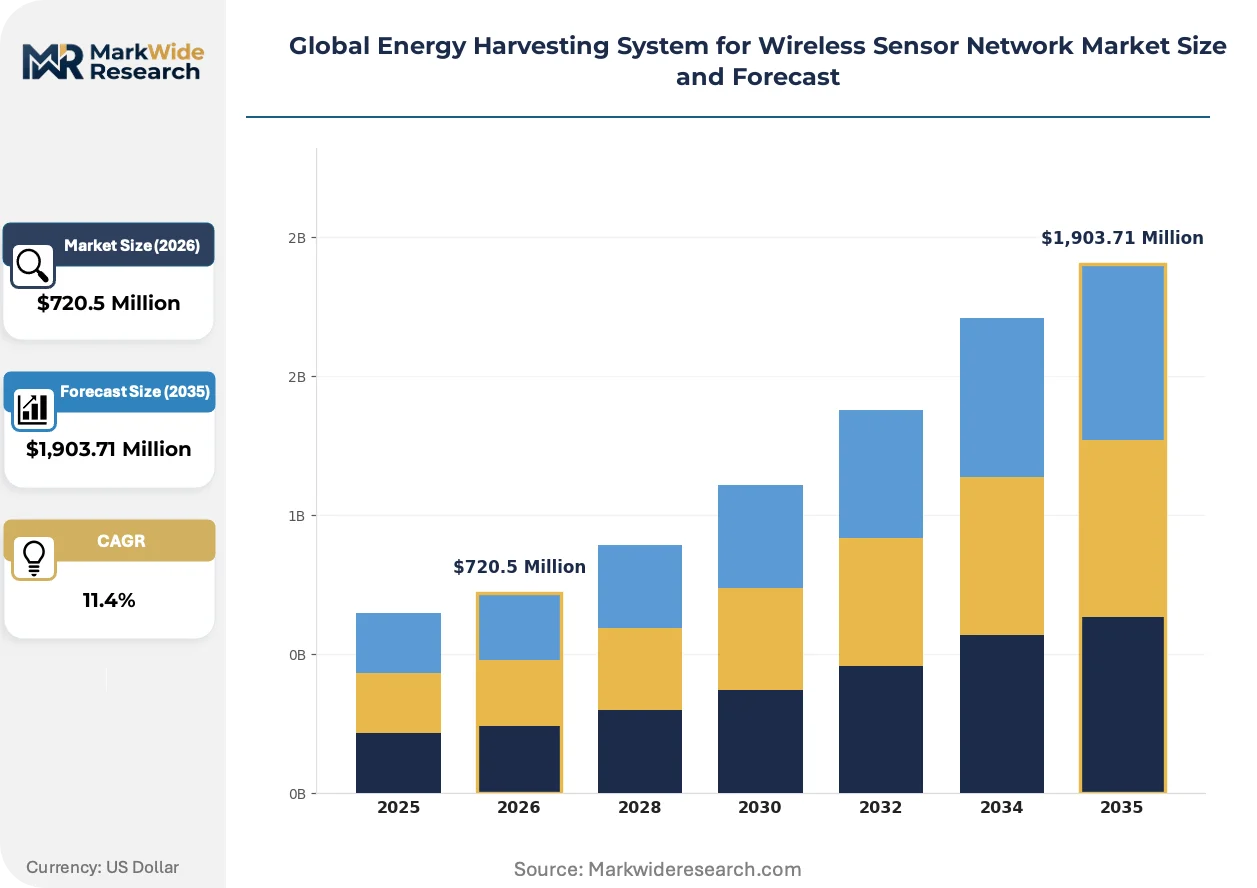
| Market Size in 2026 | $720.5 Million |
| Market Size in 2035 | $1,903.71 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Energy Source: Photovoltaic, Thermoelectric, Piezoelectric, Radio Frequency, Electromagnetic, Electrostatic Technology Type: Micro-Electromechanical Systems, Nanogenerators, Vibration Energy Harvesters, Solar Cells, Thermoelectric Generators, RF Energy Harvesters Application: Smart Cities, Agricultural Monitoring, Structural Health Monitoring, Environmental Tracking, Wildlife Tracking, Infrastructure Management End User: Telecommunication Providers, Defense Organizations, Smart Grid Operators, Oil & Gas Exploration, Transportation Networks, Building Automation |
| Companies Covered | EnOcean GmbH, Texas Instruments, STMicroelectronics, Microchip Technology, Analog Devices, Infineon Technologies, ABB Ltd, Perpetuum, Cymbet, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Energy Harvesting System for Wireless Sensor Network Market Shifts & Advancements
Convergence between ambient energy capture and ultra-low-power management ICs is collapsing the traditional separation between power generation and sensor node design. This integration is forcing architectural decisions earlier in product development cycles.
Multi-source hybrid harvesters combining photovoltaic, thermal, and vibration inputs are electrifying the premium tier of industrial predictive maintenance. Automotive plants in Stuttgart and Toyota City deploy these systems on rotating equipment where single-source reliability proves inadequate. The technology is electrifying demand for application-specific power management ICs that arbitrage between intermittent sources.
REACH chemical restrictions and the EU F-Gas Regulation are eliminating legacy thermoelectric encapsulants and refrigerant-based thermal interfaces from European supply chains. Manufacturers reformulate bismuth telluride modules with polymer substitutes that maintain thermal conductivity under restricted substance frameworks. German oil and gas sensor suppliers absorb material cost premiums to retain market access.
Buyers in heavy manufacturing are consolidating vendor relationships around full-stack energy harvesting system integrators rather than discrete component suppliers. This concentration displaces pure-play photovoltaic and piezoelectric module vendors from specification processes at German automotive and Japanese electronics producers. Channel power is accumulating with firms offering calibrated power budgets matched to specific wireless protocols.
Global Energy Harvesting System for Wireless Sensor Network Market Segmentation
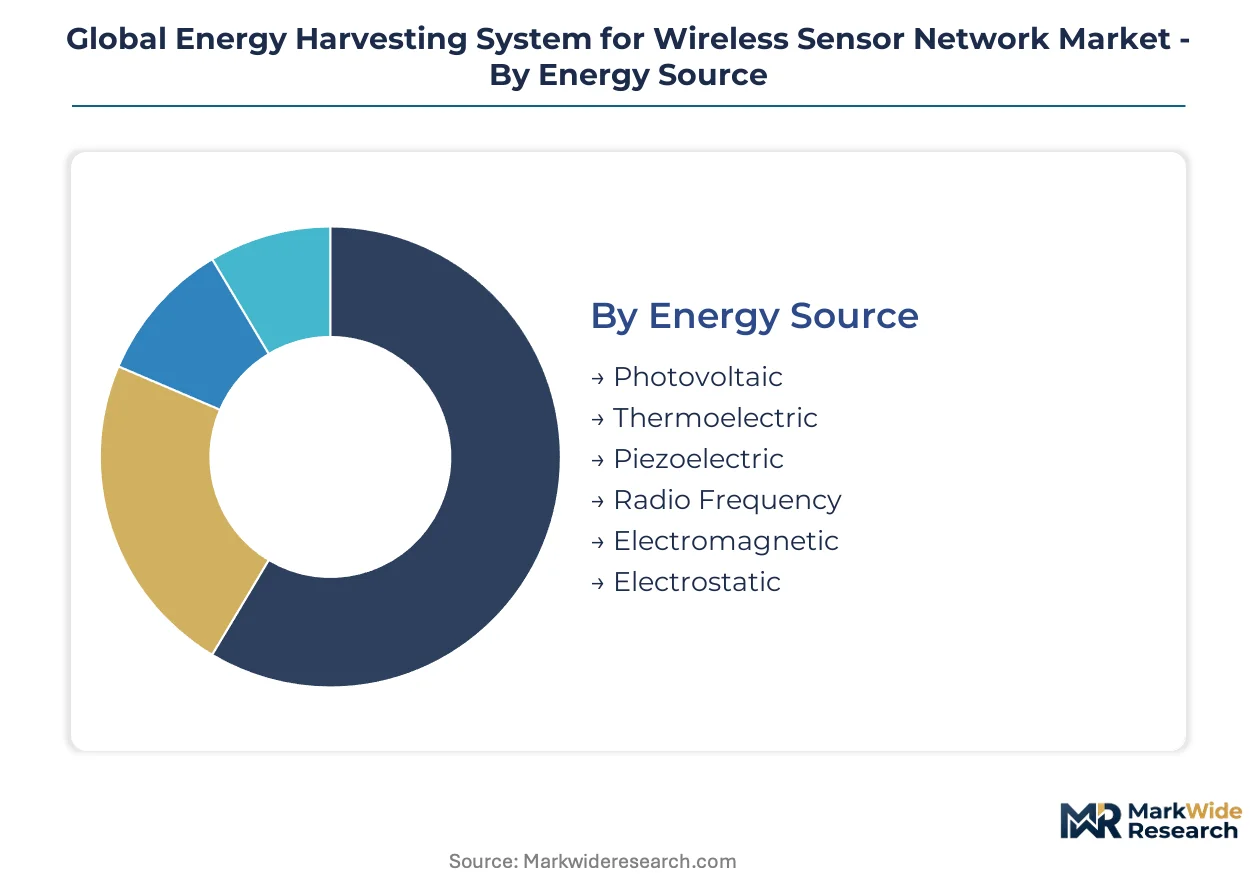
Segmentation in energy harvesting systems reveals how power generation architectures align with deployment constraints. Each dimension—energy source, technology, application, and end user—determines whether systems operate as standalone modules or embed deeply into host equipment.
Energy Source:
Photovoltaic and thermoelectric segments dominate embedded industrial applications where thermal gradients or solar exposure integrate naturally with host systems. Standalone kinetic harvesters serve retrofit markets lacking ambient infrastructure.
- Photovoltaic:Crystalline silicon and thin-film architectures convert ambient light across outdoor agricultural fields and smart city street furniture. Demand clusters in East Asian manufacturing corridors where Taiwanese fabs deploy solar-powered environmental monitors without wired infrastructure.
- Thermoelectric:Bismuth telluride junctions exploit temperature differentials in automotive exhaust systems and oil pipeline monitoring. Stuttgart automotive plants and German oil & gas sensor suppliers absorb material cost premiums under EU F-Gas and REACH chemical restrictions.
- Piezoelectric:Ceramic and polymer composites transform mechanical strain into electrical output for bridge structural integrity systems.
- Radio Frequency:Rectenna arrays capture ambient electromagnetic radiation from telecommunications infrastructure.
- Electromagnetic:Coil-and-magnet configurations harvest kinetic energy from rotating machinery in predictive maintenance programs.
- Electrostatic:Variable capacitance structures convert vibration into charge displacement for micro-watt sensor nodes.
Volume placements concentrate in Photovoltaic; the faster expansion belongs to Electromagnetic harvesters retrofitting existing industrial equipment.
Technology Type:
Technology selection tracks the power budget threshold of target applications, with MEMS-scale devices penetrating cost-sensitive volume markets while discrete generators serve high-reliability defense and energy infrastructure.
- Micro-Electromechanical Systems:Silicon-fabricated resonators and transducers achieve sub-milliwatt sensitivity through batch processing economies. STMicroelectronics anchors supply through European MEMS foundry scale, conditioning intermittent harvester output for reliable sensor operation.
- Vibration Energy Harvesters:Resonant mass-spring systems tuned to machinery fundamental frequencies electrify industrial predictive maintenance. Toyota City automotive plants and Stuttgart manufacturing facilities deploy these on rotating equipment where single-source reliability proves inadequate.
- Nanogenerators:Zinc oxide and polymer nanowire arrays target ultra-low-power biomedical and wearable applications.
- Solar Cells:Amorphous silicon and organic photovoltaic layers conform to irregular surfaces in building-integrated deployments.
- Thermoelectric Generators:Segmented thermoelectric modules optimize figure-of-merit across temperature gradients in defense and oil & gas applications.
- RF Energy Harvesters:Broadband rectenna designs face hard efficiency ceilings under US FCC Part 15 emission limits in unlicensed spectrum bands.
MEMS-based solutions claim the densest volume; Vibration Energy Harvesters are climbing the fastest as industrial retrofit programs accelerate.
Application:
Application segmentation maps directly to duty cycle requirements and accessibility constraints, with perpetual operation mandates driving specification toward multi-source hybrid architectures.
- Smart Cities:Street lighting control, parking occupancy detection, and air quality networks demand predictable power budgets across varying weather conditions. Dutch logistics facilities and German commercial real estate prioritize reliability over unit cost in building automation deployments.
- Structural Health Monitoring:Bridge strain gauges and pipeline corrosion sensors operate for decades without maintenance access. EnOcean GmbH leverages proprietary kinetic-to-electrical transducers to dominate European commercial real estate channels for these installations.
- Agricultural Monitoring:Soil moisture and microclimate sensors span remote fields with consistent solar exposure.
- Environmental Tracking:Continuous emissions and water quality monitoring requires calibrated power budgets matched to specific wireless protocols.
- Wildlife Tracking:Miniaturized biologgers impose severe weight and volume constraints on harvester design.
- Infrastructure Management:Railway track and tunnel ventilation systems integrate harvesters into existing mechanical infrastructure.
Smart Cities command the largest installed base; Structural Health Monitoring is gaining share fastest as civil engineering mandates tighten.
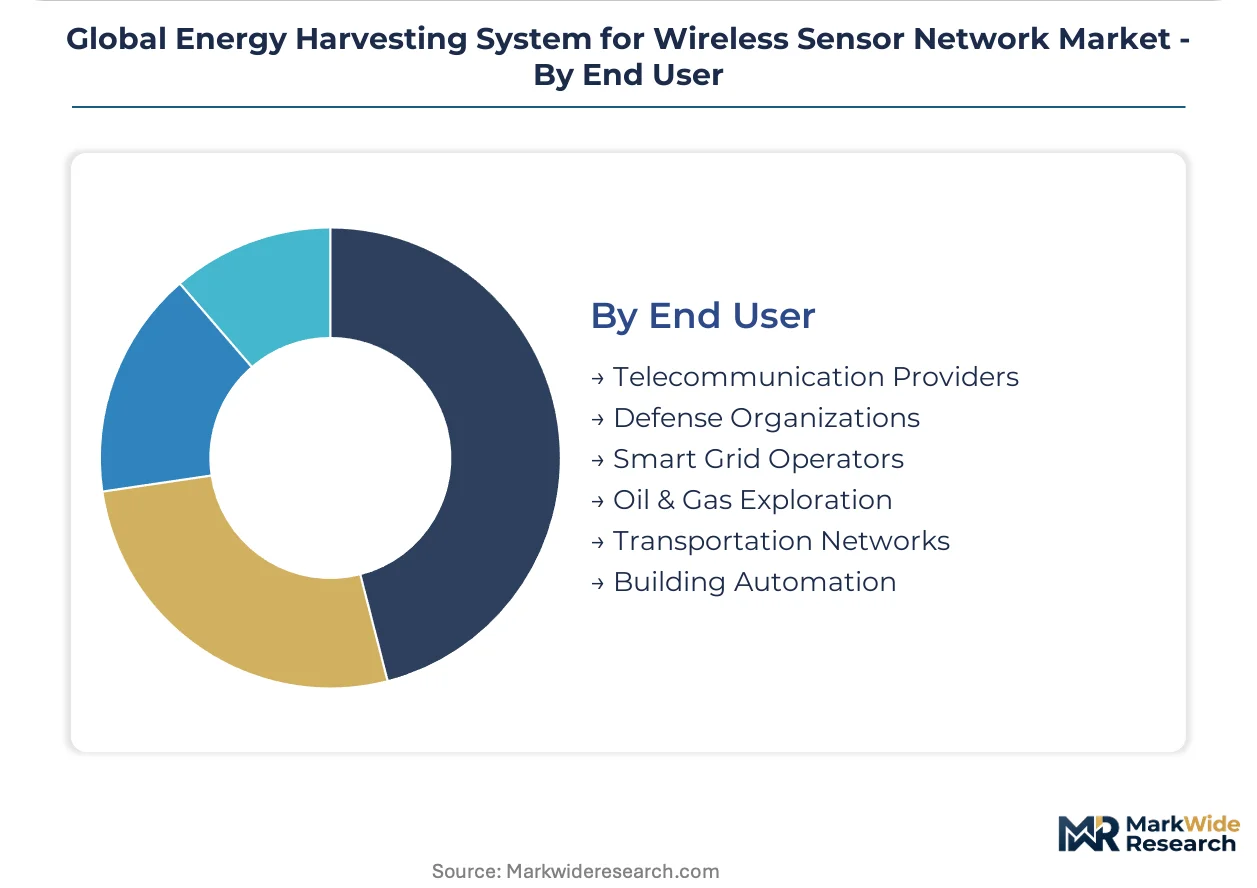
End User:
End user segmentation distinguishes between regulated infrastructure operators with extended procurement cycles and commercial buyers consolidating around full-stack system integrators.
- Building Automation:HVAC optimization and occupancy sensing in commercial structures create concentrated demand for kinetic-to-electrical transducers. Japan's METI carbon neutrality roadmap mandates wireless sensor networks, generating regulatory tailwind for European suppliers.
- Smart Grid Operators:Distribution transformer monitoring and line fault detection require electromagnetic immunity certification under China's GB standards and US FCC rules.
- Telecommunication Providers:Base station environmental monitoring and tower structural sensors deploy RF energy harvesting modules subject to extended EMC validation timelines.
- Defense Organizations:Unattended ground sensors and perimeter security systems prioritize thermoelectric reliability in extreme environments.
- Oil & Gas Exploration:Downhole pressure monitoring and pipeline leak detection justify specialized material costs for high-temperature thermoelectric generators.
- Transportation Networks:Rolling stock bearing monitors and airport baggage handling sensors convert operational vibration into sensor power.
Building Automation generates the deepest volume penetration; Smart Grid Operators show the steepest expansion trajectory as electrification infrastructure investment accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors European demand for vibration energy harvesters retrofitting automotive manufacturing lines, while East Asian manufacturing corridors from Taiwan to South Korea drive concentrated procurement of multi-source hybrid systems for fab environmental monitoring.
United States
Defense organizations and oil & gas operators in Houston and the Permian Basin deploy thermoelectric generators for unattended ground sensors and downhole pressure monitoring. The US FCC Part 15 rules constrain RF energy harvester efficiency in unlicensed spectrum bands. Silicon Valley and Boston-area IoT developers integrate photovoltaic and kinetic harvesting for smart building retrofits.
Germany
Industrial automation networks across Baden-Württemberg and Bavaria install thermoelectric harvesters for predictive maintenance on rotating machinery. The EU Green Deal efficiency mandates and REACH chemical restrictions accelerate battery substitution in commercial real estate. EnOcean GmbH leverages proprietary kinetic-to-electrical transducers to dominate building automation channels in Frankfurt and Munich logistics facilities.
China
MIIT enforces GB standards for electromagnetic compatibility that determine market access for RF energy harvesting modules in telecommunications infrastructure. The country's dual carbon goals drive substitution of battery-dependent sensors in Yangtze River Delta manufacturing zones. Shenzhen and Shanghai fabs require continuous environmental monitoring without wired power, concentrating demand for photovoltaic and vibration hybrid systems.
Japan
METI carbon neutrality roadmaps mandate wireless sensor networks in commercial structures across Tokyo and Osaka, creating regulatory tailwind for kinetic-to-electrical transducers. Toyota City automotive plants deploy vibration energy harvesters on rotating equipment where single-source reliability proves inadequate. Japanese electronics producers consolidate vendor relationships around full-stack system integrators rather than discrete component suppliers.
India
The PLI scheme for electronics creates localized assembly opportunities for vibration harvesters targeting textile plants in Gujarat and cement facility retrofits in Rajasthan. Domestic manufacturing incentives attract component suppliers to Maharashtra and Karnataka industrial corridors. Mumbai and Bangalore-based system integrators bridge between imported MEMS devices and regional deployment in smart grid and building automation applications.
Global Energy Harvesting System for Wireless Sensor Network Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology integration depth, with hybrid multi-source architectures commanding material premiums over single-source silicon photovoltaic designs. The competitive terrain separates into three tiers: MEMS-scale fabricators with foundry economies, discrete generator specialists serving defense and energy infrastructure, and full-stack system integrators consolidating channel power. Strategic moves concentrate on backward integration into thermoelectric materials and captive supply of power management ICs, alongside geographic expansion into India's PLI-subsidized assembly corridors.
Within the MEMS-fabrication tier, STMicroelectronics anchors European supply through batch-processing scale for piezoelectric resonators with sub-milliwatt threshold sensitivity. Texas Instruments and Analog Devices occupy positions in ultra-low-power management ICs that condition intermittent harvester output. EnOcean GmbH exemplifies the full-stack integrator archetype, dominating building automation channels through proprietary kinetic-to-electrical transducers rather than commodity component sales.
| Leading Market Players |
|---|
| EnOcean GmbH |
| Texas Instruments |
| STMicroelectronics |
| Microchip Technology |
| Analog Devices |
| Infineon Technologies |
| ABB Ltd |
| Perpetuum |
| Cymbet |
| Others |
Supply & Pricing Matrix
Captive integration into bismuth telluride refining and MEMS fabrication anchors supply position for premium harvester tiers, while outsourced silicon photovoltaic assembly cedes pricing power to Southeast Asian contract manufacturers. This structural split concentrates margin capture with firms controlling thermoelectric material formulations and foundry-scale resonator production.
Pricing Analysis
Value-based pricing anchored to uptime guarantees and predictive maintenance yield compression dominates industrial procurement. Three-tier pricing structure across premium hybrid systems, standard single-source modules, and economy photovoltaic cells reflects certification grade differentiation under EU F-Gas and REACH frameworks. Cost compression in commodity silicon tiers intensifies as Taiwanese and Chinese contract manufacturers expand crystalline cell capacity. Smart grid operators and defense organizations exhibit lowest price sensitivity, while agricultural monitoring buyers prioritize unit economics over reliability specifications.
Supply Chain Analysis
Freight costs from Chinese and Russian tellurium mining operations to German and Japanese thermoelectric fabricators impose geographic premiums on bismuth telluride junctions. Supply draws from concentrated rare earth extraction in Inner Mongolia, refined semiconductor-grade silicon in Hsinchu, and polymer encapsulant production in Bavaria. Single-source vulnerability in tellurium supply exposes generator costs to export restriction risk. Distribution runs through full-stack system integrators consolidating channel power away from discrete component vendors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where EU F-Gas Regulation and REACH chemical restrictions erect barrier-to-entry moats favoring incumbent material reformulation capabilities.
For Market Incumbents: Anticipate displacement by MEMS-piezoelectric convergence from STMicroelectronics-scale fabricators by deepening captive bismuth telluride supply and accelerating power management IC integration. Prioritize certification investment for China's GB electromagnetic compatibility standards to preempt extended validation timelines for telecommunications infrastructure deployment. For New Entrants and Emerging Players: Capture white-space in India's PLI-subsidized assembly corridors for vibration harvesters targeting Gujarat textile and Rajasthan cement retrofits, where localized production escapes incumbent channel lock-in. Penetrate through Mumbai and Bangalore system integrators bridging imported MEMS devices with regional smart grid deployment. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by industrial automation conglomerates seeking wireless sensor network capabilities; long-term viability hinges on hybrid architecture IP and regulatory compliance infrastructure. Monitor Japan's METI carbon neutrality roadmap enforcement as inflection signal for kinetic-to-electrical transducer demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Thermoelectric Materials | Captive bismuth telluride supply secures margin against Chinese and Russian tellurium volatility. |
| MEMS-Piezoelectric Convergence R&D | Micro-fabricated resonators enable sub-milliwatt sensitivity for bridge structural monitors. |
| GB Standards Certification Investment | Preemptive EMC validation accelerates telecommunications infrastructure deployment access. |
| PLI Scheme Localization in India | Maharashtra and Karnataka assembly corridors capture textile and cement plant retrofit demand. |
| Full-Stack System Integration | Calibrated power budget matching to wireless protocols consolidates channel power against component vendors. |
Research Methodology
SEC filings from energy harvesting power management IC suppliers, ECHA REACH substance restriction databases, and MIIT GB standards documentation formed the secondary backbone, cross-referenced with primary interviews across plant engineers at Stuttgart automotive facilities, procurement leads at Dutch logistics operators, and regulatory affairs specialists at German oil and gas sensor suppliers. Bottom-up unit economics from fab environmental monitoring deployments and top-down industrial automation capex trajectories were triangulated against disclosed foundry capacity expansions.
Historical trendline analysis across thermoelectric material cost curves, MEMS batch processing yield improvements, and photovoltaic efficiency trajectories informed the projection framework. Segmentation dimensions modeled encompass energy source architecture, technology type scale, application duty cycle requirements, and end-user procurement consolidation patterns. CAGRs derived from regression against industrial IoT sensor node shipment growth and wireless protocol adoption curves, with specific inputs from EU Green Deal implementation timelines and China's dual carbon goal enforcement intensity.
The model holds under sustained regulatory enforcement of EU F-Gas and REACH restrictions; deviation in rare earth export controls or electromagnetic compatibility standard harmonization would shift competitive positioning. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors
Global Radio Frequency Identification (RFID) Smart Cabinet Market
Sensors
Mobile Lidar Scanner Market
Sensors
Weigh-In-Motion System Market
Sensors
Wireless Occupancy Sensors Market
Sensors
Global Weather Monitoring Solutions and Services Market
Sensors
Conveyor Monitoring Market
Sensors
North America Eye Tracking Solutions Market
Sensors
Handheld RFID Readers Market
Sensors
Automated Weather Observation System Market
Sensors
Europe Remote Sensing Technology Market
Sensors
Lidar in Construction Market
Sensors
Bluetooth Beacons Market
Sensors
Asset Tags Market
Sensors
India Asset Tracking Market
Sensors
Asia-Pacific Remote Sensing Technology Market
Sensors
Global Smart Leak Detection Solutions Market