
 Global Next Generation Wireless Communication Market | 2026-2036
Global Next Generation Wireless Communication Market Size, Share, and Industry Trends Forecast 2026-2036
Global Next Generation Wireless Communication Market Outlook
Automotive connectivity is consolidating as the fastest-expanding end-use vertical for next generation wireless infrastructure. Qualcomm Technologies anchors cellular modem leadership through sustained R&D intensity in C-V2X protocols. Samsung Electronics dominates network equipment supply for Korean and Southeast Asian carrier rollouts. Ericsson AB navigates European Open RAN transitions while competing for greenfield 5G contracts across the Middle East and Africa.
Next generation wireless communication encompasses radio access networks, core network virtualization, and spectrum-efficient transmission protocols operating across sub-6 GHz and millimeter-wave bands with latency targets below one millisecond for ultra-reliable low-latency communication. The technology enables massive machine-type communications, enhanced mobile broadband, and critical IoT services across industrial and consumer domains. 5G deployment models currently generate the largest revenue pools as carriers amortize spectrum investments through enterprise service contracts. Edge computing architectures represent the fastest-growing structural segment as manufacturers and logistics operators demand localized data processing. Satellite communication remains nascent for direct-to-device consumer services but commands premium margins in defense and maritime applications.
The FCC governs spectrum allocation and equipment authorization in the United States, while ETSI and national regulators across Germany, France, and Italy enforce CE marking and cybersecurity standards for network infrastructure. China's MIIT mandates domestic encryption standards and equipment certification procedures that shape vendor market access. Stakeholders must monitor spectrum harmonization negotiations between ITU regions and assess how national security screening regimes affect supplier diversification strategies.
Market Dynamics
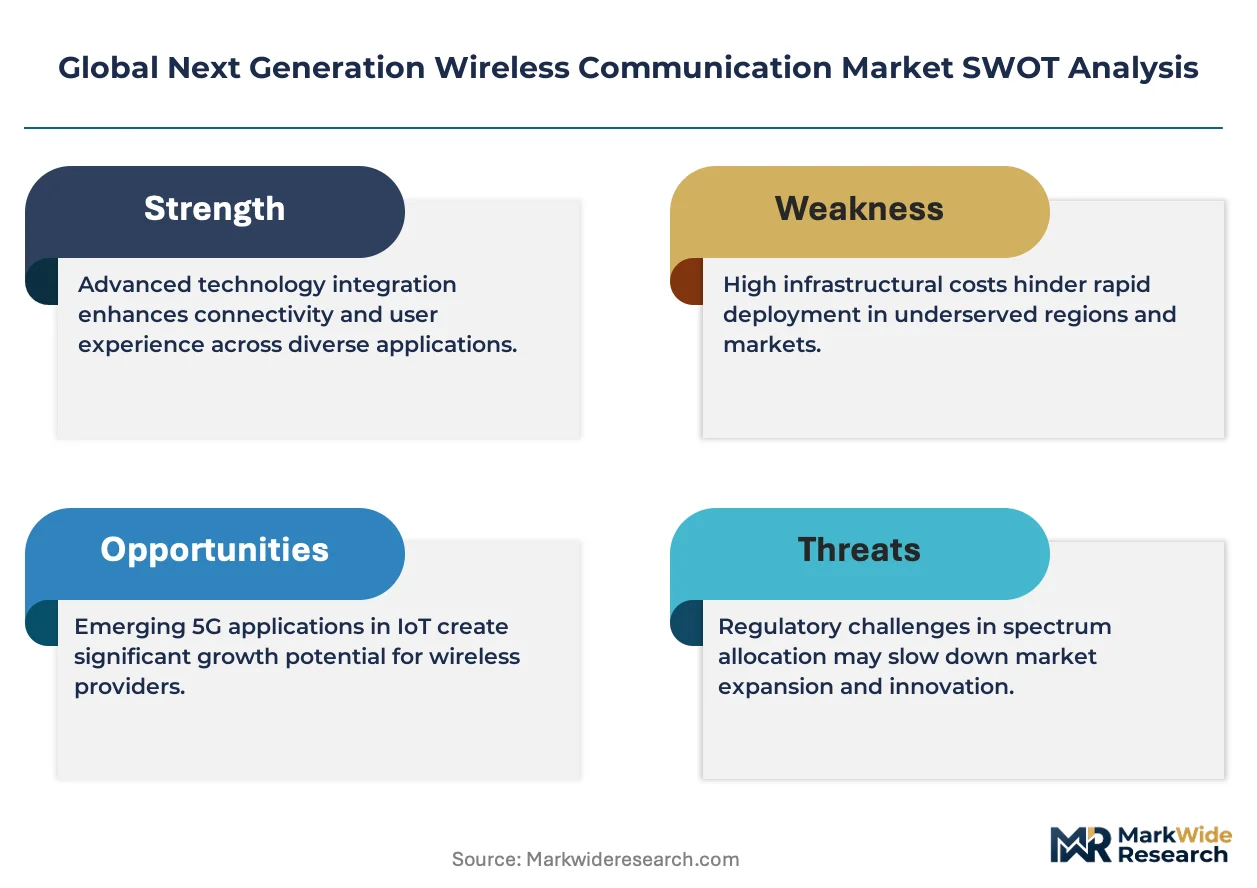
Open RAN mandates from the FCC and EU AI Act compliance requirements are accelerating infrastructure replacement cycles across carrier networks. Spectrum harmonization negotiations between ITU regions and national security screening regimes are forcing vendor diversification strategies.
Growth Catalysts
- Automotive C-V2X deployment:Vehicle-to-everything protocols are mandating cellular modem integration across passenger and commercial fleets in Germany and the United States.
- EU AI Act infrastructure mandates:Network equipment must meet cybersecurity certification timelines, compressing replacement cycles for European carriers.
- Industrial edge computing demand:Manufacturing and logistics operators in China require localized data processing below one millisecond latency.
Market Restraints
- Millimeter-wave spectrum scarcity:Physical propagation limitations constrain deployment density in urban environments across Japan and South Korea.
- Equipment vendor concentration:Korean and Southeast Asian carrier rollouts depend on a narrow supplier base for radio access network hardware.
- FCC equipment authorization delays:Certification backlogs extend time-to-market for new base station architectures in the United States.
Strategic Opportunities
- Sub-6 GHz rural expansion:Underserved regions in India present white-space deployment potential for massive machine-type communications.
- Satellite-to-device convergence:Direct-to-handset services combining terrestrial and non-terrestrial networks unlock maritime and defense premiums.
- Greenfield 5G contracts:Middle Eastern and African carriers lack legacy infrastructure, enabling native Open RAN architectures.
Industry Challenges
- RF engineering talent scarcity:Specialized expertise in millimeter-wave antenna design concentrates in Qualcomm and Samsung hiring pools.
- Core network virtualization integration:Legacy 4G packet core systems require complex interworking with 5G standalone architectures.
- Dual carbon compliance timelines:China's MIIT energy efficiency mandates compress power consumption reduction targets for base station deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Next Generation Wireless Communication Market |
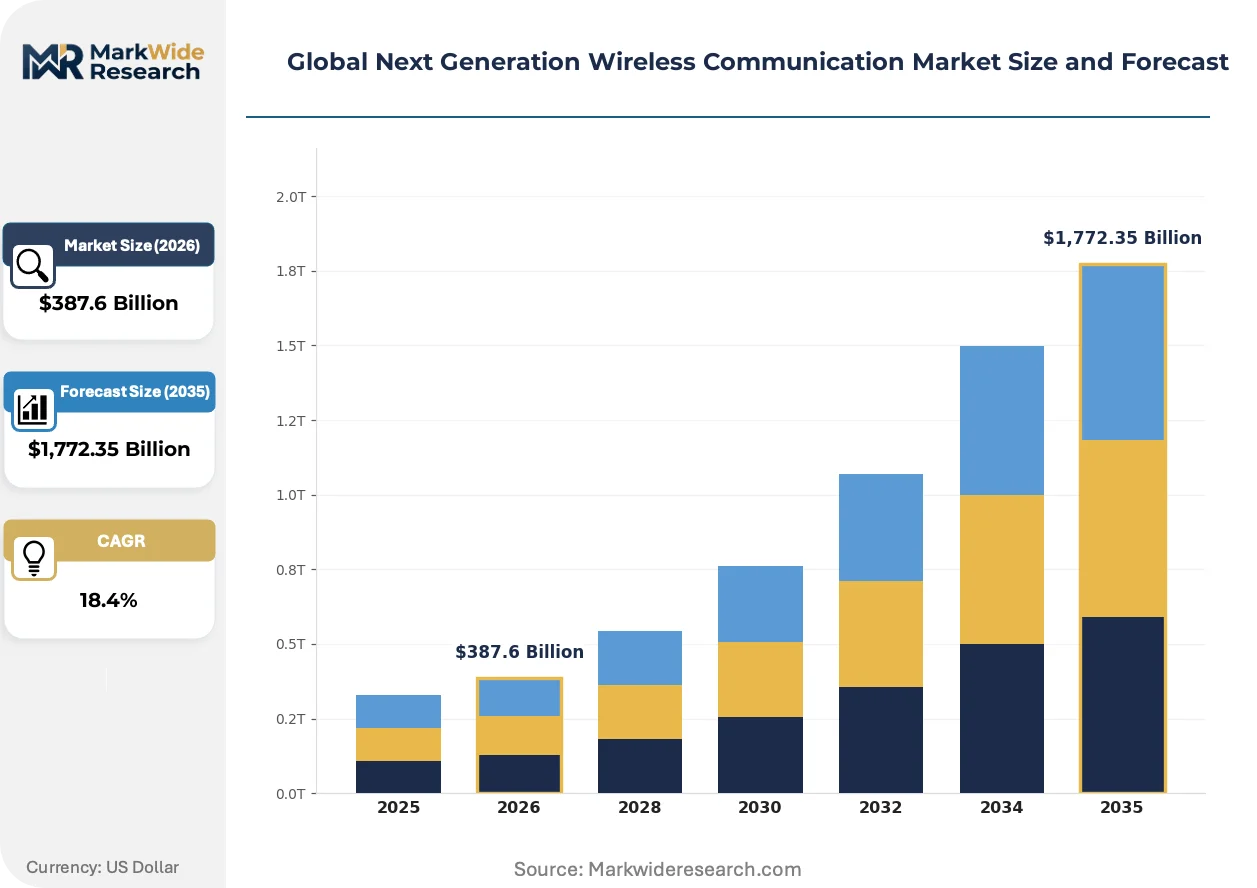
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $1,772.35 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: 5G, LTE, Wi-Fi 6, Satellite Communication Deployment Model: On-Premises, Cloud, Hybrid, Edge Computing End User: Telecom Providers, Enterprise, Government, Automotive Application: IoT, Smart Cities, AR/VR, Industrial Automation |
| Companies Covered | Huawei Technologies Co. Ltd, Qualcomm Technologies, Ericsson AB, Nokia Corporation, Samsung Electronics Co. Ltd, Cisco Systems Inc, Intel Corporation, ZTE Corporation, Broadcom Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Next Generation Wireless Communication Market Strategic Shifts
Wireless infrastructure is fragmenting across multiple simultaneous technology transitions. Radio access network architectures, spectrum utilization methods, and service delivery models are all undergoing parallel reinvention.
Open RAN disaggregation is overtaking monolithic base station designs. The architecture separates radio units, distributed units, and centralized units through standardized interfaces. Tier-one carriers in Germany and Japan are piloting multi-vendor combinations. This interface standardization is compressing incumbent equipment margins while enabling specialized component suppliers.
The EU AI Act imposes cybersecurity certification and risk classification on network infrastructure vendors. Equipment must demonstrate conformity with CE marking extensions for automated decision-making systems. European carriers are restructuring procurement specifications to embed these compliance checkpoints into vendor qualification workflows.
Enterprise buyers are consolidating wireless service contracts around outcome-based performance guarantees. Manufacturing and automotive clients now specify latency, reliability, and throughput thresholds rather than bandwidth volumes. This metric shift is most visible in United States industrial digitization programs where private 5G networks displace Wi-Fi for mission-critical control systems.
Global Next Generation Wireless Communication Market Segmentation
Wireless infrastructure investment patterns diverge sharply across technology generations and deployment architectures. Procurement decisions in this market hinge on latency specifications, spectrum availability, and regulatory compliance timelines that vary by national jurisdiction.
Technology:
Technical specifications determine spectrum utilization efficiency and equipment interoperability requirements across carrier networks.
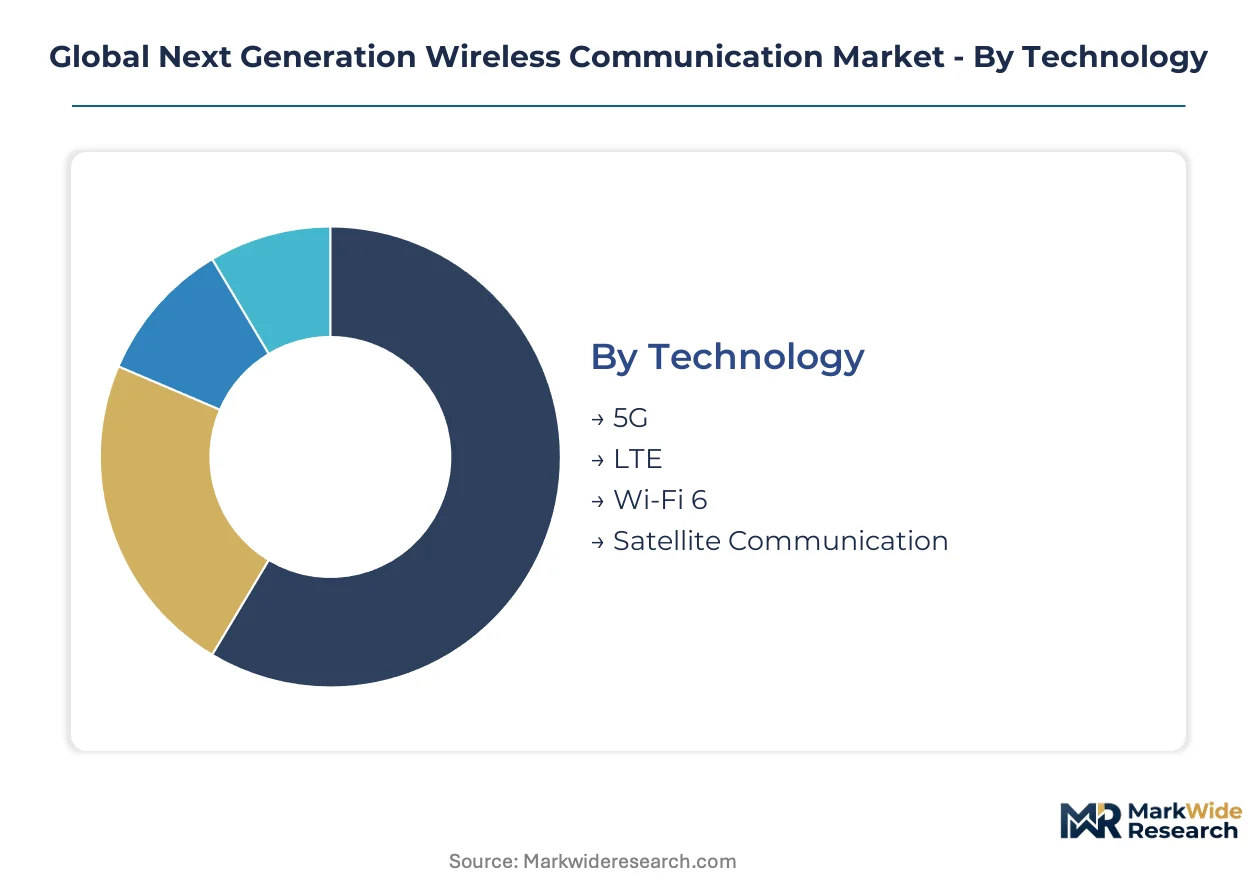
- 5G:New radio interfaces operate across sub-6 GHz and millimeter-wave bands with sub-one-millisecond latency targets. Telecom providers in Germany and the United States prioritize standalone 5G core deployments to support network slicing for industrial clients.
- LTE:Existing 4G infrastructure provides fallback coverage and voice services during 5G non-standalone transitions. Chinese carriers leverage extensive LTE footprints to anchor dual-connectivity architectures while spectrum auctions proceed.
- Wi-Fi 6:IEEE 802.11ax standards deliver orthogonal frequency-division multiple access for dense enterprise environments. Manufacturing facilities in Japan deploy Wi-Fi 6 for indoor asset tracking where cellular penetration remains economically prohibitive.
- Satellite Communication:Non-terrestrial networks extend coverage to maritime corridors and remote defense installations. Direct-to-device services command premium pricing in applications where terrestrial infrastructure cannot achieve economic density.
5G leads on scale; satellite communication leads on momentum.
Deployment Model:
Capital expenditure flexibility and operational control requirements shape infrastructure architecture choices across enterprise and carrier segments.
- On-Premises:Dedicated hardware installations provide deterministic performance for mission-critical control systems. Automotive manufacturers in Germany deploy private on-premises networks to isolate C-V2X traffic from public carrier congestion.
- Cloud:Centralized network functions virtualization reduces physical footprint and accelerates service provisioning. Telecom providers in India favor cloud-native core deployments to minimize real estate costs in dense urban markets.
- Hybrid:Split processing between edge and central facilities balances latency requirements against economies of scale. Logistics operators in the United States adopt hybrid models to process sensitive inventory data locally while aggregating analytics centrally.
- Edge Computing:Distributed compute nodes position processing within one hop of end devices. Industrial automation deployments in China require edge architectures to meet sub-ten-millisecond response thresholds for robotic control systems.
Cloud deployments dominate carrier procurement volumes; edge computing is climbing the fastest as manufacturing digitization accelerates.
End User:
Buyer sophistication and procurement scale create distinct commercial dynamics across customer categories.
- Telecom Providers:National carriers amortize spectrum investments through multi-year enterprise service contracts. FCC equipment authorization requirements and Open RAN mandates in the United States compress vendor qualification timelines.
- Enterprise:Private network deployments bypass public infrastructure congestion for security-sensitive operations. Mining and energy extraction companies in Australia commission dedicated wireless systems where terrestrial coverage gaps persist.
- Government:Defense and public safety agencies mandate encrypted communications with sovereign control over routing infrastructure. Military procurement in Saudi Arabia prioritizes satellite-terrestrial convergence for theater-wide connectivity.
- Automotive:C-V2X protocol integration requires cellular modems across passenger and commercial vehicle fleets. German KBA type-approval regulations mandate interoperability certification for vehicle-to-infrastructure communications.
Telecom providers anchor volume commitments; automotive is gaining share fastest as regulatory mandates proliferate.
Application:
Use-case performance requirements dictate radio access network configuration and core network resource allocation.
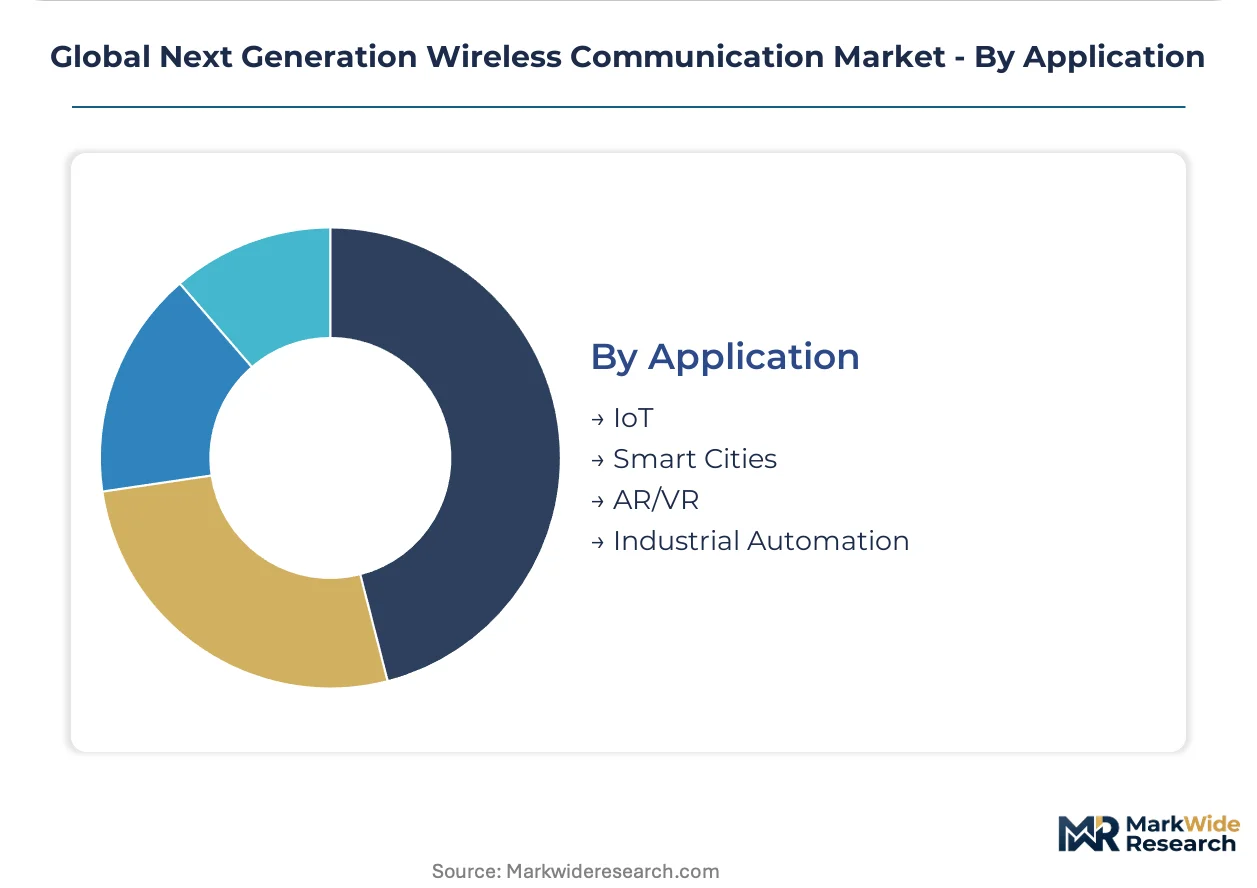
- IoT:Massive machine-type communications support sensor densities exceeding one million devices per square kilometer. Agricultural operators in Brazil deploy narrowband-IoT for precision irrigation monitoring across remote plantation estates.
- Smart Cities:Integrated traffic management and environmental monitoring systems require heterogeneous network access. Municipal authorities in Singapore coordinate 5G, Wi-Fi 6, and LPWAN overlays to unify civic data platforms.
- AR/VR:Immersive media applications demand sustained throughput above one hundred megabits per second with motion-to-photon latency below twenty milliseconds. South Korean carriers target consumer AR/VR as a differentiated service tier in saturated mobile markets.
- Industrial Automation:Time-sensitive networking for robotic control mandates ultra-reliable low-latency communication slices. Automotive assembly plants in Mexico specify private 5G networks to replace wired fieldbus connections on flexible production lines.
IoT leads on installed device base; industrial automation shows the steepest expansion trajectory as manufacturing reshoring intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting wireless infrastructure investment toward jurisdictions with faster equipment certification timelines and clearer spectrum allocation rules. The FCC's streamlined authorization processes attract vendor R&D facilities, while EU AI Act compliance costs push some testing activities toward Asian certification hubs.
United States
Automotive C-V2X mandates from the NHTSA and FCC spectrum auctions for 3.45 GHz and 2.5 GHz bands are accelerating carrier capital deployment. The FCC's Open RAN roadmap pressures incumbent vendors to disaggregate radio access network architectures. Detroit's automotive corridor and Austin's semiconductor cluster anchor private 5G network pilots for manufacturing automation.
Germany
Industrial digitization programs under the EU Green Deal and KBA vehicle-to-infrastructure certification requirements are compressing procurement cycles for network equipment. The EU AI Act imposes cybersecurity conformity assessments on automated network management systems. Bavaria's automotive belt and North Rhine-Westphalia's Ruhr industrial zone host dense private 5G deployments for factory automation.
China
MIIT mandates for domestic encryption standards and dual carbon energy efficiency targets are reshaping base station deployment specifications. The country's spectrum harmonization with ITU Region 3 allocations accelerates millimeter-wave trials. Shenzhen's electronics manufacturing hub and Beijing's R&D corridor concentrate vendor engineering centers for radio unit design.
Japan
METI subsidies for local 5G networks and JIS standards for industrial wireless are expanding enterprise procurement beyond carrier-managed services. Spectrum allocations in the 28 GHz and 4.5 GHz bands support manufacturing use cases. Nagoya's automotive cluster and Tokyo's financial district drive demand for ultra-reliable low-latency communication slices.
South Korea
MFDS equipment certification alignment with 3GPP Release 17 and government funding for 6G pre-standardization research are sustaining R&D intensity. Carrier competition in saturated mobile markets pushes AR/VR service differentiation. Seoul's metropolitan network and Busan's port complex deploy edge computing nodes for logistics automation.
Global Next Generation Wireless Communication Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated equipment vendors holding dominant positions in radio access networks while semiconductor specialists capture modem and baseband value. The market exhibits tiered concentration: three large-scale infrastructure providers anchor carrier procurement, followed by component specialists and regional system integrators. Strategic archetypes include spectrum-integrated full-stack vendors, silicon-focused semiconductor designers, and Open RAN software specialists. Competitive dynamics center on vertical integration into radio unit manufacturing and geographic expansion through greenfield 5G contracts in emerging markets.
Within the infrastructure tier, Huawei Technologies Co. Ltd and Ericsson AB occupy positions reflecting divergent geographic market access strategies. Among semiconductor specialists, Qualcomm Technologies and Broadcom Corporation exemplify contrasting approaches to cellular modem and radio frequency component supply. Samsung Electronics Co. Ltd anchors a hybrid archetype spanning network equipment and consumer device integration. These three named entities represent the primary competitive anchors without exhaustively mapping the vendor landscape.
| Leading Market Players |
|---|
| Huawei Technologies Co. Ltd |
| Qualcomm Technologies |
| Ericsson AB |
| Nokia Corporation |
| Samsung Electronics Co. Ltd |
| Cisco Systems Inc |
| Intel Corporation |
| ZTE Corporation |
| Broadcom Corporation |
| Others |
Value Chain & Pricing Dynamics
RF engineering talent concentration in South Korea and Taiwan widens labor-cost differentials between premium-tier base station architectures and economy-grade radio units. Equipment vendors leverage these regional wage spreads to stratify pricing across performance tiers while maintaining margin buffers on high-complexity millimeter-wave designs.
Pricing Analysis
Distributor margins on radio access network hardware typically absorb 12-18 points before carrier procurement. Three-tier pricing structure across premium, standard, and economy levels separates Open RAN-compliant multi-vendor stacks from monolithic legacy deployments and white-label component sourcing. Price differentiation rests on certification grade—FCC equipment authorization and CE marking extensions for EU AI Act compliance command substantial premia. Cost compression in standard-tier baseband units is intensifying because Chinese vendors are flooding sub-6 GHz markets with MIIT-certified alternatives. Enterprise buyers in industrial automation show lowest price sensitivity, while rural carriers in emerging markets operate under severe budget constraints.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale carrier demand for radio units and baseband processors, bypassing distributor markups on volume commitments. Geographic supply concentration centers on China for printed circuit board fabrication and final assembly, South Korea for RF front-end components and memory modules, and Taiwan for advanced semiconductor foundry services. Raw material dependencies include gallium nitride substrates for power amplifiers, high-purity copper for antenna conductors, and rare earth elements for ceramic filter substrates. Single-source vulnerability in millimeter-wave filter supply creates chokepoint exposure when Japanese specialty ceramic producers face capacity constraints. Distribution runs through carrier-direct procurement for tier-one deployments and systems integrators for private enterprise networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Next Generation Wireless Communication Market functions as a regulatory compounder where FCC Open RAN mandates and EU AI Act compliance deadlines are compressing infrastructure replacement cycles into concentrated demand windows.
For Market Incumbents: Deepen captive supply of gallium nitride power amplifiers through backward integration into semiconductor foundry partnerships. Fortify Open RAN software stacks against emerging cloud-native challengers by accelerating multi-vendor interoperability certification. Prioritize R&D allocation toward C-V2X protocol optimization as automotive connectivity displaces consumer broadband as the primary revenue anchor. For New Entrants and Emerging Players: EU AI Act cybersecurity certification requirements in Germany open a window for specialized compliance-testing service providers. Greenfield 5G contracts across Middle Eastern carriers present the most penetrable infrastructure segment given minimal legacy equipment lock-in. Position around satellite-to-device convergence architectures where defense and maritime premiums offset terrestrial market saturation. For Investors and Strategic Acquirers: Defense contractors are the most active acquirer in this space, consolidating satellite-terrestrial convergence capabilities for sovereign communications infrastructure. Long-term viability hinges on 5G-Advanced and 6G pre-standardization positioning rather than current-generation equipment margins. Target acquisition archetypes include Open RAN software specialists with proven multi-vendor integration track records. Monitor NHTSA C-V2X mandate enforcement timelines as inflection indicators for automotive modem demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Open RAN Architecture Disaggregation | FCC mandates in the United States force incumbent vendors to unbundle radio units from baseband processing. |
| C-V2X Protocol Certification Investment | German KBA type-approval requirements mandate interoperability testing for vehicle-to-infrastructure communications. |
| Edge Computing Node Deployment | MIIT energy efficiency targets in China compress power consumption specifications for distributed compute infrastructure. |
| Satellite-Terrestrial Convergence Development | Saudi defense procurement prioritizes theater-wide connectivity combining non-terrestrial and cellular networks. |
| Multi-Vendor Interoperability Testing | Japanese carrier pilots in Nagoya validate standardized interfaces between radio units and centralized units. |
Study Parameters
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Primary interviews engaged carrier procurement executives, RF engineering directors at equipment vendors, regulatory affairs specialists, and enterprise IT infrastructure leads. Secondary sources included FCC equipment authorization databases, ETSI standardization documents, MIIT certification registries, 3GPP release documentation, and carrier capital expenditure disclosures. Bottom-up equipment shipment modeling and top-down spectrum investment aggregation were triangulated against disclosed vendor revenue allocations.
Granularity-level modeling operated at technology generation, deployment architecture, and end-user segment dimensions across the analysis window. Separate projections were constructed for sub-6 GHz versus millimeter-wave radio unit volumes, standalone versus non-standalone core deployments, and private enterprise versus carrier-managed service delivery. CAGRs were derived from logistic diffusion curves fitted to announced spectrum auction timelines and regulatory mandate enforcement dates. Industry-specific forecast inputs encompassed FCC Open RAN roadmap milestones, EU AI Act certification deadline schedules, and NHTSA C-V2X mandate implementation phases.
Revisions become necessary when spectrum harmonization negotiations between ITU regions stall, equipment vendor concentration triggers antitrust intervention, or geopolitical restrictions disrupt semiconductor supply chains. Forecasts reflect assumptions regarding regulatory enforcement consistency, standardization body timeline adherence, and carrier capital commitment durability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Next Generation Technologies
Hyperscale Edge Computing Market
Next Generation Technologies
Hyperloop Technology Market
Next Generation Technologies
Poc Platform and Technology Market
Next Generation Technologies
Enterprise Quantum Computing Market
Next Generation Technologies
Fog Computing Market
Next Generation Technologies
Malaysia ICT Market
Next Generation Technologies
M2M Connections Market
Next Generation Technologies
Next Generation Wireless Network Market
Next Generation Technologies
Information and Communications Technology (ICT) Market
Next Generation Technologies
GCC ICT Market
Next Generation Technologies
Europe Quantum Computing Market
Next Generation Technologies
Quantum Computing Market
Next Generation Technologies
Next-Generation Communication Devices Market
Next Generation Technologies
Nearfield Communication (NFC) Market
Next Generation Technologies
Nigeria ICT Market
Next Generation Technologies
Ireland ICT Market