
 Global Smart Hubs Market | 2026-2036
Global Smart Hubs Market Size, Share, and Industry Trends Forecast 2026-2036
Global Smart Hubs Market Outlook
Buyer concentration in the residential construction sector is decoupling from traditional retail channels as property developers and utility providers become direct procurement channels for smart hub deployments. Samsung Electronics leverages its appliance ecosystem to anchor hub functionality within kitchen and climate product lines. Amazon.com Inc. sustains channel control through Alexa-enabled distribution, while Google LLC competes by extending Nest integration into energy utility partnerships across multiple continents.
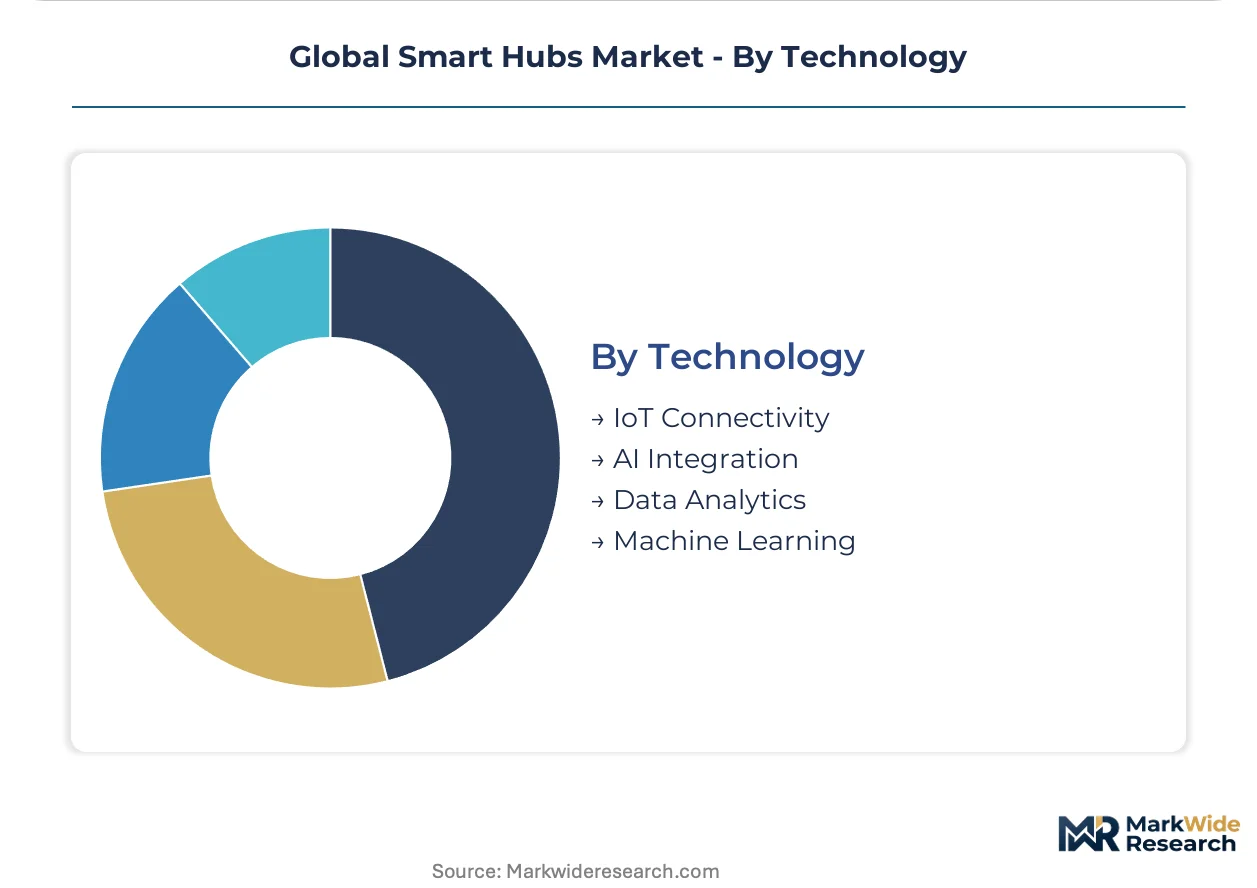
A smart hub functions as a centralized control device that aggregates wireless protocols including Zigbee, Z-Wave, Wi-Fi, and Thread to orchestrate connected devices within residential, commercial, or industrial environments. The hardware processes local automation routines while maintaining cloud synchronization for remote access and firmware updates. Integrated solutions currently occupy the largest margin pool as bundled platform-and-service contracts generate recurring revenue streams. Cloud-based platforms represent the fastest-expanding category as over-the-air update architectures reduce hardware replacement cycles. IoT Connectivity leads technology adoption while AI Integration differentiates premium offerings through predictive automation and anomaly detection capabilities.
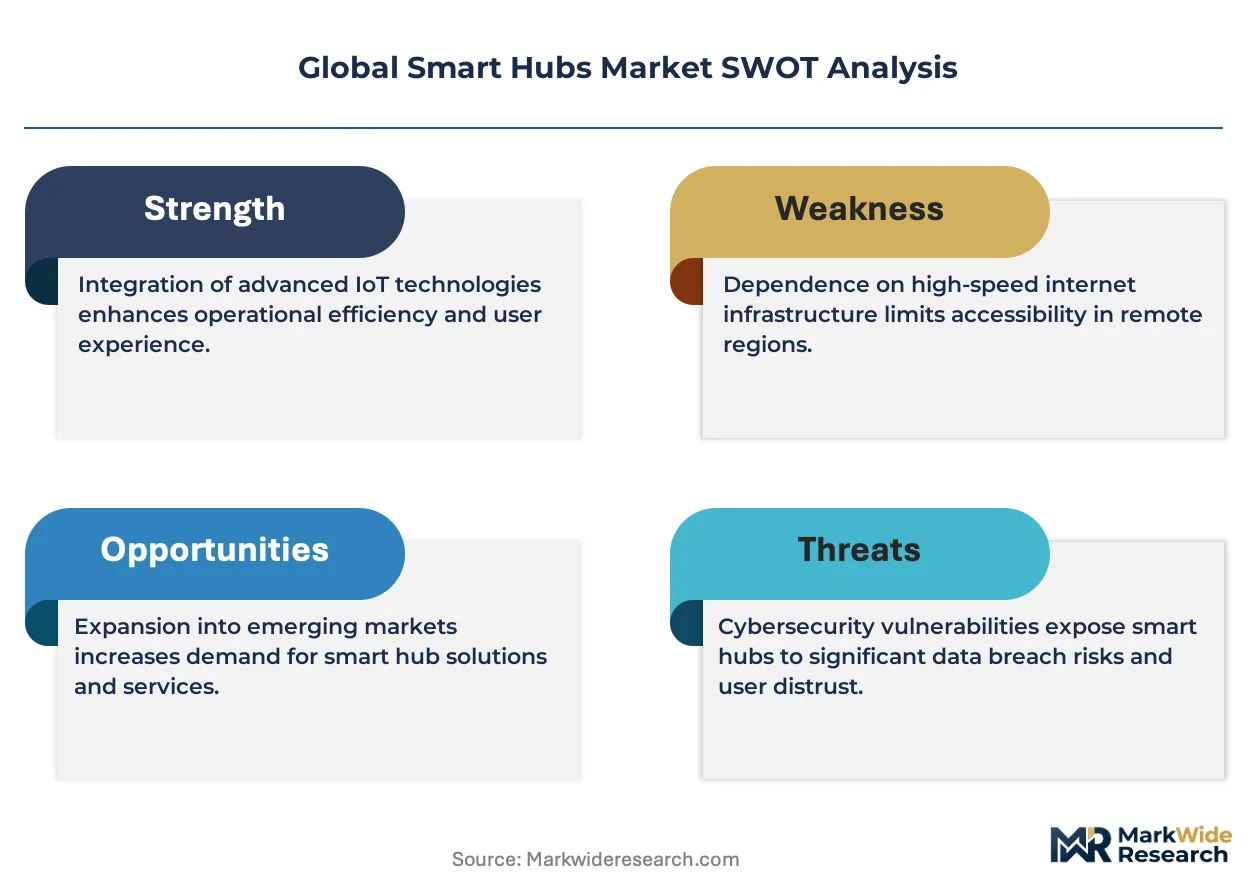
The EU Cyber Resilience Act and CE marking requirements under the EU Radio Equipment Directive are mandating baseline security architectures for connected devices entering European markets. The United States Federal Communications Commission governs spectrum allocation for hub wireless protocols while the National Institute of Standards and Technology publishes IoT cybersecurity frameworks shaping enterprise procurement standards. China's Ministry of Industry and Information Technology enforces GB standards for domestic smart home device interoperability. Stakeholders must monitor divergence between regional certification regimes when designing unified product platforms for cross-border deployment.
Market Dynamics
Utility providers in Germany, South Korea, and the United States are bundling smart hubs with demand-response energy programs, redirecting procurement away from retail channels toward direct B2B contracts with hardware manufacturers.
Growth Catalysts
- EU Cyber Resilience Act:Mandatory security-by-design requirements for IoT devices entering European markets are accelerating baseline encryption and secure boot architecture adoption across hub manufacturers.
- Thread protocol convergence:Unified wireless standards are reducing fragmentation in device interoperability, enabling single-hub deployment across previously incompatible sensor ecosystems.
- Residential construction pre-installation:North American property developers are specifying smart hubs as standard infrastructure in new multifamily units, creating captive demand channels independent of consumer electronics retail.
Market Restraints
- Semiconductor supply concentration:Taiwan-based foundries dominate Zigbee and Thread radio chip production, exposing hub manufacturers to single-source vulnerability for mesh networking components.
- CE marking compliance costs:EU Radio Equipment Directive testing and notified body certification adds substantial fixed cost per SKU, compressing margins for low-volume product variants.
- Smartphone substitution threat:Native Matter controller functionality in iOS and Android devices reduces standalone hub necessity for basic home automation use cases.
Strategic Opportunities
- India smart city integration:Municipal energy distribution companies in Mumbai, Delhi, and Bangalore are piloting hub-based grid balancing programs with residential load aggregation.
- FERC Order 2222 implementation:U.S. wholesale electricity market reforms enable distributed energy resource participation, creating utility procurement demand for hub-enabled home battery and EV coordination.
- AI-edge convergence:On-device neural processing unit integration with local large language models enables privacy-preserving voice control without cloud dependency.
Industry Challenges
- Firmware security engineering talent scarcity:Embedded systems security specialists capable of implementing secure boot chains and encrypted over-the-air update architectures command premium compensation in competitive labor markets.
- Multi-protocol certification complexity:Simultaneous Zigbee 3.0, Z-Wave Plus, and Matter 1.3 compliance testing extends product launch timelines by six to nine months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Smart Hubs Market |
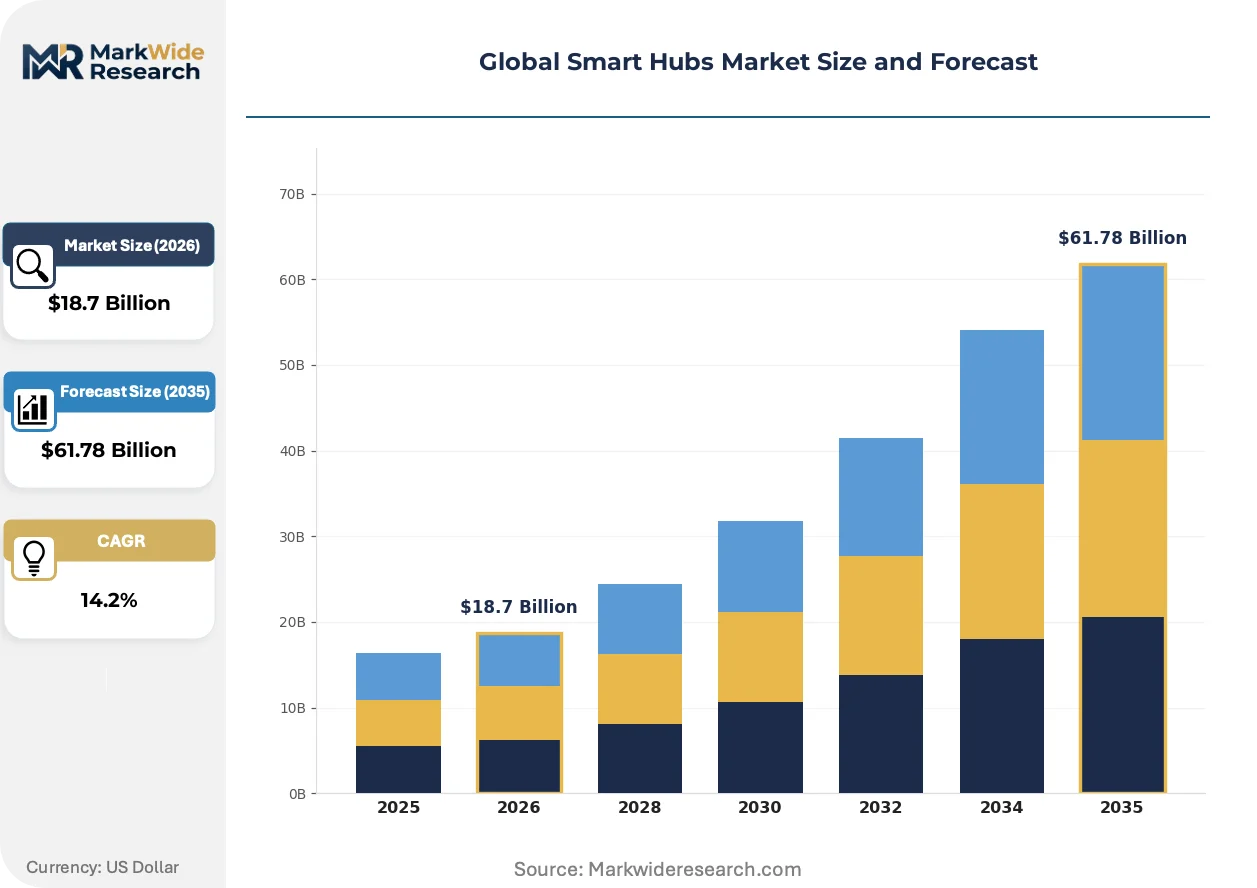
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Individual Hubs, Integrated Solutions, Cloud-based Platforms, Hardware Devices Installation: Standalone Systems, Networked Solutions, Modular Installations, Pre-configured Devices End User: Home Automation, Commercial Buildings, Industrial Automation, Transportation Networks Technology: IoT Connectivity, AI Integration, Data Analytics, Machine Learning |
| Companies Covered | Samsung Electronics, LG Electronics, Amazon.com Inc., Control4 Corporation, Logitech International, Google LLC, Xiaomi Corporation, Aeotec Group, Apple Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Smart Hubs Market Strategic Shifts
Edge computing architectures are displacing cloud-dependent automation routines, while regulatory pressure on data sovereignty accelerates local processing requirements across multiple jurisdictions.
Thread border router functionality is modularizing across smart home hardware categories. Appliance manufacturers in climate control and kitchen equipment are embedding hub capabilities directly into product mainboards. This distributed architecture is compressing the addressable market for standalone hub hardware while expanding total system deployment volume.
CE marking requirements under the EU Cyber Resilience Act are mandating vulnerability disclosure programs and automatic security update capabilities for all connected devices. Manufacturers serving European markets are restructuring firmware development workflows to accommodate ten-year support commitments. Premium product tiers are differentiating through faster patch cadence and extended support guarantees.
Buyer concentration among utility providers and property developers is fragmenting traditional retail distribution. Direct procurement contracts now specify custom firmware builds and white-label hardware configurations. Germany and South Korea exhibit the most advanced utility bundling programs, with energy retailers subsidizing hub hardware to secure demand-response enrollment.
Global Smart Hubs Market Segmentation
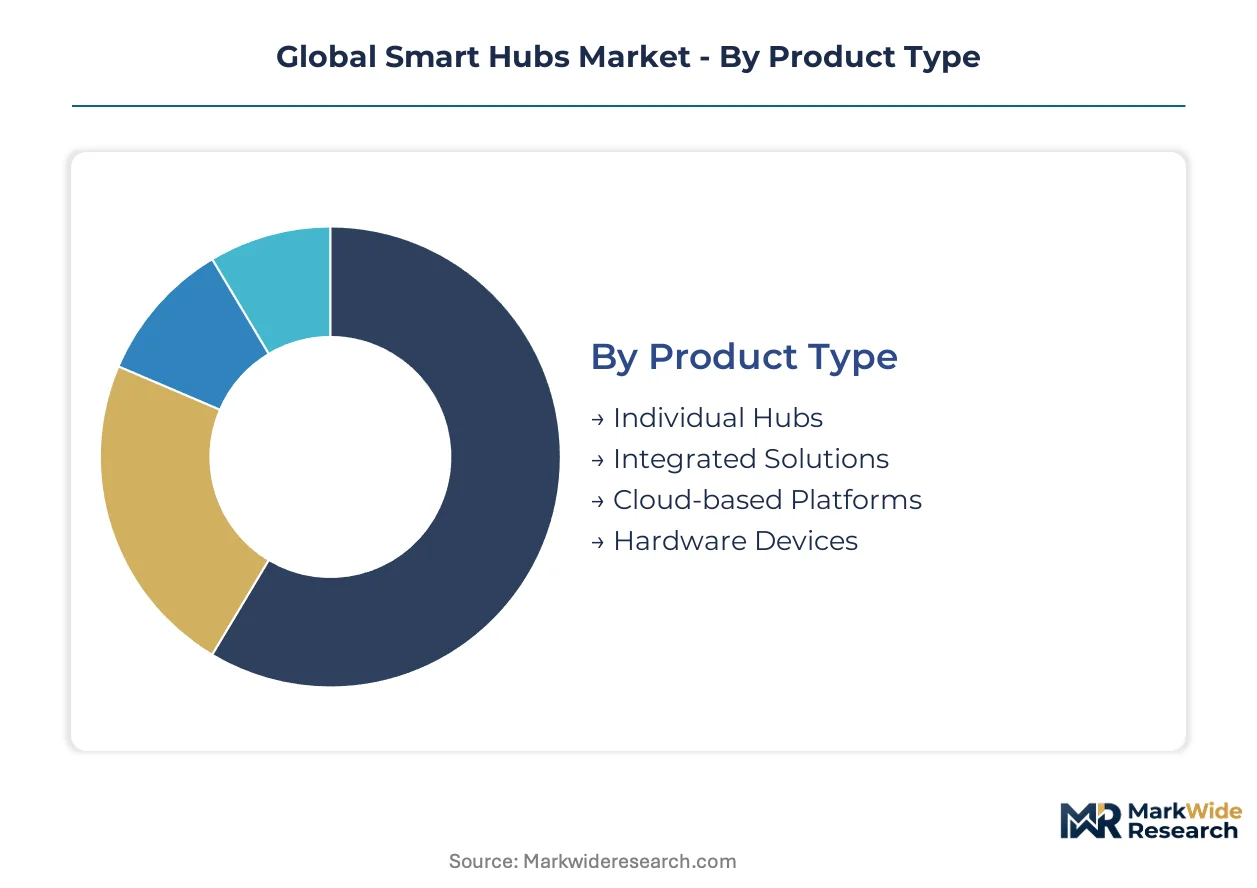
Smart hub procurement patterns diverge sharply across deployment contexts, with replacement cycles stretching from three years in consumer hardware to ten-plus years in embedded industrial systems. Segmentation reveals how technology architecture and installation methodology determine margin structure and customer lifetime value.
Product Type:
Upgrade cadence varies dramatically by product architecture, with hardware-centric offerings facing compressed replacement windows against platform-based alternatives that monetize through service continuity.
- Integrated Solutions:Bundled platform-and-service contracts embed hub functionality within appliance ecosystems and building management systems. German utility providers and South Korean energy retailers specify these configurations for demand-response programs, locking in recurring revenue streams through firmware-locked hardware.
- Cloud-based Platforms:Over-the-air update architectures decouple hardware refresh from feature expansion, extending effective replacement cycles indefinitely. North American property developers favor this model for multifamily pre-installation, minimizing on-site maintenance overhead through remote management capabilities.
- Individual Hubs:Standalone hardware units targeting retrofit installations in existing residential structures.
- Hardware Devices:Purpose-built controller units with fixed functionality and limited software extensibility.
Volume placements concentrate in Integrated Solutions; the faster expansion belongs to Cloud-based Platforms.
Installation:
Deployment methodology determines upfront capital requirements and ongoing operational flexibility, with cost-to-serve varying by an order of magnitude across the spectrum.
- Networked Solutions:Mesh-configured hub arrays coordinate across distributed sensor networks through Thread and Zigbee protocols. Municipal grid balancing pilots in Mumbai and Bangalore deploy these architectures for residential load aggregation, prioritizing interoperability over single-point control.
- Standalone Systems:Single-hub deployments operate independently without network dependency. U.S. suburban retrofit markets favor this simplicity where broadband reliability varies, though Matter controller functionality in smartphones is compressing addressable demand.
- Modular Installations:Scalable hub capacity through add-on radio modules and processing units.
- Pre-configured Devices:Factory-provisioned units with embedded security certificates and default automation routines.
Cost tier separation runs deepest between Networked Solutions and Standalone Systems, with the former commanding three-to-five-x hardware premiums justified by integration complexity.
End User:
Customer type dictates security certification requirements and support commitment duration, with industrial procurement mandating decade-long firmware maintenance against consumer expectations of obsolescence tolerance.
- Home Automation:Residential deployments span retrofit consumer purchases and developer-specified new construction infrastructure. EU Cyber Resilience Act ten-year support mandates are restructuring vendor economics, pushing premium pricing for extended-coverage tiers.
- Commercial Buildings:Enterprise facility management integrates hub functionality with HVAC and access control through BACnet and Modbus bridges. CE marking compliance costs under the EU Radio Equipment Directive add fixed overhead per SKU, favoring standardized configurations over customization.
- Industrial Automation:Manufacturing and logistics environments demand hardened hardware with deterministic latency guarantees.
- Transportation Networks:Hub coordination across vehicle fleets and charging infrastructure for EV load management.
Margin concentration sits with Commercial Buildings; the steepest volume climb tracks Home Automation as property developer channels displace retail.
Technology:
Capability stack differentiation determines competitive defensibility, with connectivity-layer commoditization forcing investment toward intelligence and automation layers.
- IoT Connectivity:Protocol aggregation across Zigbee, Z-Wave, Wi-Fi, Thread, and Matter enables single-hub device orchestration. Taiwan-based foundry concentration for mesh networking radio chips exposes manufacturers to single-source supply vulnerability.
- AI Integration:On-device neural processing enables predictive automation and anomaly detection without cloud dependency. Edge LLM deployment for privacy-preserving voice control represents the primary premium differentiation vector.
- Data Analytics:Aggregation and visualization of sensor-derived operational metrics for optimization workflows.
- Machine Learning:Pattern recognition for automated routine generation and energy consumption forecasting.
Technology maturity gaps separate IoT Connectivity from AI Integration, with the latter expanding most quickly as NPU cost curves enable local inference at consumer price points.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taiwan-based foundries supply the Zigbee and Thread radio chips that power mesh networking capabilities across smart hub architectures worldwide. Germany, South Korea, and the United States concentrate procurement demand through utility bundling programs. Municipal grid pilots in India and developer pre-installation mandates in North America reshape distribution geography.
United States
FERC Order 2222 implementation enables distributed energy resource participation in wholesale electricity markets, creating procurement demand for hub-enabled home battery coordination. The FCC governs spectrum allocation for hub wireless protocols while NIST publishes IoT cybersecurity frameworks shaping enterprise procurement standards. Property developers in Texas and Florida specify smart hubs as standard infrastructure in new multifamily units.
Germany
Energy retailers subsidize hub hardware to secure demand-response enrollment, redirecting procurement toward direct B2B contracts. The EU Cyber Resilience Act and CE marking requirements under the EU Radio Equipment Directive mandate baseline security architectures for connected devices entering European markets. Industrial clusters in Bavaria and North Rhine-Westphalia host utility providers bundling smart hubs with grid balancing services.
South Korea
Utility providers bundle smart hubs with demand-response energy programs, creating captive demand channels independent of consumer electronics retail. The country's national telecommunications regulator enforces device certification requirements for IoT security. Seoul Capital Area municipalities pilot hub-based residential load aggregation for municipal energy distribution optimization.
China
The Ministry of Industry and Information Technology enforces GB standards for domestic smart home device interoperability, shaping hardware design requirements. MIIT regulations on data localization accelerate edge computing architectures that reduce cloud dependency. Pearl River Delta manufacturing clusters produce Thread border router modules for appliance-embedded hub capabilities.
India
Municipal energy distribution companies in Mumbai, Delhi, and Bangalore pilot hub-based grid balancing programs with residential load aggregation. The Central Electricity Authority issues technical standards for smart grid device interoperability that influence procurement specifications. Karnataka's technology corridor hosts pilot deployments integrating smart hubs with renewable energy forecasting systems.
Global Smart Hubs Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue appliance-embedded hub capabilities and utility-direct contracting channels. The vendor base stratifies across three tiers: diversified electronics conglomerates with appliance ecosystem integration, cloud-platform operators leveraging voice assistant distribution, and specialized automation providers serving commercial installations. Competitive positioning depends on protocol aggregation breadth and firmware security certification depth. Primary competitive moves include strategic partnerships with energy utilities and backward integration into radio chip design.
Among diversified electronics conglomerates, Samsung Electronics and LG Electronics anchor the appliance-embedded tier, exemplifying ecosystem integration strategies that embed hub functionality within climate and kitchen product lines. Amazon.com Inc. occupies a position within the cloud-platform operator archetype, leveraging Alexa-enabled distribution to sustain channel control. Google LLC sits within the same tier, competing through Nest integration into energy utility partnerships. Xiaomi Corporation represents the scale-driven hardware specialist archetype, while Apple Inc. exemplifies premium-tier positioning through privacy-preserving architecture design.
| Leading Market Players |
|---|
| Samsung Electronics |
| LG Electronics |
| Amazon.com Inc. |
| Control4 Corporation |
| Logitech International |
| Google LLC |
| Xiaomi Corporation |
| Aeotec Group |
| Apple Inc. |
| Others |
Value Chain & Pricing Dynamics
Thread border router modularization across appliance mainboards is compressing standalone hardware margins while fragmenting procurement channels toward utility-direct contracts and developer-specified infrastructure. This production-method transition simultaneously erodes price premiums for discrete hub units and concentrates volume purchasing power among German energy retailers, South Korean municipal utilities, and North American multifamily developers.
Pricing Analysis
Warranty bundling and firmware support commitments now separate premium tiers from standard offerings, with EU Cyber Resilience Act ten-year update mandates forcing vendors to price extended coverage into upfront hardware costs. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth, with CE marking and FCC Part 15 compliance adding fixed overhead that compresses margins on low-volume SKUs. Pricing pressure stems from smartphone Matter controller substitution, which eliminates hub necessity for basic automation use cases. Property developers and utility providers exhibit lowest price sensitivity due to captive demand channels, while retrofit consumers in suburban markets face highest substitution elasticity.
Supply Chain Analysis
Mesh networking radio chip supply rests on Taiwan-based foundries for Zigbee and Thread silicon, with South Korean memory suppliers and Chinese PCB assembly clusters completing the hardware stack. Critical inputs include ARM Cortex-M processor cores, sub-GHz radio front-ends, and flash memory for firmware storage. Single-source vulnerability in Taiwan semiconductor fabrication exposes manufacturers to geopolitical disruption and foundry allocation constraints. Distribution runs through direct B2B contracts with energy utilities and property developers, bypassing traditional consumer electronics retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around firmware security certification depth and utility partnership scale, with EU Cyber Resilience Act compliance costs forcing sub-scale vendors toward exit or acquisition.
For Market Incumbents: Hedge against smartphone substitution by embedding hub functionality into appliance ecosystems and climate control hardware. Secure demand-response enrollment contracts with German and South Korean energy retailers to lock in recurring revenue streams. Invest in secure boot chain engineering talent to maintain CE marking certification velocity as compliance timelines extend. For New Entrants and Emerging Players: Capture white-space in India's municipal grid balancing pilots, where Mumbai and Bangalore distribution companies seek hub-enabled residential load aggregation. Target commercial building BACnet integration in North American enterprise facilities, where deterministic latency requirements favor specialized automation providers over consumer-focused platforms. Pursue white-label hardware configurations for utility-direct procurement channels. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified electronics conglomerates seeking appliance-embedded hub capabilities. Long-term viability favors vendors with demonstrated firmware security engineering depth and established utility partnership frameworks. Watch FERC Order 2222 implementation velocity as the signal indicating distributed energy resource market readiness.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Radio Chip Design | Captive supply of Thread and Zigbee silicon reduces Taiwan foundry dependency for Samsung and LG. |
| Utility Partnership Expansion | Direct B2B contracts with German energy retailers redirect procurement away from Amazon and Google retail channels. |
| Edge AI NPU Integration | On-device neural processing enables privacy-preserving voice control without cloud dependency for Apple and Google. |
| Firmware Security Certification Investment | CE marking and EU Cyber Resilience Act compliance creates barrier against sub-scale competitors. |
| Appliance-Embedded Hub Modularization | Climate and kitchen product lines absorb standalone hub functionality, compressing Aeotec and Control4 addressable market. |
Study Parameters
SEC filings, FCC equipment authorization databases, and EU notified body certification records formed the secondary backbone, supplemented by customs trade data for Zigbee and Thread radio chip import flows. Primary fieldwork encompassed interviews with smart home platform engineers, utility demand-response program managers, property development procurement leads, and embedded systems security specialists. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions across integrated solutions, cloud-based platforms, and standalone hardware categories.
Historical trendline analysis of smart home device penetration rates and utility bundling program rollouts informed the projection framework. Segmentation dimensions modeled include product architecture, installation methodology, end-user vertical, and technology capability stack, with particular attention to AI integration adoption curves and IoT connectivity protocol convergence. CAGRs derived from regression analysis of replacement cycle compression and pre-installation mandate expansion across North American residential construction.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to semiconductor supply concentration risks and Matter protocol adoption velocity. Forecasts reflect documented assumptions regarding regulatory implementation timelines and utility procurement budget allocations. A small set of named triggers warrants ongoing watch: Taiwan foundry allocation shifts, EU Cyber Resilience Act enforcement stringency, and FERC Order 2222 state-level implementation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart City Technology
Global Smart/Connected Street Lights Market
Smart City Technology
Smart Ticketing Solutions Market
Smart City Technology
Saudi Arabia Smart Cities Market
Smart City Technology
Global Smart Ticketing Market
Smart City Technology
Smart Parcel Delivery Locker Market
Smart City Technology
Smart Communities Market
Smart City Technology
Smart Parking Meters Market
Smart City Technology
Global Smart City Market
Smart City Technology
Smart City Framework Market
Smart City Technology
Smart City Kiosk Market
Smart City Technology
Global Smart City ICT Infrastructure Market
Smart City Technology
US Smart Cities Market
Smart City Technology
Smart City Platform Market
Smart City Technology
Singapore ICT Market
Smart City Technology
Smart City Kiosk Deployment Market
Smart City Technology
India Smart City Market