
 Next Generation Wireless Network Market | 2026-2036
Next Generation Wireless Network Market Size, Share, and Industry Trends Forecast 2026-2036
Next Generation Wireless Network Market Outlook
Millimeter-wave spectrum tiers is reorganizing capital allocation across the Next Generation Wireless Network Market. Qualcomm Technologies leverages its modem-RF system integration to sustain design wins in premium smartphone platforms. Cisco Systems anchors enterprise private 5G deployments with converged core architectures. Nokia Corporation differentiates through Open RAN interoperability commitments that compete against integrated stack vendors.
Next generation wireless networks encompass radio access infrastructure, core network functions, and terminal equipment operating above 6 GHz with sub-millisecond latency targets, designed to support massive machine-type communications and ultra-reliable low-latency industrial control. 5G technology captures the dominant share of carrier capex as spectrum auctions accelerate, while Wi-Fi 6E extends enterprise coverage into the 6 GHz band for high-density indoor environments. IoT Solutions applications are expanding fastest in manufacturing and logistics, where edge computing deployment models co-locate processing with sensors to reduce backhaul dependency.
The FCC governs spectrum allocation and equipment authorization in the United States, while the EU AI Act and GDPR impose data governance requirements on automated network management systems across Europe. China's MIIT sets domestic 5G base station density targets and equipment certification protocols through GB standards. Stakeholders must monitor spectrum harmonization timelines and open interface mandates that will determine vendor substitution economics.
Market Dynamics
Millimeter-wave spectrum auctions and Open RAN mandates are fragmenting vendor lock-ins while compressing deployment timelines for radio access networks across industrial corridors.
Growth Catalysts
- FCC Mid-Band Auctions:The FCC's accelerated C-band and 3.45 GHz releases in the United States are unlocking capacity for dense urban deployments and private enterprise networks.
- Industrial IoT Clusters:Manufacturing complexes in Shenzhen and Shanghai are driving base station density requirements through massive machine-type communications for automated quality control.
- EU AI Act Compliance:Automated network management systems across Europe face mandatory algorithmic transparency rules, creating replacement demand for explainable AI-driven traffic optimization tools.
Market Restraints
- GaN-on-SiC Substrate Costs:Gallium nitride power amplifiers for millimeter-wave radios depend on silicon carbide substrates concentrated among Japanese and US suppliers, creating input cost volatility.
- Integrated Stack Concentration:Three vendors control over seventy percent of macro baseband unit supply, limiting price competition for Open RAN disaggregation.
- Sub-6 GHz Interference:Coexistence protocols with legacy LTE networks impose spectral efficiency penalties that delay standalone 5G ROI realization.
Strategic Opportunities
- Private 5G in German Automotive:Volkswagen and BMW manufacturing campuses seek dedicated spectrum allocations under BNetzA local licensing frameworks for robotic welding coordination.
- AI-RAN Convergence:Machine learning inference at the distributed unit layer enables real-time beamforming optimization, merging silicon roadmaps from compute and telecom vendors.
- US IRA Manufacturing Credits:Domestic semiconductor fabrication incentives under the Inflation Reduction Act are reshoring mmWave frontend module production for defense and critical infrastructure supply assurance.
Industry Challenges
- Open RAN Integration Complexity:Multi-vendor radio unit and distributed unit interoperability testing extends deployment timelines by eight to fourteen months versus integrated stacks.
- RF Engineering Talent Scarcity:Phased array antenna design and beam management algorithm development face acute shortages across European and North American labor markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Next Generation Wireless Network Market |
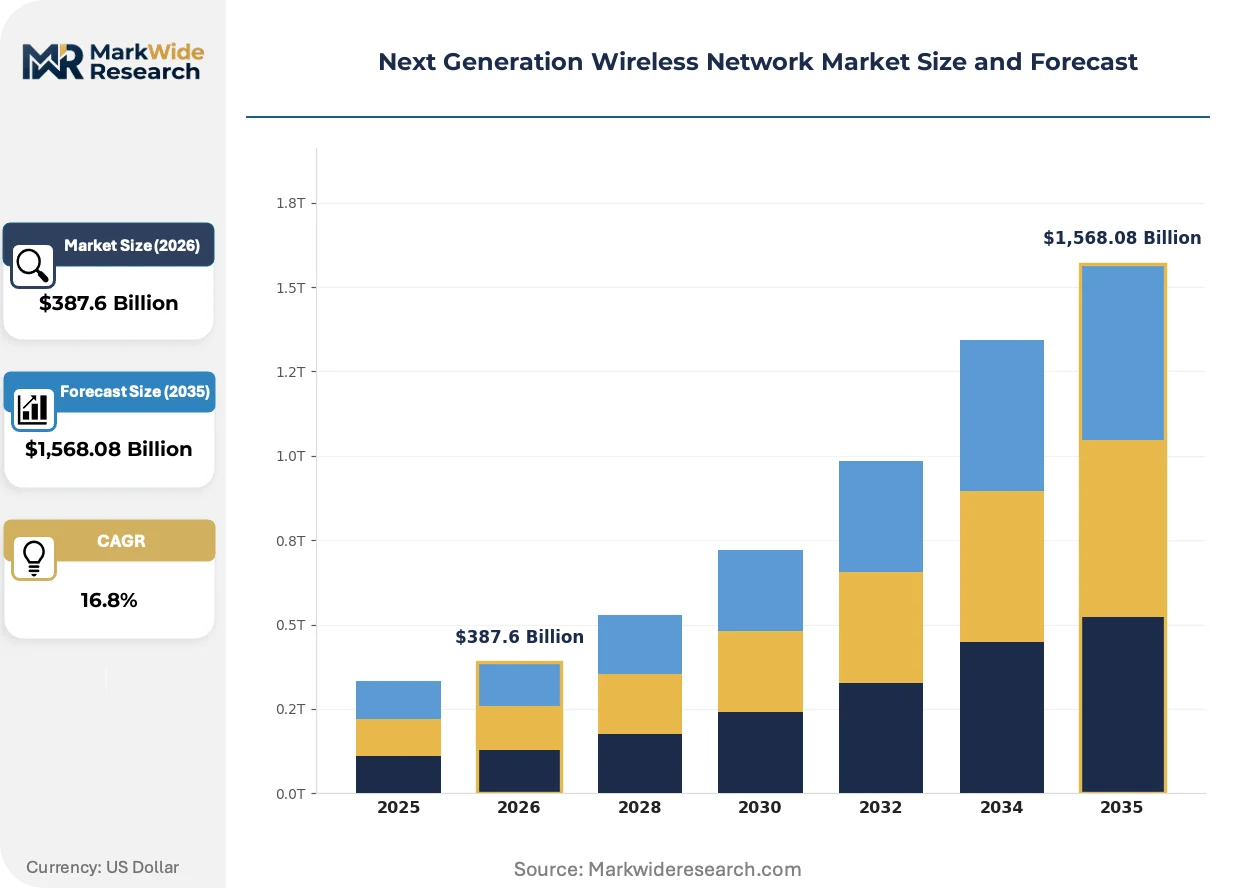
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $1,568.08 Billion |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: 5G, Wi-Fi 6E, Li-Fi, Ultra-Wideband Application: Smart Cities, IoT Solutions, Autonomous Vehicles, Virtual Reality End User: Telecom Operators, Enterprises, Government, Multi-National Corporations Deployment Model: Private Network, Public Network, Hybrid Network, Edge Computing |
| Companies Covered | Qualcomm Technologies, Inc., Cisco Systems, Inc., Nokia Corporation, Huawei Technologies Co., Ltd., AT&T Inc., Ericsson, Samsung Electronics, IBM Corporation, ZTE Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Next Generation Wireless Network Market Strategic Shifts
Software-defined architectures are decoupling hardware dependencies while edge computing co-location reshapes traffic engineering economics for latency-sensitive applications.
Cloud-native radio access networks are displacing purpose-built baseband appliances. Tier-one carriers in South Korea and Japan are migrating central unit functions to containerized deployments on hyperscaler infrastructure. This shift is compressing capital intensity per cell site while extending vendor substitution flexibility through Kubernetes-orchestrated workloads.
REACH restrictions on per- and polyfluoroalkyl substances are forcing substrate material transitions in high-frequency printed circuit boards. European equipment manufacturers face compliance deadlines that accelerate ceramic-filled hydrocarbon laminate adoption. Base station suppliers serving Germany and France are requalifying supply chains to eliminate fluorinated process chemicals from millimeter-wave antenna module production.
Enterprise buyers are consolidating procurement authority for private network deployments away from IT departments toward operational technology leadership. Manufacturing and logistics facilities in the Netherlands and Singapore now specify ultra-reliable low-latency performance guarantees in service-level agreements directly with system integrators. This bypasses traditional carrier resale channels and compresses margin capture for wholesale connectivity providers.
Next Generation Wireless Network Market Segmentation
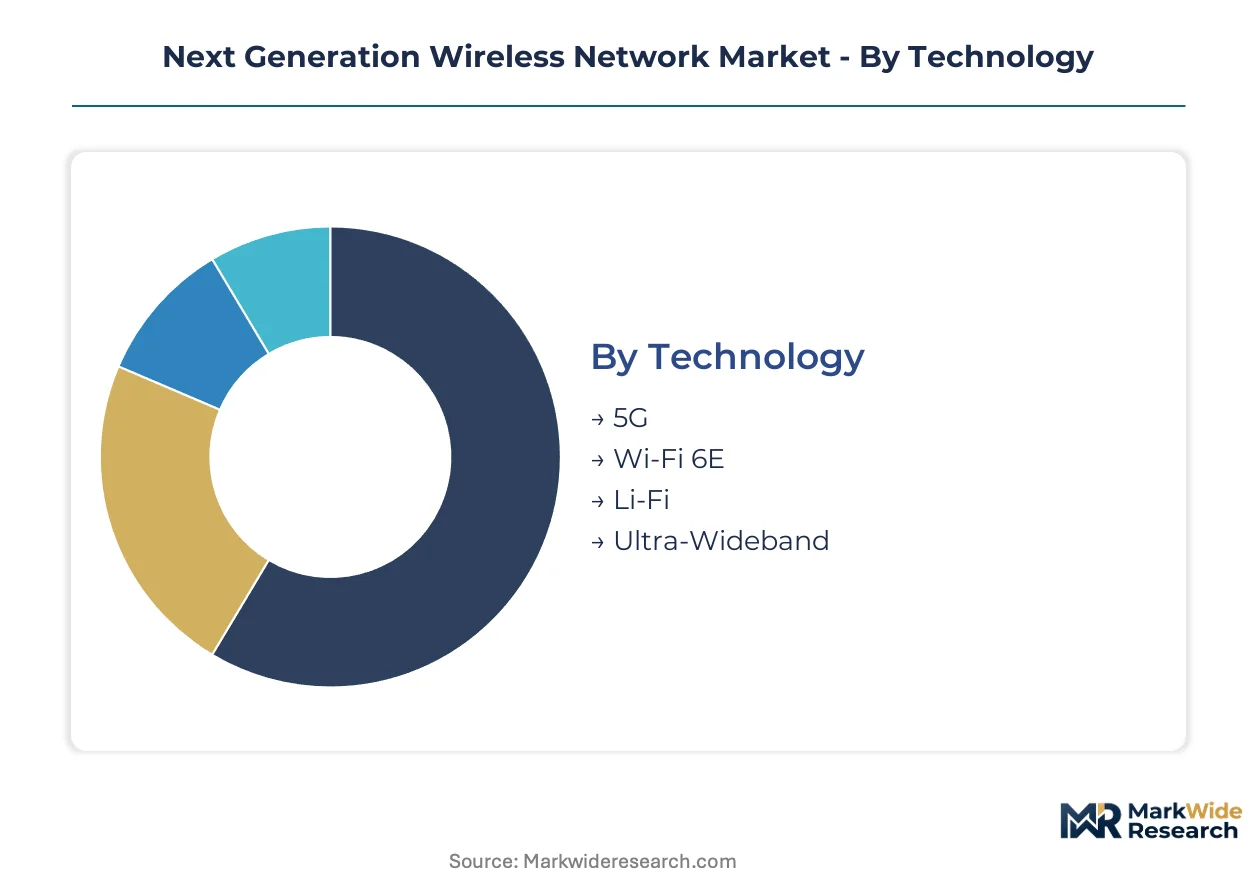
Next generation wireless networks fragment across technology generations, use-case intensity, and ownership models. Each segmentation axis carries distinct procurement patterns, margin structures, and regulatory exposure that reshape vendor go-to-market priorities.
Technology:
Equipment flows through carrier procurement channels for licensed spectrum gear, while enterprise IT distributors handle unlicensed indoor systems.
- 5G:Radio access infrastructure operating in sub-6 GHz and millimeter-wave bands delivers sub-millisecond latency for industrial control. South Korean carriers drive standalone deployment density through government-mandated coverage targets.
- Wi-Fi 6E:Extended spectrum access in the 6 GHz band supports high-density indoor environments with 160 MHz channel widths. Enterprise buyers in Germany and the United States prioritize this for manufacturing floor connectivity to bypass carrier dependency.
- Li-Fi:Visible light communication systems enable electromagnetic-sensitive deployments in healthcare and aviation.
- Ultra-Wideband:Short-range precise positioning technology anchors asset tracking in logistics warehouses and automotive manufacturing.
By volume, 5G leads. By growth pace, Wi-Fi 6E is climbing the fastest.
Application:
Cost tiers separate mission-critical industrial deployments from consumer-facing service layers.
- Smart Cities:Integrated sensor networks for traffic management, environmental monitoring, and public safety require municipal procurement cycles spanning 18-36 months. Barcelona and Singapore operate reference deployments with open data APIs.
- IoT Solutions:Massive machine-type communications for predictive maintenance and automated quality control dominate manufacturing corridors in Shenzhen. Edge computing co-location reduces backhaul costs for sensor-dense environments.
- Autonomous Vehicles:Vehicle-to-everything communication modules demand ultra-reliable low-latency links for collision avoidance.
- Virtual Reality:Immersive enterprise training and remote collaboration drive localized edge rendering requirements.
IoT Solutions commands the largest installed base. Smart Cities shows the steepest expansion trajectory.
End User:
Customer type determines contract structure, with carriers favoring multi-year framework agreements and enterprises seeking outcome-based performance guarantees.
- Telecom Operators:Licensed spectrum holders in Japan, South Korea, and the United States account for the dominant share of macro base station procurement. FCC auction timelines and MIIT coverage mandates shape capital release schedules.
- Enterprises:Manufacturing and logistics facilities in the Netherlands and Singapore now contract directly with system integrators for private network performance guarantees, bypassing wholesale carrier channels.
- Government:Defense and critical infrastructure agencies prioritize supply chain assurance and domestic fabrication.
- Multi-National Corporations:Cross-border standardization needs drive converged procurement across regional operating units.
Telecom Operators anchor volume. Enterprises are gaining share fastest.
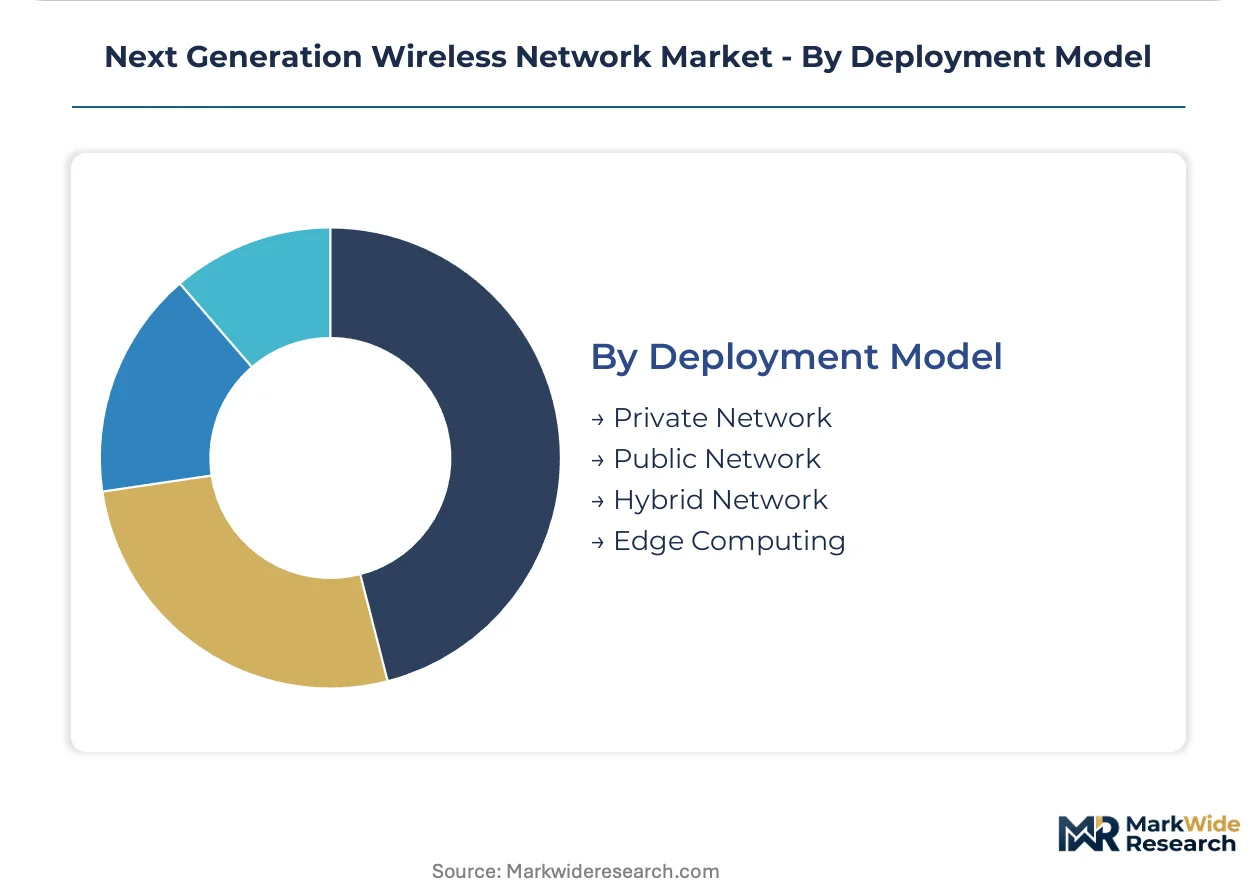
Deployment Model:
Supply concentration varies by orchestration complexity, with integrated stack vendors dominating public networks and multi-vendor interoperability characterizing private builds.
- Private Network:Dedicated spectrum allocations under BNetzA local licensing in Germany and FCC CBRS in the United States enable campus-wide robotic coordination. Volkswagen and BMW manufacturing sites represent reference architectures.
- Public Network:Carrier-operated macro coverage serves mass-market mobility and broadband substitution.
- Hybrid Network:Dual-mode operation combines licensed carrier capacity with local unlicensed offload for cost optimization.
- Edge Computing:Distributed unit containerization on hyperscaler infrastructure compresses capital intensity per cell site in South Korea and Japan.
Public Network retains volume leadership. Private Network exhibits the sharpest growth inflection.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise buyers in Germany exhibit the lowest price elasticity for private 5G deployments, while telecom operators in India face acute capital constraints that compress equipment margins. South Korea and China occupy intermediate positions where government mandates override pure cost optimization.
United States
Telecom operators are accelerating C-band and 3.45 GHz deployments for dense urban coverage and enterprise private networks. The FCC governs spectrum allocation and equipment authorization through auction timelines that shape capital release schedules. Industrial corridors in Texas and the Midwest are driving base station density for automated manufacturing and logistics coordination.
South Korea
Carriers are migrating central unit functions to containerized hyperscaler infrastructure under government-mandated coverage targets. The Ministry of Science and ICT sets domestic 5G standalone deployment timelines through spectrum licensing frameworks. The Seoul Capital Area anchors reference architectures for cloud-native radio access networks with sub-millisecond latency guarantees.
Germany
Automotive manufacturers are securing dedicated spectrum allocations under BNetzA local licensing frameworks for robotic welding coordination. The EU AI Act imposes algorithmic transparency requirements on automated network management systems across European operations. Manufacturing campuses in Bavaria and Baden-Württemberg represent the continent's densest private 5G infrastructure concentrations.
China
Industrial IoT corridors spanning Shenzhen and Shanghai are driving massive machine-type communications for predictive maintenance and automated quality control. The MIIT sets 5G base station density targets and equipment certification protocols through GB standards. The Yangtze River Delta and Pearl River Delta manufacturing clusters account for the dominant share of edge computing co-location deployments.
Japan
Telecom operators are compressing capital intensity per cell site through distributed unit containerization on hyperscaler infrastructure. METI coordinates spectrum harmonization timelines with industrial automation roadmaps. The Kanto and Kansai regions host the densest deployments of ultra-reliable low-latency networks for automotive and electronics manufacturing.
Next Generation Wireless Network Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the Next Generation Wireless Network Market. Integrated stack vendors dominate macro baseband unit supply with concentrated market positions, while Open RAN specialists fragment the radio unit layer through multi-vendor interoperability commitments. The competitive arena separates into three strategic archetypes: modem-RF system integrators, converged core architects, and Open RAN interoperability champions. Dominant competitive moves include strategic partnerships for cloud-native workload orchestration and vertical integration into gallium nitride power amplifier substrates.
Among North American technology developers, Qualcomm Technologies, Inc. and Cisco Systems, Inc. occupy positions within the integrated systems tier, while Nokia Corporation exemplifies the European vendor archetype competing through open interface commitments. These entities represent contrasting strategic postures on hardware-software decoupling and vendor substitution economics.
| Leading Market Players |
|---|
| Qualcomm Technologies, Inc. |
| Cisco Systems, Inc. |
| Nokia Corporation |
| Huawei Technologies Co., Ltd. |
| AT&T Inc. |
| Ericsson |
| Samsung Electronics |
| IBM Corporation |
| ZTE Corporation |
| Others |
Value Chain & Pricing Dynamics
Base station manufacturing scale economies in South Korea and Japan compress unit economics for millimeter-wave radio access networks while simultaneously concentrating supplier power among GaN-on-SiC substrate specialists. This scale concentration establishes price floors for integrated stack vendors and fragments margin capture for Open RAN disaggregators competing through multi-vendor interoperability.
Pricing Analysis
FCC spectrum auction timelines dictate the pricing tier structure for radio access equipment across carrier procurement cycles. Three-tier pricing structure across premium, standard, and economy levels separates standalone 5G macro deployments from non-standalone upgrades and legacy LTE extensions. Cost compression in the standard tier is intensifying because Open RAN radio unit vendors are undercutting integrated stack pricing by fifteen to twenty percent on comparable spectral efficiency. Telecom operators exhibit the lowest price sensitivity due to government-mandated coverage targets, while enterprise private network buyers negotiate outcome-based performance guarantees that shift risk to system integrators.
Supply Chain Analysis
Substrate chokepoints in Japanese and US silicon carbide wafer production constrain gallium nitride power amplifier output for millimeter-wave phased arrays. Equipment manufacturing draws from South Korean memory foundries, Taiwanese RF component specialists, and Chinese PCB laminate suppliers for high-frequency antenna modules. Single-source vulnerability concentrates in GaN-on-SiC epitaxy capacity controlled by two Japanese conglomerates. Distribution runs through carrier-direct procurement frameworks for licensed spectrum gear and IT distributors for enterprise Wi-Fi 6E deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Open RAN interoperability commitments are transforming this market into a platform-economics inflection where ecosystem orchestration displaces vertical integration as the primary value-capture mechanism. Multi-vendor radio unit certification programs now determine vendor substitution economics more than hardware performance specifications.
For Market Incumbents: Fortify modem-RF system integration advantages through captive supply of millimeter-wave frontend modules. Defensive consolidation should prioritize backward integration into gallium nitride substrate capacity to neutralize Japanese supplier concentration risk. Incumbents must also accelerate cloud-native central unit containerization to match South Korean carrier migration timelines and preempt hyperscaler infrastructure capture.
For New Entrants and Emerging Players: FCC CBRS certification fast-tracks offer the most penetrable entry pathway for private 5G radio unit specialists targeting US manufacturing campuses. White-space opportunities concentrate in automated network management software where EU AI Act compliance creates replacement demand for explainable AI-driven traffic optimization. New entrants should pursue direct system integrator partnerships rather than carrier resale channels to capture enterprise outcome-based contract margins.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among software-defined RAN orchestration platforms with Kubernetes-native deployment models. Long-term viability over the next decade favors acquisition targets with established Open RAN interoperability testing credentials and active participation in O-RAN Alliance specification development. The critical signal to watch is BNetzA local licensing uptake among German automotive manufacturers, which would validate private network monetization models beyond carrier wholesale channels.
| Strategic Initiative | Industry Significance |
|---|---|
| Open RAN Interoperability Certification | O-RAN Alliance compliance unlocks multi-vendor procurement for tier-one carriers in South Korea. |
| GaN-on-SiC Substrate Backward Integration | Captive wafer supply insulates millimeter-wave radio margins from Japanese supplier concentration. |
| Cloud-Native Central Unit Migration | Kubernetes containerization on hyperscaler infrastructure compresses capital intensity per cell site. |
| EU AI Act Compliance Software Development | Explainable AI traffic optimization replaces opaque legacy systems under algorithmic transparency mandates. |
| Private 5G System Integrator Partnership | Direct enterprise contracting bypasses carrier wholesale channels for manufacturing campus deployments. |
Study Parameters
Operator-level perspectives from radio access network planners, spectrum auction strategists, and enterprise private network procurement leads anchored the qualitative base. Primary interviews with Open RAN interoperability test engineers and GaN-on-SiC substrate procurement specialists were cross-validated against FCC auction records, MIIT base station deployment disclosures, and hyperscaler infrastructure capex filings. Secondary sources included O-RAN Alliance specification documents, BNetzA local licensing registers, and EU AI Act implementation guidance. Bottom-up equipment shipment analysis and top-down carrier capex aggregation were triangulated to establish market sizing.
Sensitivity analysis across spectrum auction timing scenarios, substrate cost volatility bands, and Open RAN adoption curves shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include technology generation, deployment model ownership structure, application latency intensity, and regional regulatory cluster. CAGRs were derived from installed base replacement cycles and greenfield deployment pipelines. Industry-specific forecast inputs encompassed MIIT-mandated coverage density targets and BNetzA local licensing application volumes.
Decision-makers should treat outputs as directional under assumptions of sustained FCC mid-band release schedules and stable GaN-on-SiC substrate supply; material deviation in either would warrant model refresh. Practitioners should keep alternative scenarios live as EU AI Act enforcement intensity and Open RAN interoperability testing timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Next Generation Technologies
GCC ICT Market
Next Generation Technologies
Hyperloop Technology Market
Next Generation Technologies
Fog Computing Market
Next Generation Technologies
Oman ICT Market
Next Generation Technologies
Japan ICT Market
Next Generation Technologies
Nearfield Communication (NFC) Market
Next Generation Technologies
5G New Radio Market
Next Generation Technologies
Jordan ICT Market
Next Generation Technologies
Global Next Generation Wireless Communication Market
Next Generation Technologies
Quantum Information Processing Market
Next Generation Technologies
M2M Connections Market
Next Generation Technologies
Bulgaria ICT Market
Next Generation Technologies
Nigeria ICT Market
Next Generation Technologies
Information and Communications Technology (ICT) Market
Next Generation Technologies
Hyperscale Edge Computing Market
Next Generation Technologies
Quantum Computing Market