
 5G New Radio Market | 2026-2036
5G New Radio Market Size, Share, and Industry Trends Forecast 2026-2036
5G New Radio Market Analytics
Aftermarket service revenue is fragmenting as carriers diversify beyond traditional network equipment procurement. Qualcomm Technologies sustains its position through R&D intensity in modem chipset architectures. Samsung Electronics anchors manufacturing scale across baseband and radio unit production. Nokia Corporation competes through geographic dominance in European carrier infrastructure swaps.
5G New Radio constitutes the air interface standard defining physical layer connectivity between user equipment and next-generation base stations, operating across sub-6 GHz and millimeter wave spectrum bands with OFDM-based waveforms and scalable numerology. Its primary purpose enables ultra-reliable low latency communication for industrial automation and enhanced mobile broadband for dense consumer environments. Sub-6 GHz deployments currently occupy the largest installed base due to propagation efficiency, while millimeter wave infrastructure represents the fastest-growing technology segment as carriers address capacity constraints in urban hotspots. Fixed wireless access applications command expanding margin pools as cable substitution accelerates in suburban markets.
The FCC governs spectrum allocation and equipment authorization in the United States, directly conditioning carrier rollout timelines and vendor market access. ETSI and 3GPP frameworks harmonize technical specifications across European and Asian regulatory domains, reducing fragmentation in equipment interoperability standards. Stakeholders must monitor spectrum reallocation proceedings and open RAN policy mandates as these decisions will determine vendor qualification pathways and capital deployment priorities.
Market Dynamics
Carrier capital allocation is pivoting from macro-cell densification toward indoor small-cell and private network deployments, compressing traditional equipment procurement cycles while fragmenting vendor relationships across multiple radio access technologies.
Growth Catalysts
- Sub-6 GHz spectrum refarming:Regulators in Germany, Japan, and Brazil are releasing mid-band frequencies previously allocated to satellite and defense applications, expanding contiguous channel availability for wide-area coverage.
- Industrial automation protocols:Manufacturing facilities in automotive and semiconductor verticals are specifying 5G NR as the wireless layer for time-sensitive networking, replacing wired Ethernet in motion-control applications.
- Smart city infrastructure mandates:Municipal procurement frameworks in Singapore, Barcelona, and Dubai are embedding 5G connectivity requirements into traffic management and public safety system tenders.
Market Restraints
- Millimeter wave propagation physics:Line-of-sight limitations and rain fade attenuation constrain deployment economics in tropical and subtropical climates, forcing carriers to overbuild site density.
- Radio frequency front-end concentration:Gallium nitride substrate supply for power amplifiers concentrates among a limited set of foundry operators in Taiwan and South Korea, creating single-source vulnerability.
- Open RAN interoperability certification delays:Multi-vendor integration testing timelines extend deployment schedules by six to eighteen months versus integrated single-supplier alternatives.
Strategic Opportunities
- Private network deployments in mining:Underground operations in Australia, Chile, and Canada are procuring dedicated 5G NR systems for autonomous haulage and remote drilling, bypassing public carrier infrastructure.
- Fixed wireless access for cable substitution:Suburban households in the United States and United Kingdom are adopting millimeter wave customer premises equipment as a primary broadband alternative, opening retail channel partnerships.
- Spectrum sharing frameworks:Citizens Broadband Radio Service and similar licensed-shared access regimes are enabling enterprise verticals to deploy localized networks without exclusive spectrum auctions.
Industry Challenges
- RF systems engineering talent scarcity:Design expertise in massive MIMO antenna arrays and beamforming algorithms concentrates among a narrow cohort of specialists with legacy cellular and radar backgrounds.
- Multi-generational network coexistence complexity:Operators must maintain LTE, 5G NSA, and 5G SA core interoperability while managing inter-system handoff latency and spectrum refarming coordination.
- Equipment authorization timeline variability:FCC, ETSI, and national type-approval processes for new radio units diverge in testing scope, creating regional launch delays for integrated product portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 5G New Radio Market |
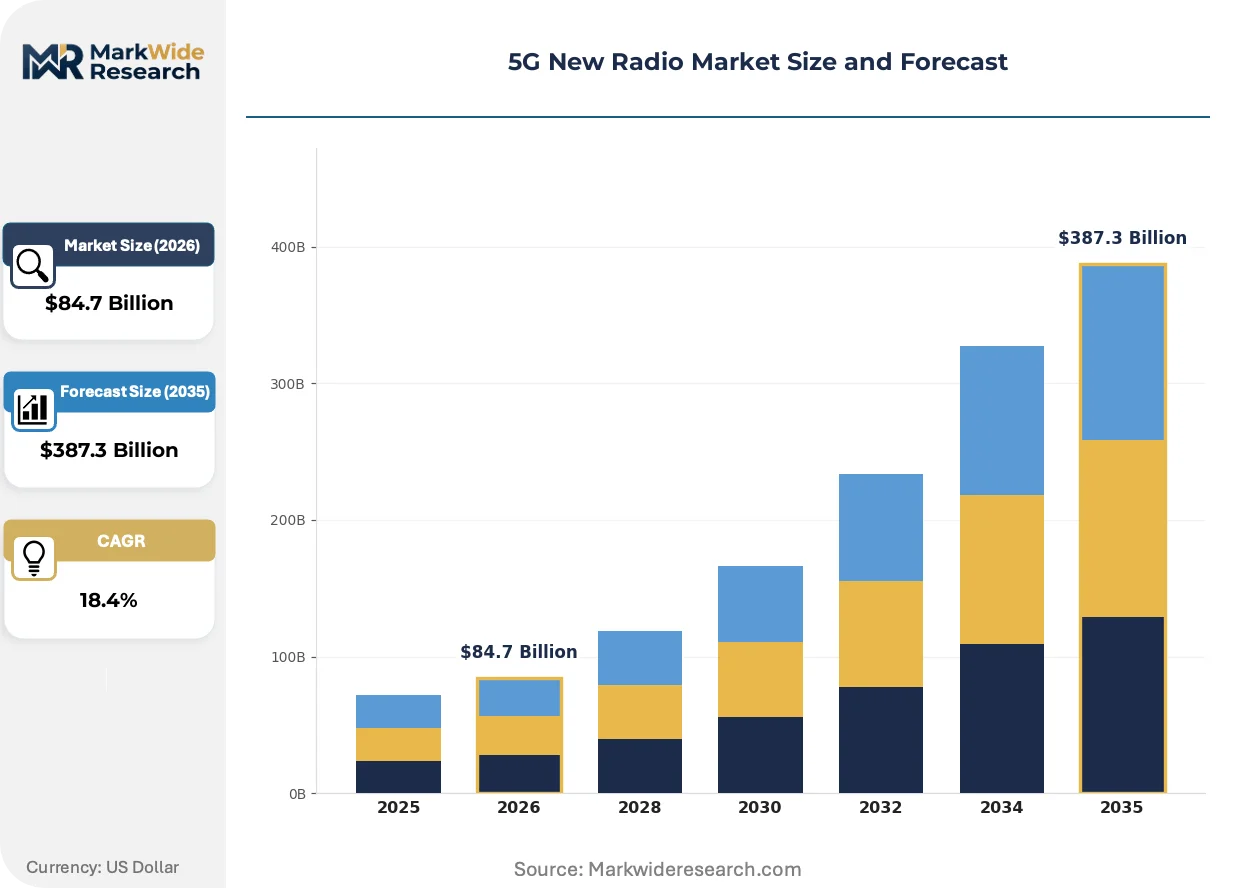
| Market Size in 2026 | $84.7 Billion |
| Market Size in 2035 | $387.3 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Enhanced Mobile Broadband, Massive Machine Type Communication, Ultra-Reliable Low Latency Communication, Fixed Wireless Access Technology: Millimeter Wave, Sub-6 GHz, MIMO, Beamforming End User: Telecommunications, Automotive, Healthcare, Smart Cities Deployment: On-Premises, Private Networks, Public Networks, Cloud-Based |
| Companies Covered | Ericsson AB, Qualcomm Technologies, Inc., Samsung Electronics Co., Ltd., Huawei Technologies Co., Ltd., Cisco Systems, Inc., Verizon Communications, Inc., Nokia Corporation, Fujitsu Limited, NEC Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
5G New Radio Market Evolving Landscape
Open radio access network architectures are fragmenting the traditional integrated base station supply model, enabling disaggregation between radio units, distributed units, and centralized units while introducing new interoperability certification requirements.
Massive MIMO antenna systems are hybridizing active antenna unit designs by integrating power amplifiers, transceivers, and radiating elements into single enclosures. Mobile network operators in South Korea and Japan are deploying 64T64R configurations at sub-6 GHz frequencies to maximize spectral efficiency in dense urban corridors. This convergence is compressing the addressable market for standalone remote radio head suppliers while elevating system-level integration capabilities.
The FCC's updated equipment authorization framework is tightening electromagnetic compatibility testing scope for millimeter wave devices operating above 24 GHz. Manufacturers must now demonstrate coexistence with existing fixed satellite service earth stations and radar altimeters, extending pre-market approval timelines. Aviation and maritime communication equipment categories face the most stringent documentation requirements under the revised rules.
Enterprise buyers are consolidating radio access network procurement decisions within centralized IT infrastructure teams rather than distributed operational technology departments. Manufacturing and logistics facilities in Germany and the United States are issuing single-vendor contracts spanning private core, edge compute, and radio infrastructure, displacing the traditional multi-supplier model. This concentration elevates systems integration capabilities above discrete component specifications in vendor selection criteria.
5G New Radio Market Segmentation
5G New Radio market segmentation reveals how deployment economics vary across spectrum bands, latency requirements, and infrastructure ownership models. Understanding these dimensions helps vendors calibrate R&D investment and pricing architecture against addressable margin pools.
Application:
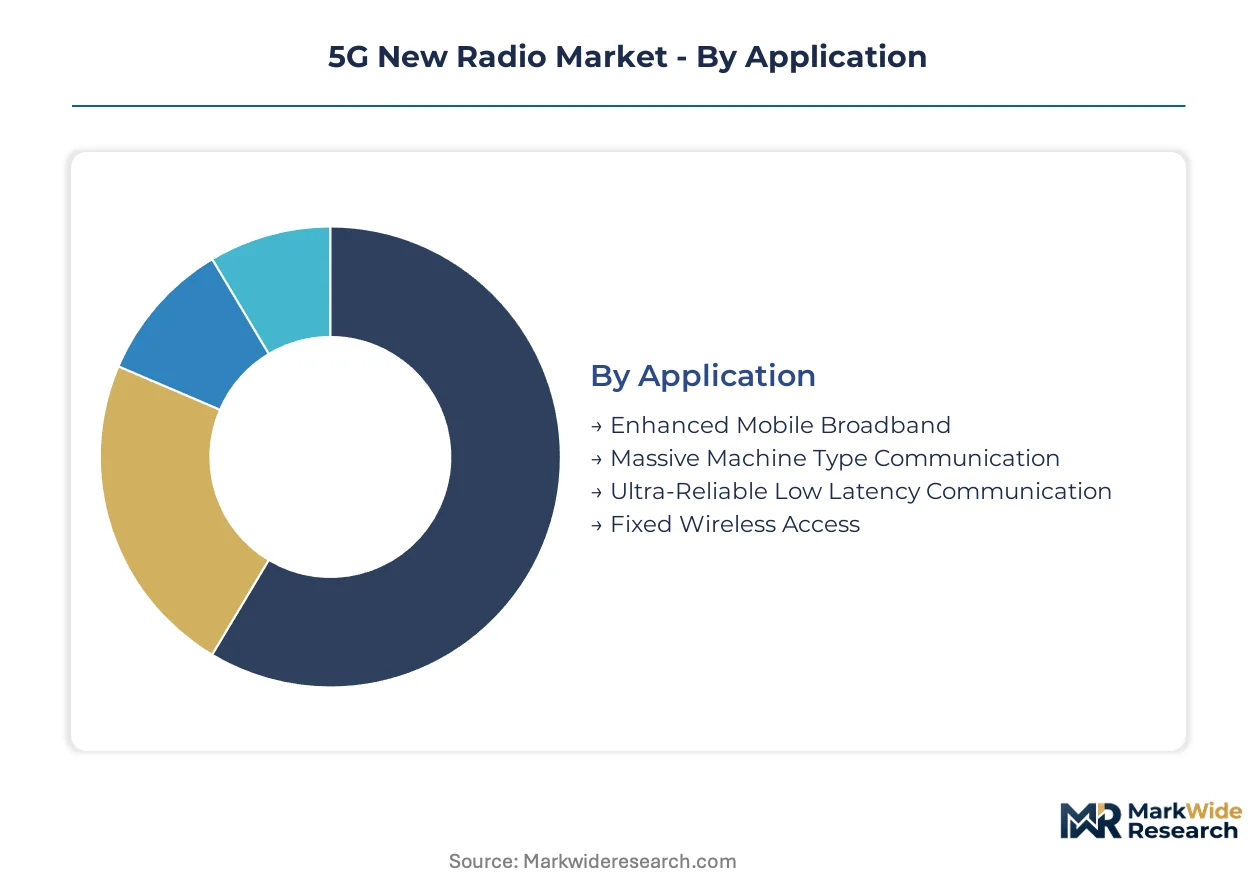
Application segmentation distinguishes use cases by throughput, latency, and connection density requirements, mapping directly to radio resource allocation strategies and core network slicing configurations.
- Enhanced Mobile Broadband:High-throughput consumer and enterprise connectivity leveraging wide-area sub-6 GHz coverage and millimeter wave capacity layers. Dense urban corridors in South Korea and Japan concentrate infrastructure investment as carriers compete on peak data rates for streaming and cloud gaming services.
- Ultra-Reliable Low Latency Communication:Time-critical industrial control and vehicular safety applications requiring sub-1 millisecond air interface latency. Automotive manufacturing facilities in Germany specify this protocol for motion-control networks, displacing wired Ethernet in robotic assembly lines.
- Massive Machine Type Communication:Low-power wide-area sensor networks for utility metering and agricultural monitoring. Narrowband IoT coexistence within 5G NR guard bands preserves spectrum efficiency.
- Fixed Wireless Access:Residential broadband substitution using millimeter wave customer premises equipment. Suburban markets in the United States show accelerating household adoption as cable alternative.
Enhanced Mobile Broadband holds installed capacity. Ultra-Reliable Low Latency Communication is rotating up the share rankings.
Technology:
Technology segmentation tracks the physical layer and antenna processing methods that determine spectral efficiency, coverage radius, and equipment cost structures.
- Sub-6 GHz:Mid-band and low-band frequencies enabling contiguous wide-area coverage with favorable propagation characteristics. Regulators in Germany, Japan, and Brazil are releasing previously restricted mid-band spectrum, expanding channel availability for carrier aggregation.
- Millimeter Wave:Frequencies above 24 GHz delivering multi-gigabit capacity in dense hotspots through extreme bandwidth allocation. Line-of-sight limitations and rain fade attenuation constrain deployment economics in tropical climates, forcing site density overbuild.
- MIMO:Multiple-input multiple-output spatial multiplexing multiplying spectral efficiency through independent data streams. 64T64R active antenna configurations dominate South Korean urban deployments.
- Beamforming:Dynamic antenna weighting concentrating radiated energy toward user equipment locations. Hybrid analog-digital architectures balance power consumption against beam steering precision.
Sub-6 GHz dominates volume shipments. Millimeter Wave is climbing the fastest on capacity-driven urban investments.
End User:
End user segmentation captures how procurement authority, technical specifications, and lifecycle requirements diverge across industry verticals.
- Telecommunications:Mobile network operators deploying macro-cell, small-cell, and indoor distributed antenna systems. Carrier capital allocation is pivoting from wide-area coverage toward indoor enterprise and private network opportunities.
- Automotive:Vehicle-to-everything communication modules and manufacturing facility wireless networks. OEMs specify 5G NR for autonomous driving sensor fusion and over-the-air update pipelines.
- Smart Cities:Municipal infrastructure integrating traffic management, public safety, and environmental monitoring. Singapore, Barcelona, and Dubai embed connectivity mandates into system procurement tenders.
- Healthcare:Remote surgery, patient monitoring, and hospital campus networks requiring deterministic latency guarantees. Medical device authorization timelines extend equipment qualification schedules.
Telecommunications retains procurement volume leadership. Smart Cities is gaining share fastest on infrastructure stimulus deployment.
Deployment:
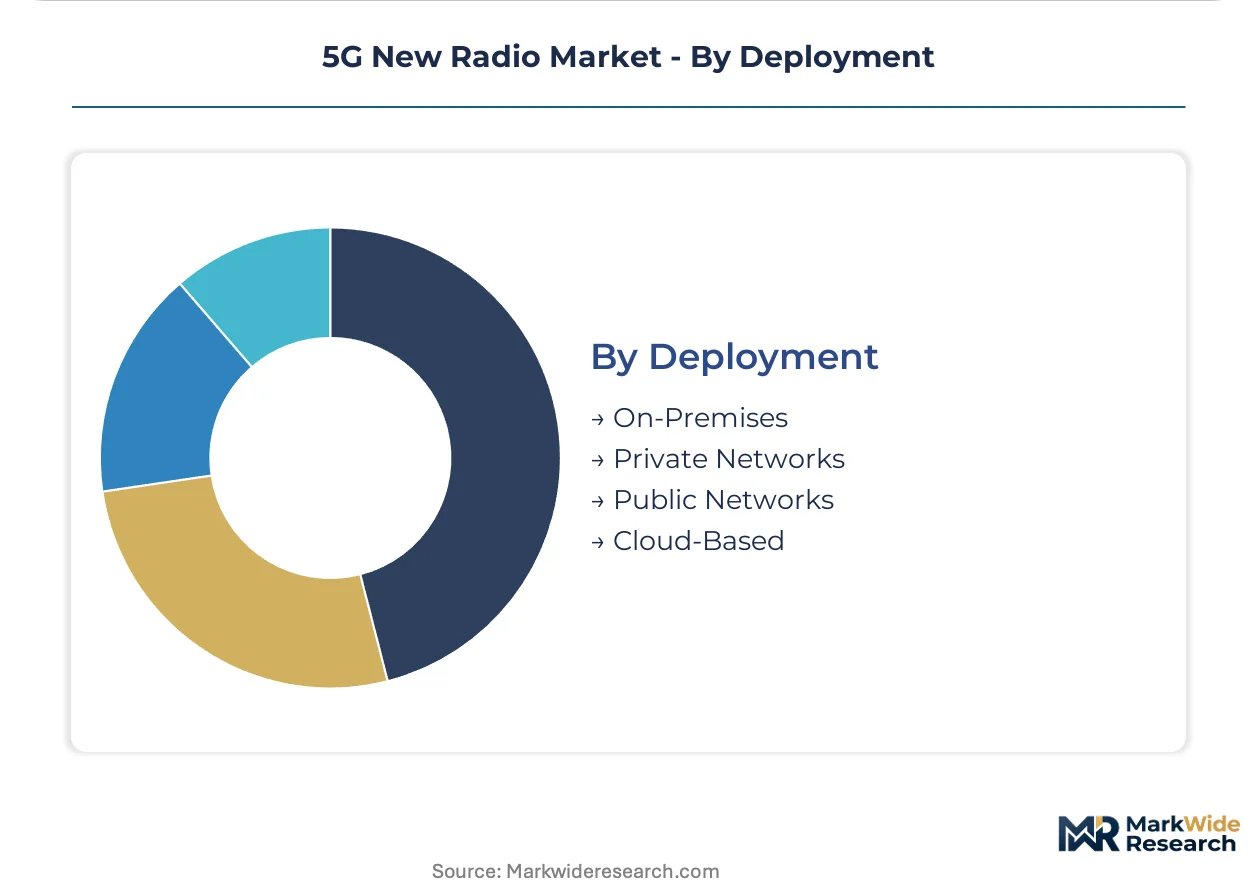
Deployment segmentation differentiates infrastructure ownership, operational responsibility, and integration depth with enterprise IT systems.
- Public Networks:Carrier-operated wide-area infrastructure serving consumer and enterprise subscribers through standardized service level agreements. FCC spectrum auctions and ETSI frameworks condition rollout timelines and vendor market access.
- Private Networks:Dedicated radio access and core infrastructure for single-enterprise use with localized spectrum licensing. Mining operations in Australia, Chile, and Canada procure standalone systems for autonomous haulage and remote drilling.
- On-Premises:Enterprise-owned edge compute and radio units integrated with factory automation or building management systems. IT infrastructure teams in Germany and the United States consolidate procurement decisions previously distributed across operational technology departments.
- Cloud-Based:Centralized baseband processing and network functions virtualization delivered through hyperscaler partnerships. Radio unit disaggregation enables multi-vendor interoperability under Open RAN architectures.
Public Networks anchor current installed base. Private Networks is expanding most quickly as verticals bypass carrier infrastructure for mission-critical applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across geographies. South Korean carriers absorb premium equipment costs for competitive positioning, while Brazilian operators negotiate aggressively on total cost of ownership. German industrial buyers prioritize deterministic latency over unit economics.
United States
Verizon and AT&T drive millimeter wave densification in urban corridors. The FCC's spectrum auction framework and equipment authorization rules condition vendor qualification timelines. Dallas-Fort Worth and Chicago anchor the largest metro deployments of 28 GHz and 39 GHz infrastructure.
South Korea
SK Telecom and KT Corporation maintain the densest sub-6 GHz and millimeter wave overlay globally. The Ministry of Science and ICT coordinates spectrum harmonization with manufacturing priorities. Seoul's Gangnam and Yeouido districts concentrate 64T64R massive MIMO installations.
Germany
Deutsche Telekom and Vodafone Germany prioritize industrial automation verticals over consumer mobile broadband. The Federal Network Agency (Bundesnetzagentur) governs spectrum licensing and open RAN interoperability mandates. Bavaria's automotive manufacturing belt around Munich and Ingolstadt deploys private 5G NR for robotic assembly networks.
Japan
NTT Docomo and KDDI balance Olympic legacy infrastructure with rural coverage obligations. The Ministry of Internal Affairs and Communications (MIC) manages 3.7 GHz and 4.5 GHz band allocations. Tokyo's Shibuya and Osaka's Umeda districts host the highest small-cell density in Asia-Pacific.
Brazil
Claro and Vivo navigate macroeconomic volatility while expanding coverage to underserved interior states. Anatel's 3.5 GHz auction terms shape carrier capital deployment schedules. São Paulo's financial district and Rio de Janeiro's port complex anchor initial enterprise private network trials.
5G New Radio Market Competitive Landscape
Integrated system vendors and modular component specialists split the market along architectural philosophy lines. The vendor base concentrates around three strategic archetypes: full-stack infrastructure providers, semiconductor platform licensors, and radio unit disaggregation enablers. Consolidation pressure intensifies as open RAN interoperability requirements fragment procurement decisions across multi-vendor ecosystems. Dominant competitive moves include spectrum-specific product portfolio diversification and geographic expansion through carrier framework agreements.
Within the full-stack infrastructure tier, Ericsson AB and Nokia Corporation represent contrasting geographic anchoring strategies, while Qualcomm Technologies, Inc. occupies a position as the dominant modem chipset architecture licensor. Samsung Electronics Co., Ltd. exemplifies vertical integration spanning baseband silicon through radio unit manufacturing. These three entities collectively illustrate how R&D intensity, manufacturing scale, and geographic footprint define competitive positioning in carrier infrastructure procurement cycles.
| Leading Market Players |
|---|
| Ericsson AB |
| Qualcomm Technologies, Inc. |
| Samsung Electronics Co., Ltd. |
| Huawei Technologies Co., Ltd. |
| Cisco Systems, Inc. |
| Verizon Communications, Inc. |
| Nokia Corporation |
| Fujitsu Limited |
| NEC Corporation |
| Others |
Value Network & Pricing Analysis
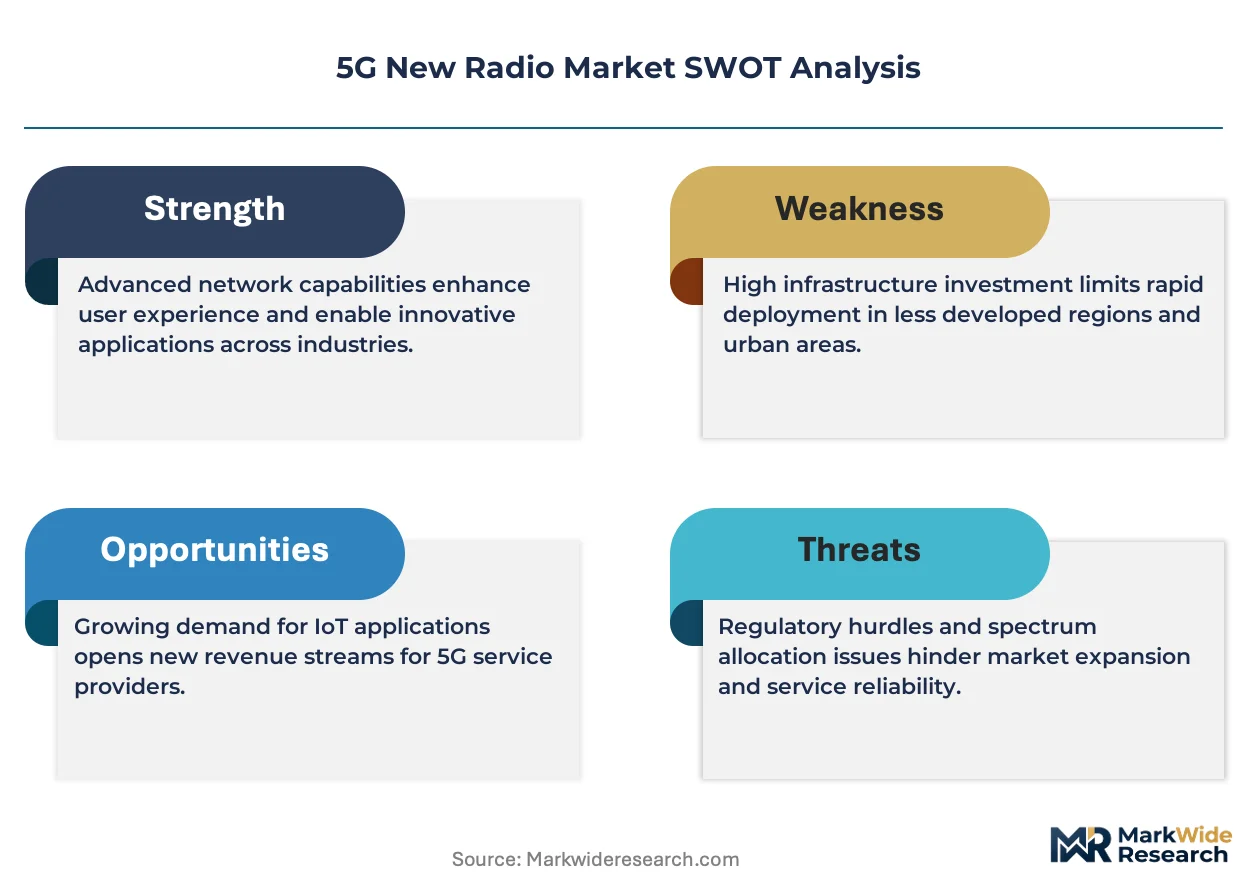
Gallium nitride substrate supply concentration among Taiwanese and South Korean foundry operators creates single-source vulnerability that compresses equipment pricing spreads while forcing buyers into long-term capacity reservation contracts.
Pricing Analysis
Aftermarket service revenue streams including network optimization contracts and extended warranty coverage drive lifetime value capture for infrastructure vendors. Three-tier pricing structure across premium, standard, and economy levels segments buyers by deployment scale and integration complexity. Cost compression in millimeter wave radio units is intensifying because carrier procurement teams consolidate volume across fewer framework agreements. Municipal smart city buyers exhibit highest price sensitivity due to budget cycle constraints, while South Korean carriers absorb premium equipment costs for competitive positioning.
Supply Chain Analysis
Foundry capacity at TSMC and Samsung Electronics anchors radio frequency front-end production for power amplifiers and transceivers. Taiwan and South Korea dominate semiconductor substrate processing, while China and Vietnam host final assembly for passive antenna components. The supply chain draws from gallium nitride wafers, ceramic filter substrates, and precision machined housings as critical inputs. Single-source vulnerability concentrates in GaN-on-SiC epitaxy services. Distribution runs through carrier framework agreements and direct enterprise procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Network lifecycle services including predictive maintenance analytics and software-defined radio updates are expanding faster than hardware shipments as carriers prioritize operational expenditure models over capital-intensive refresh cycles.
For Market Incumbents: Entrench position through captive supply of gallium nitride substrates and backward integration into antenna calibration services. Open RAN interoperability mandates from ETSI and national regulators threaten integrated vendor margins by fragmenting procurement across multi-supplier ecosystems. Incumbents should anchor carrier relationships through exclusive spectrum-band product roadmaps and localized technical support centers in Germany and South Korea.
For New Entrants and Emerging Players: Build out private network deployment capabilities targeting mining operations in Australia, Chile, and Canada where autonomous haulage systems bypass public carrier infrastructure. The most penetrable segment sits in underground radio access networks requiring explosion-proof certification and deterministic latency guarantees. A direct enterprise sales model with systems integration partnerships offers the cleanest go-to-market angle against incumbent carrier channels.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors semiconductor platform licensors with modem chipset architecture dominance. Long-term viability hinges on R&D intensity in massive MIMO beamforming algorithms and millimeter wave RF front-end integration. Acquisition targets should display vertical integration from baseband silicon through radio unit manufacturing. The signal to watch is FCC equipment authorization timeline compression for open RAN multi-vendor configurations.
| Strategic Initiative | Industry Significance |
|---|---|
| Open RAN Interoperability Certification | ETSI and O-RAN Alliance testing protocols enable multi-vendor deployments while fragmenting procurement decisions. |
| Millimeter Wave Capacity Expansion | Verizon and AT&T densification in Dallas-Fort Worth and Chicago drives 28 GHz and 39 GHz infrastructure demand. |
| Private Network Vertical Integration | Deutsche Telekom and Vodafone Germany consolidate core, edge compute, and radio infrastructure for Bavarian automotive manufacturers. |
| Spectrum Sharing Framework Deployment | FCC Citizens Broadband Radio Service enables enterprise localized networks without exclusive spectrum auctions. |
| RF Systems Engineering Talent Acquisition | Massive MIMO antenna array expertise concentrates among legacy cellular and radar specialists in South Korea and Japan. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with carrier network planning executives, radio unit procurement managers, semiconductor foundry operations leads, and private network deployment specialists at mining and manufacturing facilities. Secondary validation drew from FCC equipment authorization databases, ETSI technical specification releases, 3GPP standardization documents, and carrier capital expenditure disclosures. Bottom-up triangulation across deployment volume estimates and top-down reconciliation against spectrum auction proceeds anchored market sizing.
Calibration across historical deployment trajectories in South Korea, Japan, and the United States informed projection parameters throughout the forecast period. Segmentation dimensions modeled include spectrum band, deployment architecture, end-use vertical, and geographic regulatory cluster. CAGRs were derived from slope analysis of installed base expansion curves and carrier procurement cycle timing. Industry-specific forecast inputs encompassed millimeter wave site density economics and private network spectrum licensing velocity.
The forecast holds incumbent behavior within observed patterns; aggressive moves by hyperscaler-led open RAN consortia or Chinese equipment vendors facing expanded FCC exclusion would shift outcomes materially. Regulatory reallocation proceedings, gallium nitride substrate supply disruptions, and open RAN interoperability certification delays represent specific revision risks. Quarterly review of carrier capital expenditure guidance and equipment authorization pipeline velocity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Next Generation Technologies
Hyperscale Edge Computing Market
Next Generation Technologies
Enterprise Quantum Computing Market
Next Generation Technologies
Next Generation Network (NGN) Equipment Market
Next Generation Technologies
Poc Platform and Technology Market
Next Generation Technologies
Nigeria ICT Market
Next Generation Technologies
Nearfield Communication (NFC) Market
Next Generation Technologies
Next Generation Wireless Network Market
Next Generation Technologies
Japan ICT Market
Next Generation Technologies
Quantum Computing Market
Next Generation Technologies
Next-Generation Communication Devices Market
Next Generation Technologies
Fog Computing Market
Next Generation Technologies
Malaysia ICT Market
Next Generation Technologies
Information and Communications Technology (ICT) Market
Next Generation Technologies
M2M Connections Market
Next Generation Technologies
Smart Surfaces Market
Next Generation Technologies
Bulgaria ICT Market