
 Smart Home Market | 2026-2036
Smart Home Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Home Market Intelligence
The EU Green Deal's mandate for increased energy efficiency in buildings is recalibrating product development priorities for smart home device manufacturers. This shift favors companies with strong positions in building automation and energy control. Siemens leverages its extensive portfolio in building management systems to offer integrated solutions. Honeywell International sustains its market leadership through its specialization in smart thermostats and climate control. Meanwhile, Johnson Controls International competes by offering combined HVAC, security, and automation platforms for residential applications.
A smart home is a residential setup where internet-connected devices enable the remote monitoring and management of appliances and systems. These systems rely on communication protocols like Zigbee, Z-Wave, and Thread to create an interoperable network for automation. The primary purpose is to enhance convenience, comfort, energy efficiency, and security for occupants. The safety and security application segment, encompassing smart locks and security cameras, currently holds a dominant market position. Concurrently, energy management applications, driven by smart thermostats and monitors, are poised for significant expansion.
Regulatory frameworks directly influence device design and market access. The US EPA's ENERGY STAR program sets standards for energy consumption, while the EU's GDPR imposes strict data privacy and security requirements on all connected devices. In China, the MIIT governs IoT device standards and network connectivity protocols. Navigating the fragmentation of communication standards while adhering to disparate regional data privacy laws remains the central challenge for device manufacturers seeking to achieve mass-market adoption.
Market Dynamics
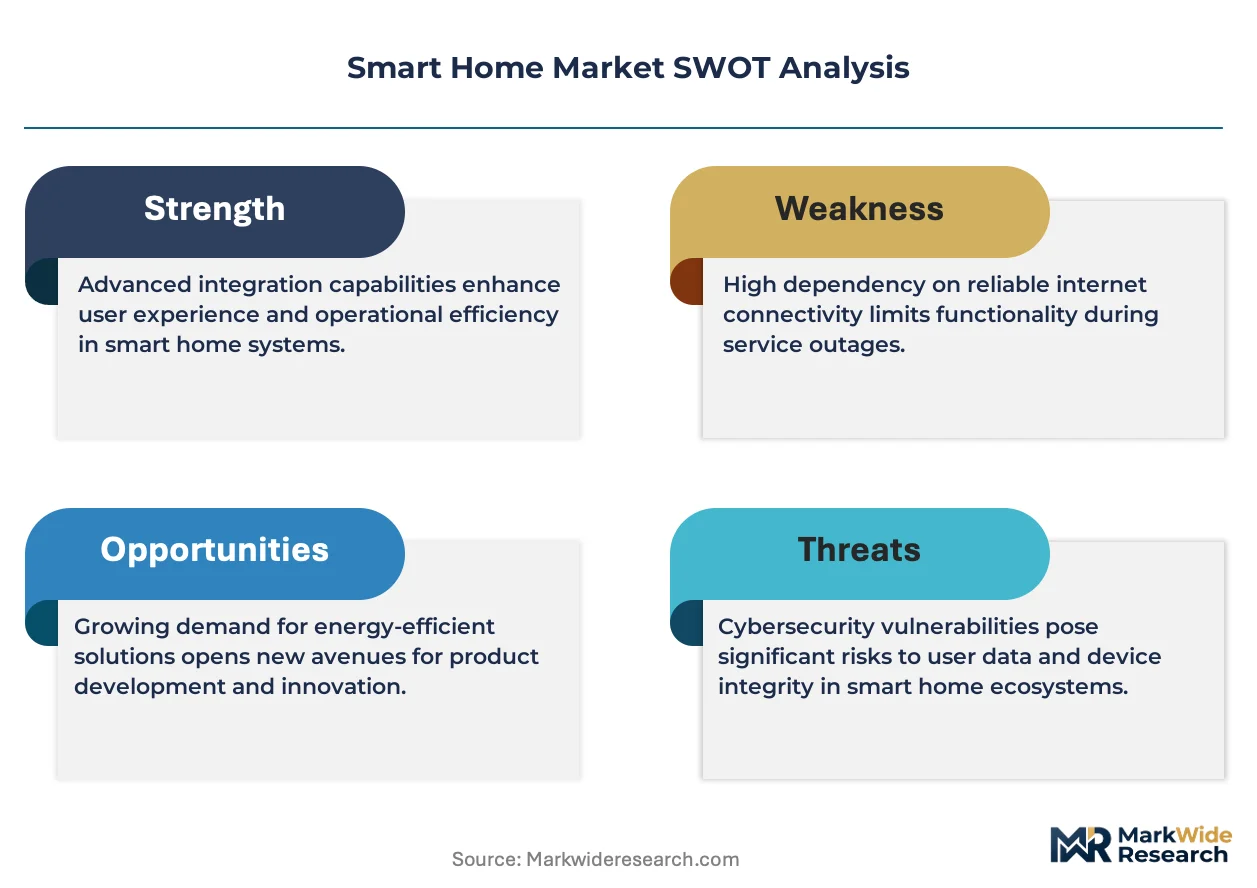
The central structural force shaping the smart home market is the tension between platform interoperability and data governance. A global regulatory push for energy efficiency and data privacy is forcing manufacturers to build more open and secure systems, directly challenging the historically fragmented and proprietary nature of device ecosystems.
Growth Catalysts
- Energy Efficiency Mandates:The EU Green Deal and similar building codes in US states incentivize the adoption of smart thermostats and energy management systems to reduce residential power consumption and meet sustainability targets.
- New Construction Integration:A surge in smart technology integration within new residential construction projects, particularly in affluent urban centers in the United States and coastal China, establishes a foundational user base.
- Protocol Standardization:The maturation of interoperability protocols like Thread and Matter simplifies device setup and communication, lowering the technical barrier for consumers and encouraging broader ecosystem development.
Market Restraints
- High Initial Investment:The significant upfront cost for whole-home automation systems, including professional installation, restricts market penetration to affluent households and new-build projects, limiting mass-market adoption.
- Protocol Fragmentation:Despite standardization efforts, the persistence of legacy protocols like Z-Wave and Zigbee alongside newer standards creates consumer confusion and potential interoperability dead-ends for purchased devices.
- Data Privacy Concerns:Consumer apprehension regarding the collection and use of personal data by connected devices, amplified by regulations like GDPR, creates a significant barrier to trust and adoption for monitoring-centric applications.
Strategic Opportunities
- Assisted Living Solutions:Developing integrated systems for elder care that combine ambient monitoring, automated safety alerts, and voice-activated assistance presents a major opportunity in countries with aging populations, such as Japan and Germany.
- Insurance-Linked Services:Partnering with home insurance providers to offer discounts for homes equipped with certified smart security, fire, and water leak detection systems creates a new B2B2C sales channel.
- Retrofit Market in Europe:Targeting the extensive existing housing stock in Europe with easy-to-install, modular energy management solutions addresses regulatory pressure on homeowners to improve building energy performance ratings.
Industry Challenges
- Cybersecurity Vulnerabilities:The proliferation of connected endpoints creates a vast attack surface, requiring constant vigilance and software updates to protect against breaches that could compromise user safety and privacy.
- Integration with Legacy Infrastructure:Ensuring seamless functionality between new smart devices and existing, non-connected home infrastructure, such as older HVAC systems or electrical wiring, remains a complex and costly technical hurdle for installers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Home Market |
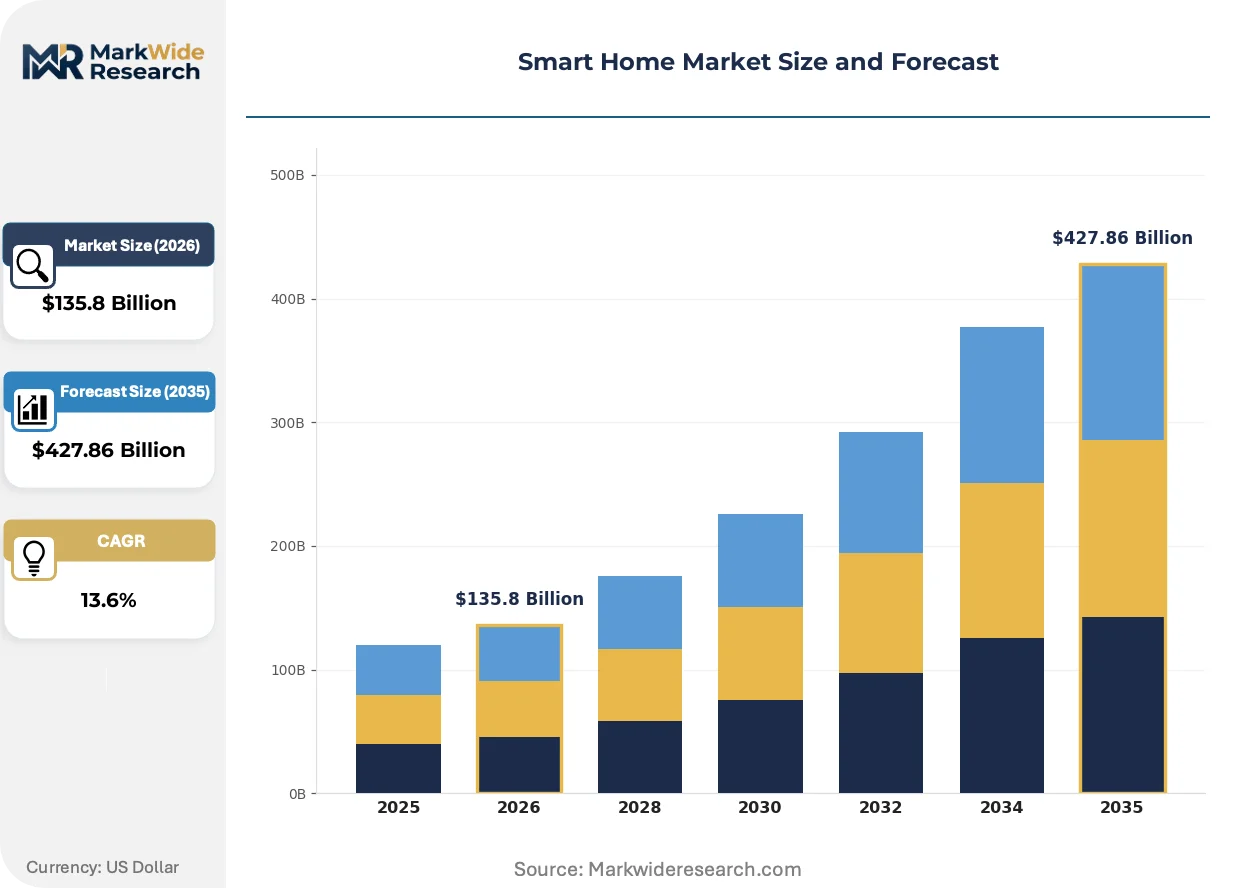
| Market Size in 2026 | $135.8 Billion |
| Market Size in 2035 | $427.86 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Thermostats, Security Cameras, Voice Assistants, Smart Lighting, Smart Locks, Energy Monitors Technology: Wi-Fi, Zigbee, Z-Wave, Bluetooth LE, Thread, Infrared Application: Home Automation, Energy Management, Safety & Security, Voice Control, Entertainment, Elderly Care End User: Homeowners, Property Managers, Tenants, Smart Building Operators |
| Companies Covered | Siemens, Samsung, Honeywell International, Apple, LG Electronics, ABB, Alphabet, Amazon, Johnson Controls International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Home Market Strategic Shifts & Innovations
The market's evolution is defined by the transition from discrete, single-function devices to interconnected ecosystems. This integration is driven by advancements in on-device AI and a regulatory push for holistic home management, particularly concerning energy consumption and data security.
Matter, the connectivity standard, provides a unified application layer for diverse smart home devices from different manufacturers. Major technology firms and device makers are rapidly adopting the standard to ensure future compatibility. Matter is expanding into the domain of proprietary ecosystems, breaking down walled gardens and simplifying the consumer experience by ensuring devices work together seamlessly.
Europe's Cyber Resilience Act (CRA) imposes stringent cybersecurity requirements on manufacturers of all products with digital elements. This forces companies to embed security throughout the product lifecycle, from design to end-of-life support. The regulation most heavily affects hardware vendors targeting the EU market, who must now provide security patches and transparently disclose vulnerabilities.
Homeowner preference is shifting toward professionally installed, whole-home systems rather than a piecemeal collection of DIY gadgets. This trend disrupts the retail model focused on individual device sales, favoring system integrators and custom installers. This behavioral shift is most pronounced in the North American and Chinese luxury housing markets during new construction and major renovations.
Smart Home Market Segmentation
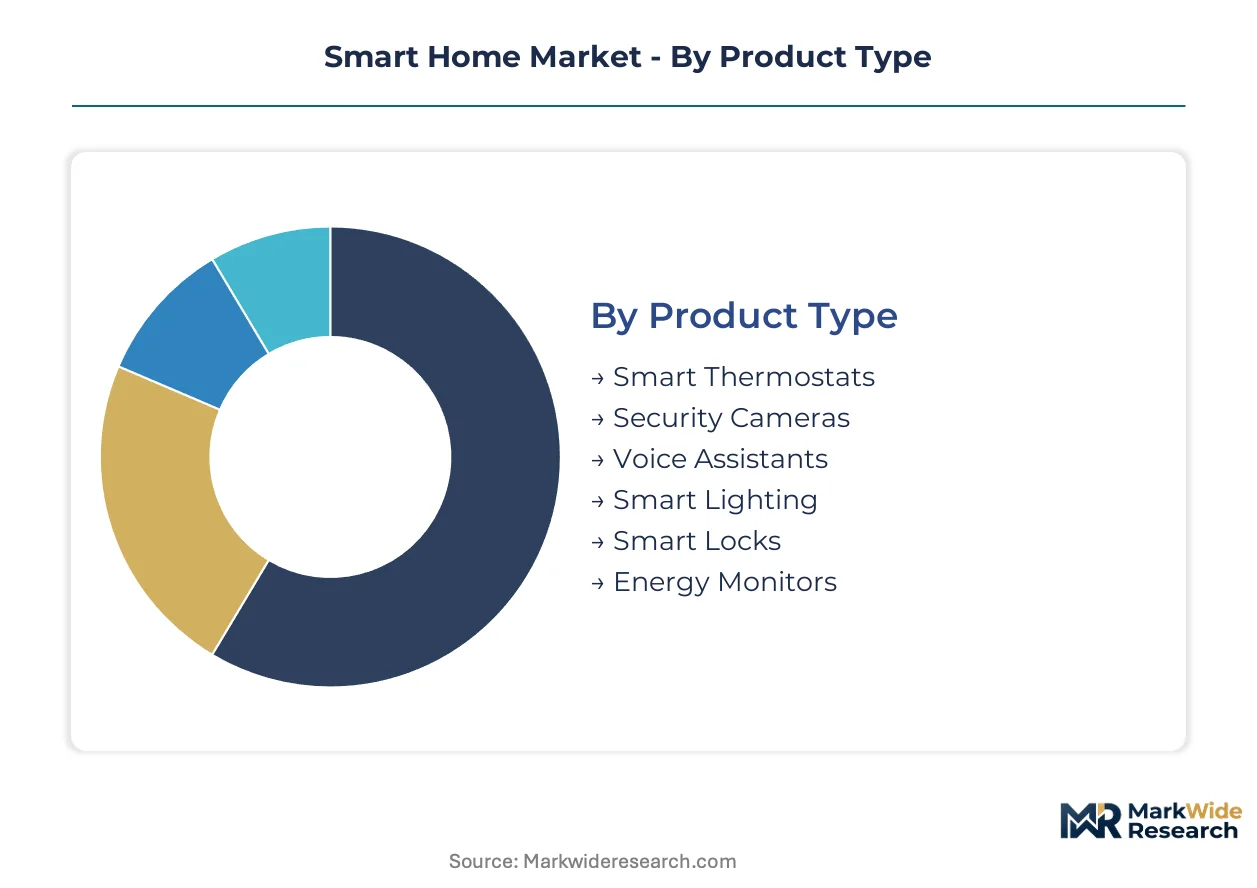
Understanding the varied components of the smart home market provides clarity on demand drivers and technological shifts. This segmentation highlights the distinct product types, underlying communication technologies, diverse applications, and primary end-user groups. Analyzing these segments reveals where value creation and innovation are most concentrated.
Product Type:
The supply chain for smart home product types is increasingly concentrating around integrated device manufacturers and platform providers. These entities control the design and production of connected hardware that consumers install within their residences.
- Smart Thermostats:These devices intelligently control heating and cooling systems, optimizing energy usage based on occupancy and external factors. Demand for smart thermostats is particularly strong in European markets due to stringent energy efficiency mandates and carbon reduction goals.
- Security Cameras:Connected cameras offer real-time visual monitoring and recording capabilities, enhancing property surveillance and occupant safety. Adoption of security cameras is high in affluent urban centers across the United States, driven by a desire for enhanced personal and property protection.
- Voice Assistants:These AI-powered devices respond to spoken commands, facilitating control over other smart home devices and providing information services.
- Smart Lighting:Networked lighting systems allow for remote control, scheduling, and color adjustment, improving ambiance and energy savings.
- Smart Locks:Electronic door locks enable keyless entry and remote access management, bolstering home security.
- Energy Monitors:Devices that track and display real-time electricity consumption, empowering users to make informed decisions about energy use.
Security Cameras absorb the bulk of installed capacity; Smart Thermostats are expanding most quickly.
Technology:
The maturity of various communication technologies directly influences their interoperability and ease of integration within smart home ecosystems. Established protocols provide broad compatibility, while newer standards address limitations in speed, range, or power consumption.
- Wi-Fi:This ubiquitous wireless standard provides high-bandwidth connectivity for many smart home devices, leveraging existing home network infrastructure. Wi-Fi remains a primary choice for devices requiring substantial data transfer, particularly in North American residential installations.
- Thread:A low-power, mesh networking protocol designed for reliable and secure device-to-device communication, crucial for Matter-enabled ecosystems. Thread's adoption is accelerating in new construction projects seeking robust and future-proof smart home foundations.
- Zigbee:A low-power, short-range wireless technology that creates mesh networks for device control, commonly used in smart lighting and sensor applications.
- Z-Wave:Another low-power wireless mesh network protocol, optimized for reliable communication over longer distances within residential environments.
- Bluetooth LE:Bluetooth Low Energy provides short-range, low-power connectivity, frequently integrated into personal devices and smaller smart home accessories.
- Infrared:An older wireless technology primarily used for line-of-sight remote control of entertainment systems and some legacy appliances.
Wi-Fi technology underpins a majority of current smart home installations, while Thread is gaining market share at the fastest rate.
Application:
The perceived value and initial investment associated with smart home applications often dictate their market penetration across different consumer segments. Certain applications offer immediate cost savings, while others prioritize long-term convenience or safety benefits.
- Safety & Security:This application segment includes smart locks, security cameras, and alarm systems, providing robust protection against intrusions and hazards. Demand for safety and security solutions is particularly high in luxury housing markets and for properties in high-density urban areas.
- Energy Management:Solutions like smart thermostats and energy monitors optimize power consumption, reducing utility bills and environmental impact. The European retrofit market is a significant driver for energy management applications, responding to regulatory pressures for building efficiency.
- Home Automation:This broad category encompasses systems that automate routine tasks, such as lighting control, blind operation, and appliance scheduling.
- Voice Control:Integration with voice assistants enables hands-free operation of various smart home devices, enhancing user convenience.
- Entertainment:Smart home integration with audio-visual systems allows for centralized control of media consumption and immersive experiences.
- Elderly Care:Specialized smart home systems provide ambient monitoring, fall detection, and communication tools to support independent living for seniors.
Home Automation applications offer broad utility, but Elderly Care solutions are demonstrating the most significant expansion.
End User:
The volume of smart home device deployment varies significantly across different end-user segments, reflecting distinct purchasing power, technical aptitude, and specific requirements. Each user group presents unique opportunities for product development and service offerings.
- Homeowners:Individual property owners constitute the largest consumer base, seeking enhanced comfort, security, and energy efficiency for their primary residences. Homeowners in affluent urban centers of the United States are early adopters, integrating smart technologies during new construction or major renovations.
- Smart Building Operators:Professionals managing large residential or commercial complexes deploy smart systems for centralized control, maintenance, and resource optimization. New construction projects in coastal provinces of China frequently incorporate smart building solutions for efficiency and tenant appeal.
- Property Managers:These professionals oversee rental properties, utilizing smart devices for remote access, security, and utility monitoring across multiple units.
- Tenants:Renters often adopt individual smart devices for personal convenience and security, though whole-home system integration is less common due to property ownership limitations.
Homeowners represent the largest segment by volume, with Smart Building Operators showing strong growth in new deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
San Francisco's vibrant tech ecosystem drives smart home innovation, influencing global trends in connected living. The adoption of smart home technologies varies significantly by region, shaped by local regulatory environments and consumer priorities. Key urban centers globally demonstrate strong demand, particularly for energy management and security applications.
United States
Demand for smart home solutions in the United States concentrates in affluent urban centers, driven by new construction and major renovations. The US EPA's ENERGY STAR program encourages energy-efficient smart thermostats. Cities like Seattle and Boston lead in integrating advanced smart home systems into high-end residential developments.
China
China's coastal provinces exhibit a significant surge in smart home integration, particularly within new smart building projects. The MIIT governs IoT device standards and network connectivity protocols, fostering a structured market. Technology hubs such as Shenzhen and Shanghai are centers for both manufacturing and sophisticated smart home deployments.
Germany
Germany presents a strong market for assisted living solutions and energy management, catering to its aging population and sustainability goals. The EU Green Deal mandates increased energy efficiency in buildings, influencing product development. Munich and Hamburg are urban centers prioritizing energy savings in smart home retrofits and new installations.
Japan
Japan's market for smart home technologies increasingly focuses on solutions for its aging demographic, emphasizing convenience and safety. METI initiatives support smart community development and energy management systems. The Tokyo metropolitan area spearheads advanced smart home system deployments in both new and existing residences.
United Kingdom
The United Kingdom's extensive existing housing stock offers a substantial retrofit market for energy management and security. GDPR imposes strict data privacy requirements on connected devices, impacting manufacturer design. London's urban development projects and renovation efforts frequently incorporate smart lighting and security systems.
Smart Home Market Key Industry Players
Premium-margin players sit above commodity-margin players across the smart home ecosystem, differentiating through integrated platforms and specialized services. The market exhibits a tiered structure, with established technology giants competing alongside niche specialists. Strategic archetypes include comprehensive building automation providers and focused application developers. Companies frequently engage in strategic partnerships to expand ecosystem compatibility and portfolio diversification to capture broader customer segments.
Within the integrated solutions archetype, Siemens and Honeywell International exemplify established players leveraging extensive portfolios. Siemens, a German-based AG, anchors solutions in building management systems, representing a legacy of industrial control expertise. Honeywell International, an Inc., occupies a position of market leadership through its specialization in smart thermostats and climate control. Johnson Controls International, also an Inc., sits within this group by offering combined HVAC, security, and automation platforms for residential applications. These entities collectively demonstrate the market's shift towards holistic, enterprise-grade smart home offerings.
| Leading Market Players |
|---|
| Siemens |
| Samsung |
| Honeywell International |
| Apple |
| LG Electronics |
| ABB |
| Alphabet |
| Amazon |
| Johnson Controls International |
| Others |
Cost & Logistics Intelligence
Premium-tier whole-home smart systems, offering integrated platforms and professional installation, command higher prices and rely on specialized integrators. Commodity-level DIY devices, conversely, compete on volume and flow through mass retail channels.
Pricing Analysis
Value-based pricing, anchored to energy savings and enhanced security outcomes, gains traction for integrated smart home solutions. The market employs a hybrid pricing model, combining project-based fees for whole-home systems with per-unit transactional sales for individual devices. Brand premium and comprehensive after-sales service drive price differentiation in the high-end segment, while pricing softness stems from intense competition in the DIY segment. Luxury homeowners exhibit lower price sensitivity compared to tenants.
Supply Chain Analysis
Dual-sourcing requirements for critical components are increasingly common among smart home device manufacturers to mitigate supply risks. Supply chain concentration centers on China for device manufacturing, with key semiconductor and sensor dependencies drawing from Taiwan and South Korea. Specialized communication modules represent a single-source vulnerability within the ecosystem. Distribution runs through a fragmented model, encompassing direct-to-consumer sales, mass retail channels, and specialized system integrators for whole-home solutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The smart home market operates under supply constraints, particularly regarding specialized semiconductor components essential for advanced device functionality. This persistent bottleneck for critical chips props up pricing for sophisticated integrated systems, impacting deployment timelines.
For Market Incumbents: Deepen integration with emerging interoperability standards like Matter to fortify platform stickiness against emerging entrant archetypes. Expand comprehensive service offerings, including professional installation and maintenance, to differentiate from DIY solutions. Invest in advanced R&D for on-device AI capabilities, enhancing security and personalization features. This strategy mitigates margin pressure from commodity device providers.
For New Entrants and Emerging Players: Capture white-space opportunities in the rapidly expanding assisted living solutions segment, particularly in Germany and Japan. Target the European retrofit market for energy management applications with easy-to-install, modular systems. Partner with home insurance providers to offer discounted security and leak detection systems, creating a new B2B2C sales channel. Focus on niche applications where established players face integration challenges.
For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated platform providers, given the accelerating shift towards holistic home management solutions. The long-term viability of the smart home market points towards ecosystem consolidation over the next decade. Acquisition targets should focus on niche specialists in cybersecurity or advanced energy management software. Accelerated adoption of the Matter communication standard serves as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration with Matter | Ensures broad device compatibility and simplifies the consumer experience across diverse smart home devices. |
| Expansion of Professional Installation Services | Addresses consumer demand for whole-home solutions, mitigating high initial investment concerns and enhancing user satisfaction. |
| Investment in AI-powered Security Analytics | Strengthens device resilience against cyber threats and provides proactive protection for user data and privacy. |
| Strategic Partnerships with Utility Companies | Incentivizes energy management adoption by linking smart devices to utility rebates and demand response programs. |
| Development of Assisted Living Ecosystems | Taps into an underserved demographic, providing critical monitoring and support for aging populations in key regions. |
Research Approach
Independent corroboration across device manufacturers' R&D leads, system integrators, and smart building operators underwrites the qualitative findings. Primary interviews with these industry stakeholders provided granular insights. Secondary validation drew from US EPA's ENERGY STAR program data, EU Green Deal reports, and MIIT IoT standards. This approach ensured robust bottom-up and top-down triangulation of market intelligence.
Rate-of-change decomposition informed the quantitative forecast framework across the analysis window. Segmentation dimensions modeled included product type, underlying technology, application segment, end-user group, and regional regulatory environment. Compound annual growth rates were derived by assessing historical trends and projected market drivers. Key forecast inputs included smart home device adoption rates and new construction starts in affluent urban centers.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to evolving data privacy regulations and communication protocol fragmentation. The forecasts reflect assumptions regarding technological advancements and consumer acceptance. Deviation in Matter standard adoption would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Belt Press Filter Market
Others
Tripod Market
Others
Folding Screen Mobile Phone Market
Others
Africa 3D Printing Construction Market
Others
China Cloud Gaming Technology Market
Others
Thermal Insulation Solution for LNG and LPG Market
Others
Semiconductor Gas Filters Market
Others
Ambient Assisted Living and Smart Home Market
Others
Baking Paper Market
Others
Europe Electric Forklift Market
Others
Spinner Flask Market
Others
Hip Tendinitis Market
Others
GCC Shisha Tobacco Market
Others
Process Spectroscopy Market
Others
Spain Feed Additives Market
Others
Middle East and Africa Cocoa Products Market