
 Folding Screen Mobile Phone Market | 2026-2036
Folding Screen Mobile Phone Market Size, Share, and Industry Trends Forecast 2026-2036
Folding Screen Mobile Phone Market Insights
Leasing and device-as-a-service financing is narrowing the addressable base to carriers and enterprise fleet managers with balance-sheet capacity for multi-year obligations. Samsung Electronics Co., Ltd. leverages vertical integration across display substrates and final assembly to sustain margin structures that pure hardware assemblers cannot match. Huawei Technologies Co., Ltd. anchors its position through captive semiconductor design and domestic channel control in mainland China. BOE Technology Group Co., Ltd. competes as a panel supplier rather than brand owner, extending its reach into tier-one OEM supply chains.
A folding screen mobile phone integrates flexible organic light-emitting diode substrates with multi-axis hinge mechanisms to deliver tablet-equivalent display area within pocketable form factors, typically rated for hundreds of thousands of fold cycles under standardized mechanical stress testing. Foldable Devices dominate current shipment volumes while Flip Phones command premium positioning in fashion-conscious consumer segments; LTPO backplane technology is displacing conventional OLED drivers in high-refresh-rate configurations where power efficiency determines battery endurance benchmarks. Online Retail channels are capturing enterprise bulk orders through configurable B2B portals, diverting volume from Physical Stores in mature markets.
South Korea's national radio research agency enforces electromagnetic compatibility and SAR exposure limits that gate market entry for non-compliant hardware designs. China's MIIT and SAMR jointly administer network access licenses and product quality certifications that mandate fold-cycle durability disclosure. The EU's RoHS and REACH frameworks restrict hazardous substance use in flexible substrate lamination adhesives. Stakeholders must monitor how durability certification thresholds in major economies reshape R&D allocation between hinge engineering and display substrate chemistry.
Market Dynamics
LTPO backplane technology is collapsing power consumption differentials between foldable and conventional handsets, forcing OEMs to redesign thermal management architectures and battery cell configurations to sustain competitive endurance benchmarks.
Growth Catalysts
- Enterprise fleet mobility mandates:Procurement departments in logistics and field services are standardizing on foldable form factors for workforce productivity applications, creating recurring volume commitments independent of consumer upgrade cycles.
- China's MIIT durability certification tightening:The Ministry of Industry and Information Technology's escalating fold-cycle disclosure requirements are filtering out substandard hinge designs and elevating baseline quality expectations across export supply chains.
- Flexible substrate chemistry advances:Polyimide and ultra-thin glass lamination processes are extending display lifespan ratings, reducing total cost of ownership calculations for institutional buyers.
Market Restraints
- Display substrate supply concentration:Korean and Chinese panel manufacturers control critical flexible OLED capacity, creating allocation bottlenecks during demand surges and limiting pricing leverage for downstream assemblers.
- Hinge mechanism precision manufacturing costs:Multi-axis torque engineering and aerospace-grade alloy sourcing sustain bill-of-material premiums that compress margins at volume price points.
- Electromagnetic compatibility certification friction:South Korea's RRA testing protocols and SAR exposure limits impose redesign costs and timeline delays for non-domestic hardware entrants.
Strategic Opportunities
- India's PLI scheme for electronics manufacturing:Production-linked incentives for display assembly and component sourcing are attracting module integration investments that could diversify supply origins beyond East Asian concentration.
- Device-as-a-service channel expansion:Carrier and enterprise leasing platforms are creating predictable revenue streams and reducing upfront adoption barriers for premium-tier foldable procurement.
- LTPO-OLED convergence with 5G mmWave antenna integration:Combined engineering of adaptive refresh backplanes and flexible radio frequency modules enables differentiated product positioning in high-bandwidth enterprise segments.
Industry Challenges
- Reliability engineering talent scarcity:Specialized mechanical design expertise for hinge fatigue analysis and fold-cycle simulation remains concentrated among a limited pool of experienced practitioners, constraining R&D velocity.
- Multi-jurisdiction certification synchronization:Parallel compliance timelines across China's MIIT network access, South Korea's RRA electromagnetic approvals, and EU REACH substance restrictions extend product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Folding Screen Mobile Phone Market |
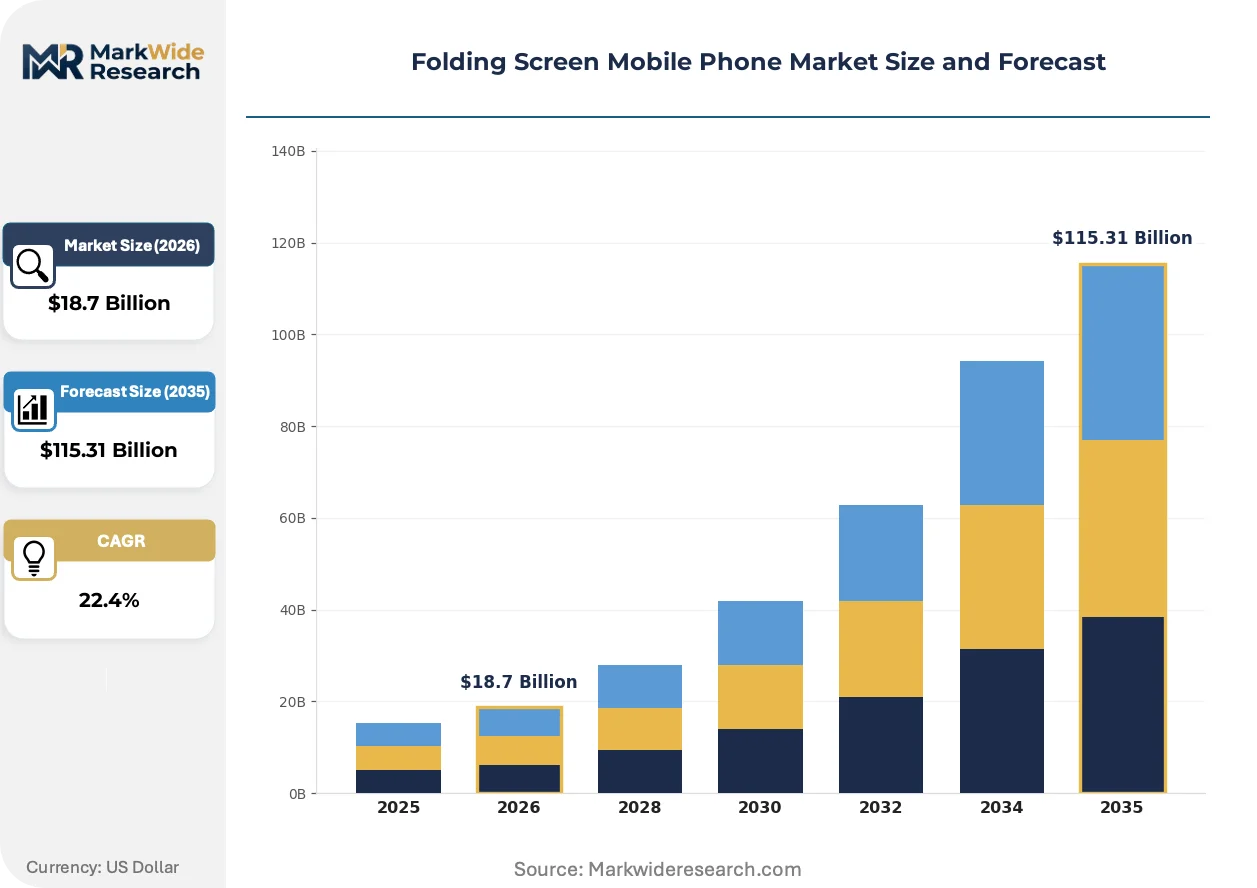
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $115.31 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flip Phones, Foldable Devices, Multi-Display Phones, Hybrid Phones Technology: OLED, LTPO, MicroLED, Flexible Displays End User: Consumers, Enterprises, Tech Enthusiasts, Gamers Distribution Channel: Online Retail, Physical Stores, Direct Sales, Authorized Resellers |
| Companies Covered | Samsung Electronics Co., Ltd., Motorola Mobility LLC, BOE Technology Group Co., Ltd., Visionox Company, Huawei Technologies Co., Ltd., Honor Device Co., Ltd., Google, OnePlus, TCL China Star Optoelectronics Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Folding Screen Mobile Phone Market Trends and Innovations
Three converging forces are restructuring how foldable devices are engineered, certified, and financed. Material science breakthroughs are compressing form factor trade-offs. Regulatory disclosure mandates are reshaping competitive transparency. Procurement model evolution is decoupling ownership from access.
Ultra-thin glass (UTG) substrate technology is collapsing the durability gap between flexible displays and rigid smartphone panels. Samsung Display and Chinese panel suppliers are scaling UTG lamination capacity to serve both in-house brands and third-party OEM programs. The structural consequence is collapsing premium pricing power for early-generation polyimide-only designs, forcing portfolio-wide refresh cycles.
China's MIIT and SAMR joint certification framework is mandating standardized fold-cycle durability disclosure before network access license issuance. The industrial consequence is elevating R&D allocation toward hinge mechanism engineering and substrate adhesion chemistry. Export-oriented manufacturers are responding by pre-certifying platforms for multiple jurisdiction requirements simultaneously, compressing regional launch intervals.
Enterprise procurement departments are consolidating handset acquisition through carrier-managed leasing platforms with configurable end-of-term refresh options. Physical retail channels in South Korea and select European markets are ceding volume to B2B portal configurations that bundle fleet management software with hardware obligations. The shift is most visible in logistics and field service verticals where total cost of ownership calculations dominate specification decisions.
Folding Screen Mobile Phone Market Segmentation
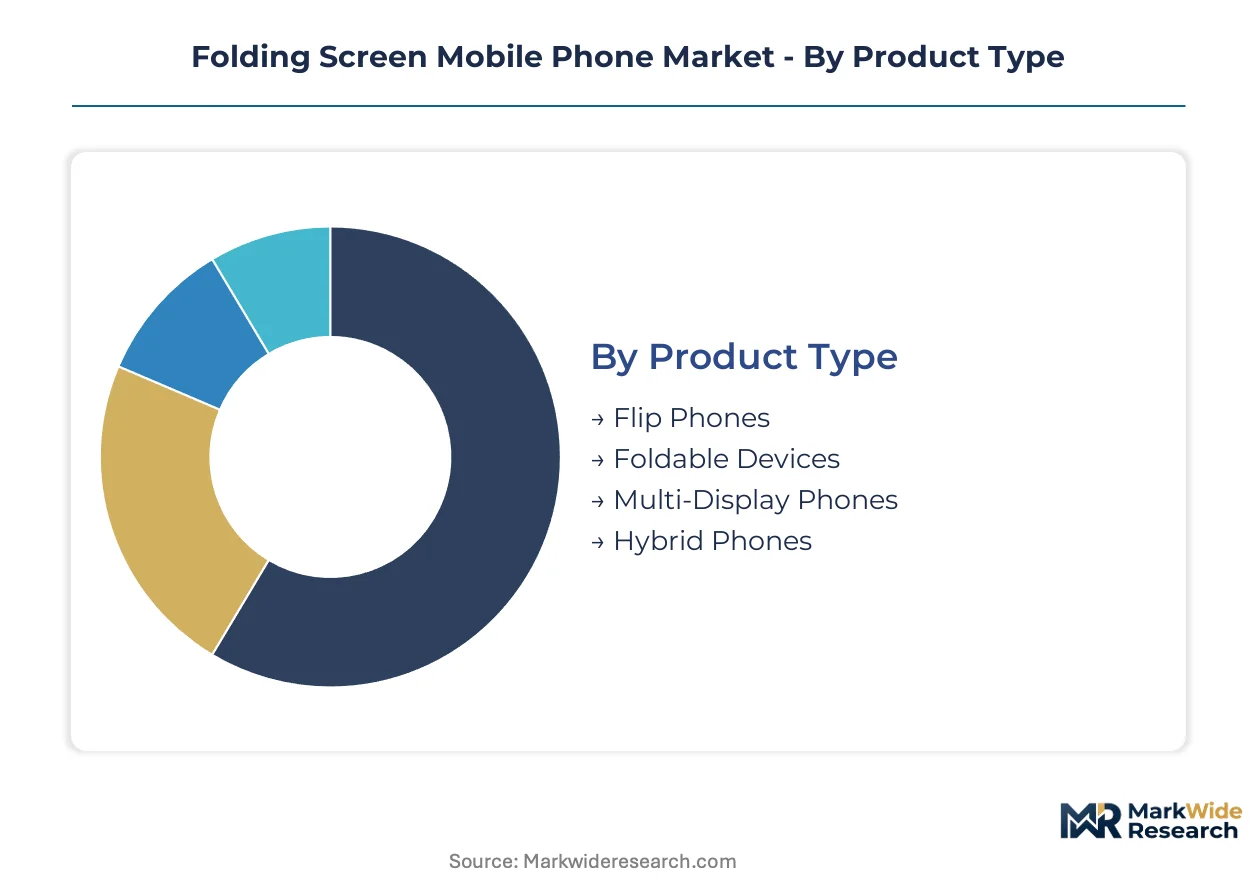
Form factor preferences, display technology roadmaps, and procurement channel strategies diverge sharply across customer types in the folding screen mobile phone market. Each segmentation axis reveals distinct margin structures and competitive dynamics that reshape how OEMs allocate R&D and manufacturing capacity.
Product Type:
The use-case spectrum spans pocketable clamshell designs through multi-panel productivity tools, with hinge complexity and display area driving fundamentally different engineering investments and price positioning.
- Flip Phones:Vertical-folding clamshell designs pair compact portability with external cover displays for notification triage. Fashion-conscious consumers in South Korea's premium retail corridors drive volume, with hinge aesthetic engineering and colorway customization commanding margin premiums over functional specifications alone.
- Foldable Devices:Horizontal-folding book-style form factors deliver tablet-equivalent screen real estate through flexible OLED substrates bonded to precision torque hinges. Enterprise fleet managers in logistics and field services concentrate procurement here, prioritizing document readability and multitasking workflows over pocketability metrics.
- Multi-Display Phones:Dual rigid panels connected by mechanical hinges or magnetic coupling systems bypass flexible substrate durability concerns. Niche positioning targets productivity-focused users unwilling to accept fold-cycle degradation risks.
- Hybrid Phones:Experimental form factors combining rollable, slideable, or tri-fold mechanisms remain pre-commercial, with concept demonstrations at trade events preceding limited production runs for technology showcase purposes.
The dominant share belongs to Foldable Devices, while Flip Phones is closing the gap fastest.
Technology:
Backplane architecture and emitter material choices determine power efficiency, refresh rate capability, and manufacturing cost structure across the competitive landscape.
- OLED:Conventional organic light-emitting diode stacks on polyimide substrates established the foundational flexible display technology. Mature manufacturing processes at Korean and Chinese panel suppliers support cost-down trajectories for mid-tier foldable introductions.
- LTPO:Low-temperature polycrystalline oxide backplanes enable adaptive refresh rate scaling from 1Hz to 120Hz, collapsing power consumption differentials against conventional rigid smartphones. Samsung Display and BOE Technology Group Co., Ltd. have prioritized capacity expansion here, with flagship-tier foldables now standardizing on this architecture.
- MicroLED:Inorganic emitter technology promises superior brightness and elimination of organic degradation mechanisms, though transfer yield challenges and pixel density limitations constrain deployment to proof-of-concept devices and luxury limited editions.
- Flexible Displays:Ultra-thin glass lamination and advanced polyimide chemistry iterations extend fold-cycle ratings, with substrate suppliers competing on durability certification thresholds demanded by China's MIIT disclosure mandates.
LTPO has captured the flagship tier, while MicroLED remains furthest from volume scaling.
End User:
Procurement authority and total cost of ownership calculation methods fragment demand across consumer preference-driven and institutional specification-driven segments.
- Consumers:Individual purchasers prioritize form factor novelty, brand prestige signaling, and content consumption ergonomics. Upgrade cycles align with carrier subsidy refresh windows and trade-in program incentives.
- Enterprises:Fleet procurement departments standardize specifications across field workforce populations, with device-as-a-service financing and end-of-term refresh obligations creating predictable multi-year revenue commitments independent of consumer sentiment volatility.
- Tech Enthusiasts:Early adopter cohorts drive initial volume for experimental form factors, providing real-world durability feedback that shapes subsequent mainstream product iterations.
- Gamers:Mobile gaming specialists demand high-refresh-rate LTPO configurations with thermal headroom for sustained performance, representing a premium sub-segment with distinct accessory ecosystem requirements.
Enterprise procurement is expanding fastest, though Consumer volume retains absolute scale leadership.
Distribution Channel:
Channel economics and customer acquisition cost structures diverge between high-touch physical retail and configurable digital platforms.
- Online Retail:E-commerce platforms and carrier digital storefronts capture bulk enterprise orders through B2B portals with configurable fleet management software bundling. South Korean and European markets show accelerating channel shift here.
- Physical Stores:Premium retail corridors in Seoul and select Chinese tier-one cities sustain tactile evaluation importance for first-time foldable purchasers, with hinge mechanism demonstration and display quality comparison driving conversion.
- Direct Sales:OEM-owned flagship stores and enterprise account teams handle large-scale institutional negotiations with customized service level agreements and dedicated technical support provisioning.
- Authorized Resellers:Regional distributor networks extend geographic coverage in markets where direct retail infrastructure remains underdeveloped, though margin compression and inventory risk allocation create friction in manufacturer-partner relationships.
Online Retail is gaining share fastest, while Physical Stores defends position through experiential differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in folding screen mobile phones reflect concentrated display substrate production in East Asia against distributed final assembly and enterprise procurement across North America and Europe. Import dependency for flexible OLED panels shapes regional market entry costs and certification sequencing.
South Korea
Seoul's premium retail corridors sustain tactile evaluation culture for first-time foldable purchasers, with Gangnam district flagship stores driving conversion through hinge mechanism demonstration. The Radio Research Agency enforces electromagnetic compatibility and SAR exposure limits that gate market entry for non-compliant hardware designs. Samsung Electronics anchors domestic volume through vertical control of display substrates and final assembly.
China
Enterprise fleet procurement in logistics verticals concentrates demand for horizontal-folding form factors across Beijing and Shanghai corporate headquarters. The Ministry of Industry and Information Technology and SAMR jointly administer network access licenses mandating standardized fold-cycle durability disclosure before commercialization. BOE Technology Group and TCL China Star Optoelectronics dominate flexible panel supply from facilities in the Yangtze River Delta and Pearl River Delta.
United States
Carrier-managed leasing platforms capture enterprise bulk orders through configurable B2B portals, diverting procurement from physical retail channels. The FCC governs radio frequency equipment authorization and electromagnetic emissions compliance for foldable devices operating on domestic networks. Google's Android ecosystem integration efforts concentrate engineering talent in the San Francisco Bay Area and Seattle metropolitan clusters.
Germany
Automotive sector procurement departments evaluate foldable devices for field engineering workforce mobility, with Stuttgart and Munich industrial corridors driving B2B specification standards. The EU REACH framework restricts hazardous substance use in flexible substrate lamination adhesives alongside RoHS directives. Berlin-based enterprise software vendors bundle fleet management platforms with hardware leasing obligations.
India
Production-linked incentive schemes for electronics manufacturing attract display module integration investments targeting export markets and domestic enterprise demand. The Bureau of Indian Standards and TRAI administer equipment certification and spectrum allocation for devices operating on domestic networks. Tamil Nadu and Karnataka industrial corridors host final assembly investments from Korean and Chinese OEM supply chain partners.
Folding Screen Mobile Phone Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream controlling critical substrate and hinge supply. The vendor base concentrates around vertically integrated conglomerates with captive display manufacturing against pure-brand assemblers dependent on external panel procurement. Three archetypes dominate: conglomerate platforms with semiconductor and display fabrication, panel specialists supplying multiple OEMs, and brand-assemblers leveraging software differentiation. Competitive positioning hinges on backward integration into flexible OLED capacity and multi-jurisdiction certification pre-positioning.
Among Korean conglomerates, Samsung Electronics Co., Ltd. exemplifies the vertically integrated archetype spanning display substrates through final assembly. Chinese panel specialists BOE Technology Group Co., Ltd. and TCL China Star Optoelectronics Co., Ltd. occupy upstream positions supplying tier-one OEM programs without direct brand ownership. Motorola Mobility LLC represents the brand-assembler model dependent on external component sourcing and software ecosystem partnerships.
| Leading Market Players |
|---|
| Samsung Electronics Co., Ltd. |
| Motorola Mobility LLC |
| BOE Technology Group Co., Ltd. |
| Visionox Company |
| Huawei Technologies Co., Ltd. |
| Honor Device Co., Ltd. |
| OnePlus |
| TCL China Star Optoelectronics Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Chinese flexible OLED fabs is compressing supplier pricing power while Korean display makers defend premium positioning through UTG lamination differentiation. This utilization asymmetry drives divergent procurement strategies: volume buyers exploit panel allocation abundance while quality-sensitive OEMs pay premiums for durability-certified supply.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures with volume-scale discounts and certification-grade tiering. Price differentiation hinges on fold-cycle durability ratings under MIIT disclosure mandates and hinge mechanism precision grades. Cost compression in mid-tier configurations is intensifying because polyimide substrate suppliers are expanding capacity faster than brand demand. Enterprise fleet managers show lowest price sensitivity due to total cost of ownership calculations, while consumer channel distributors face highest margin pressure from trade-in program subsidies.
Supply Chain Analysis
Extended payment terms from Korean panel suppliers are stabilizing cash flow for downstream assemblers amid display substrate supply concentration. Flexible OLED capacity concentrates in South Korea, China, and Taiwan, drawing from ultra-thin glass substrates, aerospace-grade hinge alloys, and polyimide films. Single-source vulnerability in UTG lamination equipment creates allocation bottlenecks during demand surges. Distribution runs through carrier-managed leasing platforms and B2B enterprise portals, diverting volume from physical retail channels in mature markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The folding screen mobile phone market represents high-growth hardware disruption as LTPO backplane technology collapses power consumption barriers against conventional smartphones. China's MIIT durability certification tightening is filtering out substandard hinge designs and elevating baseline quality thresholds.
For Market Incumbents: Insulate flagship margin structures by deepening backward integration into flexible OLED capacity and pre-certifying platforms for multi-jurisdiction requirements simultaneously. Samsung Electronics and Huawei Technologies demonstrate how captive display fabrication and domestic channel control defend pricing power against pure-brand assemblers dependent on external panel procurement. Priority investment in hinge fatigue simulation talent pools addresses reliability engineering scarcity constraining R&D velocity.
For New Entrants and Emerging Players: Establish a beachhead in India's PLI-subsidized manufacturing corridor, where production-linked incentives for display assembly are attracting module integration investments beyond East Asian concentration. Enterprise fleet mobility mandates in logistics and field services represent the most penetrable segment, with device-as-a-service financing reducing upfront adoption barriers. Go-to-market positioning should bundle fleet management software with hardware obligations through carrier digital storefronts.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among panel specialists supplying multiple OEM programs without direct brand ownership, as BOE Technology Group and TCL China Star Optoelectronics demonstrate. Long-term viability across the projection horizon favors upstream component suppliers with certification pre-positioning and capacity expansion in India. Watch for fold-cycle durability disclosure threshold escalations by China's MIIT as the signal for R&D allocation shifts between hinge engineering and substrate chemistry.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Flexible OLED Capacity | Samsung Display's captive supply anchors margin structures that external panel buyers cannot replicate. |
| Multi-Jurisdiction Certification Pre-Positioning | Parallel MIIT, RRA, and REACH compliance compresses regional launch intervals for export-oriented manufacturers. |
| Device-as-a-Service Channel Expansion | Carrier leasing platforms with configurable refresh options create predictable revenue independent of consumer sentiment. |
| India PLI Manufacturing Investment | Tamil Nadu and Karnataka assembly corridors diversify supply origins beyond Korean and Chinese concentration. |
| LTPO-OLED Convergence with 5G mmWave Integration | Combined adaptive refresh and flexible RF module engineering enables differentiated enterprise positioning. |
Research Methodology
Initial hypotheses were tested against primary input from hinge mechanism engineers, display substrate R&D directors, enterprise fleet procurement managers, and carrier device financing leads, then refined through secondary validation. Bottom-up triangulation combined SEC filings from Samsung Electronics and BOE Technology Group, MIIT network access license databases, South Korean RRA electromagnetic compliance records, and IHS Markit smartphone production data. Top-down cross-checks incorporated customs trade flows for flexible OLED panels and hinge component import records.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, modeling volume and value outputs through form factor, display technology, end-user archetype, and distribution channel segmentation. CAGRs were derived from installed base evolution and replacement cycle assumptions, calibrated against enterprise fleet deployment pipelines and consumer upgrade elasticity parameters. Fold-cycle durability certification thresholds and LTPO backplane adoption curves served as industry-specific forecast inputs.
Stress conditions across panel capacity utilization rates, hinge alloy commodity volatility, and multi-jurisdiction certification timeline synchronization were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about enterprise procurement consolidation and carrier leasing platform expansion. Macroeconomic contraction, regulatory durability threshold escalation, or breakthrough rollable display technology would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Internet of Things Testing Market
Others
AI in Precision Medicine Market
Others
Wearable AI Market
Others
Italy Feed Additives Market
Others
High-Performance Films Market
Others
Latin America IT Device Market
Others
Pin Mills Market
Others
Europe Postal Services Market
Others
North America Video Conferencing Hardware Market
Others
Brazil Cane Sugar Market
Others
Global Wireless Asset Management Market
Others
Fluorite Market
Others
AC Switchgear Market
Others
Balsa Wood Market
Others
Global Social Networking Market
Others
Couscous Market