
 Europe Electric Forklift Market | 2026-2036
Europe Electric Forklift Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Electric Forklift Market Intelligence
The split between premium lithium-ion configurations and commodity lead-acid models is hardening across European procurement channels. Jungheinrich AG leverages its integrated battery production to dominate the high-voltage segment. KION GROUP AG sustains scale advantages through captive supply chains in Germany and Czechia. Combilift anchors its position in narrow-aisle specialization for Irish and UK warehousing clients.
Europe electric forklifts are battery-powered industrial trucks designed for horizontal transport and vertical lifting, typically operating at 24V to 80V with load centers ranging from 500mm to 600mm for palletized goods handling. Counterbalance forklifts occupy the mature volume tier where margin compression is most acute, while lithium-ion battery types are displacing lead-acid across the fastest-growing warehousing installations. Reach trucks command premium positioning in high-density racking environments where vertical storage efficiency determines facility economics.
EMA machinery directives, CE marking requirements, and EU Green Deal carbon benchmarks collectively mandate zero-emission transitions in indoor logistics operations. REACH chemical restrictions and the F-Gas Regulation constrain battery chemistry choices and thermal management system designs. Stakeholders must weigh total cost of ownership against residual value risk as battery technology cycles compress replacement timelines.
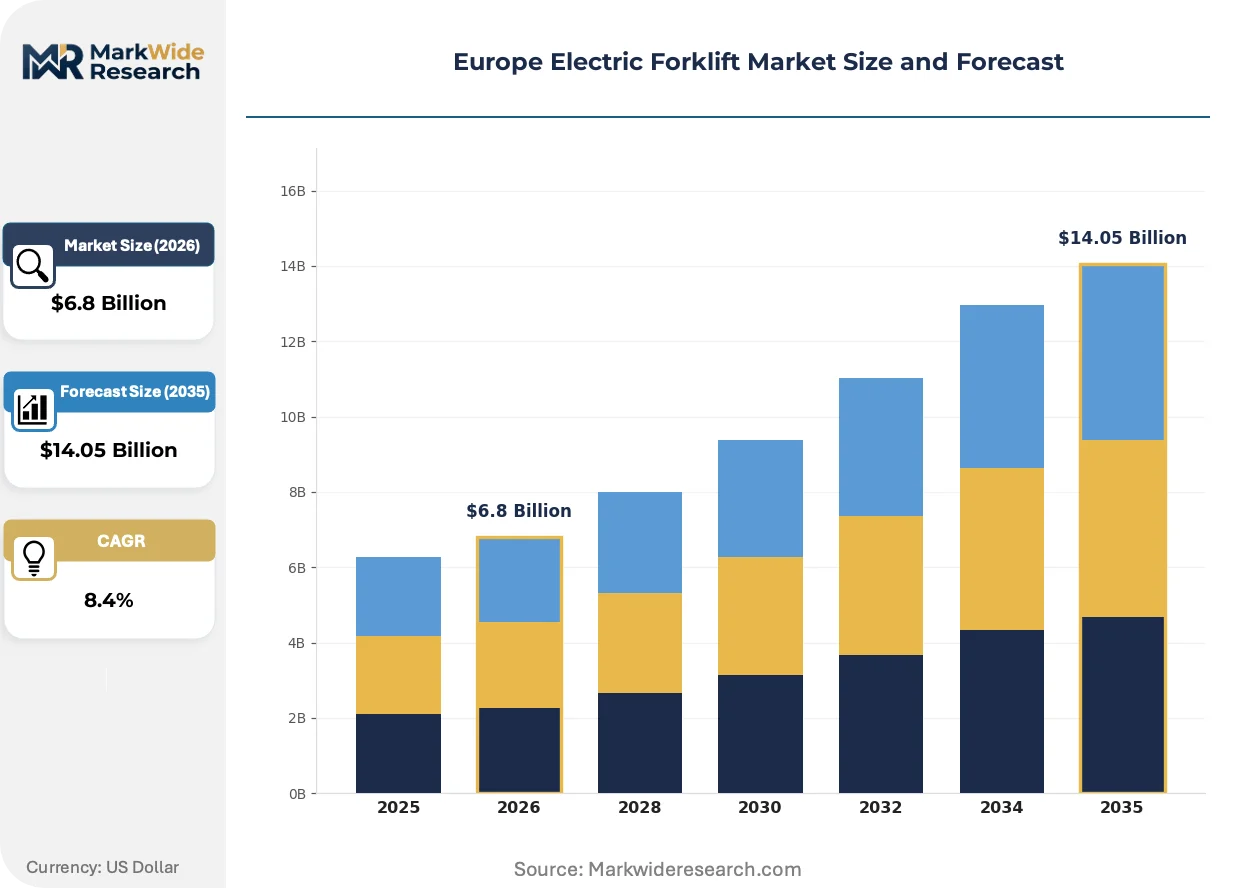
Market Dynamics
The EU F-Gas Regulation and REACH chemical restrictions are compressing battery chemistry choices while lithium-ion substitution accelerates across German and Italian warehousing clusters, forcing fleet operators to recalibrate total cost of ownership models against residual value risk.
Growth Catalysts
- Cold-chain logistics electrification:German food distribution operators are mandating zero-emission fleets for indoor cold storage facilities, pulling high-voltage lithium-ion configurations into temperature-controlled environments.
- REACH compliance protocols:Chemical substance restrictions are eliminating lead-acid battery options from premium procurement channels, redirecting capital toward sealed lithium-ion thermal management systems.
- Rhine-Ruhr industrial corridor concentration:Dense warehousing clusters across Düsseldorf, Cologne, and Dortmund are generating fleet-scale demand that justifies dedicated charging infrastructure investments.
Market Restraints
- Lithium carbonate price volatility:Raw material input costs for cathode production swing unpredictably, compressing margin visibility for battery pack assemblers serving the forklift segment.
- High-voltage technician scarcity:Certified service capacity for 80V systems concentrates in Germany and Czechia, creating maintenance bottlenecks for operators in peripheral European markets.
- Lead-acid residual value collapse:Secondary market liquidity for legacy battery assets is evaporating as recyclers face stricter ECHA waste classification requirements.
Strategic Opportunities
- Polish and Romanian distribution hub expansion:Greenfield warehousing investments in Central European logistics corridors lack mature electrified fleet suppliers, creating first-mover positioning for integrated solution providers.
- EU Green Deal carbon benchmarking:Mandatory emissions disclosure for logistics real estate is converting tenant preference into electrification clauses in warehouse lease agreements.
- Battery telematics convergence:Real-time state-of-health monitoring is converging with predictive maintenance platforms, enabling usage-based financing models that transfer residual risk from operators to manufacturers.
Industry Challenges
- CE marking timeline compression:Machinery directive certification cycles for new lithium-ion thermal configurations are extending as notified bodies grapple with evolving battery safety standards.
- Legacy fleet integration friction:Mixed-voltage operations combining 24V lead-acid units with 48V-80V lithium platforms require expensive charging infrastructure duplication and operator retraining.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Electric Forklift Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Counterbalance Forklifts, Reach Trucks, Pallet Jacks, Order Pickers End User: Warehousing, Manufacturing, Retail, Distribution Battery Type: Lead-Acid, Lithium-Ion, Nickel-Cadmium, Others Capacity: 1-2 tons, 2-3 tons, 3-4 tons, Above 4 tons |
| Companies Covered | Toyota Material Handling, Combilift, Jungheinrich AG, Doosan Corporation, TCM, KION GROUP AG, Crown Equipment Corporation, Cargotec Corporation, Linde Material Handling, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Electric Forklift Market Strategic Shifts & Innovations
Electrification architecture is splitting between integrated battery-forklift systems and modular swap-capable designs, with regulatory pressure and operational intensity determining which configuration dominates specific use cases.
Lithium iron phosphate chemistry is converging with opportunity charging infrastructure to eliminate battery changeout downtime. High-throughput e-commerce fulfillment centers in northern Italy are deploying 350V fast-charge stations that restore 80 percent capacity within 15 minutes. This convergence is compressing fleet sizing requirements and shifting capital allocation from spare battery inventory toward charging hardware.
The EU F-Gas Regulation is prohibiting hydrofluorocarbon-based thermal management fluids in battery cooling systems. Manufacturers are retrofitting production lines for CO2-based or dielectric fluid alternatives. Cold-chain operators in Germany face the most acute compliance pressure, as temperature-dependent battery performance directly impacts uptime guarantees.
Leasing structures are displacing outright purchase for mid-size fleet operators. Third-party logistics providers across the Benelux region are bundling maintenance, charging infrastructure, and energy supply into per-hour usage contracts. This shift transfers residual value risk to equipment financiers and prioritizes asset durability over acquisition price in supplier selection criteria.
Europe Electric Forklift Market Segmentation
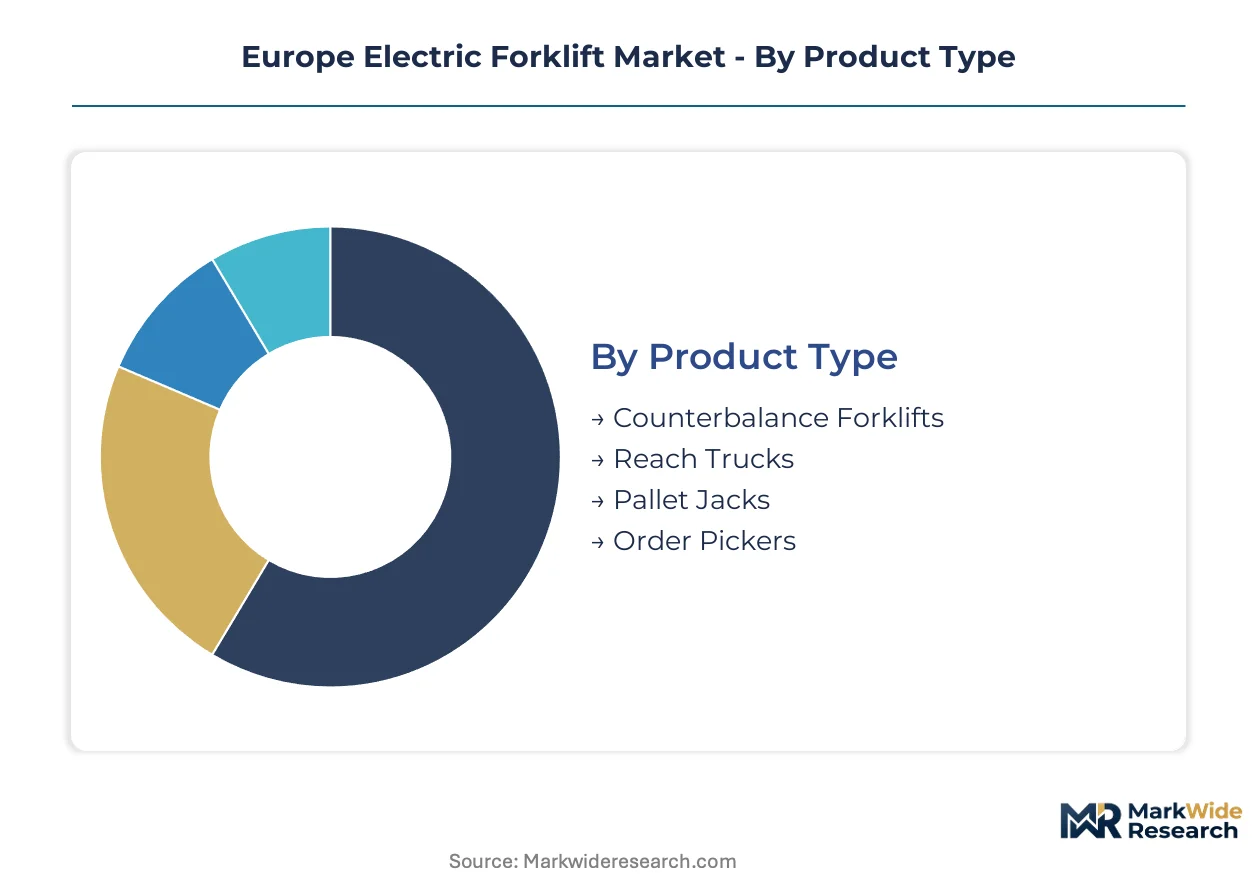
Fleet electrification programs across German cold-chain operators and Italian distribution hubs create divergent upgrade cycles across product configurations. Procurement channels now stratify sharply between premium lithium-ion platforms and legacy lead-acid replacements, with total cost of ownership calculations driving segment selection.
Product Type:
Replacement-cycle timing varies dramatically by aisle geometry and racking density, with narrow-aisle installations demanding faster technology refresh than standard warehouse layouts.
- Counterbalance Forklifts:These units dominate outdoor yards and bulk loading operations with load capacities spanning 1.5 to 8 tons. Rhine-Ruhr logistics clusters in Düsseldorf and Dortmund generate concentrated demand as operators retire diesel fleets ahead of EU Green Deal carbon benchmarking deadlines.
- Reach Trucks:Designed for vertical lifting in high-density racking environments up to 12 meters, these configurations command premium positioning. Northern Italian e-commerce fulfillment centers near Milan are pulling 48V-80V lithium platforms into temperature-controlled installations where uptime guarantees justify higher capital outlay.
- Pallet Jacks:Low-lift horizontal transport units serve last-mile distribution and cross-docking facilities.
- Order Pickers:Man-up vertical access platforms support piece-picking operations in retail distribution.
Volume placements concentrate in Counterbalance Forklifts; the faster expansion belongs to Reach Trucks.
End User:
Margin profiles diverge sharply by facility type, with temperature-controlled environments justifying premium battery configurations that general manufacturing floors reject.
- Warehousing:Third-party logistics providers across the Benelux region are bundling electrified fleets into per-hour usage contracts that transfer residual value risk to equipment financiers. CE marking requirements for lithium-ion thermal systems are extending certification timelines for new warehouse deployments.
- Manufacturing:Assembly-line feed operations and just-in-time component delivery drive demand for opportunity-charging compatible platforms. Czech automotive suppliers are retrofitting production logistics with 350V fast-charge infrastructure to eliminate battery changeout downtime.
- Retail:Store-level receiving and backroom operations favor compact 24V configurations with reduced maintenance requirements.
- Distribution:Cross-dock and consolidation facilities prioritize fleet flexibility over specialization.
Procurement scale favors Warehousing; Manufacturing shows the steepest technology-upgrade trajectory.
Battery Type:
REACH compliance protocols and F-Gas Regulation constraints are eliminating chemistry options from approved procurement channels faster than fleet depreciation schedules allow.
- Lithium-Ion:Lithium iron phosphate cells with sealed thermal management dominate new installations requiring opportunity charging. German food distribution operators are mandating these configurations for indoor cold storage as hydrofluorocarbon-based cooling fluids face prohibition.
- Lead-Acid:Flooded and sealed lead-acid systems retain installed base presence where capital constraints override operating cost considerations. Secondary market liquidity for these assets is evaporating as ECHA waste classification requirements tighten recycler economics.
- Nickel-Cadmium:Niche presence in extreme temperature applications where lithium performance degrades.
- Others:Emerging sodium-ion and solid-state chemistries in pilot deployment phases.
Installed base concentration remains with Lead-Acid; Lithium-Ion is gaining share fastest across new procurement.
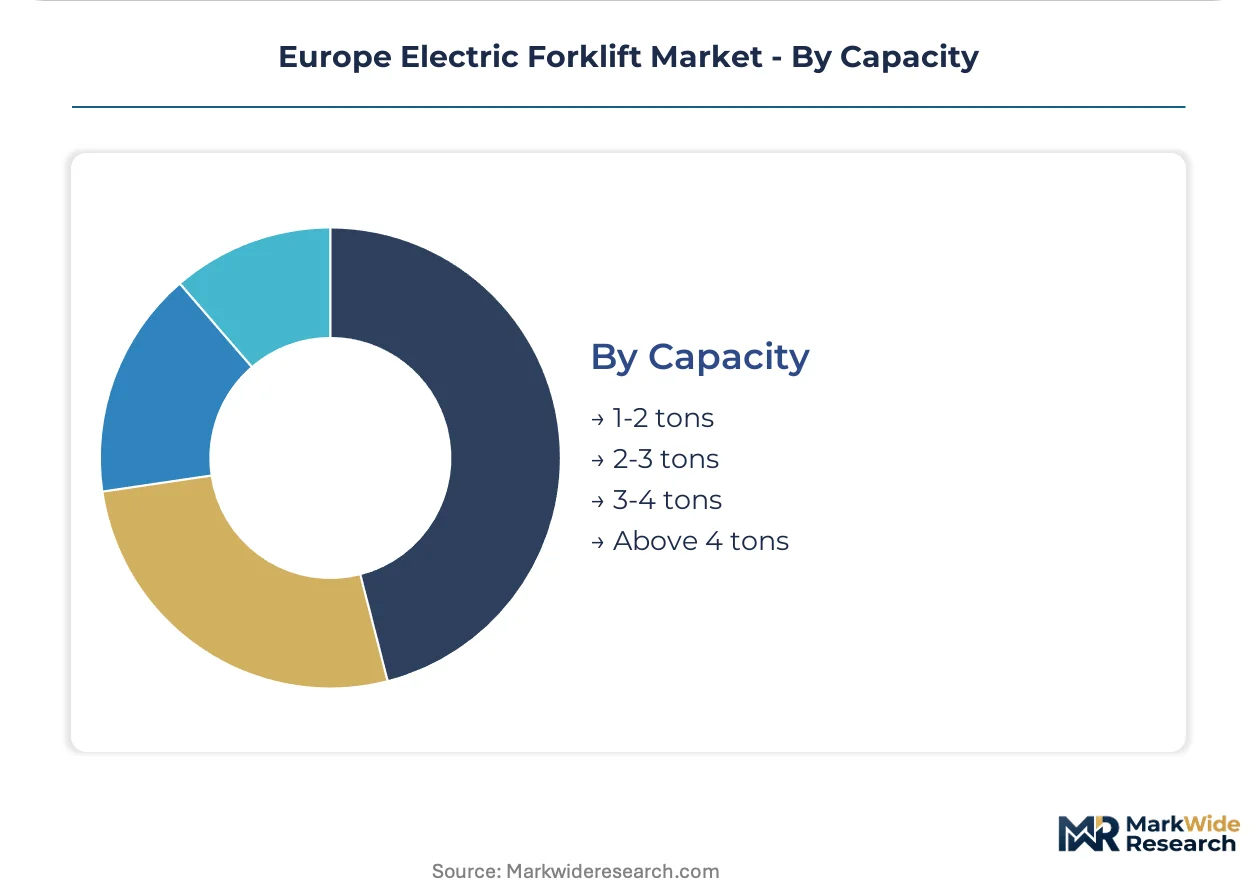
Capacity:
Load rating directly determines battery voltage architecture and charging infrastructure investment, creating segmentation lock-in that outlasts individual asset lifecycles.
- 2-3 tons:This mid-range tier captures standard pallet handling across retail distribution and light manufacturing. Polish and Romanian greenfield warehousing investments are concentrating demand here as Central European logistics corridors expand electrified fleet capacity.
- 3-4 tons:Heavy-duty units serve manufacturing feed operations and bulk distribution with reinforced mast structures. Northern Italian distribution hubs are deploying these configurations for mixed-load handling where SKU diversity prevents standardization on lighter platforms.
- 1-2 tons:Compact units for narrow-aisle and mezzanine operations.
- Above 4 tons:Specialized outdoor and heavy manufacturing applications.
Fleet standardization gravitates toward 2-3 tons; the 3-4 tons tier is expanding most quickly in multi-use distribution environments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Ruhr industrial corridor spanning Düsseldorf, Cologne, and Dortmund anchors fleet electrification momentum across European warehousing. Dense logistics clusters here justify dedicated charging infrastructure investments that pull high-voltage lithium-ion configurations into temperature-controlled distribution networks.
Germany
Cold-chain logistics operators in Hamburg and Berlin are mandating zero-emission fleets for indoor facilities. The EU F-Gas Regulation and REACH compliance protocols eliminate lead-acid options from premium procurement channels. The Rhine-Ruhr corridor generates concentrated demand as operators retire diesel fleets ahead of EU Green Deal carbon benchmarking deadlines.
Italy
E-commerce fulfillment centers near Milan pull 48V-80V lithium platforms into high-density racking environments. EMA machinery directives and CE marking requirements compress certification timelines for new warehouse deployments. Northern Italian distribution hubs deploy 350V fast-charge stations that restore 80 percent capacity within 15 minutes.
Netherlands
Third-party logistics providers across Rotterdam and Amsterdam bundle electrified fleets into per-hour usage contracts. The EU Green Deal mandates emissions disclosure for logistics real estate, converting tenant preference into electrification clauses. Benelux leasing structures transfer residual value risk to equipment financiers.
Poland
Greenfield warehousing investments in Warsaw and Łódź lack mature electrified fleet suppliers. Central European logistics corridors expand electrified fleet capacity in the 2-3 ton mid-range tier. Polish distribution hub expansion creates first-mover positioning for integrated solution providers.
France
Automotive suppliers in Lyon and Paris retrofit production logistics with opportunity-charging compatible platforms. ECHA waste classification requirements tighten recycler economics for legacy lead-acid assets. French manufacturing feed operations drive demand for 350V fast-charge infrastructure.
Europe Electric Forklift Market Key Industry Players
Capital-heavy producers compete with asset-light designers across a consolidated vendor base where captive battery production and integrated thermal management systems separate premium positioning from commodity volume. The market structure hardens around three strategic archetypes: integrated battery-forklift manufacturers, narrow-aisle specialists, and scale-driven fleet solution providers. Competitive moves concentrate on backward integration into cell production and geographic expansion into underpenetrated Central European corridors.
Among Germany-based integrated manufacturers, Jungheinrich AG and KION GROUP AG exemplify the premium-tier archetype through captive supply chains and high-voltage system specialization. Irish narrow-aisle specialist Combilift anchors positioning for UK and Irish warehousing clients. Toyota Material Handling represents the scale-driven multinational archetype with broad portfolio coverage across voltage configurations and load capacities.
| Leading Market Players |
|---|
| Toyota Material Handling |
| Combilift |
| Jungheinrich AG |
| Doosan Corporation |
| TCM |
| KION GROUP AG |
| Crown Equipment Corporation |
| Cargotec Corporation |
| Linde Material Handling |
| Others |
Cost & Logistics Intelligence
Lithium-ion premium-commodity bifurcation separates fleet operators who prioritize uptime guarantees from those optimizing capital deployment, with this divergence manifesting in both per-hour usage contracts and captive battery production investments across German and Czech manufacturing clusters. REACH compliance costs and F-Gas Regulation thermal system redesigns feed directly into supplier pricing power, while lead-acid residual value collapse eliminates secondary market offsets for budget-constrained buyers.
Pricing Analysis
Uptime-guarantee pricing anchors the European electric forklift market, with German cold-chain operators accepting 40-60% capital premiums for sealed thermal management systems that maintain performance in temperature-controlled environments. Price differentiation rests on CE marking tier and charging infrastructure bundling, with integrated battery-forklift configurations commanding premiums over modular swap-capable alternatives. Pricing pressure stems from lithium carbonate input volatility compressing margin visibility for battery pack assemblers. Third-party logistics providers across the Benelux region exhibit highest price sensitivity due to per-hour contract structures, while Rhine-Ruhr automotive suppliers show lowest sensitivity given downtime cost exposure.
Supply Chain Analysis
EU Green Deal domestic-content benchmarks for logistics real estate are reshaping sourcing patterns, with battery cell production increasingly tethered to European manufacturing to satisfy carbon disclosure requirements for warehouse lease agreements. Geographic supply concentration centers on Germany, Czechia, and Poland for forklift assembly, with lithium iron phosphate cathode materials drawing from China and South Korea. Raw material dependencies span lithium carbonate, cobalt-free cathode precursors, and CO2-based thermal management fluids replacing prohibited hydrofluorocarbons. Single-source vulnerability concentrates in high-voltage technician certification capacity, which clusters in Germany and Czechia. Distribution runs through OEM-direct channels for large fleet operators and specialized industrial equipment dealers serving mid-size warehousing clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified high-voltage service capacity scarcity across peripheral European markets props pricing power for integrated manufacturers, constraining fleet operator procurement options and sustaining premium capture for captive battery producers.
For Market Incumbents: Anticipate margin compression from Polish and Romanian greenfield entrants by accelerating backward integration into lithium iron phosphate cell production and securing exclusive charging infrastructure partnerships with Rhine-Ruhr logistics developers. Prioritize CE marking pre-certification for CO2-based thermal management configurations ahead of F-Gas Regulation enforcement deadlines. Channel control through captive financing arms transfers residual value risk while locking in multi-year fleet refresh cycles.
For New Entrants and Emerging Players: Mid-size Polish distribution hubs lacking mature electrified fleet suppliers represent the most penetrable entry point, with Warsaw and Łódź greenfield warehousing investments creating first-mover positioning for integrated solution providers. Romanian logistics corridors offer parallel white-space opportunity given EU Green Deal carbon benchmarking adoption. A battery-telemetry-as-service go-to-market angle, bundling predictive maintenance with usage-based financing, bypasses incumbent scale advantages in hardware production.
For Investors and Strategic Acquirers: Re-rating potential sits with narrow-aisle specialists possessing UK-Irish warehousing relationships given e-commerce fulfillment center expansion and vertical storage efficiency premiums. Long-term viability over a multi-year horizon favors manufacturers with in-house thermal management system design capabilities, as F-Gas Regulation compliance becomes non-negotiable for cold-chain operator procurement. The inflection indicator to monitor is Polish and Romanian lease agreement electrification clause penetration, which signals addressable market expansion timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cell Production | Jungheinrich AG's captive battery manufacturing insulates margin from lithium carbonate volatility. |
| Charging Infrastructure Partnership | 350V fast-charge station deployment in northern Italy eliminates battery changeout downtime for e-commerce operators. |
| CE Marking Pre-Certification | Early CO2-based thermal system approval accelerates warehouse deployment timelines ahead of competitors. |
| Usage-Based Financing Launch | Benelux per-hour contracts transfer residual value risk from operators to equipment financiers. |
| Geographic Expansion into Central Europe | Polish greenfield warehousing investments lack mature electrified fleet suppliers, creating positioning opportunity. |
Research Approach
Multi-period observation of fleet electrification program announcements, regulatory filing timelines, and battery chemistry substitution rates anchored the trend analysis, supplemented by interviews with warehouse operations directors, OEM procurement teams, aftermarket service heads, and industrial equipment financing specialists. Primary fieldwork combined with secondary validation from EU F-Gas Regulation implementation reports, ECHA substance restriction databases, customs trade data for lithium-ion battery imports, and SEC filings from publicly listed material handling equipment manufacturers. Bottom-up fleet size modeling and top-down logistics real estate investment flow analysis were triangulated to constrain value estimates.
Input-output matrices mapping battery voltage architecture to charging infrastructure investment requirements, load capacity tiers to end-use facility types, and thermal management configurations to regulatory compliance timelines structured the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, battery chemistry, end-use facility category, and regional logistics corridor development stage. CAGRs were derived from fleet replacement cycle timing, technology substitution elasticity estimates, and carbon benchmarking policy adoption curves. Forecast inputs incorporated lithium iron phosphate cost curves and certified technician training pipeline capacity.
Revisions become necessary when EU Green Deal carbon benchmarking enforcement timelines accelerate, lithium carbonate price volatility exceeds historical bands, or notified body CE marking capacity constraints extend certification cycles beyond fleet operator planning horizons. Forecasts reflect documented assumptions regarding regulatory implementation pacing and technology cost reduction trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
South America Halal Food and Beverages Market
Others
Fluorite Market
Others
Global B2B Enterprise and Industrial Wearables Market
Others
Fiberglass Storage Tanks Market
Others
Dried Fruit Extracts Market
Others
Pin Mills Market
Others
Augmented Shopping Market
Others
North America Compressor Oil Market
Others
Radar Speed Signs Market
Others
Augmented Reality (AR) in Manufacturing Market
Others
South Korea Intellectual Property Market
Others
Mobile Edge Computing Market
Others
Plastic Films and Sheets Market
Others
Automatic Barriers and Bollards Market
Others
Connected TV Market
Others
Legal Services Market