
 Smart Home Devices Market | 2026-2036
Smart Home Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Home Devices Market Intelligence
The shift towards devices with integrated AI for proactive automation is rotating the market towards higher-margin products. Google (Nest) leverages its AI and software expertise to build predictive home management ecosystems. Amazon dominates the voice assistant space, creating a central control point for a vast partner network. Samsung Electronics differentiates through its SmartThings platform, integrating home appliances with its broader consumer electronics portfolio.
Smart home devices are consumer electronics equipped with sensors, processors, and network connectivity for remote monitoring and control. These devices utilize low-power wireless protocols such as Zigbee or Thread to communicate with a central hub or directly with cloud services. The home security use case, encompassing security cameras and smart locks, commands a significant share due to consumer safety priorities. In terms of device types, smart thermostats and smart lighting continue to represent mature, high-volume categories.
Data privacy regulations like Europe's GDPR impose strict requirements on how user data is collected, a critical consideration for device makers. Concurrently, bodies such as the US Federal Communications Commission (FCC) and agencies enforcing China's GB standards regulate radio frequency emissions and device safety, shaping market access. Navigating the fragmented landscape of connectivity standards to ensure seamless interoperability remains the central challenge for all ecosystem participants.
Market Dynamics
The push for universal interoperability is the central force defining the smart home device market. This drive, crystallized by the development of standards like Matter, aims to resolve the long-standing fragmentation that has hindered consumer adoption and limited ecosystem growth across different brands.
Growth Catalysts
- Integrated AI:The embedding of artificial intelligence for proactive and predictive automation is elevating device functionality, moving beyond simple remote control to create truly responsive home environments.
- Hospitality Sector Adoption:Hotels and short-term rental providers are increasingly deploying smart devices, from locks to lighting, to streamline operations and offer personalized, high-tech guest experiences.
- Matter Connectivity Standard:The industry-wide rollout of the Matter protocol is a significant catalyst, promising to eliminate compatibility barriers between devices from different manufacturers and simplify the consumer setup process.
Market Restraints
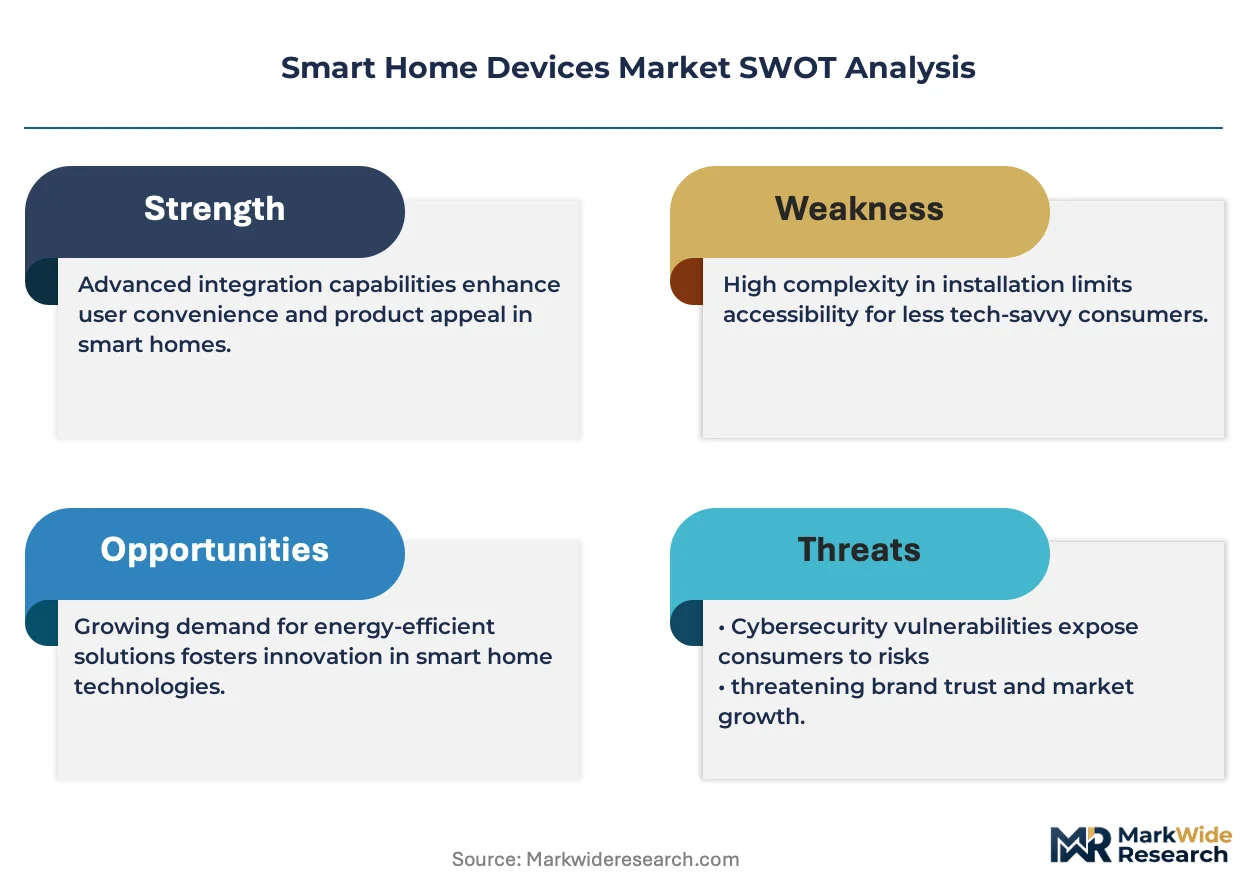
- Data Privacy Regulation:Europe's GDPR imposes strict consent and data handling requirements, creating significant compliance overhead and design constraints for manufacturers collecting user data for personalization.
- High Initial Cost:The premium price point of many smart home devices compared to their conventional counterparts remains a significant barrier to entry for mass-market consumers, slowing replacement cycles.
- Interoperability Fragmentation:Despite progress with Matter, a vast installed base of devices relies on older, proprietary protocols like Zigbee or Z-Wave, creating persistent ecosystem fragmentation and consumer confusion.
Strategic Opportunities
- Health and Wellness Integration:There is a growing opportunity to develop devices that integrate with health monitoring platforms, providing services like ambient assisted living for seniors or air quality management.
- Emerging Urban Centers:High-income urban clusters in regions like the Middle East and Southeast Asia represent underpenetrated markets with significant potential for smart home technology adoption.
- Energy Management Convergence:The convergence of smart home hubs with residential energy systems, including solar panels, battery storage, and EV chargers, opens new value streams in home energy optimization.
Industry Challenges
- Legacy System Integration:A primary operational hurdle is ensuring new smart devices can communicate and function effectively with existing, non-connected home infrastructure and appliances.
- Navigating RF Certification:Securing device approvals for radio frequency emissions from bodies like the FCC in the United States and complying with CE marking in Europe is a complex and time-consuming process.
- Cybersecurity Threat Mitigation:The constant evolution of cybersecurity threats requires manufacturers to invest heavily in ongoing software updates and vulnerability management to protect consumer privacy and safety.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Home Devices Market |
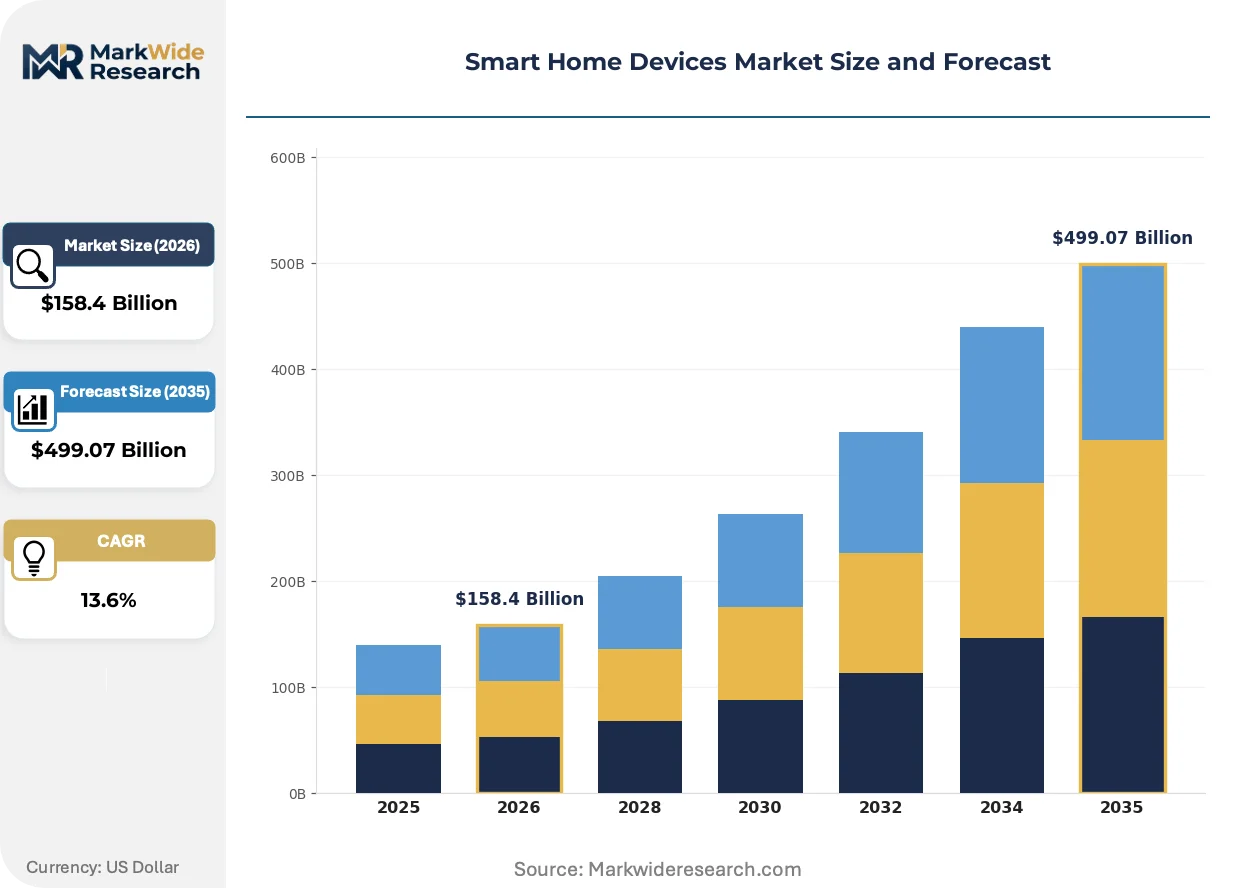
| Market Size in 2026 | $158.4 Billion |
| Market Size in 2035 | $499.07 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Smart Thermostats, Security Cameras, Voice Assistants, Smart Lighting, Smart Locks, Smart Plugs Connectivity Technology: Wi-Fi, Zigbee, Z-Wave, Bluetooth, Thread, LoRaWAN Use Case: Energy Management, Home Security, Voice Control, Lighting Automation, Remote Monitoring, Appliance Management End User: Homeowners, Property Managers, Hospitality Providers, Vacation Rental Operators, Smart Apartment Developers |
| Companies Covered | Samsung Electronics, Honeywell International, Amazon, Johnson Controls, Siemens, Google (Nest), LG Electronics, Schneider Electric, Apple, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Home Devices Market Strategic Shifts & Innovations
The market's evolution is defined by a decisive shift away from standalone gadgets toward deeply integrated, intelligent home ecosystems. This transition prioritizes proactive automation and seamless user experiences over single-point device functionality, altering product design and competitive strategy.
Edge computing allows for AI processing directly on a device, enabling faster responses and greater data privacy by reducing reliance on the cloud. Security-focused consumers and buyers in the premium segment are rapidly adopting devices with this capability. This trend is bifurcating the market into cloud-reliant, mass-market products and higher-margin, edge-powered devices that offer local control and enhanced performance.
The European Union's AI Act introduces a risk-based framework for artificial intelligence systems. Its primary industrial consequence is the imposition of stringent transparency, risk management, and data quality requirements on AI used in high-risk applications. Smart home security systems using AI-driven analytics are most affected, forcing manufacturers targeting the EU to re-architect their platforms for compliance.
A notable behavioral shift is the move from purchasing individual devices to acquiring complete, professionally-installed smart home packages. This disrupts the direct-to-consumer retail model in favor of channels like custom installers, home builders, and telecommunication companies offering managed services. The pattern is most pronounced in the new residential construction sector in the United States and Germany.
Smart Home Devices Market Segmentation
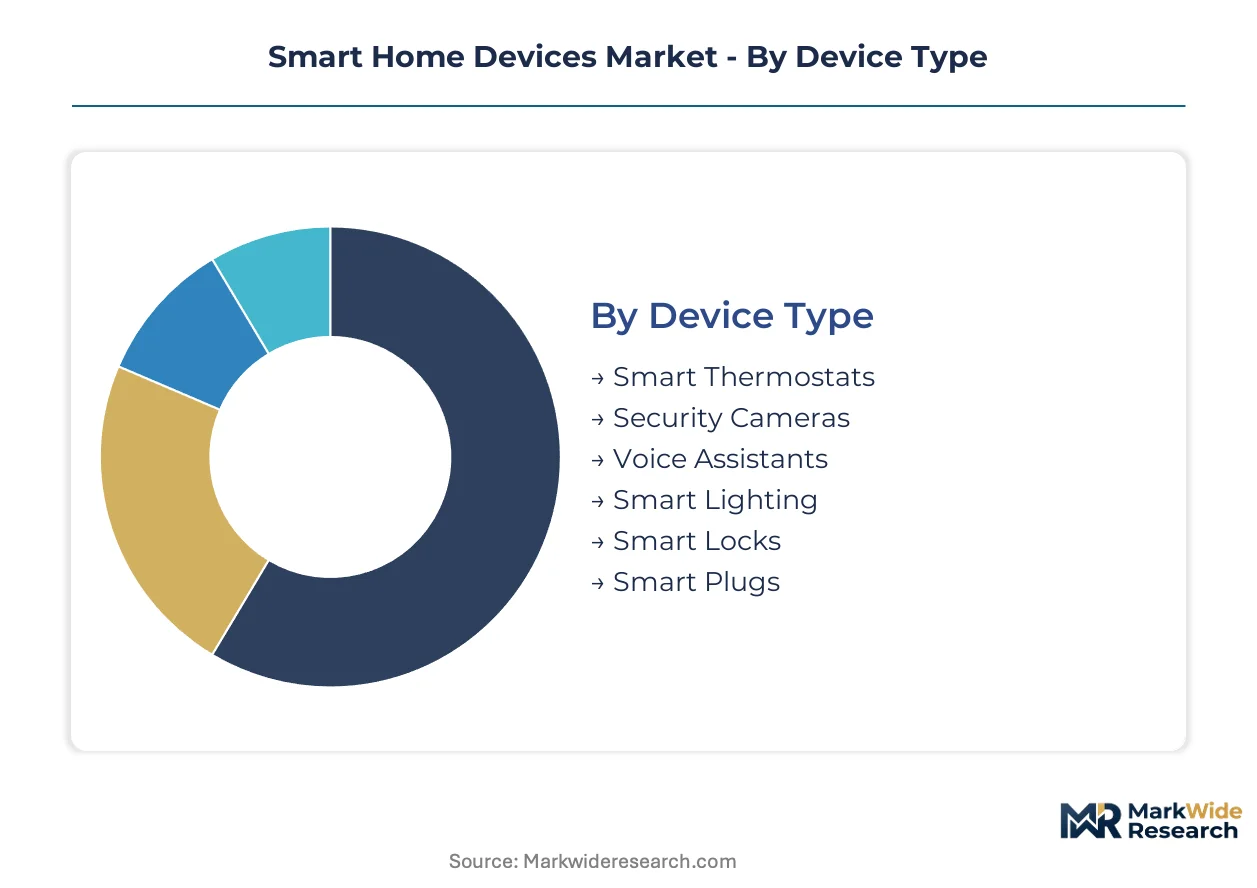
The Smart Home Devices Market segmentation reveals distinct functional areas and user profiles, each presenting unique value propositions and technological requirements. Understanding these segments is crucial for manufacturers to tailor product development and market entry strategies effectively. This detailed breakdown highlights areas of concentrated demand and evolving consumer expectations.
Device Type:
Margin pools within the device type category often sit with security-focused products and integrated systems offering proactive automation. These devices command higher price points due to their critical function and advanced analytical capabilities.
- Security Cameras:These devices incorporate high-definition video, motion detection, and cloud storage for surveillance, often integrating AI for person or pet recognition. Demand concentrates in high-income urban centers in the United States and Germany, driven by consumer safety priorities.
- Smart Thermostats:Programmable devices manage heating and cooling systems, learning user preferences and optimizing energy consumption through integrated sensors. This category sees high volume adoption in established residential markets due to cost-saving benefits.
- Voice Assistants:Centralized hubs like Amazon Echo and Google Home provide voice-activated control over other smart devices and access to information services. These devices serve as foundational control points within diverse smart home ecosystems.
- Smart Lighting:Connected bulbs and fixtures offer remote control, scheduling, and color temperature adjustments, enhancing ambiance and energy efficiency. This segment appeals to consumers seeking convenience and personalized home environments.
- Smart Locks:Keyless entry systems provide remote access control, visitor management, and activity logs, enhancing home security and convenience. Property managers and short-term rental operators increasingly deploy these solutions.
- Smart Plugs:These simple devices convert traditional appliances into smart devices, enabling remote power control and scheduling through a connected app. Smart plugs represent an accessible entry point for new smart home users.
Smart Thermostats hold installed capacity due to early market penetration. Security Cameras are rotating up the share rankings, driven by escalating consumer safety concerns.
Connectivity Technology:
The application of connectivity technologies determines device reliability and interoperability across the smart home ecosystem. Each protocol addresses specific requirements for range, power consumption, and data throughput.
- Wi-Fi:This ubiquitous protocol offers high bandwidth for streaming video and data-intensive applications, directly connecting devices to home networks and cloud services. Wi-Fi remains essential for devices requiring frequent data exchange, such as security cameras.
- Thread:A mesh networking protocol built for low-power, secure, and reliable communication between smart home devices, Thread is a foundational technology for the Matter standard. Adoption is expanding rapidly for new device installations aiming for future compatibility.
- Zigbee:A low-power, short-range wireless mesh network protocol optimized for small data packets and long battery life in smart home sensors and controls. It is a mature standard widely used in lighting and environmental monitoring.
- Z-Wave:Another low-power wireless mesh network protocol, Z-Wave operates on a different frequency, offering reliable communication for security and automation devices. Its robust signal penetration makes it suitable for larger homes.
- Bluetooth:Primarily used for short-range device pairing and direct control, Bluetooth Low Energy (BLE) enables efficient communication for personal devices and smaller smart home gadgets. It often serves as a setup or local control mechanism.
- LoRaWAN:This long-range, low-power wide-area network protocol suits applications requiring extended coverage and minimal power consumption, such as remote environmental monitoring or asset tracking. Its use in smart homes is emerging for specific outdoor or perimeter applications.
The integration of Wi-Fi and Thread protocols is expanding most quickly, while Zigbee maintains a foundational presence for many installed systems.
Use Case:
Volume in smart home device adoption is driven by clearly defined use cases that offer tangible benefits to consumers. These applications address fundamental needs like safety, convenience, and resource management.
- Home Security:This critical application encompasses security cameras, smart locks, motion sensors, and alarm systems, providing comprehensive protection and remote monitoring capabilities. Consumer safety priorities drive significant investment in this category.
- Energy Management:Smart thermostats, smart plugs, and energy monitoring systems optimize power consumption, reduce utility bills, and support sustainable living practices. This use case gains traction in regions with high energy costs like Germany.
- Voice Control:Integration with voice assistants allows users to control various smart devices, play music, and access information using spoken commands. This application enhances convenience across the entire smart home ecosystem.
- Lighting Automation:Smart lighting systems enable scheduled lighting, remote control, and adaptive illumination based on occupancy or time of day. This use case enhances comfort and contributes to energy savings.
- Remote Monitoring:This application allows users to check on their homes, pets, or elderly relatives from anywhere using cameras, sensors, and mobile apps. It provides peace of mind for homeowners and property managers.
- Appliance Management:Smart appliances like refrigerators, ovens, and washing machines offer remote control, diagnostics, and optimized operation. This functionality streamlines household chores and enhances convenience.
Home Security and Energy Management represent critical functionalities for consumers. Lighting Automation is gaining significant traction for both comfort and efficiency.
End User:
Customer type significantly influences product design and service delivery within the smart home market. Each end-user group has distinct purchasing drivers and operational requirements.
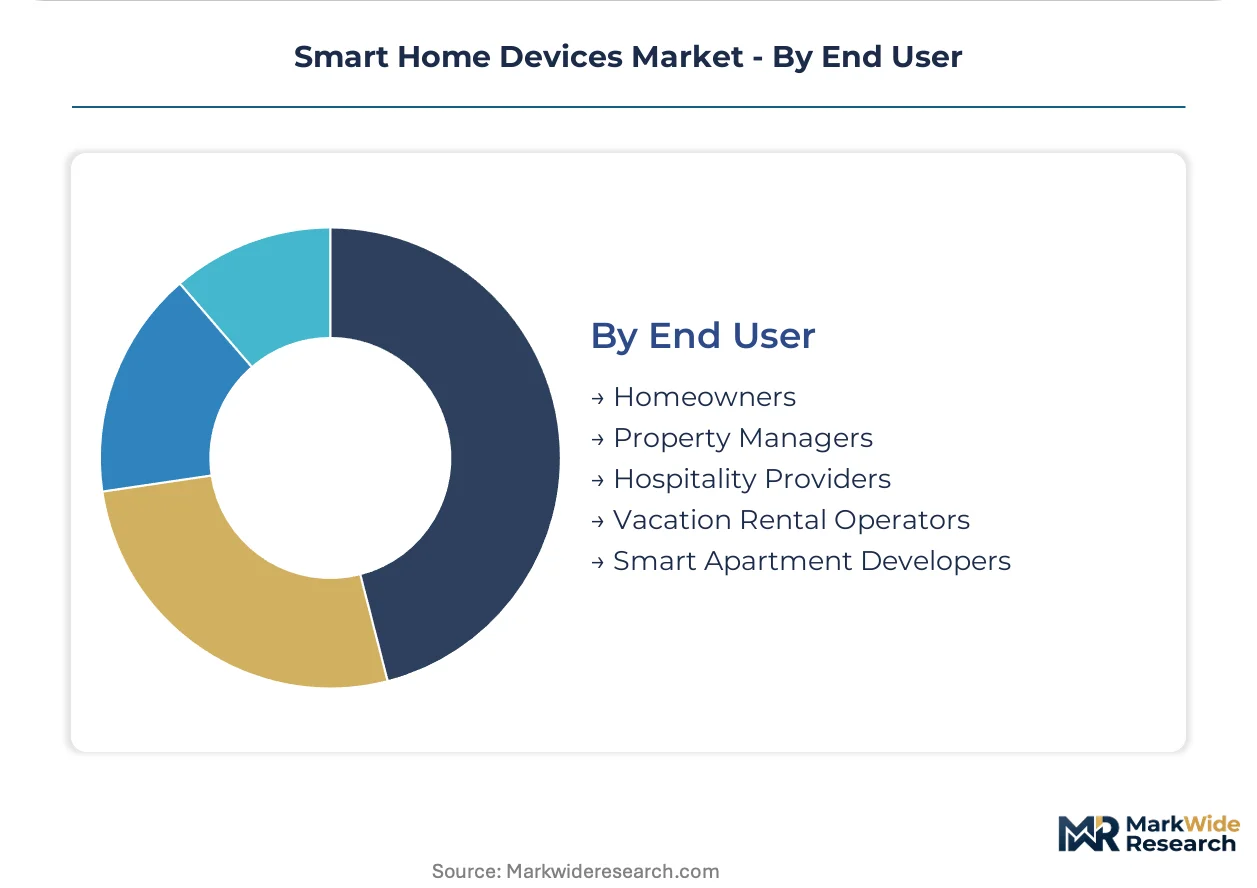
- Homeowners:The largest segment, individual homeowners seek convenience, security, and energy efficiency for their primary residences. This group drives demand for a broad range of consumer-grade devices.
- Hospitality Providers:Hotels and short-term rental operators deploy smart devices for enhanced guest experiences, operational efficiency, and personalized services. This segment values seamless integration and robust management platforms.
- Property Managers:These professionals manage residential and commercial properties, utilizing smart devices for access control, security, and maintenance efficiency across multiple units. Scalability and remote management features are essential.
- Vacation Rental Operators:Operators of vacation homes use smart locks, thermostats, and security systems for remote guest access, climate control, and property monitoring. Automation helps streamline check-ins and reduce operational costs.
- Smart Apartment Developers:Developers integrate smart home technology into new residential constructions, offering pre-installed solutions to attract tenants and differentiate properties. This segment prioritizes robust, future-proof infrastructure.
Homeowners constitute the largest user base. Specialized demands from Hospitality Providers are driving new product development and service models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supply-side concentration for smart home devices primarily sits with technology hubs that possess strong R&D capabilities and advanced manufacturing infrastructure. These regions drive innovation in AI integration, connectivity standards, and hardware development. High consumer disposable income also fuels early adoption and market expansion in these areas.
United States
Demand for smart home devices in the United States is driven by consumer safety priorities and a strong preference for convenience technologies. The US Federal Communications Commission (FCC) regulates radio frequency emissions, shaping market access for new devices. Silicon Valley and other tech clusters in California continue to innovate in AI-powered home automation systems.
Germany
High energy costs and a strong environmental consciousness drive demand for energy management solutions like smart thermostats in Germany. Europe's GDPR imposes strict data privacy requirements on device manufacturers operating within the country. Munich and Berlin are key centers for smart home technology development and adoption, particularly in new residential construction.
South Korea
South Korea exhibits significant demand for integrated smart home ecosystems, fueled by a digitally native population and high urban density. The country's national regulatory bodies enforce stringent safety and performance standards for consumer electronics. Seoul's advanced technology sector, including major electronics manufacturers, leads in developing next-generation smart appliances and platforms.
China
China represents a vast consumer market for smart home devices, with demand concentrating in its rapidly growing urban centers. Compliance with China's GB standards for product safety and quality is essential for market entry and scale. The Yangtze River Delta region, particularly cities like Shenzhen, serves as a global manufacturing and innovation hub for smart home hardware.
Japan
Japan's demand for smart home technology is influenced by an aging population, creating opportunities for ambient assisted living and remote monitoring solutions. The Ministry of Economy, Trade and Industry (METI) promotes smart energy initiatives that integrate with home automation. Tokyo and Osaka remain focal points for consumer electronics innovation and smart city development.
Smart Home Devices Market Key Industry Players
Concentration sits with large technology conglomerates and established consumer electronics manufacturers. The market structure is tiered, featuring a few dominant platform providers alongside numerous specialized device makers. Strategic partnerships and extensive ecosystem development represent dominant competitive moves among these players, aiming to broaden device compatibility and user reach.
Within the technology conglomerate tier, Amazon and Google (Nest) exemplify platform-centric strategies, leveraging their voice assistants to create central control points for vast partner networks. Samsung Electronics occupies a strong position by integrating its SmartThings platform with a broad consumer electronics portfolio. These companies compete on ecosystem breadth, AI capabilities, and seamless user experience across diverse product categories.
| Leading Market Players |
|---|
| Samsung Electronics |
| Honeywell International |
| Amazon |
| Johnson Controls |
| Siemens |
| Google (Nest) |
| LG Electronics |
| Schneider Electric |
| Apple |
| Others |
Cost & Logistics Intelligence
The substitution of proprietary connectivity modules with Matter-compatible Thread and Wi-Fi chipsets reshapes the supply geography for smart home devices, simultaneously influencing pricing economics towards broader accessibility. This shift from specialized vendors to larger semiconductor manufacturers drives down component costs for mass-market products.
Pricing Analysis
Europe's GDPR dictates the pricing tier structure for data-intensive smart home devices, particularly those with AI-driven analytics, due to compliance overheads. Pricing stratifies across premium, standard, and economy tiers, differentiating by AI integration levels and bundled after-sales support services. Pricing pressure stems from the high initial cost of many devices, hindering mass-market adoption. Homeowners seeking basic functionality demonstrate the highest price sensitivity, while hospitality providers prioritize integrated solutions over raw cost.
Supply Chain Analysis
Inventory levels for smart home components are subject to semiconductor lead times, impacting device manufacturing schedules. Geographic supply concentration sits primarily within China for hardware assembly and South Korea for advanced sensor and display technologies. Raw material dependencies include specialized semiconductors and low-power wireless modules. A structural risk exists in geopolitical tensions affecting semiconductor supply chains, creating potential for component shortages. Distribution runs through a hybrid model, combining direct-to-consumer sales with growing reliance on custom installers and telecommunication companies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The smart home device market requires specialized expertise in integrated platform development, creating a capability scarcity for seamless ecosystem orchestration.
For Market Incumbents: Consolidate ecosystem control by actively integrating Matter protocol support across all product lines, mitigating interoperability fragmentation. Invest heavily in AI integration R&D to enhance proactive automation and differentiate premium offerings. Acquire specialized software firms focusing on cybersecurity and data privacy solutions to strengthen platform integrity. Expand partnerships with professional installation networks to capture new residential construction opportunities.
For New Entrants and Emerging Players: Lead with niche solutions addressing specific unmet needs, such as ambient assisted living or advanced energy management convergence. Target underpenetrated high-income urban centers in regions like the Middle East with tailored offerings. Leverage managed service offerings through partnerships with utility companies or property developers as a go-to-market angle. Focus on developing devices with robust edge computing capabilities for enhanced privacy and local control.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with specialized device manufacturers focused on single-use cases or proprietary platforms. The market exhibits long-term viability, driven by increasing consumer demand for integrated ecosystems over the next decade. Target specialized cybersecurity firms or AI analytics providers with proven interoperability expertise for strategic acquisitions. Widespread Matter adoption across major manufacturers serves as a critical signal to watch for accelerated market consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Matter Protocol Development | Ensures cross-platform compatibility and simplifies consumer setup, expanding market reach. |
| Acquire AI-Driven Analytics Firms | Enhances proactive automation capabilities and differentiates product offerings in premium segments. |
| Expand Professional Installation Channels | Captures demand from new residential construction and managed service providers. |
| Develop Health and Wellness Integrations | Addresses an emerging market opportunity with high-value, specialized device applications. |
| Strengthen Cybersecurity Vulnerability Management | Builds consumer trust and ensures compliance with evolving data privacy regulations. |
Research Approach
Findings reconcile primary fieldwork against secondary review of regulatory filings, industry association reports, and academic research on IoT. This includes interviews with smart home device R&D directors, hospitality technology managers, property managers, and telecom service leads. Both bottom-up and top-down triangulation methods validate market sizing and growth projections.
The analytical framework models segmentation across device type, connectivity technology, use case, end-user, and geographic region. Compound annual growth rates were derived from historical trend analysis combined with future growth projections over the analysis window. Key industry-specific forecast inputs include Matter standard adoption rates and smart city infrastructure investments.
Underlying assumptions cover technological advancements, regulatory stability, and consumer spending patterns, with deviation risk concentrated in geopolitical events impacting supply chains. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Goods
Cat Mat Market
Consumer Goods
Heated Tobacco Products Market
Consumer Goods
Smart Ashtray Market
Consumer Goods
Athleisure Wear Market
Consumer Goods
Dog Shampoo Market
Consumer Goods
Baby Bedding Market
Consumer Goods
Nail Care Products Market
Consumer Goods
Europe E-Cigarettes Market
Consumer Goods
Skimboard Market
Consumer Goods
Baby Sleeping Bag Market
Consumer Goods
Europe Fashion Accessories Market
Consumer Goods
Candle Market
Consumer Goods
Laundry Detergent Sheets Market
Consumer Goods
Electric Mop Market
Consumer Goods
Middle East Fragrances Market
Consumer Goods
Personal Accessories Market