
 Baking Paper Market | 2026-2036
Baking Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Baking Paper Market Outlook
Subscription-based replenishment programs for food-service operators is pivoting how baking paper suppliers monetize volume relationships. Nordic Paper leverages its Nordic pulp integration to sustain cost-advantaged supply to European commercial bakeries. Reynolds Consumer Products anchors North American shelf presence through dominant retail channel control. Mondi Group differentiates via specialty silicone-coating capabilities that serve premium confectionery tiers.
Baking paper comprises cellulose-based substrates treated with silicone or quilon coatings to achieve non-stick, heat-resistant surfaces typically rated for sustained oven temperatures. Manufacturers apply aqueous or solvent-based silicone emulsions through on-machine coating lines to create release properties essential for automated bakery production lines. Parchment paper occupies the largest volume share across home and commercial applications due to its broad temperature tolerance and established food-contact safety profile. Silicone paper captures expanding share in high-throughput commercial baking where release consistency directly affects line speed and yield. Wax paper retains niche positioning in cold-applications and budget retail tiers where heat resistance requirements remain minimal.
The EU Green Deal and REACH frameworks restrict fluorochemical treatments while pushing compostability mandates that reshape coating chemistry R&D priorities. FDA food-contact substance notifications govern silicone and quilon formulations in the United States, creating divergent compliance pathways for multinational suppliers. BIS certification requirements in India add another layer of product testing for exporters targeting food-service growth in South Asia. Stakeholders must monitor how evolving per- and polyfluoroalkyl substance restrictions across multiple jurisdictions will force coating reformulation investments and potentially consolidate supplier bases unable to fund compliance transitions.
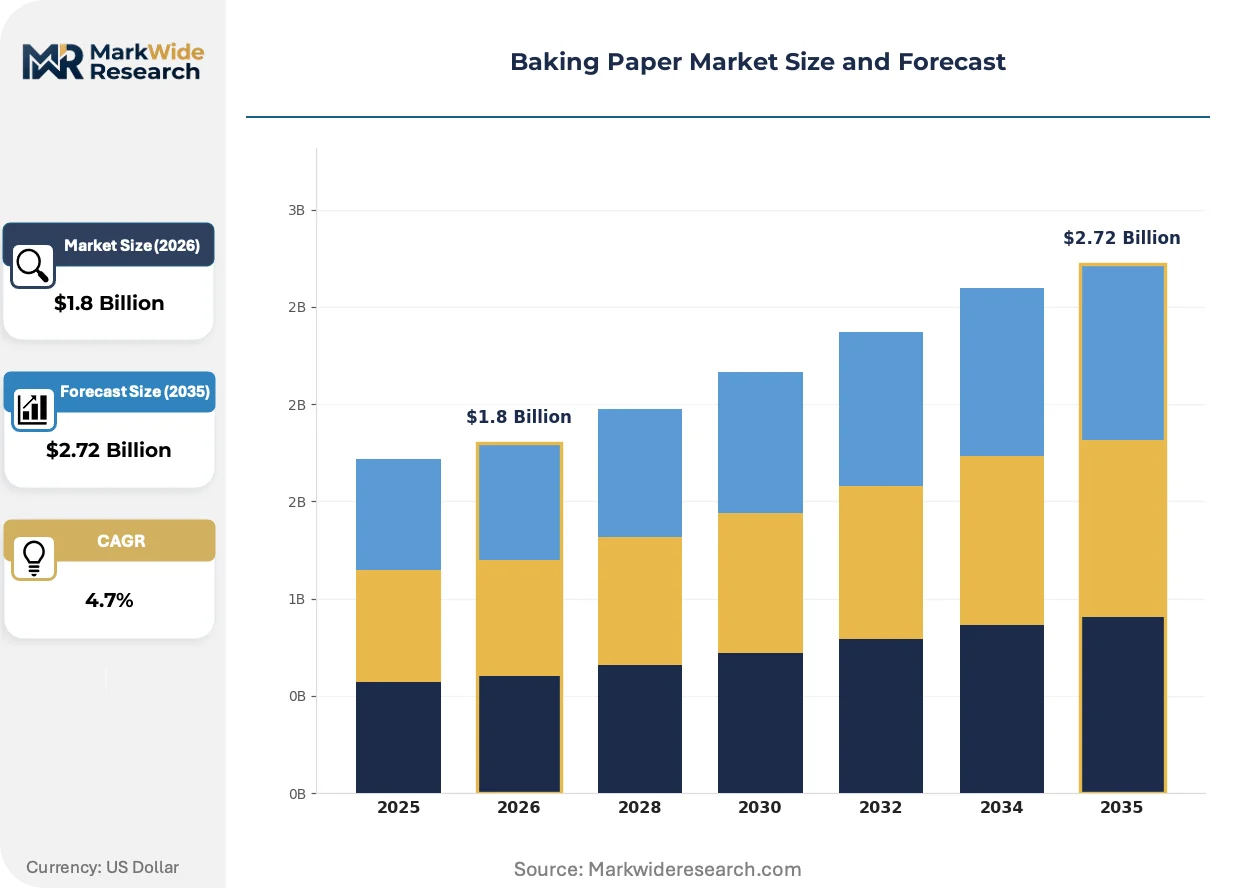
Market Dynamics
The EU Green Deal is forcing coating chemistry reformulation across European commercial bakeries as compostability mandates eliminate fluorochemical treatments and silicone-coated grades scale to meet packaging compliance deadlines.
Growth Catalysts
- REACH fluorochemical restrictions:ECHA phase-outs of per- and polyfluoroalkyl substances accelerate silicone coating R&D investment and create first-mover advantages for compliant suppliers serving German industrial baking corridors.
- Compostable parchment demand:Food-service distributors in France and Germany prioritize biodegradable alternatives, pulling volume toward cellulose substrates with aqueous silicone emulsions rated for commercial oven lines.
- Automated bakery production:High-throughput commercial facilities require release consistency that directly affects line speed, expanding silicone paper adoption over traditional parchment in continuous-process environments.
Market Restraints
- Pulp cost volatility:Nordic pulp integration provides cost advantages to integrated producers while non-integrated suppliers face margin compression from cellulose fiber price swings tied to Scandinavian supply.
- Coating equipment concentration:On-machine silicone coating lines require specialized capital investment concentrated among German and French equipment manufacturers, limiting new entrant capacity expansion.
- Wax paper substitution ceiling:Budget retail tiers retain wax paper for cold applications where heat resistance remains minimal, capping premium substrate penetration in price-sensitive consumer segments.
Strategic Opportunities
- Subscription replenishment models:Food-service operators are pivoting toward automated restocking programs that lock in volume commitments and reduce customer acquisition costs for baking paper suppliers.
- India BIS certification pathway:Exporters targeting South Asian food-service growth can capture first-entry advantages through compliance with Bureau of Indian Standards product testing requirements.
- Quilon-to-silicone conversion:FDA food-contact substance notifications for silicone formulations enable suppliers to displace legacy quilon coatings in US commercial baking applications with higher-temperature performance.
Industry Challenges
- Coating chemistry talent scarcity:Formulation chemists with expertise in aqueous silicone emulsions and compostable substrate compatibility command premium compensation, constraining R&D team scaling.
- Multi-jurisdiction compliance timelines:Suppliers must simultaneously navigate EU REACH phase-outs, FDA notification pathways, and India BIS testing, fragmenting certification resources across divergent technical standards.
- Legacy quilon line retrofit costs:Existing coating infrastructure requires capital-intensive modification to handle silicone emulsion viscosity and curing parameters, delaying compliance transitions for capital-constrained producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Baking Paper Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Parchment Paper, Silicone Paper, Wax Paper, Release Paper Material: Bleached Fiber, Unbleached Fiber, Silicone Coating, Plastic Film Application: Home Baking, Commercial Baking, Confectionery, Catering Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Nordic Paper, Ahlstrom-Munksjö, Reynolds Consumer Products, Delfortgroup AG, Georgia-Pacific, Mondi Group, Krpa Paper Company, Paterson Pacific Parchment Company, Expera Specialty Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Baking Paper Market Strategic Shifts
Coating chemistry evolution and procurement model transformation are restructuring how baking paper suppliers capture value, with regulatory compliance investments now determining competitive survival rather than optional differentiation.
Aqueous silicone emulsion coatings are overtaking solvent-based formulations in European commercial bakeries as ECHA restrictions eliminate fluorochemical alternatives. German industrial baking corridors adopt these water-based systems at accelerating pace to maintain EU Green Deal compliance. This technology shift is compressing the supplier base by favoring capital-rich producers capable of funding on-machine coating line conversions.
REACH per- and polyfluoroalkyl substance restrictions are eliminating legacy release treatments from food-contact applications across European Union member states. Industrial bakeries in France and Germany face 2025-2030 phase-out deadlines that force immediate coating reformulation investments. Premium confectionery tiers respond fastest, leveraging specialty silicone-coating capabilities to maintain release performance while meeting compostability mandates.
Food-service distributors are consolidating vendor relationships around subscription-based replenishment programs that guarantee volume commitments in exchange for preferential pricing. This procurement transformation disintermediates traditional spot-market purchasing and locks in multi-year supply agreements. The shift is most visible in Germany's industrial baking corridor, where large-scale operators prioritize supply security over transactional flexibility.
Baking Paper Market Segmentation
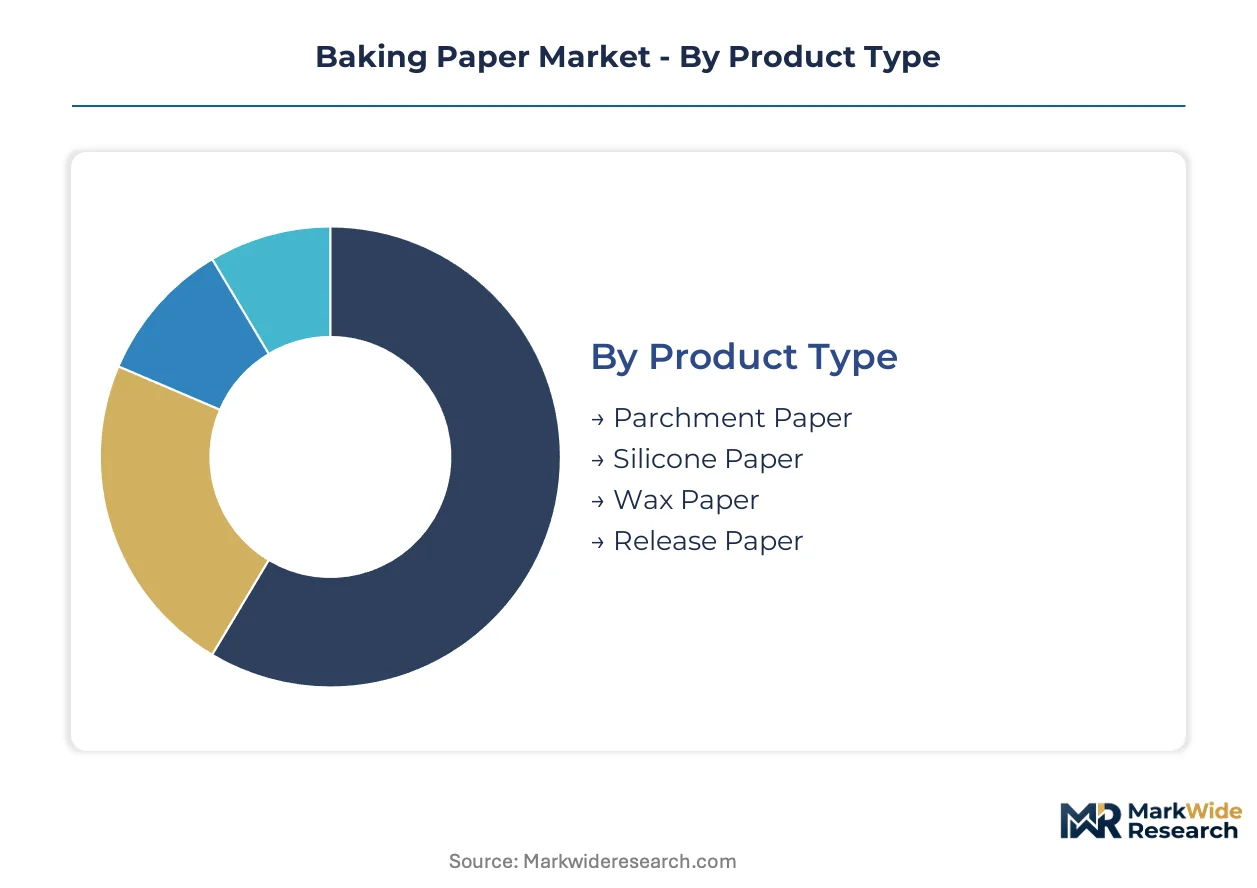
Segmentation in baking paper determines which coating chemistries and substrate grades command compliance premiums versus commodity positioning. Product type and material composition dictate regulatory pathways, while application and channel structures shape margin capture and replenishment economics.
Product Type:
Certification burden varies sharply across product types: parchment paper requires FDA food-contact substance notifications in the United States and EFSA compliance in Europe; silicone paper demands REACH registration for emulsion chemistries; wax paper faces fewer coating restrictions but limited temperature ratings; release paper carries dual compliance for food-contact and industrial adhesive applications.
- Parchment Paper:Cellulose substrates treated with sulfuric acid or silicone to create dense, grease-resistant barriers rated for sustained oven exposure. Demand concentrates in Germany's industrial baking corridor, where commercial facilities prioritize established food-contact safety profiles over experimental coatings. ECHA fluorochemical phase-outs reinforce parchment's position as the compliant default.
- Silicone Paper:Aqueous or solvent-based silicone emulsions applied through on-machine coating lines deliver superior release consistency for high-throughput production. French and German commercial bakeries scale silicone-coated grades fastest to meet EU Green Deal packaging deadlines and compostability mandates. REACH registration requirements favor capital-rich suppliers capable of funding formulation R&D.
- Wax Paper:Paraffin or vegetable wax coatings provide moisture barriers for cold applications with minimal heat resistance requirements.
- Release Paper:Specialized substrates designed for industrial adhesive and food-contact separation applications with dual compliance obligations.
Leading the category by volume: parchment paper. Growing fastest: silicone paper.
Material:
Material selection drives cost structure and sustainability positioning across supply tiers. Bleached fiber commands premium pricing in visual-sensitive applications; unbleached fiber captures compostability premiums; silicone coating determines release performance; plastic film offers moisture barriers outside traditional baking paper specifications.
- Bleached Fiber:Chlorine or oxygen-bleached cellulose delivers bright white appearance valued in retail consumer segments and premium confectionery presentation. Nordic pulp integration provides cost advantages to European producers sourcing Scandinavian fiber.
- Unbleached Fiber:Natural brown cellulose substrates align with compostability mandates and sustainability marketing in EU member states. German and French food-service distributors prioritize unbleached grades for Green Deal compliance.
- Silicone Coating:Aqueous emulsion systems displace solvent-based formulations under ECHA restrictions, requiring specialized on-machine coating infrastructure concentrated among German equipment manufacturers.
- Plastic Film:Polyester or polypropylene barriers serve non-oven applications where traditional cellulose substrates underperform on moisture resistance.
Highest volume share: bleached fiber. Steepest expansion trajectory: unbleached fiber.
Application:
Application segmentation separates replenishment-model economics from transactional retail purchasing. Home baking relies on shelf presence and brand recognition; commercial baking demands release consistency affecting line speed; confectionery requires premium coating performance; catering balances cost with presentation requirements.
- Home Baking:Consumer retail purchases driven by supermarket placement and established brand equity, with price sensitivity highest in budget tiers retaining wax paper alternatives.
- Commercial Baking:High-throughput industrial facilities in Germany's baking corridor prioritize silicone paper for automated production lines where release consistency directly affects yield and throughput metrics.
- Confectionery:Premium silicone-coating capabilities serve specialty tiers requiring precise release properties for delicate sugar work and chocolate handling.
- Catering:Food-service operators balancing presentation requirements against cost constraints, increasingly adopting subscription replenishment programs for volume security.
Dominant volume position: home baking. Gaining share fastest: commercial baking.
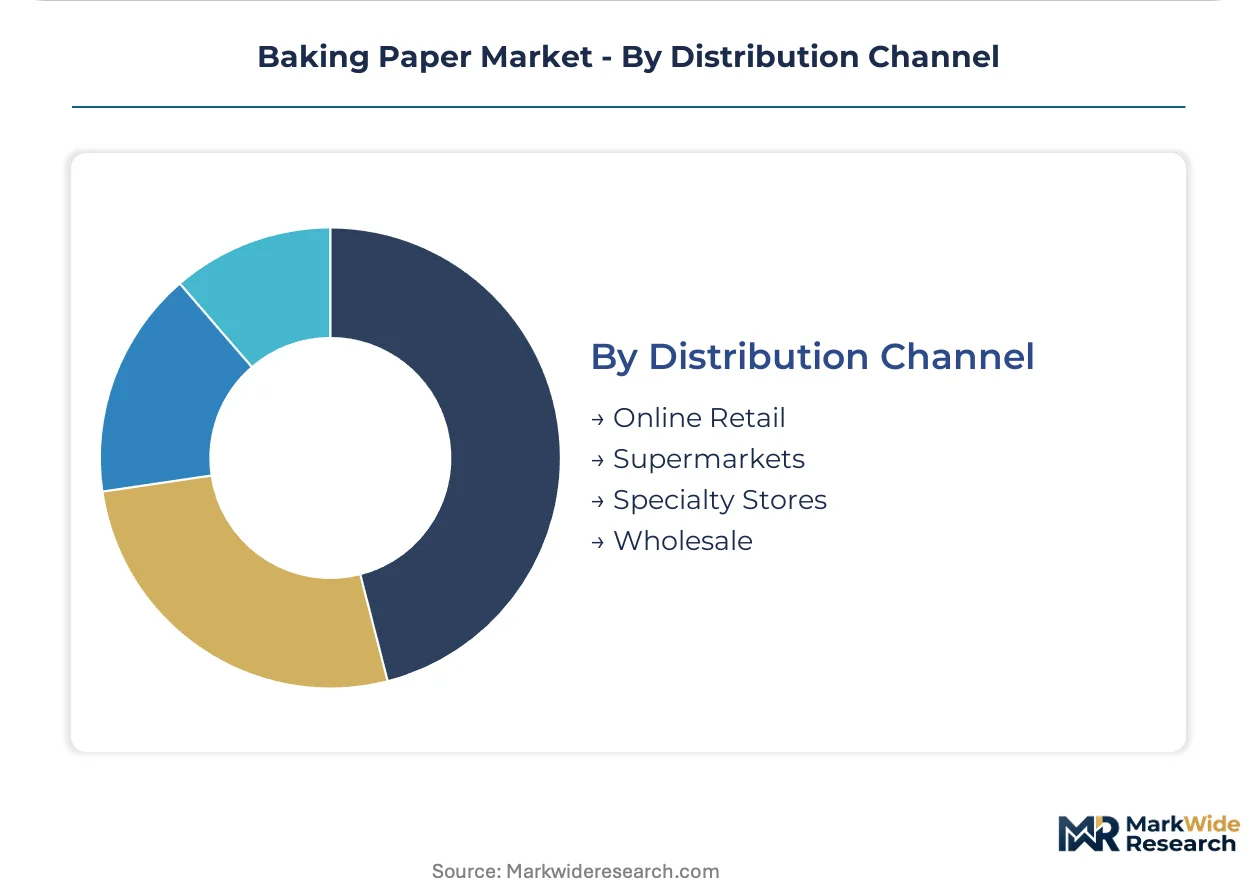
Distribution Channel:
Channel structure determines customer acquisition economics and pricing power. Online retail enables subscription model penetration; supermarkets anchor brand presence; specialty stores serve premium niches; wholesale captures institutional volume with thin margins.
- Online Retail:E-commerce platforms enable direct-to-operator subscription replenishment programs that lock in multi-year volume commitments and reduce customer acquisition costs.
- Supermarkets:Dominant retail shelf presence in North America and Europe drives consumer brand recognition, with Reynolds Consumer Products leveraging channel control for market position.
- Specialty Stores:Culinary supply and restaurant equipment retailers serve professional segments seeking technical specification guidance.
- Wholesale:Food-service distributors in France and Germany consolidate vendor relationships around guaranteed volume agreements with preferential pricing.
Largest transaction volume: supermarkets. Expanding most quickly: online retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity clusters in Scandinavian pulp-integrated facilities while consumption concentrates in German and French commercial baking corridors. This geographic split creates freight-logistics arbitrage opportunities for suppliers with multi-regional coating infrastructure.
Germany
Industrial bakeries along the Rhine-Ruhr corridor drive silicone paper demand for automated production lines. ECHA REACH phase-outs of per- and polyfluoroalkyl substances force coating reformulation investments by 2025. The Baden-Württemberg region hosts specialized equipment manufacturers supplying on-machine coating lines to domestic producers.
United States
Food-service distributors prioritize FDA-compliant silicone formulations for high-throughput commercial facilities. FDA food-contact substance notifications govern quilon-to-silicone conversion pathways. The Midwest industrial baking cluster around Chicago anchors North American volume consumption.
France
Premium confectionery tiers in Île-de-France demand specialty silicone-coating capabilities for delicate sugar work. EU Green Deal compostability mandates accelerate unbleached fiber adoption. The Auvergne-Rhône-Alpes region concentrates parchment production for export to Mediterranean markets.
India
Food-service growth in Maharashtra and Gujarat pulls imported baking paper volume. BIS certification requirements create compliance barriers for first-entry suppliers. The Delhi-NCR corridor emerges as a distribution hub for South Asian commercial bakery expansion.
Sweden
Nordic pulp integration sustains cost-advantaged supply to European commercial bakeries. EFSA food-contact compliance underpins export competitiveness to EU member states. The Värmland region hosts integrated pulp-to-paper facilities serving German industrial corridors.
Baking Paper Market Competitive Environment
Capital-heavy producers compete with asset-light designers across coating chemistry and substrate sourcing. The market structures around three tiers: integrated pulp-to-paper operators with Nordic fiber access, specialized coating houses with German equipment partnerships, and regional converters serving price-sensitive retail tiers. Dominant competitive moves include backward integration into pulp supply and strategic partnerships with food-service distributors for subscription replenishment lock-in.
Among Nordic-integrated producers, Nordic Paper exemplifies pulp-advantaged supply architecture. Reynolds Consumer Products anchors North American retail channel control. Mondi Group occupies a position within specialty silicone-coating tiers serving premium confectionery applications.
| Leading Market Players |
|---|
| Nordic Paper |
| Ahlstrom-Munksjö |
| Reynolds Consumer Products |
| Delfortgroup AG |
| Georgia-Pacific |
| Mondi Group |
| Krpa Paper Company |
| Paterson Pacific Parchment Company |
| Expera Specialty Solutions |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal compostability mandates gate qualified supply and premium-tier pricing access, forcing coating chemistry investments that separate compliant producers from stranded capacity. Buyers in Germany's industrial baking corridor now pay certification premiums for REACH-registered silicone formulations while non-integrated suppliers absorb pulp cost volatility.
Pricing Analysis
Margin tightening in standard parchment tiers reflects Nordic pulp integration advantages held by Scandinavian producers. Three-tier pricing structure across premium silicone-coated, standard parchment, and economy wax paper levels stratifies by certification grade and volume scale. Cost-down pressure on unbleached fiber grades accelerates because French and German food-service distributors mandate compostable substrates. Budget retail segments show highest price sensitivity, while automated commercial bakeries prioritize release consistency over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from German industrial bakeries mandate multi-supplier qualification for silicone coating chemistries. Supply concentrates in Sweden, Germany, and France, drawing from Nordic pulp, specialized coating equipment, and confectionery demand clusters. Raw material dependencies rest on Scandinavian cellulose fiber, aqueous silicone emulsions, and quilon alternatives. Single-source vulnerability looms in on-machine coating line equipment concentrated among Baden-Württemberg manufacturers. Distribution runs through food-service wholesalers consolidating around subscription replenishment programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU REACH fluorochemical phase-outs force coating reformulation investments that will consolidate the supplier base, eliminating capital-constrained players unable to fund compliance transitions.
For Market Incumbents: Extend Nordic pulp integration advantages by locking long-term supply agreements with German commercial bakeries before REACH deadlines strand competitors. Capture subscription replenishment volume commitments from food-service distributors to defend against emerging asset-light coating houses. Prioritize aqueous silicone emulsion R&D to maintain release performance leadership as ECHA restrictions eliminate legacy alternatives. For New Entrants and Emerging Players: Aqueous silicone coating technology adapted for Indian BIS certification requirements offers entry into South Asian food-service expansion. Target Maharashtra and Gujarat commercial bakery clusters where imported substrate demand outpaces domestic supply. Pursue white-label partnerships with European distributors seeking dual-sourcing alternatives to Nordic-integrated incumbents. For Investors and Strategic Acquirers: First-mover silicone coating line conversions among mid-tier producers is the leading indicator that consolidation value will accrue to compliant capacity. Five-to-ten year viability favors integrated pulp-to-paper operators with captive Nordic fiber supply. Monitor ECHA enforcement intensity as the signal for accelerated M&A windows.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulp Supply | Nordic fiber access insulates margin compression from Scandinavian cellulose price swings. |
| REACH-Compliant Coating Conversion | Aqueous silicone emulsion R&D secures German industrial bakery volume through compliance deadlines. |
| Subscription Replenishment Partnerships | Multi-year food-service agreements reduce customer acquisition costs and lock out spot-market competitors. |
| India BIS Certification Pathway | First-entry compliance captures South Asian commercial bakery growth before domestic capacity scales. |
| Quilon-to-Silicone Line Retrofit | Equipment modification enables FDA-compliant supply to US Midwest industrial baking clusters. |
Study Parameters
Document review covered ECHA regulatory filings, FDA food-contact substance notifications, and Nordic pulp trade data, complemented by interviews with coating chemistry formulators, German food-service procurement directors, and French confectionery production managers. Primary fieldwork triangulated against secondary validation from customs records, SEC filings of listed paper producers, and EU packaging compliance databases. Bottom-up volume estimates from application-level consumption patterns cross-referenced top-down market sizing derived from pulp production statistics.
Historical volume trajectories were cross-referenced against panel input from equipment manufacturers and distributor category managers. The analytical framework modeled product type, material composition, application segment, and distribution channel dimensions across the projection horizon. CAGRs were derived from regression analysis of coating chemistry adoption curves and regulatory phase-out timelines. Industry-specific forecast inputs included ECHA enforcement schedules and German industrial bakery automation rates.
Several conditions sit outside the modeled scope, including abrupt pulp supply disruptions from Scandinavian labor actions or accelerated EU per- and polyfluoroalkyl substance bans beyond current ECHA timelines. Forecasts reflect assumptions about coating line conversion capex availability and food-service distributor consolidation patterns. Deviation in REACH enforcement intensity or Nordic pulp pricing volatility would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Rugged Tablet Market
Others
Japan Smart Home Market
Others
Metal Air Battery Market
Others
Badminton Apparel Market
Others
Smart Home Service Market
Others
South Korea Automotive LED Lighting Market
Others
Germany 3D Printing Construction Market
Others
5G Devices Market
Others
Evidence Management Market
Others
Level Measuring Instrument Market
Others
PC As a Service Market
Others
Asia-Pacific Programmatic Display Advertising Market
Others
Dry-Cleaning and Laundry Services Market
Others
Performance Testing Tools Market
Others
North America Smart Homes Market
Others
Global Flexible PVC Films Market