
 Tripod Market | 2026-2036
Tripod Market Size, Share, and Industry Trends Forecast 2026-2036
Tripod Market Analysis
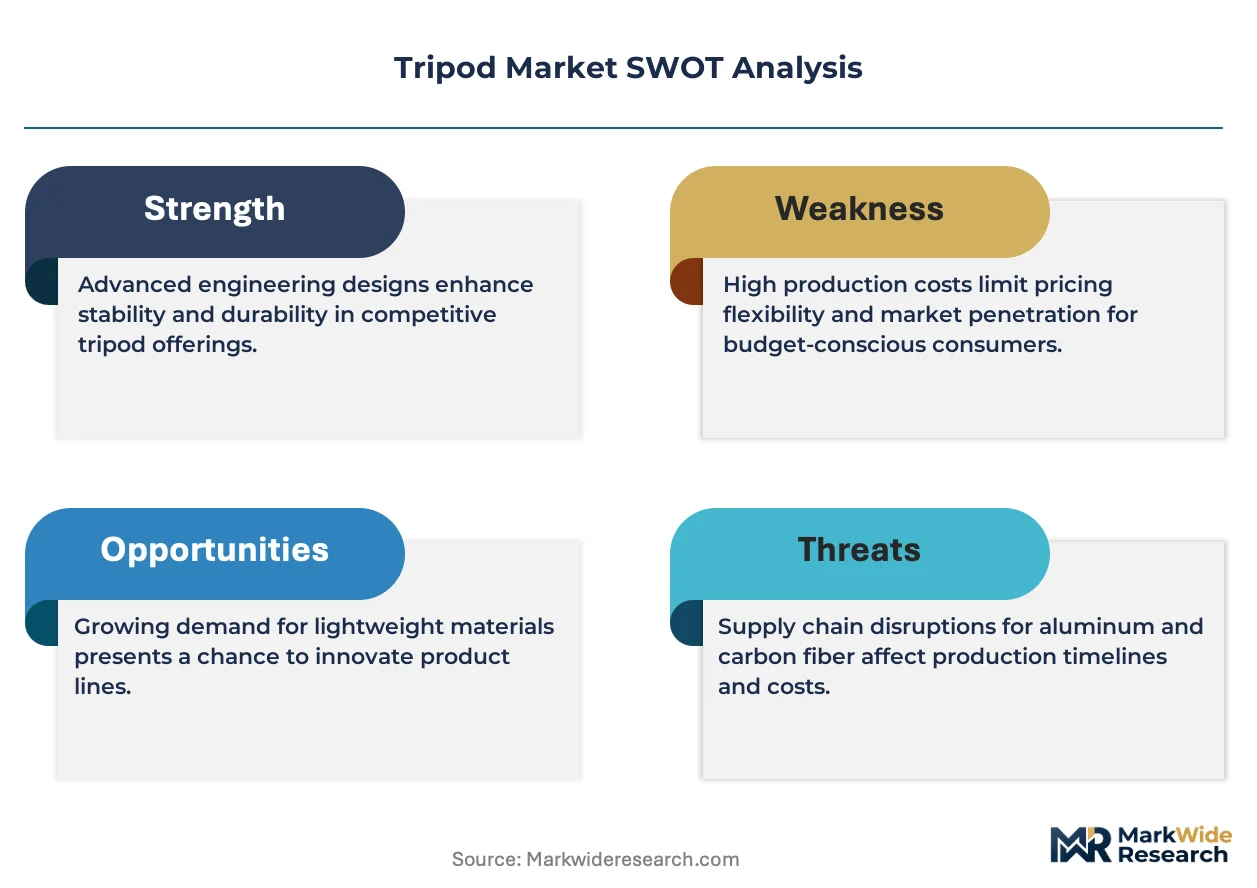
Chinese carbon fiber processing capacity is shifting toward higher-grade filament supply for precision imaging equipment. Gitzo leverages its Italian design heritage and proprietary carbon fiber weaving techniques to command premium positioning in professional photography circles. Manfrotto sustains broad retail penetration through its dual-track distribution across consumer electronics chains and specialized dealer networks. Really Right Stuff anchors the ultra-premium segment with American-made precision-machined aluminum components and modular arca-swiss compatible systems.
A tripod constitutes a three-legged support structure engineered to stabilize cameras, optical instruments, or measurement devices through adjustable leg angles, telescoping column mechanisms, and load-bearing head assemblies typically rated between two and twenty kilograms. Carbon fiber variants dominate professional workflows where vibration dampening and weight reduction prove critical, while aluminum constructions retain cost-sensitive amateur markets. Camera tripods occupy the largest revenue pool due to hybrid photo-video sensor convergence, yet video tripods with fluid drag heads capture the fastest expansion as streaming production standards professionalize. Material segmentation reveals carbon fiber commanding margin concentration despite aluminum sustaining volume leadership across emerging markets.
FCC equipment authorization rules govern wireless-enabled smart tripods in the United States, while EU REACH compliance constrains chemical treatments applied to carbon fiber resins and anodized aluminum finishes. Japan's METI energy-efficiency guidelines indirectly shape motorized tripod head development through standby power regulations. Stakeholders must monitor how California's Proposition 65 disclosure requirements and emerging EU digital product passport mandates will alter material traceability obligations and supplier certification costs.
Market Dynamics
Carbon fiber supply consolidation among aerospace-grade filament producers is compressing margin structures for precision imaging equipment manufacturers while simultaneously enabling weight-performance breakthroughs in professional-grade stabilization hardware.
Growth Catalysts
- Content creator platform economics:YouTube and TikTok monetization frameworks have professionalized independent production workflows, generating sustained equipment refresh cycles among solo operators and micro-studios.
- EU Green Deal material traceability:REACH compliance documentation requirements are accelerating substitution toward recycled carbon fiber composites in mid-tier product lines.
- MIIT industrial clustering policy:China's Ministry of Industry and Information Technology incentives for Shenzhen's imaging equipment corridor are reinforcing export manufacturing scale advantages.
Market Restraints
- Carbon fiber precursor cost volatility:Acrylonitrile feedstock price swings tied to petrochemical cycles directly compress gross margins on professional-grade tripod systems.
- Japanese Toray supply concentration:Three manufacturers control over eighty percent of aerospace-qualified filament output, creating single-source vulnerability for premium product tiers.
- Aluminum substitution ceiling:Vibration transmission limitations in aluminum leg assemblies prevent material downgrading beyond enthusiast-grade price points without performance degradation.
Strategic Opportunities
- India PLI scheme leverage:Production-linked incentive frameworks for electronics manufacturing are attracting assembly investment for export-oriented imaging accessory production.
- Smart tripod sensor convergence:Integration of accelerometer-based auto-leveling with smartphone app control is opening new price-performance positioning between manual and motorized systems.
- FCC Part 15 unlicensed spectrum:Wireless-enabled remote head positioning is creating service-revenue attachment opportunities through firmware subscription models.
Industry Challenges
- Carbon fiber layup technician scarcity:Precision filament winding and bladder molding expertise concentrates in Italian and Japanese supplier workforces, constraining geographic expansion of in-house manufacturing.
- Dual certification timeline compression:Simultaneous FCC authorization and EU CE marking processes for motorized smart tripods extend product launch windows by eight to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tripod Market |
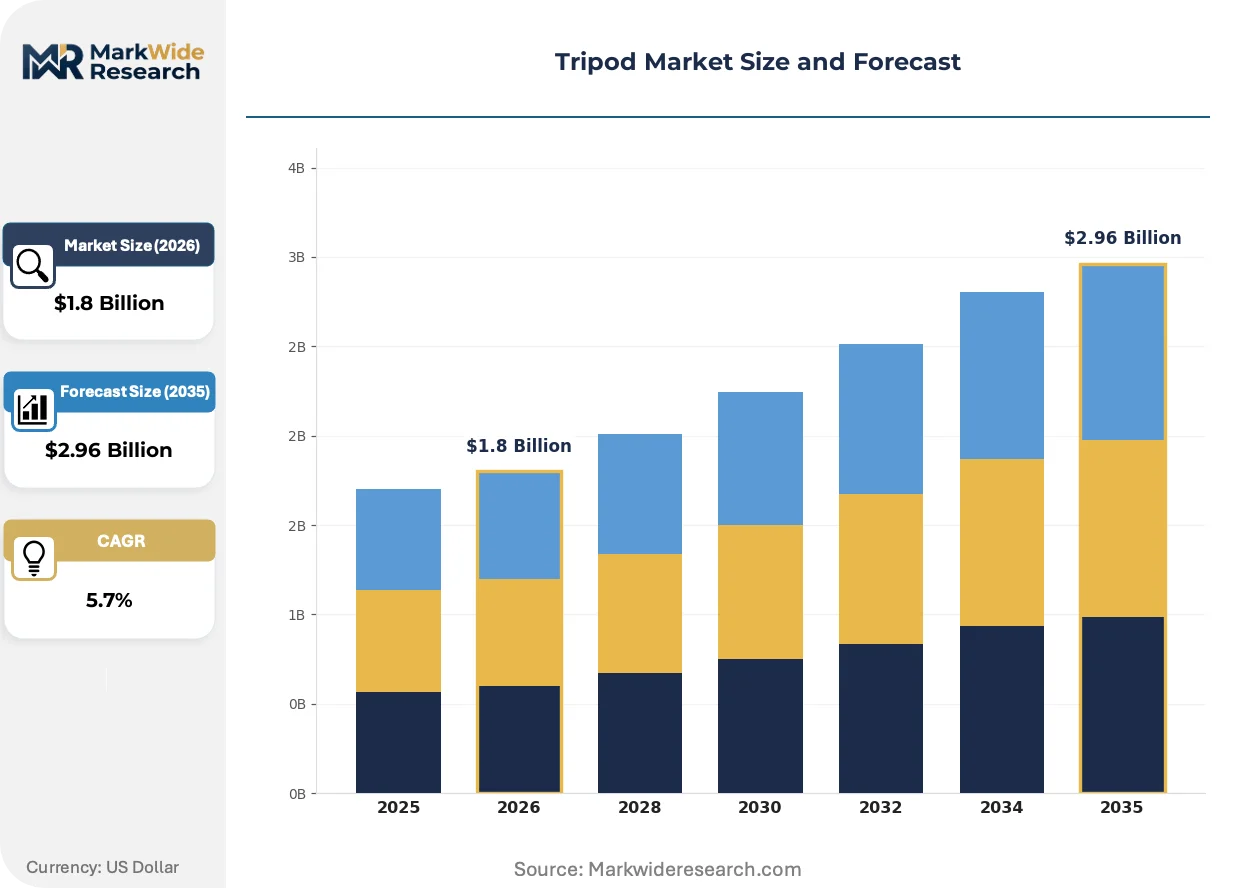
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Camera Tripods, Video Tripods, Mini Tripods, Professional Tripods Material: Aluminum, Carbon Fiber, Plastic, Steel End User: Photographers, Videographers, Content Creators, Amateur Users Feature: Lightweight, Adjustable Height, Quick Release, Stability |
| Companies Covered | Gitzo, SIRUI, Manfrotto, Really Right Stuff, K&F Concept, Peak Design, 3 Legged Thing, SLIK, Vanguard, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tripod Market Emerging Trajectories
Computational stabilization algorithms from smartphone ecosystems are pressuring dedicated hardware manufacturers to differentiate through load-bearing capacity and modular accessory ecosystems rather than basic vibration reduction.
Carbon fiber braided tube construction is converging with aerospace-derived automated fiber placement techniques to produce leg assemblies with asymmetric stiffness profiles. Wedding cinematographers and wildlife documentarians are adopting these systems fastest, prioritizing transportability against extended payload ratings. This convergence is compressing the performance gap between collapsible travel tripods and traditional studio pedestal systems.
California's Proposition 65 disclosure mandates are forcing reformulation of anodized aluminum surface treatments across supply chains serving North American distribution. Manufacturers must now document bisphenol-A and chromium VI compound content in etched finishes, adding certification overhead but creating compliance-based segmentation between disclosed and non-disclosed product lines. Video-focused SKUs with extended leg locks face the heaviest documentation burden.
Direct-to-creator sales through platform-integrated storefronts is displacing traditional dealer showroom evaluation for sub-five-hundred-dollar price tiers. Solo operators now purchase based on peer-review density and unboxing content rather than hands-on load testing, compressing brand loyalty cycles and elevating Shenzhen-based challengers with aggressive content marketing budgets. This pattern concentrates most visibly among TikTok-native creators in Southeast Asian metropolitan markets.
Tripod Market Segmentation
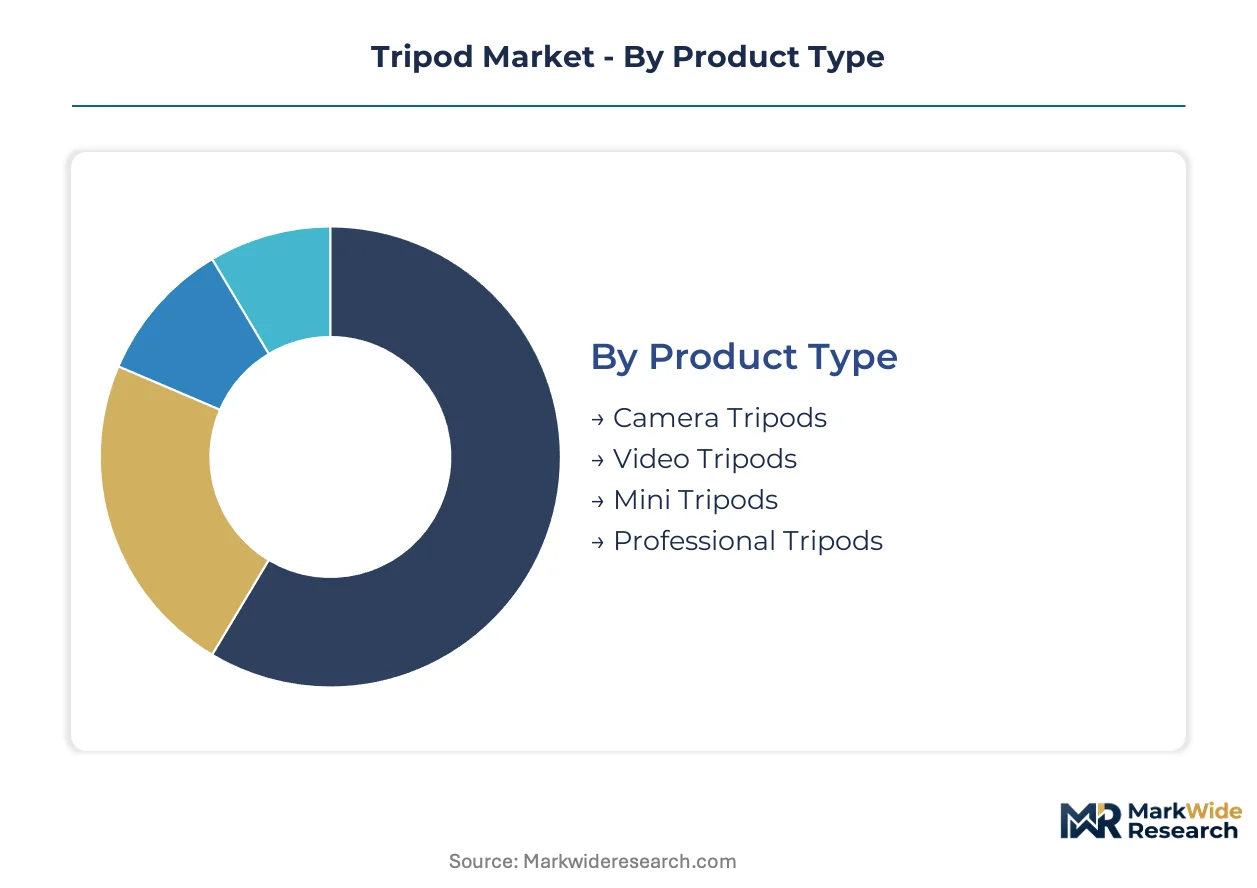
Tripod purchasing decisions cluster around payload requirements, transport constraints, and certification burdens that vary sharply across professional and consumer tiers. Material composition and end-use application determine which regulatory frameworks apply, creating divergent cost structures for manufacturers serving multiple segments.
Product Type:
FCC Part 15 authorization governs wireless-enabled smart tripods in the US market, while EU CE marking requirements extend to motorized video systems with electromagnetic compatibility testing. Professional-grade systems face the heaviest dual-certification timelines.
- Camera Tripods:Hybrid photo-video sensor convergence has expanded payload ratings on traditional three-leg systems to accommodate mirrorless bodies with battery grips and telephoto configurations. Demand concentrates among wedding photographers and real estate visualizers in Shenzhen's domestic market, where rapid equipment refresh cycles follow camera body release schedules.
- Video Tripods:Fluid drag heads with counterbalance systems dominate streaming production workflows, requiring precision machining that concentrates manufacturing among Italian and Japanese suppliers. Wedding cinematographers and documentary crews in China's tier-one cities adopt these systems fastest as platform monetization professionalizes independent production.
- Mini Tripods:Tabletop and grip-style supports target smartphone content creation with simplified mechanical designs avoiding motorized components and their associated regulatory burdens.
- Professional Tripods:Studio pedestal and heavy-duty cine systems carry the steepest certification overhead due to integrated electronics and extended load ratings.
Leading the category by volume: Camera Tripods. Growing fastest: Video Tripods.
Material:
Cost tier stratification separates aerospace-grade filament systems from commodity metal sourcing, with REACH compliance documentation requirements adding overhead to carbon fiber supply chains serving European distribution.
- Carbon Fiber:Braided tube construction with asymmetric stiffness profiles enables vibration dampening critical for long-exposure astrophotography and telephoto wildlife work. Aerospace-derived automated fiber placement techniques concentrate production among Toray-supplied manufacturers in Italy and Japan, where layup technician scarcity constrains capacity expansion.
- Aluminum:Anodized finishes face California Proposition 65 disclosure mandates for bisphenol-A and chromium VI content, forcing reformulation across supply chains serving North American markets. Cost-sensitive amateur demand in India's emerging creator economy sustains volume leadership despite vibration transmission limitations.
- Plastic:Injection-molded polymer legs target entry-level smartphone users with minimal regulatory exposure and compressed manufacturing cycles.
- Steel:Cast and welded constructions retain niche positioning in studio environments where absolute rigidity outweighs transport weight considerations.
Volume leadership: Aluminum. Margin concentration: Carbon Fiber.
End User:
Customer type determines distribution channel selection and service-revenue attachment potential, with platform-native creators bypassing traditional dealer evaluation entirely.
- Content Creators:YouTube and TikTok monetization frameworks have professionalized independent production workflows among solo operators and micro-studios. Direct-to-creator sales through platform-integrated storefronts now dominate sub-five-hundred-dollar purchases in Southeast Asian metropolitan markets, where peer-review density and unboxing content replace hands-on load testing.
- Videographers:Streaming production standards drive fluid head adoption and extended leg lock configurations with the heaviest documentation burdens under California disclosure mandates.
- Photographers:Hybrid stills-motion workflows prioritize collapsible travel designs with modular arca-swiss compatibility.
- Amateur Users:Price-sensitive first-time buyers concentrate in China's domestic e-commerce channels and India's electronics retail corridors.
Fastest-expanding segment: Content Creators. Largest installed base: Amateur Users.
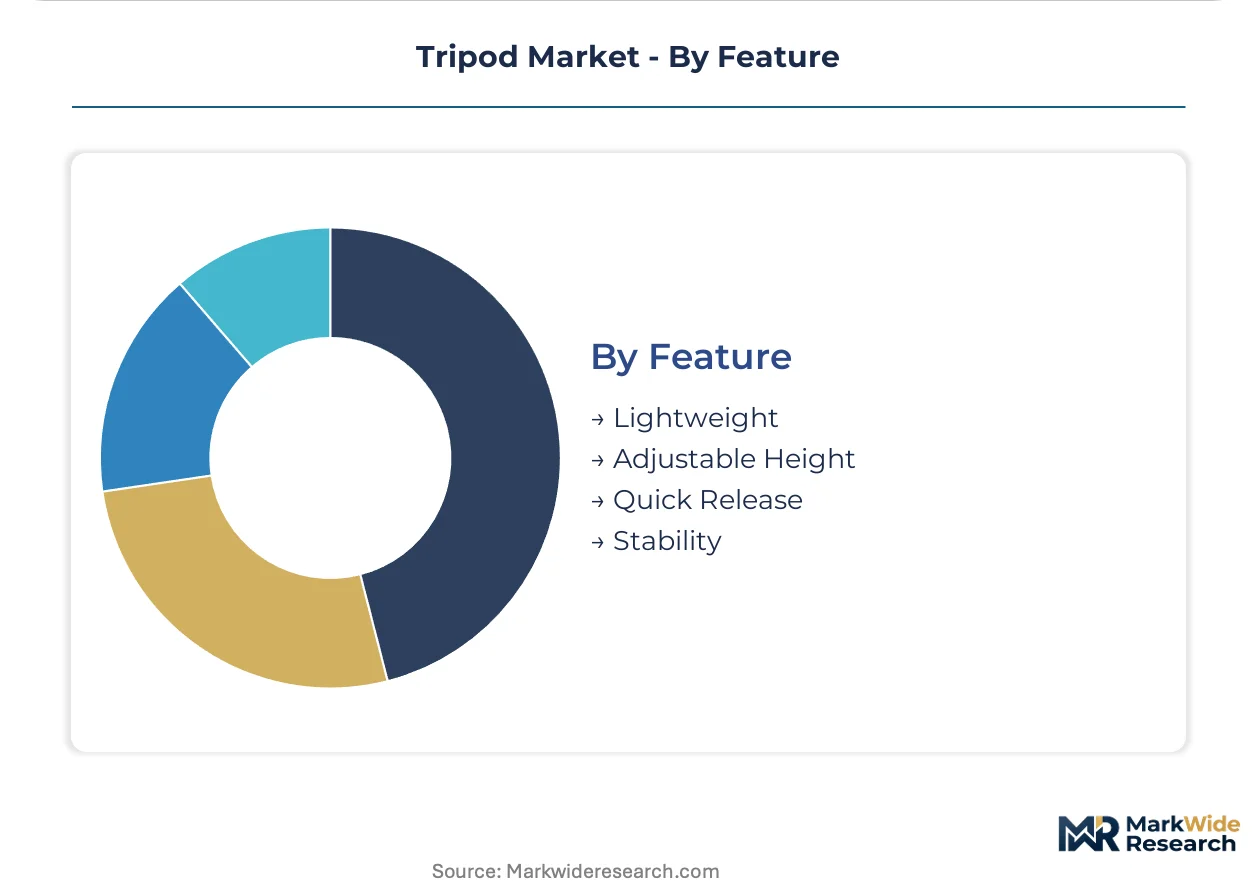
Feature:
Technology maturity separates commoditized mechanical functions from sensor-integrated smart systems with firmware subscription revenue potential.
- Quick Release:Arca-swiss compatible clamp systems with dovetail standards have become table stakes for professional workflows, with Really Right Stuff and Gitzo proprietary designs commanding loyalty among precision-oriented users.
- Lightweight:Carbon fiber dominance in professional tiers and aluminum retention in consumer markets define the weight-performance tradeoff landscape.
- Adjustable Height:Telescoping column mechanisms with twist-lock or flip-lock designs span all price tiers without differential regulatory exposure.
- Stability:Accelerometer-based auto-leveling with smartphone app control opens new price-performance positioning between manual and motorized systems, requiring FCC authorization for wireless-enabled variants.
Widest adoption: Adjustable Height. Steepest technology trajectory: Stability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Acrylonitrile feedstock from Texas Gulf Coast petrochemical complexes supplies precursor material for aerospace-grade carbon fiber filaments used in precision imaging equipment worldwide.
United States
Content creator platform economics drives equipment refresh cycles among YouTube and TikTok monetizers. FCC Part 15 authorization governs wireless-enabled smart tripod systems with accelerometer-based auto-leveling. California's Proposition 65 disclosure mandates force bisphenol-A documentation across anodized aluminum finishes serving North American distribution.
China
Shenzhen's imaging equipment cluster feeds domestic consumption and export manufacturing for hybrid photo-video workflows. MIIT industrial clustering policy reinforces export scale advantages through production incentives. Pearl River Delta assembly operations concentrate carbon fiber layup capacity for mid-tier professional systems.
Japan
Toray supply concentration creates single-source vulnerability for aerospace-qualified filament output serving premium product tiers. METI energy-efficiency guidelines shape motorized tripod head development through standby power regulations. Chubu region maintains precision machining expertise for fluid drag head manufacturing.
Germany
EU REACH compliance constrains chemical treatments applied to carbon fiber resins and anodized aluminum finishes serving European distribution. EU Green Deal material traceability accelerates substitution toward recycled carbon fiber composites. Baden-Württemberg precision engineering heritage supports professional-grade stabilization hardware development.
India
PLI scheme frameworks for electronics manufacturing attract assembly investment for export-oriented imaging accessory production. Cost-sensitive amateur demand sustains aluminum volume leadership despite vibration transmission limitations. Maharashtra and Karnataka electronics corridors concentrate domestic distribution for emerging creator economy buyers.
Tripod Market Vendor Landscape
Global majors compete with regional champions across certification sophistication and material sourcing tiers. The vendor base stratifies between aerospace-grade carbon fiber specialists and aluminum-focused volume manufacturers serving price-sensitive segments. Three archetypes dominate: Italian-Japanese precision houses with proprietary layup techniques, American precision-machining boutiques serving ultra-premium niches, and Shenzhen-scale assemblers leveraging platform-direct distribution. Competitive moves concentrate on dual-certification timeline compression and smart tripod firmware subscription models.
Within the heritage precision tier, Gitzo exemplifies Italian design lineage married to proprietary carbon fiber weaving techniques. Manfrotto occupies broad retail penetration positioning across consumer electronics chains and specialized dealer networks. Really Right Stuff anchors American-made precision-machined positioning with modular arca-swiss compatible systems. These three represent divergent strategic bets on geographic manufacturing concentration, distribution architecture, and price-performance segmentation.
| Leading Market Players |
|---|
| Gitzo |
| SIRUI |
| Manfrotto |
| Really Right Stuff |
| K&F Concept |
| Peak Design |
| 3 Legged Thing |
| SLIK |
| Vanguard |
| Others |
Supply Flow & Price Mechanics
Aerospace-grade carbon fiber certification tiers split the tripod market into divergent pricing architectures and supply chain configurations. Premium Italian and Japanese manufacturers command margin concentration through proprietary layup techniques and Toray filament supply, while Shenzhen-scale assemblers compete on aluminum volume with compressed documentation overhead and platform-direct distribution.
Pricing Analysis
Warranty and service bundling separates professional-grade positioning from consumer tiers, with Gitzo and Really Right Stuff including lifetime repair commitments against entry-level competitors offering minimal coverage. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation—FCC Part 15 authorization and EU CE marking add cost layers that amateur-focused SKUs avoid. Pricing pressure stems from acrylonitrile feedstock volatility compressing carbon fiber margins. Amateur users in India and Southeast Asia exhibit highest price sensitivity, while wedding cinematographers and wildlife documentarians prioritize payload ratings over cost.
Supply Chain Analysis
Single-source vulnerability sits with Japanese Toray for aerospace-qualified carbon fiber filament, where three manufacturers control over eighty percent of qualified output. Manufacturing concentrates in China for aluminum assembly and final integration, Italy and Japan for precision carbon fiber layup, and the United States for precision-machined aluminum components. Raw material dependencies include acrylonitrile precursors from Texas Gulf Coast petrochemical complexes, anodized aluminum surface treatments, and REACH-compliant resin formulations. Tariff exposure on Chinese-manufactured electronics threatens margin structures for brands with Pearl River Delta assembly. Distribution runs through platform-integrated storefronts for sub-five-hundred-dollar tiers and specialized dealer networks for professional systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The tripod market occupies a technology-transition phase where computational stabilization from smartphone ecosystems displaces basic vibration-reduction hardware. Smart tripod sensor convergence with accelerometer-based auto-leveling and firmware subscription models now separates growth trajectories from legacy mechanical competitors.
For Market Incumbents: Lock in carbon fiber supply agreements with Toray and Italian layup specialists before capacity constraints widen. Invest in dual-certification timeline compression—simultaneous FCC authorization and EU CE marking processes currently extend launch windows by eight to fourteen months. Defend against Shenzhen challengers by deepening proprietary quick-release ecosystems and platform-direct content marketing budgets.
For New Entrants and Emerging Players: Platform-native creators represent the most penetrable segment, particularly TikTok monetizers in Southeast Asian metropolitan markets. Target India's PLI scheme corridors for export-oriented assembly investment. White-space exists in smart tripod firmware subscription models between manual and motorized price-performance tiers. Go-to-market leverage rests on unboxing content density and peer-review cultivation rather than traditional dealer showroom presence.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by imaging equipment conglomerates seeking carbon fiber layup expertise and FCC-authorized smart system platforms. Long-term viability favors manufacturers with backward integration into aerospace-grade filament sourcing or proprietary modular accessory ecosystems. Watch for inflection where California Proposition 65 disclosure mandates and EU digital product passport requirements trigger consolidation among mid-tier players unable to absorb certification overhead.
| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Certification Timeline Compression | Simultaneous FCC and CE processes shorten launch windows for motorized smart tripods. |
| Carbon Fiber Supply Agreement | Toray filament contracts secure aerospace-grade material access against single-source vulnerability. |
| Platform-Direct Storefront Launch | TikTok and YouTube integrated sales bypass traditional dealer networks for creator segments. |
| Firmware Subscription Model | Accelerometer-based auto-leveling with smartphone control generates recurring service revenue. |
| REACH-Compliant Resin Reformulation | EU Green Deal material traceability accelerates recycled carbon fiber composite substitution. |
Methodological Framework
Trade customs databases, SEC filings from imaging equipment manufacturers, and EU REACH compliance registries formed the secondary backbone of this analysis. Primary fieldwork incorporated interviews with carbon fiber layup technicians, procurement leads at aerospace filament suppliers, platform content creators, and specialized tripod dealers across Shenzhen, Tokyo, and Milan. Bottom-up demand modeling from equipment refresh cycles among YouTube and TikTok monetizers was triangulated against top-down market sizing from import-export data.
Historical trendline analysis of carbon fiber precursor pricing and platform monetization growth rates established baseline assumptions across the analysis window. Segmentation modeling incorporated product type, material composition, end user archetype, and feature technology maturity. CAGRs were derived from weighted averages of equipment replacement cycles, regional adoption curves, and regulatory implementation timelines. Industry-specific forecast inputs included MIIT industrial clustering policy incentives and METI standby power regulations shaping motorized head development.
Caveats apply where acrylonitrile feedstock price volatility, Japanese Toray supply disruption, or accelerated EU digital product passport mandates could materially shift the outlook. Forecasts reflect documented assumptions about platform creator economics and certification timeline standardization. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
5G Smartphone Market
Others
Gym Wipes Market
Others
Content Experience Platforms Market
Others
Asia Pacific Foodservice Paper Packaging Market
Others
Halogen Free Flame Retardant Bopet Films Market
Others
Digital Bass Processor Market
Others
Global Maritime Freight Transport Market
Others
Couscous Market
Others
Dental Ceramics Market
Others
Coriolis Meters Market
Others
Industrial PC Market
Others
Folding Mobile Phone Market
Others
Japan Indoor LBS Market
Others
Industrial Hooters Market
Others
Boston Round Bottle Market
Others
Global Application Testing Services Market