
 Global Automotive LED Lighting Market | 2026-2036
Global Automotive LED Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive LED Lighting Market Analysis
The capability gap between vertically integrated LED chip fabricators and assembly-only lamp suppliers is collapsing as wafer-scale packaging and chip-on-board architectures commoditize photonic performance. Koito Manufacturing leverages captive optomechanical design centers in Japan to sustain premium headlamp positioning. HELLA GmbH & Co. KGaA anchors European OEM relationships through matrix-beam calibration expertise. Nichia Corporation dominates high-flux chip supply with in-house gallium-nitride crystal growth.
Automotive LED lighting comprises solid-state electroluminescent devices utilizing indium-gallium-nitride semiconductor junctions to produce directional white light with luminous efficacy exceeding 150 lumens per watt, primarily serving vehicle forward illumination, signaling, and interior ambient functions. Headlamp assemblies command the deepest margin pools due to thermal management complexity and optical precision requirements. Electric Vehicles represent the fastest-growing vehicle-type segment as platform voltage architectures enable higher LED drive currents. Matrix LED technology leads the technology hierarchy through pixelated beam shaping that satisfies ECE R48 without mechanical shutters.
FDA maintains photobiological safety jurisdiction over aftermarket LED retrofit kits in the United States, while ECE regulations govern OEM headlamp homologation across Europe and aligned markets. China's GB standards and MIIT certification protocols dictate domestic LED lamp performance benchmarks and electromagnetic compatibility thresholds. Stakeholders must monitor divergence between regional glare-limitation protocols and the pace of software-defined beam-pattern updates.
Market Dynamics
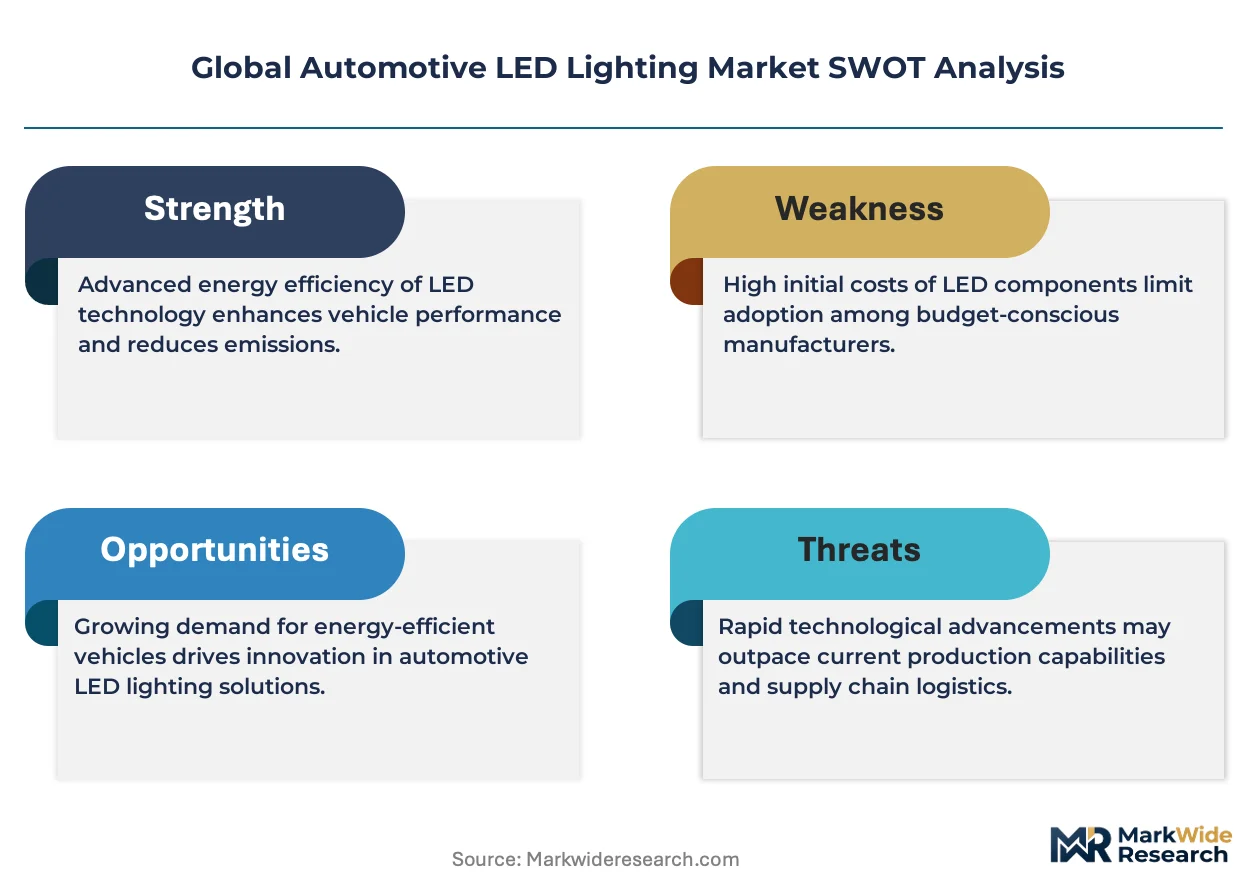
Wafer-scale packaging and chip-on-board architectures are collapsing the capability gap between integrated LED fabricators and assembly-only lamp suppliers, compressing margin pools for mid-tier players while rewarding those with captive optomechanical design expertise.
Growth Catalysts
- Matrix LED Mandates:Europe's ECE R48 regulations now require adaptive front-lighting for new vehicle categories, forcing OEM adoption of pixelated beam systems without mechanical shutters.
- NEV Platform Voltage:China's New Energy Vehicle architectures enable higher LED drive currents than internal combustion platforms, accelerating headlamp electrification in the world's largest automotive market.
- Gallium-Nitride Crystal Growth:In-house GaN substrate production is concentrating high-flux chip supply among vertically integrated fabricators, locking in performance advantages for captive suppliers.
Market Restraints
- Silicon Carbide Substrate Costs:Thermal management substrates for high-power headlamp assemblies face price volatility tied to automotive power electronics demand, squeezing module margins.
- Japanese Optomechanical Concentration:Captive design centers in Japan control premium headlamp positioning, limiting European and Chinese suppliers to standard-tier calibration work.
- Halogen Aftermarket Persistence:Low-cost retrofit kits in developing markets delay LED penetration in vehicle parc turnover, particularly where FDA photobiological enforcement remains limited.
Strategic Opportunities
- Software-Defined Beam Patterns:Over-the-air updates enable dynamic glare-limitation protocols, creating recurring revenue streams beyond hardware sales for calibration-capable suppliers.
- Interior Ambient Expansion:Cabin lighting systems are migrating from static to programmable multi-zone configurations, opening new margin pools in premium electric vehicle segments.
- India BIS Certification Pathways:Domestic LED lamp standardization under Bureau of Indian Safety protocols is accelerating local assembly partnerships for global tier-1 suppliers.
Industry Challenges
- Optical Calibration Talent Scarcity:Matrix-beam pixel mapping requires specialized optomechanical engineers, with training pipelines lagging OEM deployment timelines by 18-24 months.
- Homologation Timeline Compression:ECE R48 certification cycles for adaptive systems now span 14-18 months, delaying platform launches and freezing design iterations mid-cycle.
- Legacy Vehicle Integration Complexity:Retrofitting matrix LED controllers into 12-volt electrical architectures requires complete harness replacement, limiting aftermarket conversion economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive LED Lighting Market |
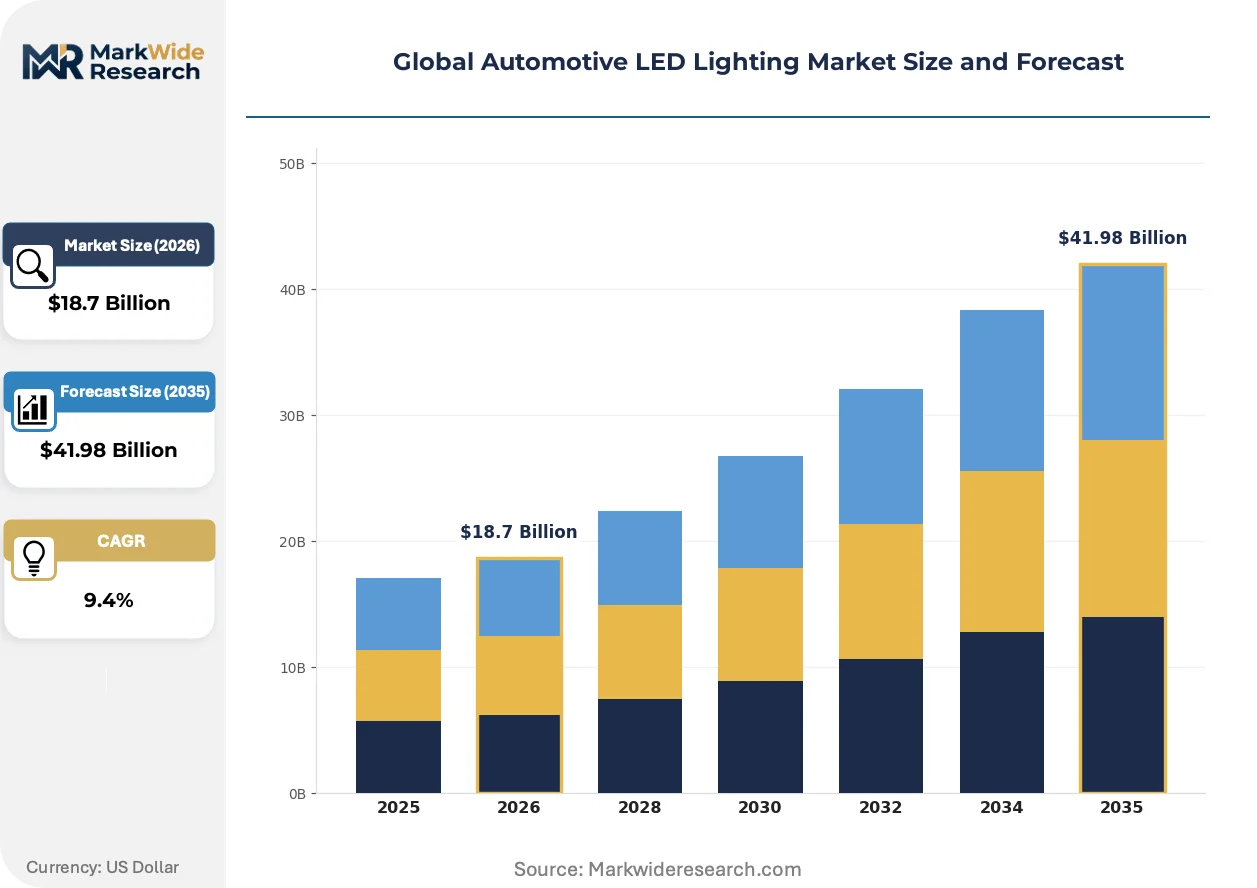
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Headlamps, Fog Lamps, Tail Lamps, Turn Signal Lights Vehicle Type: Passenger Cars, Commercial Vehicles, Electric Vehicles, Motorcycles Technology: Adaptive Lighting, Matrix LED, Laser LED, Standard LED Distribution Channel: OEMs, Aftermarket, Retail, Online |
| Companies Covered | Koito Manufacturing Co., Ltd., HELLA GmbH & Co. KGaA, Valeo SA, OSRAM GmbH, Stanley Electric Co., Ltd., Hyundai Mobis Co., Ltd., Nichia Corporation, Denso Corporation, Grupo Antolin-Irausa, S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive LED Lighting Market Emerging Trajectories
Active matrix driving and miniaturized thermal substrates are redefining performance benchmarks in forward illumination, while regulatory divergence between glare-limitation protocols is fragmenting homologation strategies across major automotive markets.
Mini-LED backlighting for automotive displays is displacing conventional edge-lit LCD modules in instrument cluster and center-stack applications. Tier-1 suppliers in Germany and Japan are adopting these architectures for 2026 platform launches. The shift is displacing legacy cold-cathode fluorescent inventory and compressing procurement timelines for display integrators.
China's MIIT certification protocols for GB-standard LED lamps now mandate electromagnetic compatibility testing that exceeds baseline UN ECE requirements. Domestic NEV manufacturers must demonstrate compliance with both sets of thresholds for export eligibility. This dual-certification burden is concentrating supplier relationships among firms with parallel testing capabilities in Shanghai and Stuttgart.
Fleet procurement of LED lighting as a service is emerging in European commercial vehicle segments, with leasing structures bundling hardware, calibration maintenance, and regulatory update subscriptions. Traditional component distributors are losing direct OEM relationships to platform integrators offering outcome-based uptime guarantees. Germany's KBA type-approval framework is adapting to accommodate these service-model certifications.
Global Automotive LED Lighting Market Segmentation
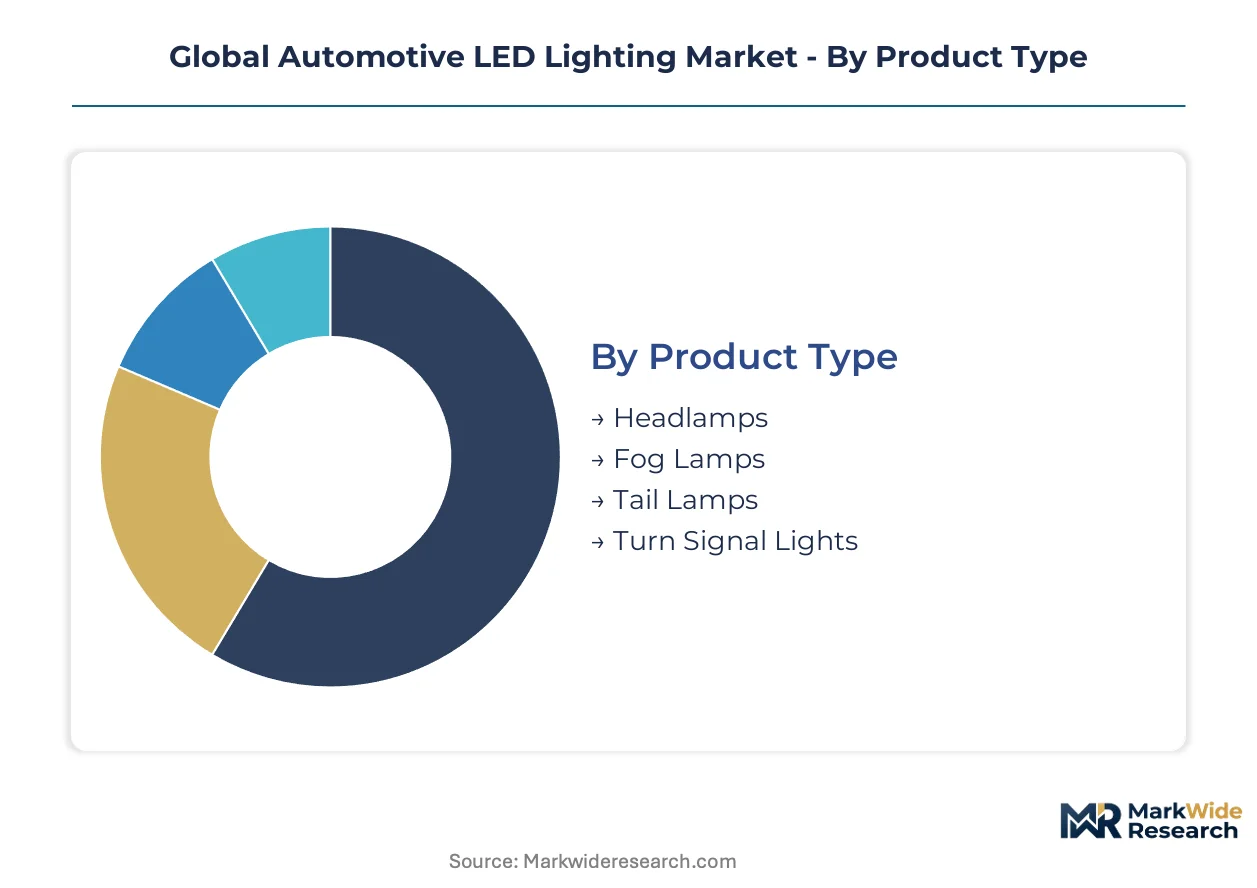
Margin pools in automotive LED lighting concentrate disproportionately in thermal-intensive forward illumination and adaptive beam systems. Segmentation reveals where technology premiums command pricing power versus commoditized replacement volumes.
Product Type:
Headlamp assemblies capture the deepest margins due to thermal management complexity and optical precision requirements that assembly-only suppliers cannot replicate.
- Headlamps:Forward illumination modules utilizing indium-gallium-nitride junctions with active matrix driving and pixelated beam shaping. Demand concentrates in Germany and Japan where ECE R48 mandates and captive optomechanical design centers sustain premium positioning.
- Fog Lamps:Low-beam auxiliary systems operating below 1000 lumens with simplified thermal substrates. China's NEV manufacturers are accelerating adoption as platform voltages enable higher drive currents than internal combustion architectures.
- Tail Lamps:Rear signaling assemblies with lower flux requirements and standardized form factors.
- Turn Signal Lights:Directional indicators with rapid cycling tolerance and amber wavelength specificity.
The dominant share belongs to Headlamps, while Fog Lamps are closing the gap fastest through NEV platform electrification.
Vehicle Type:
Volume concentration tracks electrification trajectories, with high-voltage architectures unlocking LED performance advantages unavailable to legacy 12-volt systems.
- Electric Vehicles:Battery-electric platforms operating at 400-800 volts enable LED drive currents exceeding 3 amperes, supporting matrix-beam functionality without voltage conversion losses. China's MIIT-certified NEV volume leadership concentrates demand among domestic tier-1 suppliers.
- Passenger Cars:Internal combustion and mild-hybrid platforms representing the installed base for adaptive lighting retrofits. European OEM relationships in Germany anchor matrix-beam calibration expertise for premium segment penetration.
- Commercial Vehicles:Fleet procurement with uptime-guarantee service models emerging in Germany's KBA-adapted certification framework.
- Motorcycles:Two-wheeler applications with compact thermal constraints and simplified optical requirements.
Electric Vehicles command the steepest expansion trajectory, while Passenger Cars retain volume leadership through parc turnover cycles.
Technology:
Performance hierarchies stratify by beam control granularity, with pixelated systems commanding 3-4x module pricing over standard architectures.
- Matrix LED:Pixelated beam systems with 25-84 individually addressable segments enabling dynamic glare limitation without mechanical shutters. ECE R48 mandates in Europe are forcing OEM adoption across new vehicle categories, locking in 14-18 month homologation timelines.
- Adaptive Lighting:Motorized headlamp leveling and cornering functions with simpler electromechanical actuation. Japan's METI-industry coordination supports domestic supplier retention of premium positioning through captive design centers.
- Laser LED:Hybrid architectures extending throw distance through phosphor-converted blue laser excitation.
- Standard LED:Fixed-beam replacements for halogen and xenon with basic thermal management and no dynamic control.
Matrix LED holds the technology premium, while Adaptive Lighting maintains volume scale through mid-tier platform fitment.
Distribution Channel:
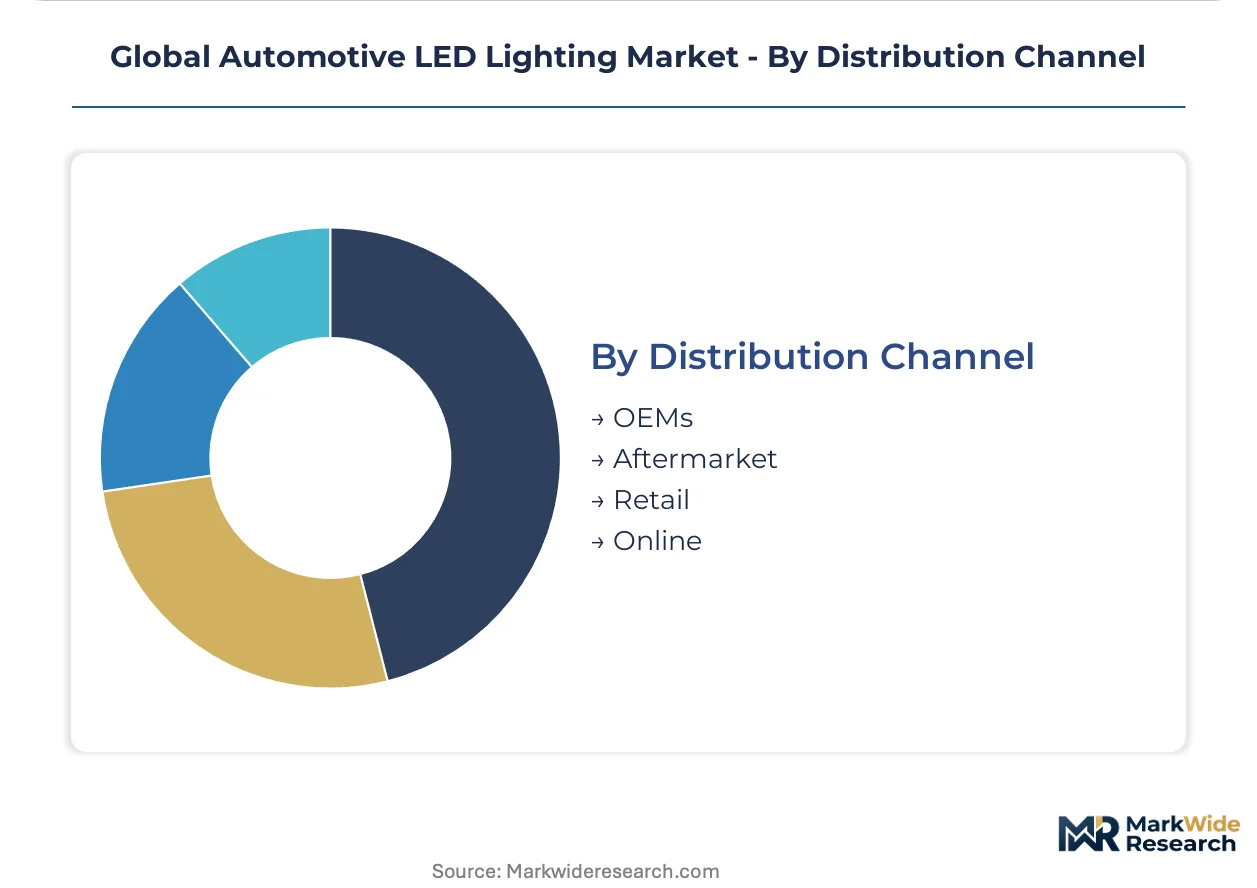
Channel economics diverge sharply between calibration-dependent OEM integration and price-driven aftermarket replacement.
- OEMs:Direct tier-1 supply with embedded calibration maintenance and over-the-air update subscriptions. Germany's platform integrators are displacing traditional distributors through outcome-based uptime guarantees in commercial vehicle segments.
- Aftermarket:Retrofit kit distribution subject to FDA photobiological safety jurisdiction in the United States, with enforcement gaps sustaining halogen persistence in developing markets.
- Retail:Bricks-and-mortar automotive parts channels with inventory carrying standard replacement inventories.
- Online:E-commerce platforms with compressed procurement timelines and direct consumer access.
OEMs dominate value capture, while Online channels are gaining transaction velocity fastest through procurement timeline compression.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany and Japan where captive optomechanical design centers command matrix-beam calibration premiums, while Chinese suppliers compete on NEV platform volume without equivalent margin capture.
Germany
KBA type-approval frameworks now accommodate fleet service-model certifications for commercial vehicle uptime guarantees. ECE R48 mandates force OEM adoption of pixelated beam systems across new vehicle categories. Stuttgart anchors European matrix-beam calibration expertise through tier-1 platform integrators displacing traditional distributors.
China
NEV manufacturers operating at 400-800 volt architectures enable LED drive currents exceeding 3 amperes unavailable to legacy platforms. MIIT certification protocols mandate electromagnetic compatibility testing exceeding baseline UN ECE requirements for export eligibility. Shanghai concentrates dual-certification testing capabilities serving domestic tier-1 supplier expansion.
Japan
METI-industry coordination supports domestic supplier retention of premium headlamp positioning through captive optomechanical design centers. JIS standards govern domestic LED lamp performance benchmarks alongside international alignment. Tokyo and Nagoya clusters control high-flux chip supply through in-house gallium-nitride crystal growth capabilities.
United States
FDA maintains photobiological safety jurisdiction over aftermarket LED retrofit kits, though enforcement gaps sustain halogen persistence in price-sensitive segments. NHTSA regulations govern forward illumination performance without mandating adaptive beam systems. Michigan's automotive corridor hosts OEM integration centers for North American platform launches.
India
BIS certification pathways under Bureau of Indian Safety protocols accelerate local assembly partnerships for global tier-1 suppliers seeking import substitution. Central government electric mobility incentives expand addressable vehicle platforms for LED headlamp fitment. Tamil Nadu and Gujarat automotive clusters attract component localization investments from East Asian fabricators.
Global Automotive LED Lighting Market Vendor Landscape
Concentration sits with vertically integrated LED fabricators and assembly specialists possessing captive optomechanical design expertise. The capability gap between these tiers is collapsing as wafer-scale packaging commoditizes photonic performance, compressing margin pools for mid-tier assembly-only players. Two strategic archetypes dominate: gallium-nitride substrate producers controlling high-flux chip supply, and calibration-capable lamp integrators commanding premium headlamp positioning. Competitive moves center on backward integration into crystal growth and geographic expansion through dual-certification testing capabilities.
Among Japanese fabricators, Koito Manufacturing Co., Ltd. and Stanley Electric Co., Ltd. occupy positions within the premium-tier optomechanical design cluster. HELLA GmbH & Co. KGaA represents European matrix-beam calibration expertise anchoring OEM relationships. Nichia Corporation exemplifies vertical control through in-house gallium-nitride substrate production.
| Leading Market Players |
|---|
| Koito Manufacturing Co., Ltd. |
| HELLA GmbH & Co. KGaA |
| Valeo SA |
| OSRAM GmbH |
| Stanley Electric Co., Ltd. |
| Hyundai Mobis Co., Ltd. |
| Nichia Corporation |
| Denso Corporation |
| Grupo Antolin-Irausa, S.A. |
| Others |
Supply Flow & Price Mechanics
ECE R48 homologation timelines gate both supplier qualification and price differentiation simultaneously, with 14-18 month certification cycles forcing tier-1 integrators to absorb upfront engineering costs that assembly-only competitors cannot replicate. This regulatory barrier stratifies the market into calibration-capable premium suppliers and commoditized standard-tier assemblers.
Pricing Analysis
Configured-to-order pricing for matrix-beam systems commands 3-4x premiums over standard fixed-beam modules. Three-tier pricing structure across premium, standard, and economy levels reflects ECE certification grade and captive optomechanical design ownership. Cost compression in mid-tier fog lamp assemblies is intensifying because wafer-scale packaging commoditizes photonic performance. Fleet procurement managers in commercial vehicle segments show least price sensitivity due to uptime-guarantee service bundling, while aftermarket retrofit consumers in developing markets remain most sensitive.
Supply Chain Analysis
Japan and Taiwan anchor high-flux chip fabrication through in-house gallium-nitride crystal growth and wafer-scale packaging capabilities. Germany concentrates matrix-beam calibration expertise and optomechanical design centers. Supply chains draw from silicon carbide substrates, indium-gallium-nitride epitaxy wafers, and precision optical-grade polymers. Single-source vulnerability concentrates in GaN substrate supply where Nichia Corporation maintains dominant production share. Distribution runs through tier-1 platform integrators offering embedded calibration maintenance and over-the-air update subscriptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software-defined beam patterns with over-the-air update subscriptions represent a service-attach opportunity expanding faster than hardware sales, creating recurring revenue streams for calibration-capable suppliers.
For Market Incumbents: Fortify captive optomechanical design centers in Japan and Germany against wafer-scale packaging commoditization threatening mid-tier margin pools. Deepen backward integration into gallium-nitride substrate production to lock in high-flux chip supply advantages. Prioritize dual-certification testing capabilities in Shanghai and Stuttgart to capture China's NEV export demand. For New Entrants and Emerging Players: Anchor in India's BIS certification pathways for domestic LED lamp assembly partnerships serving import substitution demand. Target Tamil Nadu and Gujarat automotive clusters where central government electric mobility incentives expand addressable platforms. Pursue fleet procurement service models with uptime-guarantee structures in European commercial vehicle segments. For Investors and Strategic Acquirers: ECE R48 mandate expansion reshapes the acquisition landscape toward calibration-capable lamp integrators with matrix-beam pixel mapping expertise. Long-term viability favors vertically integrated fabricators controlling upstream crystal growth and downstream homologation relationships. Monitor divergence between regional glare-limitation protocols as inflection indicator for software-defined beam-pattern revenue potential.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into GaN Substrate Production | Nichia Corporation's captive supply locks in high-flux chip performance advantages unavailable to assembly-only competitors. |
| Dual-Certification Testing Capabilities | Parallel Shanghai and Stuttgart facilities capture China's MIIT and UN ECE requirements for NEV export eligibility. |
| Software-Defined Beam Pattern Subscriptions | Over-the-air updates enable recurring revenue beyond hardware sales for ECE R48-compliant suppliers. |
| Captive Optomechanical Design Center Expansion | Koito Manufacturing's Japan-based centers sustain premium headlamp positioning against commoditization pressure. |
| Fleet Service Model Certification | Germany's KBA-adapted framework accommodates uptime-guarantee structures displacing traditional distributors. |
Methodological Framework
Desk research of regulatory filing databases, vehicle production statistics, and semiconductor trade flows preceded structured interviews with tier-1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and ECE homologation specialists. Primary intelligence combined with secondary validation from KBA type-approval records, MIIT certification registries, and IHS Markit vehicle registration data. Bottom-up segment sizing triangulated against top-down market value estimates.
Variance decomposition across technology tiers, vehicle propulsion architectures, and regional regulatory clusters shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include headlamp assembly complexity, NEV platform voltage class, and matrix-beam pixel density tier. CAGRs derived from production volume trajectories, content-per-vehicle expansion curves, and technology substitution rates across the analysis window. Forecast inputs incorporated ECE R48 mandate phase-in schedules and China's NEV sales penetration assumptions.
Underlying assumptions cover ECE regulatory continuity, GaN substrate supply stability, and NEV platform voltage standardization, with deviation risk concentrated in homologation timeline delays and regional glare-protocol divergence. Recalibration cycles align with material shifts in ECE mandate scope, MIIT certification requirement updates, and fleet procurement model adoption rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Receiving Scales Market
Others
Bulgur Market
Others
Industrial Air Purifiers Market
Others
Palatants Market
Others
Hotel Wardrobe Market
Others
Brazil Cane Sugar Market
Others
8K Technology Market
Others
Agitation System Market
Others
Workbench Tanks Market
Others
HPHT Diamond Cubic Press Market
Others
Pin Mills Market
Others
Italy Smart Home Market
Others
Middle East and Africa Medium Voltage Switchgear Market
Others
Coalescing Filter Market
Others
China Automotive LED Lighting Market
Others
Dandelion Market