
 China Cloud Gaming Technology Market | 2026-2036
China Cloud Gaming Technology Market Size, Share, and Industry Trends Forecast 2026-2036
China Cloud Gaming Technology Market Outlook
Asset-light server-leasing models is reconfiguring capital barriers for mid-tier entrants in China's cloud gaming arena. Tencent Holdings leverages its hyperscale data center footprint to dominate streaming infrastructure. NetEase Inc anchors its position through proprietary game engine optimization for low-latency delivery. Perfect World Games specializes in PC-to-cloud porting, occupying a narrow but defensible technical niche.
China Cloud Gaming Technology encompasses remote rendering architectures where game logic executes on centralized servers and compressed video streams transmit to endpoint devices, typically requiring sub-20ms latency and H.266 codec compatibility for 4K resolution at 60 frames per second. The primary commercial purpose is eliminating hardware dependency for graphically intensive titles while enabling cross-platform continuity. Mobile Gaming leads volume adoption among casual demographics, whereas Cloud Services command premium pricing from enterprise distributors. Edge Computing infrastructure is expanding fastest as provincial governments subsidize localized node deployment. VR Technology remains nascent in consumer penetration but draws concentrated R&D investment from hardware-software integrated platforms.
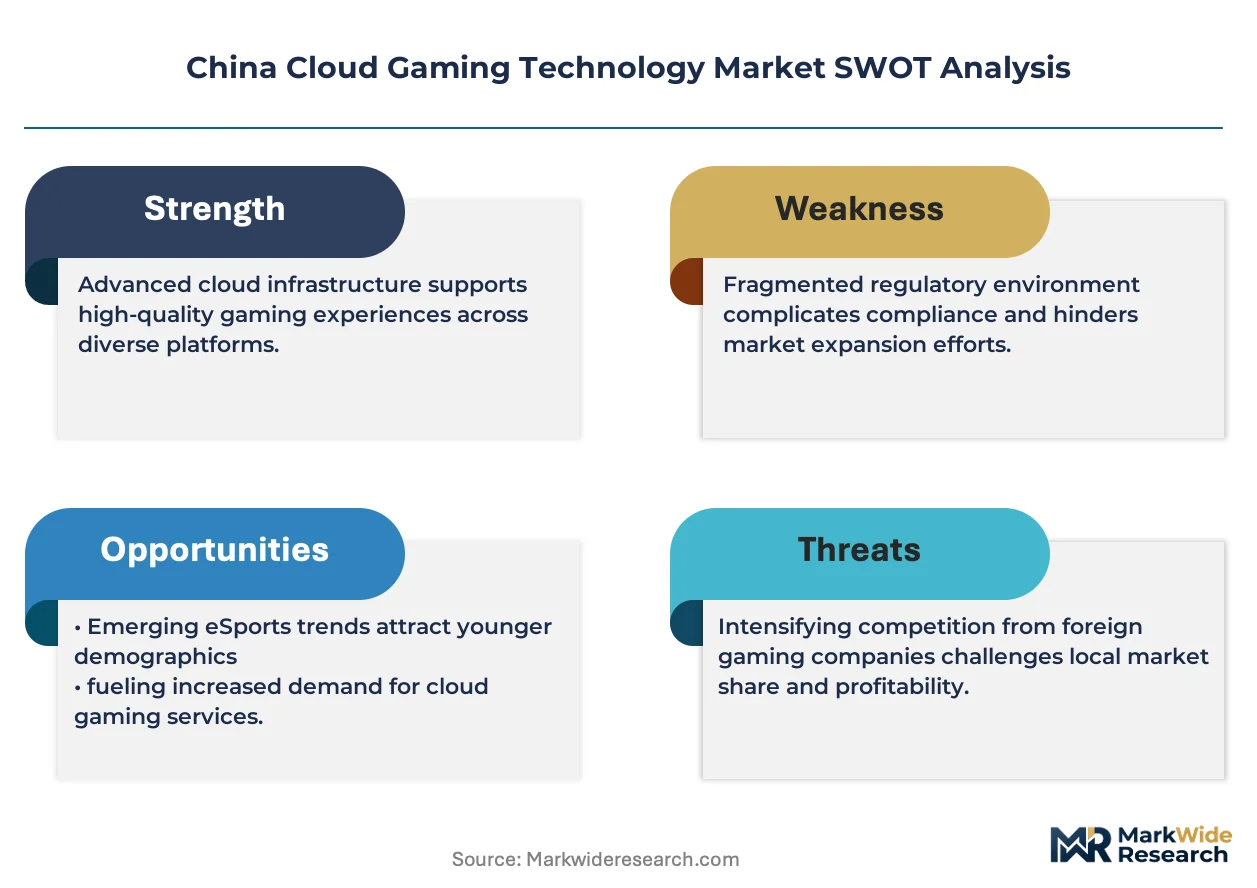
MIIT's 5G spectrum allocation and SAMR's data security compliance mandates jointly shape platform licensing requirements and cross-border content restrictions. GB standards for streaming quality and NMPA content approval protocols determine which titles reach commercial distribution. Stakeholders must monitor evolving interpretations of personal data localization rules and their interaction with real-time biometric input capture in next-generation interfaces.
Market Dynamics
MIIT's 5G infrastructure rollout and SAMR's data localization mandates are compressing latency thresholds while erecting compliance barriers, forcing platforms to rebuild architecture around edge node proximity rather than centralized hyperscale efficiency.
Growth Catalysts
- Edge Computing Deployment:Provincial governments in Guangdong and Zhejiang subsidize localized node construction, reducing round-trip latency for real-time rendering below 20 milliseconds.
- GB Standards for Streaming Quality:Unified technical specifications for H.266 codec compatibility accelerate hardware-software integration across device manufacturers.
- Casual Gamer Demographics:Tier-two city populations adopt mobile-first cloud gaming without legacy console investment, expanding addressable user bases beyond traditional hardware owners.
Market Restraints
- Data Center Concentration Risk:Rendering infrastructure clusters disproportionately in eastern coastal provinces, exposing service continuity to regional power grid constraints.
- NMPA Content Approval Protocols:Title-by-title licensing timelines create inventory gaps that prevent platform launch synchronization with global release schedules.
- Bandwidth Cost Volatility:Commercial 5G data pricing for high-definition streaming remains unpredictable, compressing unit economics for free-to-play monetization models.
Strategic Opportunities
- VR Technology Convergence:Biometric input capture systems merge with cloud-rendered immersive environments, opening premium subscription tiers for hardware-software integrated platforms.
- PC-to-Cloud Porting Services:Technical specialization in legacy title virtualization addresses back-catalog demand from aging hardware owners seeking continuity without replacement purchases.
- Provincial Dual Carbon Goals:Local government incentives for renewable-powered edge nodes attract platform investment into western interior data center construction.
Industry Challenges
- Real-Time Biometric Compliance:SAMR's evolving personal data localization rules interact unpredictably with gaze-tracking and gesture-capture input systems in next-generation interfaces.
- Cross-Platform Certification Complexity:Separate approval pathways for mobile, PC, and television endpoints fragment release engineering resources and extend quality assurance cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Cloud Gaming Technology Market |
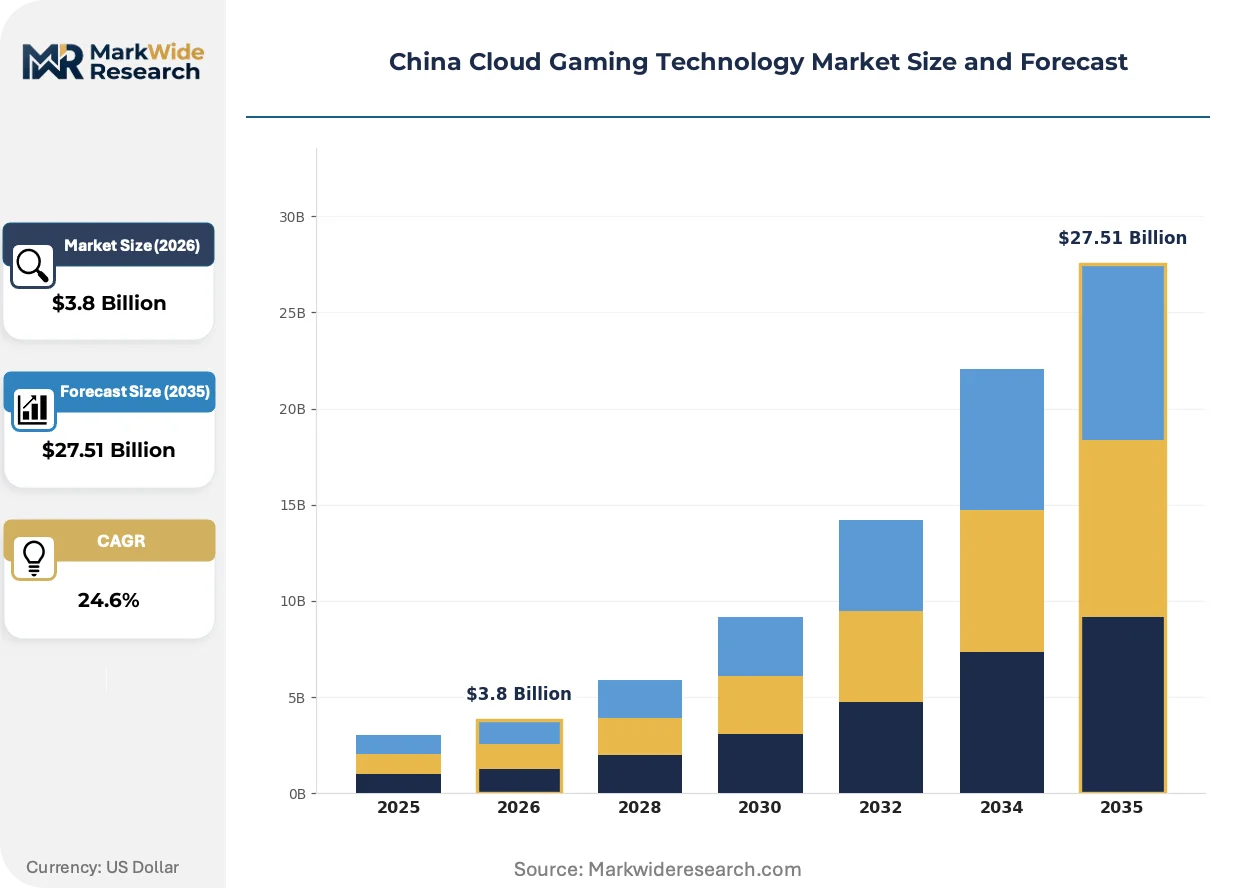
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $27.51 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gaming Consoles, Mobile Gaming, PC Gaming, Cloud Services Technology: 5G, Edge Computing, AI, VR Technology User Engagement: Multiplayer Modes, Live Streaming, Virtual Communities, In-Game Purchases End User: Casual Gamers, Professional Gamers, Families, Educational Institutions |
| Companies Covered | 37 Interactive Entertainment, Elex Technology, Tencent Holdings, KongZhong Corporation, NetDragon Websoft, NetEase Inc, Shanda Games, The9 Limited, Perfect World Games, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Cloud Gaming Technology Market Strategic Shifts
H.266 codec implementation is collapsing bandwidth requirements for 4K streaming, while MIIT's spectrum policy and shifting gamer demographics rewrite platform economics and distribution priorities simultaneously.
Hardware-agnostic rendering pipelines are collapsing the traditional console upgrade cycle by centralizing GPU investment in server farms. Casual gamers in tier-two and tier-three cities adopt these services without purchasing dedicated gaming hardware, compressing the addressable market for traditional semiconductor suppliers dependent on discrete graphics card sales.
SAMR's data security compliance mandates now require real-time biometric input processing to occur within domestic jurisdictional boundaries. Platforms must reconstruct their edge node topology to satisfy these requirements, affecting most severely those services targeting VR Technology integration where gaze and gesture data volumes exceed conventional control inputs.
Subscription bundling with telecommunications carriers is displacing direct-to-consumer platform registrations across Guangdong and Zhejiang provinces. Mobile network operators leverage existing billing relationships to capture cloud gaming distribution, compressing platform margins while accelerating subscriber acquisition velocity beyond standalone marketing capabilities.
China Cloud Gaming Technology Market Segmentation
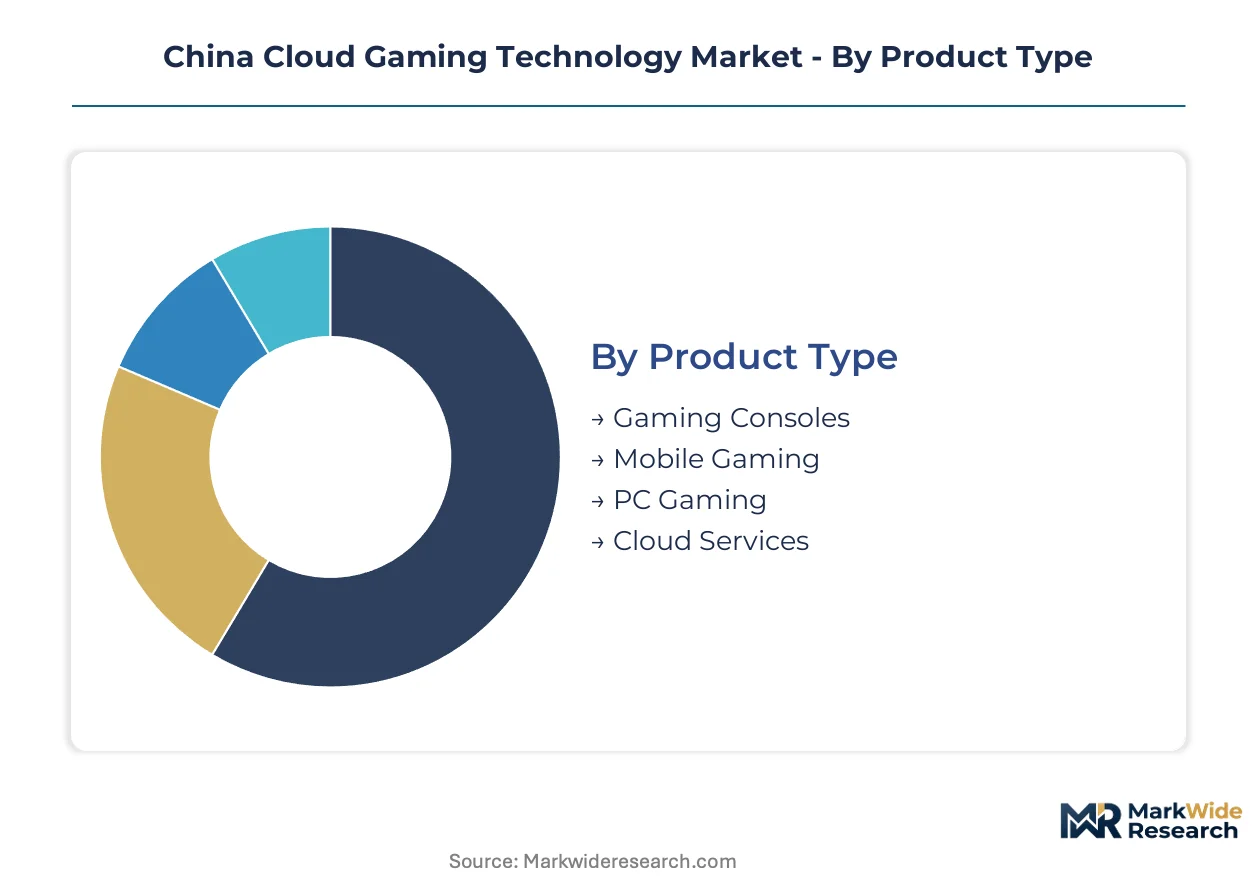
Segmentation in China's cloud gaming market reveals how infrastructure investments, user behavior patterns, and regulatory requirements fragment commercial opportunity across distinct technical and demographic boundaries. Platform operators must align architecture choices with the specific latency, content, and monetization profiles of each segment cluster.
Product Type:
Cost tier differentiation separates hardware-dependent entry points from infrastructure-heavy service models, with capital intensity determining competitive barriers for each segment.
- Mobile Gaming:Compressed video streams deliver console-equivalent graphics to smartphones via H.266 codec optimization. Demand concentrates in tier-two cities across Guangdong and Zhejiang provinces where 5G penetration eliminates local GPU requirements for casual demographics.
- Cloud Services:Subscription-based remote rendering infrastructure eliminates hardware ownership entirely. Enterprise distributors in coastal data center clusters drive premium pricing for white-label platform licensing and bandwidth arbitrage.
- Gaming Consoles:Hybrid devices combining local processing with cloud augmentation for latency-sensitive inputs.
- PC Gaming:High-fidelity streaming targeting aging hardware owners seeking continuity without discrete GPU replacement.
Mobile Gaming commands the established base. The steepest expansion runs through Cloud Services.
Technology:
Application maturity varies sharply across this dimension, with deployment-ready infrastructure contrasting against experimental interfaces still navigating compliance uncertainty.
- Edge Computing:Distributed node deployment reduces round-trip latency below 20 milliseconds for real-time rendering. Provincial subsidies in Guangdong and Zhejiang accelerate localized infrastructure construction, though western interior expansion lags due to grid constraints.
- 5G:MIIT spectrum allocation enables commercial streaming at 4K resolution. Urban density in tier-one and tier-two cities determines viable addressable markets given current base station topology.
- AI:Predictive frame generation and adaptive bitrate algorithms optimize bandwidth utilization during network congestion.
- VR Technology:Biometric input systems require reconstructed edge topology to satisfy SAMR data localization mandates for gaze and gesture processing.
5G infrastructure anchors current deployment. Edge Computing is climbing the fastest as latency requirements tighten.
User Engagement:
Volume concentration in this category tracks monetization mechanics, with direct purchase behavior commanding higher per-user value than audience aggregation models.
- In-Game Purchases:Microtransaction architectures generate recurring revenue without upfront hardware investment. Free-to-play titles in mobile-first ecosystems dominate revenue concentration across tier-two city demographics.
- Live Streaming:Real-time broadcast of cloud-rendered gameplay creates secondary monetization through viewer tipping and advertising. Platform bandwidth costs scale nonlinearly with concurrent stream density.
- Multiplayer Modes:Synchronized session management requires sub-20ms latency coordination across distributed edge nodes.
- Virtual Communities:Persistent social environments with user-generated content moderation overhead.
In-Game Purchases command the established base. Live Streaming is gaining share fastest through telecommunications carrier bundling.
End User:
Customer type stratification reflects hardware ownership history, with legacy console and PC owners presenting different migration economics than device-naive entrants.
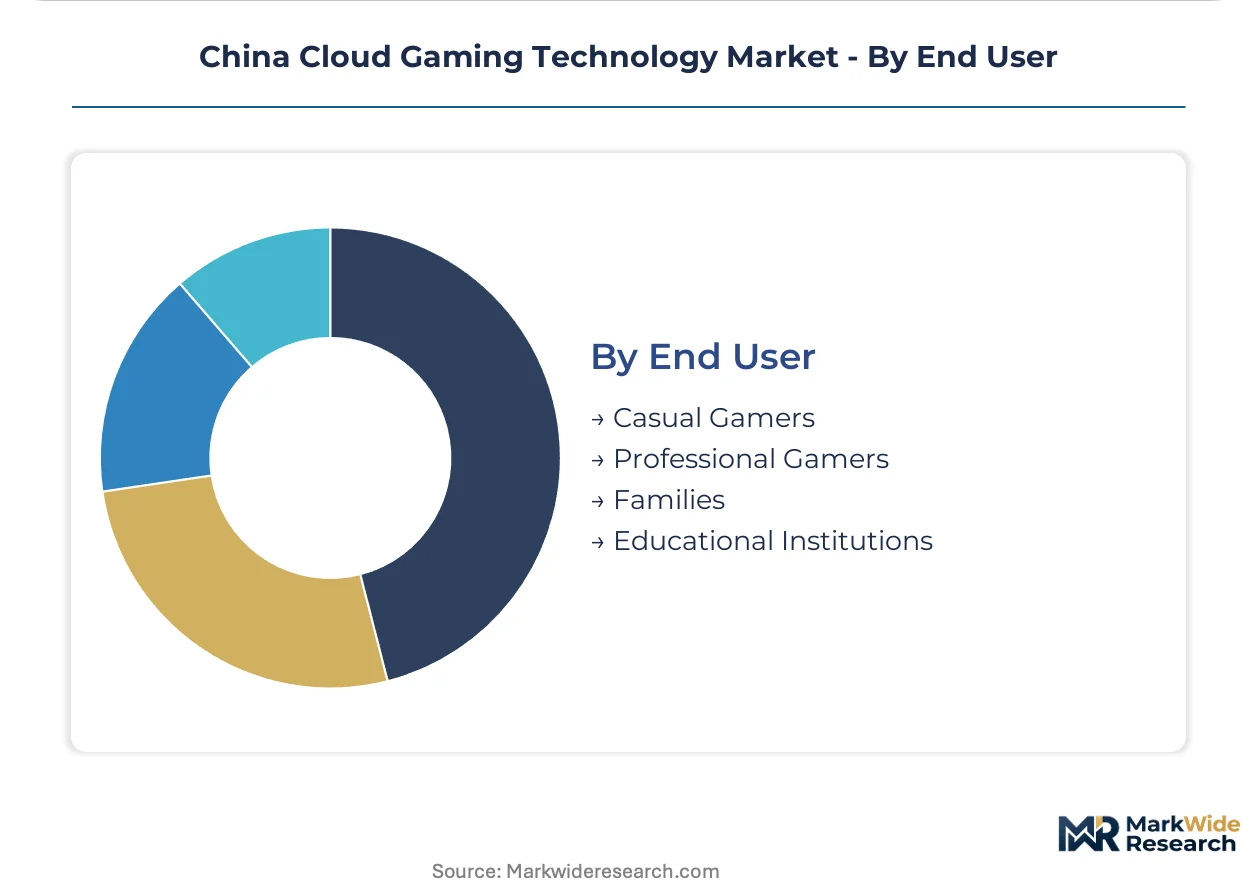
- Casual Gamers:Device-agnostic users prioritizing convenience over performance fidelity. Population concentration in tier-two and tier-three cities without legacy console investment expands addressable bases beyond traditional hardware ownership patterns.
- Professional Gamers:Latency-sensitive competitive players requiring guaranteed sub-15ms performance tiers. Subscription willingness exceeds casual segments, though NMPA content approval delays fragment tournament title availability.
- Families:Multi-account household structures with parental control and spending limit requirements.
- Educational Institutions:Curriculum-integrated simulation and training applications with procurement cycle constraints.
Casual Gamers command the established base. Professional Gamers show the steepest expansion trajectory through premium tier subscriptions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's cloud gaming sector runs a technology trade surplus through equipment exports and service licensing, while importing specialized GPU hardware and codec intellectual property. Provincial data center construction concentrates investment flows along eastern coastal corridors. MIIT's infrastructure directives redistribute activity toward western renewable energy zones.
Guangdong Province
Shenzhen and Guangzhou anchor the nation's densest edge computing node deployment, driven by hyperscaler facility investment and 5G base station density requirements. Provincial dual carbon subsidies attract renewable-powered data center construction into the northern Pearl River Delta periphery. MIIT's GB standards for streaming quality accelerate H.266 codec hardware integration among local device manufacturers.
Zhejiang Province
Hangzhou's gaming development ecosystem generates disproportionate cloud porting demand from legacy PC title owners seeking hardware continuity. SAMR data localization mandates force platform reconstruction around provincial edge topology for biometric input processing. Ningbo and Wenzhou telecommunications carriers bundle subscription services that displace direct platform registrations.
Beijing-Tianjin-Hebei
Regulatory headquarters concentration shapes NMPA content approval protocol interpretation and cross-border data flow restrictions. State-owned cloud infrastructure providers dominate enterprise distribution licensing in this corridor. Langfang and Zhangjiakou data center clusters absorb hyperscaler investment seeking proximity to content regulatory decision centers.
Sichuan-Chongqing
Western interior renewable energy abundance supports provincial government incentives for carbon-neutral edge node construction. Chengdu's gaming development studios generate native cloud-optimized title pipelines that reduce PC-to-cloud porting dependency. Chongqing's telecommunications infrastructure bridges western latency gaps through MIIT-subsidized 5G expansion.
Jiangsu Province
Nanjing and Suzhou semiconductor packaging facilities supply codec hardware components for H.266-compatible streaming endpoints. Provincial industrial policy targets upstream cloud gaming infrastructure manufacturing rather than platform operation. Yangtze River Delta integration agreements facilitate cross-provincial edge node load balancing with Shanghai and Zhejiang counterparts.
China Cloud Gaming Technology Market Competitive Environment
On the supply side, the industry is consolidating around hyperscale infrastructure operators with captive data center footprints and telecommunications carrier distribution channels. Platform economics favor entities controlling both rendering capacity and subscriber billing relationships. Three archetypes dominate: hyperscale integrated platforms, specialized game engine optimizers, and telecommunications-coupled distributors. Competitive moves concentrate on edge node proximity acquisition and subscription bundling negotiations with mobile network operators.
Among integrated platform operators, Tencent Holdings and NetEase Inc exemplify contrasting infrastructure strategies, while Perfect World Games occupies a position within specialized PC-to-cloud porting services. Tencent Holdings leverages hyperscale data center ownership to control streaming infrastructure economics directly. NetEase Inc anchors its competitive position through proprietary engine optimization rather than facility investment. Perfect World Games represents the technical specialization archetype, targeting legacy title virtualization demand without competing for hyperscale infrastructure dominance.
| Leading Market Players |
|---|
| 37 Interactive Entertainment |
| Elex Technology |
| Tencent Holdings |
| KongZhong Corporation |
| NetDragon Websoft |
| NetEase Inc |
| Shanda Games |
| The9 Limited |
| Perfect World Games |
| Others |
Value Chain & Pricing Dynamics
GPU server farm concentration in eastern coastal provinces concentrates rendering cost leverage among hyperscale operators, while subscription bundling through telecommunications carriers diverts margin pools toward distribution intermediaries.
Pricing Analysis
Telecommunications carriers anchor subscription pricing through bundled mobile data packages that compress standalone platform margins. Three-tier pricing structure across premium, standard, and economy levels differentiates by latency guarantee and resolution tier, with professional gamers showing lowest price sensitivity. Cost compression in economy tiers intensifies because bandwidth arbitrage from 5G data pricing volatility erodes unit economics. Casual gamers in tier-two cities demonstrate highest price sensitivity, driving platform focus on freemium conversion mechanics.
Supply Chain Analysis
Foxconn and Inventec hold contract manufacturing capacity for H.266 codec hardware components deployed in streaming endpoints. GPU semiconductor supply draws from Taiwan, South Korea, and USA foundries, while edge node construction rests on steel and concrete inputs from domestic suppliers. Single-source vulnerability in advanced GPU procurement exposes infrastructure buildout timelines to export control restrictions. Distribution runs through telecommunications carrier partnerships that displace direct platform subscriber relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's cloud gaming sector is recovering from infrastructure investment cyclicality as MIIT's 5G spectrum allocation renews capital deployment momentum.
For Market Incumbents: Insulate rendering infrastructure economics through captive edge node ownership in Guangdong and Zhejiang, where provincial subsidies lower renewable power costs. Defend against telecommunications carrier margin capture by developing proprietary billing relationships with high-ARPU professional gamer segments. Prioritize NMPA content approval pipeline investment to reduce title launch delays that fragment user acquisition timing. For New Entrants and Emerging Players: Build out technical specialization in PC-to-cloud porting services for aging hardware owners in tier-two cities, the most penetrable segment given incumbent focus on native cloud titles. Target western interior provinces such as Sichuan and Chongqing where provincial dual carbon incentives attract overlooked edge node investment. Pursue go-to-market angles through educational institution procurement channels with curriculum-integrated simulation applications. For Investors and Strategic Acquirers: Capital is best deployed toward edge computing infrastructure operators with renewable-powered data center footprints and established MIIT compliance protocols. Long-term viability across the projection horizon favors entities controlling both rendering capacity and provincial government relationships for node deployment licensing. Monitor MIIT's evolving GB standards for streaming quality as the signal indicating codec hardware refresh cycles and infrastructure replacement demand.| Strategic Initiative | Industry Significance |
|---|---|
| Edge Node Geographic Expansion | Provincial dual carbon subsidies in western interior reduce renewable power costs for latency-critical infrastructure. |
| Telecommunications Carrier Partnership | Mobile network operators in Guangdong and Zhejiang capture subscriber billing relationships that accelerate acquisition velocity. |
| H.266 Codec Hardware Integration | MIIT's GB standards for streaming quality mandate compatibility upgrades across device manufacturer supply chains. |
| PC-to-Cloud Porting Service Development | Legacy title virtualization addresses back-catalog demand from aging hardware owners without GPU replacement investment. |
| Biometric Input Compliance Architecture | SAMR data localization mandates require reconstructed edge topology for gaze and gesture processing in VR convergence. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of MIIT policy directives, NMPA content approval databases, and hyperscaler capex disclosures. Platform engineering directors, telecommunications carrier partnership managers, and provincial data center development officers provided operational perspective. Secondary validation drew from SAMR regulatory filings, GB standards documentation, and 5G infrastructure deployment records. Bottom-up segment sizing triangulates against top-down infrastructure investment flow analysis.
Forecast inputs include edge node deployment velocity, 5G base station density trajectories, and NMPA title approval throughput across the projection horizon. Segmentation models incorporate product type, technology layer, user engagement mechanism, and end user archetype dimensions. CAGRs derive from infrastructure capacity buildout curves correlated with subscriber adoption patterns in tier-one through tier-three city clusters. Codec hardware refresh cycles and provincial subsidy program durations inform replacement demand assumptions.
Sensitivities concentrate around MIIT spectrum policy adjustments, SAMR data localization rule interpretations, and NMPA content approval timeline variability. Forecasts reflect assumptions regarding continued provincial government edge node subsidies and stable 5G commercial data pricing. Quarterly review of MIIT infrastructure investment disbursements and NMPA monthly approval volumes is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Wearable Translator Market
Others
Ammeters Market
Others
Middle East Location-Based Services Market
Others
Global Emergency Spill Response Market
Others
China Online Gambling Market
Others
Biopharma Plastics Market
Others
Global Flexible PVC Films Market
Others
South America Automotive LED Lighting Market
Others
Cat Dry Food Market
Others
Smart Plug Market
Others
Europe Flow Battery Market
Others
Duckweed Market
Others
India 3D Printing Construction Market
Others
Binoculars and Mounting Solutions Market
Others
Germany 3D Printing Construction Market
Others
Safety Critical Software Testing Market