
 Ambient Assisted Living and Smart Home Market | 2026-2036
Ambient Assisted Living and Smart Home Market Size, Share, and Industry Trends Forecast 2026-2036
Ambient Assisted Living and Smart Home Market Analysis
German sensor manufacturers and Nordic system integrators are restructuring supply chains to meet surge orders from eldercare providers. Koninklijke Philips N.V. leverages its clinical-grade monitoring heritage to anchor hospital-to-home transitions. Siemens AG dominates building automation integration, while Robert Bosch GmbH competes through its MEMS sensor manufacturing scale. Johnson Controls sustains channel control via long-term facility management contracts with North American senior living chains.
Ambient Assisted Living and Smart Home denotes an ecosystem of networked sensors, actuators, and intelligent platforms that monitor environmental conditions, physiological signals, and activity patterns to enable autonomous living for aging or disabled populations. Core technical specifications include Zigbee and Z-Wave wireless protocols operating at sub-gigahertz frequencies to penetrate residential walls, plus edge AI inference engines processing data locally to minimize cloud dependency. Smart Sensors and Health Monitoring Systems represent the fastest-expanding product categories, driven by reimbursement codes for remote patient monitoring in Medicare Advantage plans. IoT connectivity infrastructure captures the deepest margin pools, as platform providers extract recurring SaaS fees atop hardware sales.
The FDA regulates Software as a Medical Device claims for fall-detection algorithms, while the EU AI Act imposes conformity assessments on biometric inference systems deployed in European homes. HIPAA and GDPR compliance costs are forcing vendors to adopt federated architectures that keep raw health data on local hubs. Stakeholders must decide whether to absorb certification expenses or cede European and North American markets to incumbent clinical device manufacturers.
Market Dynamics
The EU AI Act's conformity assessment mandate for biometric inference systems deployed in European homes is forcing platform vendors to rearchitect data flows and absorb certification costs, compressing margins for non-compliant suppliers.
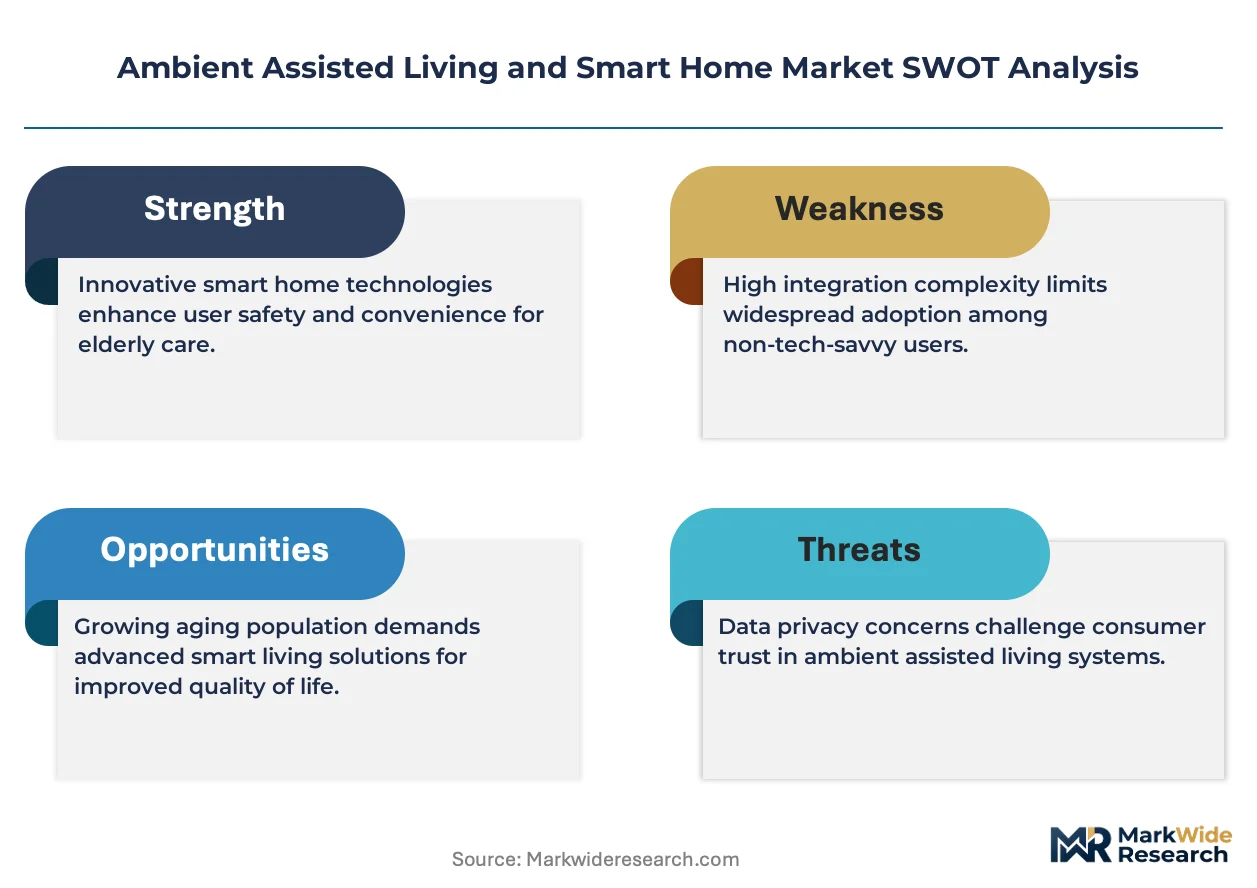
Growth Catalysts
- Medicare Advantage RPM reimbursement codes:US payers now cover remote patient monitoring for chronic condition management, pulling clinical-grade sensors into residential settings.
- German municipal eldercare budgets:Technology-agnostic procurement rules in Bavaria and North Rhine-Westphalia favor interoperable Zigbee and Z-Wave networks over proprietary systems.
- Edge AI inference engines:Local processing architectures minimize cloud dependency and GDPR transfer risks, accelerating deployment in privacy-sensitive European markets.
Market Restraints
- MEMS sensor supply concentration:Wafer fabrication for sub-gigahertz RF components clusters in East Asian foundries, exposing European integrators to geopolitical shipment delays.
- GDPR-HIPAA compliance cost stacking:Federated data architectures require redundant local hub infrastructure, raising per-unit hardware costs for North American vendors entering Europe.
- Fall-detection algorithm validation:FDA Software as a Medical Device claims demand clinical trial evidence that many consumer electronics firms lack, blocking hospital-to-home transitions.
Strategic Opportunities
- Skilled nursing facility penetration:US operators seek sensor networks that bridge acute discharge and long-term care, creating white space for clinical-grade platform extensions.
- EU Green Deal building retrofits:Energy efficiency mandates for existing housing stock create bundled installation opportunities for combined HVAC and assisted living sensor packages.
- Nordic system integrator partnerships:Norwegian and Swedish eldercare providers prioritize supplier neutrality, opening channel access for compliant hardware-agnostic platforms.
Industry Challenges
- Firmware-over-the-air certification maintenance:Continuous algorithm updates trigger recurring FDA and EU AI Act reassessments, straining quality assurance teams.
- Legacy building automation integration:Siemens and Johnson Controls protocols from the 1990s resist API standardization, forcing costly middleware development for new entrants.
- Clinical validation talent scarcity:Biostatisticians with geriatric endpoint expertise command premium compensation, slowing startup product pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ambient Assisted Living and Smart Home Market |
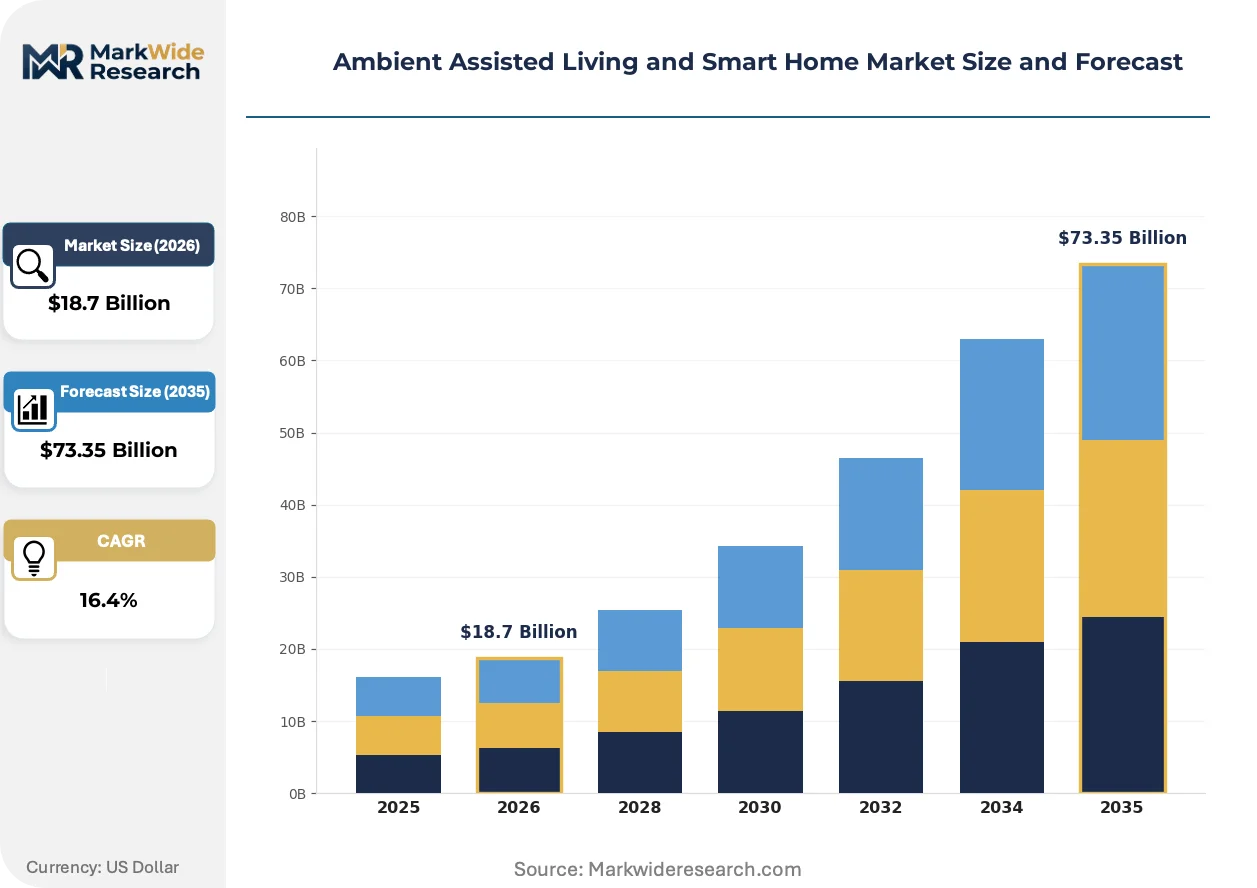
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Sensors, Home Automation Systems, Wearable Devices, Health Monitoring Systems Technology: IoT, AI, Voice Recognition, Robotics End User: Senior Citizens, Disabled Individuals, Caregivers, Families Application: Healthcare Monitoring, Home Security, Energy Management, Daily Activity Assistance |
| Companies Covered | Legrand SA, Johnson Controls, Koninklijke Philips N.V., Resideo Technologies, Inc., Siemens AG, Tunstall Healthcare Group, Robert Bosch GmbH, Alarm.com Holdings, Inc., Honeywell International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ambient Assisted Living and Smart Home Market Emerging Trajectories
Platform vendors are racing to embed clinical-grade monitoring into ambient infrastructure without triggering medical device regulatory thresholds, reshaping R&D priorities and partnership strategies.
Millimeter-wave radar sensors for contactless vital sign monitoring are consolidating around single-chip CMOS architectures that slash unit costs. Independent living facility operators in Denmark and the Netherlands are piloting these devices for sleep apnea detection. The technology is consolidating fall-risk assessment and respiratory monitoring into unified ceiling-mounted units, eliminating wearable adherence problems.
The EU AI Act's risk-based classification system for biometric inference imposes third-party conformity assessments on emotion-recognition algorithms in smart home hubs. German sensor manufacturers are pre-certifying edge processing modules to accelerate procurement cycles. Skilled nursing deployments face the steepest compliance burden, as patient-facing cameras trigger high-risk system designations.
Facility management contracts are unbundling hardware procurement from recurring SaaS fees, forcing platform vendors to compete on pure software value. North American senior living chains now separate sensor installation from analytics subscriptions, compressing upfront margins. This shift is most pronounced in Texas and Florida, where private equity-backed operators standardize on multi-vendor interoperability clauses.
Ambient Assisted Living and Smart Home Market Segmentation
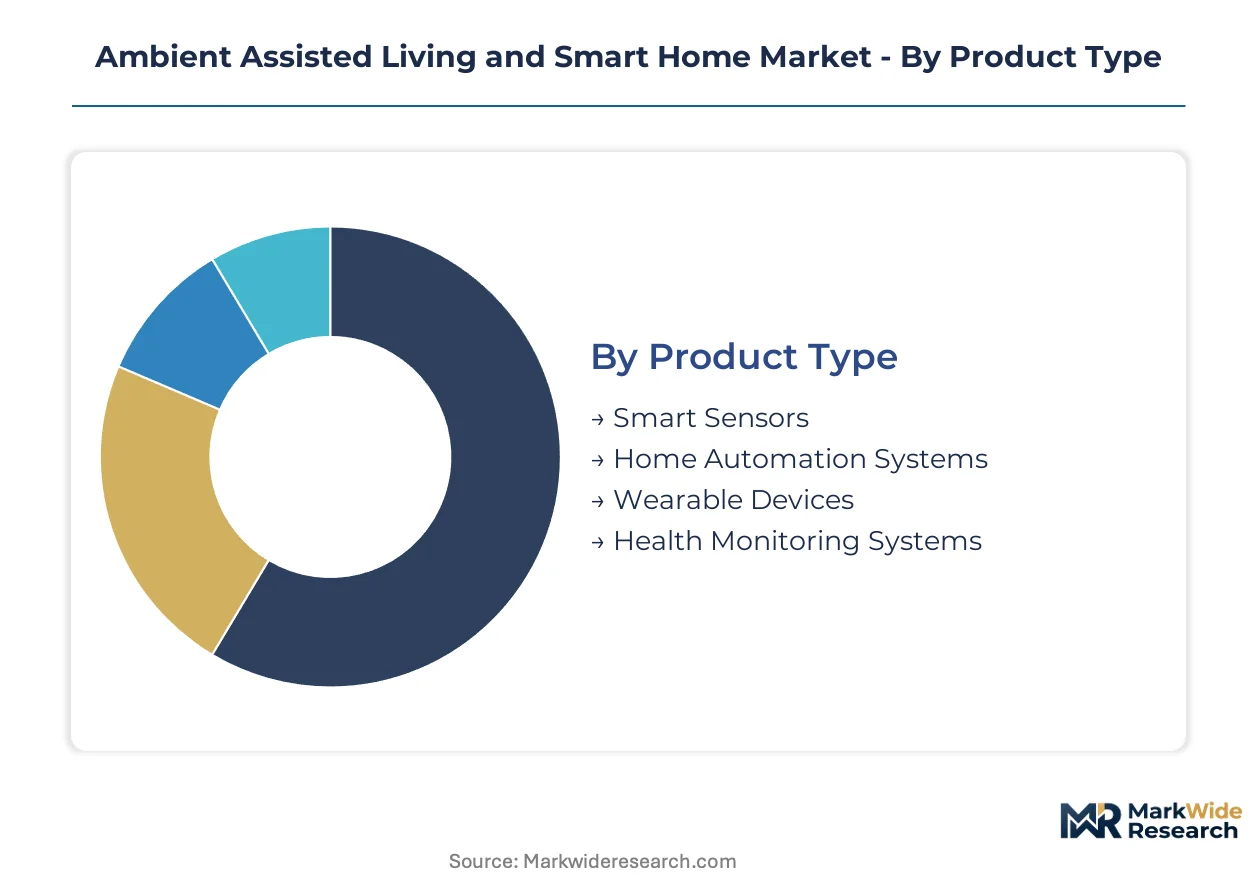
Product, technology, and application boundaries blur as vendors embed clinical-grade functions into ambient infrastructure. Segmentation choices determine which FDA, EU AI Act, and GDPR compliance burdens apply.
Product Type:
FDA Software as a Medical Device claims and EU AI Act conformity assessments cluster unevenly across hardware categories, with biometric inference triggering the steepest certification costs.
- Smart Sensors:Zigbee and Z-Wave wireless modules operating at sub-gigahertz frequencies penetrate residential walls for environmental and motion detection. Demand concentrates in Bavaria and North Rhine-Westphalia, where municipal procurement rules favor interoperable networks over proprietary systems.
- Health Monitoring Systems:Millimeter-wave radar sensors with single-chip CMOS architectures enable contactless vital sign tracking without wearable adherence. Danish and Dutch independent living operators pilot these for sleep apnea detection, pulling clinical functions into ambient infrastructure.
- Home Automation Systems:Building automation controllers integrating HVAC, lighting, and assisted living functions.
- Wearable Devices:Wrist and pendant units for emergency response and activity tracking.
Leading the category by volume: Smart Sensors. Expanding most quickly: Health Monitoring Systems.
Technology:
Edge processing architectures versus cloud-dependent systems determine GDPR transfer risk exposure and recurring SaaS margin capture.
- IoT:Connectivity infrastructure capturing recurring platform fees atop hardware sales through federated data architectures that keep raw health data on local hubs. Texas and Florida senior living chains now unbundle sensor installation from analytics subscriptions, compressing upfront margins while extending customer lifetime value.
- AI:Edge inference engines processing data locally to minimize cloud dependency and accelerate deployment in privacy-sensitive European markets. EU AI Act high-risk designations apply to patient-facing camera systems in skilled nursing settings.
- Voice Recognition:Natural language interfaces for command and control without physical interaction.
- Robotics:Mobile and fixed assistive platforms for physical task support.
Generating the deepest margin pools: IoT. Climbing the fastest: AI.
End User:
Reimbursement pathways and procurement authority vary sharply across user types, shaping go-to-market economics.
- Senior Citizens:Primary beneficiaries of Medicare Advantage remote patient monitoring coverage for chronic condition management, pulling clinical-grade sensors into residential settings.
- Caregivers:Professional and family care coordinators purchasing through facility management contracts or direct-to-consumer channels.
- Disabled Individuals:Users requiring accessibility-focused system configurations.
- Families:Adult children purchasing monitoring solutions for aging parents.
Driving procurement volume: Senior Citizens. Gaining share fastest: Caregivers.
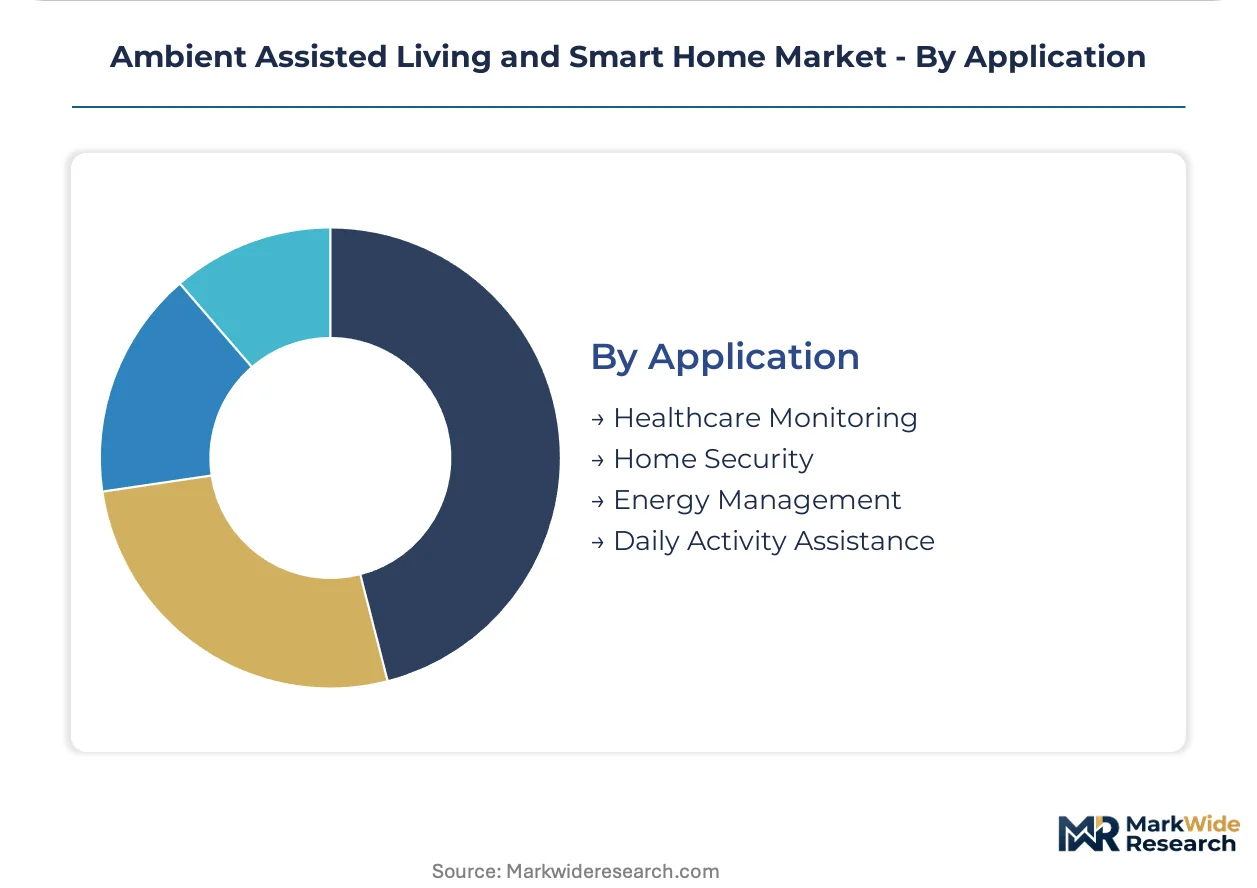
Application:
Functional use cases determine which regulatory frameworks apply and which reimbursement codes activate.
- Healthcare Monitoring:Fall detection, medication adherence, and vital sign tracking regulated as Software as a Medical Device by FDA when marketed with diagnostic claims. Clinical trial evidence requirements block many consumer electronics firms from hospital-to-home transitions.
- Home Security:Intrusion detection and emergency response systems with lower regulatory burden than clinical applications. Bundled installation opportunities arise from EU Green Deal building retrofit mandates combining HVAC and assisted living sensor packages.
- Energy Management:Smart thermostats and load control for efficiency optimization.
- Daily Activity Assistance:Task reminders, navigation support, and cognitive aids.
Commanding highest price points: Healthcare Monitoring. Seeing steepest expansion trajectory: Home Security.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon wafer fabrication for sub-gigahertz RF components clusters in East Asian foundries, yet demand-side deployment concentrates in Western European eldercare systems and North American senior living chains. Municipal procurement rules and reimbursement pathways determine where interoperable sensor networks achieve scale.
United States
Medicare Advantage remote patient monitoring reimbursement codes pull clinical-grade sensors into residential settings. The FDA regulates Software as a Medical Device claims for fall-detection algorithms, demanding clinical trial evidence that blocks consumer electronics firms from hospital-to-home transitions. Texas and Florida senior living chains unbundle hardware procurement from analytics subscriptions, compressing upfront margins.
Germany
Bavaria and North Rhine-Westphalia municipal eldercare budgets favor technology-agnostic procurement rules that prioritize interoperable Zigbee and Z-Wave networks. The EU AI Act imposes conformity assessments on biometric inference systems deployed in European homes. Siemens AG anchors building automation integration from its Munich and Erlangen facilities.
Denmark
Independent living facility operators pilot millimeter-wave radar sensors for contactless sleep apnea detection. GDPR compliance requirements accelerate demand for edge AI inference engines that process data locally. Copenhagen and Aarhus host Nordic system integrators restructuring supply chains to meet surge orders from eldercare providers.
Netherlands
EU Green Deal building retrofit mandates create bundled installation opportunities for combined HVAC and assisted living sensor packages. Dutch independent living operators consolidate fall-risk assessment and respiratory monitoring into unified ceiling-mounted units. Eindhoven's semiconductor ecosystem supplies CMOS architectures for radar sensor cost reduction.
Sweden
Norwegian and Swedish eldercare providers prioritize supplier neutrality, opening channel access for compliant hardware-agnostic platforms. The EU AI Act's risk-based classification system applies third-party conformity assessments to patient-facing camera systems in skilled nursing settings. Stockholm-based integrators compete on pure software value as facility management contracts unbundle hardware from SaaS fees.
Ambient Assisted Living and Smart Home Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue clinical-grade platform extensions and edge AI certification. The vendor base stratifies across clinical device heritage, building automation integration, and MEMS sensor manufacturing scale. Three archetypes dominate: hospital-to-home transition specialists, facility management contract holders, and federated data architecture providers. Competitive moves concentrate on strategic partnerships with Nordic system integrators and absorption of EU AI Act certification costs to defend European market access.
Within the clinical-grade monitoring tier, Koninklijke Philips N.V. and Siemens AG exemplify divergent positioning strategies. Philips represents the hospital-to-home transition archetype, leveraging clinical heritage for residential deployment. Siemens occupies the building automation integration vector, dominating protocols for facility-wide sensor networks. Robert Bosch GmbH anchors the MEMS manufacturing scale tier, competing through captive production of sub-gigahertz RF components.
| Leading Market Players |
|---|
| Legrand SA |
| Johnson Controls |
| Koninklijke Philips N.V. |
| Resideo Technologies, Inc. |
| Siemens AG |
| Tunstall Healthcare Group |
| Robert Bosch GmbH |
| Alarm.com Holdings, Inc. |
| Honeywell International Inc. |
| Others |
Supply Flow & Price Mechanics
Silicon wafer spot prices cascade through MEMS foundry contracts into three-tier pricing structures across premium, standard, and economy levels for assisted living sensor networks. German municipal procurement rules compress margins on interoperable Zigbee modules while Texas senior living chains force SaaS unbundling that shifts revenue recognition downstream.
Pricing Analysis
Warranty and firmware-over-the-air update bundling now separates premium clinical-grade platforms from stripped hardware-only SKUs. Pricing stratifies across FDA-cleared, CE-marked, and uncertified tiers, with EU AI Act conformity assessments adding fifteen to twenty percent to patient-facing camera systems. Cost compression in the standard tier intensifies as Nordic system integrators consolidate volume orders. Skilled nursing facility operators show least price sensitivity due to Medicare Advantage reimbursement codes, while family purchasers in direct-to-consumer channels drive hardest bargain.
Supply Chain Analysis
Container freight rates from East Asian semiconductor hubs to Rotterdam and Hamburg directly determine landed costs for European integrators. Wafer fabrication for sub-gigahertz RF components clusters in Taiwan, South Korea, and mainland China, drawing from polysilicon feedstock and photoresist chemical inputs. Single-source vulnerability concentrates in 200mm MEMS foundry capacity. Distribution runs through Johnson Controls and Siemens facility management contracts that lock in multi-year sensor procurement schedules.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's third-party conformity assessment mandate erects a cost-of-compliance barrier that cements advantage for pre-certified platform vendors while screening out consumer electronics entrants lacking clinical validation infrastructure.
For Market Incumbents: Extend edge AI certification coverage into millimeter-wave radar modules before emerging entrants achieve CE marking. Absorb EU AI Act reassessment costs to defend German municipal procurement relationships against Nordic system integrators offering hardware-agnostic alternatives. Vertical integration into MEMS sensor manufacturing insulates margin position from East Asian foundry bottlenecks. For New Entrants and Emerging Players: Launch via white-label partnerships with Danish and Dutch independent living operators seeking contactless sleep apnea detection pilots. Target the caregiver segment in Norway and Sweden where supplier neutrality clauses open channel access without legacy facility management contract lock-in. Lead with pure software value propositions as hardware procurement unbundles from SaaS subscriptions across Texas and Florida. For Investors and Strategic Acquirers: Distressed-cycle entries favor federated data architecture specialists with GDPR-compliant local hub technology in Copenhagen and Aarhus. Long-term viability hinges on regulatory moat sustainability rather than hardware scale. Watch FDA Software as a Medical Device clearance velocity for millimeter-wave fall-detection algorithms as inflection signal for hospital-to-home transition economics.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Conformity Pre-Certification | Accelerates procurement cycles for German municipal eldercare budgets in Bavaria and North Rhine-Westphalia. |
| Millimeter-Wave Radar Platform Launch | Consolidates fall-risk and respiratory monitoring into unified ceiling-mounted units for Danish operators. |
| Federated Data Architecture Partnership | Minimizes GDPR transfer risk for Nordic system integrators restructuring supply chains. |
| Municipal Procurement Channel Lock-In | Secures multi-year facility management contracts with technology-agnostic interoperability clauses. |
| Clinical Validation Talent Acquisition | Addresses biostatistician scarcity slowing startup product pipelines for geriatric endpoint trials. |
Methodological Framework
Document review covered EU AI Act implementation guidance, FDA Software as a Medical Device guidance documents, and municipal eldercare procurement regulations across German states, complemented by interviews with senior living facility operators, biomedical engineers, GPO contracts managers, and Nordic system integrators. Secondary validation drew from CMS Medicare Advantage reimbursement filings, EMA medical device borderline determinations, and Zigbee Alliance interoperability certifications. Bottom-up unit economics triangulated against top-down market sizing across the analysis window.
Segmentation outputs reflect product type, technology architecture, end user category, and application function modeled throughout the forecast period. CAGRs derived from elasticity-adjusted adoption curves incorporating Medicare Advantage penetration rates, EU Green Deal building retrofit timelines, and edge AI inference engine cost decline trajectories. Supply-side constraints from MEMS foundry capacity and polysilicon price volatility fed into hardware shipment projections.
Regulatory enforcement variance, reimbursement code expansion delays, and semiconductor supply disruption are the dominant revision risks for forecast assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Augmented Reality (AR) in Warehousing and Logistics Market
Others
PCB Laminate Market
Others
US Cat Food Market
Others
Subtilisin Market
Others
Aluminium Clad Printed Circuit Board Market
Others
Eye Balm Market
Others
Global Microcontroller Embedded Systems Market
Others
Asia-Pacific Intercom Devices Market
Others
Dandelion Market
Others
North America Machine Vision Systems Market
Others
Global Enterprise Mobility in Healthcare Market
Others
North America Industrial Wearable Devices Market
Others
Video Conferencing Hardware Market
Others
Safety Critical Software Testing Market
Others
Europe Polycarbonate Sheets Market
Others
Global Sports and Fitness Wears Market