
 Middle East and Africa Cocoa Products Market | 2026-2036
Middle East and Africa Cocoa Products Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Cocoa Products Market Foresight
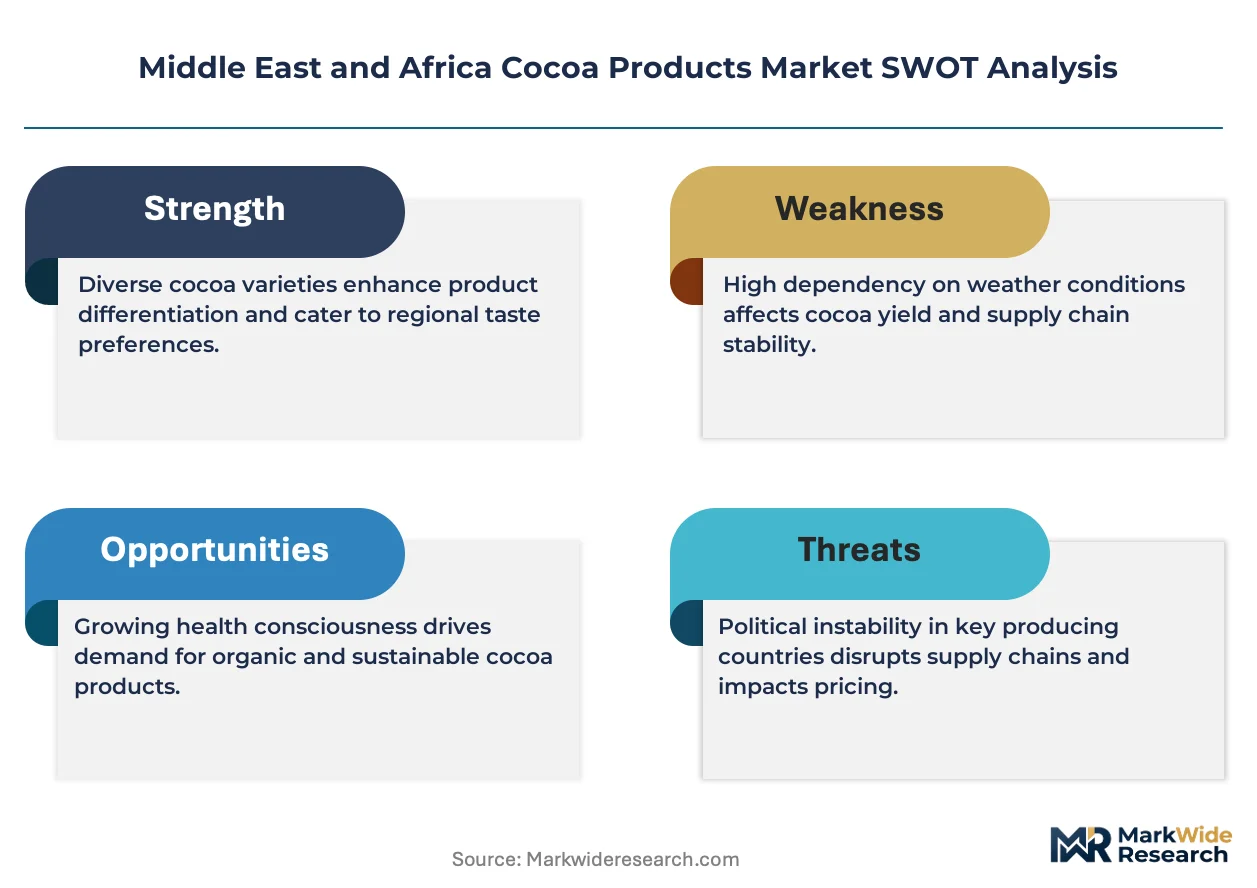
Shea butter is hardening as a partial cocoa butter substitute in cost-sensitive cosmetic and confectionery formulations across the region. Barry Callebaut leverages its Ghanaian grinding assets to secure West African bean supply. Mars Incorporated sustains regional manufacturing through its Egypt-based chocolate operations. Cargill competes by anchoring sustainability programs that trace beans from Ivorian cooperatives to Gulf processors.
Middle East and Africa cocoa products encompass fermented, dried, roasted, and processed Theobroma cacao derivatives including liquor, butter, powder, and finished chocolate, with cocoa butter maintaining a melting point between 34°C and 38°C critical for confectionery mouthfeel and tropical climate stability. These materials serve food formulation, cosmetic emollient systems, and pharmaceutical coating applications across markets where temperature tolerance and halal compliance determine commercial viability. Cocoa butter commands premium positioning in pharmaceutical coatings where precise polymorphism controls drug release profiles, while chocolate segments in the confectionery end-user category absorb volume through seasonal gifting cycles in the Gulf. Cocoa powder segments in food and beverage applications extend into bakery and dairy flavoring as regional dairy processors expand flavored milk portfolios.
FSSAI import protocols, South African Department of Health food safety standards, and Gulf Standards Organization halal certification requirements collectively govern ingredient labeling, allergen disclosure, and cross-contamination prevention across the value chain. These frameworks elevate compliance costs for smaller traders while creating market access barriers that favor integrated processors with dedicated quality laboratories. Stakeholders must monitor evolving Saudi Food and Drug Authority traceability mandates and Ethiopian agricultural export standards as both regulators expand digital verification systems for origin documentation.
Market Dynamics
Gulf retail networks are expanding premium chocolate shelf space while FSSAI-aligned import standards and local halal certification protocols simultaneously tighten ingredient traceability requirements across the value chain.
Growth Catalysts
- FSSAI Import Protocols:India's food safety regulator mandates digitized origin documentation that elevates compliance costs for informal traders, creating market access advantages for integrated processors with dedicated quality laboratories.
- Pharmaceutical Coatings:Cocoa butter's precise polymorphism controls drug release profiles in tropical climates, driving specialized demand from regional pharmaceutical manufacturers seeking temperature-stable coating materials.
- Cold-Chain Distribution:Nigeria and South Africa are building refrigerated logistics networks that enable temperature-sensitive cocoa derivatives to reach inland markets previously constrained by heat degradation.
Market Restraints
- Cocoa Butter Price Volatility:Fermented bean supply fluctuations from West African cooperatives transmit directly into input cost instability for confectionery formulators.
- Shea Butter Substitution:Cost-sensitive cosmetic and confectionery manufacturers in the region are hardening shea butter as a partial cocoa butter replacement, compressing volume demand for authentic derivatives.
- Gulf Standards Organization Halal Certification:Cross-contamination prevention requirements and allergen disclosure mandates create compliance friction that disproportionately burdens smaller trading operations.
Strategic Opportunities
- Ethiopian Agricultural Export Standards:The regulator's expansion of digital verification systems for origin documentation creates first-mover advantages for processors establishing traceable supply relationships with emerging highland growing regions.
- Flavored Milk Portfolio Expansion:Regional dairy processors are extending cocoa powder applications into dairy flavoring, opening volume absorption channels beyond traditional confectionery.
- Saudi Food and Drug Authority Traceability Mandates:Evolving digital documentation requirements favor integrated operators capable of end-to-end bean-to-bar verification systems.
Industry Challenges
- Halal Certification Timeline:Cross-contamination prevention protocols and ingredient segregation requirements extend product launch cycles for multi-purpose processing facilities.
- Cold-Chain Capex Intensity:Temperature-controlled warehousing and transport infrastructure demands substantial capital deployment that strains regional logistics operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Cocoa Products Market |
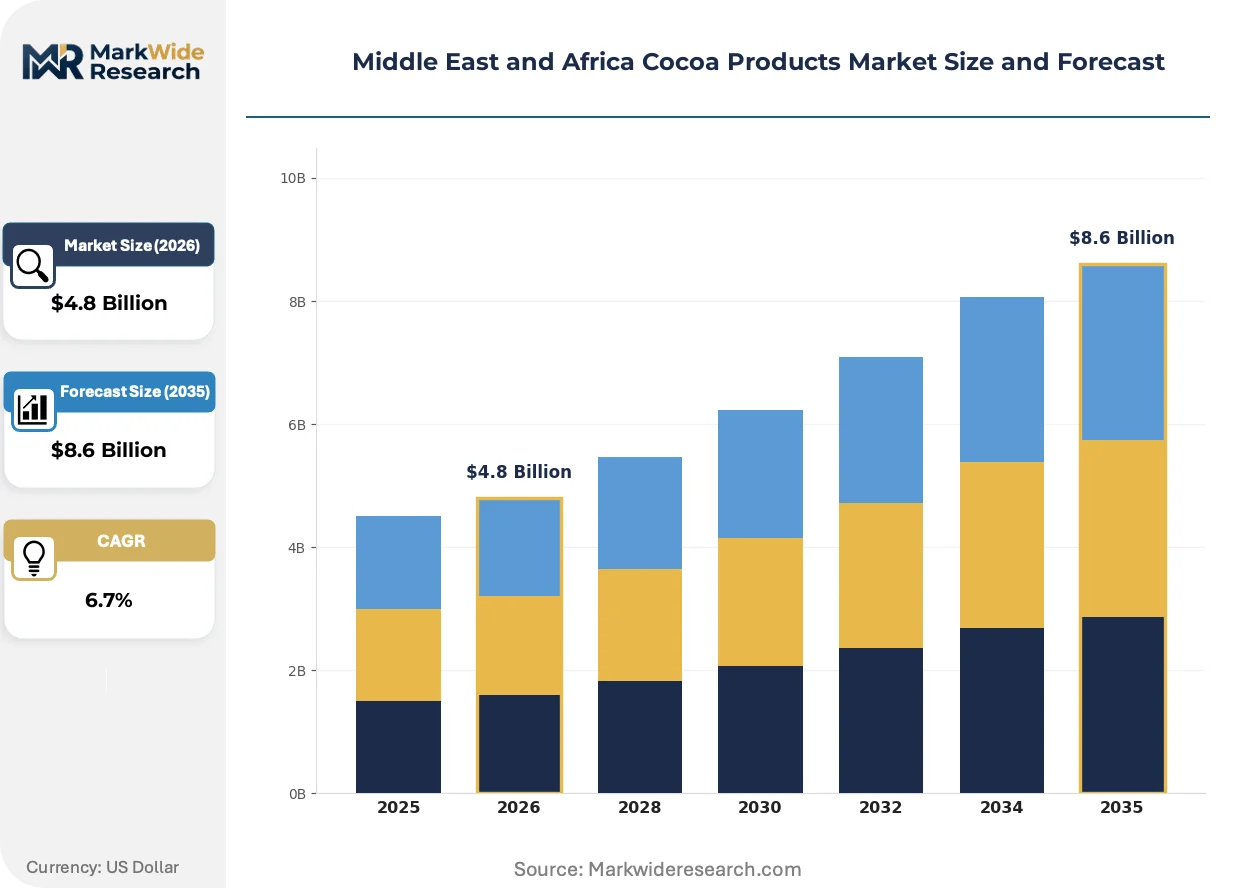
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cocoa Liquor, Cocoa Butter, Cocoa Powder, Chocolate End User: Food & Beverage, Cosmetics, Pharmaceuticals, Confectionery Packaging Type: Bags, Boxes, Tubs, Pouches Distribution Channel: Wholesale, Retail, Online, Direct Sales |
| Companies Covered | Nestle S.A., Mars Incorporated, Barry Callebaut, JB Foods Limited, Ferrero Group, Cargill, Mondelez International Inc., Patchi, ADM, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Cocoa Products Market Shifts & Advancements
Processing technology and certification protocols are reshaping competitive positioning in Middle East and Africa cocoa derivatives, with digitization and climate adaptation emerging as defining vectors of change.
Precision fermentation for cocoa butter alternatives is electrifying ingredient formulation capabilities in cosmetic and pharmaceutical applications. Regional cosmetic manufacturers are adopting these bio-identical lipids at accelerated pace to circumvent tropical climate stability challenges. This technology is compressing traditional bean-dependent supply chains while enabling localized production of functional equivalents.
Saudi Food and Drug Authority traceability mandates are forcing processors to deploy blockchain-verified origin documentation systems. Industrial consequence includes elevated capital requirements for quality laboratories and digital infrastructure. Premium chocolate segments in Gulf retail networks are most affected, responding through exclusive supplier partnerships that guarantee batch-level halal compliance.
Seasonal gifting cycles in Gulf markets are compressing procurement planning horizons for confectionery distributors. Traditional wholesale channels are fragmenting as direct-to-hotel and direct-to-airport retail relationships displace layered distribution. This pattern is most visible in Dubai and Riyadh, where duty-free operators and hospitality groups now source finished chocolate through verified single-origin contracts rather than commodity brokers.
Middle East and Africa Cocoa Products Market Segmentation
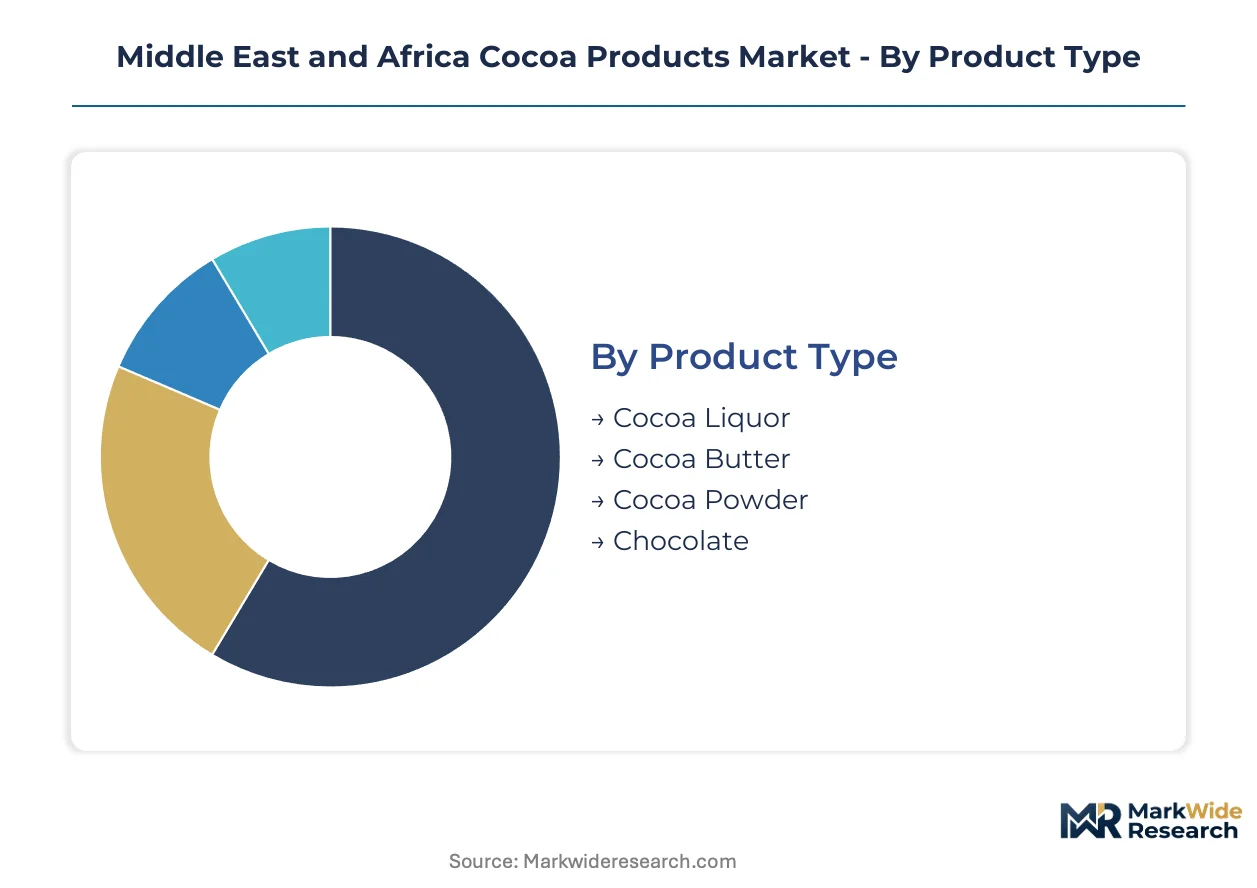
Segmentation in Middle East and Africa cocoa products reveals how temperature tolerance requirements and halal certification protocols reshape demand patterns across derivative categories. Product form, end-use application, and distribution pathway each carry distinct compliance burdens and margin structures that determine competitive positioning.
Product Type:
Volume concentrates in commodity-grade powder and liquor, while premium positioning clusters around specialized butter grades with defined polymorphism specifications.
- Cocoa Butter:Refined fat fraction with melting point between 34°C and 38°C enables tropical climate stability for confectionery mouthfeel. Nigerian and South African pharmaceutical manufacturers drive specialized demand for coating-grade material with precise crystal structure control. Temperature-sensitive supply chains concentrate procurement around verified cold-chain handlers.
- Chocolate:Finished confectionery absorbs volume through seasonal gifting cycles in Gulf retail networks, with premium shelf space expanding across Dubai and Riyadh duty-free channels. FSSAI-aligned import standards and Gulf Standards Organization halal certification tighten traceability requirements that favor integrated processors with dedicated quality laboratories.
- Cocoa Liquor:Fermented and roasted bean mass serves as foundational input for downstream processing across regional grinding facilities.
- Cocoa Powder:Defatted solids extend into bakery applications and regional dairy flavoring as processors expand flavored milk portfolios.
Today's leader: Chocolate. Tomorrow's challenger: Cocoa Butter.
End User:
Application maturity separates established food channels from emerging pharmaceutical specifications that command technical compliance premiums.
- Confectionery:Gulf retail networks and seasonal gifting cycles absorb finished chocolate volume through direct-to-hotel and direct-to-airport procurement relationships displacing traditional wholesale layers.
- Food & Beverage:Cocoa powder penetration into regional dairy flavoring opens absorption channels beyond traditional confectionery as processors build flavored milk portfolios.
- Pharmaceuticals:Coating-grade butter with polymorphism-controlled release profiles attracts specialized demand from manufacturers seeking tropical climate stability for drug delivery systems.
- Cosmetics:Shea butter substitution pressures authentic cocoa butter volume in cost-sensitive emollient formulations across the region.
Confectionery holds current volume dominance. Pharmaceutical coatings present the steepest expansion trajectory as regional drug manufacturers scale.
Packaging Type:
Format selection tracks supply chain position, with bulk industrial packaging dominating upstream and consumer formats concentrating at retail termination points.
- Bags:Multi-layer industrial sacks protect powder and liquor from moisture ingress during extended tropical transit.
- Boxes:Rigid secondary packaging supports premium chocolate presentation requirements in Gulf retail and hospitality procurement.
- Tubs:Airtight containers preserve butter integrity for cosmetic and pharmaceutical formulation customers with contamination-sensitive processes.
- Pouches:Flexible single-serve formats gain traction in direct-to-consumer channels and airline catering specifications.
Industrial bags anchor upstream logistics. Premium boxes capture downstream value in hospitality-serving segments.
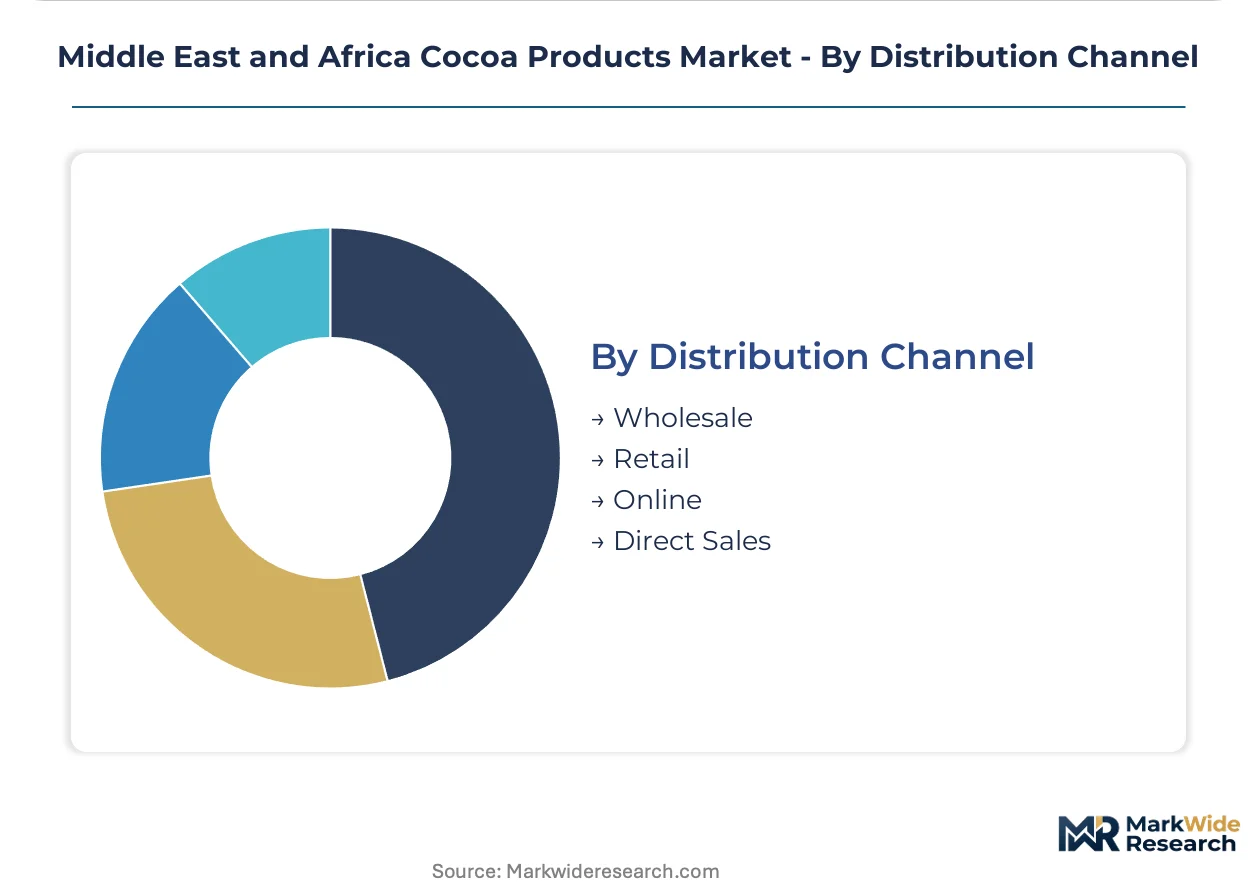
Distribution Channel:
Channel fragmentation accelerates as verified direct relationships displace layered intermediaries, particularly in premium segments.
- Wholesale:Traditional layered distribution retains commodity-grade powder and liquor volume but loses share in finished chocolate as procurement patterns shift.
- Direct Sales:Verified single-origin contracts now dominate Dubai and Riyadh duty-free and hospitality sourcing, displacing commodity brokers through batch-level halal compliance guarantees.
- Retail:Gulf supermarket networks expand premium chocolate shelf space while requiring digitized origin documentation that elevates compliance costs for informal traders.
- Online:E-commerce channels remain underdeveloped for temperature-sensitive derivatives but attract specialty and gifting segments with controlled logistics.
Direct sales command premium positioning. Wholesale retains commodity volume but faces margin compression.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Jebel Ali industrial corridor anchors cocoa processing capacity for Gulf distribution networks serving premium confectionery and pharmaceutical coating demand.
United Arab Emirates
Dubai's duty-free operators and hospitality groups now source finished chocolate through verified single-origin contracts rather than commodity brokers. Gulf Standards Organization halal certification mandates digitized origin documentation that elevates compliance costs for informal traders. Jebel Ali's cold-chain warehousing clusters enable temperature-sensitive butter derivatives to reach Saudi and Qatari markets without heat degradation.
Saudi Arabia
Seasonal gifting cycles compress procurement planning horizons for Riyadh-based confectionery distributors. Saudi Food and Drug Authority traceability mandates force processors to deploy blockchain-verified origin documentation systems. The Eastern Province's industrial zones host grinding facilities that supply pharmaceutical manufacturers seeking polymorphism-controlled coating materials.
South Africa
Refrigerated logistics networks enable temperature-sensitive cocoa derivatives to reach inland markets previously constrained by heat degradation. South African Department of Health food safety standards govern allergen disclosure and cross-contamination prevention across the value chain. Cape Town's port infrastructure anchors import flows for regional dairy processors expanding flavored milk portfolios.
Nigeria
Cold-chain distribution buildout concentrates demand for cocoa butter in pharmaceutical coating applications. The country's national food safety regulator aligns import protocols with digitized traceability requirements that favor integrated processors. Lagos industrial corridors host formulation facilities serving West African cosmetic manufacturers adopting shea butter substitutes.
Egypt
Regional chocolate manufacturing sustains volume absorption through Mars Incorporated's local operations. Egyptian agricultural export standards expand digital verification systems for origin documentation. Cairo-Alexandria logistics clusters enable butter and liquor shipments to Levantine markets requiring FSSAI-aligned compliance documentation.
Middle East and Africa Cocoa Products Market Competitive Landscape
Capacity expansion dominates the current landscape as integrated processors build dedicated quality laboratories to meet tightening halal certification protocols. The vendor base concentrates around three strategic tiers: multinational grinders with West African bean supply relationships, Gulf-based confectionery specialists with hospitality procurement networks, and regional dairy processors extending into cocoa powder applications. M&A activity and sustainability program deployment represent the dominant competitive vectors as operators seek traceable supply relationships with Ivorian and Ghanaian cooperatives.
Within the integrated processing tier, Barry Callebaut and Cargill exemplify archetypes leveraging upstream grinding assets and sustainability traceability programs respectively. Mars Incorporated occupies a position representing regional manufacturing commitment through Egypt-based chocolate operations. These three anchors illustrate how geographic footprint and certification infrastructure determine competitive positioning as Saudi Food and Drug Authority mandates elevate capital requirements for market access.
| Leading Market Players |
|---|
| Nestle S.A. |
| Mars Incorporated |
| Barry Callebaut |
| JB Foods Limited |
| Ferrero Group |
| Cargill |
| Mondelez International Inc. |
| Patchi |
| ADM |
| Others |
Supply & Pricing Matrix
Gulf retail procurement teams now mandate batch-level halal compliance documentation that forces suppliers to deploy dedicated quality laboratories and blockchain-verified traceability systems, compressing margins for informal traders while granting pricing power to integrated processors with captive certification infrastructure.
Pricing Analysis
Fermented bean supply fluctuations from Ivorian and Ghanaian cooperatives transmit directly into input cost instability that regional confectionery formulators must absorb or pass through. Pricing stratifies across premium, standard, and economy tiers based on Gulf Standards Organization halal certification grade and cold-chain integrity guarantees. Cost compression in commodity-grade powder and liquor segments is intensifying because shea butter substitution pressures authentic cocoa butter volume. Pharmaceutical manufacturers seeking polymorphism-controlled coating materials exhibit the least price sensitivity, while cost-sensitive cosmetic formulators demonstrate maximum elasticity to butter price movements.
Supply Chain Analysis
Refrigerated container freight from West African ports to Jebel Ali anchors logistics cost structures for temperature-sensitive butter derivatives. Supply concentrates in Côte d'Ivoire, Ghana, and Nigeria as the primary bean origination points, with grinding capacity clustering in Egypt and the UAE. The chain draws from fermented bean mass, refined butter fractions, and defatted powder solids as core inputs. Single-source vulnerability around Ivorian cooperative supply creates structural risk exposure. Distribution runs through verified direct sales relationships with Dubai duty-free operators and Riyadh hospitality groups, displacing traditional wholesale layers in premium segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pharmaceutical coating demand for polymorphism-controlled butter grades provides a stable compounding force as regional drug manufacturers scale tropical climate-stable drug delivery systems.
For Market Incumbents: Lock in exclusive supplier partnerships with Ivorian and Ghanaian cooperatives to secure traceable bean supply before Ethiopian highland regions achieve commercial scale. Defend margin position by investing in captive quality laboratories capable of batch-level halal certification that informal traders cannot replicate. Prioritize backward integration into cold-chain warehousing at Jebel Ali to control logistics chokepoints serving Saudi and Qatari markets. For New Entrants and Emerging Players: Saudi Food and Drug Authority traceability mandates in the Kingdom open a window for digital verification specialists to capture first-mover advantages with blockchain-enabled origin documentation systems. Target pharmaceutical coating-grade butter supply to Nigerian and South African drug manufacturers as the most penetrable premium segment. Pursue a go-to-market angle anchored in precision fermentation for bio-identical cocoa butter alternatives that circumvent tropical climate stability challenges. For Investors and Strategic Acquirers: Asymmetric upside sits with integrated processors combining West African grinding assets with Gulf-based certification infrastructure capable of serving both confectionery and pharmaceutical end-users. Over a five-to-ten year horizon, operators with end-to-end traceability systems will outcompete commodity traders as regulatory mandates harden. Target acquisition archetypes include Egyptian grinding facilities with Levantine market access and Lagos-based formulation houses serving West African cosmetic manufacturers. The signal to watch is Saudi Food and Drug Authority acceleration of digital verification timelines, which would abruptly devalue non-compliant inventory positions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cooperative Supply | Secures traceable Ivorian and Ghanaian bean flows ahead of Ethiopian commercialization. |
| Cold-Chain Infrastructure Expansion | Enables Jebel Ali-based processors to reach Saudi pharmaceutical manufacturers without heat degradation. |
| Halal Certification Laboratory Investment | Creates compliance moats that Gulf Standards Organization mandates render mandatory for market access. |
| Precision Fermentation Capability Buildout | Generates bio-identical butter alternatives that circumvent West African supply volatility. |
| Direct-to-Hospitality Distribution Pivot | Captures premium margin pools as Dubai and Riyadh duty-free operators displace commodity brokers. |
Research Methodology
Multiple input streams — primary interviews with grinding facility managers, Gulf retail procurement leads, and pharmaceutical formulation chemists; secondary validation through customs trade data, FSSAI regulatory filings, and Gulf Standards Organization certification records; plus SEC disclosures from listed processors — were reconciled through bottom-up volume triangulation against top-down value aggregation.
Data-stream reconciliation across product type, end-user application, and distribution channel dimensions enabled CAGR derivation through trend extrapolation and driver elasticity modeling across the analysis window. Forecast inputs incorporated cold-chain infrastructure deployment timelines, halal certification mandate evolution, and shea butter substitution elasticity in cosmetic formulations.
Revisions become necessary when Saudi Food and Drug Authority accelerates traceability timelines, Ivorian cooperative supply experiences climate-induced disruption, or precision fermentation alternatives achieve cost parity with bean-derived butter. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Smart Home Platforms Market
Others
Europe Transportation Management Systems Market
Others
Spend Analytics Market
Others
Banknote Printing Machine Market
Others
Molybdenum-99 Market
Others
Android STB and TV Market
Others
Technical Films Market
Others
Global Computer Peripherals Market
Others
Gesture Recognition for Smart TV Market
Others
Germany 3D Printing Construction Market
Others
Short Video Applications Market
Others
Asia-Pacific Air Separation Unit Market
Others
Griffin Beaker Market
Others
Transportation Lighting Market
Others
Commercial Aircraft Angle of Attack Sensors Market
Others
Industrial Wearable Devices Market