
 Smart Home Automation Market | 2026-2036
Smart Home Automation Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Home Automation Market Intelligence
The migration from proprietary hubs to open interoperability protocols built on Matter is rewriting how device ecosystems integrate across brands. Amazon.com Inc. leverages its Alexa voice platform and Ring hardware portfolio to anchor a vertically integrated smart home stack. Google LLC competes through Nest thermostats and Thread border routers that sustain deep Android ecosystem ties. Apple Inc. differentiates via HomeKit and its privacy-first architecture, which controls premium positioning among security-conscious homeowners.
Smart home automation encompasses networked devices, sensors, controllers, and software platforms that enable remote or autonomous management of residential environments through standardized communication protocols such as Zigbee mesh networking operating at 2.4 GHz with typical node ranges of 10–100 meters. The primary purpose spans security monitoring, climate optimization, energy load balancing, and assisted living support for aging populations. Lighting and security sensors command the largest installed base, while health monitoring applications represent the fastest-expanding segment as biometric wearables integrate with home hubs. Wi-Fi retains dominance for high-bandwidth entertainment applications, though Zigbee and Z-Wave are displacing it in battery-powered sensor networks where power efficiency determines device longevity.
The Federal Communications Commission governs radio-frequency emissions for wireless home devices in the United States, while the EU Cyber Resilience Act imposes mandatory security update obligations and vulnerability disclosure timelines for connected products sold in Europe. These frameworks shape demand by raising compliance costs for entrants and favoring established vendors with dedicated certification resources. Stakeholders must monitor whether fragmented national cybersecurity labeling schemes converge toward mutual recognition or perpetuate market access barriers that advantage regionally entrenched suppliers.
Market Dynamics
The migration from proprietary hubs to open interoperability protocols built on Matter is rewriting how device ecosystems integrate across brands, forcing vendors to abandon closed architectures in favor of unified connectivity standards.
Growth Catalysts
- EU Cyber Resilience Act:Mandatory security update obligations and vulnerability disclosure timelines accelerate compliance investments by hardware vendors, raising barriers for entrants while favoring established suppliers with dedicated certification resources.
- Utility-sponsored energy management programs:United States electricity providers deploy demand-response platforms that subsidize smart thermostat and load-control device installations, directly reducing homeowner acquisition costs.
- Thread border router proliferation:Low-power mesh networking at 2.4 GHz enables battery-operated sensors to achieve multi-year lifespans, displacing Wi-Fi in residential security and climate monitoring applications.
Market Restraints
- Silicon supply concentration:Zigbee and Thread radio chip fabrication concentrates among a limited set of foundry operators, exposing device manufacturers to lead-time volatility and allocation constraints.
- Interoperability certification costs:Matter compliance testing and logo licensing impose five-figure expenditures per product variant, compressing margins for low-volume hardware entrants.
- Consumer substitution toward standalone devices:Smartphone-based security cameras and voice assistants reduce perceived need for integrated hub-based systems in rental housing segments.
Strategic Opportunities
- Aging-in-place assisted living:Fall-detection sensors and biometric wearables integrating with home hubs address Japan's demographic compression, creating demand for predictive health monitoring platforms.
- Insurance-linked security incentives:United States property underwriters offer premium discounts for professionally monitored smart home systems, converting cost-sensitive homeowners into recurring-service subscribers.
- Matter-over-Thread convergence:Unified application-layer protocol eliminates gateway fragmentation, enabling multi-brand retail bundles that reduce consumer configuration friction.
Industry Challenges
- Embedded systems firmware engineering scarcity:Battery-constrained device development requires specialized expertise in real-time operating systems and radio power management, tightening talent acquisition for mid-tier vendors.
- Multi-protocol certification timelines:Simultaneous Zigbee, Thread, and Wi-Fi qualification extends product launch schedules by six to nine months, delaying revenue recognition against fixed R&D burn rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Home Automation Market |
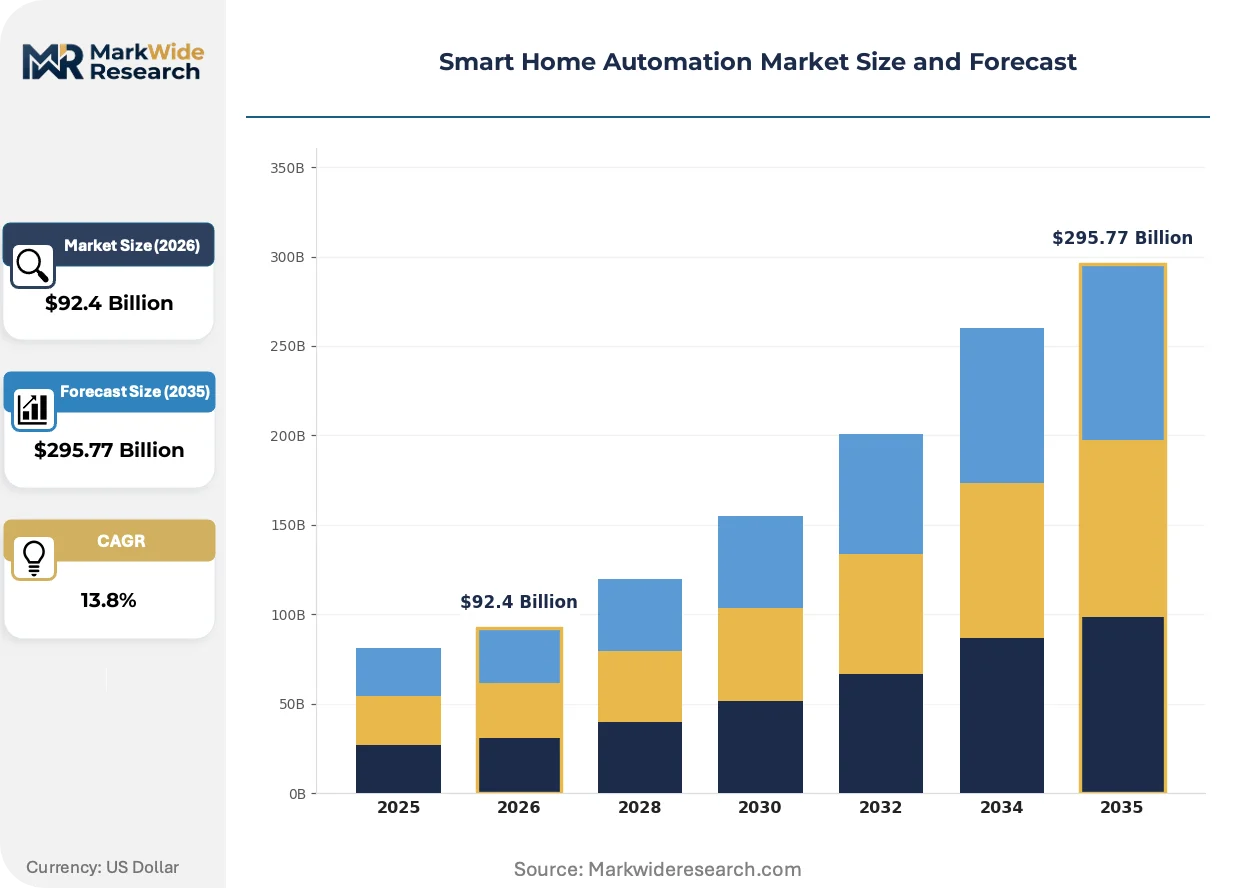
| Market Size in 2026 | $92.4 Billion |
| Market Size in 2035 | $295.77 Billion |
| CAGR (2026 – 2036) | 13.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lighting, Security Sensors, Thermostats, Smart Speakers Technology: Wi-Fi, Zigbee, Z-Wave, Bluetooth Customer Type: Homeowners, Tenants, Builders, Property Managers Application: Home Security, Energy Management, Entertainment, Health Monitoring |
| Companies Covered | Amazon.com Inc., Google LLC, Apple Inc., Samsung Electronics Co. Ltd., Honeywell International Inc., Schneider Electric SE, Johnson Controls International plc, Siemens, Robert Bosch GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Home Automation Market Strategic Shifts & Innovations
Artificial intelligence inference at the network edge is compressing response latency for voice recognition and anomaly detection, eliminating cloud round-trips that previously constrained real-time home automation performance.
Edge AI accelerators embedded in smart speakers and security cameras is digitizing acoustic and visual pattern recognition, enabling local processing of wake-word detection and occupancy sensing. Residential security installers in the United States specify these devices for latency-sensitive perimeter monitoring. The shift is digitizing competitive differentiation away from cloud subscription tiers toward on-device capability depth.
The EU Cyber Resilience Act imposes mandatory security update obligations spanning the full product lifecycle for connected devices sold in Europe. Hardware vendors must maintain vulnerability disclosure channels and patch distribution infrastructure for minimum support periods. European smart home manufacturers are responding by shortening hardware revision cycles and embedding over-the-air update capabilities as standard features.
Homeowners increasingly expect seamless handoff between professional installation and self-managed expansion, blurring the historical split between dealer-channel and retail-channel purchasing. United States builder-grade pre-installation packages now ship with consumer-accessible expansion ports, allowing residents to add devices without truck rolls. This hybrid ownership model concentrates in new construction segments where initial system specification locks in long-term accessory purchasing patterns.
Smart Home Automation Market Segmentation
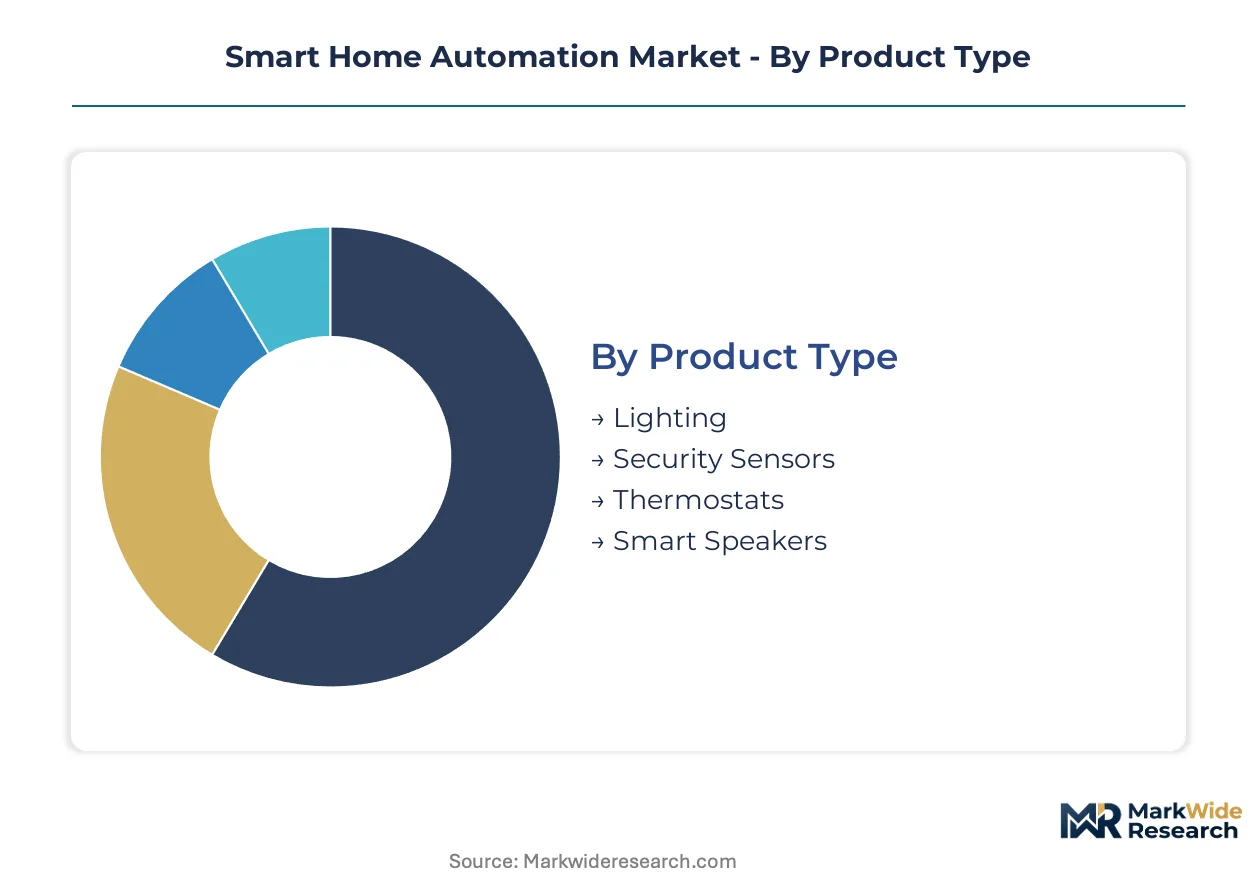
Smart home automation vendors configure product portfolios around distinct technical specifications, buyer economics, and installation contexts. Segmentation clarity determines pricing architecture, channel strategy, and compliance investment priorities across hardware ecosystems.
Product Type:
Cost tier stratification separates commodity hardware from premium integrated systems with professional monitoring tie-ins.
- Lighting:LED fixture controllers and tunable white systems dominate unit volumes. Demand clusters in United States new construction where builder pre-installation packages lock in long-term accessory purchasing. Energy rebate programs in California and Texas accelerate retrofit adoption.
- Security Sensors:Door-window contacts, motion detectors, and glass-break sensors form the core of monitored home security. United States property insurers offer premium discounts for professionally installed systems, converting hardware sales into recurring service subscriptions. Matter-over-Thread convergence is displacing proprietary wireless protocols.
- Thermostats:Utility-sponsored demand-response platforms subsidize device costs.
- Smart Speakers:Voice-first control hubs anchor ecosystem lock-in for platform vendors.
Security Sensors hold installed capacity. Lighting is rotating up the share rankings.
Technology:
Radio protocol selection governs power budget, range, and interoperability certification burden for device engineers.
- Wi-Fi:High-bandwidth protocol retains dominance for video streaming and firmware updates. Entertainment applications in United States households drive sustained deployment despite battery drain limitations. FCC Part 15 emissions compliance adds regulatory overhead.
- Zigbee:Mesh networking at 2.4 GHz enables multi-year battery life for sensors. European deployment concentrates in Germany and France where CE marking and EU Cyber Resilience Act obligations favor established vendors with dedicated certification resources.
- Z-Wave:Sub-GHz spectrum avoids 2.4 GHz congestion in dense urban installations.
- Bluetooth:Low-energy variants support proximity-based device commissioning and temporary guest access.
Wi-Fi holds installed capacity. Zigbee is rotating up the share rankings.
Customer Type:
Buyer identity shapes purchase authority, financing method, and expected ownership duration for automation systems.
- Homeowners:Permanent residents prioritize whole-system integration with insurance-linked security incentives. United States single-family detached housing generates the highest per-dwelling equipment spend. Aging-in-place applications drive health monitoring attachment rates.
- Builders:Production home developers specify pre-installed automation packages to differentiate new construction. North American builder-grade systems now ship with consumer-accessible expansion ports, enabling resident self-management without truck rolls.
- Tenants:Rental housing constraints favor portable standalone devices over permanent fixture installation.
- Property Managers:Multi-dwelling unit operators seek centralized control platforms for common area energy management.
Homeowners hold installed capacity. Builders is rotating up the share rankings.
Application:
Use case maturity determines whether deployments prioritize standalone functionality or deep ecosystem integration.
- Home Security:Perimeter monitoring and intrusion detection command the largest installed device base. Professional monitoring services in United States markets generate recurring revenue that subsidizes upfront hardware costs. Edge AI accelerators in cameras enable local anomaly detection without cloud latency.
- Health Monitoring:Fall-detection sensors and biometric wearable integration address Japan's demographic compression. Biometric data pipelines integrating with home hubs represent the steepest expansion trajectory as predictive analytics migrate to residential settings.
- Energy Management:Utility demand-response programs subsidize smart thermostat adoption.
- Entertainment:Whole-home audio and unified remote control maintain steady replacement demand.
Home Security holds installed capacity. Health Monitoring is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese smart home device manufacturers export Zigbee and Thread radio modules to European and North American assembly facilities, creating a trade-flow corridor that concentrates silicon sourcing risk while enabling regional customization.
United States
Utility-sponsored demand-response platforms subsidize smart thermostat installations while property insurers offer premium discounts for professionally monitored security systems. The FCC governs radio-frequency emissions under Part 15 rules. Silicon Valley and Austin clusters anchor software platform development and edge AI accelerator integration.
Germany
CE marking and EU Cyber Resilience Act obligations favor established vendors with dedicated certification resources. The KBA and federal network agency shape device approval timelines. Bavaria and Baden-Württemberg industrial zones concentrate HVAC controller manufacturing and Thread border router assembly.
China
MIIT standards and GB certification frameworks govern domestic device interoperability while export-oriented foundries supply Zigbee radio chips globally. MIIT and SAMR regulate network security mandates. Shenzhen and Dongguan manufacturing clusters dominate sensor module fabrication and Matter protocol testing.
Japan
Aging-in-place applications drive demand for fall-detection sensors and biometric wearable integration with home hubs. METI promotes energy efficiency standards for residential automation. Tokyo and Osaka metropolitan areas concentrate predictive health monitoring platform development.
United Kingdom
Building regulations for new construction increasingly mandate pre-installed automation packages with consumer-accessible expansion ports. The Information Commissioner's Office and product safety regulators enforce data protection for connected devices. London and Cambridge clusters anchor smart speaker software development and voice recognition engineering.
Smart Home Automation Market Key Industry Players
Channel-controlling players compete with product-specialist players for installation footprint and consumer mindshare. The vendor base concentrates around three tiers: ecosystem-anchoring technology platforms, industrial conglomerates with building-automation heritage, and component-specialist hardware vendors. Strategic moves center on Matter protocol certification acceleration and insurance-channel partnership formation.
Among ecosystem-anchoring technology platforms, Amazon.com Inc., Google LLC, and Apple Inc. occupy positions that exemplify voice-first control hub strategies. Amazon leverages Alexa platform reach and Ring hardware integration. Google sustains Android ecosystem ties through Nest thermostats and Thread border routers. Apple differentiates via privacy-first HomeKit architecture. These three represent distinct competitive vectors: retail-channel scale, mobile OS integration depth, and premium security positioning.
| Leading Market Players |
|---|
| Amazon.com Inc. |
| Google LLC |
| Apple Inc. |
| Samsung Electronics Co. Ltd. |
| Honeywell International Inc. |
| Schneider Electric SE |
| Johnson Controls International plc |
| Siemens |
| Robert Bosch GmbH |
| Others |
Cost & Logistics Intelligence
Shenzhen's radio module manufacturing clusters determine pricing power for Matter-compliant device vendors across North America and Europe, as foundry allocation constraints tighten during protocol migration waves. Component scarcity at these hubs transmits directly into hardware margin compression for mid-tier automation suppliers lacking long-term silicon contracts.
Pricing Analysis
Legacy Zigbee 3.0 hardware, current Matter-over-Thread devices, and next-generation edge-AI sensor platforms occupy distinct pricing bands separated by certification tier and local processing capability. Three-tier pricing structure across premium, standard, and economy levels reflects UL cybersecurity certification status and professional monitoring bundling. Pricing pressure stems from Matter compliance testing costs that compress margins for low-volume entrants. Tenants in rental housing exhibit highest price sensitivity, while aging-in-place homeowners accept premium positioning for health monitoring integration.
Supply Chain Analysis
Extended payment terms from Shenzhen and Dongguan module suppliers now stretch to ninety days as foundries prioritize high-volume platform vendors over niche hardware entrants. China, Taiwan, and Vietnam concentrate Zigbee radio chip fabrication and Thread border router assembly. Supply chains draw from silicon wafers, lithium coin cells, and injection-molded enclosures. Single-source vulnerability concentrates in 2.4 GHz radio chip fabrication. Distribution runs through Amazon and big-box retail for consumer self-install, with professional security dealers capturing monitored system channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hardware margins flatten while recurring service revenue from professional monitoring and utility demand-response programs accelerates faster than device sales. This service-attach dynamic repositions automation vendors as subscription platforms rather than equipment suppliers.
For Market Incumbents: Insulate ecosystem lock-in by accelerating Matter certification for entire product portfolios before compliance costs rise further. Acquire Thread border router specialists to secure gateway control points. Vertical integration into firmware development teams addresses embedded systems engineering scarcity threatening product launch timelines. For New Entrants and Emerging Players: Build out white-label health monitoring sensor lines for Japanese aging-in-place deployments where predictive analytics integration remains underdeveloped. Target Germany's CE marking and EU Cyber Resilience Act compliance services gap for mid-tier manufacturers lacking dedicated certification resources. Partner with United States property insurers to embed hardware into premium discount programs. For Investors and Strategic Acquirers: Long-term, this sits as a platform consolidation play because Matter protocol convergence eliminates gateway fragmentation and concentrates value capture among ecosystem-anchoring vendors. Target acquisition archetypes include edge-AI accelerator specialists and regional security monitoring service operators. Monitor Thread border router shipment volumes as inflection signal for protocol transition velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Matter Certification Acceleration | First-mover certification locks in retail shelf placement before compliance costs escalate. |
| Insurance Channel Partnership | United States property underwriter alliances convert hardware into recurring monitoring subscriptions. |
| Edge AI Hardware Integration | On-device inference capability differentiates premium tiers from cloud-dependent alternatives. |
| Utility Demand-Response Integration | Subsidized thermostat programs reduce customer acquisition costs in regulated energy markets. |
| Aging-in-Place Platform Development | Fall-detection and biometric wearable integration addresses Japan's demographic compression. |
Research Approach
Desk research of regulatory filings, customs trade databases, and hyperscaler hardware capex disclosures preceded structured interviews with smart home platform engineers, professional security installers, utility demand-response program managers, and CE marking consultants. Primary fieldwork with device manufacturers and retail category buyers validated secondary estimates. Bottom-up unit shipment modeling triangulated against top-down service revenue projections.
Assumptions held fixed include Matter protocol adoption velocity, EU Cyber Resilience Act enforcement timelines, and United States utility rebate program continuity across the analysis window. Segmentation dimensions modeled encompass radio protocol type, customer archetype, application use case, and regional regulatory cluster. CAGRs derived from logistic diffusion curves fitted to historical technology substitution patterns, with edge AI attach rates and professional monitoring penetration as key forecast inputs.
Stress conditions across silicon allocation volatility, tariff regime shifts, and cybersecurity incident frequency were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions. Macroeconomic contraction, regulatory divergence, or breakthrough battery technology would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automation
RFID Kanban Systems Market
Automation
Global Remote Monitoring and Control Market
Automation
Global Business Process Automation Software Market
Automation
Industrial Vending Machines Market
Automation
IoT Home Automation Market
Automation
Global Direct Mail Automation Software Market
Automation
Global Warehouse Barcode System Market
Automation
Distributed Control System Market
Automation
Automation Lifecycle Services Market
Automation
Computer Numerical Control Market
Automation
Global Cloud Automation Market
Automation
Data Center Automation Market
Automation
Playout Automation Market
Automation
Recruiting Automation Software Market
Automation
Task-Level Labor Planning and Workforce Orchestration for Fulfillment Market
Automation
Lab Automation Market