
 APAC Smart Home Market | 2026-2036
APAC Smart Home Market Size, Share, and Industry Trends Forecast 2026-2036
APAC Smart Home Market Insights
Online retail channels across Southeast Asia and India is fragmenting as platform-specific ecosystems emerge, pulling consumer electronics away from unified marketplaces. Samsung Electronics leverages its proprietary SmartThings platform to anchor premium appliance sales through direct digital storefronts. Xiaomi Corporation competes on cost-optimized device bundles distributed through its Mi Home app ecosystem, dominating entry-level automation penetration.
APAC smart home technology encompasses networked residential systems integrating sensors, actuators, and communication protocols to automate lighting, climate, security, and appliance control, typically operating through centralized hubs or cloud-connected mobile interfaces with latency requirements below 100 milliseconds for real-time responsiveness. Smart Security Systems and Smart Lighting command the largest installed bases due to immediate safety and energy cost benefits for homeowners. Wi-Fi technology leads connectivity deployments for its ubiquity, though Zigbee gains traction in multi-device installations where mesh networking reduces bandwidth congestion.
China's MIIT enforces GB standards for IoT device cybersecurity, while India's BIS mandates compulsory registration for wireless smart home products before domestic sale. Japan's METI promotes interoperability through JIS standards for home energy management systems, creating compliance layers that shape product development roadmaps. Stakeholders must monitor evolving cross-border data localization rules that could fragment cloud-dependent service architectures across the region.
Market Dynamics
Real estate developers across China and Southeast Asia are embedding pre-installed smart home infrastructure into new residential towers, creating a structural pull that shifts device procurement from retail consumers to construction-phase B2B contracts and locking in ecosystem choices years before occupancy.
Growth Catalysts
- India's PLI scheme for electronics manufacturing:Production-linked incentives accelerate local assembly of connected sensors and control hubs, reducing import dependency and shortening supply chains for domestic brands.
- Smart Security Systems demand:Tier-one city households in China prioritize integrated surveillance and access control, driving bundled hardware-software subscriptions with recurring revenue streams.
- Wi-Fi 6E protocol adoption:Lower latency and higher device density support real-time responsiveness for climate and lighting automation in multi-room installations.
Market Restraints
- Semiconductor input cost volatility:Memory chip and microcontroller pricing fluctuations compress margins for mid-tier device manufacturers dependent on external foundries.
- Supply concentration in coastal China:Component sourcing clusters in Guangdong and Jiangsu provinces create geographic vulnerability to logistics disruptions and regional lockdowns.
- GB standards cybersecurity friction:China's MIIT mandatory certification timelines extend product launch cycles by four to six months for foreign entrants.
Strategic Opportunities
- Underpenetrated Indian tier-two cities:Rising disposable incomes and urban housing stock expansion create first-mover advantage for localized automation bundles priced below premium imports.
- Matter protocol convergence:Cross-platform interoperability between Zigbee and Wi-Fi ecosystems reduces consumer lock-in and enables multi-brand installations.
- Direct-to-builder channel innovation:Bypassing retail entirely, vendors secure multi-year maintenance contracts with property developers during construction phase.
Industry Challenges
- Embedded systems firmware talent scarcity:Shortage of engineers skilled in low-power wireless stack development delays product iteration cycles for regional startups.
- BIS wireless certification backlog:India's compulsory registration scheme for radio-frequency devices creates queue delays that stall market entry timelines.
- Legacy electrical infrastructure incompatibility:Retrofit installations in older Japanese and Korean housing stock require costly rewiring that deters automation adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APAC Smart Home Market |
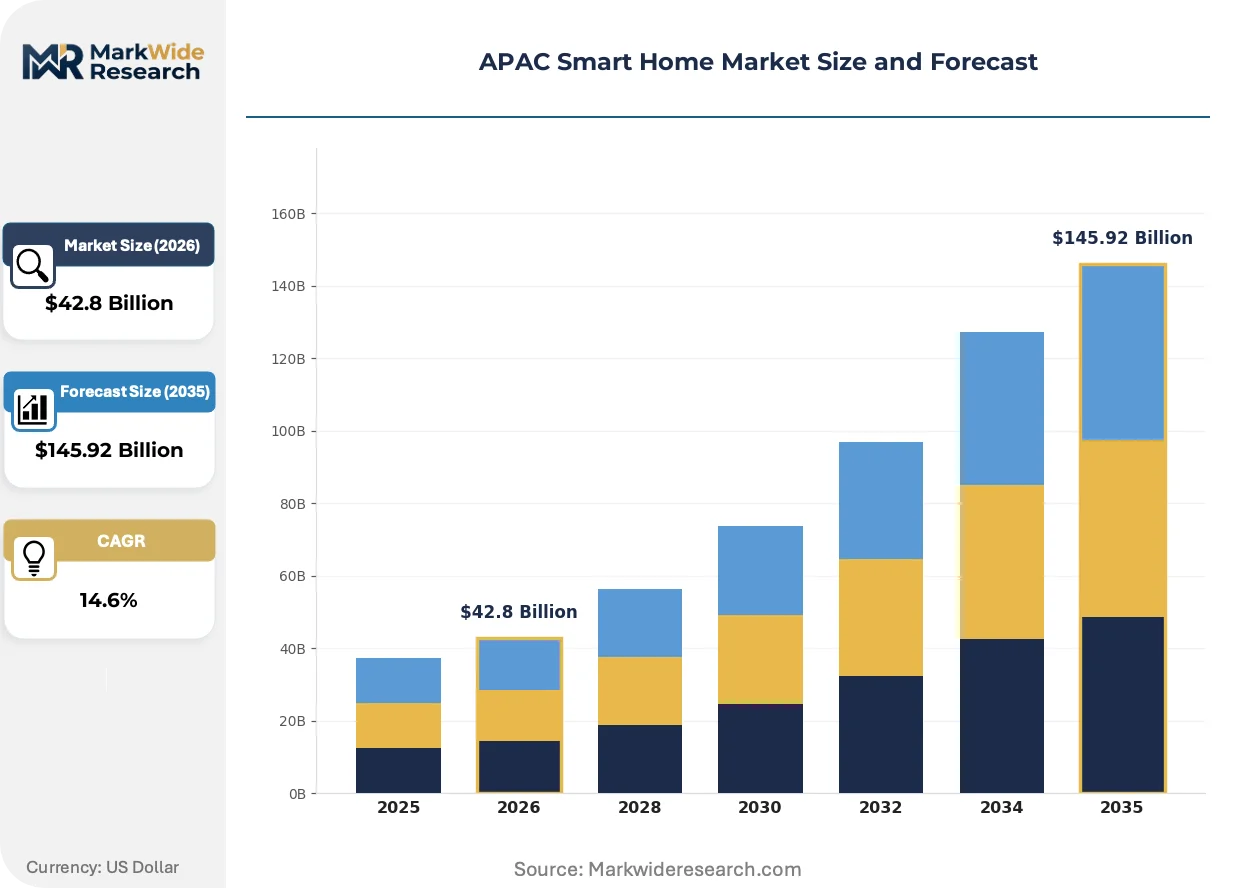
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $145.92 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Lighting, Smart Thermostats, Smart Security Systems, Smart Appliances Technology: Wi-Fi, Zigbee, Z-Wave, Bluetooth End User: Residential, Rental Properties, Real Estate Developers, Home Automation Enthusiasts Distribution Channel: Online Retail, Specialty Stores, Wholesalers, Direct Sales |
| Companies Covered | Samsung Electronics, LG Electronics, Xiaomi Corporation, Haier Group Corporation, Honeywell International, Schneider Electric SE, Siemens AG, Midea Group, Panasonic Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APAC Smart Home Market Trends and Innovations
Protocol unification and edge computing architectures are compressing the traditional hub-and-cloud model, enabling local processing that reduces dependency on persistent internet connectivity and cross-border data flows.
Thread mesh networking combined with border router functionality is rendering obsolete the single-point-of-failure hub architecture that dominated early smart home deployments. Japanese and Korean apartment developers now specify Thread-native devices in new construction specifications. This shift compresses hardware BOM costs by eliminating dedicated hub silicon while improving failover resilience.
Japan's METI JIS standards for home energy management systems now mandate interoperability between solar inverters, battery storage, and load controllers. Manufacturers must certify cross-brand communication protocols before receiving construction subsidies. Residential projects in Tokyo and Osaka metropolitan areas face the tightest compliance deadlines, accelerating firmware updates across installed device bases.
Builder procurement teams now specify outcome-based performance contracts rather than discrete hardware purchases, tying vendor payments to achieved energy savings and system uptime metrics. Southeast Asian property developers in Vietnam and Indonesia lead this shift, displacing traditional distributor markups with direct manufacturer relationships. This model concentrates purchasing power among fewer buyers and extends payment terms to post-occupancy verification.
APAC Smart Home Market Segmentation
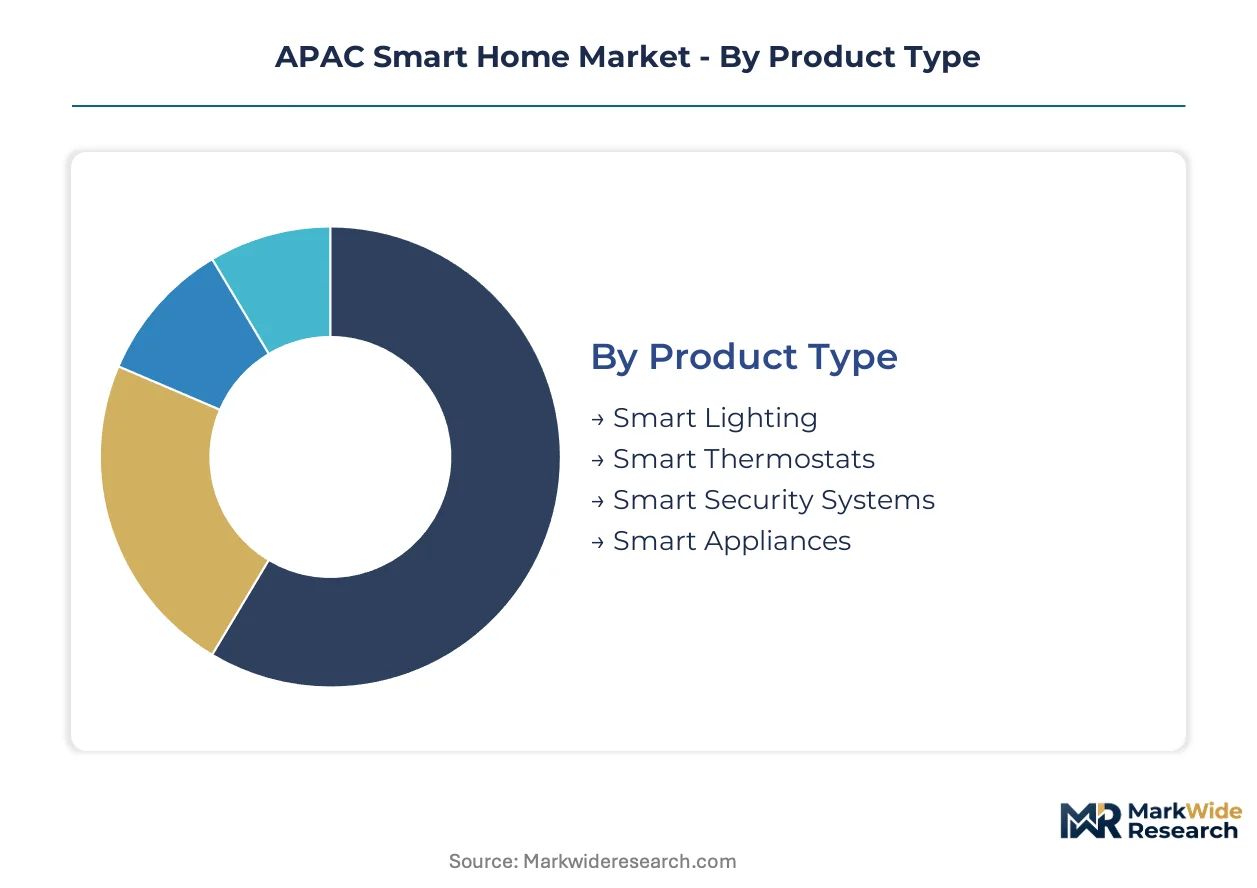
Segmentation across APAC smart home markets reveals how procurement patterns diverge between retail consumers and institutional buyers. Technology choices and distribution channels fragment sharply between China's tier-one cities and India's emerging urban corridors.
Product Type:
Smart home deployments span a use-case spectrum from single-device convenience to whole-home automation, with safety and energy applications commanding earliest adoption.
- Smart Lighting:LED fixtures with dimming, color temperature control, and scheduling capabilities integrate with ambient sensors for daylight harvesting. Demand concentrates in Japanese and Korean apartment renovations where retrofit bulb replacements bypass rewiring costs.
- Smart Thermostats:Climate controllers with occupancy sensing and weather-responsive algorithms reduce HVAC energy consumption. China's tier-one cities drive procurement as MIIT efficiency standards tighten for new construction, though legacy split-system incompatibility limits retrofit penetration.
- Smart Security Systems:Integrated surveillance cameras, door sensors, and cloud storage subscriptions anchor bundled service offerings across Southeast Asian condominiums.
- Smart Appliances:Refrigerators, washing machines, and cooking equipment with remote monitoring and predictive maintenance alerts target premium residential segments in Australia and Singapore.
The dominant share belongs to Smart Security Systems, while Smart Lighting is closing the gap fastest.
Technology:
Protocol selection reflects trade-offs between bandwidth requirements, mesh reliability, and device density tolerance across multi-room installations.
- Wi-Fi:Ubiquitous IP-based connectivity leverages existing router infrastructure without dedicated hubs. China's coastal manufacturing clusters produce cost-optimized modules that dominate entry-level device BOMs, though 2.4GHz congestion degrades performance in high-density apartment blocks.
- Zigbee:Low-power mesh networking enables battery-operated sensors with multi-year lifespans. Indian smart city pilots in Pune and Hyderabad specify Zigbee for streetlight-to-residence integration, creating procurement pull for compatible indoor ecosystems.
- Z-Wave:Sub-GHz spectrum avoids Wi-Fi interference in Japanese residential deployments where 920MHz band allocation supports whole-building automation without cross-protocol contention.
- Bluetooth:Point-to-point pairing dominates wearable-adjacent devices and temporary guest access scenarios with minimal infrastructure requirements.
Wi-Fi commands installed volume leadership, yet Zigbee expands most quickly in multi-device commercial specifications.
End User:
Customer archetypes range from price-sensitive individual purchasers to institutional buyers with multi-year maintenance horizons and outcome-based contracting preferences.
- Residential:Individual homeowners purchasing through retail channels prioritize smartphone app integration and voice assistant compatibility for convenience automation.
- Rental Properties:Landlords in Australian and New Zealand urban markets deploy minimal sensor packages for energy compliance reporting and vacancy monitoring without tenant-facing complexity.
- Real Estate Developers:Vietnamese and Indonesian construction firms now specify pre-installed infrastructure with performance-based vendor payments tied to post-occupancy verification.
- Home Automation Enthusiasts:Early adopters in South Korea and Japan drive demand for Thread-native devices and Matter protocol interoperability across multi-brand installations.
Real Estate Developers capture procurement volume concentration, while Home Automation Enthusiasts push protocol standardization fastest.
Distribution Channel:
Channel structure shifts from fragmented retail toward direct manufacturer relationships as builder procurement teams consolidate purchasing power.
- Online Retail:Platform-specific ecosystems fragment across Southeast Asia as Shopee, Lazada, and proprietary app stores displace unified marketplaces with exclusive device bundles.
- Specialty Stores:Physical showrooms in Singapore and Hong Kong demonstrate integrated room scenarios, converting high-consideration purchasers through tactile experience.
- Wholesalers:Traditional distributor networks retain relevance in India's tier-two cities where local installer relationships determine brand selection for first-time automation buyers.
- Direct Sales:Manufacturer-to-builder contracts eliminate margin stacking in Vietnam and Indonesia, with payment terms extending to post-occupancy performance verification.
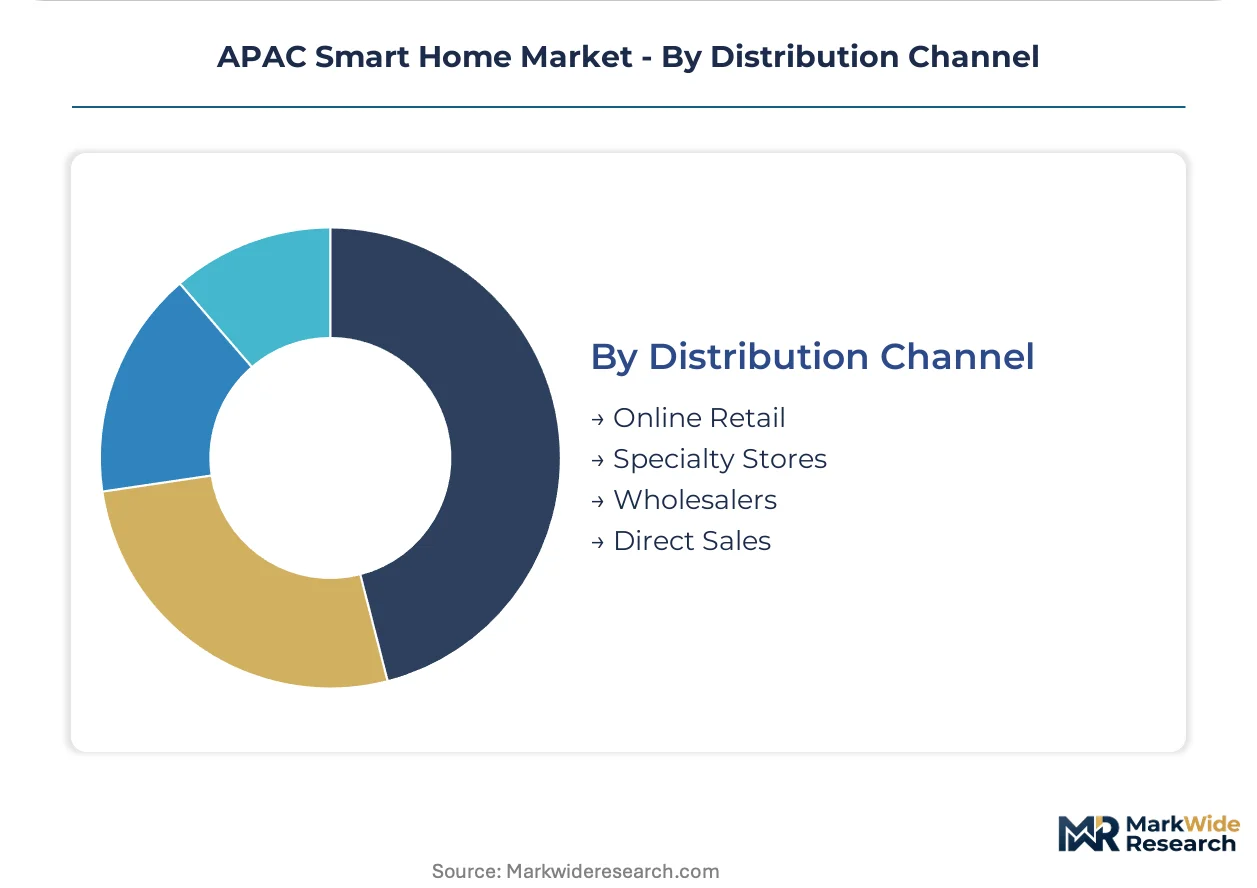
Direct Sales is gaining share fastest among institutional buyers, though Online Retail retains volume leadership in consumer segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme for electronics manufacturing is accelerating local assembly of connected sensors and control hubs. China's MIIT enforces GB standards for IoT device cybersecurity, creating compliance layers that shape product development roadmaps. Japan's METI promotes interoperability through JIS standards for home energy management systems.
China
Tier-one city households prioritize integrated surveillance and access control systems. MIIT mandatory certification timelines extend product launch cycles by four to six months for foreign entrants. Guangdong and Jiangsu provinces concentrate component sourcing clusters, creating geographic vulnerability to logistics disruptions.
India
Rising disposable incomes in tier-two cities create first-mover advantage for localized automation bundles. BIS mandates compulsory registration for wireless smart home products before domestic sale, creating queue delays that stall market entry timelines. Pune and Hyderabad smart city pilots specify Zigbee for streetlight-to-residence integration.
Japan
Residential projects in Tokyo and Osaka metropolitan areas face the tightest compliance deadlines for METI JIS standards. METI mandates interoperability between solar inverters, battery storage, and load controllers before construction subsidies are released. Kanto and Kansai regions drive Thread-native device specifications in new apartment developments.
South Korea
Early adopters push demand for Matter protocol interoperability across multi-brand installations. Legacy electrical infrastructure in older housing stock requires costly rewiring that deters automation adoption. Seoul Capital Area concentrates procurement for premium integrated room scenarios.
Vietnam
Property developers specify pre-installed infrastructure with performance-based vendor payments tied to post-occupancy verification. Direct manufacturer-to-builder contracts eliminate margin stacking and extend payment terms. Construction firms in Ho Chi Minh City and Hanoi lead outcome-based contracting adoption.
APAC Smart Home Market Competitive Landscape
On the supply side, the industry is structured around three distinct tiers. Premium-tier vendors anchor ecosystem plays through proprietary platforms, while mid-tier specialists compete on cost-optimized device bundles. Entry-level manufacturers leverage coastal China production clusters for module cost advantages. Strategic moves concentrate on direct-to-builder channel innovation and cross-platform interoperability certification.
Within the premium-tier ecosystem, Samsung Electronics and LG Electronics exemplify platform-centric positioning through proprietary smart home architectures. Xiaomi Corporation occupies a position in the cost-optimized bundle segment, leveraging direct digital storefronts and app ecosystem distribution. Panasonic Corporation represents the integrated appliance specialist archetype, anchoring multi-device installations through construction-phase specifications.
| Leading Market Players |
|---|
| Samsung Electronics |
| LG Electronics |
| Xiaomi Corporation |
| Haier Group Corporation |
| Honeywell International |
| Schneider Electric SE |
| Siemens AG |
| Midea Group |
| Panasonic Corporation |
| Others |
Pricing and Supply Chain Analysis
Semiconductor input cost volatility compresses margins across device tiers while simultaneously forcing supply chain consolidation toward vertically integrated coastal China clusters that dominate microcontroller and memory chip sourcing. This dual pressure widens pricing spreads between premium certified products and uncertified entry-level alternatives.
Pricing Analysis
Certification level under MIIT GB standards creates the primary spread between premium and economy tiers, with foreign entrants absorbing four-to-six month compliance delays that domestic manufacturers avoid. Three-tier pricing structure across premium, standard, and economy levels reflects bundle complexity, after-sales service attachment, and protocol interoperability breadth. Cost compression in mid-tier Wi-Fi modules intensifies as Chinese coastal foundries expand capacity, squeezing specialists dependent on external fabrication. Real estate developers exhibit lowest price sensitivity due to outcome-based contracting, while individual retail consumers in India's tier-two cities drive hardest bargain hunting.
Supply Chain Analysis
Memory chip feedstock from Taiwan and South Korea combines with microcontroller silicon from coastal China to anchor component costs for connected device manufacturers. Raw material dependencies span lithium-ion cells for battery-operated sensors, rare earth elements for RF modules, and copper substrates for PCB fabrication. Single-source vulnerability concentrates in Guangdong and Jiangsu province clusters, exposing procurement timelines to regional logistics disruptions. Distribution runs through direct manufacturer-to-builder contracts in Vietnam and Indonesia, displacing traditional wholesaler networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hardware-software subscription bundles now expand faster than standalone device sales, transforming procurement economics toward recurring revenue models with multi-year maintenance horizons.
For Market Incumbents: Harden ecosystem lock-in through Thread-native device certification and exclusive construction-phase specifications with Vietnamese and Indonesian developers. Defend against Matter protocol convergence by accelerating proprietary platform feature releases. Deepen backward integration into microcontroller design to offset foundry pricing volatility.
For New Entrants and Emerging Players: India's tier-two cities offer whitespace penetration with localized automation bundles priced below premium import alternatives. Target Zigbee-compatible installations in Pune and Hyderabad smart city corridors where municipal procurement creates anchor demand. Pursue wholesaler partnerships in South Indian states where installer relationships determine brand selection.
For Investors and Strategic Acquirers: The market sits at a protocol consolidation phase that favors vertically integrated platform specialists over point-solution hardware vendors. Five-to-ten year viability hinges on recurring service attachment rates exceeding hardware depreciation cycles. Monitor BIS certification queue lengths as inflection indicator for Indian market entry timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Builder Channel Development | Bypasses distributor markups and locks multi-year maintenance contracts with Vietnamese construction firms. |
| Matter Protocol Certification Investment | Enables cross-platform interoperability that reduces consumer lock-in and expands addressable installation base. |
| Backward Integration into Microcontroller Design | Captures margin from memory chip and sensor silicon production concentrated in Guangdong province clusters. |
| Hardware-Subscription Bundle Launch | Transforms transactional device sales into recurring revenue streams with cloud storage and predictive maintenance. |
| Indian PLI Scheme Manufacturing Localization | Qualifies for production-linked incentives while shortening supply chains for domestic tier-two city distribution. |
Research Methodology
The analysis maps smart lighting, security systems, climate control, and appliance connectivity segments, each validated through construction procurement officers, smart home platform engineers, electronics manufacturing executives, and real estate development leads. Primary interview data triangulates against MIIT regulatory filings, BIS registration databases, METI subsidy disbursement records, and customs trade statistics. Bottom-up device shipment estimates reconcile with top-down construction pipeline valuations across the analysis window.
Assumption sets held regulatory certification timelines and protocol adoption curves fixed while varying semiconductor pricing scenarios and builder procurement penetration rates. Segmentation dimensions span product type, connectivity protocol, end-user archetype, and distribution channel, with regional regulatory clusters as cross-cutting layer. CAGRs derive from installed base growth rates adjusted for replacement cycles and new construction absorption. Forecast inputs incorporate Zigbee mesh density specifications and Thread border router deployment timelines.
Practitioners should monitor MIIT cybersecurity standard revisions and BIS queue processing speeds for early signals of competitive entry barrier shifts. Forecasts reflect assumptions about sustained real estate developer pre-installation preferences and Matter protocol interoperability timelines. Cross-checking against smart city pilot procurement databases and construction permit filings is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Thailand Travel Retail Market
Others
Disposable Non Woven Sponge Market
Others
Mainframe Market
Others
Asia Pacific Cloud Infrastructure Testing Services Market
Others
Global Surface Analysis Market
Others
Industrial Gauges Market
Others
North America Medical Simulation Market
Others
Conditional Access System (CAS) Market
Others
Signal Transformer Market
Others
Aircraft Lighting Market
Others
Bamboo Straws Market
Others
Astrology Market
Others
Fibert Market
Others
Global Wireless Asset Management Market
Others
Rugged Devices Market
Others
Baking Paper Market