
 Semiconductor Gas Filters Market | 2026-2036
Semiconductor Gas Filters Market Size, Share, and Industry Trends Forecast 2026-2036
Semiconductor Gas Filters Market Intelligence
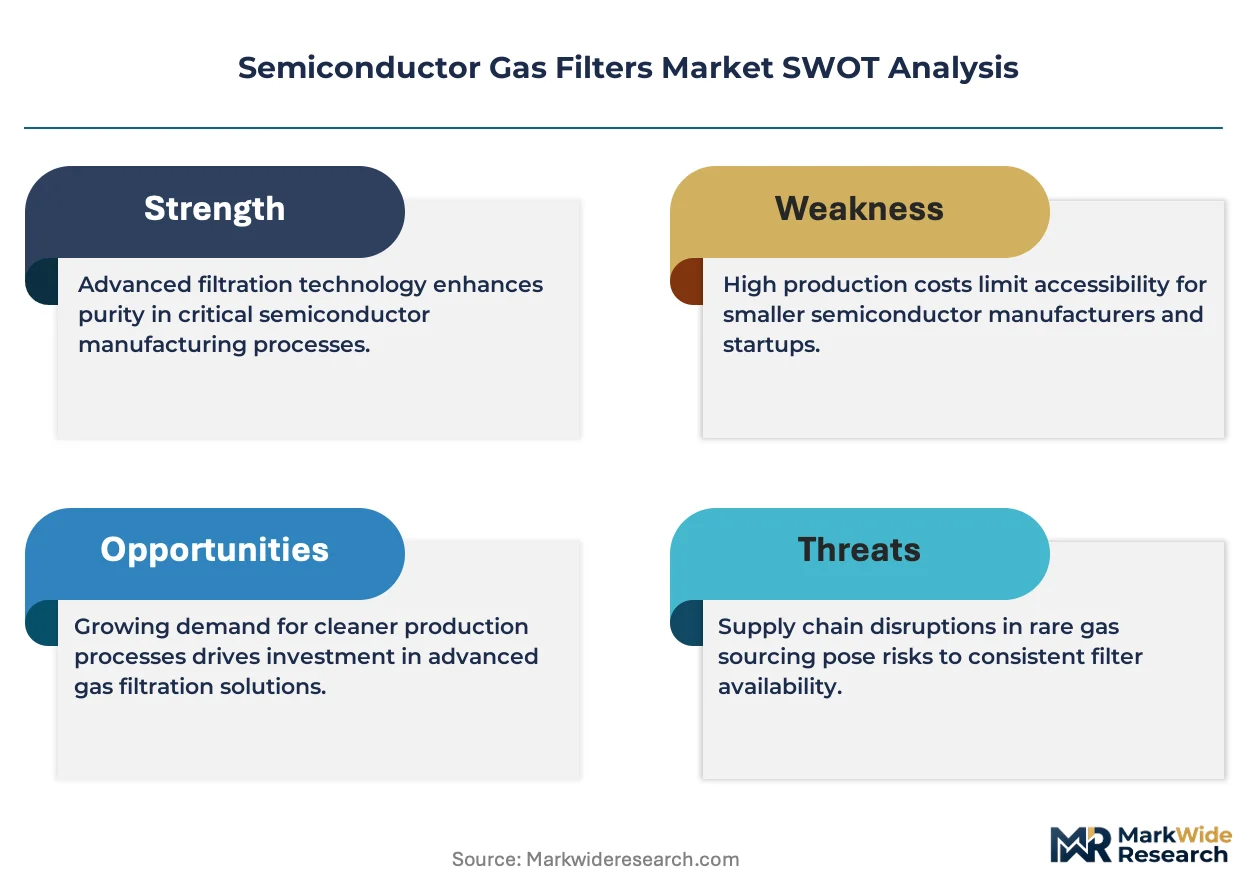
Sub-3nm process node migration is reshaping gas purity thresholds across semiconductor manufacturing. Entegris anchors North American supply through its materials cleanroom infrastructure. Pall Corporation dominates membrane filtration for aggressive chemistries in EUV lithography. Donaldson Company extends its industrial filtration expertise into high-purity semiconductor applications.
Semiconductor gas filters remove molecular contaminants, particles, and condensable vapors from process gases using pleated membranes, sintered metals, or activated carbon media with retention ratings below 0.003 micrometers. These filters protect wafer yields in deposition, etch, and lithography steps where parts-per-billion contamination causes defectivity. Membrane filters command premium positioning due to EUV lithography's extreme purity demands, while particulate filters remain the volume workhorse across mature nodes. Coalescing filters gain share in chemical vapor deposition as precursor gas complexity rises.
EPA oversight of perfluorinated compound emissions tightens abatement requirements tied to filter exhaust pathways. EU REACH restricts fluoropolymer chemistries in filter housings, forcing material substitutions. Japan's METI semiconductor subsidy programs accelerate domestic filter qualification cycles. Stakeholders must track how regional subsidy eligibility rules reshape supplier qualification timelines.
Market Dynamics
Sub-3nm logic node ramp-ups are compressing gas purity thresholds from parts-per-billion to parts-per-trillion specifications, forcing filter replacement cycles shorter and qualification timelines longer across wafer fabrication facilities.
Growth Catalysts
- EUV Lithography Expansion:Extreme ultraviolet systems require molecular contamination control below 0.001 ppb, driving membrane filter upgrades across deposition and etch process lines.
- EPA Perfluorinated Compound Rules:Tighter abatement mandates for PFAS emissions from CVD exhaust streams accelerate filter replacement frequency in US-based fabs.
- Pyongtaek Cluster Investment:Samsung's expanded DRAM and logic capacity in South Korea concentrates demand for point-of-use filtration at aggressive chemistry process steps.
Market Restraints
- Fluoropolymer Input Volatility:PTFE and PFA resin prices fluctuate with semiconductor-grade chemical supply constraints, compressing margin on high-purity membrane production.
- Taiwan Supply Concentration:TSMC and UMC procurement patterns dominate global volume, creating customer dependency risk for filter suppliers without diversified fab relationships.
- EU REACH Material Substitution:Restrictions on fluorinated chemistries in filter housings force costly requalification of alternative polymer formulations.
Strategic Opportunities
- India Semiconductor Mission:PLI scheme subsidies for domestic fab construction create first-mover advantage for filter suppliers establishing local qualification labs.
- ALD Precursor Purity Demands:Atomic layer deposition for 3D NAND stacks requires novel coalescing filter architectures at precursor delivery points.
- Direct OEM Channel Expansion:Bypassing distribution to sell point-of-use filters directly to lithography equipment manufacturers compresses lead times.
Industry Challenges
- Cleanroom Technician Scarcity:Filter installation and validation in ISO Class 1 environments requires specialized contamination control expertise that fabs struggle to staff.
- Fab-Specific Qualification Timelines:Each semiconductor manufacturer's particle counting protocols and outgassing test methods extend sales cycles by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Semiconductor Gas Filters Market |
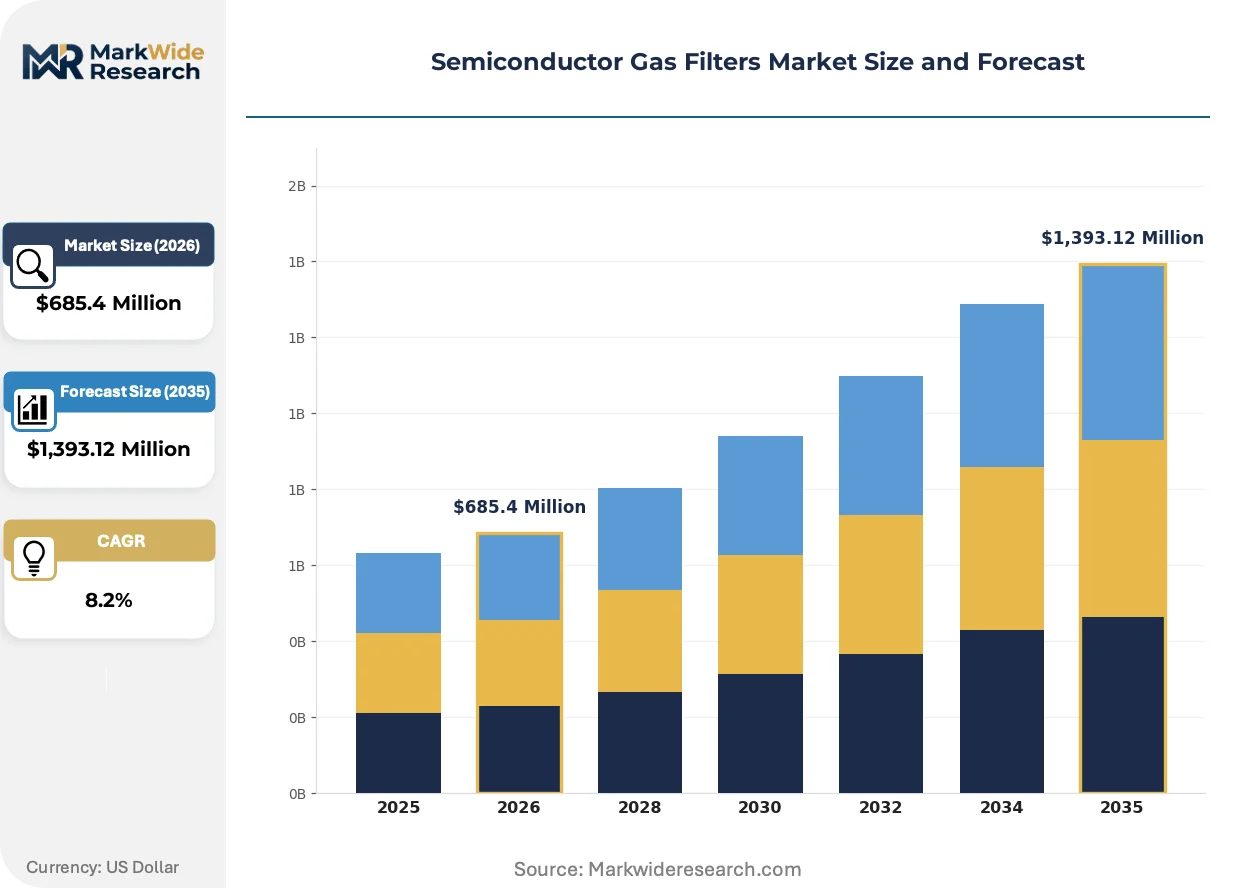
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,393.12 Million |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coalescing Filters, Carbon Filters, Particulate Filters, HEPA Filters, Membrane Filters Technology: Adsorption, Absorption, Catalytic Conversion, Chemical Scrubbing, Filtration Application: Wafer Fabrication, Chemical Vapor Deposition, Etching Processes, Photolithography, Ion Implantation End User: Fabrication Facilities, Equipment Manufacturers, Research Institutes, Testing Laboratories |
| Companies Covered | Donaldson Company, Inc., Porvair Filtration Group, Entegris, Inc., Tokyo Electron Limited, Applied Materials, Inc., Parker Hannifin Corporation, Mott Corporation, IDeas Co., Ltd., Pall Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Semiconductor Gas Filters Market Strategic Shifts & Innovations
Process gas filtration is converging with real-time contamination monitoring, creating closed-loop systems that predict filter failure before yield loss occurs. This integration is compressing maintenance windows and redefining service relationships between filter suppliers and fab operators.
Predictive analytics platforms are digitizing filter performance tracking across multiple process tools simultaneously. Leading-edge fabs in Taiwan and South Korea deploy these systems to correlate pressure-drop signatures with molecular contamination events. The resulting data streams enable condition-based replacement rather than fixed-interval maintenance, digitizing how filter lifecycles get managed.
Japan's METI semiconductor subsidy programs now require domestic content verification for imported filtration components. This industrial policy is accelerating local qualification of Japanese-made membrane media for EUV lithography gas lines. Equipment suppliers are responding by dual-sourcing filter architectures to maintain subsidy eligibility.
Consolidated procurement contracts are displacing tool-specific filter purchasing across multi-fab operators. TSMC and Intel now negotiate enterprise-level agreements covering all process gas filtration across their respective manufacturing networks. This concentration is most visible in Arizona and Dresden, where new fab construction coincides with procurement centralization initiatives.
Semiconductor Gas Filters Market Segmentation
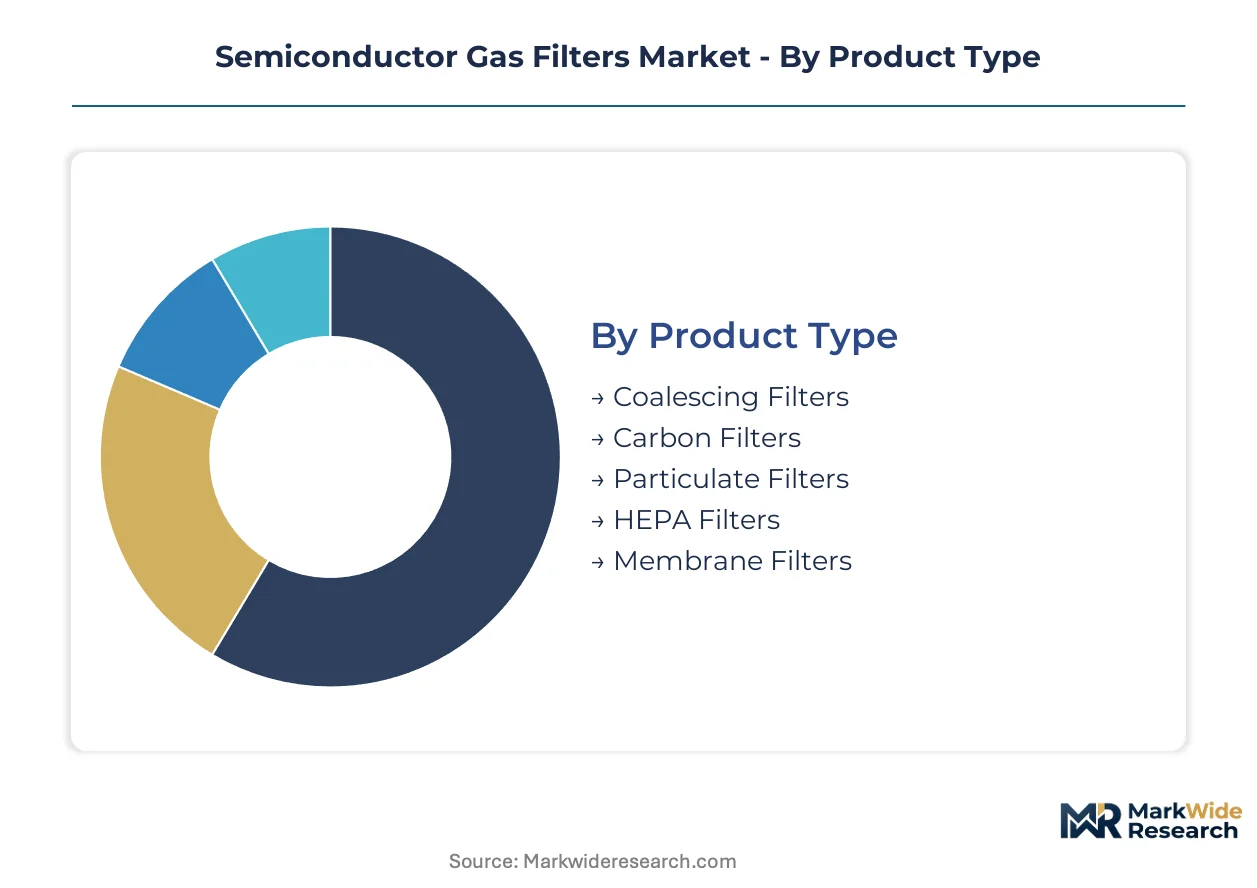
Semiconductor gas filter segmentation reveals divergent replacement economics across product architectures. Cycle times compress from months to years depending on contamination exposure severity and process node sensitivity. Procurement strategies increasingly weight total cost of ownership against upfront unit pricing.
Product Type:
Replacement cycles stretch from six months for aggressive chemistry exposure to five years for inert gas protection, creating tiered aftermarket revenue profiles across filter architectures.
- Membrane Filters:Polytetrafluoroethylene and perfluoroalkoxy membranes achieve retention below 0.003 micrometers for EUV lithography gas lines. Taiwan's Science Park corridor drives specification tightening as TSMC migrates sub-3nm processes.
- Particulate Filters:Pleated borosilicate or fluoropolymer media capture particles above 0.1 micrometers in bulk nitrogen and argon distribution. Mature node fabs in South Korea's Pyeongtaek cluster sustain volume demand despite slower specification evolution.
- Coalescing Filters:Specialized media separate liquid aerosols from compressed process gases at chemical vapor deposition precursor delivery points.
- Carbon Filters:Activated carbon beds adsorb molecular contaminants and condensable vapors from specialty gas streams.
- HEPA Filters:High-efficiency particulate air systems protect gas cabinet environments and distribution manifolds in ISO Class 1 cleanrooms.
Particulate filters dominate installed base. Membrane filters are where expansion concentrates.
Technology:
Cost tiers separate disposable media from regenerable systems, with capital-intensive catalytic units commanding premium positioning against consumable filtration cartridges.
- Filtration:Physical barrier separation through porous membranes or fiber matrices constitutes the baseline approach for particle and droplet removal. Volume concentration rests with deposition and etch process lines where contamination tolerance remains above parts-per-billion thresholds.
- Adsorption:Surface-binding mechanisms on activated carbon or zeolite media capture molecular contaminants at trace concentrations. Atomic layer deposition precursor purity demands in 3D NAND manufacturing are climbing the fastest.
- Absorption:Liquid-phase scrubbing dissolves reactive gases into chemical solutions for exhaust abatement.
- Catalytic Conversion:High-temperature reactor beds transform hazardous effluents into benign compounds for environmental compliance.
- Chemical Scrubbing:Reactive liquid systems neutralize acid gases and dopant compounds at exhaust points.
Filtration architectures anchor current procurement volumes. Adsorption systems are capturing incremental share at leading-edge nodes.
Application:
Customer type stratification separates high-volume repetitive purchasers from specification-driven project buyers with extended qualification timelines.
- Wafer Fabrication:Point-of-use filtration at process tool gas inlets protects yield across deposition, etch, and lithography sequences. Samsung's expanded Pyeongtaek capacity concentrates demand for multi-stage filtration trains.
- Photolithography:EUV scanner gas lines require molecular contamination control below 0.001 parts-per-billion, driving membrane filter upgrades with the steepest expansion trajectory.
- Chemical Vapor Deposition:Precursor gas delivery systems employ coalescing and adsorptive stages to prevent particle nucleation on wafer surfaces.
- Etching Processes:Reactive plasma effluent handling demands corrosion-resistant filtration media for fluorinated and chlorinated chemistries.
- Ion Implantation:Dopant gas purification prevents cross-contamination between species in high-current beamline systems.
Wafer fabrication commands the broadest installed base. Photolithography filtration is where specification investment concentrates.
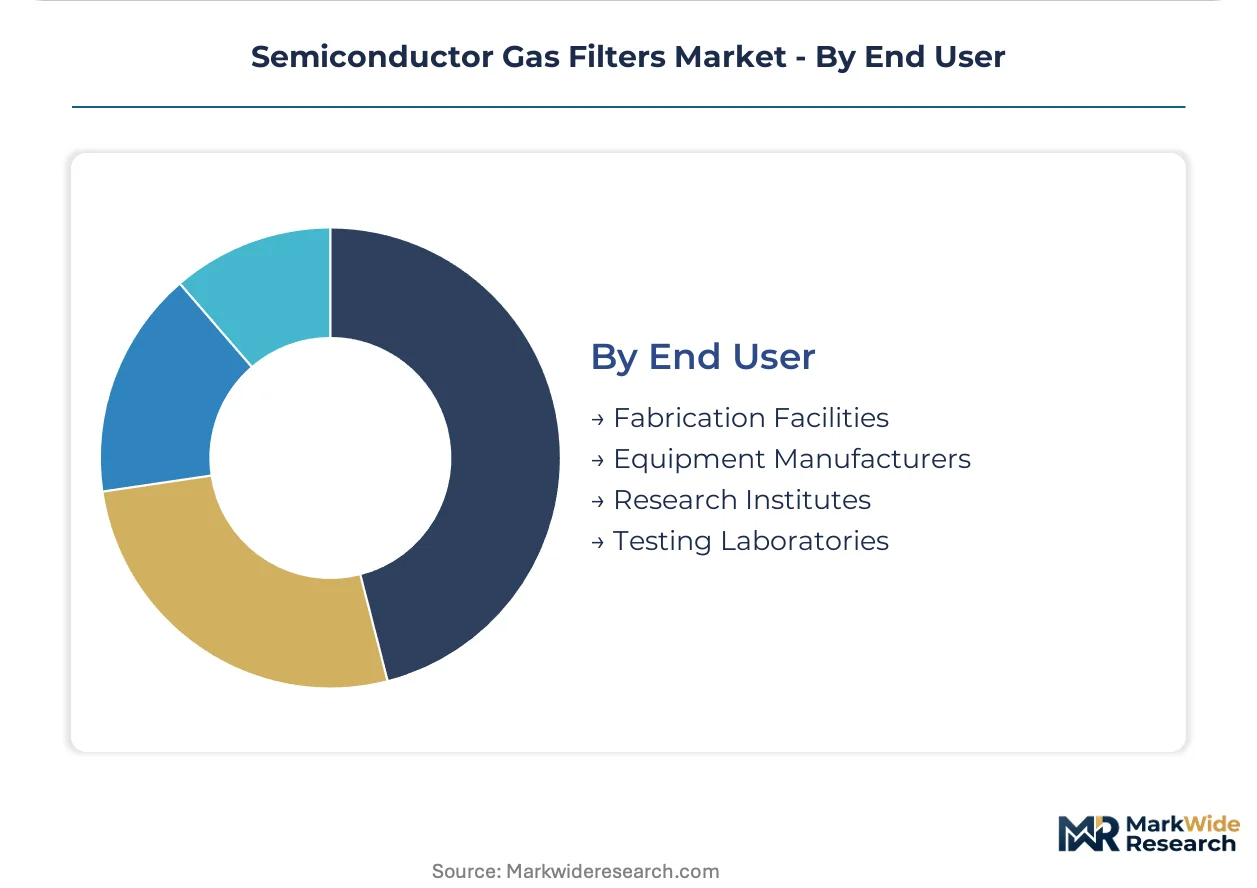
End User:
Supply concentration differs dramatically between captive procurement by integrated device manufacturers and third-party sales through equipment OEM channels.
- Fabrication Facilities:IDMs and foundries operate direct filter procurement for consumables replacement with enterprise-level contract consolidation. TSMC and Intel now negotiate network-wide agreements spanning Arizona and Dresden construction.
- Equipment Manufacturers:Lithography and deposition tool OEMs specify point-of-use filters as original equipment, compressing lead times through direct supplier relationships.
- Research Institutes:Academic and government laboratories purchase lower volumes with extended qualification cycles for experimental process development.
- Testing Laboratories:Third-party analytical services require filtration for calibration gas standards and contamination analysis.
Fabrication facilities dominate procurement volume. Equipment manufacturer channels are where supplier relationship restructuring concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated device manufacturers and foundries cluster procurement decisions in three dominant geographies. Taiwan's Science Park corridor, South Korea's Pyeongtaek cluster, and the southwestern United States concentrate point-of-use filter demand for sub-3nm process ramps.
Taiwan
TSMC's N2 node qualification drives membrane filter specification tightening at Hsinchu Science Park. EPA perfluorinated compound oversight affects abatement system design for US-owned equipment suppliers serving Taiwanese fabs. Tainan's Southern Taiwan Science Park anchors the most aggressive chemistry filtration demand as 3nm capacity scales.
South Korea
Samsung's expanded Pyeongtaek DRAM and logic investment concentrates multi-stage filtration procurement. METI semiconductor subsidy programs in neighboring Japan accelerate qualification of alternative membrane suppliers for Korean tool imports. Seoul Capital Area engineering centers coordinate filter validation protocols across Samsung's domestic fab network.
United States
Intel's Arizona and Ohio fab construction drives enterprise-level filter contract consolidation. EPA PFAS emission rules compress replacement cycles for chemical vapor deposition exhaust pathways. Greater Phoenix anchors the fastest-growing North American cluster as TSMC and Intel simultaneous builds concentrate technician demand.
Japan
Tokyo Electron and Shin-Etsu equipment specifications propagate Japanese filter standards globally. METI domestic content verification requirements accelerate local membrane qualification for EUV lithography gas lines. Kyushu's Kumamoto Prefecture hosts expanding Taiwan Semiconductor Manufacturing Company capacity that imports Japanese filtration protocols.
Germany
EU REACH fluoropolymer restrictions force material substitution in filter housing supply chains serving Dresden's new Intel fab. ECHA oversight of perfluorinated compounds extends qualification timelines for alternative polymer formulations. Saxony's semiconductor cluster concentrates European demand for deposition and etch process filtration.
Semiconductor Gas Filters Market Key Industry Players
Channel-controlling players compete with product-specialist players across tiered procurement relationships. The vendor base organizes around three archetypes: materials science conglomerates with cleanroom infrastructure, membrane technology specialists, and industrial filtration diversifiers. Consolidation pressure intensifies as enterprise-level contracts displace tool-specific purchasing. Strategic moves concentrate on dual-sourcing qualification and direct OEM channel bypass.
Among North American materials specialists, Entegris, Inc. anchors the cleanroom-integrated archetype through its contamination control infrastructure. Pall Corporation exemplifies membrane technology leadership for aggressive chemistry applications. Donaldson Company, Inc. represents industrial filtration diversification into semiconductor-grade specifications. These three players occupy distinct competitive positions based on upstream integration depth and customer relationship structure.
| Leading Market Players |
|---|
| Donaldson Company, Inc. |
| Porvair Filtration Group |
| Entegris, Inc. |
| Tokyo Electron Limited |
| Applied Materials, Inc. |
| Parker Hannifin Corporation |
| Mott Corporation |
| IDeas Co., Ltd. |
| Pall Corporation |
| Others |
Cost & Logistics Intelligence
Hsinchu Science Park's membrane filter foundry capacity shapes downstream pricing power for EUV-grade media, compressing margins for suppliers without direct qualification relationships with TSMC's procurement consortium.
Pricing Analysis
Cost-plus contracts indexed to fluoropolymer resin spot markets dominate procurement between Taiwanese foundries and their qualified filter suppliers. Price differentiation rests on ISO Class 1 certification tier and volume scale, with enterprise-level agreements commanding 15-20 point discounts against spot purchases. Cost compression in membrane-grade PTFE is intensifying because South Korean chemical suppliers are expanding semiconductor-grade resin output. Mature node fabs in China's secondary cities exhibit the highest price sensitivity, while EUV lithography tool OEMs show minimal elasticity due to qualification lock-in effects.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculus for filter housing manufacturers serving Arizona fab construction. Raw material sourcing draws from Japanese fluoropolymer resin producers, German precision machining centers, and Taiwanese membrane casting operations. Single-source vulnerability concentrates in semiconductor-grade PTFE supply, where three Japanese chemical conglomerates control over 80 percent of qualified output. Distribution runs through lithography equipment OEMs for point-of-use filters and direct fab procurement for replacement cartridges.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cleanroom technician scarcity constrains installation velocity at new fab sites, creating a bottleneck where qualified labor availability determines supplier selection more than unit pricing.
For Market Incumbents: Pre-empt emerging membrane media substitutes by locking in dual-source qualification status with Intel's Arizona and Dresden procurement teams. Expand captive supply of fluoropolymer resin through backward integration into Japanese chemical supplier partnerships. Defend against Chinese membrane entrants by accelerating EUV-specific validation timelines. For New Entrants and Emerging Players: Pursue India's Semiconductor Mission PLI scheme as the most penetrable geography, where domestic fab construction lacks established filter qualification infrastructure. Target coalescing filter architectures for ALD precursor delivery as the specification gap most vulnerable to new entrants. Lead with local qualification lab investment as the go-to-market angle. For Investors and Strategic Acquirers: Long-term, this sits as a consumables-annuity play because replacement cycles compress indefinitely at sub-3nm nodes. Target membrane technology specialists with EUV lithography qualification rather than industrial filtration diversifiers. Watch TSMC's N2 node yield ramp as the signal indicating whether membrane filter specification tightening accelerates or plateaus.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Source Qualification Program | Intel's enterprise procurement now mandates redundant membrane suppliers for Arizona capacity. |
| Local Qualification Lab Buildout | India's PLI scheme requires domestic validation capability to access subsidy-eligible fab contracts. |
| Predictive Maintenance Platform Integration | Real-time contamination monitoring creates recurring service revenue beyond cartridge replacement. |
| Fluoropolymer Backward Integration | Captive resin supply insulates margin from Japanese chemical supplier price volatility. |
| Direct OEM Channel Bypass | ASML and Tokyo Electron point-of-use specifications enable filter suppliers to compress lead times. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with cleanroom engineering directors, fab procurement leads, lithography tool OEM supply chain managers, and fluoropolymer resin technical sales specialists; alongside secondary validation through SEMI equipment market data, EPA PFAS regulatory filings, EU REACH substance restriction updates, and customs trade records for semiconductor-grade filtration components. Bottom-up and top-down triangulation cross-checked replacement volume estimates against fab capacity announcements.
Forecast inputs span membrane versus particulate filter technology splits, wafer fabrication versus photolithography application concentration, and IDM versus foundry end-user procurement patterns across the projection horizon. CAGRs derive from segment-level growth rate blending weighted by replacement cycle economics. Industry-specific inputs include EUV scanner installation forecasts and atomic layer deposition precursor purity specification evolution.
Sensitivities concentrate around EPA perfluorinated compound rule enforcement intensity and Taiwan Strait logistics disruption scenarios. Forecasts reflect assumptions about qualification timeline stability and fluoropolymer resin supply continuity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Global Food Fiber Market
Others
Balsa Wood Market
Others
Cat Food and Snacks Market
Others
Global Essential Oils and Plant Extracts for Livestock Market
Others
Tripod Market
Others
Fenoxanil Market
Others
Europe Battery Packaging Market
Others
Commercial Aircraft Angle of Attack Sensors Market
Others
Dried Egg Market
Others
Biopharma Plastics Market
Others
Bimodal Identity Management Solutions Market
Others
Shisha Tobacco Market
Others
Retail Media Platform Market
Others
Middle East and Africa Electric Vehicle Battery Electrolyte Market
Others
Global Computer Graphics Market
Others
Signal Transformer Market