
 GCC Shisha Tobacco Market | 2026-2036
GCC Shisha Tobacco Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Shisha Tobacco Market Foresight
The gap between premium and commodity shisha tobacco is expanding as lounge operators in Dubai and Riyadh demand higher-grade molasses with refined glycerin ratios and extended burn consistency. Al Fakher leverages its integrated UAE manufacturing base to supply bulk volumes across the Gulf. Nakhla Tobacco anchors Egypt-to-GCC export corridors with traditional dark-leaf formulations. Starbuzz Tobacco differentiates through American-style flavor intensity targeting expatriate consumers in Qatar and Kuwait.
Shisha tobacco comprises cured Virginia or Burley leaf blended with molasses, vegetable glycerin, and flavoring agents, then heated indirectly to produce inhalable aerosol for social consumption sessions lasting 45-90 minutes. The flavor type dimension spans Mint, Apple, Grape, Cola, Berry, and Rose, with mint and mixed-fruit profiles dominating cafe procurement while berry variants capture fastest growth among female lounge patrons in Jeddah and Manama. Packaging format splits across Foil Pouch, Glass Jar, Metal Tin, Plastic Container, and Cardboard Box, where metal tins command margin premiums in duty-free channels and foil pouches sustain volume in supermarket convenience tiers.
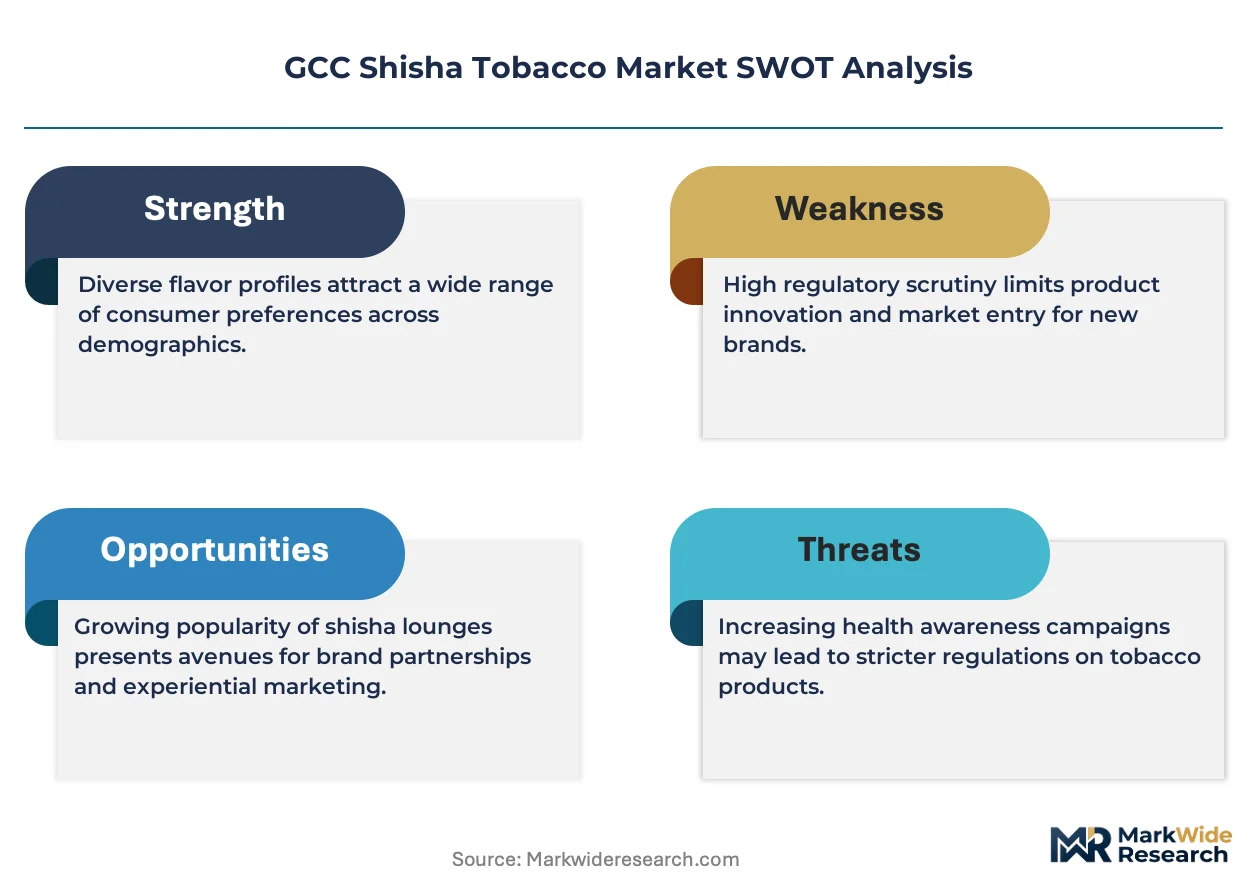
SFDA standards in Saudi Arabia, Emirates Authority for Standardization and Metrology (ESMA) specifications in the UAE, and GCC Standardization Organization (GSO) harmonized technical regulations collectively govern nicotine disclosure, additive prohibitions, and import labeling requirements across member states. These frameworks elevate compliance costs for smaller importers while favoring established manufacturers with dedicated regulatory affairs capacity. Stakeholders must monitor pending flavor restriction proposals and adapt portfolio composition toward compliant base-tobacco SKUs before enforcement timelines crystallize.
Market Dynamics
SFDA flavor restrictions and ESMA additive standards are compressing formulation flexibility while lounge operators in Riyadh and Dubai demand higher-grade molasses with certified glycerin ratios, creating a bifurcation between compliant bulk supply and premium artisanal tiers.
Growth Catalysts
- Premium lounge culture:High-end venues in Jeddah and Manama are extending session durations through refined heat-management accessories, lifting per-capita consumption among patrons aged 22-35.
- GSO harmonization:Unified technical regulations across Bahrain, Kuwait, Oman, Qatar, Saudi Arabia, and the UAE are reducing cross-border compliance duplication for established manufacturers with dedicated regulatory affairs capacity.
- Dark-leaf traditional formats:Heritage-oriented consumers in Egypt-to-GCC export corridors are sustaining demand for unflavored base tobacco as a compliant substrate under pending additive restrictions.
Market Restraints
- Vegetable glycerin price volatility:Input costs for USP-grade glycerin fluctuate with palm oil and biodiesel feedstock markets, squeezing margin on mid-tier foil pouch formats.
- Import concentration risk:Bahrain and Kuwait rely on single-corridor sea freight through Jebel Ali, exposing inventory cycles to Red Sea routing disruptions.
- Flavor prohibition scope:SFDA draft guidelines on characterizing flavors threaten the mint and mixed-fruit SKUs that dominate cafe procurement volumes.
Strategic Opportunities
- Oman underpenetration:Muscat and Salalah exhibit lounge density at roughly one-third of Dubai levels, presenting first-mover positioning for heat-not-compatible accessory bundling.
- Duty-free metal tin premiumization:Airport retail channels in Doha and Abu Dhabi are allocating shelf space to gift-format packaging with extended shelf-life seals.
- ESMA traceability mandates:Digital labeling requirements for nicotine disclosure are creating compliance-as-a-service openings for third-party testing laboratories.
Industry Challenges
- Formulation chemist scarcity:GCC universities produce limited graduates with dual competency in tobacco curing and food-grade flavor chemistry, forcing manufacturers to recruit from Egypt and Jordan.
- Legacy equipment retrofit costs:Converting molasses-mixing lines for rapid SKU changeovers under tighter batch-control standards demands capital outlays that strain mid-tier producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Shisha Tobacco Market |
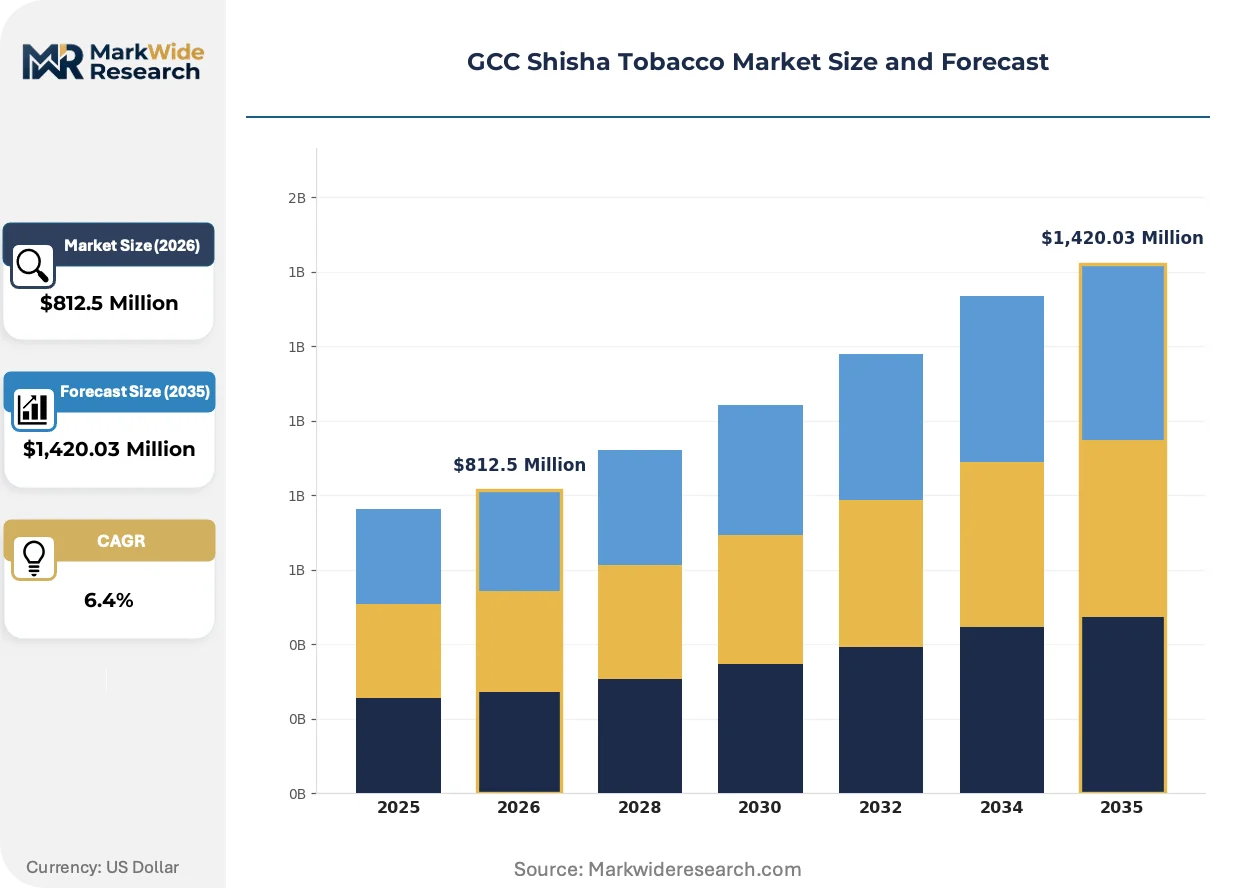
| Market Size in 2026 | $812.5 Million |
| Market Size in 2035 | $1,420.03 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Flavor Type: Mint, Apple, Grape, Cola, Berry, Rose Packaging Format: Foil Pouch, Glass Jar, Metal Tin, Plastic Container, Cardboard Box End User: Cafes, Restaurants, Lounges, Private Residences, Event Organizers Distribution Channel: Specialty Stores, Online Retailers, Convenience Stores, Supermarkets, Duty-Free Shops |
| Companies Covered | Fumari, Social Smoke, Al Fakher, Al Andalus Flavoured Tobacco & Molasses Co. Llc, Haze Tobacco, Nakhla Tobacco, Mazaya, Alzawrae Industrial Company, Starbuzz Tobacco, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Shisha Tobacco Market Shifts & Advancements
Heat-management devices and glycerin-ratio engineering are displacing traditional foil-and-charcoal preparation methods, while regulatory disclosure mandates are digitizing supply chain traceability. These shifts are compressing the innovation cycle from annual flavor rotations to quarterly formulation adjustments.
Stone heat-retention devices paired with perforated aluminum lids are expanding into premium lounge service across Riyadh and Dubai. Venues in these cities are adopting the devices to standardize session duration and reduce charcoal-handling labor. This hardware layer is expanding into a recurring revenue stream through branded accessory replacement cycles.
SFDA batch-level nicotine disclosure rules and ESMA digital labeling specifications are forcing manufacturers to reconfigure packaging lines for variable-data printing. The industrial consequence is elevated capital intensity for compliance infrastructure. Smaller importers without dedicated regulatory affairs capacity are exiting the Saudi market rather than absorbing these fixed costs.
Female lounge patrons in Jeddah and Manama are rotating toward berry and floral flavor profiles, displacing the apple and grape dominance of male-skewed cafe demographics. Boutique venues in these cities are responding with gender-segmented menu engineering and dedicated seating configurations. This behavioral split is visible in procurement patterns where berry variants now command volume premiums in quarterly purchasing agreements.
GCC Shisha Tobacco Market Segmentation
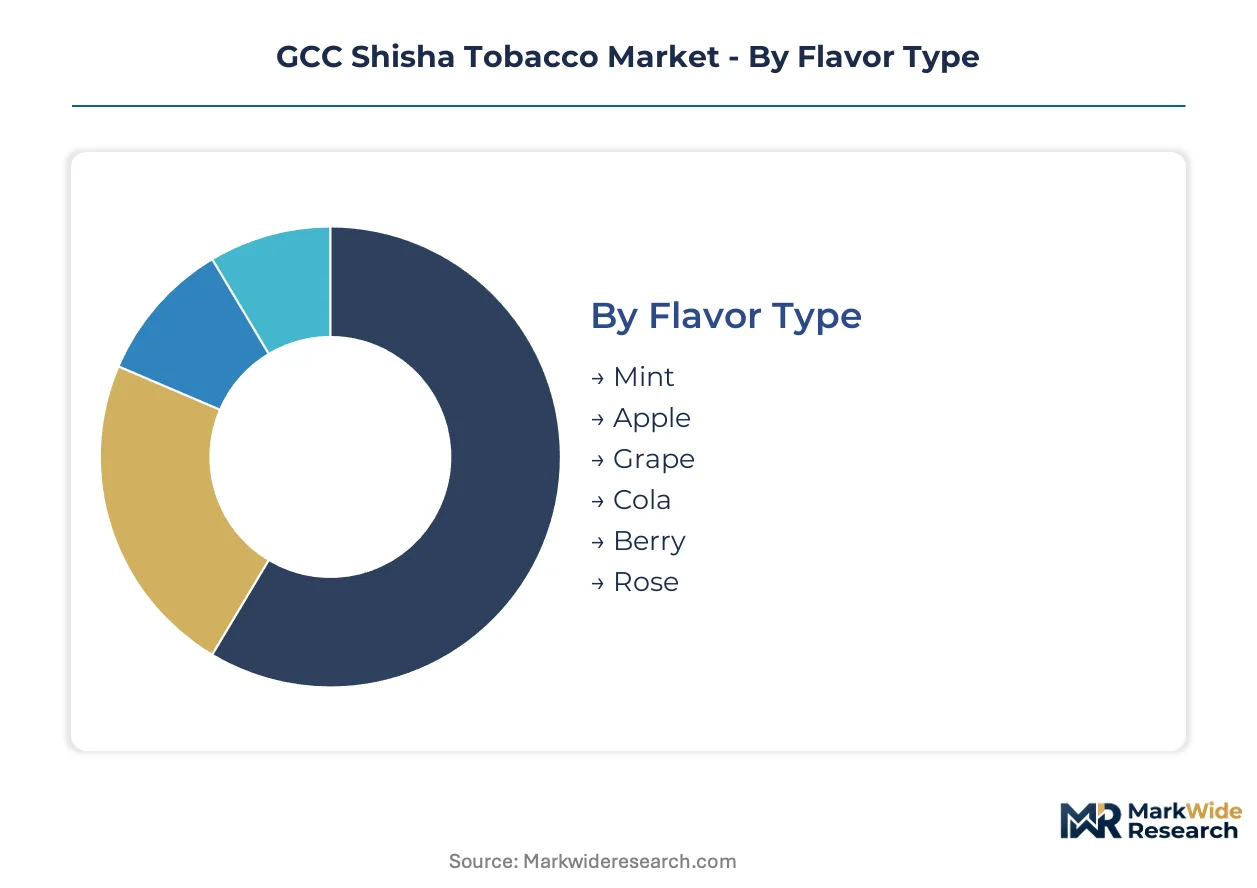
Shisha tobacco segmentation in the GCC reflects divergent capital requirements across manufacturing, packaging, and distribution layers. Lounge operators and duty-free channels command premium positioning through format and flavor investments, while commodity tiers compete on logistics efficiency.
Flavor Type:
Capital intensity peaks in flavor development, where certified food-grade laboratories and SFDA-compliant additive testing create steep barriers for new entrants.
- Mint:Dominant flavor profile combining menthol-derived cooling agents with base Virginia leaf. Riyadh and Dubai cafes procure mint SKUs in bulk volumes, though SFDA draft guidelines threaten this segment's formulation flexibility.
- Apple:Traditional anise-tinged profile requiring precise molasses-to-glycerin ratios for extended burn consistency. Heritage venues in Jeddah and Manama sustain demand despite generational preference shifts.
- Grape:Synthetic and natural ester blends targeting male-skewed cafe demographics across Bahrain and Kuwait.
- Cola:Niche carbonated-beverage flavoring capturing expatriate consumers in Qatar's hospitality sector.
- Berry:Mixed-fruit profiles with cranberry and raspberry notes gaining traction among female lounge patrons in Jeddah and Manama.
- Rose:Floral distillate formulations serving gender-segmented boutique venues with premium positioning.
Mint absorbs the bulk of installed capacity; Berry is expanding most quickly.
Packaging Format:
Packaging differentiation tracks distribution channel requirements, with metal tins and glass jars demanding specialized sealing equipment versus commodity pouch lines.
- Metal Tin:Airtight containers with extended shelf-life seals commanding margin premiums in Doha and Abu Dhabi duty-free channels. ESMA traceability mandates favor tin-based variable-data printing infrastructure.
- Foil Pouch:Lightweight barrier packaging sustaining supermarket and convenience store volumes across Saudi Arabia and the UAE. Glycerin price volatility squeezes margins on mid-tier pouch formats.
- Glass Jar:Transparent containers showcasing leaf quality for premium lounge procurement in Dubai.
- Plastic Container:Cost-optimized formats for high-turnover cafe supply chains in Kuwait and Oman.
- Cardboard Box:Bulk shipping configurations for B2B restaurant and event organizer channels.
Foil Pouch dominates unit economics at scale; Metal Tin captures the steepest expansion trajectory in airport retail.
End User:
End-user segmentation aligns with session-duration economics, where lounges invest in heat-management hardware while private residences prioritize convenience.
- Lounges:Premium venues in Riyadh and Dubai driving per-capita consumption through 45-90 minute session extensions and branded accessory replacement cycles.
- Cafes:High-frequency, lower-margin establishments across Jeddah and Manama procuring mint and apple SKUs in quarterly purchasing agreements.
- Restaurants:Hospitality-integrated service requiring compact storage formats and rapid table-turn logistics.
- Private Residences:Consumer-direct purchases through online retailers and specialty stores in Saudi Arabia and the UAE.
- Event Organizers:Seasonal demand concentrators for wedding and corporate hospitality in Qatar and Bahrain.
Lounges anchor manufacturer revenue concentration; Private Residences are gaining share fastest through e-commerce channel development.
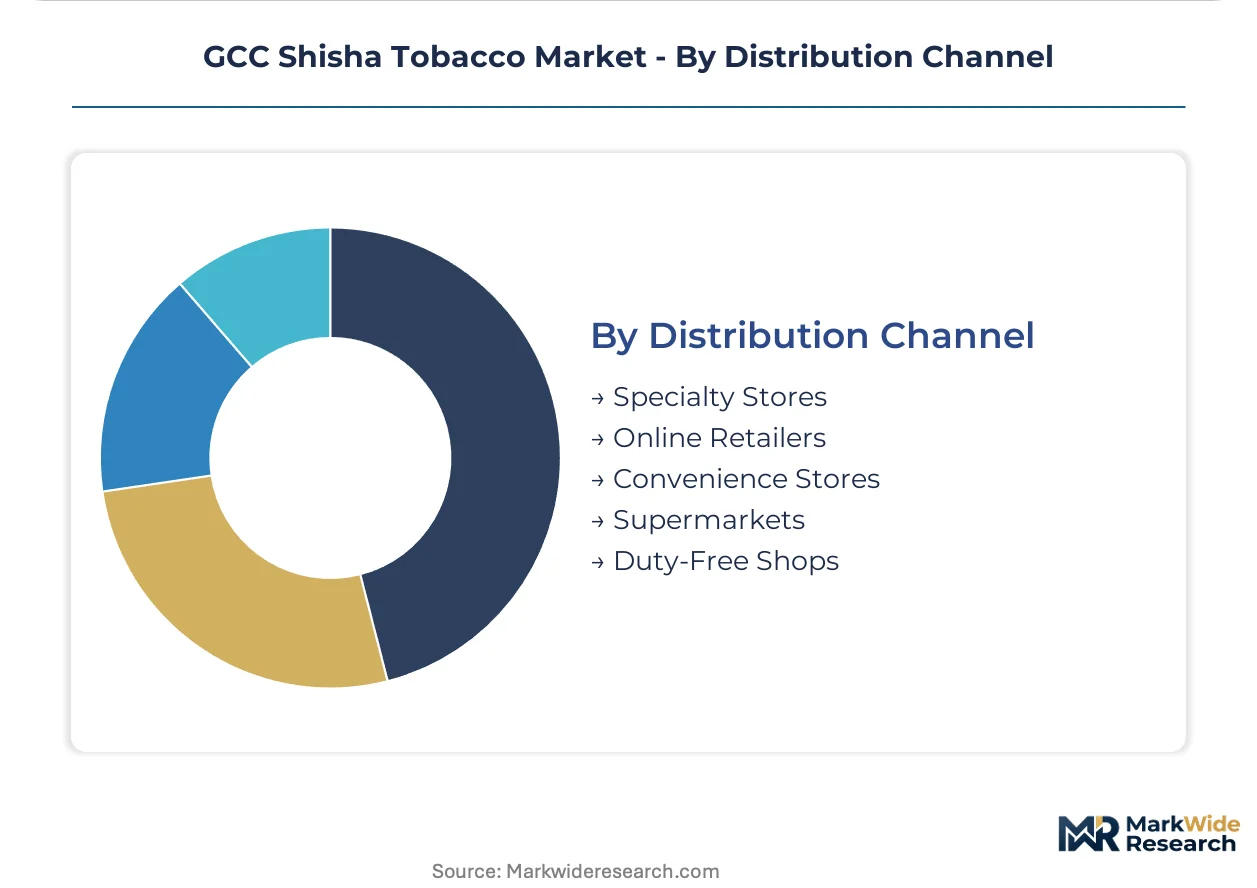
Distribution Channel:
Channel economics diverge on compliance infrastructure, with duty-free and specialty stores absorbing ESMA and SFDA labeling investments that exclude smaller importers.
- Duty-Free Shops:Airport retail in Doha and Abu Dhabi allocating shelf space to gift-format metal tins with premium positioning and extended shelf-life requirements.
- Specialty Stores:Knowledge-intensive outlets in Dubai and Riyadh providing flavor consultation and heat-management accessory bundling.
- Online Retailers:Digital platforms capturing private residence demand with ESMA-compliant digital labeling and nicotine disclosure requirements.
- Supermarkets:High-volume foil pouch distribution across Saudi Arabia's retail consolidation.
- Convenience Stores:Impulse-purchase formats in Bahrain and Kuwait's urban corridors.
Specialty Stores concentrate regulatory compliance investment; Online Retailers are climbing the fastest on logistics platform scaling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai anchors consumption density across the GCC shisha tobacco market, with lounge clustering along Sheikh Zayed Road and Dubai Marina driving per-capita spend premiums among expatriate and tourist demographics.
Saudi Arabia
Riyadh and Jeddah concentrate premium lounge development, with venue operators sourcing metal-tin formats for extended session economics. The Saudi Food and Drug Authority enforces batch-level nicotine disclosure and additive prohibition frameworks that compress formulation flexibility for imported SKUs. Eastern Province industrial zones near Dammam host domestic mixing facilities serving bulk cafe procurement.
United Arab Emirates
Abu Dhabi duty-free channels allocate expanding shelf space to gift-format packaging with ESMA-mandated digital traceability labels. The Emirates Authority for Standardization and Metrology governs glycerin-ratio certification and variable-data printing requirements that elevate packaging line capital intensity. Sharjah manufacturing corridors supply foil-pouch volumes to supermarket consolidation across the northern emirates.
Qatar
Doha's hospitality-integrated venues drive demand for American-style flavor intensity among expatriate consumers in the West Bay district. The Ministry of Public Health aligns with GSO harmonized technical regulations for import labeling and nicotine disclosure. Industrial zones near Hamad Port facilitate sea-freight consolidation from Jebel Ali transit corridors.
Kuwait
Urban cafe density in Kuwait City sustains high-frequency procurement of mint and apple SKUs in quarterly purchasing agreements. Single-corridor sea freight through Jebel Ali exposes inventory cycles to Red Sea routing disruptions. Salmiya and Hawalli districts concentrate mid-tier lounge operations with compressed heat-management hardware adoption.
Bahrain
Manama's boutique venues pioneer gender-segmented menu engineering with berry and floral profile rotation among female lounge patrons. The national standards body implements GSO technical regulations for cross-border compliance harmonization. Muharraq cafe clusters sustain heritage-oriented demand for traditional dark-leaf formats as compliant substrates under additive restrictions.
GCC Shisha Tobacco Market Competitive Landscape
Premium-margin players sit above commodity-margin players across packaging format and flavor development dimensions, with metal-tin and glass-jar specialists capturing duty-free and lounge premiums while foil-pouch fabricators compete on logistics efficiency. The vendor base stratifies into three archetypes: integrated manufacturers with captive UAE production, Egypt-to-GCC export specialists, and American-style flavor houses targeting expatriate segments. Dominant competitive moves include regulatory compliance capacity expansion and heat-management accessory bundling.
Within the integrated manufacturing tier, Al Fakher anchors volume supply across Gulf markets through its UAE-based production footprint. Nakhla Tobacco exemplifies the Egypt-to-GCC export specialist archetype, with traditional dark-leaf formulations serving heritage-oriented procurement channels. Starbuzz Tobacco occupies a position among American-style flavor houses, representing intensity-driven product positioning targeting Qatar and Kuwait expatriate demographics.
| Leading Market Players |
|---|
| Fumari |
| Social Smoke |
| Al Fakher |
| Al Andalus Flavoured Tobacco & Molasses Co. Llc |
| Haze Tobacco |
| Nakhla Tobacco |
| Mazaya |
| Alzawrae Industrial Company |
| Starbuzz Tobacco |
| Others |
Supply & Pricing Matrix
Premium-commodity bifurcation between metal-tin duty-free formats and foil-pouch supermarket tiers manifests divergent margin structures across GCC markets, with certified glycerin-ratio compliance costs feeding into pricing power at the top while vegetable glycerin volatility compresses mid-tier economics. This tier divergence shapes sourcing strategies: lounge operators in Dubai and Riyadh negotiate long-term offtake agreements for heat-management-compatible SKUs, while convenience channels absorb spot-market glycerin exposure.
Pricing Analysis
Session-yield pricing anchors value capture across GCC shisha tobacco tiers, with venues pricing access per minute of aerosol delivery rather than gram weight. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and heat-management compatibility, with ESMA-traceable metal tins commanding premiums over commodity foil pouches. Cost compression in mid-tier pouch formats is intensifying because USP-grade glycerin feeds from palm oil and biodiesel volatility. Private residence buyers through online channels exhibit highest price sensitivity; duty-free tourists show lowest.
Supply Chain Analysis
Formulation chemist scarcity in UAE and Saudi Arabia manufacturing zones forces recruitment from Egypt and Jordan, tightening labor markets for dual-competency tobacco curing and food-grade flavor chemistry. Production gravity centers on UAE integrated facilities, Egypt-to-GCC export corridors, and American-style flavor houses serving Qatar and Kuwait. Raw material flows draw from Virginia and Burley leaf sourcing, molasses refining, and USP-grade glycerin procurement. Single-corridor sea freight through Jebel Ali exposes Bahrain and Kuwait inventory cycles to Red Sea routing disruptions. Distribution runs through duty-free airport retail, specialty store channels, and scaling e-commerce platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply-side formulation chemist scarcity and batch-control equipment retrofit requirements prop pricing power for compliant manufacturers, constraining volume expansion from mid-tier producers. This capacity bottleneck sustains margin premiums for integrated players with dedicated regulatory affairs infrastructure.
For Market Incumbents: Anticipate SFDA flavor prohibition enforcement by accelerating compliant base-tobacco SKU development and securing heat-management device bundling partnerships with Riyadh and Dubai lounge operators. Capacity addition in Sharjah manufacturing corridors strengthens foil-pouch supply security against Red Sea logistics disruption.
For New Entrants and Emerging Players: Launch via Oman's underpenetrated lounge market with heat-not-compatible accessory bundling targeting Muscat and Salalah venue density at one-third Dubai levels. Berry and floral profile specialization captures fastest-growing female patron segments in Jeddah and Manama boutique channels.
For Investors and Strategic Acquirers: Re-rating potential sits with Egypt-to-GCC export specialists given GSO harmonization reducing cross-border compliance duplication. Long-term viability over a 5-10 year window favors traditional dark-leaf format capabilities as compliant substrates under additive restrictions. Watch pending SFDA draft guideline crystallization as inflection signal for portfolio rotation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Compliance Capacity Expansion | SFDA and ESMA batch-level nicotine disclosure rules favor manufacturers with dedicated regulatory affairs infrastructure over smaller importers. |
| Heat-Management Accessory Bundling | Stone heat-retention devices paired with perforated aluminum lids create recurring revenue streams through branded replacement cycles in Riyadh lounges. |
| Flavor Portfolio Rotation | Berry and floral profile development captures gender-segmented procurement patterns among female patrons in Jeddah and Manama boutique venues. |
| Manufacturing Footprint Consolidation | UAE-based integrated production anchors volume supply security against Egypt-to-GCC corridor transit risks and Jebel Ali concentration exposure. |
| Digital Traceability Infrastructure | ESMA-mandated variable-data printing capabilities create compliance-as-a-service openings for third-party testing laboratories serving mid-tier producers. |
Research Methodology
Multi-period observation of lounge venue density, flavor procurement patterns, and regulatory filing trajectories anchored the trend analysis, supplemented by interviews with shisha tobacco manufacturing executives, regulatory affairs specialists at SFDA and ESMA, duty-free retail category managers, and lounge operators across Riyadh, Dubai, Jeddah, and Manama. Secondary validation drew from GSO harmonized technical regulation databases, Saudi Food and Drug Authority public consultation records, Emirates Authority for Standardization and Metrology specifications, customs and trade flow data, and SEC filings from publicly traded parent entities. Bottom-up venue counting and top-down import value triangulation cross-checked volume estimates.
Input-output matrices mapping flavor type, packaging format, end-user segment, and distribution channel through the projection horizon structured the analytical framework. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Modeled dimensions included mint-apple-grape-berry-rose flavor profiles, metal-tin-glass-jar-foil-pouch-plastic-container packaging tiers, lounge-cafe-restaurant-private residence-event organizer end-use splits, and duty-free-specialty store-online-supermarket-convenience channel flows. Forecast inputs incorporated glycerin feedstock price trajectory assumptions and pending additive restriction enforcement probability weightings.
The model assumes a particular technology adoption path; alternative pathways for heat-not-compatible devices versus traditional foil-and-charcoal preparation would alter the outlook for session-duration economics and accessory revenue streams. Forecasts reflect assumptions about GSO harmonization implementation timing and SFDA enforcement crystallization. Material deviation in these regulatory triggers or Red Sea logistics disruption persistence warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Saudi Arabia Laser Hair Removal Market
Others
Lightweight Compact Wheel Loader Market
Others
Convenience Stores Market
Others
Foldable Smartphone Market
Others
Communication Base Station Body Market
Others
Balsa Wood Market
Others
Pollen Allergy Market
Others
Global Webinar and Webcast Market
Others
Cloud Gaming Baas Market
Others
US Legal Services Market
Others
Taiwan Retail Market
Others
Spain Smart Home Market
Others
LAMEA Astrology Market
Others
3D Printing Construction Market
Others
Middle East and Africa Surface Analysis Market
Others
Ultra Mobile Devices (UMD) Market