
 Process Spectroscopy Market | 2026-2036
Process Spectroscopy Market Size, Share, and Industry Trends Forecast 2026-2036
Process Spectroscopy Market Intelligence
The capital-intensity divergence between installed-base incumbents and modular newcomers is bifurcating competitive dynamics in process spectroscopy. Thermo Fisher Scientific leverages its integrated mass spectrometry-spectroscopy platform to anchor premium positions in pharmaceutical process development. Bruker Corporation specializes in magnetic resonance and Raman architectures, sustaining deep relationships with academic and industrial research centers.
Process spectroscopy deploys electromagnetic radiation absorption, emission, or scattering to identify molecular composition and monitor chemical transformations in real time, typically operating across ultraviolet through terahertz wavelengths with resolution thresholds reaching sub-nanometer precision. Its primary industrial purpose centers on enabling continuous manufacturing validation without destructive sampling. Near-Infrared Spectroscopy dominates installed volume due to mature fiber optic probe compatibility and minimal sample preparation requirements. Raman Spectroscopy captures expanding share in bioprocess monitoring where aqueous interference complicates infrared methods. Fourier Transform Spectroscopy occupies the reference-standard tier, commanding margin pools in regulatory filing support and method transfer protocols.
The FDA's Process Analytical Technology framework and EMA's quality-by-design guidelines mandate spectroscopic method validation for real-time release, directly expanding instrument replacement cycles and software compliance spending. REACH chemical characterization requirements and EPA emissions monitoring rules further embed spectroscopic analysis into continuous compliance infrastructure. Stakeholders must weigh captive versus outsourced spectroscopy service models as regulatory scope broadens from quality control into environmental and safety monitoring domains.
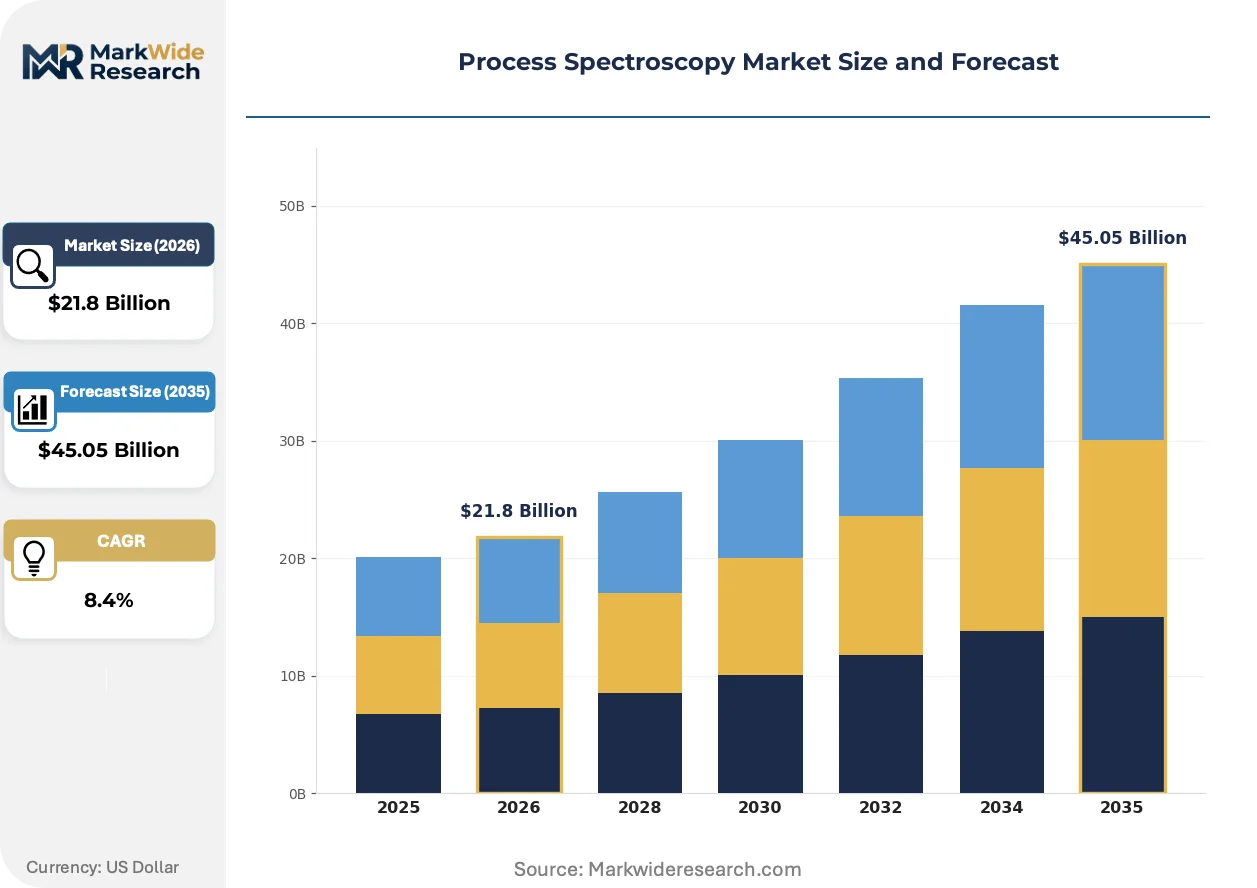
Market Dynamics
Continuous manufacturing mandates from FDA and EMA are compressing batch-release timelines, forcing pharmaceutical producers to replace offline quality labs with embedded spectroscopic sensing networks. This regulatory pressure is restructuring capital allocation toward real-time analytical infrastructure.
Growth Catalysts
- EU GMP Annex 15 revisions:Updated validation protocols for spectroscopic methods are triggering instrument replacement cycles across European pharmaceutical manufacturing facilities.
- Bioprocess aqueous interference:Raman architectures are capturing expanded deployment in cell culture monitoring where infrared methods face signal degradation from water absorption.
- Germany:Merck KGaA and BASF operate advanced process analytical chemistry centers that concentrate regional demand for high-resolution spectroscopic systems.
Market Restraints
- Reference-standard instrument costs:Fourier Transform Spectroscopy systems command premium pricing that limits adoption among mid-cap pharmaceutical producers.
- Specialized optics supply:German and Japanese suppliers dominate precision grating and detector manufacturing, creating geographic concentration risk.
- Method transfer complexity:FDA's Process Analytical Technology framework imposes extensive validation documentation that extends deployment timelines.
Strategic Opportunities
- India:CDSCO's expanding quality-by-design requirements for generic drug manufacturing create underpenetrated demand for in-line spectroscopic monitoring.
- Terahertz-Raman convergence:Hybrid architectures combining terahertz imaging with Raman scattering are opening non-destructive pharmaceutical tablet analysis applications.
- Service model unbundling:Spectroscopy-as-a-service contracts are emerging as an alternative to capital purchase for contract manufacturing organizations.
Industry Challenges
- Chemometric expertise scarcity:Multivariate calibration and spectral interpretation require specialized analytical chemists that outpace current training pipeline output.
- Legacy SCADA integration:Pharmaceutical producers face protocol translation complexity when connecting modern spectroscopic probes to established manufacturing execution systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Process Spectroscopy Market |
| Market Size in 2026 | $21.8 Billion |
| Market Size in 2035 | $45.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Near-Infrared Spectroscopy, Ultraviolet Spectroscopy, Raman Spectroscopy, Fourier Transform Spectroscopy, Terahertz Spectroscopy Technology: Fiber Optic Probes, Laser-Based Systems, Imaging Spectrometers, Interferometers, Multichannel Analyzers Application: Quality Control, Process Monitoring, Material Identification, Reaction Kinetics, Component Verification End User: Chemical Manufacturers, Pharmaceutical Producers, Food Processors, Petrochemical Plants, Cosmetic Laboratories |
| Companies Covered | Thermo Fisher Scientific Inc., Bruker Corporation, Agilent Technologies, Inc., Shimadzu Corporation, ABB Ltd., HORIBA, Ltd., Danaher Corporation, BÜCHI Labortechnik AG, Sartorius AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Process Spectroscopy Market Strategic Shifts & Innovations
Portable and miniaturized spectroscopic architectures are compressing the boundary between laboratory reference methods and production-floor deployment. This hardware evolution is reshaping skill requirements, procurement patterns, and regulatory filing strategies across pharmaceutical and chemical manufacturing.
Handheld Raman spectrometers with embedded chemometric engines are supplanting benchtop systems for raw material identity verification at pharmaceutical receiving docks. Quality assurance teams at contract manufacturing organizations are deploying these units for immediate lot-release decisions. This portability is compressing inventory holding periods and reducing centralized laboratory capital requirements.
EMA's quality-by-design guidelines now mandate spectroscopic method validation for real-time release testing of oral solid dosage forms. Pharmaceutical sponsors must submit multivariate calibration protocols alongside traditional chemistry data in regulatory filings. European generic manufacturers are responding by embedding Fourier Transform-Near Infrared systems directly into tablet press feedback loops.
After-sales service contracts are fragmenting into separate hardware maintenance, software update, and chemometric support subscriptions. Large pharmaceutical buyers are unbundling these elements to source chemometric expertise from specialized consultancies rather than instrument vendors. This disintermediation is most pronounced in Germany and Switzerland where independent analytical service providers have established strong relationships with manufacturing quality departments.
Process Spectroscopy Market Segmentation
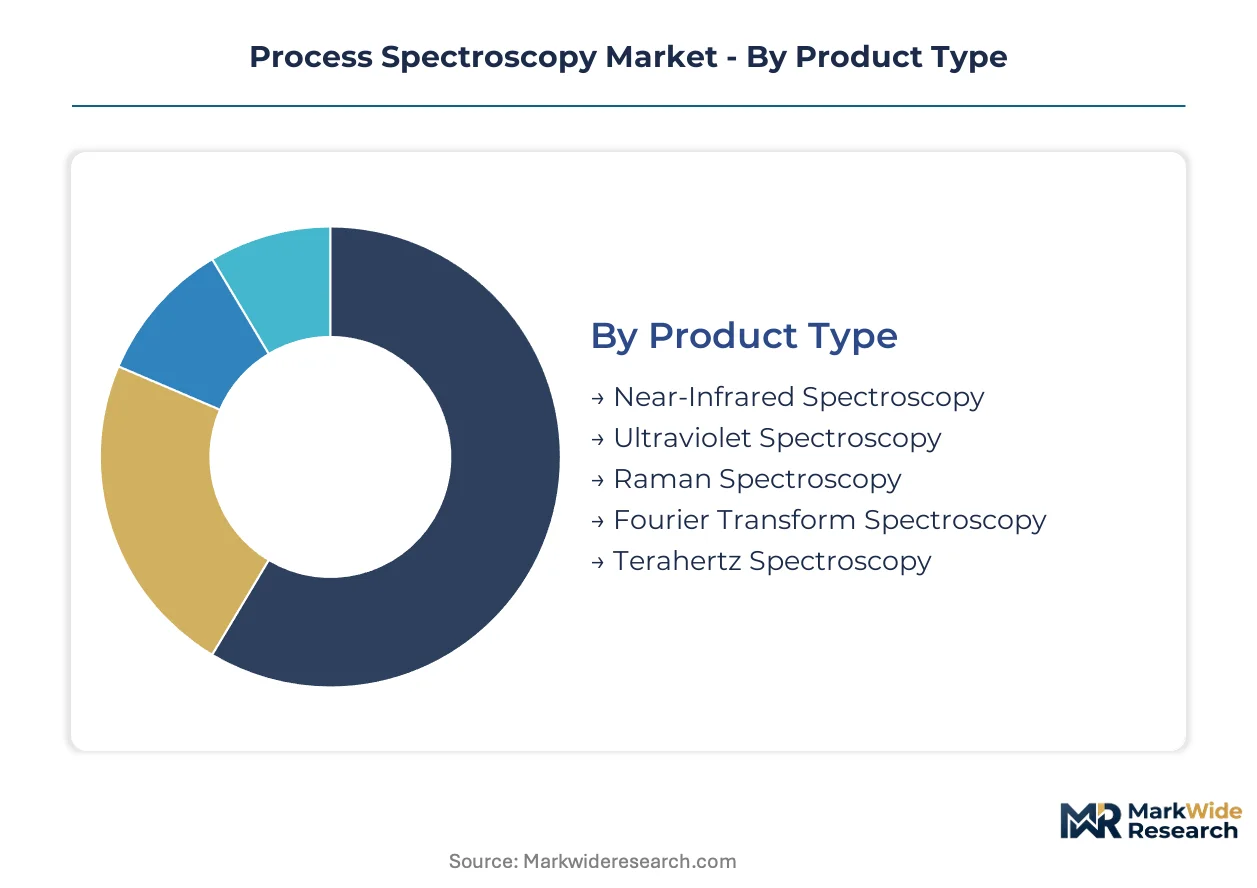
Segmentation in process spectroscopy reveals how regulatory validation tiers and manufacturing complexity drive technology selection. Pharmaceutical producers navigate distinct instrument categories based on FDA Process Analytical Technology requirements versus chemical processors optimizing for throughput economics.
Product Type:
FDA and EMA validation protocols differentiate spectroscopic platforms by documentation burden and reference-standard status, directly shaping procurement patterns across regulated industries.
- Near-Infrared Spectroscopy:Fiber optic probe compatibility enables direct insertion into pharmaceutical manufacturing lines without sample extraction. German pharmaceutical producers at Merck KGaA and BASF facilities deploy these systems for real-time moisture monitoring in solid dosage production, driven by EU GMP Annex 15 validation requirements for continuous manufacturing.
- Raman Spectroscopy:Laser excitation avoids water absorption interference that degrades infrared signals in aqueous bioprocess media. Cell culture monitoring applications at biologics manufacturing sites in Switzerland and Massachusetts are expanding deployment, constrained by higher capital costs and specialized operator training requirements.
- Ultraviolet Spectroscopy:Electronic transition detection suits chromatography detection and purity verification in small-molecule pharmaceutical synthesis.
- Fourier Transform Spectroscopy:Interferometer-based architectures deliver reference-grade precision for regulatory filing support and method transfer protocols.
- Terahertz Spectroscopy:Non-ionizing radiation penetrates opaque packaging for tablet coating integrity assessment without destructive sampling.
Near-Infrared Spectroscopy handles the majority of throughput; Raman Spectroscopy is gaining share fastest in bioprocess applications.
Technology:
Component sourcing concentration in German and Japanese optics manufacturing shapes technology tiering by supply security and lead time exposure.
- Fiber Optic Probes:Silica-based light transmission enables remote sensing in hazardous chemical environments with minimal signal degradation. Petrochemical facilities in Texas and Rotterdam deploy these for reactor monitoring where direct instrument placement risks thermal damage, constrained by probe fouling in viscous process streams.
- Laser-Based Systems:Coherent excitation sources deliver Raman and fluorescence sensitivity for trace-level impurity detection. Biologics contract manufacturers in India are expanding adoption for raw material identity verification, driven by CDSCO quality-by-design mandates for generic drug production.
- Imaging Spectrometers:Spatially resolved detection maps chemical heterogeneity across pharmaceutical tablet surfaces.
- Interferometers:Michelson and Fabry-Perot architectures provide the optical path difference measurement foundation for Fourier Transform platforms.
- Multichannel Analyzers:Photodiode array detection enables simultaneous multi-wavelength acquisition for high-speed process monitoring.
Fiber Optic Probes dominate installed volume; Laser-Based Systems show the steepest expansion trajectory in biopharmaceutical quality assurance.
Application:
Regulatory scope expansion from quality control into environmental monitoring is restructuring application prioritization by compliance burden intensity.
- Quality Control:Spectroscopic method validation for real-time release testing replaces traditional laboratory-based batch release. Oral solid dosage manufacturers in Germany and Switzerland embed Near-Infrared systems directly into tablet press feedback loops, responding to EMA quality-by-design guidelines requiring multivariate calibration protocol submission.
- Process Monitoring:Continuous chemical transformation tracking enables parametric release without intermediate sampling. Continuous manufacturing mandates from FDA are compressing batch-release timelines and forcing replacement of offline quality labs with embedded sensing networks.
- Material Identification:Handheld Raman units at pharmaceutical receiving docks verify raw material identity against certified reference spectra.
- Reaction Kinetics:Time-resolved spectroscopic tracking quantifies conversion rates and intermediate formation in chemical synthesis.
- Component Verification:Packaging and excipient authentication prevents counterfeiting and supply chain contamination.
Quality Control absorbs the largest compliance spending; Process Monitoring is climbing the fastest on capital allocation priority.
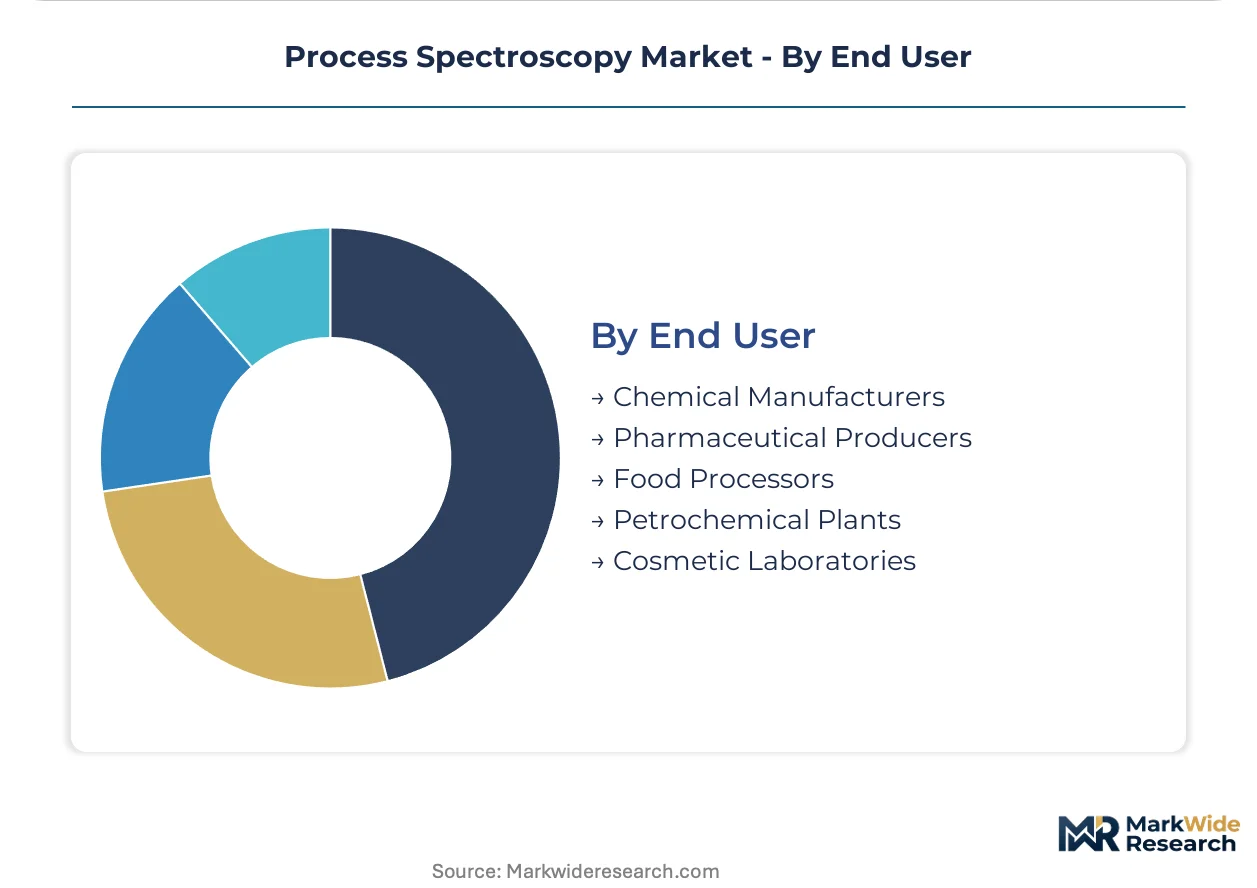
End User:
End-user sophistication with chemometric expertise and regulatory filing experience determines service contract unbundling patterns and vendor selection criteria.
- Pharmaceutical Producers:FDA Process Analytical Technology framework compliance requires extensive validation documentation and specialized analytical chemists. Large sponsors in the US and EU are unbundling after-sales service contracts to source chemometric expertise from independent consultancies rather than instrument vendors.
- Chemical Manufacturers:Continuous production economics prioritize instrument uptime and fiber optic probe durability in corrosive environments. BASF and Dow facilities concentrate demand for ruggedized systems with predictive maintenance capabilities.
- Food Processors:Near-Infrared deployment for moisture, fat, and protein quantification in continuous production lines.
- Petrochemical Plants:Hydrocarbon stream monitoring for distillation column optimization and product specification compliance.
- Cosmetic Laboratories:Raw material verification and formulation consistency testing for premium product lines.
Pharmaceutical Producers command the premium tier; Chemical Manufacturers represent the broadest installed base expansion opportunity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German precision optics clusters while Indian generic pharmaceutical producers face cost compression from CDSCO compliance mandates. This asymmetry reshapes vendor selection criteria across developed and emerging manufacturing bases.
United States
FDA Process Analytical Technology enforcement compresses batch-release timelines for pharmaceutical sponsors. Continuous manufacturing mandates force replacement of offline quality labs with embedded spectroscopic sensing networks. Massachusetts biologics clusters and New Jersey pharmaceutical corridors anchor demand for Raman architectures in cell culture monitoring applications.
Germany
Merck KGaA and BASF operate advanced process analytical chemistry centers that concentrate regional demand for high-resolution systems. EU GMP Annex 15 revisions trigger instrument replacement cycles across European pharmaceutical manufacturing facilities. Bavarian and North Rhine-Westphalian industrial clusters embed Fourier Transform-Near Infrared systems directly into tablet press feedback loops.
Switzerland
Swissmedic quality-by-design guidelines mandate spectroscopic method validation for real-time release testing. Contract manufacturing organizations in Basel and Zurich unbundle after-sales service contracts to source chemometric expertise from independent consultancies. This disintermediation pattern is most pronounced where analytical service providers maintain strong manufacturing quality department relationships.
India
CDSCO expanding quality-by-design requirements for generic drug manufacturing create underpenetrated demand for in-line spectroscopic monitoring. Maharashtra and Gujarat pharmaceutical corridors deploy handheld Raman units for raw material identity verification at receiving docks. Chemometric expertise scarcity constrains deployment velocity despite regulatory pressure.
Japan
PMDA alignment with ICH quality guidelines accelerates spectroscopic method adoption for parametric release. METI industrial technology roadmaps prioritize fiber optic probe durability in corrosive chemical environments. Osaka and Nagoya manufacturing belts concentrate demand for ruggedized systems with predictive maintenance capabilities.
Process Spectroscopy Market Key Industry Players
Concentration sits with diversified analytical instrument conglomerates that leverage integrated platform architectures to anchor premium positions. The vendor base spans three strategic tiers: mass spectrometry-spectroscopy integrators, magnetic resonance and Raman specialists, and modular fiber optic probe fabricators. Competitive moves center on M&A for chemometric software capabilities and strategic partnerships for predictive maintenance service models.
Within the diversified analytical conglomerate tier, Thermo Fisher Scientific Inc., Bruker Corporation, and Agilent Technologies, Inc. exemplify contrasting platform strategies. Thermo Fisher Scientific occupies a position anchored by integrated mass spectrometry-spectroscopy platforms for pharmaceutical process development. Bruker Corporation exemplifies specialization in magnetic resonance and Raman architectures with deep academic and industrial research center relationships. Agilent Technologies represents the chromatography-spectroscopy convergence archetype with electronic transition detection capabilities for small-molecule synthesis monitoring.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Bruker Corporation |
| Agilent Technologies, Inc. |
| Shimadzu Corporation |
| ABB Ltd. |
| HORIBA, Ltd. |
| Danaher Corporation |
| BÜCHI Labortechnik AG |
| Sartorius AG |
| Others |
Cost & Logistics Intelligence
Eighteen-to-twenty-four month lead times for Fourier Transform interferometer assemblies from German optics houses concentrate pricing power with incumbent instrument vendors serving FDA-validated pharmaceutical installations. This supply bottleneck amplifies the premium commanded by configured-to-order spectroscopic platforms against standard modular units.
Pricing Analysis
The customization-premium spread separates reference-grade Fourier Transform systems with embedded chemometric engines from fiber-optic probe bundles sold on specification sheets. Pricing stratifies across premium, standard, and economy tiers according to validation documentation burden and after-sales service bundling. Cost compression in the standard tier is intensifying because Indian generic manufacturers are forcing competitive bidding for handheld Raman units. Contract manufacturing organizations exhibit the highest price sensitivity; Merck KGaA and BASF quality departments show the lowest due to regulatory filing risk aversion.
Supply Chain Analysis
Inventory buffers for precision gratings and InGaAs detectors rarely exceed sixty days, exposing instrument assemblers to disruption from Japanese component foundries and Bavarian optics workshops. German and Japanese suppliers dominate holographic grating manufacturing, while Chinese gallium arsenide foundries feed mid-tier detector assembly. Single-source vulnerability concentrates in Michelson interferometer mirror substrates sourced from Thuringian glassworks. Distribution runs through direct vendor relationships with pharmaceutical quality departments and analytical instrument distributors serving chemical processing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
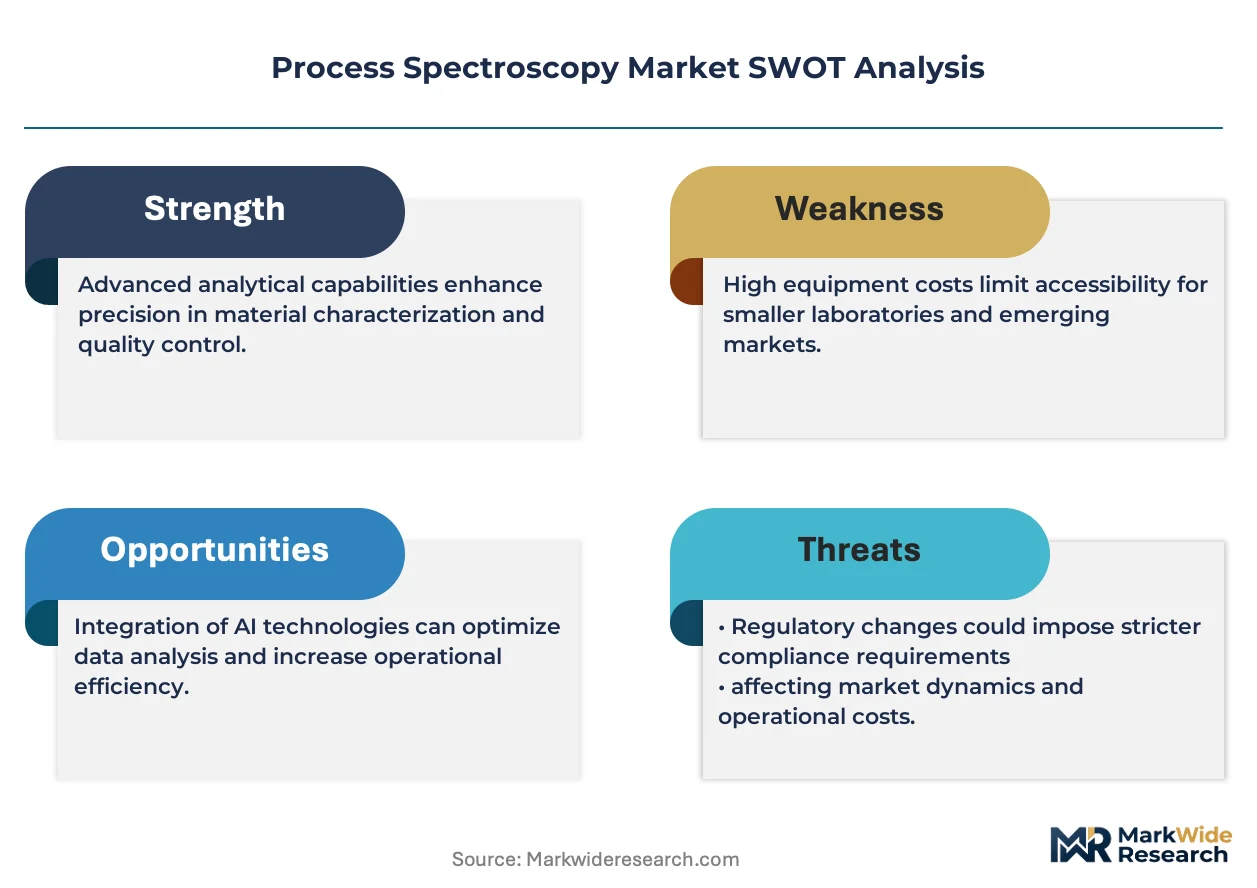
Regulatory fragmentation across FDA, EMA, and CDSCO validation protocols fragments procurement criteria, creating specialist niches for modular probe fabricators and independent chemometric consultancies alongside integrated platform vendors.
For Market Incumbents: Shield installed-base revenue by embedding predictive maintenance algorithms into legacy Fourier Transform platforms before modular competitors capture replacement cycles. Acquire specialized chemometric software capabilities to defend against unbundling trends in German and Swiss pharmaceutical quality departments. Vertical integration into fiber-optic probe manufacturing reduces lead-time exposure from Japanese silica suppliers. For New Entrants and Emerging Players: CDSCO fast-track certification for quality-by-design spectroscopic methods opens immediate deployment opportunities in Maharashtra and Gujarat generic drug corridors. Target handheld Raman verification at pharmaceutical receiving docks where incumbents overprice benchtop alternatives. Partner with independent analytical service providers in Basel and Zurich to bypass direct sales force requirements. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance compounder play because FDA and EMA continuous manufacturing mandates extend instrument replacement cycles indefinitely. Acquire mid-cap modular probe specialists with embedded chemometric engines rather than diversified analytical conglomerates. Watch for CDSCO enforcement acceleration in Indian generic manufacturing as the inflection signal for emerging market demand validation.| Strategic Initiative | Industry Significance |
|---|---|
| Chemometric Software Acquisition | Captures unbundled service revenue from pharmaceutical quality departments seeking independent calibration expertise. |
| Fiber Optic Probe Manufacturing Scale-Up | Reduces lead-time dependency on German and Japanese precision optics suppliers for mid-tier instrument vendors. |
| CDSCO Validation Fast-Track Investment | Accelerates market entry into Indian generic pharmaceutical corridors with quality-by-design compliance mandates. |
| Predictive Maintenance Service Launch | Locks in recurring revenue from BASF and Dow chemical manufacturing facilities prioritizing uptime economics. |
| Terahertz-Raman Hybrid Platform Development | Opens non-destructive pharmaceutical tablet analysis applications beyond incumbent infrared-dominated installed base. |
Research Approach
A spread of perspectives from pharmaceutical quality directors, analytical instrument procurement managers, regulatory affairs specialists, and independent chemometric consultants converged on the working assumptions around FDA Process Analytical Technology enforcement intensity. Primary fieldwork across Massachusetts biologics clusters, Bavarian pharmaceutical manufacturing belts, and Gujarat generic drug corridors combined with secondary validation from FDA 483 inspection observations, EMA quality guideline revisions, and CDSCO compliance circulars. Bottom-up instrument shipment tracking and top-down pharmaceutical capital expenditure analysis triangulated market sizing.
Segmentation dimensions modeled include spectroscopic technology type, probe architecture, application intensity across quality control and process monitoring, and end-user sophistication tier across the projection horizon. CAGRs derived from multivariate regression against pharmaceutical manufacturing capital formation indices and regulatory filing volume trends. Industry-specific forecast inputs incorporated EU GMP Annex 15 revision implementation timelines and Indian generic export growth trajectories.
Underlying assumptions cover sustained FDA and EMA continuous manufacturing mandate enforcement, with deviation risk concentrated in chemometric expertise training pipeline expansion and German precision optics supply disruption. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
5G Devices Market
Others
Telecom Transformers Market
Others
Rotary Union Market
Others
India Smart Home Market
Others
Aluminium Clad Printed Circuit Board Market
Others
Global Enterprise Mobility in Healthcare Market
Others
Enterprise Video Market
Others
Digital Mortgage Software Market
Others
Connected TV Market
Others
Aircraft Exterior Lighting Market
Others
North America Machine Vision Systems Market
Others
Global Compact Wheel Loaders Market
Others
South Asia Geosynthetics Market
Others
Global Contactless Biometrics Technology Market
Others
Remanufacturing-as-a-Service (RaaS) Market
Others
Social Media Engagement Applications Market