
 Spain Feed Additives Market | 2026-2036
Spain Feed Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Feed Additives Market Analytics
Phytase enzymes is expanding their share in mineral-replacement formulations across Spanish compound feed operations. DSM Nutritional Products Inc leverages its premix network to dominate northern Spain's dairy nutrition segment. Cargill Inc anchors its position through direct-to-farm distribution across Extremadura's swine-dense provinces. BASF SE competes on carotenoid and vitamin specialization for layer and broiler integrators.
Feed additives comprise biologically active compounds including vitamins, minerals, amino acids, and enzymes that are incorporated into animal diets at inclusion rates typically below one percent to enhance nutrient utilization, growth performance, or health status. These substances undergo formulation into dry granular, liquid, or micro-encapsulated matrices to ensure stability during pelleting and storage. Amino acids and enzymes capture expanding margin pools as Spanish producers pursue reduced-protein diets to comply with EU nitrogen directives. Poultry applications lead volume absorption due to Catalonia and Aragon's vertically integrated broiler chains, while aquaculture represents the fastest-growing application as Galicia's marine fish farms scale recirculating systems.
Spain's national feed regulator enforces EU-wide bans on antibiotic growth promoters through compliance with EFSA safety assessments and EMA veterinary residue monitoring. The EU Green Deal's Farm to Fork strategy tightens maximum residue limits and pushes additive portfolios toward organic acid and phytogenic alternatives. Stakeholders must monitor how the EU AI Act and evolving CSRD disclosure rules reshape supply chain traceability requirements for feed ingredient sourcing.
Market Dynamics
Spanish compound feed producers face intensifying pressure from the EU Green Deal's nitrogen emission caps, forcing rapid reformulation toward reduced-protein diets that rely on precision amino acid balancing and enzyme supplementation to maintain performance.
Growth Catalysts
- EFSA Safety Assessments:The EU-wide ban on antibiotic growth promoters channels investment into phytogenic and organic acid alternatives, expanding the addressable additive portfolio for Spanish integrators.
- Castile and León Pig Belt:Intensive swine operations in this region drive concentrated demand for phytase enzymes to replace inorganic phosphorus and lower manure mineral loads.
- Recirculating Aquaculture Systems:Galicia's marine fish farms deploy specialized feed additives to manage water quality in closed-loop tanks, creating a high-margin application segment.
Market Restraints
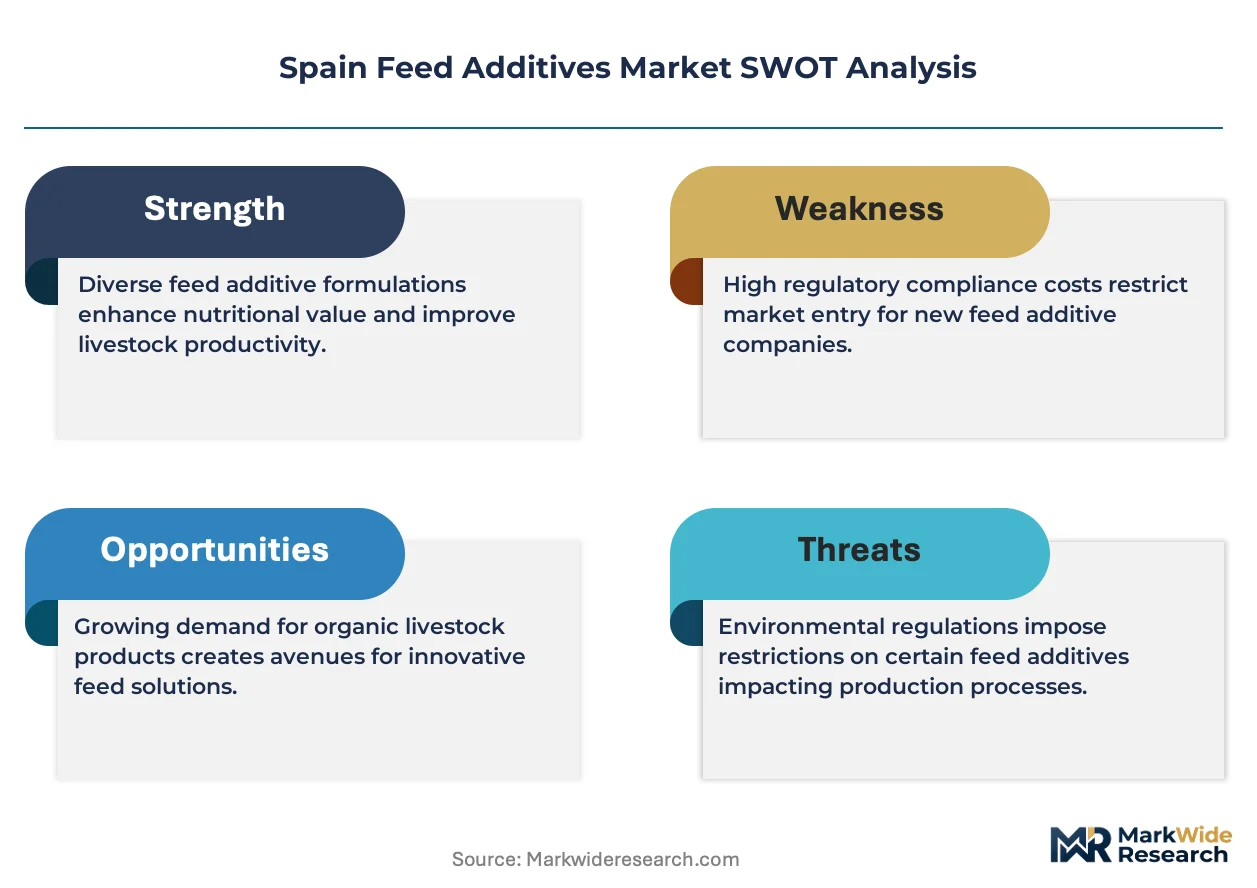
- Feed-Grade Vitamin Concentration:Three suppliers control over 70 percent of European vitamin premix capacity, exposing Spanish blenders to input cost volatility and allocation constraints during supply shocks.
- F-Gas Regulation Compliance:Cooling requirements for certain liquid additive storage systems face tightening refrigerant phase-down schedules, elevating capex for distribution infrastructure in Extremadura and Aragon.
- Plant Protein Substitution Ceiling:Soybean meal remains cost-competitive against synthetic amino acid programs below 16 percent crude protein levels, limiting enzyme penetration in price-sensitive broiler operations.
Strategic Opportunities
- CSRD Disclosure Rules:The EU Corporate Sustainability Reporting Directive mandates supply chain traceability for feed ingredient sourcing, creating first-mover advantage for additive suppliers with verified low-carbon production pathways.
- Catalonia Poultry Cluster:Vertically integrated broiler chains in this region seek carotenoid and vitamin specialization for export-grade layer operations, opening premium formulation contracts.
- Micro-Encapsulation Convergence:Combining lipid coating technology with precision-release matrix design enables heat-stable enzyme delivery through high-temperature pelleting, unlocking new application protocols.
Industry Challenges
- EMA Veterinary Residue Monitoring:Compliance timelines for novel additive approvals stretch 18-24 months, compressing product development cycles and delaying revenue recognition for innovation pipelines.
- Precision Nutrition Skill Gap:Spanish feed mills lack sufficient formulation technologists trained in amino acid digestibility coefficients and enzyme matrix value calculations, constraining diet optimization execution.
- Legacy ERP Integration:Traceability systems required by the EU AI Act for automated supply chain monitoring face friction when interfacing with decade-old feed mill management software.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Feed Additives Market |
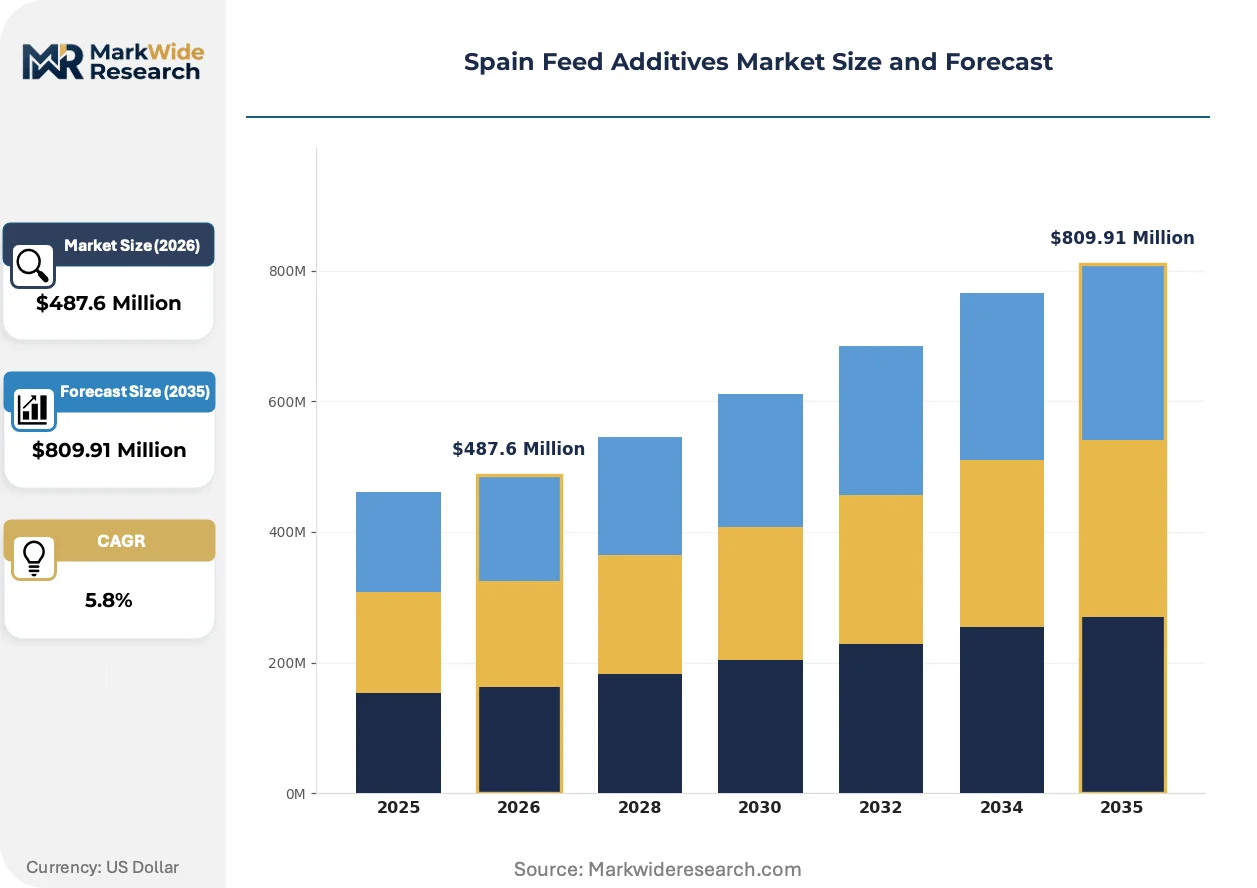
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $809.91 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamins, Minerals, Amino Acids, Enzymes Application: Poultry, Swine, Ruminants, Aquaculture Formulation Type: Dry, Liquid, Micro-encapsulated, Blends Distribution Channel: Retail, Wholesale, Direct Sales, E-commerce |
| Companies Covered | Adisseo, DSM Nutritional Products Inc, Cargill Inc, Evonik Industries AG, Archer Daniels Midland Co, BASF SE, Nanta SA, Nutreco N.V., Alltech, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Feed Additives Market Evolving Landscape
Active reformulation of Spanish livestock diets is compressing traditional additive categories while elevating precision nutrition tools that deliver measurable environmental compliance outcomes alongside performance metrics.
Micro-encapsulated enzyme systems is decentralizing feed manufacturing flexibility by protecting biological activity through pelleting temperatures exceeding 85 degrees Celsius. Medium-scale compounders in Aragon and Valencia adopt these heat-stable formulations to produce specialty starter diets without capital investment in conditioning system upgrades. This technology is decentralizing production geography away from large central mills toward regional blending facilities that serve specific integrator contracts.
The EU Farm to Fork strategy tightens maximum residue limits and pushes additive portfolios toward organic acid and phytogenic alternatives that satisfy EFSA safety assessments. Spanish layer and broiler integrators in Catalonia reformulate rations to eliminate synthetic antioxidant carryover risks that could trigger export market rejections. Pig farming operations in Castile and León accelerate phytase adoption to preempt stricter manure phosphorus application limits anticipated in the next regulatory review cycle.
Buyer concentration among poultry integrators compresses switching cycles and demands unbundled technical service contracts separate from product supply. Large broiler chains in Catalonia and Aragon now procure amino acids through direct manufacturer agreements while sourcing enzymes and vitamins through competing distributors, fragmenting supplier relationships. This pattern concentrates price negotiation leverage with integrators and pressures additive margins in Spain's most volume-intensive application segment.
Spain Feed Additives Market Segmentation
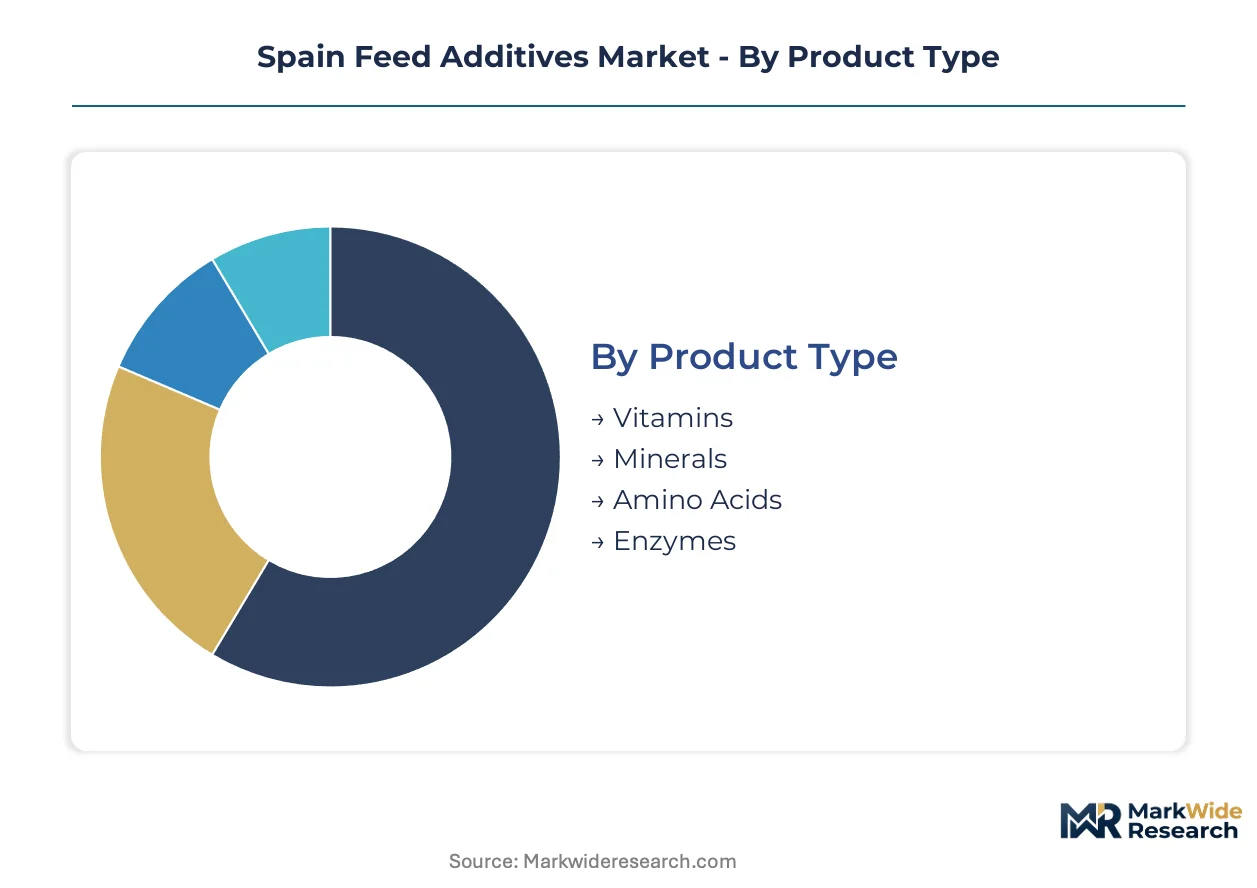
Feed additive purchasing patterns in Spain diverge sharply across livestock sectors, with poultry integrators demanding precision nutrition bundles while swine operators prioritize mineral-replacement economics. Formulation choices and channel preferences further fragment procurement behavior, creating distinct margin pools for suppliers to target.
Product Type:
Spanish compounders differentiate procurement by functional sophistication, with high-value biologicals commanding technical service attachments while commodity minerals compete on logistics efficiency.
- Enzymes:Phytase and carbohydrase formulations enable reduced-protein diet compliance with EU nitrogen directives. Castile and León's intensive pig belt concentrates demand for phytase programs that cut inorganic phosphorus inclusion and lower manure mineral loads for environmental permitting.
- Amino Acids:Synthetic lysine, methionine, and threonine facilitate precision balancing in low-crude-protein rations. Catalonia's vertically integrated broiler chains absorb substantial volumes as they reformulate to preempt EU Green Deal nitrogen emission caps without sacrificing feed conversion ratios.
- Vitamins:Fat-soluble and water-soluble premixes stabilize nutritional profiles across storage cycles. Spanish blenders face allocation constraints from concentrated European premix capacity during supply shocks.
- Minerals:Inorganic and organic trace element sources maintain baseline nutritional adequacy. Extremadura's swine-dense provinces drive steady demand through direct-to-farm distribution networks.
Amino acids lead volumes today; enzymes are gaining share fastest.
Application:
End-use concentration determines service intensity, with aquaculture demanding specialized water-quality additives while poultry procurement fragments across competing distributor relationships.
- Poultry:Layer and broiler operations in Catalonia and Aragon require carotenoid-enhanced formulations for export-grade shell color and yolk pigmentation. Buyer concentration among large integrators compresses switching cycles and demands unbundled technical service contracts.
- Aquaculture:Galicia's marine fish farms deploying recirculating aquaculture systems absorb specialized additives for water quality management in closed-loop tanks. This segment commands premium pricing due to technical complexity and limited qualified suppliers.
- Swine:Intensive operations across Castile and León and Extremadura prioritize phytase adoption to preempt stricter manure phosphorus application limits. Regulatory pressure accelerates reformulation timelines beyond typical procurement cycles.
- Ruminants:Northern Spain's dairy nutrition segment relies on vitamin and mineral premixes for high-production herds. DSM Nutritional Products anchors supply through established premix networks serving this geography.
Poultry leads volumes today; aquaculture climbs the fastest.
Formulation Type:
Manufacturing scale and heat tolerance requirements split procurement between centralized mills investing in conditioning upgrades and regional blenders seeking formulation flexibility.
- Micro-encapsulated:Lipid-coated enzymes and vitamins protect biological activity through pelleting temperatures exceeding 85 degrees Celsius. Medium-scale compounders in Aragon and Valencia adopt these heat-stable systems to produce specialty starter diets without capital investment in conditioning infrastructure.
- Dry:Granular and powder matrices dominate high-volume applications where storage stability and flowability matter. Large central mills serving Catalonia's poultry clusters standardize on dry formulations for operational efficiency.
- Liquid:Pumpable concentrates suit automated dosing systems in industrial aquaculture and select swine operations. F-Gas Regulation compliance elevates cooling capex for liquid additive storage in Extremadura and Aragon distribution nodes.
- Blends:Custom premix combinations address specific integrator specifications for starter, grower, and finisher phases. Regional blending facilities proliferate to serve contract-specific requirements away from central mill geographies.
Dry formulations lead volumes today; micro-encapsulated formats are expanding most quickly.
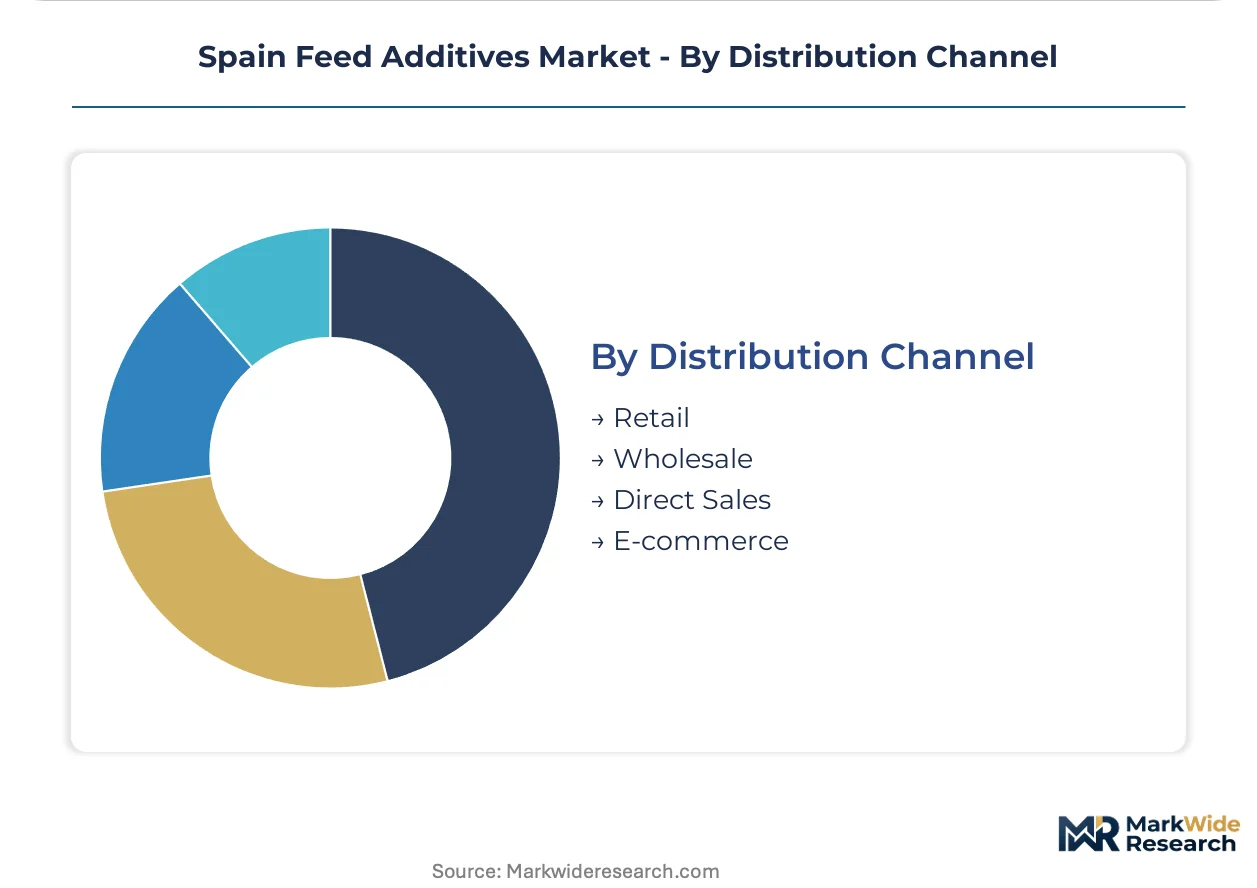
Distribution Channel:
Channel selection tracks customer scale and technical sophistication, with large integrators disintermediating distributors for core inputs while smaller operations rely on bundled service relationships.
- Direct Sales:Cargill anchors its position through direct-to-farm distribution across Extremadura's swine provinces. Large broiler chains in Catalonia procure amino acids through direct manufacturer agreements while fragmenting enzyme and vitamin sourcing through competing channels.
- Wholesale:Regional distributors serve medium-scale compounders and independent feed mills with consolidated additive portfolios. These relationships bundle credit terms, technical support, and logistics coordination.
- Retail:Agricultural supply stores reach smaller livestock operations and hobby farms with packaged vitamin and mineral supplements. This channel captures limited volume but maintains brand visibility among fragmented end-users.
- E-commerce:Digital procurement platforms emerge for standardized additive categories with clear specifications. Traceability requirements under the EU AI Act and CSRD disclosure rules create friction for automated supply chain monitoring through legacy feed mill management systems.
Direct sales lead volumes today; e-commerce shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Catalonia's vertically integrated poultry cluster anchors Spanish feed additive consumption through concentrated broiler and layer operations demanding precision nutrition bundles.
Catalonia
Broiler integrators in this northeastern region absorb substantial amino acid volumes for reduced-protein diet reformulation. EFSA safety assessments channel investment toward phytogenic alternatives as antibiotic growth promoters face EU-wide prohibition. Barcelona-Girona corridor operations seek carotenoid-enhanced formulations for export-grade shell color specifications.
Castile and León
Intensive swine operations across this central plateau drive concentrated phytase enzyme demand for mineral-replacement economics. EU Green Deal nitrogen emission caps force rapid reformulation toward precision amino acid balancing. Valladolid-Palencia pig belt facilities preempt stricter manure phosphorus application limits through accelerated enzyme adoption.
Extremadura
Swine-dense provinces in this western region maintain steady mineral premix consumption through direct-to-farm distribution networks. F-Gas Regulation compliance elevates cooling capex for liquid additive storage infrastructure. Badajoz-Cáceres operations prioritize feed conversion optimization through vitamin and trace element supplementation.
Galicia
Marine fish farms deploying recirculating aquaculture systems absorb specialized water-quality management additives. CSRD disclosure rules mandate supply chain traceability for ingredient sourcing verification. Vigo-A Coruña coastal facilities command premium pricing for closed-loop tank nutrition solutions.
Aragon
Medium-scale compounders in this northeastern region adopt micro-encapsulated enzyme systems for heat-stable pelleting flexibility. EU AI Act traceability requirements create friction with legacy feed mill management software. Zaragoza-Huesca blending facilities decentralize production geography toward regional contract-specific manufacturing.
Spain Feed Additives Market Competitive Landscape
Global majors compete with regional champions across distribution reach and technical service depth, creating a tiered structure where scale advantages fragment against local relationship density. Market concentration splits between diversified nutrition conglomerates and specialized additive pure-plays, with mid-tier blenders occupying intermediary positions. Three archetypes dominate: premix network operators, direct-to-farm distributors, and carotenoid-vitamin specialists. Competitive moves center on unbundled technical service contracts and micro-encapsulation technology licensing.
Within the premix network tier, DSM Nutritional Products Inc anchors northern Spain's dairy nutrition segment through established distribution infrastructure. Cargill Inc exemplifies the direct-to-farm archetype across Extremadura's swine provinces. BASF SE occupies a specialist position serving layer and broiler integrators with vitamin and carotenoid formulation expertise.
| Leading Market Players |
|---|
| Adisseo |
| DSM Nutritional Products Inc |
| Cargill Inc |
| Evonik Industries AG |
| Archer Daniels Midland Co |
| BASF SE |
| Nanta SA |
| Nutreco N.V. |
| Alltech |
| Others |
Value Network & Pricing Analysis
Phytase enzyme costs cascade from concentrated European fermentation capacity through Spanish compound feed operations, with vitamin premix allocation constraints during supply shocks forcing tiered contract structures that separate large integrators from regional blenders.
Pricing Analysis
Input-cost pass-through from feed-grade amino acid and vitamin feedstocks anchors contract negotiations, with three suppliers controlling European vitamin premix capacity enabling allocation-driven price spikes during supply disruptions. Price differentiation separates Catalonia's poultry integrators demanding carotenoid-enhanced premium formulations from Extremadura's swine operators prioritizing mineral-replacement economics. Pricing pressure stems from buyer concentration among broiler chains fragmenting supplier relationships and compressing additive margins. Regional blenders in Aragon and Valencia exhibit highest price sensitivity due to limited volume leverage, while DSM Nutritional Products and Cargill anchor least-sensitive positions through captive distribution networks.
Supply Chain Analysis
Direct-to-farm channels handle hyperscale swine and poultry integrator demand across Extremadura and Catalonia, while wholesale distributors serve medium-scale compounders with consolidated additive portfolios and bundled technical service. Geographic supply concentration centers on Netherlands and Belgium for fermentation-derived amino acids, Germany for vitamin synthesis, and China for select mineral and organic acid intermediates. Raw material dependencies include corn-derived dextrose for microbial fermentation, petrochemical feedstocks for vitamin precursors, and phosphate rock for mineral supplements. Supply chain risk manifests in single-source vulnerability for heat-stable enzyme micro-encapsulation technology. Distribution runs through Cargill's direct-to-farm infrastructure in western Spain and DSM's premix network in northern dairy regions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spain's feed additives market functions as a stable compounder, with EU Green Deal nitrogen emission caps and antibiotic growth promoter prohibitions driving sustained reformulation demand across livestock sectors.
For Market Incumbents: To counter buyer concentration leverage among Catalonia's poultry integrators, deepen technical service unbundling to protect margin pools, and accelerate micro-encapsulation licensing to regional compounders seeking heat-stable formulation flexibility without conditioning infrastructure investment. For New Entrants and Emerging Players: E-commerce procurement platforms for standardized additive categories with CSRD-compliant traceability documentation offer the most penetrable entry vector, targeting medium-scale Aragon and Valencia compounders underserved by incumbent distributor technical intensity. For Investors and Strategic Acquirers: Consolidation pressure builds where CSRD disclosure mandates fragment supplier relationships among sustainability-verified additive pure-plays. Long-term viability favors acquisition of micro-encapsulation technology specialists with validated low-carbon production pathways. The signal to watch is EMA approval timeline compression for novel phytogenic alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Micro-Encapsulation Technology Licensing | Enables regional compounders to bypass capital-intensive conditioning upgrades while maintaining enzyme activity through high-temperature pelleting. |
| CSRD-Compliant Supply Chain Traceability | Creates first-mover advantage for additive suppliers with verified low-carbon production pathways ahead of mandatory disclosure deadlines. |
| Direct-to-Farm Distribution Expansion | Strengthens Cargill's anchor position across Extremadura's swine-dense provinces through unbundled technical service contracts. |
| Phytogenic Alternative R&D Investment | Channels EFSA-aligned innovation pipelines toward organic acid and botanical extract formulations replacing prohibited antibiotic growth promoters. |
| Regional Blending Facility Partnerships | Decentralizes production geography toward Aragon and Valencia contract-specific manufacturing away from Catalonia's concentrated central mill infrastructure. |
Research Methodology
Bottom-up livestock sector modeling reconciled against top-down additive supply tracking forms the analytical core, combining primary interviews with compound feed plant managers, poultry integrator procurement directors, swine operation nutritionists, and distribution channel partners with secondary validation from EFSA safety assessment databases, EMA veterinary residue monitoring reports, EU Green Deal regulatory filings, and Spanish national feed production statistics.
Input-output matrices mapping amino acid inclusion rates, enzyme matrix values, and vitamin premix consumption against livestock population forecasts and feed conversion ratio improvements drive projection mechanics across product type, application, formulation, and distribution channel dimensions. CAGRs derive from segmented growth rate reconciliation against aggregate market expansion. Industry-specific inputs include EU nitrogen directive compliance timelines and F-Gas Regulation refrigerant phase-down schedules affecting liquid additive storage infrastructure.
The model assumes a particular technology adoption path; alternative pathways for micro-encapsulation heat-stability standards would alter the outlook. Forecasts reflect base-case assumptions regarding EMA approval velocity and CSRD implementation enforcement intensity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
UK Cat Food Market
Others
Canada Feed Additives Market
Others
Global Maritime Freight Transport Market
Others
Digital Tattoos Market
Others
Aerospace Tester Market
Others
Global Military Wearable Sensors Market
Others
Asia-Pacific Induced Pluripotent Stem Cells (Ipscs) Market
Others
Port Replicator Market
Others
Edge Computing in Healthcare Market
Others
Rotary Dial Machine Market
Others
CAR T Cell Therapy Market
Others
Synthetic Leather Market
Others
Stand-Up Pouch Valves Market
Others
Global Surface Analysis Market
Others
Asia-Pacific Medical Simulation Market
Others
Refractometer Market