
 Smart Home Technologies Market | 2026-2036
Smart Home Technologies Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Home Technologies Market Analysis
Subscription-based software layers for predictive energy optimization is expanding the recurring revenue base beyond hardware sales. Amazon.com, Inc. leverages its Alexa ecosystem to anchor smart speaker penetration and voice-controlled automation hubs. Samsung Electronics Co., Ltd. sustains competitive positioning through vertical integration across appliances, displays, and proprietary SmartThings protocols. Schneider Electric SE specializes in building-to-grid energy management interfaces that bridge residential solar and utility demand-response programs.
Smart home technologies encompass networked sensor arrays, actuators, and control interfaces that automate residential environmental, security, and entertainment functions through centralized or distributed computing architectures operating on protocols such as Zigbee mesh networks with sub-gigahertz fallback for penetration through building materials. These systems primarily reduce operational energy expenditure, enhance occupant safety through real-time anomaly detection, and consolidate fragmented household device control into unified interfaces. Smart thermostats and smart locks currently command the deepest margin pools as utility rebate programs and insurer premium incentives subsidize upfront costs, while smart appliances face slower replacement cycles tied to durable goods lifespans. Wi-Fi and Zigbee together dominate connectivity architecture, though Z-Wave retains defensible position in security-focused installations where dedicated spectrum isolation matters.
FCC Part 15 rules govern unlicensed radio emissions for smart home devices in the United States, while the EU AI Act imposes conformity assessment obligations on automated decision-making features in climate and security systems sold across Europe. BIS certification requirements in India create compliance barriers for imported IoT hardware, favoring localized assembly partnerships. Stakeholders must monitor evolving interoperability mandates from regulators and standards bodies as fragmentation across proprietary protocols threatens consumer lock-in and retrofit economics.
Market Dynamics
The EU AI Act's conformity assessment obligations for automated climate and security systems are forcing hardware manufacturers to redesign firmware architectures and data processing pipelines before devices can legally enter European markets.
Growth Catalysts
- Utility Rebate Programs:Germany's utility-backed smart thermostat initiatives subsidize upfront hardware costs, compressing payback periods for residential property managers and accelerating device penetration in multifamily housing.
- Building Efficiency Mandates:Stringent energy codes in several European markets require connected environmental controls in new construction and major renovations, creating regulatory pull for integrated sensor-actuator systems.
- Insurer Premium Incentives:Property and casualty insurers in North America and Europe now discount premiums for homes with certified smart security and leak-detection installations, expanding the addressable customer base beyond tech-forward early adopters.
Market Restraints
- Protocol Fragmentation:Proprietary control standards from dominant ecosystem vendors create consumer lock-in and degrade retrofit economics, slowing whole-home automation adoption.
- Silicon Supply Concentration:Zigbee and Z-Wave radio chip fabrication concentrates in Taiwan and mainland China, exposing device manufacturers to geopolitical supply disruptions and export control risks.
- Biometric Data Friction:GDPR's lawful basis requirements and the EU AI Act's high-risk system classification for voice biometric processing impose compliance costs that deter smaller vendors from European market entry.
Strategic Opportunities
- Building-to-Grid Integration:Residential solar plus storage deployments create demand for utility-facing energy management interfaces that aggregate distributed flexibility into demand-response programs.
- Predictive Maintenance Layers:Subscription software for appliance failure prediction and energy optimization represents recurring revenue expansion beyond one-time hardware margins.
- India Localization Partnerships:BIS certification requirements for imported IoT hardware favor joint ventures with domestic electronics assemblers, opening access to price-sensitive mass-market segments.
Industry Challenges
- Cybersecurity Certification Timelines:Common Criteria and IEC 62443 evaluations for connected locks and cameras extend product launch schedules by 8-14 months, compressing effective product lifecycles.
- Legacy System Interoperability:Retrofit installations must bridge incompatible wiring standards and communication protocols from decades-old HVAC and security infrastructure, raising deployment complexity and service costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Home Technologies Market |
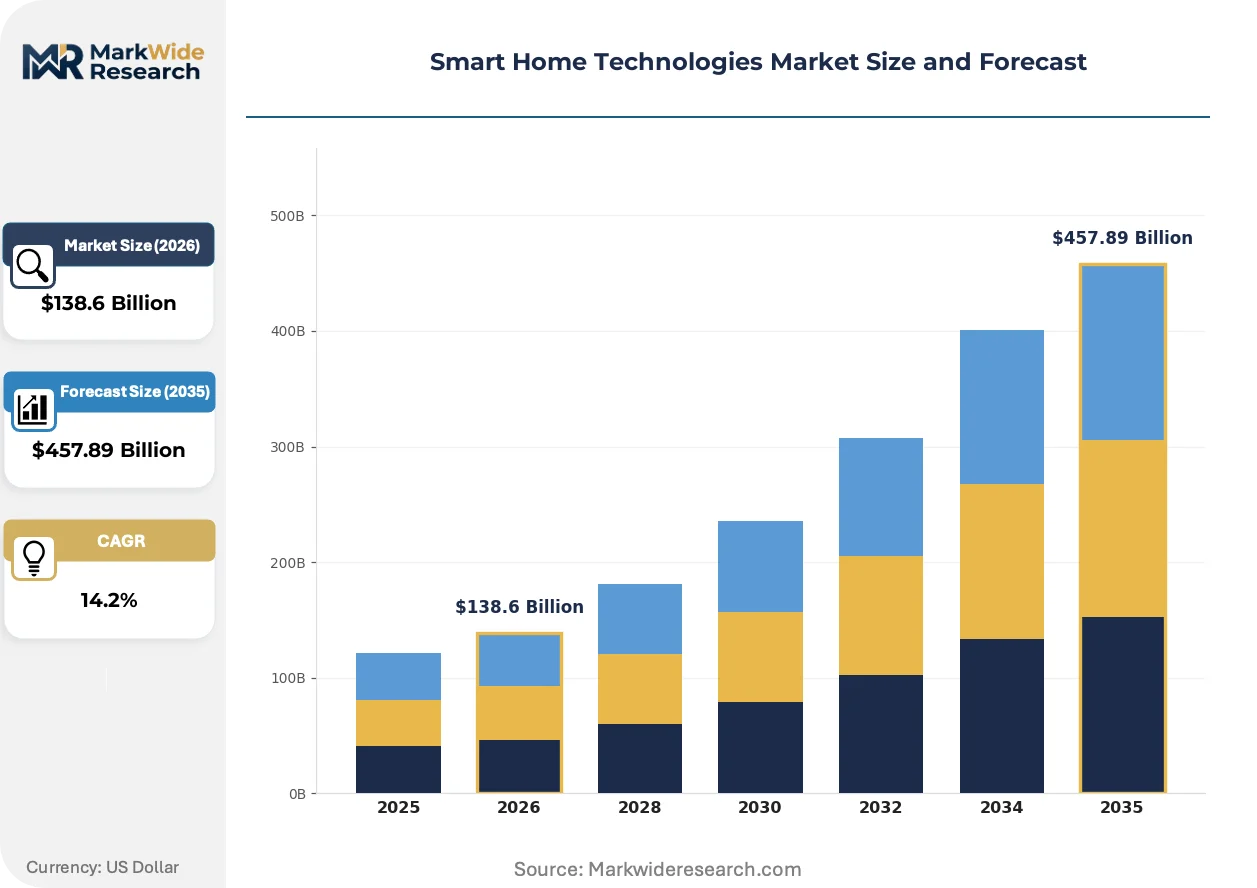
| Market Size in 2026 | $138.6 Billion |
| Market Size in 2035 | $457.89 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Lighting, Smart Thermostats, Smart Locks, Smart Appliances Technology: Wi-Fi, Zigbee, Z-Wave, Bluetooth Application: Home Security, Energy Management, Indoor Climate Control, Entertainment End User: Homeowners, Renters, Property Managers, Hospitality |
| Companies Covered | Amazon.com, Inc., Apple Inc., Samsung Electronics Co., Ltd., Google LLC, Schneider Electric SE, LG Electronics, Inc., Robert Bosch GmbH, Honeywell International, Inc., Siemens AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Home Technologies Market Emerging Trajectories
Matter protocol standardization is actively dissolving ecosystem silos that have fragmented smart home deployment for a decade, enabling cross-vendor device interoperability that reduces consumer switching costs and vendor lock-in.
Edge AI inference engines embedded in thermostats and security cameras are converging with local renewable generation data streams, allowing millisecond-level load balancing decisions without cloud latency. Multi-family housing operators in Germany and the Netherlands are piloting these systems to optimize shared thermal storage against dynamic electricity tariffs. This convergence is compressing the value capture opportunity for cloud-only analytics providers and shifting margin toward silicon-integrated software stacks.
The EU AI Act's high-risk system classification for biometric identification in residential security is compelling vendors to relocate voice and facial processing from cloud servers to on-device silicon. Hardware manufacturers must now document conformity assessment procedures and maintain post-market monitoring systems. Smart doorbell and voice assistant vendors targeting European households are absorbing compliance costs through premium pricing tiers while smaller competitors exit the market.
Property managers are consolidating vendor relationships around full-stack service contracts that bundle hardware, installation, monitoring, and predictive maintenance into per-unit monthly fees. This displaces the traditional model of fragmented procurement from multiple specialized contractors. The shift is most visible in US and German multifamily housing, where institutional owners prioritize operational simplicity and single-point accountability over lowest-first-cost acquisition.
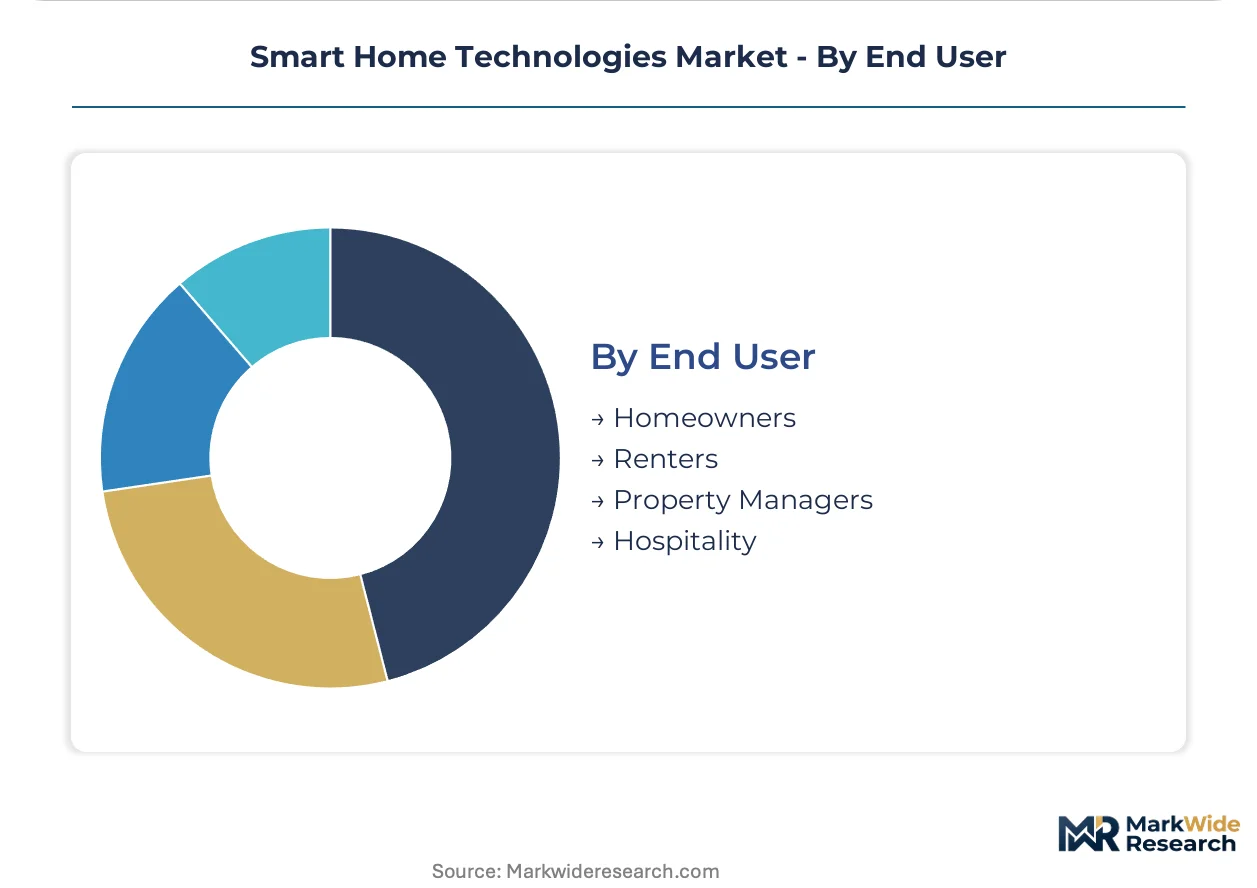
Smart Home Technologies Market Segmentation
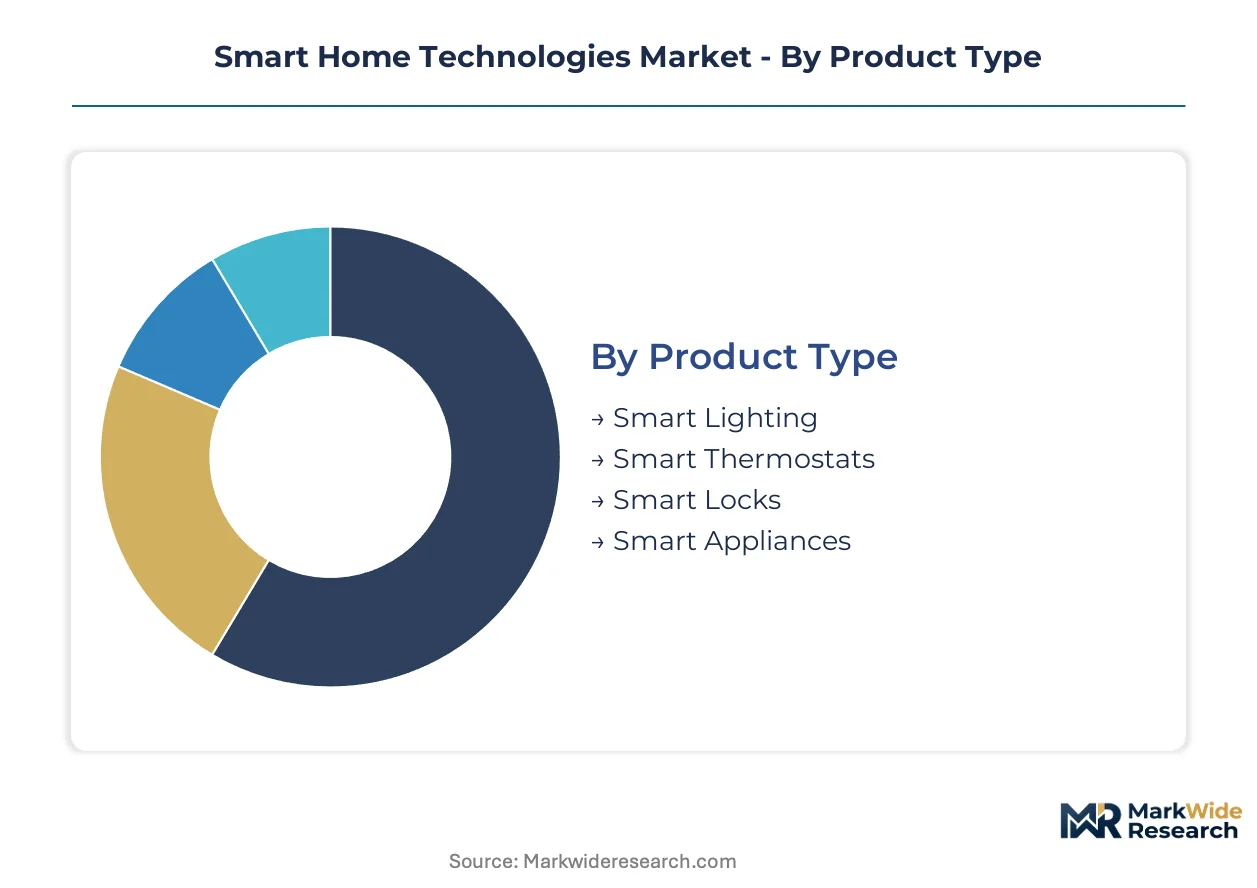
Smart home technologies fragment across four distinct dimensions that shape procurement patterns and margin capture. Product type determines hardware replacement cycles and subsidy eligibility. Technology choice locks in ecosystem compatibility and cybersecurity exposure. Application focus drives utility partnership potential. End user category dictates pricing power and service bundling economics.
Product Type:
Smart thermostats and smart locks command premium pricing pools through utility rebates and insurer incentives, while smart lighting and appliances compete on volume and replacement timing.
- Smart Thermostats:Programmable environmental controllers with occupancy sensing and utility demand-response interfaces. Demand concentrates in German multifamily housing where utility-backed subsidy programs compress payback periods below 18 months.
- Smart Locks:Keyless entry systems with biometric authentication and remote access logging. North American property managers drive procurement volume through insurer premium discounts for certified leak-detection and intrusion-monitoring installations.
- Smart Lighting:Networked LED arrays with circadian tuning and occupancy-based dimming. Residential retrofits in price-sensitive segments favor Wi-Fi-connected bulbs over hub-dependent systems.
- Smart Appliances:Connected refrigerators, washers, and HVAC units with predictive maintenance telemetry. Replacement cycles track durable goods lifespans of 10-15 years, slowing penetration versus retrofit-friendly categories.
Today's leader: Smart Thermostats. Tomorrow's challenger: Smart Locks.
Technology:
Connectivity architecture determines range, power consumption, and interoperability exposure, with mesh protocols dominating whole-home installations while Wi-Fi captures standalone device markets.
- Wi-Fi:Ubiquitous IP-native connectivity requiring no dedicated hubs. Standalone cameras and speakers leverage existing residential infrastructure, though congestion in dense multifamily buildings degrades reliability.
- Zigbee:Low-power mesh protocol with sub-gigahertz fallback for penetration through building materials. German and Dutch multi-family operators pilot edge-AI thermostats using Zigbee for shared thermal storage optimization against dynamic tariffs.
- Z-Wave:Dedicated sub-gigahertz spectrum isolated from Wi-Fi interference. Security-focused installations in North America specify Z-Wave for lock and sensor networks where jamming resistance justifies premium module costs.
- Bluetooth:Short-range protocol for proximity-based device commissioning and temporary guest access. Smart locks use Bluetooth for phone-as-key functionality before falling back to Wi-Fi for remote management.
Mesh protocols are climbing the fastest in multi-device installations; Wi-Fi retains volume leadership in single-point deployments.
Application:
Use-case focus determines regulatory touchpoints and recurring revenue potential, with energy and security applications attracting utility and insurer capital.
- Home Security:Integrated intrusion detection, video verification, and access control systems. GDPR and EU AI Act high-risk classifications for biometric processing force on-device silicon migration, raising hardware costs.
- Energy Management:Load balancing interfaces bridging residential solar, storage, and utility demand-response programs. Schneider Electric and utility partners capture margin through building-to-grid aggregation software.
- Indoor Climate Control:HVAC automation with air quality sensing and predictive thermal modeling. German building efficiency codes mandate connected environmental controls in new construction.
- Entertainment:Unified media control and multi-room audio distribution. Voice-activated platforms face EU AI Act conformity assessments for automated content recommendation algorithms.
Energy applications show steepest expansion trajectory through utility partnership models; security faces compliance cost headwinds in Europe.
End User:
Customer type segments by procurement authority, technical sophistication, and appetite for subscription service bundling.
- Property Managers:Institutional multifamily operators consolidating vendor relationships around full-stack service contracts. US and German institutional owners prioritize single-point accountability over lowest-first-cost acquisition.
- Homeowners:Single-family residents with direct rebate eligibility and DIY installation preference. Matter protocol adoption reduces switching costs and ecosystem lock-in for this segment.
- Renters:Tenants with temporary occupancy horizons favoring portable, hub-free devices and landlord-managed infrastructure. Bluetooth-based solutions dominate this price-sensitive cohort.
- Hospitality:Hotels and short-term rental operators requiring guest-facing automation with centralized management. Energy optimization and contactless check-in drive procurement decisions.
Property managers are gaining share fastest through service contract consolidation; homeowners retain volume leadership in unit shipments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hardware manufacturers are relocating firmware development and data processing operations to jurisdictions with lighter biometric compliance burdens, creating a regulatory-arbitrage dynamic that reshapes regional competitive positioning.
United States
FCC Part 15 rules govern unlicensed radio emissions for Zigbee and Z-Wave devices, while insurer premium incentives for certified smart security installations drive multifamily housing procurement. Property managers in Texas and Florida consolidate vendor relationships around full-stack service contracts that bundle hardware with predictive maintenance.
Germany
Utility-backed smart thermostat subsidies compress payback periods below 18 months for residential property managers, accelerating device penetration in multifamily housing. The EU AI Act imposes conformity assessment obligations on automated climate systems, forcing firmware redesigns before market entry. Edge-AI pilot programs in Berlin and Hamburg optimize shared thermal storage against dynamic electricity tariffs.
China
Dual carbon goals and building efficiency mandates stimulate demand for connected environmental controls in new residential construction. MIIT standards for IoT device interoperability create compliance frameworks that favor domestic protocol ecosystems. Manufacturing clusters in Shenzhen and Shanghai concentrate Zigbee radio module production for export markets.
India
BIS certification requirements for imported IoT hardware create compliance barriers that favor localized assembly partnerships with domestic electronics manufacturers. Price-sensitive mass-market segments drive demand for Wi-Fi-connected standalone devices over hub-dependent systems. Karnataka and Maharashtra host emerging assembly operations targeting residential retrofit applications.
United Kingdom
GDPR's lawful basis requirements for biometric data processing increase compliance costs for voice-activated platform vendors. Building regulations mandating connected environmental controls in new construction align with EU efficiency codes despite post-Brexit divergence. London property managers pilot full-stack service contracts that displace fragmented procurement models.
Smart Home Technologies Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with ecosystem vendors capturing premium pricing through proprietary protocols while white-label assemblers serve price-sensitive retrofit markets. The vendor base concentrates around three strategic archetypes: cloud-platform operators leveraging voice-interface dominance, industrial-electronics conglomerates with building-systems heritage, and vertical-integrated appliance manufacturers. Competitive dynamics revolve around M&A activity targeting energy-management software capabilities and strategic partnerships with utility demand-response programs.
Within the cloud-platform tier, Amazon.com, Inc. and Google LLC anchor ecosystem competition through voice-controlled automation hubs. Samsung Electronics Co., Ltd. exemplifies vertical-integrated positioning across appliances, displays, and proprietary protocols. Schneider Electric SE occupies a specialized niche in building-to-grid energy management interfaces.
| Leading Market Players |
|---|
| Amazon.com, Inc. |
| Apple Inc. |
| Samsung Electronics Co., Ltd. |
| Google LLC |
| Schneider Electric SE |
| LG Electronics, Inc. |
| Robert Bosch GmbH |
| Honeywell International, Inc. |
| Siemens AG |
| Others |
Supply Flow & Price Mechanics
Silicon wafer spot indices from Taiwan and South Korea cascade through Zigbee radio module fabrication into three-tier pricing structures across premium, standard, and economy levels for smart home device OEMs. Utility rebate eligibility and EU AI Act certification tiers stratify final pricing to property managers and homeowners.
Pricing Analysis
Distributor margins of 12-18% separate certified premium-tier devices with on-device biometric processing from standard Wi-Fi-connected alternatives lacking GDPR compliance documentation. Price differentiation hinges on CE marking tier for EU AI Act conformity and volume scale for multifamily housing procurement contracts. Cost compression in the economy tier intensifies as Shenzhen-based assemblers absorb BIS certification overhead for Indian market entry. DIY homeowners exhibit highest price sensitivity; institutional property managers prioritize single-point accountability over lowest unit cost.
Supply Chain Analysis
Container freight rates from Shenzhen to Rotterdam and Long Beach dictate landed cost volatility for hub-dependent Zigbee and Z-Wave device shipments. Zigbee radio chip fabrication concentrates in Taiwan, mainland China, and South Korea, drawing from silicon wafer and rare earth magnet feedstocks. Single-source vulnerability in Taiwan semiconductor foundries exposes device manufacturers to export control disruption. Distribution runs through electronics distributors serving retail channels and direct OEM contracts for property manager bulk procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The smart home technologies market represents a late-cycle quality story as demand shifts toward premium devices with on-device AI inference and EU AI Act certification documentation.
For Market Incumbents: Anchor ecosystem dominance by deepening backward integration into Zigbee radio module production in Taiwan and South Korea to offset geopolitical supply risk. Prioritize firmware architecture redesigns for EU AI Act conformity assessment before smaller competitors exit European markets. Certification investment in Common Criteria and IEC 62443 evaluations defends position against white-label entrants lacking cybersecurity documentation. For New Entrants and Emerging Players: Capture white-space in Indian price-sensitive segments through BIS-certified localized assembly partnerships with Karnataka and Maharashtra electronics manufacturers. Target Wi-Fi-connected standalone devices for renter cohorts with temporary occupancy horizons. Pursue hospitality vertical with contactless check-in and energy optimization bundling as the most penetrable application. For Investors and Strategic Acquirers: Asymmetric upside sits with energy-management software specialists bridging residential solar and utility demand-response programs. Five-to-ten year viability favors vendors with building-to-grid integration capabilities over hardware-only assemblers. Watch for Matter protocol adoption rates as inflection indicator for ecosystem consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Firmware Redesign | Conformity assessment documentation opens European market access while raising compliance barriers for undercapitalized competitors. |
| Building-to-Grid Software Acquisition | Energy management interfaces capturing utility demand-response margins expand recurring revenue beyond one-time hardware sales. |
| India Localization Partnership | BIS-certified domestic assembly unlocks price-sensitive mass-market segments previously blocked by import compliance costs. |
| Matter Protocol Integration | Cross-vendor interoperability reduces consumer switching costs and dissolves ecosystem lock-in that protected incumbent margins. |
| Edge AI Silicon Development | On-device inference engines for thermostats and cameras satisfy GDPR biometric processing requirements without cloud latency. |
Methodological Framework
Coverage spans Germany, the United States, China, and India, with primary inputs from each market cluster combining interviews with smart home platform engineers, multifamily property managers, utility demand-response program officers, and electronics manufacturing procurement leads. Secondary validation draws from FCC Part 15 filings, EU AI Act conformity assessment databases, BIS certification registries, and MIIT IoT interoperability standards. Bottom-up device shipment modeling triangulates against top-down utility rebate program expenditure data.
Granularity-level modeling disaggregates volume and value across product type, connectivity protocol, application focus, and end-user category throughout the forecast period. CAGRs derive from segment-level adoption curves calibrated against building efficiency mandate implementation timelines and insurer incentive program rollouts. Forecast inputs incorporate utility-backed subsidy penetration rates in German multifamily housing and BIS certification timeline assumptions for Indian market entry.
Underlying measurement precision varies by segment; smart thermostat and smart lock categories with established utility partnerships carry tighter precision than emerging edge-AI thermal storage optimization pilots. Forecasts reflect documented assumptions about regulatory implementation timelines and subsidy program continuity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Global Virtual Keyboard Market
Others
Storage Dewar and Dry Shipper Market
Others
Molybdenum-99 Market
Others
South America Orange Market
Others
ASEAN Agricultural Logistics Market
Others
Duty Free Retail Market
Others
Smart Home Water Softener Market
Others
Fiber to the X (Fttx) Tester Market
Others
Global Mobile Video Optimization Market
Others
Durian Market
Others
Thermoformed Plastics Market
Others
Reef Aquarium Market
Others
Hotel Wardrobe Market
Others
Lepidolite Market
Others
Astrology Market
Others
Iran Commercial Vehicles Lubricants Market