
 Belt Press Filter Market | 2026-2036
Belt Press Filter Market Size, Share, and Industry Trends Forecast 2026-2036
Belt Press Filter Market Analytics
Municipal wastewater treatment is hardening as the anchor application for belt press filter deployment. Mining tailings management is softening amid commodity price volatility in key extraction zones. ANDRITZ Delkor leverages its Austrian engineering heritage to dominate high-capacity mining installations across Nordic extraction sites. WesTech anchors North American municipal contracts through deep relationships with regional water authorities. FLSmidth competes in the minerals processing niche with integrated thickener-filter circuits that reduce downstream capital.
A belt press filter is a continuous dewatering device that squeezes slurry between two tensioned porous belts through a series of rollers, typically achieving cake solids content of 15-25% depending on feed characteristics and polymer conditioning. The equipment serves primarily to reduce sludge volume for disposal, cut transportation costs, and enable regulatory compliance in wastewater and minerals processing operations. Horizontal belt press systems occupy the mature volume tier where standardization keeps capital costs predictable for municipal buyers. Vacuum belt press configurations represent the fastest-growing product class as mining operators seek higher throughput per footprint in remote tailings facilities. Advanced filtration technology commands the strongest margin pool because proprietary control algorithms and real-time moisture sensors differentiate premium offerings from commodity belt systems.
EPA effluent limitation guidelines under the Clean Water Act shape municipal procurement specifications across US water treatment plants. China's MEE enforces increasingly stringent discharge standards for industrial wastewater, forcing chemical manufacturing and pulp facilities to upgrade dewatering infrastructure. The EU Urban Wastewater Treatment Directive, reinforced by CSRD-linked environmental disclosures, tightens compliance timelines for European utilities. Stakeholders must monitor how regulatory divergence between jurisdictions affects equipment certification costs and aftermarket service requirements.
Market Dynamics
EPA effluent limitation guidelines and China's MEE discharge mandates are hardening municipal procurement specifications, forcing utilities toward higher-capacity dewatering systems with real-time moisture monitoring and polymer optimization controls.
Growth Catalysts
- EPA Clean Water Act enforcement:Tightening effluent standards across US municipal wastewater plants mandate belt press upgrades to achieve 15-25% cake solids compliance.
- China's Ganga basin cleanup corridors:India's National Mission for Clean Ganga drives belt press deployment across 118 priority towns requiring sludge volume reduction infrastructure.
- Vacuum belt press technology maturation:Mining operators in Nordic extraction zones adopt vacuum configurations for 40% throughput gains per footprint in remote tailings facilities.
Market Restraints
- Polymer conditioning cost volatility:Cationic polymer prices fluctuate with acrylic acid feedstock costs, compressing operating margins for high-throughput municipal installations.
- Centrifuge substitution in compact sites:Decanter centrifuges capture share in space-constrained European utilities where building expansion is restricted by urban density.
- MEE certification complexity:China's environmental equipment certification timeline extends 8-14 months for imported belt press systems, delaying project commissioning.
Strategic Opportunities
- EU CSRD-linked environmental disclosures:The Corporate Sustainability Reporting Directive creates aftermarket demand for sensor retrofits enabling real-time dewatering performance transparency.
- India's industrial cluster densification:Chemical manufacturing corridors in Gujarat and Maharashtra require integrated thickener-filter circuits for zero-liquid-discharge compliance.
- Digital twin convergence with belt press controls:Predictive maintenance algorithms layered on legacy mechanical systems open premium service contract revenue pools.
Industry Challenges
- Polymer chemist skill scarcity:Optimal flocculation dosing requires specialized expertise rarely available in smaller municipal water authorities, forcing reliance on vendor field service.
- Legacy SCADA integration friction:Belt press automation retrofits face protocol mismatches with 1990s-era distributed control systems common in US Midwest treatment plants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Belt Press Filter Market |
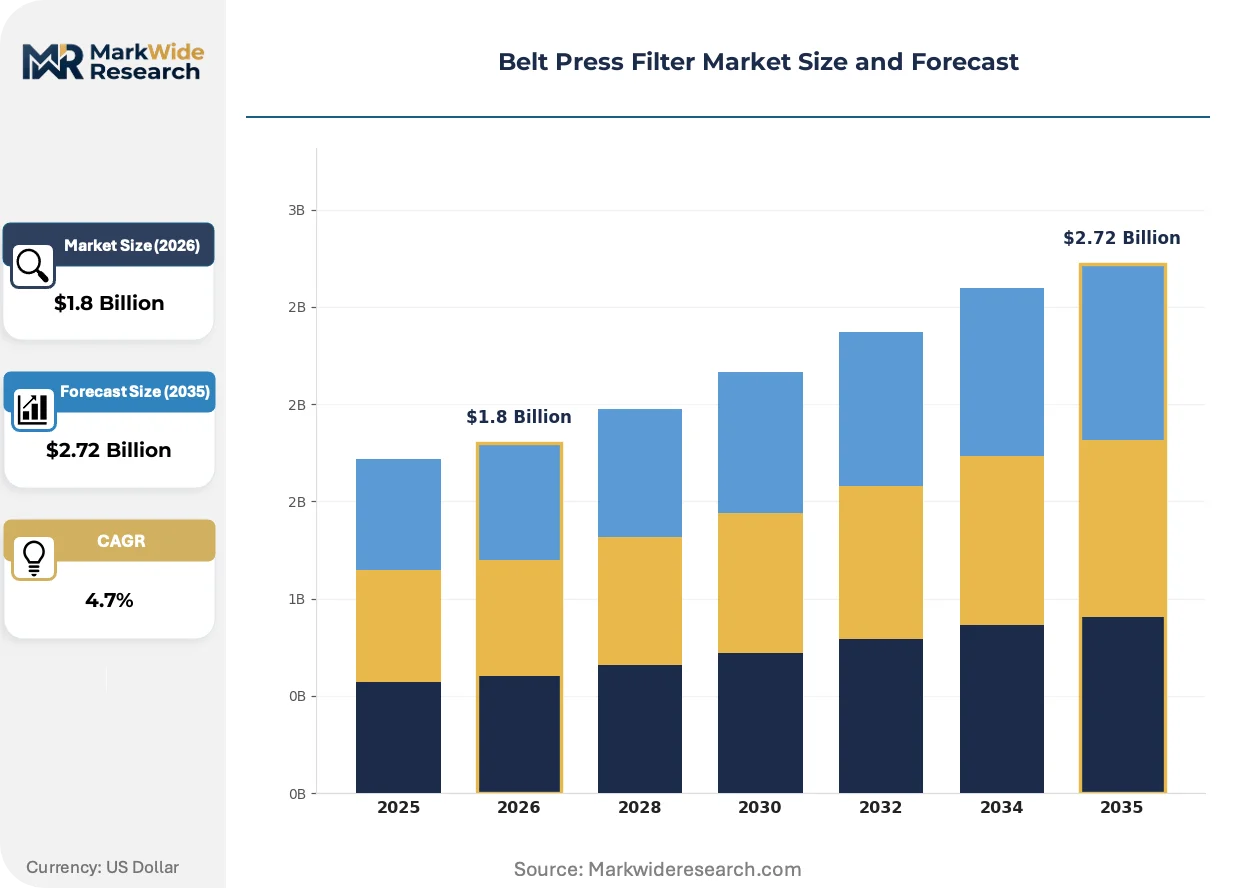
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Horizontal Belt Press, Vertical Belt Press, Vacuum Belt Press, Modular Belt Press Application: Municipal Wastewater Treatment, Industrial Sludge Dehydration, Mining Tailings, Food Processing End User: Water Treatment Plants, Chemical Manufacturing, Pulp & Paper, Oil & Gas Technology: Automatic Control, Manual Control, Hybrid Systems, Advanced Filtration |
| Companies Covered | FLSmidth, WesTech, ANDRITZ Delkor, Compositech, Outotec, Komline-Sanderson Engineering Corporation, Menardi Filter, RPA PROCESS SAS, EIMCO-K.C.P. Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Belt Press Filter Market Evolving Landscape
Real-time moisture sensing and automated polymer dosing are compressing the performance gap between commodity belt systems and premium integrated dewatering lines. Equipment suppliers now compete on algorithmic control rather than mechanical reliability alone.
Machine-vision cake monitoring is rewriting competitive positioning in high-capacity installations. Camera arrays paired with edge-computing modules track cake formation consistency across roller stages, enabling instantaneous belt tension adjustment. Nordic mining operators deploy these systems at remote tailings sites where manual inspection cycles are impractical. The technology is compressing premium vendor margins by commoditizing operator expertise into standardized sensor packages.
China's MEE is enforcing ammonia-nitrogen discharge limits below 5 mg/L for pulp and paper facilities, mandating secondary dewatering stages that belt presses must integrate with biological nutrient removal trains. Jiangsu and Shandong provinces have accelerated compliance deadlines to 2026. Equipment tenders now specify polymer consumption rates and cake dryness guarantees as enforceable performance clauses rather than design specifications.
Performance-based service contracts are displacing traditional capital procurement in European municipal markets. Dutch and German water authorities now contract for guaranteed dry solids tonnage rather than installed equipment capacity. WesTech and ANDRITZ have restructured regional sales organizations around outcome metrics, shifting revenue recognition from shipment to verified throughput. This model concentrates most visibly in the Netherlands where regional water boards consolidate purchasing across multiple treatment sites.
Belt Press Filter Market Segmentation
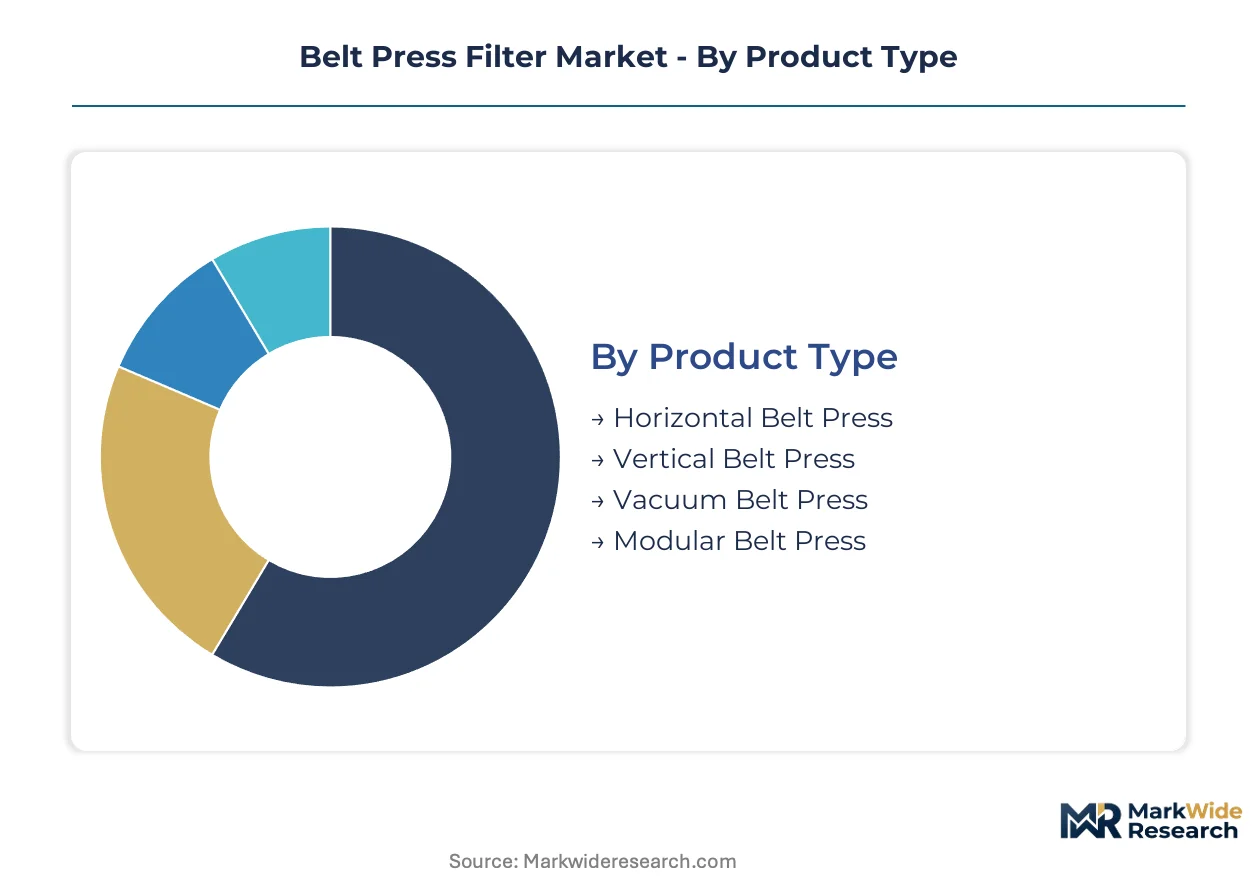
Belt press filter procurement decisions hinge on sludge characteristics, throughput requirements, and regulatory compliance timelines. Equipment specification varies sharply between municipal utilities seeking standardized reliability and industrial operators optimizing for remote-site footprint constraints.
Product Type:
Upgrade cycles differentiate replacement demand across mechanical configurations, with mature horizontal systems facing obsolescence pressure from vacuum and modular alternatives.
- Horizontal Belt Press:Two parallel porous belts squeeze slurry through graduated roller pressure zones, achieving 15-22% cake solids for typical municipal feeds. US Midwest utilities anchor replacement demand as 1990s-era installations reach end-of-design-life.
- Vacuum Belt Press:Negative pressure applied beneath the lower belt accelerates dewatering kinetics, yielding 40% throughput gains per footprint versus gravity-dependent systems. Nordic mining tailings operators in Sweden and Finland drive adoption where remote-site space constraints dominate capex planning.
- Vertical Belt Press:Gravity-assisted slurry distribution reduces polymer conditioning requirements by 12-18% for high-fiber industrial sludges.
- Modular Belt Press:Skid-mounted configurations enable rapid redeployment between seasonal food processing campaigns in California's Central Valley.
Volume placements concentrate in horizontal belt press systems; the faster expansion belongs to vacuum belt press configurations.
Application:
Regulatory enforcement intensity shapes application-tier demand, with discharge mandate timelines compressing procurement cycles in wastewater versus discretionary capital in mining.
- Municipal Wastewater Treatment:Primary and secondary sludge dewatering for EPA Clean Water Act compliance drives the largest installed base. China's MEE discharge mandates for ammonia-nitrogen below 5 mg/L force secondary dewatering stage additions in Jiangsu and Shandong provinces.
- Mining Tailings:Remote tailings facilities require continuous dewatering to reduce impoundment volume and seepage risk. Australian iron ore operators in Western Australia's Pilbara region prioritize vacuum configurations for dust suppression and water recovery targets.
- Industrial Sludge Dehydration:Chemical manufacturing corridors in Gujarat, India deploy integrated thickener-filter circuits for zero-liquid-discharge compliance.
- Food Processing:Seasonal fruit and vegetable processors favor modular systems for campaign flexibility.
Municipal wastewater treatment commands the dominant placement volume; mining tailings applications are climbing the fastest as commodity producers accelerate environmental liability management.
End User:
Customer-scale differentiation separates procurement patterns, with consolidated regional water authorities leveraging volume purchasing against fragmented chemical plant operators.
- Water Treatment Plants:Consolidated Dutch and German regional water boards now contract for guaranteed dry solids tonnage rather than installed capacity, shifting supplier relationships toward performance-based service models.
- Chemical Manufacturing:Zero-liquid-discharge mandates in India's Maharashtra industrial cluster force integrated dewatering infrastructure investments.
- Pulp & Paper:China's MEE enforcement below 5 mg/L ammonia-nitrogen limits mandates belt press integration with biological nutrient removal trains.
- Oil & Gas:Produced water management in US Permian Basin operations favors compact centrifuge alternatives where space-constrained pad sites dominate.
Water treatment plants anchor the volume base; chemical manufacturing end users are gaining share fastest on zero-liquid-discharge compliance deadlines.
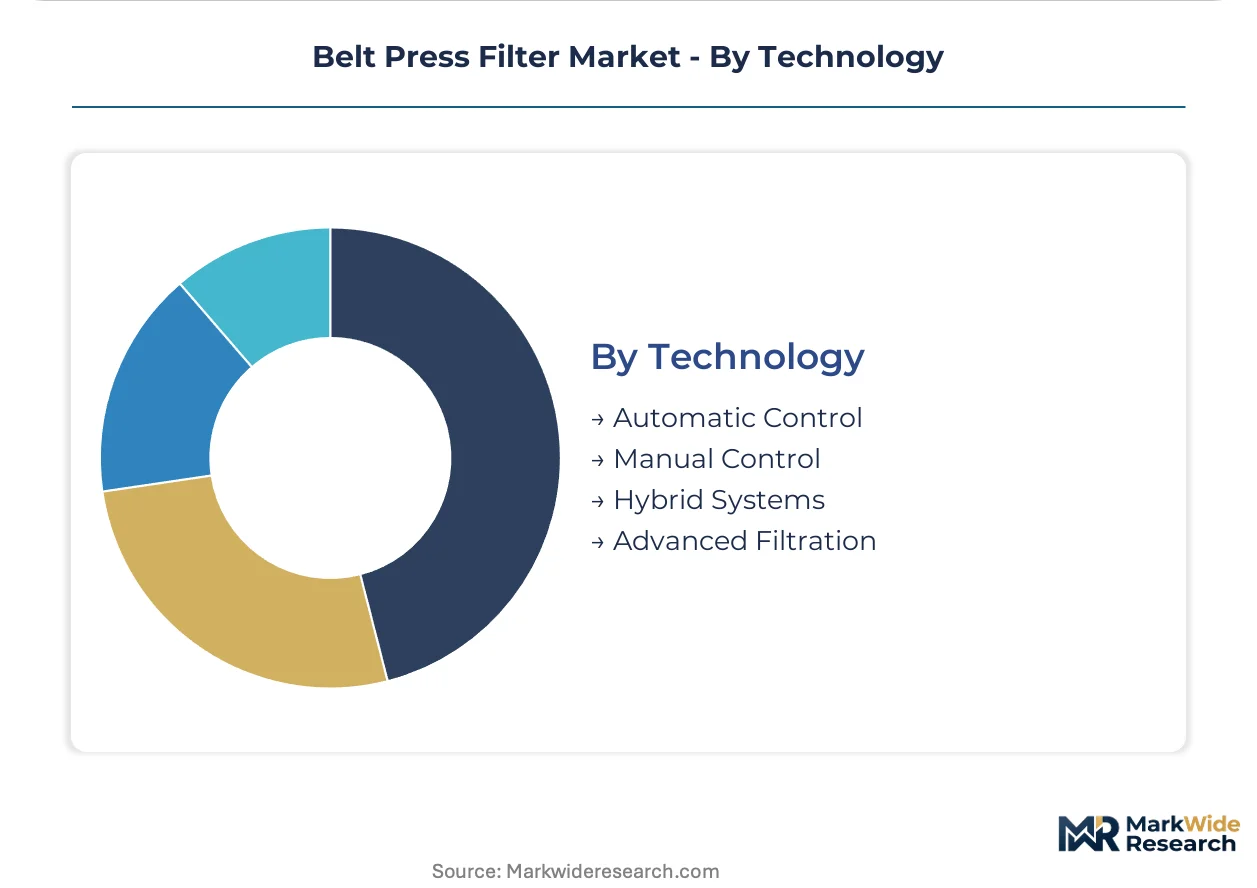
Technology:
Control sophistication tiers separate commodity mechanical systems from premium algorithmic offerings, with sensor integration driving aftermarket retrofit demand.
- Advanced Filtration:Proprietary control algorithms and real-time moisture sensors differentiate premium offerings, commanding strongest margin pools through performance guarantees rather than equipment specification. EU CSRD-linked environmental disclosures create retrofit demand for sensor packages enabling dewatering transparency.
- Automatic Control:Programmable polymer dosing and belt tension adjustment reduce operator dependency for mid-size municipal utilities facing chemist skill scarcity.
- Hybrid Systems:Manual override capabilities preserve operational flexibility during control system maintenance windows.
- Manual Control:Lowest capital entry point for small-scale food processors with seasonal, low-throughput requirements.
Automatic control systems dominate current placements; advanced filtration technology shows the steepest expansion trajectory on premium service contract conversion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment fabrication concentrates in Germany and Austria, while deployment demand clusters in China's industrial corridors and India's cleanup basins. Consumption patterns diverge sharply between mature municipal replacement cycles and emerging market compliance-driven installations.
United States
Midwest utilities drive replacement demand as 1990s-era horizontal belt press installations reach end-of-design-life. EPA effluent limitation guidelines under the Clean Water Act tighten procurement specifications for cake solids compliance. Regional water authorities in Illinois, Ohio, and Michigan consolidate purchasing across multiple treatment sites.
China
Jiangsu and Shandong provinces accelerate belt press deployment for ammonia-nitrogen discharge limits below 5 mg/L. MEE enforcement timelines compress to 2026 for pulp and paper facilities. Chemical manufacturing clusters in the Yangtze River Delta upgrade dewatering infrastructure under dual carbon goals.
Germany
Dutch and German regional water boards pioneer performance-based service contracts for guaranteed dry solids tonnage. EU CSRD-linked environmental disclosures create aftermarket sensor retrofit demand. North Rhine-Westphalia utilities consolidate procurement across Rhine-Ruhr treatment networks.
India
Maharashtra and Gujarat industrial corridors require integrated thickener-filter circuits for zero-liquid-discharge compliance. The National Mission for Clean Ganga drives belt press deployment across 118 priority towns. Chemical plants in the Mumbai-Pune belt face tightening state pollution control board mandates.
Australia
Western Australia's Pilbara iron ore operators prioritize vacuum belt press configurations for dust suppression and water recovery targets. Remote tailings facilities demand 40% throughput gains per footprint. Queensland coal seam gas producers evaluate compact dewatering alternatives for produced water management.
Belt Press Filter Market Competitive Landscape
Top-tier vendors anchor premium integrated systems, while mid-tier fabricators compete on standardized horizontal configurations. The vendor base stratifies across three tiers: algorithmic control specialists, mechanical reliability players, and regional fabrication shops. Competitive moves center on sensor retrofit service contracts and polymer optimization software licensing.
Among Austrian and Nordic engineering groups, ANDRITZ Delkor exemplifies the premium-tier archetype through its mining-tailings specialization. WesTech occupies a position within the North American municipal contracting tier, anchoring regional water authority relationships. FLSmidth sits within the minerals-processing integration tier, representing the thickener-filter circuit bundling approach.
| Leading Market Players |
|---|
| FLSmidth |
| WesTech |
| ANDRITZ Delkor |
| Compositech |
| Outotec |
| Komline-Sanderson Engineering Corporation |
| Menardi Filter |
| RPA PROCESS SAS |
| EIMCO-K.C.P. Ltd |
| Others |
Value Network & Pricing Analysis
China's MEE discharge mandates for ammonia-nitrogen below 5 mg/L gate qualified supply access and premium-tier pricing power for belt press filter vendors. Municipal utilities in Jiangsu and Shandong provinces face compressed procurement timelines, forcing acceptance of performance-guarantee contracts that bundle sensor retrofits at 15-25% markups over base mechanical systems.
Pricing Analysis
Margin tightening in horizontal belt press tiers reflects polymer conditioning cost volatility and centrifuge substitution pressure in space-constrained European sites. Three-tier pricing structure across premium algorithmic-control, standard automatic-dosing, and economy manual systems separates vendors by real-time moisture sensing capabilities. Price differentiation hinges on MEE certification grade and polymer optimization software licensing. Municipal water treatment plants in the US Midwest exhibit highest price sensitivity due to consolidated regional purchasing, while Nordic mining operators show lowest sensitivity for vacuum configurations delivering 40% throughput gains per footprint.
Supply Chain Analysis
Regional distribution centers in Germany and Austria anchor hub-and-spoke patterns serving China's Yangtze River Delta and India's Gujarat industrial corridors. Fabrication concentrates in German engineering clusters and Austrian precision-manufacturing zones, with component sourcing from Swedish steel suppliers and Italian polymer conditioning equipment specialists. Supply chain risk centers on MEE certification timeline extensions of 8-14 months for imported systems. Distribution runs through authorized service networks bundling installation supervision with polymer chemist training.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized polymer chemist talent scarcity props pricing for vendors bundling field service expertise, constraining rapid capacity expansion. Equipment qualification timelines under China's MEE certification framework limit supply elasticity.
For Market Incumbents: Acquire predictive maintenance algorithm portfolios to defend against centrifuge substitution in compact European utilities. Backward integration into cationic polymer supply hedges acrylic acid feedstock volatility. Prioritize MEE pre-certification investments in Jiangsu and Shandong to compress commissioning delays threatening market share. For New Entrants and Emerging Players: Small-scale food processors in California's Central Valley represent an underserved buyer archetype requiring seasonal redeployment flexibility. Modular skid-mounted configurations bypass entrenched municipal procurement relationships. Pursue distributor partnerships with agricultural equipment channels rather than direct water authority contracting. For Investors and Strategic Acquirers: EU CSRD-linked environmental disclosure mandates accelerating sensor retrofit tenders is the leading indicator that aftermarket service contract multiples will expand. Target algorithmic-control specialists with installed bases in Dutch and German regional water boards. Monitor polymer consumption rate guarantees shifting from design specifications to enforceable performance clauses as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Retrofit Service Contracts | EU CSRD disclosures drive real-time dewatering transparency upgrades across Dutch regional water boards. |
| Polymer Optimization Software Licensing | Proprietary dosing algorithms differentiate premium offerings from commodity belt press systems. |
| MEE Pre-Certification Investment | Compressed 2026 compliance timelines in Jiangsu and Shandong provinces reward prepared vendors. |
| Digital Twin Integration | Predictive maintenance layered on legacy mechanical systems opens premium recurring revenue pools. |
| Modular System Development | Skid-mounted configurations capture seasonal food processing demand in California's Central Valley. |
Research Methodology
Trade association filings, customs import records, and municipal procurement databases formed the secondary backbone, supplemented by EPA enforcement action records and China's MEE equipment certification registries. Primary interviews with plant engineers at regional water authorities, aftermarket service heads at belt press distributors, polymer conditioning specialists, and procurement officers at Nordic mining operators combined with secondary validation through bottom-up installation tracking and top-down market sizing triangulation.
Historical trendline analysis of replacement cycles across 1990s-era US Midwest installations and compliance-driven procurement in China's industrial provinces anchored the analytical framework. Segmentation modeling spanned product configuration, application tier, end-user scale, and control technology sophistication across the projection horizon. CAGRs derived from equipment shipment trajectories, polymer consumption intensity correlations, and regulatory deadline clustering. Industry-specific forecast inputs incorporated MEE certification queue lengths and EU CSRD disclosure phase-in schedules.
Revisions become necessary when MEE enforcement timelines accelerate, polymer feedstock costs destabilize, or centrifuge technology achieves comparable cake solids performance. Forecasts reflect assumptions regarding regulatory compliance stickiness and municipal capital budget continuity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Banknote Printing Machine Market
Others
India Data Center Physical Security Market
Others
Automotive Smart Lighting Market
Others
Asia-Pacific Battery E-Commerce Market
Others
Shisha Tobacco Market
Others
Egg and Egg Products Market
Others
Lined Tank Market
Others
Global Alpha Cypermethrin Market
Others
AC Switchgear Market
Others
Kuwait Retail Market
Others
Hearables Market
Others
Refractometer Market
Others
Bicycle Panniers Market
Others
US 3D Printing Construction Market
Others
Fire Sprinkler Market
Others
Global Video Processing Platform Market