
 Africa 3D Printing Construction Market | 2026-2036
Africa 3D Printing Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Africa 3D Printing Construction Market Analytics
A shortage of certified additive manufacturing technicians is collapsing project timelines across East and West Africa. COBOD International leverages its BOD2 gantry system to anchor large-format housing pilots in Kenya and Nigeria. ICON Technology sustains technology leadership through proprietary Lavacrete formulations optimized for tropical climates. RoboForm South Africa dominates local training ecosystems, controlling the pipeline of site-ready operators.
Africa 3D printing construction deploys layer-by-layer material deposition to fabricate structural elements without traditional formwork, typically achieving wall compression strengths of 20–40 MPa through optimized Portland-cement blends with local aggregates. The primary industrial purpose is accelerating affordable housing delivery while reducing labor intensity and material waste on constrained sites. Material Extrusion leads technology adoption because equipment portability suits remote infrastructure projects with limited grid access. Residential end users command the deepest project pipeline, though Infrastructure applications represent the fastest-growing segment as ministries test printed bridge culverts and drainage channels. Concrete materials occupy the dominant share of material type demand, with polymer composites gaining traction in decorative and non-load-bearing applications.
South Africa's National Regulator for Compulsory Specifications enforces SANS building standards that printed structures must satisfy, while Nigeria's Federal Ministry of Works and Housing develops ad-hoc guidelines for additive construction methods. Kenya's National Construction Authority inspects pilot projects against existing structural codes, creating compliance uncertainty that shapes contractor technology choices. Ethiopia's Ministry of Urban Development is drafting Africa's first dedicated 3D construction code, signaling how regulatory first-mover status could redirect regional investment flows. Stakeholders must monitor which national standards bodies formalize printed-construction pathways first, as certification reciprocity will determine cross-border equipment deployment strategies.
Market Dynamics
The Africa 3D Printing Construction Market pivots on a fundamental tension between localized concrete formulation adaptation and the scarcity of certified additive manufacturing technicians capable of deploying gantry systems at scale.
Growth Catalysts
- Affordable housing procurement mandates:Kenya's affordable housing agencies are scaling printed building component contracts. Nigeria's Federal Ministry of Works and Housing pilots are converting into repeatable procurement frameworks.
- Material Extrusion portability:Equipment mobility suits remote infrastructure sites with limited grid access. Ministries across East and West Africa are testing printed bridge culverts and drainage channels.
- SANS building code pathways:South Africa's National Regulator for Compulsory Specifications is revising standards to accommodate printed structural elements. Gauteng province pilots are accelerating site readiness for commercial deployment.
Market Restraints
- Portland-cement blend volatility:Local aggregate sourcing inconsistency disrupts compression strength targets of 20–40 MPa. Supply chain fragmentation across Nigeria and Kenya extends material qualification timelines.
- Equipment import concentration:Gantry system supply concentrates with European and North American manufacturers. Currency instability in Lagos and Nairobi corridors inflates landed equipment costs.
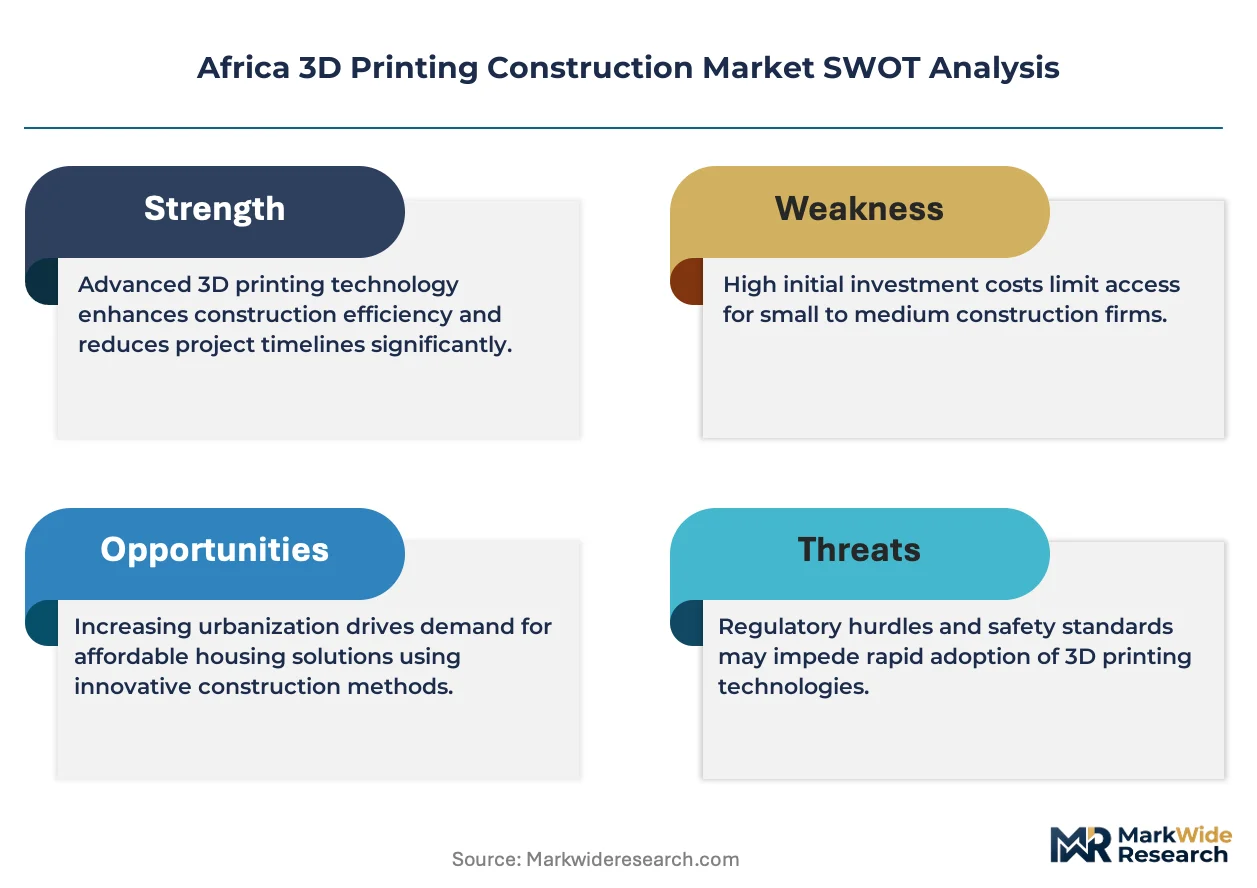
- Code compliance uncertainty:Kenya's National Construction Authority inspects pilots against legacy structural codes without additive-specific pathways. Contractor technology choices stall pending formal certification frameworks.
Strategic Opportunities
- Ethiopia's dedicated 3D construction code:The Ministry of Urban Development is drafting Africa's first purpose-built regulatory framework. First-mover certification reciprocity could redirect regional equipment deployment flows.
- Polymer composite decorative applications:Non-load-bearing printed elements are gaining traction in interior fit-out and facade cladding. Lagos corridor developers are specifying composite finishes for premium residential towers.
- Training ecosystem localization:South African operator certification programs are expanding into Kenya and Nigeria. RoboForm's pipeline control creates franchisable knowledge transfer models for regional scaling.
Industry Challenges
- Certified technician pipeline collapse:Project timelines across East and West Africa are compressing due to additive manufacturing operator shortages. Training throughput lags behind gantry system deployment schedules.
- Cross-border equipment mobility friction:Certification reciprocity gaps between South Africa, Nigeria, and Kenya block seamless gantry relocation. Customs classification disputes for printed construction equipment delay site mobilization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa 3D Printing Construction Market |
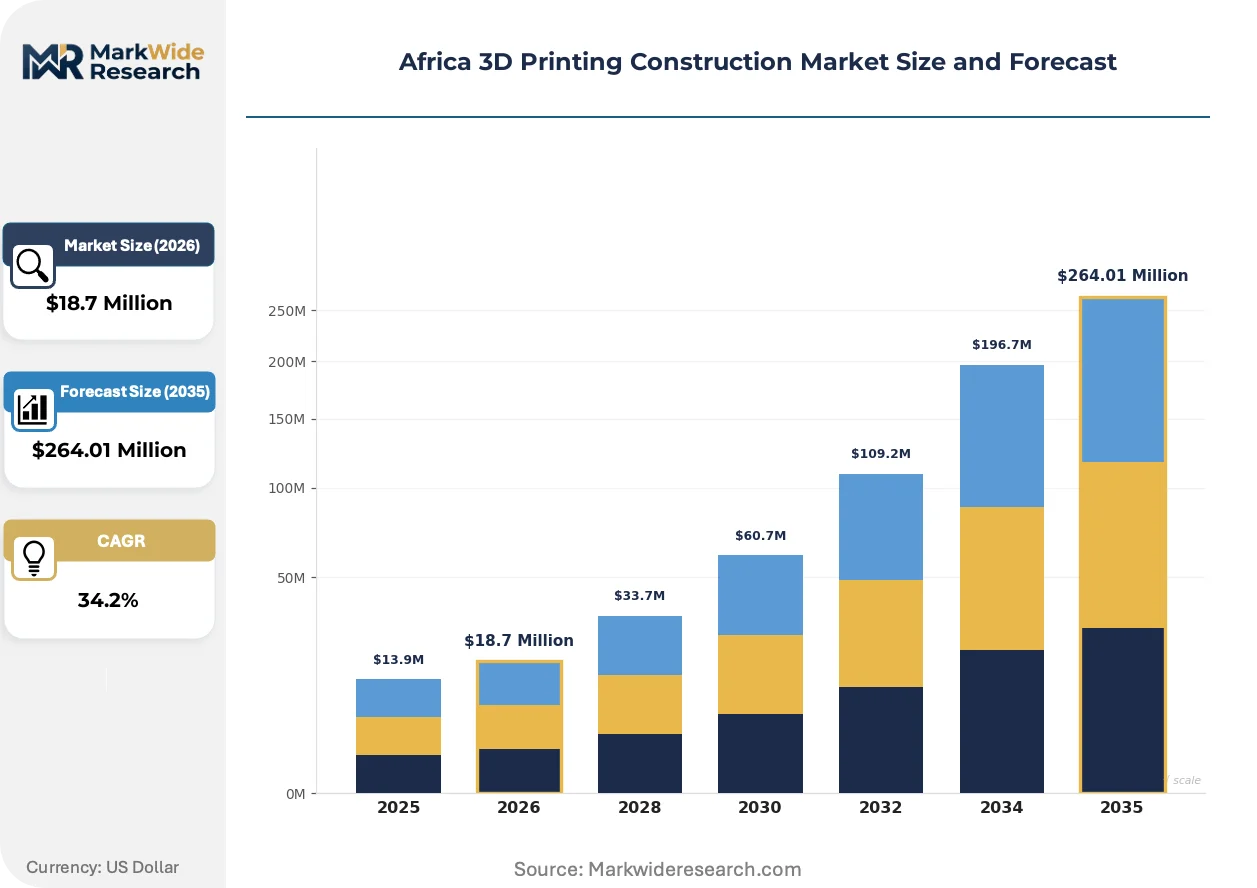
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $264.01 Million |
| CAGR (2026 – 2036) | 34.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Material Extrusion, Powder Bed Fusion, Vat Polymerization, Binder Jetting End User: Residential, Commercial, Infrastructure, Industrial Material Type: Concrete, Polymer, Metal, Composite Application: Building Components, Custom Structures, Prototyping, Art Installations |
| Companies Covered | RoboForm South Africa, AMT South Africa, Be More 3D, COBOD International, Apis Cor, ICON Technology, Betabram, CyBe Construction, Construction 3D, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa 3D Printing Construction Market Evolving Landscape
Layer-by-layer deposition systems are restructuring how affordable housing delivery intersects with tropical climate material science. Three active developments are compressing traditional construction timelines.
Optimized Lavacrete formulations are decomposing conventional Portland-cement dependency in high-humidity environments. Affordable housing agencies in Kenya's coastal counties are specifying these blends for pilot projects. The technology is decomposing legacy formwork supply chains by eliminating reusable mold inventory requirements.
South Africa's National Regulator for Compulsory Specifications is accelerating SANS standard amendments for printed structural walls. Industrial consequence includes accelerated building plan approval pathways for certified additive contractors. Gauteng province developers are responding by pre-qualifying gantry-equipped construction firms for municipal housing tenders.
Buyer specification patterns are rotating toward performance-guaranteed wall systems rather than material-grade procurement. Lagos corridor developers are unbundling structural printing from finishing trades in contract structures. This behavioral shift is most visible in Nigeria's affordable housing segment, where ministries are testing unit-price contracts for printed shell delivery.
Africa 3D Printing Construction Market Segmentation
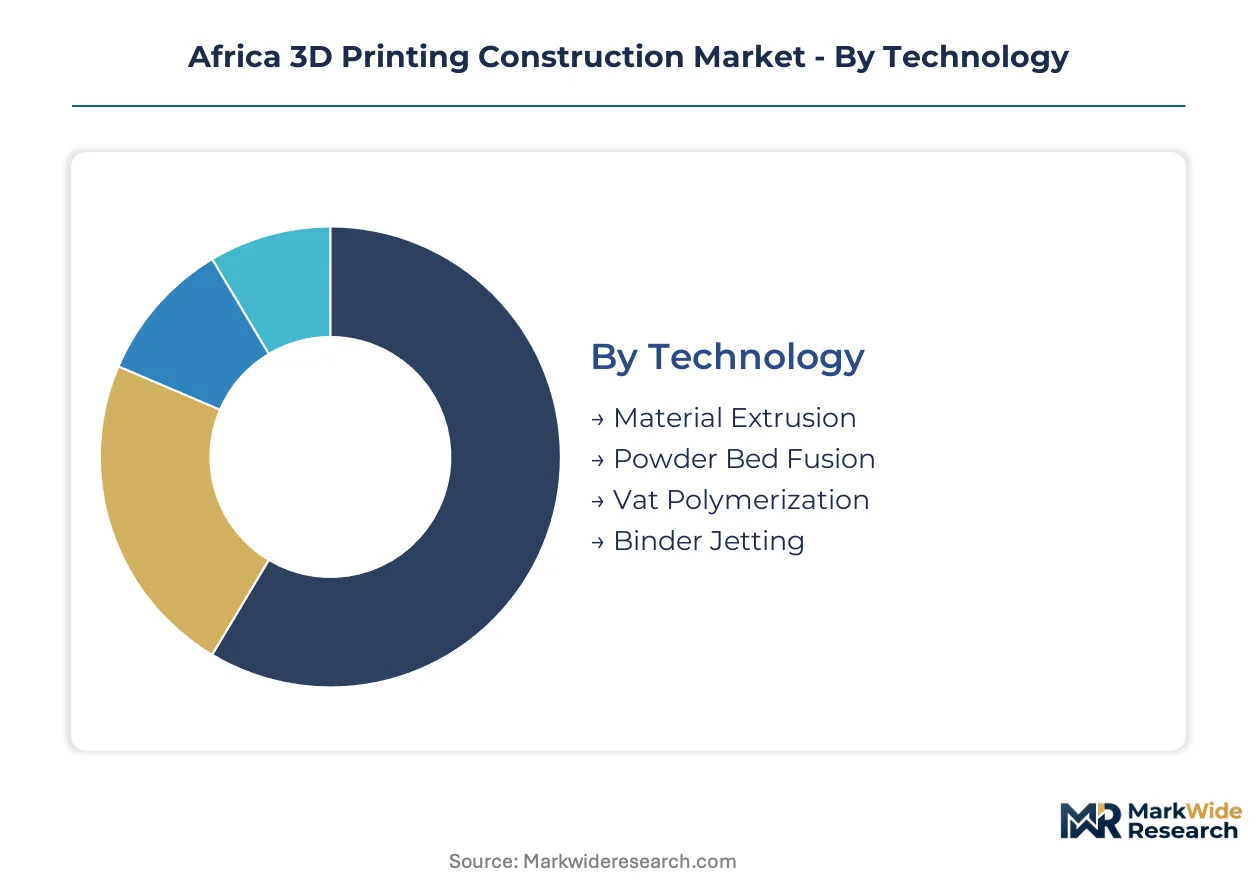
Technology choice in Africa's 3D printing construction market hinges on regulatory acceptance pathways and site infrastructure constraints. Segmentation reveals how material science, end-use requirements, and application complexity fragment procurement patterns across Kenya, Nigeria, and South Africa.
Technology:
South Africa's SANS building standards and Kenya's National Construction Authority inspection protocols create divergent certification timelines for each additive manufacturing approach.
- Material Extrusion:Layer-by-layer deposition of Portland-cement blends with local aggregates achieves 20–40 MPa compression strength. Demand concentrates in Kenya's coastal counties and Nigeria's Lagos corridor, where equipment portability suits remote sites with limited grid access.
- Powder Bed Fusion:Selective laser sintering of polymer and metal powders produces high-precision structural connectors. South Africa's Gauteng province dominates uptake for complex architectural nodes in premium residential towers.
- Vat Polymerization:Photopolymer resin curing fabricates detailed decorative elements and facade mock-ups. Lagos developers specify these for client visualization in pre-construction phases.
- Binder Jetting:Liquid binding agents fuse sand or metal powder layers for tooling and mold production. Nigeria's Federal Ministry of Works and Housing pilots use this for drainage channel formwork.
Material Extrusion handles the majority of throughput; Powder Bed Fusion is expanding most quickly on share as precision requirements intensify.
End User:
Procurement scale varies sharply between state-backed affordable housing mandates and private commercial development timelines.
- Residential:Affordable housing agencies in Kenya and Nigeria command the deepest project pipeline. South Africa's Gauteng province converts pilot projects into repeatable municipal contracts for printed wall shells.
- Infrastructure:Ministries across East and West Africa test printed bridge culverts and drainage channels. This segment climbs the fastest as material extrusion portability unlocks remote civil works.
- Commercial:Private developers in Lagos and Nairobi specify printed structural elements for mid-rise office and retail. Building plan approval delays constrain deployment velocity.
- Industrial:Warehouse and logistics facility operators trial printed column bases and foundation pads. South Africa leads with SANS-compliant industrial pilots.
Residential absorbs the largest contract volume; Infrastructure shows the steepest expansion trajectory as public procurement frameworks mature.
Material Type:
Local aggregate sourcing consistency determines which material classes can meet structural code requirements across national jurisdictions.
- Concrete:Optimized Portland-cement blends with tropical climate adaptations dominate load-bearing applications. Kenya's National Construction Authority inspects these against legacy compression standards.
- Polymer:Thermoplastic composites gain traction in decorative and non-load-bearing interior fit-out. Lagos corridor developers specify polymer finishes for premium residential facade cladding.
- Metal:Powder-based additive manufacturing produces structural connectors and reinforcement nodes. South Africa's industrial base supports localized metal powder supply chains.
- Composite:Fiber-reinforced polymers bridge structural and aesthetic requirements in custom architectural elements. Nigerian pilots test glass-fiber blends for coastal humidity resistance.
Concrete commands the dominant procurement share; Polymer is gaining share fastest as finishing specifications unbundle from structural contracts.
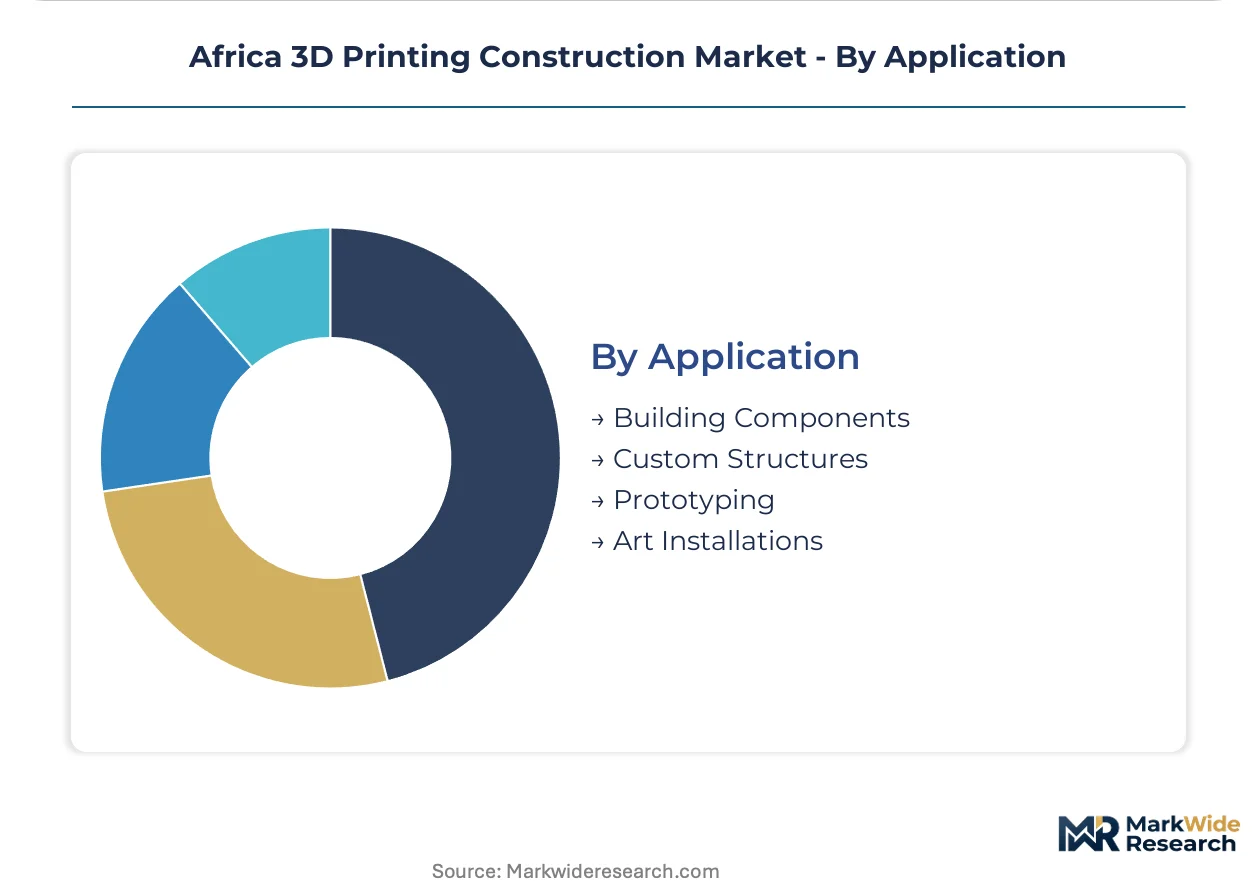
Application:
Project complexity tiers separate mass-customized housing components from one-off architectural commissions.
- Building Components:Standardized wall panels, floor slabs, and roof elements accelerate affordable housing delivery. Kenya's procurement agencies scale unit-price contracts for printed shell delivery.
- Custom Structures:Bespoke architectural forms and non-standard geometries serve premium residential and cultural projects. South Africa's SANS amendment process enables code-compliant custom approvals.
- Prototyping:Reduced-scale structural mock-ups validate design assumptions before full-scale deployment. Nigerian ministries require these for drainage channel pilot validation.
- Art Installations:Sculptural and commemorative structures exploit geometric freedom of additive methods. Kenya's coastal counties commission these for tourism infrastructure.
Building Components carries the bulk of production volume; Custom Structures is climbing fastest as code pathways formalize for non-standard geometries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in South Africa's Gauteng corridor while Nigerian operators absorb currency-driven equipment cost premiums. Kenya's coastal counties command intermediate positioning through localized concrete formulation capabilities. Ethiopia's regulatory first-mover status is redirecting investment flows across East Africa.
South Africa
Gauteng province developers are pre-qualifying gantry-equipped construction firms for municipal housing tenders. The National Regulator for Compulsory Specifications is revising SANS building standards to accommodate printed structural elements. Johannesburg-Pretoria corridor pilots are accelerating commercial deployment timelines through accelerated building plan approvals.
Nigeria
Lagos corridor affordable housing agencies are converting Federal Ministry of Works and Housing pilots into repeatable procurement frameworks. The ministry is developing ad-hoc guidelines for additive construction methods without dedicated statutory pathways. Currency instability in Lagos inflates landed equipment costs for European-manufactured gantry systems.
Kenya
Coastal county affordable housing agencies are scaling printed building component contracts for tropical climate adaptation. The National Construction Authority inspects pilot projects against legacy structural codes without additive-specific certification pathways. Mombasa-Nairobi corridor contractors face compliance uncertainty that shapes technology deployment choices.
Ethiopia
Addis Ababa-based ministries are testing printed structural elements for state-backed housing delivery programs. The Ministry of Urban Development is drafting Africa's first dedicated 3D construction code. Regulatory first-mover status is positioning Ethiopia to attract cross-border equipment deployment from regional contractors seeking certification reciprocity.
Ghana
Accra corridor developers are specifying printed wall shells for mid-rise residential towers in emerging urban districts. The country's national construction regulator is observing Ethiopian and South African code development before formalizing local pathways. Tema industrial zone fabricators are importing polymer composite materials for non-load-bearing facade applications.
Africa 3D Printing Construction Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the African 3D printing construction market. The vendor base clusters around three strategic groupings: European equipment manufacturers with proprietary gantry systems, regional training and certification specialists controlling operator pipelines, and materials science firms optimizing tropical climate formulations. Competitive moves concentrate on technology licensing partnerships and localized training ecosystem expansion.
Within the European equipment tier, COBOD International and ICON Technology anchor proprietary system deployment across Kenya and Nigeria. RoboForm South Africa exemplifies the regional specialist archetype through training pipeline control. These three occupy positions spanning equipment supply, materials optimization, and workforce certification that collectively determine project readiness timelines.
| Leading Market Players |
|---|
| RoboForm South Africa |
| AMT South Africa |
| Be More 3D |
| COBOD International |
| Apis Cor |
| ICON Technology |
| Betabram |
| CyBe Construction |
| Construction 3D |
| Others |
Value Network & Pricing Analysis
Gantry system manufacturing scale in Denmark and the United States anchors price floors across African deployment corridors, compressing margins for regional distributors while elevating barriers for uncertified equipment entrants. Equipment import concentration in Lagos and Nairobi corridors amplifies landed cost volatility, forcing contractors to absorb currency-driven premiums or defer procurement.
Pricing Analysis
Configured-to-order gantry system pricing commands premiums of 25-40% above standard BOD2 configurations due to tropical climate concrete formulation requirements. Three-tier pricing structure across premium certified, standard compliant, and economy provisional tiers separates SANS-compliant South African deployments from Kenyan pilot projects awaiting National Construction Authority pathways. Cost compression in economy tiers is intensifying because currency instability in Nigerian naira and Kenyan shilling inflates European equipment landed costs. Affordable housing agencies in Kenya's coastal counties exhibit highest price sensitivity, while Gauteng province municipal developers absorb certification premiums for accelerated plan approvals.
Supply Chain Analysis
Rotterdam port congestion and Suez Canal transit variability choke European-manufactured gantry system delivery schedules to Mombasa and Lagos. Equipment supply concentrates in Denmark, the United States, and the Netherlands, while Portland-cement blend optimization draws from South African and Kenyan aggregate testing laboratories. Supply chain risk centers on single-source vulnerability for proprietary Lavacrete formulation licensing. Distribution runs through Johannesburg-Pretoria equipment depots for southern African markets, with Mombasa and Lagos serving East and West African hubs respectively.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards regulatory entrenchment as a defensive moat, where first-mover certification reciprocity in Ethiopia's dedicated 3D construction code creates switching costs for contractors locked into approved equipment platforms.
For Market Incumbents: Fortify certification pipeline control by expanding RoboForm training ecosystems into Kenya and Nigeria before competitor operator programs achieve scale. Backward integration into localized concrete formulation testing laboratories in Gauteng and Lagos corridors defends against aggregate sourcing volatility threatening compression strength guarantees. For New Entrants and Emerging Players: Anchor in Ethiopia's regulatory first-mover corridor, where Ministry of Urban Development code development precedes equipment deployment and certification reciprocity agreements remain unclaimed. Polymer composite decorative applications in Lagos premium residential towers offer the most penetrable white-space, with facade cladding specifications unbundling from structural contracts creating service-based entry angles. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among regional training and certification specialists controlling operator pipelines, as equipment sales cycles lengthen while knowledge transfer contracts renew annually. Long-term viability hinges on regulatory reciprocity network effects rather than hardware margins. Acquisition target archetype: vertically integrated contractors with SANS-compliant deployment records and captive training capacity. The signal to watch is Ethiopian code finalization triggering cross-border equipment relocation demand.| Strategic Initiative | Industry Significance |
|---|---|
| Localized Concrete Formulation Certification | South Africa's SANS amendment process accelerates building plan approvals for qualified additive contractors. |
| Regional Training Ecosystem Expansion | RoboForm's Kenya-Nigeria pipeline replication captures operator scarcity premiums before competitor programs launch. |
| Polymer Composite Application Development | Lagos corridor developers specify non-load-bearing facade elements unbundled from structural printing contracts. |
| Equipment Import Financing Structuring | Currency hedging instruments reduce landed cost volatility for Nairobi and Lagos corridor contractors. |
| Regulatory Reciprocity Agreement Negotiation | Ethiopia's dedicated code positions first-mover contractors for cross-border deployment rights. |
Research Methodology
Desk research of equipment manufacturer technical specifications, national building code amendment drafts, and customs import classification records preceded structured interviews with additive manufacturing technicians, affordable housing procurement officers, National Construction Authority inspectors, and concrete formulation specialists. Primary fieldwork across Johannesburg-Pretoria, Lagos, Nairobi-Mombasa, and Addis Ababa corridors validated secondary data on deployment timelines and certification bottlenecks. Bottom-up project pipeline enumeration triangulated against top-down equipment import value estimates.
Variance decomposition across technology adoption curves, regulatory pathway maturation, and material qualification timelines shaped analytical framework construction throughout the projection horizon. Segmentation modeling incorporated technology type, end-use application, material class, and national regulatory cluster dimensions. CAGRs derived from equipment deployment schedules correlated with affordable housing procurement mandate acceleration rates and concrete compression strength certification throughput.
Material uncertainties — Ethiopian code finalization delays, Kenyan National Construction Authority additive-specific pathway adoption, and Nigerian naira exchange rate volatility — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding regulatory reciprocity emergence and gantry system manufacturer capacity allocation priorities. Practitioners should keep alternative scenarios live as SANS amendment implementation pace and Ethiopian regulatory export influence evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Astrology Market
Others
Human Enhancement Technology Market
Others
Military Sensors Market
Others
Education and Learning Analytics Market
Others
LAMEA Astrology Market
Others
Germany 3D Printing Construction Market
Others
Global Maritime Freight Transport Market
Others
Duty Free Retail Market
Others
Signal Transformer Market
Others
Middle East Smart Home Market
Others
Liquid-Cooled Heat Sink Market
Others
Industrial Computers Market
Others
Vortexers Market
Others
Pin Mills Market
Others
Ambient Assisted Living and Smart Home Market
Others
Reduced-Risk Products (Rrps) Market