
 Canada 3D Printing Construction Market | 2026-2036
Canada 3D Printing Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Canada 3D Printing Construction Market Insights
CSA A23.1 concrete certification for 3D-printed structural elements is collapsing the barrier between experimental construction and commercial-scale deployment. COBOD International leverages its gantry-based extrusion systems to anchor large-format projects across Canadian provinces. Apis Cor competes with mobile robotic platforms that reduce on-site labor requirements. ICON Technology Studio dominates design-build integration by controlling architectural software pipelines alongside hardware supply.
Canada 3D printing construction employs layer-by-layer material deposition, typically extruding Portland-cement-based mixes through computer-guided nozzles at deposition rates exceeding 10 kg/minute to form structural walls and building envelopes without traditional formwork. Concrete formulations currently lead product type adoption due to thermal mass advantages and code familiarity, while polymer segments attract fastest growth in non-load-bearing interior applications. Extrusion technology sustains the installed base through proven field reliability, though binder jetting extends into metal reinforcement printing where geometric complexity rewards additive methods.
Health Canada and the National Research Council of Canada jointly shape material safety protocols and structural performance benchmarks for printed building components. Provincial regulators in Ontario and British Columbia enforce site-specific amendments that exceed federal baselines, creating fragmented compliance obligations. Stakeholders must monitor municipal zoning experiments and CSA standard revision cycles to anticipate where first-mover advantages convert into scalable project pipelines.
Market Dynamics
CSA A23.1 concrete certification for 3D-printed structural elements is collapsing the barrier between experimental construction and commercial-scale deployment across Canadian provinces.
Growth Catalysts
- National Building Code updates:Additive manufacturing standards under revision create regulatory clarity that accelerates municipal project approvals in Ontario and British Columbia.
- Deposition rate improvements:Extrusion systems now exceed 10 kg/minute throughput, compressing wall-formation timelines for residential envelopes and reducing labor-hour intensity.
- Vancouver zoning pilots:Municipal experiments with streamlined permitting for printed structures reduce approval cycles and demonstrate code-compliant precedents for other cities.
Market Restraints
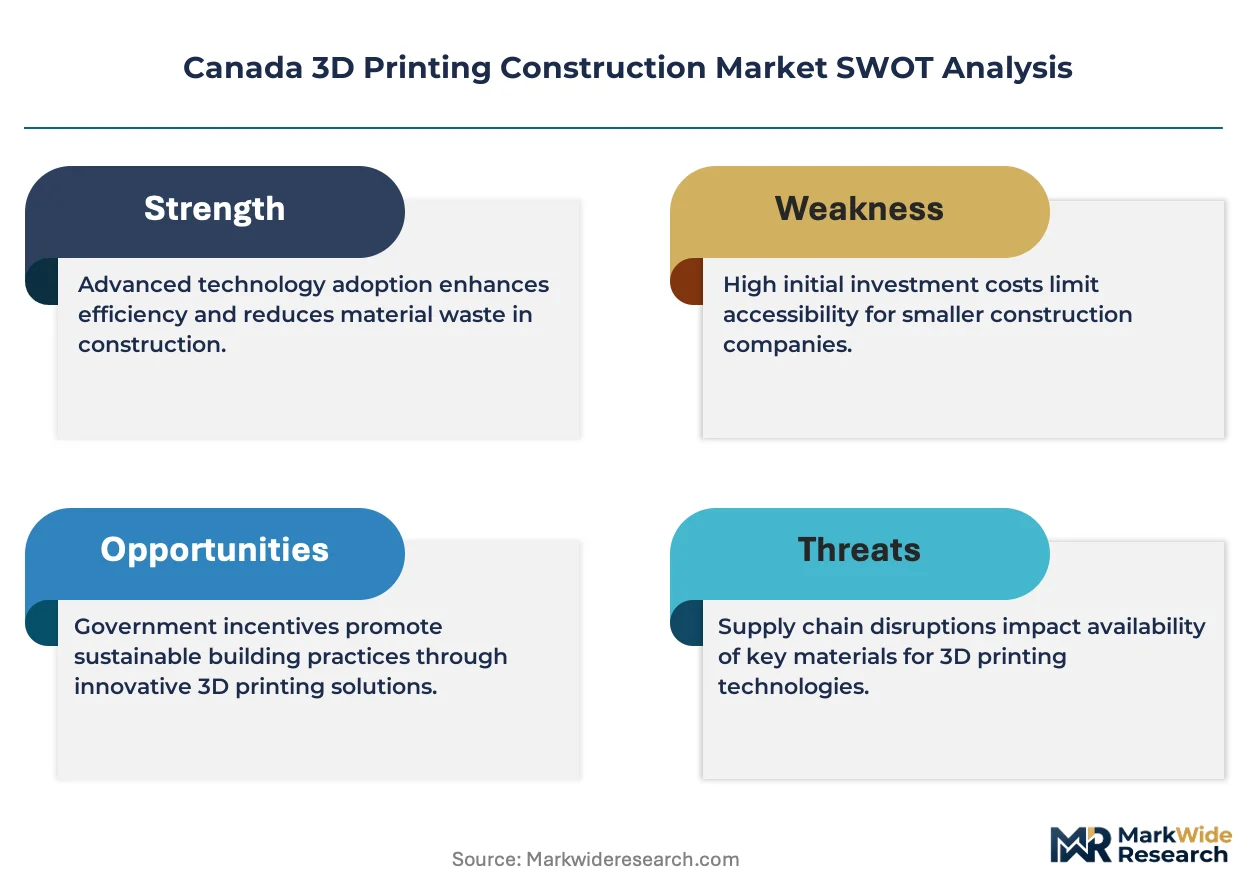
- Portland-cement input volatility:Energy-intensive clinker production faces carbon pricing pressure, exposing project cost structures to federal clean fuel regulations.
- Equipment supply concentration:Gantry-based extrusion hardware relies on limited European and North American fabricators, creating lead-time risk for large-format deployments.
- Geometric limitation of extrusion:Overhang angles and unsupported spans remain constrained without secondary reinforcement, restricting architectural freedom in vertical construction.
Strategic Opportunities
- Calgary municipal pipeline:Alberta's permitting experiments lag Ontario and British Columbia, creating first-mover positioning for contractors establishing local demonstration projects.
- Polymer interior applications:Non-load-bearing partitions and fixtures attract faster regulatory pathways than structural concrete, opening fit-out market entry.
- Binder jetting convergence:Metal reinforcement printing integrates with concrete extrusion to solve rebar placement automation, enabling geometric complexity that conventional formwork cannot achieve.
Industry Challenges
- CSA certification timelines:Structural element approval cycles extend 18-24 months, compressing project feasibility windows and tying up working capital in pre-construction phases.
- Digital fabrication skills gap:Construction trades lack training in parametric design-to-fabrication workflows, forcing contractors to recruit from aerospace and automotive talent pools.
- Legacy system integration:Building information modeling pipelines require reconfiguration to accommodate layer-wise deposition constraints, disrupting established subcontractor coordination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada 3D Printing Construction Market |
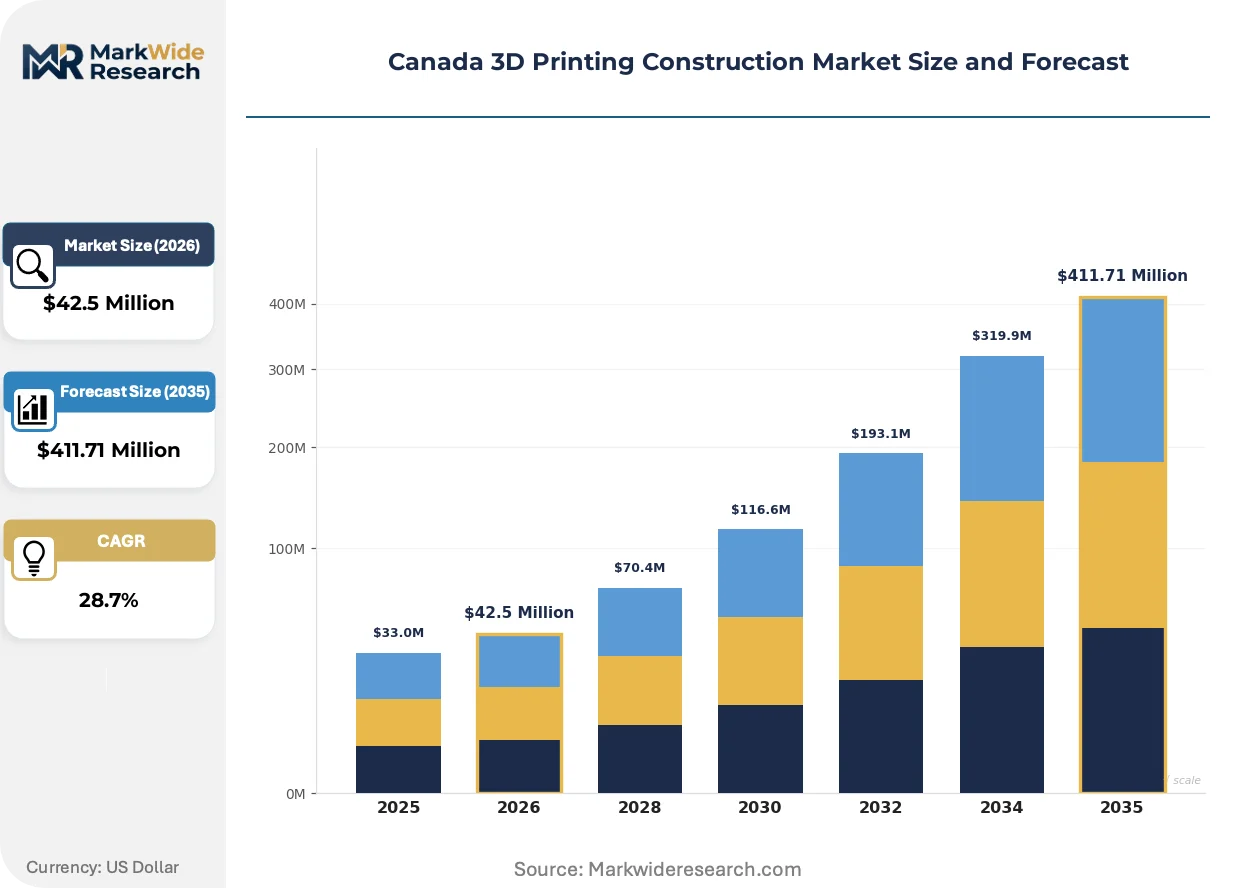
| Market Size in 2026 | $42.5 Million |
| Market Size in 2035 | $411.71 Million |
| CAGR (2026 – 2036) | 28.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Concrete, Polymer, Metal, Composite Technology: Extrusion, Powder Bed Fusion, Binder Jetting, D-Shape Application: Residential, Commercial, Infrastructure, Landscaping End User: Contractors, Architects, Developers, Engineers |
| Companies Covered | COBOD International, Apis Cor, ICON Technology Studio, Contour Crafting Corporation, Sika AG, XtreeE, CyBe Construction, MX3D, WASP, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada 3D Printing Construction Market Trends and Innovations
Layer-wise deposition is actively compressing traditional formwork economics while regulatory frameworks race to codify performance benchmarks for printed structural elements.
Extrusion-based concrete printing is displacing conventional cast-in-place methods for residential wall assemblies. Ontario and British Columbia homebuilders pilot single-family and low-rise multifamily envelopes, attracted by elimination of formwork rental and stripping labor. The technology is displacing mid-rise wood-frame dominance in Vancouver's zoning-permitted demonstration zones.
Health Canada and the National Research Council of Canada jointly shape material safety protocols and structural performance benchmarks for printed building components. Provincial regulators in Ontario and British Columbia enforce site-specific amendments that exceed federal baselines, creating fragmented compliance obligations. Residential builders concentrate investment in jurisdictions where municipal zoning experiments align with CSA standard revision cycles.
Design-build integration is compressing traditional architect-contractor-subcontractor handoffs. ICON Technology Studio and comparable vertically organized firms control software pipelines alongside hardware supply, collapsing information loss between digital models and physical deposition. Toronto and Vancouver projects demonstrate this consolidation most visibly, where speed-to-occupancy drives procurement preference toward single-source accountability.
Canada 3D Printing Construction Market Segmentation
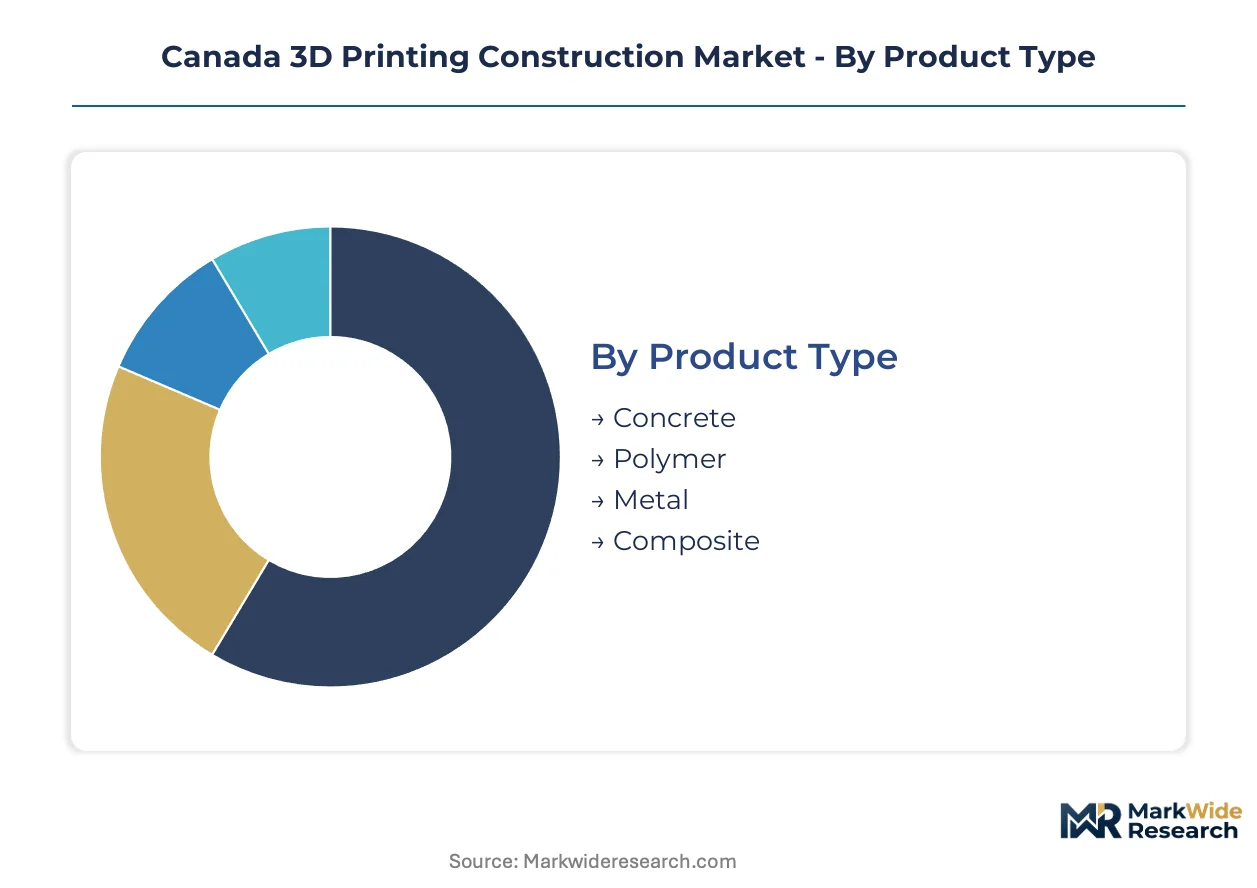
Material formulations and deposition technologies fragment the Canadian market into distinct procurement channels. Each segment carries unique certification burdens under CSA standards and municipal zoning protocols that shape where capital deploys across provinces.
Product Type:
Domestic demand concentrates in cementitious formulations familiar to provincial building inspectors, while polymer and metal segments serve export-adjacent specialty contracts.
- Concrete:Portland-cement-based mixes with supplementary cementitious materials achieve thermal mass ratings that satisfy National Building Code energy performance requirements. Ontario and British Columbia residential builders specify these formulations for wall assemblies in Vancouver and Toronto municipal pilot zones where CSA A23.1 certification accelerates permitting.
- Polymer:Acrylonitrile butadiene styrene and recycled PET blends enable rapid-cure interior partitions without structural load-bearing obligations. Calgary fit-out contractors and Vancouver commercial developers drive procurement for non-code-critical applications where geometric complexity outweighs material cost premiums.
- Metal:Titanium and aluminum powder stocks serve aerospace-adjacent architectural installations requiring high strength-to-weight ratios.
- Composite:Fiber-reinforced polymer concrete hybrids bridge thermal performance with tensile reinforcement for cantilevered elements.
Concrete commands the established base. The steepest expansion runs through Polymer.
Technology:
Cost tiers separate field-proven extrusion hardware from capital-intensive powder systems still awaiting Canadian regulatory precedent.
- Extrusion:Gantry and robotic arm systems deposit material through computer-guided nozzles at rates exceeding 10 kg/minute, eliminating formwork labor for vertical wall construction. Contractors across Ontario and British Columbia dominate installed capacity where deposition reliability supports warranty underwriting.
- Powder Bed Fusion:Selective laser sintering of polymer and metal powders produces high-resolution architectural components with isotropic mechanical properties. Toronto design studios and Vancouver specialty fabricators absorb equipment costs for bespoke facade elements where surface finish quality justifies premium pricing.
- Binder Jetting:Liquid binding agents fuse powder layers for metal reinforcement printing that integrates with concrete extrusion systems.
- D-Shape:Magnesium chloride-based binder systems enable large-scale stone-like material deposition for landscaping and artistic installations.
Extrusion holds the volume leadership position. Binder Jetting is climbing the fastest as rebar automation solutions mature.
Application:
Customer type determines whether projects flow through municipal zoning pilots or conventional permitting channels.
- Residential:Single-family and low-rise multifamily envelopes in Vancouver, Toronto, and Calgary demonstration zones eliminate formwork rental costs while compressing weather-dependent construction schedules. National Building Code additive manufacturing standard revisions create regulatory clarity that attracts Ontario homebuilder investment.
- Commercial:Office and retail fit-outs prioritize speed-to-occupancy in urban cores where labor shortages constrain conventional construction timelines. British Columbia developers specify printed interior partitions to meet aggressive lease commencement dates in Vancouver's compressed development cycles.
- Infrastructure:Bridge components and utility housing face extended CSA approval timelines that delay deployment.
- Landscaping:Non-structural hardscape elements bypass structural certification requirements for faster market entry.
Residential captures the current project pipeline. Commercial is gaining share fastest as design-build integration compresses delivery timelines.
End User:
Procurement authority sits with entities controlling both capital allocation and regulatory compliance liability.
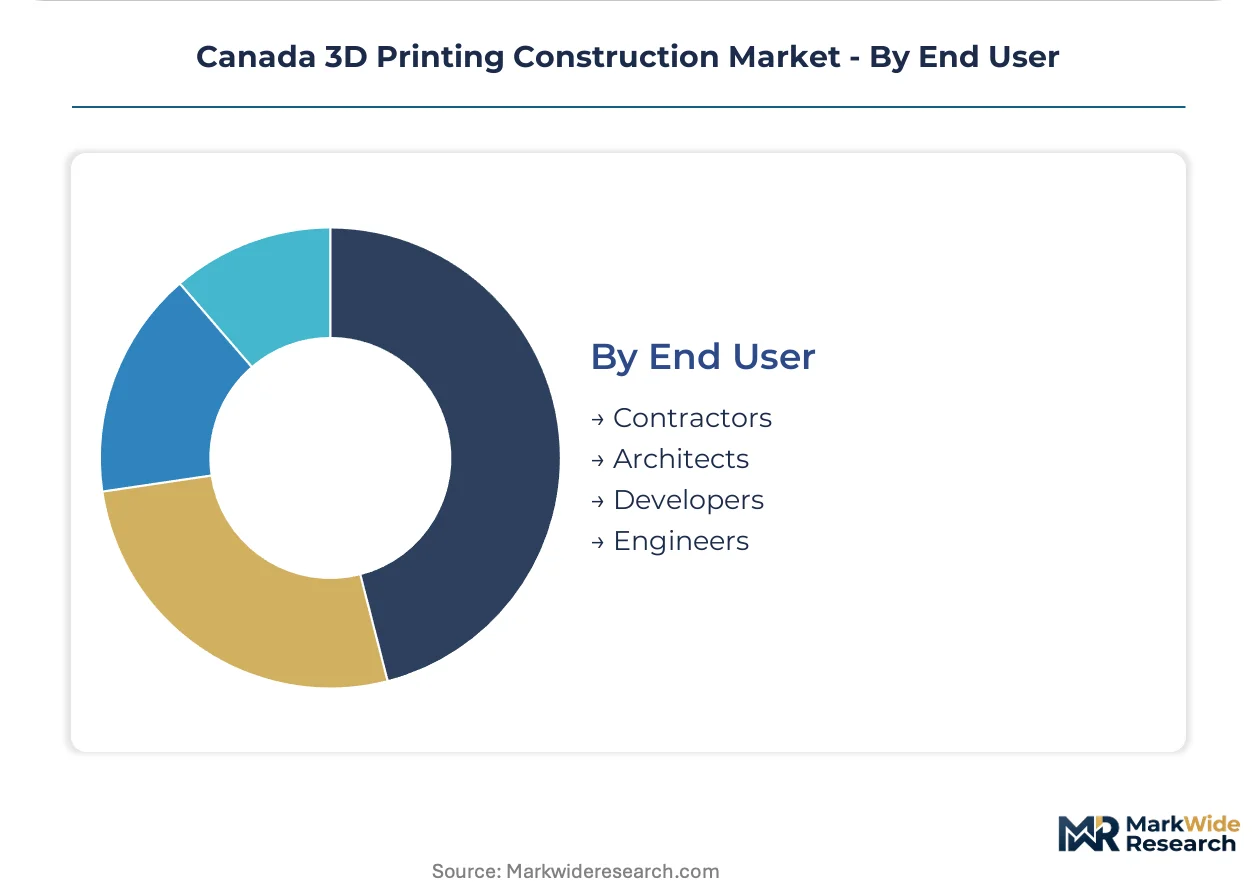
- Contractors:General and specialty construction firms own equipment procurement decisions and field deployment risk for printed wall assemblies. Ontario and British Columbia contractors with parametric design capabilities differentiate bids in municipal pilot zones where traditional formwork economics disadvantage conventional competitors.
- Developers:Real estate investment entities drive technology adoption through procurement specifications that transfer performance risk to design-build integrators. Calgary and Toronto developers increasingly mandate printed envelope solutions in requests for proposal where speed-to-market commands premium lease rates.
- Architects:Design professionals influence material specification through building information modeling pipelines that constrain fabrication options.
- Engineers:Structural consultants validate printed element performance against CSA benchmarks during pre-construction phases.
Contractors anchor equipment purchasing. Developers are expanding their specification influence fastest as single-source accountability consolidates procurement decisions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian developers and contractors concentrate procurement authority in Ontario, British Columbia, and Alberta, where municipal zoning experiments align with provincial code amendments to accelerate printed structure approvals.
Ontario
Toronto homebuilders drive residential envelope demand through National Building Code additive manufacturing standard revisions that clarify compliance pathways. Health Canada protocols for material safety shape provincial enforcement that exceeds federal baselines. The Greater Toronto Area anchors equipment deployment where contractors eliminate formwork rental costs through gantry-based extrusion systems.
British Columbia
Vancouver municipal zoning pilots compress permitting cycles for demonstration projects that validate code-compliant precedents. The National Research Council of Canada structural performance benchmarks guide provincial inspectors evaluating printed wall assemblies. Metro Vancouver concentrates design-build integration activity where speed-to-occupancy commands premium lease rates.
Alberta
Calgary developers exploit lagging permitting experiments to establish first-mover positioning through local demonstration projects. Provincial regulators enforce site-specific amendments that create fragmented compliance obligations distinct from Ontario and British Columbia. The Calgary-Edmonton corridor attracts contractor investment where parametric design capabilities differentiate bids in emerging pilot zones.
Quebec
Montreal construction firms evaluate printed envelope solutions as CSA A23.1 certification timelines extend pre-construction capital commitments. The country's national building research institute influences material formulation standards that provincial authorities adapt for climate-specific performance. Greater Montreal represents latent demand where linguistic procurement preferences shape vendor selection distinct from anglophone markets.
Atlantic Canada
Halifax and St. John's contractors monitor Ontario and British Columbia precedent projects before committing equipment capital to smaller addressable markets. Federal clean fuel regulations expose project cost structures to carbon pricing pressure that compounds maritime logistics premiums. The Atlantic region remains supply-constrained as European and North American equipment fabricators prioritize larger provincial deployments.
Canada 3D Printing Construction Market Competitive Landscape
Player mix skews toward European-origin hardware fabricators and North American design-build integrators, creating a tiered structure where equipment suppliers and vertically organized project delivery firms occupy distinct competitive positions. Two strategic archetypes dominate: gantry-based extrusion system providers and mobile robotic platform specialists. Capacity expansion through demonstration project pipelines and strategic partnerships with municipal zoning authorities constitute the primary competitive moves.
Among European-origin hardware fabricators, COBOD International and CyBe Construction occupy positions that exemplify gantry-based system deployment across Canadian provinces. Apis Cor represents the mobile robotic platform archetype that reduces on-site labor requirements through repositionable equipment configurations. These three companies anchor the equipment supply tier where lead-time risk for large-format deployments concentrates procurement decisions.
| Leading Market Players |
|---|
| COBOD International |
| Apis Cor |
| ICON Technology Studio |
| Contour Crafting Corporation |
| Sika AG |
| XtreeE |
| CyBe Construction |
| MX3D |
| WASP |
| Others |
Pricing and Supply Chain Analysis
Portland-cement substitution by supplementary cementitious materials is simultaneously shifting supply geography toward Alberta fly-ash processors and compressing material cost volatility exposure under federal clean fuel regulations.
Pricing Analysis
Cost-plus contracts with Portland-cement indexation dominate project procurement across Ontario and British Columbia. Price differentiation separates CSA A23.1-certified structural elements from non-certified experimental tiers. Pricing pressure stems from carbon pricing exposure on clinker-intensive inputs. Municipal developers exhibit highest price sensitivity, while federal infrastructure contractors absorb premiums for code-compliant precedents.
Supply Chain Analysis
Denmark and the Netherlands anchor gantry-based extrusion hardware fabrication for Canadian deployments. Equipment procurement draws from European fabricators with limited North American assembly capacity. Single-source vulnerability concentrates in robotic arm servo motors sourced from German and Japanese suppliers. Distribution runs through Calgary and Toronto equipment leasing intermediaries that bundle maintenance with field deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
CSA A23.1 certification timelines represent a regulatory inflection compressing experimental construction into commercially bankable project pipelines.
For Market Incumbents: Consolidate parametric design capabilities through acquisition of aerospace-to-construction talent pipelines. Defend against mobile robotic platform entrants by embedding warranty underwriting into equipment lease structures. Deepen backward integration into concrete formulation supply to capture margin from carbon-regulated input volatility.
For New Entrants and Emerging Players: Post-certification technical support gaps in Calgary and Edmonton demonstration zones offer white-space positioning. Target municipal zoning lag in Alberta for first-mover project precedents. Pursue design-build integration partnerships that collapse architect-contractor handoffs.
For Investors and Strategic Acquirers: The market sits at a standards-convergence phase that favors vertically organized design-build integrators. Long-term viability centers on controlling software-to-hardware pipelines rather than pure equipment fabrication. Monitor CSA revision cycles as the signal for capital deployment acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| CSA Certification Investment | Accelerates project approval timelines under National Building Code revisions. |
| Parametric Design Talent Acquisition | Addresses digital fabrication skills gap constraining field deployment capacity. |
| Municipal Zoning Partnership | Creates demonstration precedents that reduce permitting cycles in target cities. |
| Concrete Formulation Backward Integration | Hedges carbon pricing exposure on Portland-cement input costs. |
| Design-Build Vertical Consolidation | Compresses information loss between digital models and physical deposition. |
Research Methodology
A standing panel of equipment procurement managers, municipal zoning officers, concrete formulation specialists, and parametric design engineers provided ongoing calibration. Primary interviews combined with secondary validation from Health Canada material safety protocols, National Research Council structural performance benchmarks, CSA standard revision documentation, and provincial building code amendment records. Bottom-up project pipeline analysis triangulated against top-down equipment shipment data.
Model outputs were validated against external benchmarks including municipal permitting velocity metrics and equipment utilization rates reported by leasing intermediaries. Segmentation dimensions spanned material formulation, deposition technology, application type, and end-user procurement authority across the analysis window. CAGRs were derived from project pipeline scaling assumptions tied to regulatory clarity milestones and equipment depreciation schedules.
Forecasts assume regulatory continuity in Health Canada and National Research Council protocols; material policy shifts would require re-modeling. Specific risks include extended CSA certification timelines, carbon pricing escalation on clinker production, and equipment supply concentration in European fabrication bases. Recalibration cycles align with material shifts in municipal zoning experiments and standard revision announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Global Electroshock Weapons Market
Others
Global Webinar and Webcast Market
Others
Global Geotechnical Instrumentation and Monitoring Market
Others
Fresh Apples Market
Others
Solar Animal Repeller Market
Others
Military Sensors Market
Others
Prunes Market
Others
Global Supply Chain Risk Management Software Market
Others
Lepidolite Market
Others
Ultrasonic Flow Meter Market
Others
Global Solder Balls Market
Others
Aboveground Storage Tanks Market
Others
Europe Battery Packaging Market
Others
Liquid Density Meters Market
Others
Managed Testing Services Market
Others
Griffin Beaker Market